
 Organic Sulfur Market | 2026-2036
Organic Sulfur Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Sulfur Market Analytics
REACH is realigning the cost-of-entry calculus for European sulfur compound suppliers by mandating exhaustive substance registration and downstream-use documentation. Nutrien Ltd. leverages its integrated phosphate-sulfur mining network to control feedstock quality from extraction to formulation. The Mosaic Company anchors North American supply through captive sulfur recovery at its Florida phosphate operations. Yara International ASA competes on precision agriculture platforms that pair sulfur coatings with nitrogen stabilization technology.
Organic sulfur denotes naturally occurring or synthetically derived sulfur compounds—primarily elemental sulfur, sulfates, and organosulfur molecules such as dimethyl sulfide and thiols—typically refined to 99.5% purity for industrial use, functioning as essential plant nutrients, pharmaceutical intermediates, and vulcanization agents. Granular formulations dominate agricultural channels due to controlled-release compatibility with mechanized spreading equipment, while liquid sulfur suspensions represent the fastest-growing product category as fertigation systems penetrate high-value horticulture. Pharmaceutical-grade sulfonamides and personal care organosulfur actives command premium margins, though volumes remain concentrated in dermatological and antifungal applications.
EPA regulates sulfur dioxide emissions from phosphate processing facilities, directly constraining domestic production economics and favoring low-emission recovery technologies. EMA and FDA both enforce residual sulfur limits in active pharmaceutical ingredients, creating dual-compliance burdens for exporters serving transatlantic markets. India's BIS certification for agricultural micronutrients adds a third layer of testing protocols for sulfur-based fertilizers entering through DGFT-monitored import channels. Stakeholders must monitor evolving carbon border adjustment mechanisms, as embedded emissions in sulfur recovery processes will increasingly determine competitive access to regulated jurisdictions.
Market Dynamics
REACH registration requirements and the EU F-Gas Regulation are compressing supplier margins while redirecting procurement toward certified producers with established downstream-use documentation. This regulatory tightening coincides with agricultural demand concentration in Brazil and Southeast Asia, creating divergent compliance burdens across supply chains.
Growth Catalysts
- Soil health mandates:India's state-level micronutrient programs are institutionalizing sulfur-based fertilizer procurement through DGFT-monitored channels.
- REACH compliance premiums:Exhaustive substance registration requirements in Europe are rewarding early-registrant suppliers with preferred-access contracts.
- Fertigation penetration:Liquid sulfur suspensions are capturing share in high-value horticulture as drip irrigation infrastructure spreads.
Market Restraints
- Phosphate processing emissions:EPA sulfur dioxide limits constrain domestic production economics and favor capital-intensive recovery technology.
- Dual-compliance testing:EMA and FDA residual sulfur limits create redundant validation burdens for transatlantic API exporters.
- Elemental sulfur substitution:Ammonium sulfate and gypsum compete in low-specification agricultural applications.
Strategic Opportunities
- Carbon border positioning:Embedded emissions accounting in EU CBAM mechanisms will advantage low-carbon sulfur recovery operations.
- Precision agriculture convergence:Sulfur coating technology paired with nitrogen stabilization creates bundled value propositions.
- Brazilian fertilizer expansion:Agricultural input distributors are building dedicated sulfur-based nutrient programs for soybean and corn belts.
Industry Challenges
- Pharmaceutical-grade certification timelines:BIS, FDA, and EMA parallel approval pathways extend time-to-revenue for new organosulfur actives.
- Captive supply integration:Phosphate miners with in-house sulfur recovery face technical complexity integrating third-party offtake.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Sulfur Market |
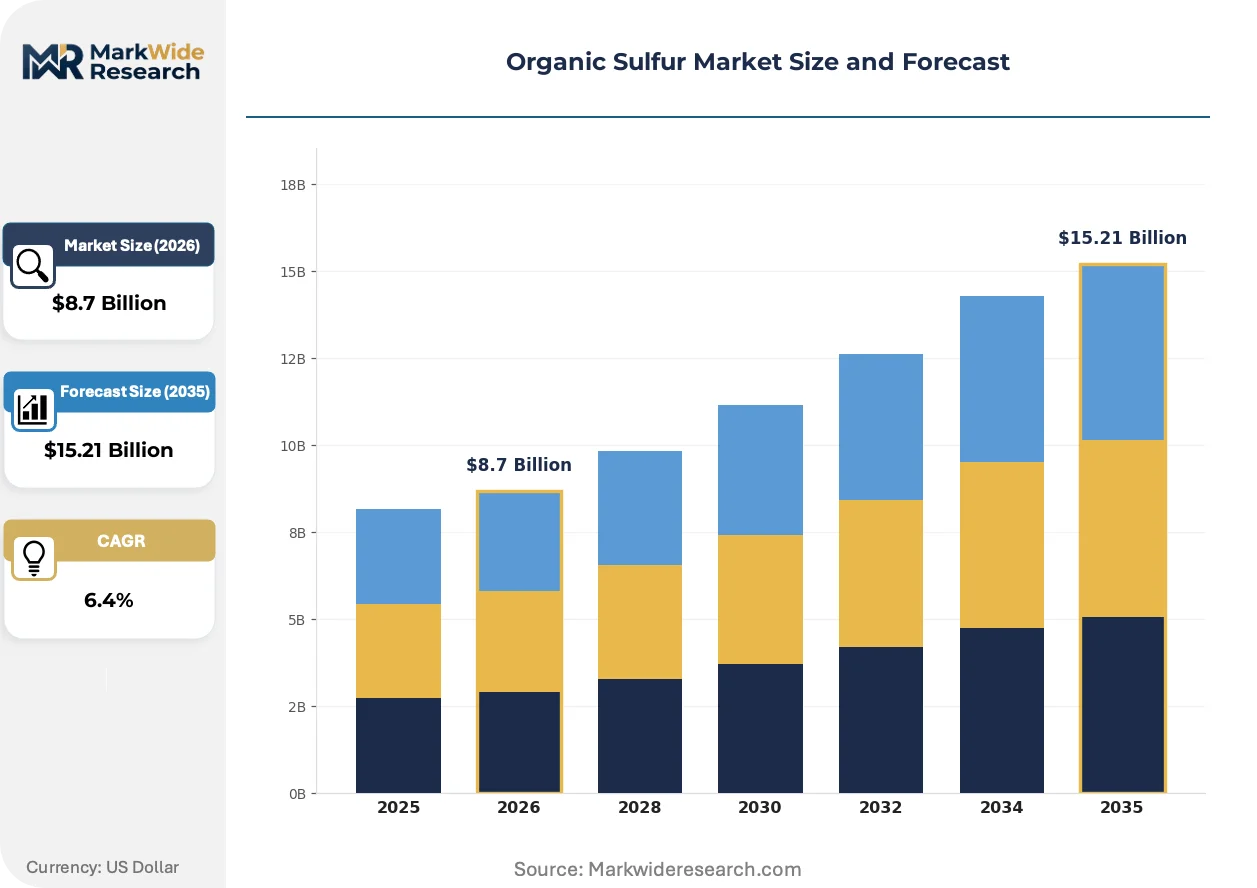
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powder, Flakes, Liquid Application: Agriculture, Animal Feed, Pharmaceuticals, Personal Care Distribution Channel: Online, Retail, Direct Sales, Distributors End User: Farmers, Manufacturers, Retailers, Consumers |
| Companies Covered | Nutrien Ltd., The Mosaic Company, Saudi Arabian Mining Company (Ma'aden), Vale S.A., ICL Group Ltd., Yara International ASA, Coromandel International Limited, K+S Group, Koch Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Sulfur Market Evolving Landscape
Controlled-release formulation technology and emissions-compliant recovery processes are restructuring competitive advantage around certification depth rather than scale alone. Suppliers are repositioning around precision agriculture platforms and pharmaceutical-grade purity tiers.
Encapsulated sulfur granules with polymer coating technology is expanding into Brazilian soybean operations and Southeast Asian palm oil plantations. Large-scale agricultural cooperatives in Mato Grosso and Riau Province are specifying coated products for mechanized spreading compatibility. This diffusion is expanding into contract fertilizer blending facilities that previously relied on uncoated elemental sulfur.
REACH downstream-use documentation mandates are forcing reformulation of imported sulfur compounds across European agrochemical and pharmaceutical channels. Suppliers without pre-registered substance portfolios face exclusion from formulated product supply chains. Specialty fertilizer distributors in Germany and France are consolidating procurement around REACH-registered producers to mitigate continuity risk.
Certification-driven procurement is compressing supplier qualification cycles as buyers prioritize pre-validated sulfur sources over spot-market purchases. Indian state agricultural departments now require BIS-certified micronutrients for subsidy eligibility, displacing informal import channels. This pattern is most visible in Maharashtra and Gujarat, where soil health card programs specify sulfur content thresholds.
Organic Sulfur Market Segmentation
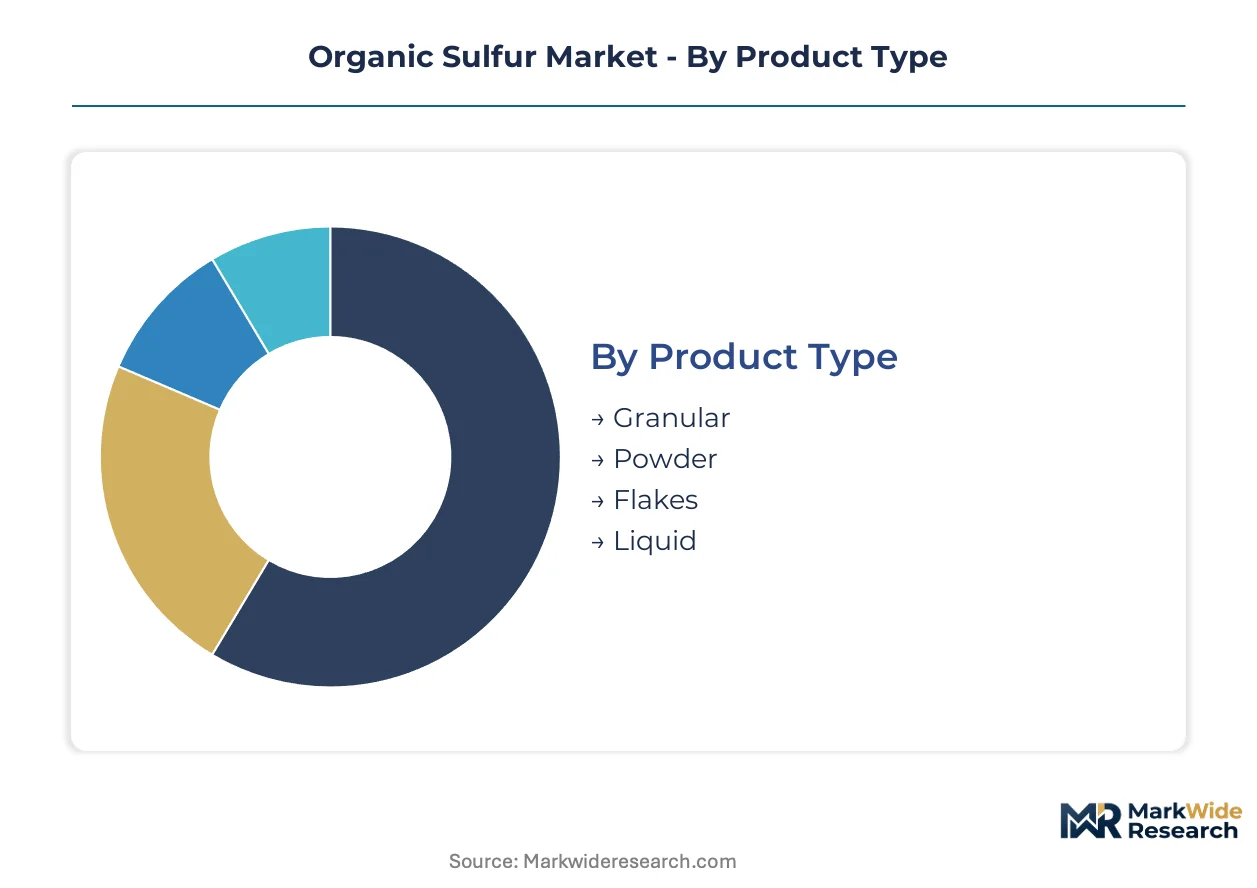
Organic sulfur markets fragment across physical form, end-use chemistry, and procurement channel. Each segmentation axis carries distinct margin profiles, compliance burdens, and customer concentration patterns that reshape supplier strategy.
Product Type:
Physical specification determines handling infrastructure, application equipment compatibility, and release kinetics in field conditions.
- Liquid:Suspensions enable fertigation integration with drip irrigation systems in high-value horticulture. Demand concentrates in Brazilian citrus operations and Southeast Asian palm oil estates where precision nutrient delivery reduces leaching losses. REACH-registered liquid formulations command procurement preference in European specialty agriculture.
- Granular:Polymer-coated granules dominate mechanized spreading in Brazilian soybean belts and Indian wheat districts. Mato Grosso cooperatives specify sulfur-enhanced NPK blends for controlled-release compatibility with no-till planting equipment. BIS certification requirements now filter informal import channels.
- Powder:Fine-milled sulfur serves pharmaceutical sulfonamide synthesis and rubber vulcanization where surface area drives reaction kinetics. FDA and EMA residual limits impose dual-validation burdens on API-grade powder exports.
- Flakes:Industrial-grade flakes supply chemical manufacturing and dusting applications in specialty crop protection. Lower purity tolerances restrict agricultural use to soil amendment in sulfur-deficient regions outside subsidy programs.
Mature deployment sits with Granular formulations. Newer deployment is concentrated in Liquid suspensions.
Application:
End-use chemistry separates commodity nutrient markets from certified pharmaceutical and personal care tiers with divergent pricing power.
- Agriculture:Soil sulfur deficiency correction drives volume through state procurement programs. India's soil health card schemes in Maharashtra and Gujarat mandate micronutrient content thresholds that institutionalize sulfur-based fertilizer adoption. DGFT-monitored import channels displace informal trade.
- Pharmaceuticals:Sulfonamide intermediates and organosulfur actives require pharmaceutical-grade purity with EMA, FDA, and CDSCO parallel approval pathways. Dermatological and antifungal applications concentrate demand among contract API manufacturers serving transatlantic markets.
- Animal Feed:Methionine precursors and sulfur-containing amino acid supplements address protein synthesis in poultry and swine operations. Feed-grade specifications fall between agricultural and pharmaceutical tiers on purity and documentation requirements.
- Personal Care:Organosulfur compounds in antifungal and keratolytic formulations command premium margins with limited volume. Cosmetic-grade certification adds testing protocols beyond pharmaceutical baselines.
Volume concentration rests with Agriculture. Margin expansion is steepest in Pharmaceuticals.
Distribution Channel:
Channel structure reflects customer scale, technical service requirements, and regulatory documentation needs across end-use segments.
- Distributors:Agricultural cooperatives and regional fertilizer blenders rely on distributor networks for inventory positioning and agronomic support. Brazilian distributors are building dedicated sulfur-based nutrient programs for soybean and corn belts.
- Direct Sales:Pharmaceutical and personal care manufacturers procure API-grade sulfur through direct contracts with REACH-registered producers to secure downstream-use documentation. Long-term offtake agreements dominate this channel.
- Retail:Smallholder farmers and specialty crop operators access packaged sulfur amendments through agricultural supply stores. BIS certification requirements now condition subsidy eligibility in Indian state programs.
- Online:E-commerce penetration remains limited to specialty horticulture and hobbyist applications where technical consultation requirements are minimal.
Procurement scale concentrates through Distributors. Documentation intensity favors Direct Sales.
End User:
User type determines specification stringency, volume scale, and technical service intensity in supplier relationships.
- Farmers:Mechanized operations in Brazil and India drive granular sulfur demand through cooperative procurement. Soil testing adoption in state-level programs is institutionalizing micronutrient specification in purchase decisions.
- Manufacturers:Pharmaceutical and chemical processors require certificate-of-analysis documentation with each lot. REACH registration status and carbon intensity disclosures are entering supplier scorecards.
- Retailers:Agricultural input stores and personal care distributors manage inventory risk on certified products with defined shelf-life requirements.
- Consumers:Direct purchases concentrate in garden and specialty horticulture segments with minimal regulatory oversight.
Institutional volume flows to Farmers. Certification burden concentrates with Manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Gujarat and Maharashtra concentrate sulfur-based fertilizer formulation capacity near port infrastructure serving agricultural procurement programs.
India
State-level soil health card programs in Maharashtra and Gujarat mandate micronutrient content thresholds that institutionalize sulfur-based fertilizer adoption. BIS certification requirements now filter informal import channels through DGFT-monitored procurement. Agricultural cooperatives in these states specify coated sulfur products for mechanized spreading compatibility with no-till equipment.
Brazil
Mato Grosso cooperatives drive granular sulfur demand through dedicated nutrient programs for soybean and corn belts. ANVISA oversees residual limits in agricultural chemical formulations entering through southeastern ports. Blending facilities in Ribeirão Preto and Campo Grande are expanding polymer-coated sulfur capacity for precision application.
Germany
REACH downstream-use documentation mandates force reformulation of imported sulfur compounds across agrochemical and pharmaceutical channels. Specialty fertilizer distributors in the Rhine-Ruhr region consolidate procurement around pre-registered producers. ECHA compliance premiums reward early-registrant suppliers with preferred-access contracts to formulated product supply chains.
United States
EPA sulfur dioxide emissions limits from phosphate processing facilities constrain domestic production economics in Florida and Louisiana. Captive sulfur recovery operations at Gulf Coast phosphate mines anchor North American supply. Low-emission recovery technologies gain competitive advantage as embedded emissions enter supplier scorecards.
China
Dual carbon goals and MEE emissions standards reshape sulfur recovery economics in Shandong and Jiangsu chemical manufacturing clusters. GB standards for agricultural micronutrients tighten purity specifications for domestic fertilizer blenders. Yangtze River Delta processors are upgrading captive sulfur recovery to meet carbon intensity disclosure requirements for EU-bound exports.
Organic Sulfur Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Integrated phosphate miners with captive sulfur recovery occupy upstream control positions, while specialty fertilizer formulators compete on precision agriculture platforms. Three archetypes dominate: mining-integrated suppliers controlling feedstock quality, regional blenders serving state procurement programs, and pharmaceutical-grade refiners managing dual-compliance documentation. Competitive moves concentrate on capacity expansion in Brazil and Southeast Asia alongside REACH registration portfolio building for European market access.
Among mining-integrated suppliers, Nutrien Ltd. and The Mosaic Company exemplify upstream control archetypes leveraging captive sulfur recovery networks. Yara International ASA occupies a position within the precision agriculture tier, pairing sulfur coating technology with nitrogen stabilization platforms. These three entities represent contrasting strategic postures: extraction-integrated supply security versus formulation-led value bundling.
| Leading Market Players |
|---|
| Nutrien Ltd. |
| The Mosaic Company |
| Saudi Arabian Mining Company (Ma'aden) |
| Vale S.A. |
| ICL Group Ltd. |
| Yara International ASA |
| Coromandel International Limited |
| K+S Group |
| Koch Industries Inc. |
| Others |
Value Network & Pricing Analysis
EU carbon border adjustment mechanisms gate both qualified supply and premium-tier pricing access, embedding emissions accounting into supplier scorecards and compressing margins for high-carbon recovery operations while rewarding low-carbon producers with preferred-contract premiums.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as Brazilian cooperatives and Indian state procurement programs prioritize inventory security over spot-market savings. Three-tier pricing structure across pharmaceutical-grade, agricultural-certified, and industrial-commodity levels reflects purity documentation burdens and REACH registration status. Cost compression in industrial flake sulfur intensifies because ammonium sulfate and gypsum substitution erodes specification-tolerant segments. Smallholder farmers accessing retail channels exhibit highest price sensitivity, while pharmaceutical manufacturers prioritize certificate-of-analysis reliability over unit cost.
Supply Chain Analysis
REACH registration and BIS certification gate supply chain participation, disqualifying informal traders from European and Indian procurement channels. Production concentrates in the United States, Brazil, and India, with captive sulfur recovery at Florida phosphate mines and Mato Grosso blending facilities anchoring regional supply. Feedstock draws from phosphate processing off-gas, petroleum refining streams, and natural gas sweetening operations. Single-source vulnerability concentrates around Gulf Coast recovery infrastructure exposed to hurricane disruption. Distribution runs through agricultural cooperatives and specialty fertilizer distributors with integrated agronomic advisory services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as REACH downstream-use documentation requirements and parallel pharmaceutical certification timelines force capital-constrained regional blenders toward acquisition or exit.
For Market Incumbents: Anticipate margin compression from low-carbon sulfur recovery entrants by accelerating captive supply integration and securing long-term offtake agreements with Brazilian cooperatives. Prioritize carbon intensity disclosure capabilities to maintain EU market access under evolving border adjustment mechanisms. Invest in polymer-coating R&D to differentiate granular formulations from ammonium sulfate substitution threats. For New Entrants and Emerging Players: Encapsulated sulfur coating technology offers a defensible entry wedge into Brazilian soybean and Southeast Asian palm oil estates where precision application commands procurement preference. Target liquid suspension formulations for Southeast Asian horticulture fertigation systems as the most penetrable white-space segment. Pursue distributor partnerships with established agronomic advisory networks rather than direct farmer engagement. For Investors and Strategic Acquirers: REACH registration portfolio completion by mid-tier regional blenders is the leading indicator that consolidation timing is compressing and valuation multiples will diverge between documented and undocumented suppliers. Frame five-to-ten-year viability around carbon-intensity positioning and certification depth rather than scale alone. Monitor BIS certification acquisition rates among Indian state-program suppliers as the critical inflection signal for regional consolidation waves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Sulfur Recovery | Phosphate miners securing feedstock control against EPA emission constraint tightening. |
| REACH Registration Portfolio Expansion | European market access preservation amid downstream-use documentation mandate enforcement. |
| Polymer-Coating Capacity Buildout | Brazilian soybean cooperative demand capture through controlled-release compatibility specification. |
| Carbon Intensity Certification Program | EU CBAM positioning advantage through verified low-emission recovery process documentation. |
| Joint Venture with Regional Blenders | Indian state-procurement channel penetration leveraging BIS-certified local formulation infrastructure. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving phosphate plant managers, agricultural cooperative procurement leads, specialty fertilizer distribution partners, and pharmaceutical regulatory affairs directors. Bottom-up volume estimates from country-level import statistics and production capacity databases reconciled against top-down demand models derived from crop acreage projections and micronutrient application rate assumptions.
Data-stream reconciliation across physical form, application chemistry, and procurement channel dimensions produced segmented volume and value outputs throughout the forecast period. CAGRs derived from trend extrapolation of state-procurement program adoption curves, fertigation infrastructure penetration rates, and pharmaceutical-grade purity tier migration patterns. Industry-specific inputs incorporated EPA emission compliance cost trajectories and EU carbon border adjustment implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt REACH substance restriction expansion or phosphate processing capacity closures. Projections reflect assumptions regarding subsidy program continuity and certification harmonization progress. A model refresh is warranted upon material change in carbon border adjustment scope or major importing country regulatory alignment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Polycarboxylate Ethers (Pces) Market
Specialty Chemicals
Keratin Products Market
Specialty Chemicals
Cellulose Ether Market
Specialty Chemicals
Freeze-Thaw Stabilizers Market
Specialty Chemicals
Textile Flame Retardants Market
Specialty Chemicals
North America Sulfonylureas Market
Specialty Chemicals
Petroleum Jelly Market
Specialty Chemicals
Asia-Pacific Niacinamide Market
Specialty Chemicals
Fluoroethylene Carbonate (FEC) Market
Specialty Chemicals
Bond Breaker Market
Specialty Chemicals
Contouring Products Market
Specialty Chemicals
Octocrylene Market
Specialty Chemicals
Crystal Hard Wax Market
Specialty Chemicals
Phytosphingosine Market
Specialty Chemicals
Betulinic Acid Market
Specialty Chemicals
Caryophyllene Market