
 Global Sulfur Hexafluoride Market | 2026-2036
Global Sulfur Hexafluoride Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sulfur Hexafluoride Market Foresight
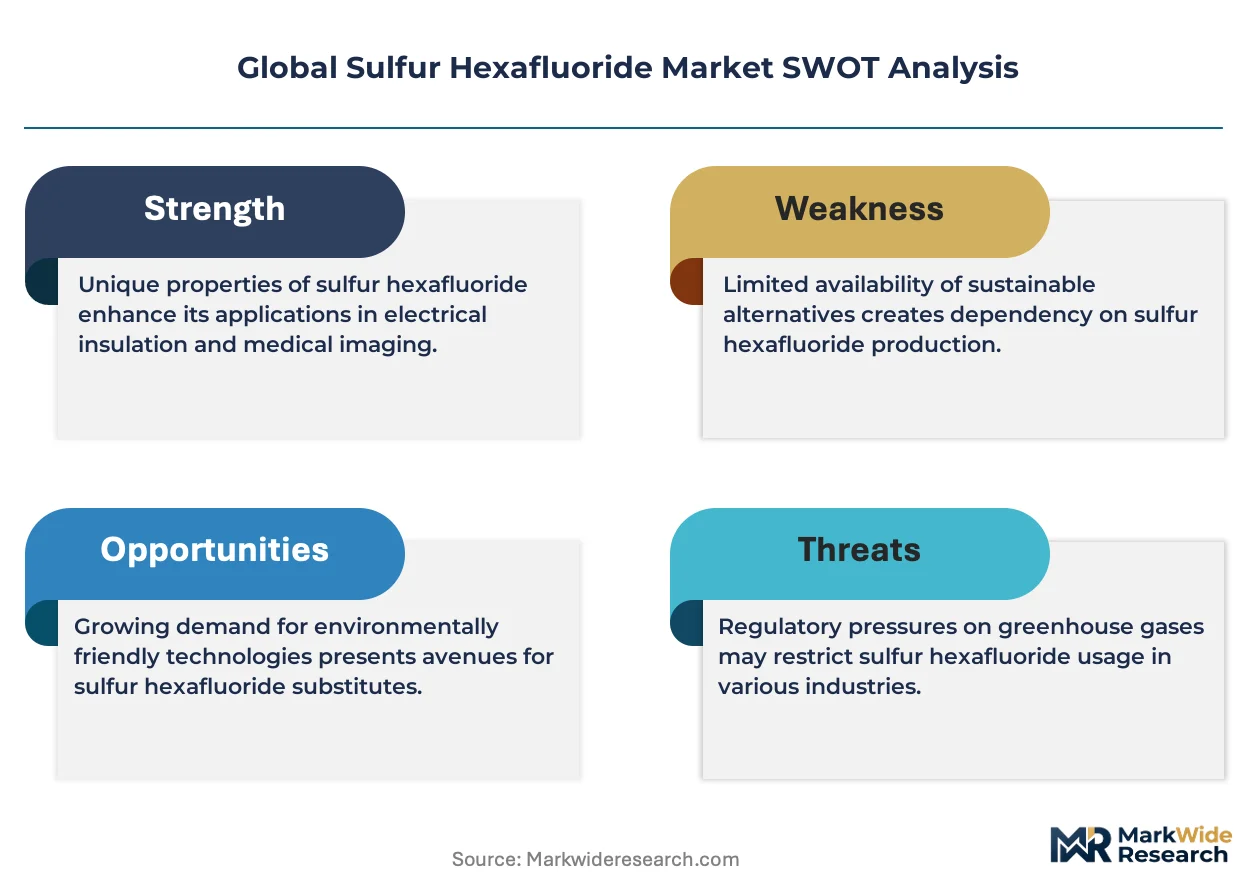
Single-source reliance on Chinese fluorite feedstock is repositioning procurement strategies across the sulfur hexafluoride value chain. Linde plc leverages captive fluorochemical production in Germany to sustain supply continuity for European power utilities. Solvay S.A. anchors its position through integrated sulfur processing and purification technology at Belgian manufacturing sites. Showa Denko K.K. competes on high-purity grades tailored to semiconductor etching requirements in East Asian fabrication facilities.
Sulfur hexafluoride is a synthetic inorganic compound with the chemical formula SF6, characterized by exceptional dielectric strength approximately 2.5 times that of air and thermal stability up to 500 degrees Celsius, manufactured through the direct fluorination of sulfur or electrolysis of hydrogen fluoride in the presence of sulfur. Its primary industrial purpose centers on electrical insulation and arc quenching in high-voltage switchgear, circuit breakers, and gas-insulated substations. The electricity transmission application dominates volume consumption as utilities replace oil-filled equipment with gas-insulated systems to reduce footprint and maintenance cycles. Specialty gas mixtures command premium positioning where semiconductor manufacturers require ultra-high purity blends for plasma etching processes in advanced node production. Bulk liquid packaging leads in utility procurement due to economies in large-scale GIS filling operations, while compressed gas cylinders serve distributed maintenance and scientific research segments with lower per-shipment volumes.
The EPA in the United States mandates comprehensive SF6 reporting under the Greenhouse Gas Reporting Program, compelling utilities to inventory leaks and track emissions from gas-insulated equipment installations. EMA and national regulators across Europe enforce the F-Gas Regulation's phased reduction quotas, restricting virgin SF6 placement on the market and elevating reclaimed gas values. China's MEE integrates SF6 within national carbon accounting frameworks under dual carbon policy implementation, tightening environmental compliance for power sector procurement. Stakeholders must monitor regulatory divergence between jurisdictions where the EU accelerates phase-down timelines while Asian markets prioritize grid reliability, creating divergent investment signals for production capacity and reclamation infrastructure.
Market Dynamics
Grid decarbonization mandates and ultra-high voltage transmission build-outs are restructuring sulfur hexafluoride demand patterns, forcing suppliers to balance volume commitments against tightening environmental compliance timelines.
Growth Catalysts
- Ultra-High Voltage Expansion:State Grid Corporation's transmission infrastructure investments in China are absorbing substantial SF6 volumes for gas-insulated switchgear and circuit breaker installations.
- F-Gas Phase-Down Mechanics:The EU F-Gas Regulation's reclamation quotas are elevating secondary gas values and incentivizing closed-loop recovery infrastructure across European utilities.
- Semiconductor Node Advancement:Plasma etching processes at sub-7nm fabrication facilities require ultra-high purity SF6 blends for precision dielectric removal.
Market Restraints
- Fluorite Feedstock Concentration:Chinese acid-grade fluorite dominates precursor supply, exposing processors to export licensing volatility and geopolitical friction.
- Technical Substitution Limits:No commercially viable alternative matches SF6's dielectric strength and thermal stability in compact GIS configurations.
- Carbon Accounting Integration:China's MEE embeds SF6 emissions within national dual carbon frameworks, constraining procurement flexibility for power sector buyers.
Strategic Opportunities
- Indian Grid Modernization:Power Grid Corporation's green corridor projects present untapped demand for gas-insulated substations as urban land scarcity intensifies.
- Reclamation Technology Convergence:Membrane separation and cryogenic distillation advances are enabling higher-yield gas recovery from decommissioned equipment.
- Industrial Gas Channel Innovation:Bulk micro-bulk delivery systems are displacing cylinder-based logistics for mid-scale semiconductor fabrication facilities.
Industry Challenges
- Certification Timeline Compression:IEC 62271-4 compliant handling and re-use certification cycles lag equipment replacement schedules, straining maintenance windows.
- Specialized Technician Scarcity:Trained personnel for leak detection, gas handling, and arc decomposition analysis remain concentrated in mature utility markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sulfur Hexafluoride Market |
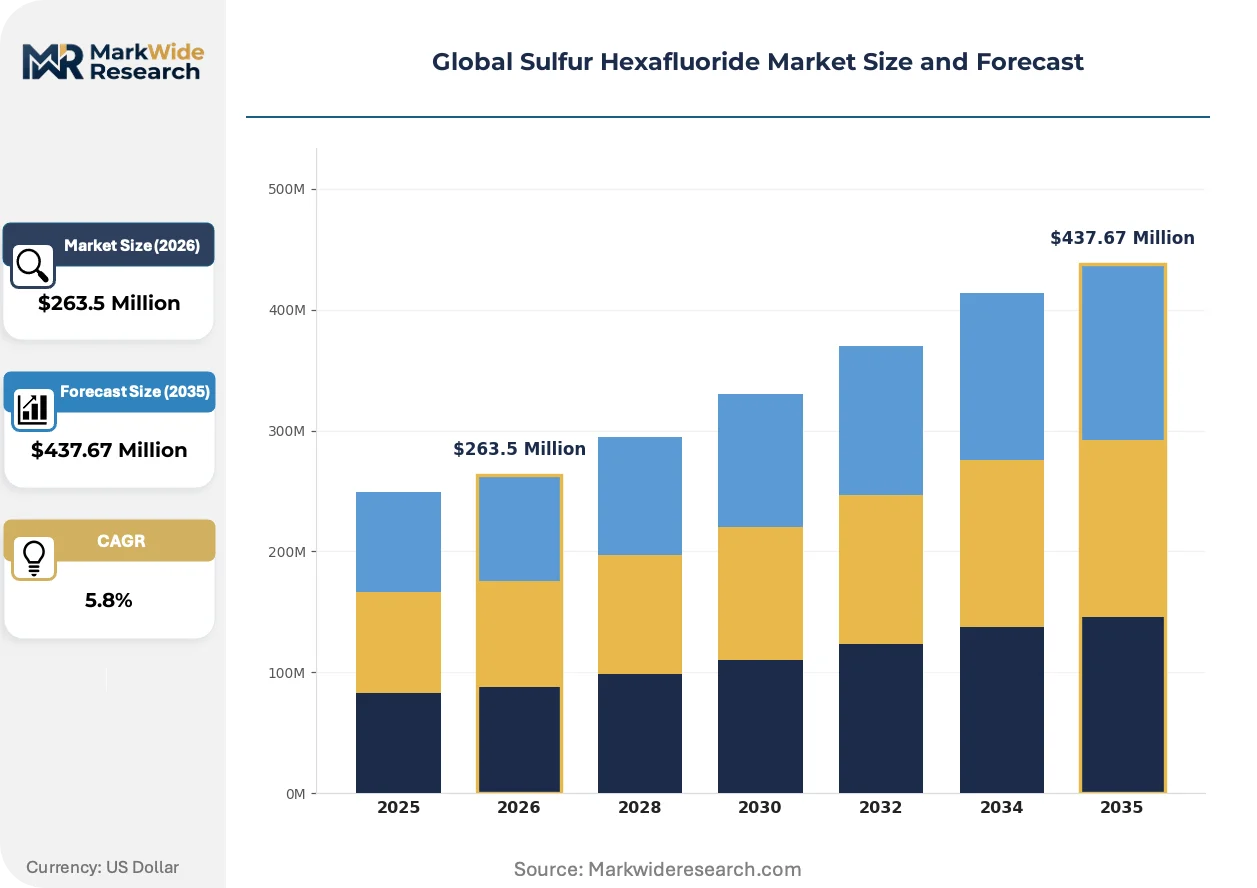
| Market Size in 2026 | $263.5 Million |
| Market Size in 2035 | $437.67 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Cylinders, Bulk Liquid, Compressed Gas, Specialty Gas Mixtures Application: Electricity Transmission, Medical Imaging, Semiconductor Manufacturing, Metal Production, Scientific Research End User: Power Utilities, Healthcare Providers, Electronics Manufacturers, Metallurgical Plants Packaging Type: Steel Cylinder, Composite Cylinder, Drum, Tanker Container, Micro Bulk |
| Companies Covered | Linde plc, Air Products and Chemicals, Inc., Solvay S.A., Air Liquide S.A., Showa Denko K.K., Matheson Tri-Gas, Inc., Fujian Shaowu Yongfei, Honeywell International Inc., Messer Group GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sulfur Hexafluoride Market Shifts & Advancements
Environmental compliance mechanisms and equipment lifecycle management practices are converging to reshape how sulfur hexafluoride circulates through industrial value chains.
Remote monitoring systems for gas-insulated switchgear are consolidating maintenance paradigms across transmission utilities. Sensors tracking pressure, temperature, and moisture enable predictive intervention rather than scheduled inspection. European operators are deploying these systems fastest, compressing service intervals and reducing unplanned outage exposure.
The EU F-Gas Regulation's 2024 tightening of virgin gas placement quotas is forcing reclamation infrastructure investment. Reclaimed SF6 now commands price parity with virgin material in several national markets. German and French utilities are securing long-term reclamation contracts to guarantee supply continuity under phase-down schedules.
Semiconductor manufacturers are unbundling gas supply from equipment service agreements, directly contracting with industrial gas specialists for purity-certified blends. This pattern is most pronounced in East Asian fabrication clusters, where foundries seek supply assurance independent of original equipment vendor relationships. Tier-one gas suppliers are responding with on-site purification and buffer storage installations.
Global Sulfur Hexafluoride Market Segmentation
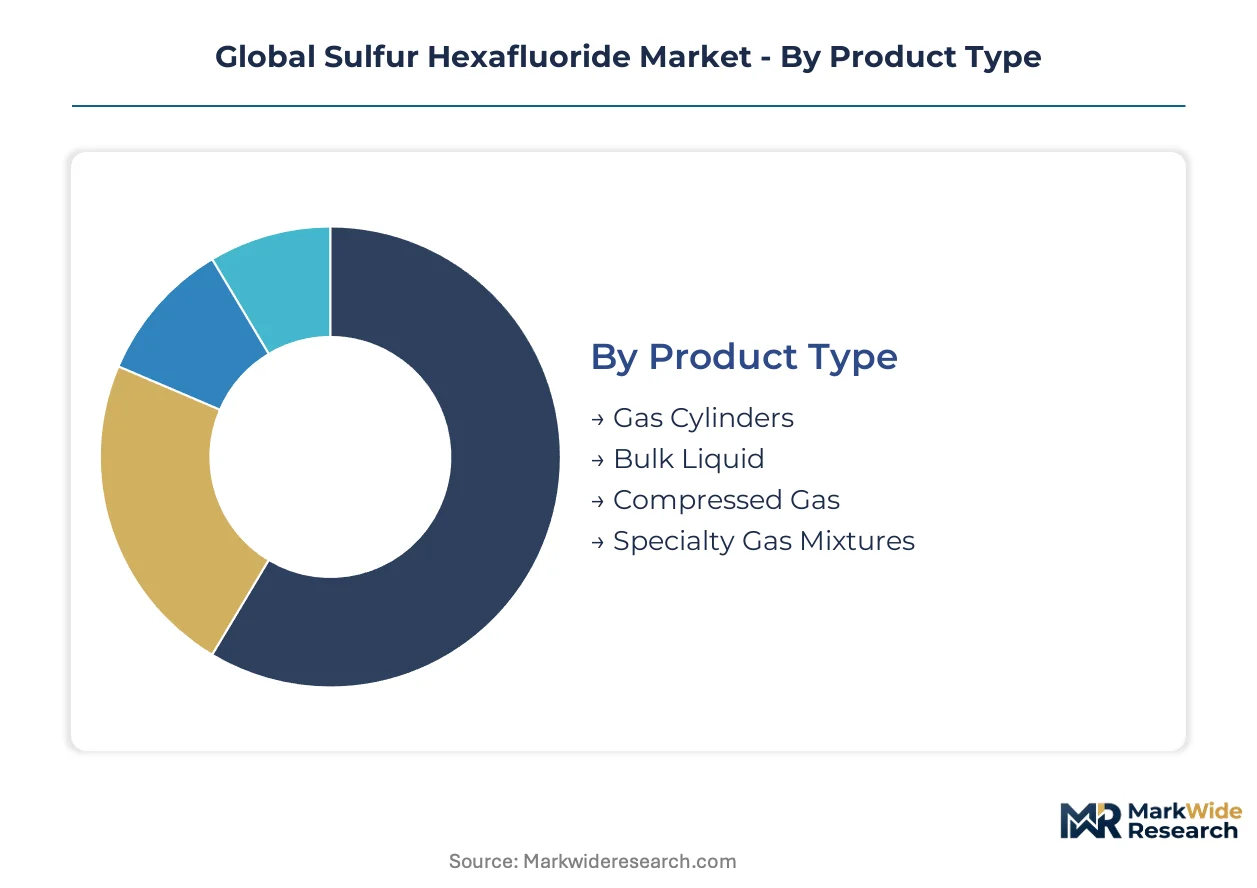
Sulfur hexafluoride segmentation reflects divergent supply chain economics between bulk utility procurement and precision semiconductor delivery. Each category captures distinct technical specifications, handling protocols, and customer concentration patterns that shape supplier positioning.
Product Type:
Packaging format determines integration depth — bulk liquid feeds centralized GIS filling stations while cylinder formats serve distributed maintenance and scientific applications.
- Bulk Liquid:Delivered in cryogenic tankers for direct transfer into gas-insulated switchgear at utility substations. State Grid Corporation's ultra-high voltage build-out in China absorbs the largest volumes through dedicated filling contracts.
- Specialty Gas Mixtures:Ultra-high purity blends formulated with precise impurity thresholds for plasma etching processes. Semiconductor fabrication facilities in Taiwan and South Korea specify these grades for sub-7nm node production.
- Gas Cylinders:Standard industrial packaging for maintenance top-ups and smaller-scale scientific applications.
- Compressed Gas:High-pressure storage format for field service operations requiring portability.
Bulk liquid leads volumes today; specialty gas mixtures are gaining share fastest.
Application:
End-use segmentation tracks the compound's functional versatility across electrical, medical, and precision manufacturing domains.
- Electricity Transmission:Dominant consumption channel centered on arc quenching and dielectric insulation in high-voltage circuit breakers and gas-insulated substations. European utilities under F-Gas Regulation quotas are accelerating reclamation investments to sustain supply.
- Semiconductor Manufacturing:Plasma etching applications demand contamination-controlled supply chains with on-site purification systems. East Asian foundries are unbundling gas procurement from equipment service agreements.
- Medical Imaging:Ultrasound contrast agent applications in ophthalmology and cardiology diagnostics.
- Metal Production:Magnesium casting operations utilizing SF6 as a cover gas to prevent oxidation.
- Scientific Research:Particle detector applications in high-energy physics facilities and tracer gas studies.
Electricity transmission commands absolute volume; semiconductor manufacturing shows steepest expansion trajectory.
End User:
Customer type segmentation reveals procurement sophistication gradients from integrated utility buyers to fragmented research institutions.
- Power Utilities:Long-term contract purchasers with dedicated gas handling infrastructure and certified reclamation partnerships. German transmission operators are securing multi-year reclaimed gas agreements under phase-down schedules.
- Electronics Manufacturers:Direct procurement from industrial gas specialists with purity certification requirements and buffer storage installations at fabrication sites.
- Healthcare Providers:Regulated medical gas users with strict sterility and traceability protocols.
- Metallurgical Plants:Process gas consumers in magnesium and aluminum casting operations.
Power utilities dominate procurement scale; electronics manufacturers are expanding contract volumes most rapidly.
Packaging Type:
Container engineering balances transport economics against gas integrity requirements across the value chain.
- Tanker Container:Cryogenic bulk transport for large-scale utility filling operations with dedicated logistics fleets.
- Micro Bulk:On-site storage systems displacing cylinder logistics for mid-scale semiconductor and research facilities.
- Steel Cylinder:Conventional high-pressure storage for maintenance and distributed applications.
- Composite Cylinder:Lightweight alternatives for field service mobility and reduced transport costs.
- Drum:Intermediate bulk format for specialty chemical handling and smaller industrial users.
Tanker containers move the greatest tonnage; micro bulk installations are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between jurisdictions is reshaping production footprints, with manufacturers relocating capacity toward regions where environmental compliance costs remain manageable while maintaining proximity to demand clusters.
China
State Grid Corporation's ultra-high voltage transmission build-out absorbs the largest SF6 volumes globally for gas-insulated switchgear installations. The MEE embeds sulfur hexafluoride within national dual carbon accounting frameworks, tightening procurement oversight for power sector buyers. Yangtze River Delta manufacturing clusters host integrated fluorochemical production serving both domestic utilities and export markets.
Germany
Transmission operators including TenneT and 50Hertz are securing multi-year reclaimed gas agreements to sustain supply under accelerating F-Gas Regulation phase-down schedules. The EU's 2024 tightening of virgin gas placement quotas elevates secondary gas values across German industrial gas markets. Bavarian chemical manufacturing sites anchor captive fluorochemical production for European power utility customers.
United States
EPA mandates under the Greenhouse Gas Reporting Program compel utilities to inventory leaks and track emissions from gas-insulated equipment installations nationwide. Grid modernization investments by utilities including Duke Energy and Southern California Edison sustain demand for high-voltage circuit breaker replacements. Gulf Coast petrochemical corridors concentrate bulk liquid packaging and distribution infrastructure.
Japan
Semiconductor fabrication facilities in Kyushu and the Kanto region specify ultra-high purity SF6 blends for sub-7nm plasma etching processes. METI oversight integrates industrial gas procurement within national technology security frameworks for advanced node production. Osaka-based industrial gas specialists maintain buffer storage installations at major foundry sites.
South Korea
Samsung Electronics and SK Hynix fabrication complexes in the Seoul Capital Area and Busan-Ulsan corridor drive specialty gas mixture demand for dielectric etching applications. MFDS regulations govern medical imaging applications where SF6 serves as an ultrasound contrast agent. Domestic industrial gas distributors are unbundling supply from equipment service agreements at semiconductor facilities.
Global Sulfur Hexafluoride Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue reclamation technology specialization and regional utility partnerships as differentiation vectors. The market structures around three tiers: integrated industrial gas conglomerates with captive fluorochemical production, regional packaging specialists serving maintenance segments, and technology-focused reclaimers extracting value from phase-down regulatory mechanics. Competitive moves concentrate on securing long-term utility reclamation contracts and deploying on-site purification systems at semiconductor fabrication clusters.
Among European-based industrial gas conglomerates, Linde plc and Solvay S.A. exemplify the integrated producer archetype with captive fluorochemical manufacturing and established utility relationships. Showa Denko K.K. represents the Asia-Pacific specialist tier, positioned to serve semiconductor purity requirements through regional production proximity. These three entities anchor competitive positioning across divergent regulatory environments where EU phase-down timelines contrast with Asian grid expansion priorities.
| Leading Market Players |
|---|
| Linde plc |
| Air Products and Chemicals, Inc. |
| Solvay S.A. |
| Air Liquide S.A. |
| Showa Denko K.K. |
| Matheson Tri-Gas, Inc. |
| Fujian Shaowu Yongfei |
| Honeywell International Inc. |
| Messer Group GmbH |
| Others |
Supply & Pricing Matrix
Chinese acid-grade fluorite export pricing cascades through sulfur hexafluoride value chains, compressing margins for processors lacking captive feedstock while elevating premiums for integrated producers serving European utilities under F-Gas Regulation reclamation quotas.
Pricing Analysis
Input-cost pass-through from fluorite concentrate and sulfur feedstocks dominates contract negotiations between industrial gas suppliers and power utilities. Three-tier pricing structure across virgin certified, reclaimed certified, and non-certified economy grades reflects purity certification and carbon-accounting compliance. Pricing pressure stems from EU F-Gas Regulation phase-down mechanics that elevate reclaimed gas values above virgin material in German and French markets. Power utilities exhibit lowest price sensitivity due to long-term supply continuity requirements, while mid-scale semiconductor fabricators face acute cost compression from unbundled procurement mandates.
Supply Chain Analysis
China's MEE domestic-content frameworks for strategic fluorochemicals are reshaping procurement patterns for non-integrated processors dependent on imported acid-grade fluorite. Geographic supply concentration centers on Chinese fluorite mining districts, German captive fluorochemical production at Linde and Solvay sites, and Japanese specialty gas purification facilities serving East Asian semiconductor clusters. Raw material dependencies span Mongolian and Mexican fluorite concentrates, elemental sulfur from Gulf Coast petrochemical corridors, and electrolytic hydrogen fluoride from integrated chemical complexes. Single-source vulnerability concentrates in Chinese acid-grade fluorite export licensing. Distribution runs through cryogenic tanker fleets for utility bulk delivery and cylinder-based logistics for maintenance and research segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in sulfur hexafluoride markets rests on reclamation infrastructure scale and premium-tier certification capture as environmental compliance costs shift procurement toward closed-loop recovery systems.
For Market Incumbents: Deepen reclamation technology investments to secure multi-year utility contracts under tightening EU F-Gas Regulation phase-down schedules. Expand membrane separation and cryogenic distillation capacity in Germany and France to capture elevated reclaimed gas premiums. Counter emerging entrant threats in Indian grid modernization by pre-positioning certified handling infrastructure ahead of Power Grid Corporation tender cycles. For New Entrants and Emerging Players: Enter via reclamation technology specialization targeting European utilities facing virgin gas placement quota restrictions. White-space opportunities concentrate in Indian gas-insulated substation maintenance contracts and mid-scale semiconductor fabrication buffer storage installations in South Korea. Pursue direct procurement relationships with foundries unbundling gas supply from equipment service agreements. For Investors and Strategic Acquirers: Asymmetric upside sits with reclamation technology specialists possessing IEC 62271-4 compliant certification infrastructure and established utility partnerships. Long-term viability over a multi-year horizon favors entities integrating backward into fluorochemical production or forward into on-site purification systems. Watch for inflection signals in Chinese MEE carbon accounting enforcement tightening and State Grid Corporation ultra-high voltage transmission budget allocations.| Strategic Initiative | Industry Significance |
|---|---|
| Reclamation Infrastructure Buildout | Captures premium pricing under EU F-Gas Regulation virgin gas placement quotas. |
| Backward Integration into Fluorite Processing | Insulates margins from Chinese export licensing volatility and feedstock concentration. |
| On-Site Purification System Deployment | Secures direct procurement relationships with Samsung Electronics and SK Hynix fabrication complexes. |
| Long-Term Reclaimed Gas Supply Agreements | Locks in TenneT and 50Hertz transmission operators under multi-year phase-down compliance schedules. |
| Indian Grid Modernization Partnership | Positions for Power Grid Corporation green corridor gas-insulated substation demand as urban land scarcity intensifies. |
Research Methodology
Direct dialogue with utility procurement directors, industrial gas supply chain managers, semiconductor fabrication facility engineers, and fluorochemical plant operators grounded primary intelligence, cross-referenced against customs trade data, EPA Greenhouse Gas Reporting Program filings, EU F-Gas Regulation compliance disclosures, and SEC 10-K industrial gas segment disclosures. Bottom-up and top-down triangulation validated volume estimates across packaging formats and end-use applications.
Bottom-up modeling aggregated segment-level consumption patterns by application, packaging type, and regional regulatory cluster, while top-down verification checked aggregate outputs against macro indicators including ultra-high voltage transmission build-out rates and semiconductor wafer start forecasts. CAGRs derived from fitted trend extrapolation across the projection horizon, with sensitivity testing around Chinese MEE enforcement intensity and EU phase-down acceleration scenarios. Industry-specific inputs incorporated gas-insulated switchgear installation pipelines and reclamation technology yield improvements.
The model holds under stable regulatory enforcement trajectories and continued grid modernization investment; deviation in Chinese dual carbon policy stringency or EU F-Gas Regulation timeline acceleration would shift supply-demand balances and price tier differentials. Forecasts embed assumptions regarding fluorite feedstock availability and reclamation infrastructure deployment rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Polypeptide Market
Specialty Compounds
Global Compound Management Market
Specialty Compounds
Methane Sulfonyl Chloride Market
Specialty Compounds
Potassium Hydrogen Sulphite Market
Specialty Compounds
Asia-Pacific Chromatography Resins Market
Specialty Compounds
Specialty Nitriles Market
Specialty Compounds
Strontium Chloride Market
Specialty Compounds
North America Polyphenylene Sulfide Compounds Market
Specialty Compounds
Chemical Synthesis Methyl Salicylate Market
Specialty Compounds
Pneumatic Seal Market
Specialty Compounds
Polypropylene Compounds Market
Specialty Compounds
China Collagen Market
Specialty Compounds
Gypsum-Free Plaster Market
Specialty Compounds
Dammar Gum Market
Specialty Compounds
Metasulphite Market
Specialty Compounds
Propoxylates Market