
 Global FCC Catalyst Market | 2026-2036
Global FCC Catalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Global FCC Catalyst Market Foresight
The International Maritime Organization's sulfur cap is shifting demand toward lower-sulfur gasoline blending components that FCC units must now produce. Albemarle Corporation leverages its integrated rare earth supply chain to sustain pricing power in zeolite formulations. BASF SE anchors its position through proprietary alumina-based catalyst platforms tailored for high-severity operations.
A fluid catalytic cracking catalyst is a microporous solid, typically containing Y-type faujasite zeolites in a silica-alumina matrix, engineered to crack heavy vacuum gas oil into lighter hydrocarbons at reactor temperatures between 480 and 540 degrees Celsius. Zeolite formulations dominate value capture due to their superior activity and selectivity toward gasoline-range products, while rare earth-doped variants are gaining traction as refiners chase higher propylene yields. Fluidized bed technology occupies the largest installed base, though hybrid systems are emerging as retrofit options for refineries seeking dual-mode gasoline and petrochemical output.
The US EPA Tier 3 gasoline sulfur standards and China's MEE emissions protocols are tightening product quality specifications, forcing catalyst suppliers to reformulate for deeper desulfurization. The EU F-Gas Regulation and REACH frameworks constrain certain binder chemistries, reshaping raw material sourcing for European supply chains. Stakeholders must monitor how carbon border adjustments and marine fuel sulfur rules cascade into FCC severity requirements and catalyst replacement cycles.
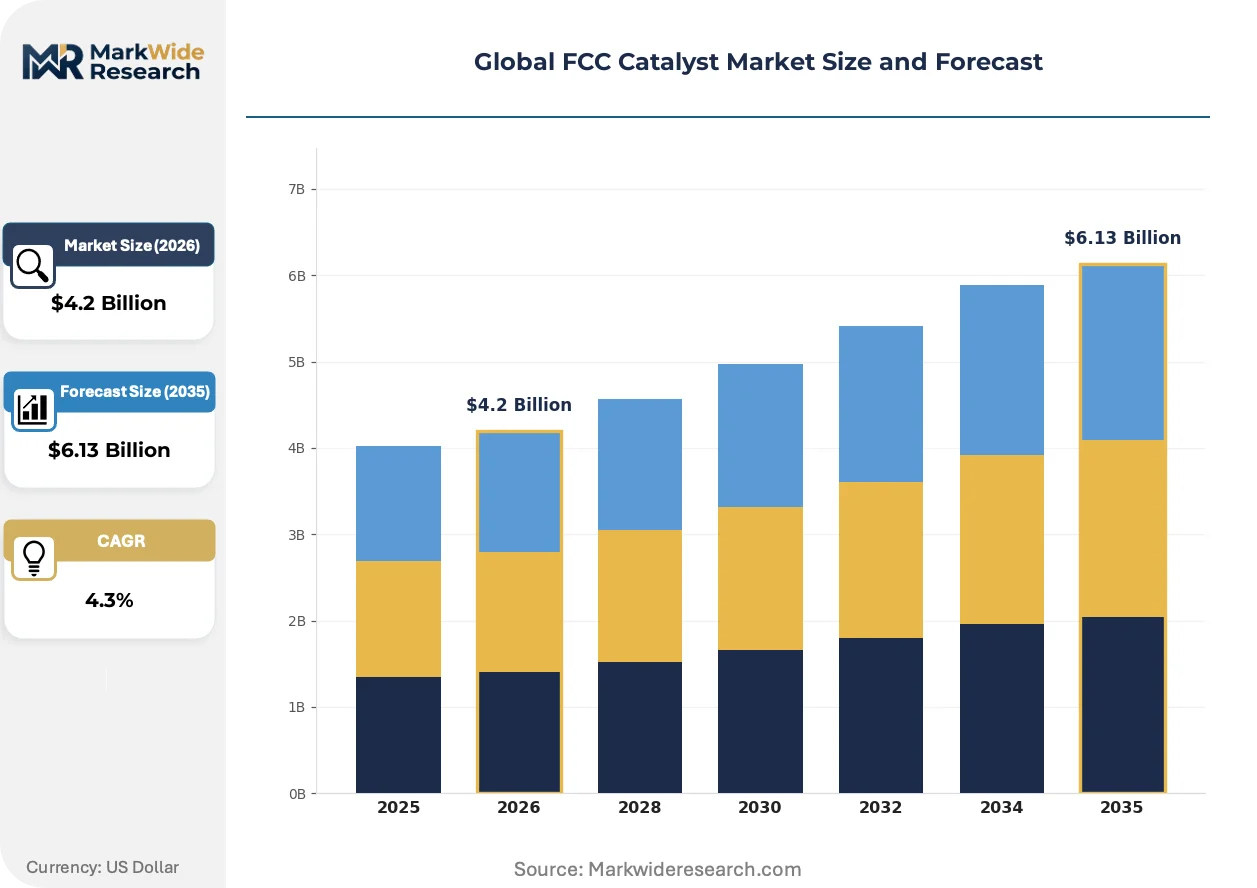
Market Dynamics
The FCC catalyst sector is reconfiguring around dual-output refinery economics, where propylene co-production margins now rival gasoline yields in investment calculations. Rare earth supply chain concentration and marine fuel sulfur regulations are compressing formulation flexibility and forcing accelerated catalyst replacement cycles across coastal refining clusters.
Growth Catalysts
- IMO sulfur caps:The International Maritime Organization's marine fuel standards are mandating deeper FCC desulfurization, expanding demand for high-activity zeolite formulations that cut gasoline sulfur to 10 ppm.
- India refinery expansion:Indian Oil Corporation and Reliance Industries are adding FCC capacity to process heavier domestic crude slates, creating pull for metals-tolerant catalyst platforms.
- Propylene yield optimization:Petrochemical integration at refineries in China and the Middle East is accelerating adoption of ZSM-5 additive systems for light olefin maximization.
Market Restraints
- Rare earth concentration:Lanthanum and cerium supply chains concentrate in Chinese processing facilities, exposing Western catalyst manufacturers to export quota volatility and price spikes.
- REACH compliance costs:The EU F-Gas Regulation and ECHA restrictions on perfluorinated binders are forcing European suppliers to reformulate matrix chemistries at elevated R&D expense.
- Alumina price volatility:Synthetic boehmite and pseudoboehmite feedstock costs fluctuate with bauxite mining output in Guinea and Australia, compressing catalyst gross margins.
Strategic Opportunities
- Bio-feedstock adaptation:Co-processing vegetable oils and pyrolysis liquids in FCC units requires new catalyst acid site distributions, opening formulation white space for suppliers with biorefinery partnerships.
- Saudi petrochemical integration:SABIC and Saudi Aramco are building resid FCC complexes for chemicals-only output, creating demand for maximum-propylene catalyst architectures.
- Carbon border adjustments:The EU CBAM is incentivizing low-carbon catalyst production methods, rewarding suppliers with renewable energy-integrated manufacturing in Norway and Iceland.
Industry Challenges
- Computational catalyst design talent:Molecular simulation expertise for zeolite framework optimization is scarce, forcing suppliers to compete for computational materials scientists against semiconductor and battery sectors.
- Retrofit integration complexity:Hybrid FCC systems combining fluidized bed and riser reactor technologies require custom catalyst formulations that delay qualification timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global FCC Catalyst Market |
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $6.13 Billion |
| CAGR (2026 – 2036) | 4.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Zeolite, Alumina-Based, Rare Earth, Clays, Mixed Metal Oxides Technology: Fluidized Bed, Moving Bed, Circulating Catalyst, Hybrid Systems Application: Petroleum Refining, Petrochemical Production, Gasoline Upgrading, Petrochemical Feedstock Preparation End User: Refineries, Chemical Plants, Lubricants Manufacturers, Specialty Chemicals Producers |
| Companies Covered | Albemarle Corporation, W. R. Grace & Co.-Conn, BASF SE, Sinopec Catalyst Company, Clariant International Ltd, Honeywell UOP, Axens, Johnson Matthey, ExxonMobil Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global FCC Catalyst Market Shifts & Advancements
Formulation science is converging with digital twin modeling to compress catalyst development cycles. Suppliers are embedding sensors in commercial units to capture real-time deactivation data, closing the loop between field performance and R&D priorities.
Dual-function catalyst architectures are unifying gasoline octane enhancement with propylene selectivity in single-particle designs. Sinopec and PetroChina are piloting these systems at scale in Shandong and Guangdong provinces. The technology is compressing the traditional trade-off between transportation fuel and petrochemical economics, enabling swing production based on real-time margin signals.
The EU Green Deal's carbon intensity benchmarks are forcing European refiners to document catalyst-related Scope 3 emissions. BASF and Albemarle are responding with life-cycle assessment certifications for their alumina and zeolite supply chains. German and Dutch refineries now require supplier-specific carbon footprints as procurement gate criteria.
Refinery technical service contracts are unbundling catalyst supply from performance guarantees. Indian and Southeast Asian operators are adopting separate procurement streams for initial catalyst loads versus subsequent makeup rates. This shift is visible most acutely in Mumbai and Singapore trading hubs, where spot purchasing of zeolite additives is displacing long-term single-source agreements.
Global FCC Catalyst Market Segmentation
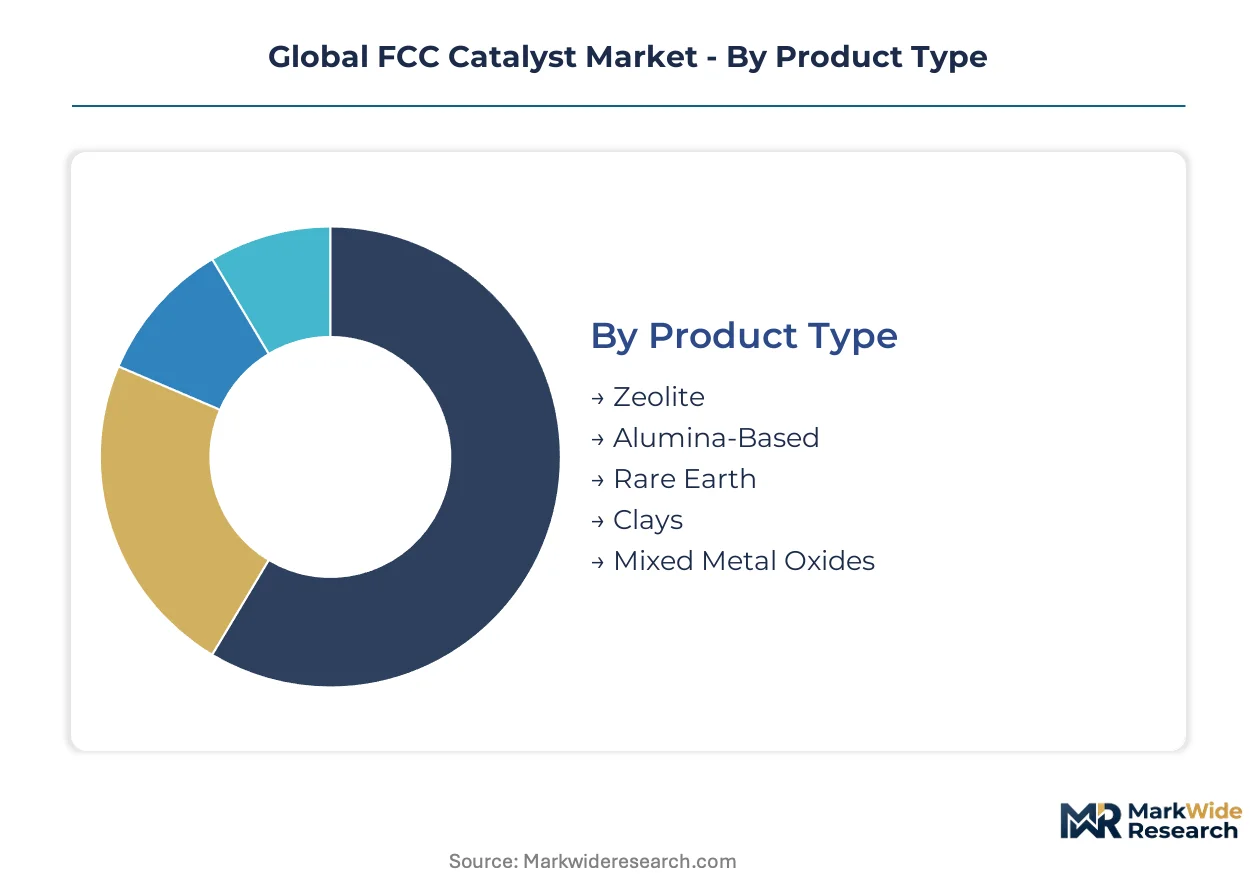
Segmentation in the FCC catalyst market reveals divergent capital requirements and technical specifications across product architectures. Refinery operators select catalyst platforms based on crude slate heaviness, product slate flexibility, and integration with existing reactor configurations.
Product Type:
Zeolite formulations demand the highest upfront capital investment due to rare earth doping requirements and precision synthesis infrastructure. Alumina-based platforms require moderate investment in boehmite precursor facilities. Clay and mixed metal oxide systems carry lower entry barriers but sacrifice performance margins.
- Zeolite:Y-type faujasite frameworks dominate commercial formulations, with rare earth exchange sites controlling acid strength and hydrothermal stability. Indian Oil Corporation and Reliance Industries specify these for heavy crude processing at their Gujarat and Jamnagar complexes, where metals tolerance justifies premium procurement costs.
- Rare Earth:Lanthanum and cerium-doped variants command formulation premiums for propylene maximization. Sinopec's Shandong refineries are accelerating adoption of these systems as petrochemical integration deepens, though Chinese export quotas on processed rare earths expose buyers to supply volatility.
- Alumina-Based:Synthetic boehmite matrices anchor BASF's high-severity platforms for European refiners facing EU F-Gas Regulation constraints on alternative binder chemistries.
- Clays:Kaolin-derived binders serve cost-sensitive operators in Southeast Asian spot markets with shorter catalyst replacement cycles.
- Mixed Metal Oxides:ZSM-5 additive systems for light olefin production are gaining traction in Saudi Aramco's resid FCC complexes targeting chemicals-only output.
Most installed capacity flows through Zeolite. Expansion is steepest in Rare Earth.
Technology:
Technology selection tracks refinery vintage and retrofit economics, with fluidized bed systems representing sunk-cost infrastructure and hybrid architectures capturing newbuild investment. Moving bed and circulating catalyst technologies occupy niche positions in specialized processing configurations.
- Fluidized Bed:The dominant installed base leverages riser-reactor designs with continuous catalyst regeneration. Coastal refining clusters in Rotterdam and Singapore rely on these systems for marine fuel sulfur compliance under IMO standards, where catalyst replacement cycles have compressed by 30% since sulfur cap implementation.
- Hybrid Systems:Dual-mode fluidized and fixed-bed configurations enable swing production between gasoline and petrochemical economics. PetroChina's Guangdong installations are piloting these architectures, though qualification timelines extend 18-24 months due to custom formulation requirements.
- Moving Bed:Reserved for resid processing at complex refineries with dedicated heavy oil upgrading trains.
- Circulating Catalyst:Compact footprints suit remote or capacity-constrained sites in Australia's Kwinana and Geelong refining hubs.
Fluidized Bed retains the largest operating base. Hybrid Systems are climbing the fastest as petrochemical integration accelerates.
Application:
Application segmentation reflects margin structure divergence between transportation fuels and chemical feedstocks. Petroleum refining remains volume-dominant while petrochemical production commands premium pricing for propylene-selective formulations.
- Petroleum Refining:Vacuum gas oil cracking to gasoline and middle distillates represents the foundational use case. US EPA Tier 3 sulfur standards and China's MEE protocols are forcing deeper desulfurization, expanding demand for high-activity zeolite systems that achieve 10 ppm gasoline sulfur.
- Petrochemical Production:Propylene and light olefin maximization now rivals gasoline yields in investment calculations. SABIC's Yanbu and Jubail complexes are specifying maximum-propylene catalyst architectures as Saudi Arabia builds chemicals-only resid FCC capacity.
- Gasoline Upgrading:Octane enhancement via ZSM-5 additives serves US Gulf Coast refiners processing tight oil feedstocks with high paraffin content.
- Petrochemical Feedstock Preparation:Pre-treatment catalysts for steam cracker naphtha supply are emerging at integrated sites in South Korea's Yeosu and Ulsan industrial zones.
Petroleum Refining absorbs the majority of catalyst volume. Petrochemical Production is gaining share fastest as refinery-petrochemical integration deepens.
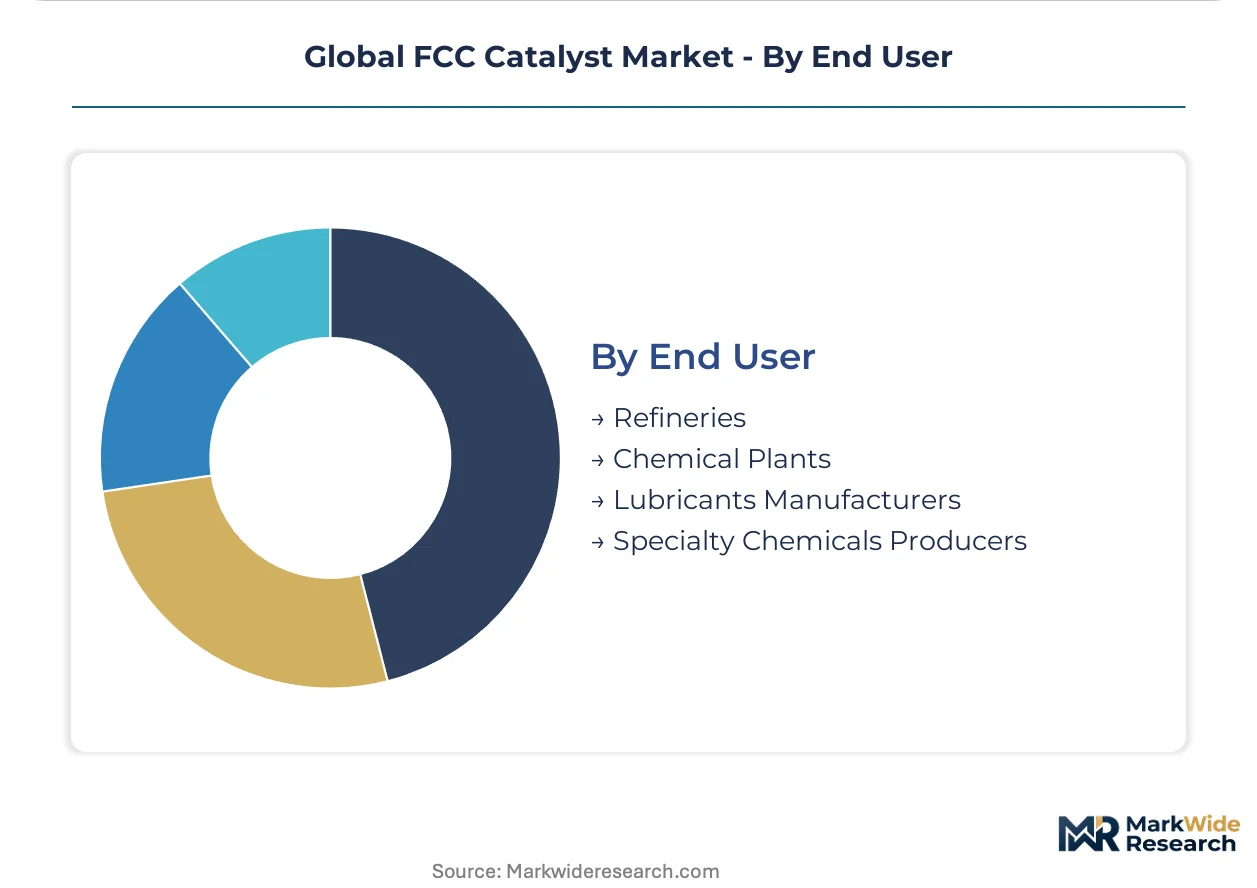
End User:
End user segmentation tracks procurement sophistication, with integrated refiners negotiating performance guarantees and specialty chemical producers demanding custom formulation services. Lubricants manufacturers represent a contracting niche as base oil production shifts to hydroprocessing routes.
- Refineries:Integrated operators like Indian Oil Corporation and Reliance Industries unbundle catalyst supply from technical service contracts, adopting separate procurement streams for initial loads versus makeup rates at Mumbai and Singapore trading hubs.
- Chemical Plants:Petrochemical producers in China's Ningbo and Zhenhai clusters require ZSM-5 additive systems with precise acid site distributions for light olefin selectivity control.
- Lubricants Manufacturers:Declining FCC-based base oil production limits this segment to legacy operations in Russia and select Central European facilities.
- Specialty Chemicals Producers:Custom zeolite synthesis for fine chemical applications commands formulation premiums at German and Swiss specialty chemical sites.
Refineries represent the dominant procurement base. Chemical Plants are expanding most quickly as petrochemical integration reshapes investment priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fluid catalytic cracking technology originated in the United States during the 1940s petroleum boom, establishing the Gulf Coast as the foundational region for catalyst manufacturing expertise. This historical lineage now distributes across refining clusters in China, India, Saudi Arabia, and the Netherlands where capacity expansion and regulatory pressure reshape demand patterns.
United States
US refiners process tight oil feedstocks with high paraffin content, requiring ZSM-5 additive systems for octane enhancement. EPA Tier 3 gasoline sulfur standards mandate 10 ppm sulfur ceilings, compressing catalyst replacement cycles at Gulf Coast facilities. The Houston-Beaumont-Port Arthur refining corridor hosts concentrated FCC capacity where operators unbundle catalyst procurement from technical service contracts.
China
Sinopec and PetroChina are modernizing aging FCC installations across Shandong and Guangdong provinces to process heavier crude slates. MEE emissions protocols tighten product quality specifications, forcing suppliers to reformulate for deeper desulfurization. The Ningbo-Zhenhai petrochemical cluster drives demand for ZSM-5 additive systems with precise acid site distributions for light olefin selectivity control.
India
Indian Oil Corporation and Reliance Industries are adding FCC capacity to process heavier domestic crude slates, creating pull for metals-tolerant catalyst platforms. The country's PLI scheme for petroleum product quality upgrades accelerates refinery modernization timelines. The Gujarat and Jamnagar complexes specify rare earth-doped zeolite formulations where metals tolerance justifies premium procurement costs.
Saudi Arabia
SABIC and Saudi Aramco are building resid FCC complexes for chemicals-only output, creating demand for maximum-propylene catalyst architectures. The national regulator enforces product quality specifications aligned with export market requirements. The Yanbu and Jubail complexes anchor petrochemical integration investments where propylene yields now rival gasoline economics in investment calculations.
Netherlands
Rotterdam's coastal refining cluster relies on fluidized bed systems for marine fuel sulfur compliance under IMO standards. The EU F-Gas Regulation and REACH frameworks constrain certain binder chemistries, reshaping raw material sourcing for European supply chains. German and Dutch refineries now require supplier-specific carbon footprints as procurement gate criteria under EU Green Deal benchmarks.
Global FCC Catalyst Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the FCC catalyst sector, creating a tiered structure where integrated rare earth processors hold pricing power against formulation specialists. The market consolidates around three strategic archetypes: integrated chemical conglomerates with captive zeolite synthesis, rare earth processors with backward integration into mining, and regional specialists serving spot markets. Competitive moves center on biorefinery partnerships for bio-feedstock adaptation and renewable energy-integrated manufacturing to satisfy EU carbon border adjustments.
Within the integrated chemical conglomerate tier, Albemarle Corporation represents rare earth supply chain integration, BASF SE anchors high-severity platform development, and Sinopec Catalyst Company exemplifies state-backed vertical consolidation. These three occupy positions spanning Atlantic, European, and Asia-Pacific supply corridors respectively. Regional specialists including W. R. Grace and Clariant International sit within formulation-intensive segments where technical service capabilities differentiate procurement decisions.
| Leading Market Players |
|---|
| Albemarle Corporation |
| W. R. Grace & Co.-Conn |
| BASF SE |
| Sinopec Catalyst Company |
| Clariant International Ltd |
| Honeywell UOP |
| Axens |
| Johnson Matthey |
| ExxonMobil Chemical Company |
| Others |
Supply & Pricing Matrix
Sovereign-backed producers in China anchor rare earth supply chains, compressing formulation flexibility for Western catalyst manufacturers while concentrating pricing power among integrated mining-to-chemical conglomerates. This ownership pattern forces independent formulators to absorb lanthanum and cerium price spikes or reformulate matrix chemistries at elevated R&D expense.
Pricing Analysis
Three-tier pricing structure across premium rare earth-doped zeolites, standard alumina-based platforms, and economy clay binders separates procurement tiers by metals tolerance and propylene selectivity. Price differentiation hinges on rare earth loading levels and IMO sulfur compliance certification, with coastal refiners least sensitive due to marine fuel margin premiums and Southeast Asian spot buyers most vulnerable to volatility. Cost compression in standard alumina tiers is intensifying because bauxite supply disruptions in Guinea and Australia feed synthetic boehmite price instability.
Supply Chain Analysis
Dual-sourcing requirements from Indian and European refiners mandate multi-supplier qualification for rare earth-doped zeolites, fragmenting procurement across Albemarle, Sinopec Catalyst, and BASF to mitigate Chinese export quota exposure. Geographic supply concentration centers on China for rare earth processing, Germany for alumina precursor synthesis, and India for kaolin-derived binders. Raw material dependencies encompass lanthanum/cerium oxides, synthetic boehmite, and perfluorinated binder chemistries constrained by REACH. Single-source vulnerability in Chinese rare earth separation facilities threatens Western catalyst gross margins. Distribution runs through Rotterdam and Singapore trading hubs serving coastal refining clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FCC catalyst market functions as a stable compounder anchored by regulatory mandates for marine fuel sulfur compliance and transportation fuel quality upgrades that sustain replacement cycle visibility.
For Market Incumbents: To counter rare earth supply concentration, secure backward integration into Australian or North American rare earth mining partnerships, and anchor capacity addition in Norway or Iceland to satisfy EU carbon border adjustment criteria for low-carbon zeolite production. For New Entrants and Emerging Players: Enter via bio-feedstock co-processing catalyst formulations for European biorefinery partnerships, targeting the white space in vegetable oil and pyrolysis liquid FCC unit adaptation where incumbents lack qualified acid site distribution architectures. For Investors and Strategic Acquirers: Valuations sit cheapest among regional formulation specialists with technical service capabilities but without captive rare earth supply, offering acquisition exposure to petrochemical integration tailwinds in Saudi Arabia and China. Watch SABIC and Saudi Aramco resid FCC procurement timelines as the inflection signal for maximum-propylene catalyst demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Rare Earth Supply Agreement | Secures lanthanum and cerium oxide streams against Chinese export quota volatility for Western formulators. |
| Biorefinery Partnership | Opens formulation white space for vegetable oil and pyrolysis liquid co-processing at EU Green Deal-aligned sites. |
| Carbon-Neutral Manufacturing Certification | Qualifies zeolite supply chains for EU CBAM procurement gate criteria at Rotterdam and German refineries. |
| Dual-Function Catalyst Launch | Unifies gasoline octane enhancement with propylene selectivity for swing production at PetroChina Guangdong installations. |
| Technical Service Unbundling | Captures spot purchasing demand from Indian Oil Corporation and Reliance Industries at Mumbai trading hub. |
Research Methodology
Direct dialogue with refinery operations managers, catalyst procurement leads at integrated oil companies, technical R&D directors at formulation suppliers, and marine fuel compliance officers grounded qualitative assessments in operational reality. Secondary validation drew from EPA Tier 3 regulatory filings, ECHA REACH substance restrictions, IMO sulfur cap implementation reports, and customs data on rare earth oxide trade flows. Bottom-up unit economics and top-down sector sizing were triangulated against refinery capacity databases and catalyst replacement cycle surveys.
Bottom-up modeling tracked individual FCC unit configurations across petroleum refining and petrochemical production applications, while top-down analysis validated aggregate demand against regional refinery throughput and regulatory compliance timelines across the projection horizon. Segmentation dimensions encompassed zeolite formulation grade, reactor technology vintage, crude slate heaviness, and propylene yield target. CAGRs were derived from regression analysis of historical catalyst consumption against FCC capacity additions and replacement frequency shifts. Industry-specific inputs included rare earth oxide price indices and marine fuel sulfur differential margins.
Inputs from refinery procurement databases and catalyst supplier technical disclosures were available through the study window; gaps in real-time deactivation sensor data from commercial units introduce uncertainty bands around performance guarantee pricing models. Deviation in IMO sulfur enforcement stringency or Chinese rare earth export policy would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Residue Hydrodesulphurization Catalyst Market
Catalysts
North America Refining Catalysts Market
Catalysts
Asia and Middle East FCC Catalyst Market
Catalysts
Asia and Middle East Polyolefin Catalyst Market
Catalysts
Precious Metal Catalysts Market
Catalysts
Polyolefin Catalyst Market
Catalysts
Oxalate Hydrogenation Catalyst Market
Catalysts
Photocatalyst Market
Catalysts
Global Catalyst Market
Catalysts
Steam Methane Reforming Market
Catalysts
Global Polypropylene Catalyst Market
Catalysts
Primary Reforming Catalyst Market
Catalysts
Platinum and Palladium Carbon Catalyst Market
Catalysts
Biodiesel Catalyst Market
Catalysts
Platinum-Based Catalysts Market
Catalysts
Aluminum-Nickel Catalyst Market