
 Platinum-Based Catalysts Market | 2026-2036
Platinum-Based Catalysts Market Size, Share, and Industry Trends Forecast 2026-2036
Platinum-Based Catalysts Market Analysis
The automotive sector is recalibrating its platinum consumption profile as hydrogen fuel cell electric vehicles gain traction alongside evolving catalytic converter requirements. BASF SE leverages its integrated precious metals refining and catalyst manufacturing footprint to maintain supply security for European automakers. Johnson Matthey anchors its position through deep R&D intensity in proton exchange membrane fuel cell electrocatalysts. Heraeus Precious Metals competes by controlling closed-loop recycling channels that lower net platinum procurement costs for industrial buyers.
Platinum-based catalysts comprise metallic platinum or platinum alloy particles dispersed on high-surface-area supports such as alumina, ceria-zirconia, or carbon black, typically manufactured through impregnation, precipitation, or vapor deposition routes to achieve controlled particle sizes of 1-5 nanometers for optimal catalytic activity. These materials accelerate chemical reactions without being consumed, serving critical functions in emissions control, hydrogen production, and fine chemical synthesis. Heterogeneous catalysts dominate current revenue given their entrenched role in automotive catalytic converters and petrochemical crackers, while electrocatalysis represents the fastest-expanding technology segment as fuel cell and electrolyzer deployments scale. Supported catalysts command premium pricing due to the engineering precision required in particle dispersion and thermal stability, whereas bulk catalyst applications in oil refining constitute a mature, volume-driven category with thinner margins.
The EPA and NHTSA in the United States, alongside the EU Green Deal and REACH framework in Europe, are tightening permissible emissions thresholds and chemical substance registration requirements that directly influence platinum loading specifications and catalyst replacement cycles. Japan's METI has established hydrogen supply chain targets that accelerate domestic platinum demand for electrolyzer stacks and fuel cell systems. Stakeholders must monitor regulatory divergence between jurisdictions on precious metals content mandates and carbon intensity benchmarks to anticipate where catalyst formulation investments will yield durable competitive advantage.
Market Dynamics
Automotive OEMs are recalibrating platinum loading specifications as hydrogen fuel cell stacks displace incremental catalytic converter demand, while electrolyzer manufacturers scale proton exchange membrane capacity. This demand bifurcation is compressing legacy refining margins and accelerating electrocatalyst specialization.
Growth Catalysts
- EU Green Deal tailpipe mandates:Tightening nitrogen oxide thresholds in Germany, France, and Italy are extending catalyst replacement cycles and increasing platinum loading per vehicle for compliance.
- Japan METI hydrogen supply chain targets:Domestic electrolyzer manufacturing subsidies are concentrating platinum offtake for polymer electrolyte membrane stack production.
- Fuel cell bus deployment in South Korea:Gyeonggi Province and Seoul Metropolitan Government procurement programs are anchoring stationary and mobility fuel cell catalyst demand.
Market Restraints
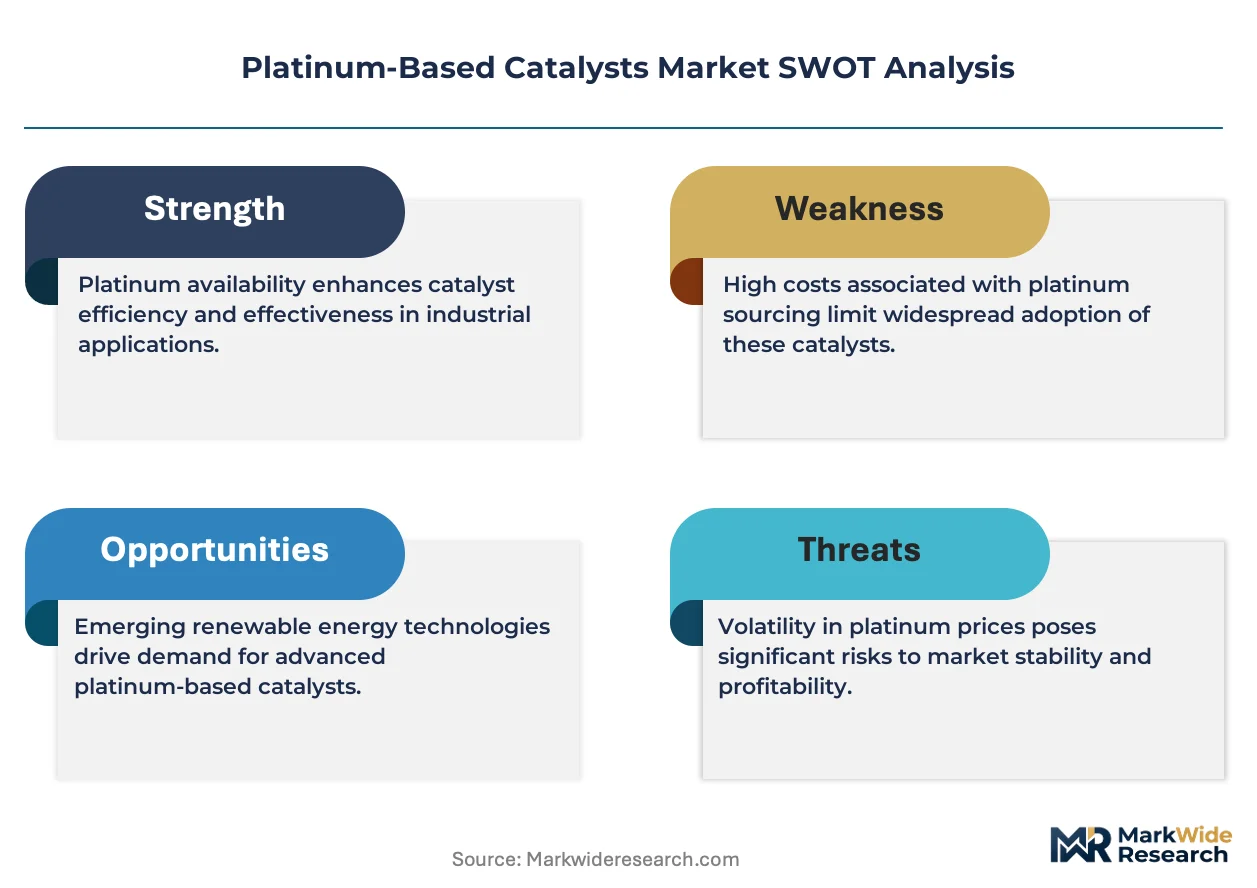
- Palladium-rhodium substitution in gasoline catalytic converters:Three-way catalyst formulations are reducing platinum intensity in light-duty gasoline applications.
- Russian and South African supply concentration:Primary platinum mining geographic clustering creates concentrate availability risk for European and Asian refiners.
- REACH substance registration friction:Extended authorization timelines for novel platinum alloy compositions delay commercialization of next-generation electrocatalysts.
Strategic Opportunities
- India electrolyzer manufacturing scale-up:National Hydrogen Mission targets and PLI scheme incentives are creating captive catalyst demand for domestic stack production.
- Closed-loop recycling channel control:Automotive catalyst collection networks in Germany and Japan enable secondary platinum supply security for fuel cell manufacturers.
- Green hydrogen export hub development:Saudi Arabia NEOM and Oman hydrogen projects are concentrating electrolyzer catalyst procurement for gigawatt-scale installations.
Industry Challenges
- Electrocatalyst synthesis skill scarcity:Thin-film deposition and particle size control expertise shortages constrain fuel cell stack manufacturing expansion.
- Membrane electrode assembly certification timelines:Extended durability testing protocols for automotive fuel cell applications delay product qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Platinum-Based Catalysts Market |
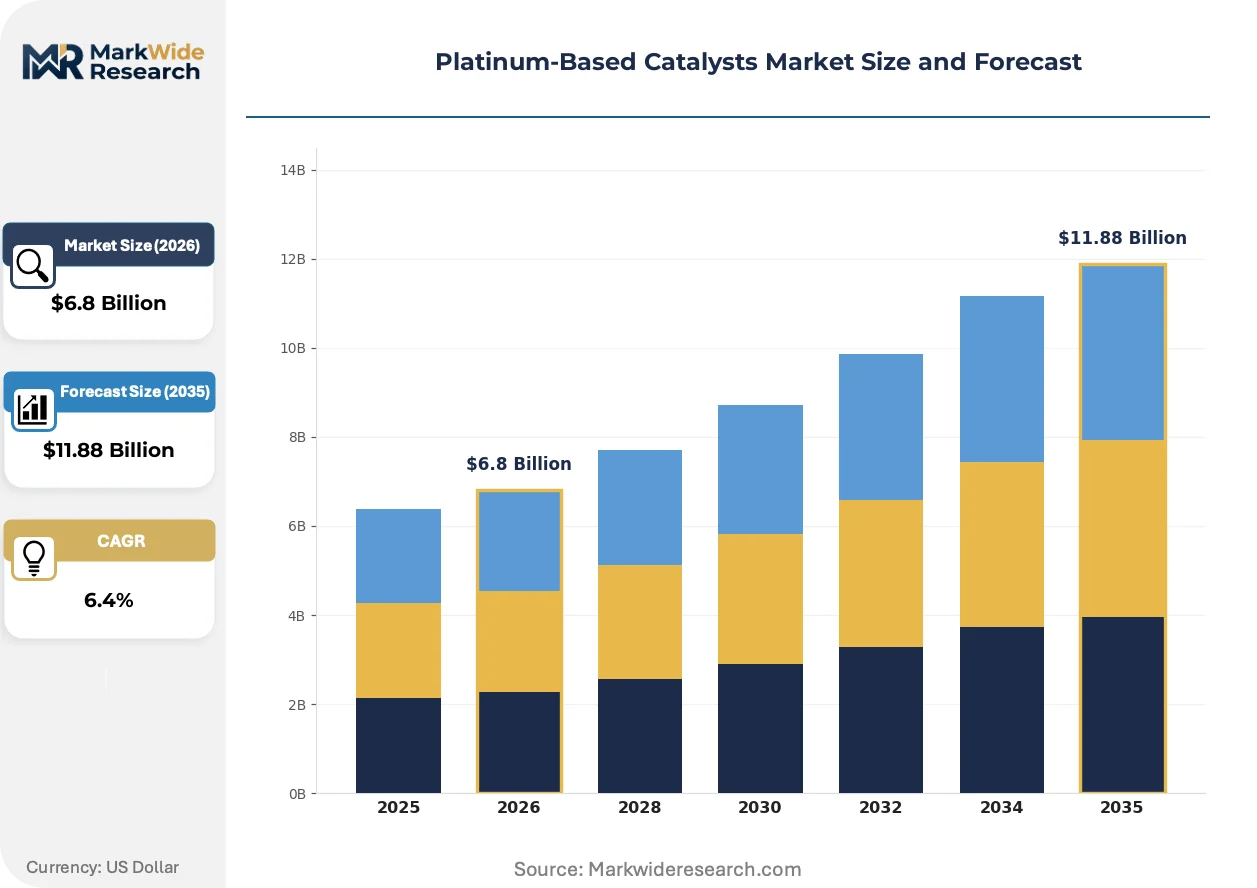
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Homogeneous Catalysts, Heterogeneous Catalysts, Supported Catalysts, Bulk Catalysts End User: Chemical Industry, Automotive Sector, Oil Refining, Pharmaceutical Sector Application: Petrochemical Production, Hydrogenation Reactions, Fuel Cells, Catalytic Converters Technology: Electrocatalysis, Photocatalysis, Thermal Catalysis, Bio-catalysis |
| Companies Covered | BASF SE, Johnson Matthey, Heraeus Precious Metals, Evonik Industries AG, Umicore, TANAKA Precious Metals, Clariant AG, Albemarle Corporation, Haldor Topsoe A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Platinum-Based Catalysts Market Emerging Trajectories
Platinum-based catalyst manufacturing is pivoting from homogeneous batch processes toward precision electrocatalyst architectures. Formulation science and deposition control are converging to meet fuel cell stack performance thresholds.
Platinum-cobalt alloy nanoparticles on carbon supports are integrating into high-performance fuel cell cathodes. Automotive OEMs in Germany and Japan are qualifying these materials for next-generation stack designs. This integration is compressing development cycles for proton exchange membrane systems and displacing lower-activity pure platinum catalysts in premium applications.
REACH authorization requirements for persistent organic pollutants are tightening impurity specifications in catalyst precursor chemicals. European refiners are retrofitting purification trains to meet ECHA substance restriction thresholds. Electrocatalyst manufacturers sourcing from German precious metals traders are absorbing compliance costs through formulation redesign rather than supply chain relocation.
Long-term offtake agreements are displacing spot market procurement for electrolyzer stack manufacturers. Korean and Japanese energy conglomerates are locking platinum supply through multi-year contracts with integrated refiners. This contracting pattern is most visible in hydrogen hub developments where project finance requirements mandate feedstock price certainty.
Platinum-Based Catalysts Market Segmentation
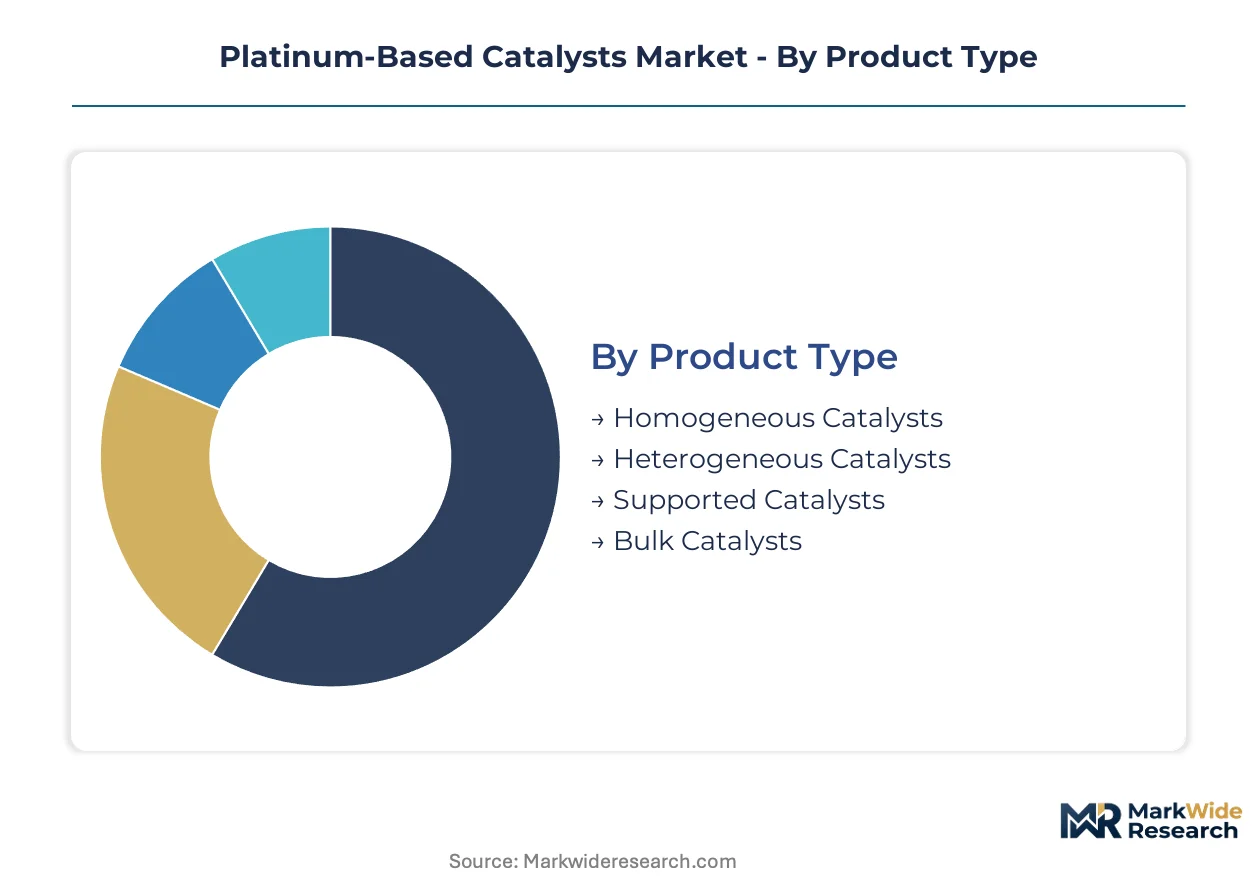
Platinum-based catalysts exhibit divergent capital requirements across product architectures, with supported and electrocatalyst variants demanding precision manufacturing infrastructure while bulk applications run on commodity-scale assets. End-use concentration in automotive and hydrogen systems is reshaping segment prioritization for catalyst producers.
Product Type:
Capital intensity varies sharply across manufacturing modalities, with particle dispersion control and thermal stability engineering driving upfront investment thresholds.
- Heterogeneous Catalysts:Solid-phase platinum particles dispersed on oxide or carbon supports enable facile separation from reaction mixtures. Automotive catalytic converter demand in Germany and Japan anchors volume, though palladium substitution in gasoline three-way catalysts is compressing platinum loadings per unit.
- Supported Catalysts:Engineered architectures with 1-5 nanometer platinum particles on high-surface-area alumina, ceria-zirconia, or carbon black command premium pricing due to impregnation and vapor deposition precision. Fuel cell stack manufacturers in South Korea and Japan are concentrating procurement for proton exchange membrane electrode assemblies.
- Homogeneous Catalysts:Molecular platinum complexes dissolved in reaction media serve fine chemical synthesis, particularly pharmaceutical intermediates where selectivity requirements dominate.
- Bulk Catalysts:Unsupported platinum metal forms in gauze or sponge configurations serve ammonia oxidation and nitric acid production, representing mature, margin-thin supply relationships with petrochemical majors.
Most installed capacity flows through Heterogeneous Catalysts. Expansion is steepest in Supported Catalysts.
End User:
Customer concentration patterns reveal divergent procurement power, with automotive OEMs and oil refiners leveraging volume scale against pharmaceutical and specialty chemical buyers prioritizing specification compliance.
- Automotive Sector:Catalytic converter and fuel cell stack procurement dominates platinum offtake. EU Green Deal tailpipe mandates in Germany, France, and Italy are extending replacement cycles while increasing per-vehicle platinum loading for nitrogen oxide compliance.
- Chemical Industry:Hydrogenation and dehydrogenation processes in bulk chemical manufacturing consume platinum catalysts for intermediate production. German and Belgian petrochemical clusters anchor regional demand.
- Oil Refining:Catalytic reforming and hydrocracking applications utilize bulk platinum catalysts in continuous regeneration units. Gulf Coast and Rotterdam refining complexes represent concentrated demand nodes.
- Pharmaceutical Sector:Asymmetric hydrogenation for active pharmaceutical ingredient synthesis employs homogeneous platinum complexes where enantioselectivity requirements justify elevated catalyst costs.
Automotive procurement commands the largest volume share. Pharmaceutical applications sustain the highest margin structure.
Application:
Technology-performance requirements stratify the application landscape, with fuel cell and emissions control systems demanding the most stringent catalyst specifications.
- Fuel Cells:Proton exchange membrane stack electrodes require platinum-cobalt alloy nanoparticles on carbon supports with controlled particle size distribution. Japanese and South Korean energy conglomerates are locking long-term offtake agreements with integrated refiners.
- Catalytic Converters:Diesel oxidation and selective catalytic reduction catalysts in heavy-duty applications retain platinum intensity despite gasoline segment palladium displacement. German commercial vehicle OEMs anchor European demand.
- Petrochemical Production:Paraxylene and propylene oxide processes utilize heterogeneous platinum catalysts in fixed-bed reactor configurations.
- Hydrogenation Reactions:Edible oil hardening and specialty chemical saturation processes employ supported platinum catalysts in slurry or trickle-bed operations.
Catalytic converter deployment retains the broadest installed base. Fuel cell applications are climbing the fastest.
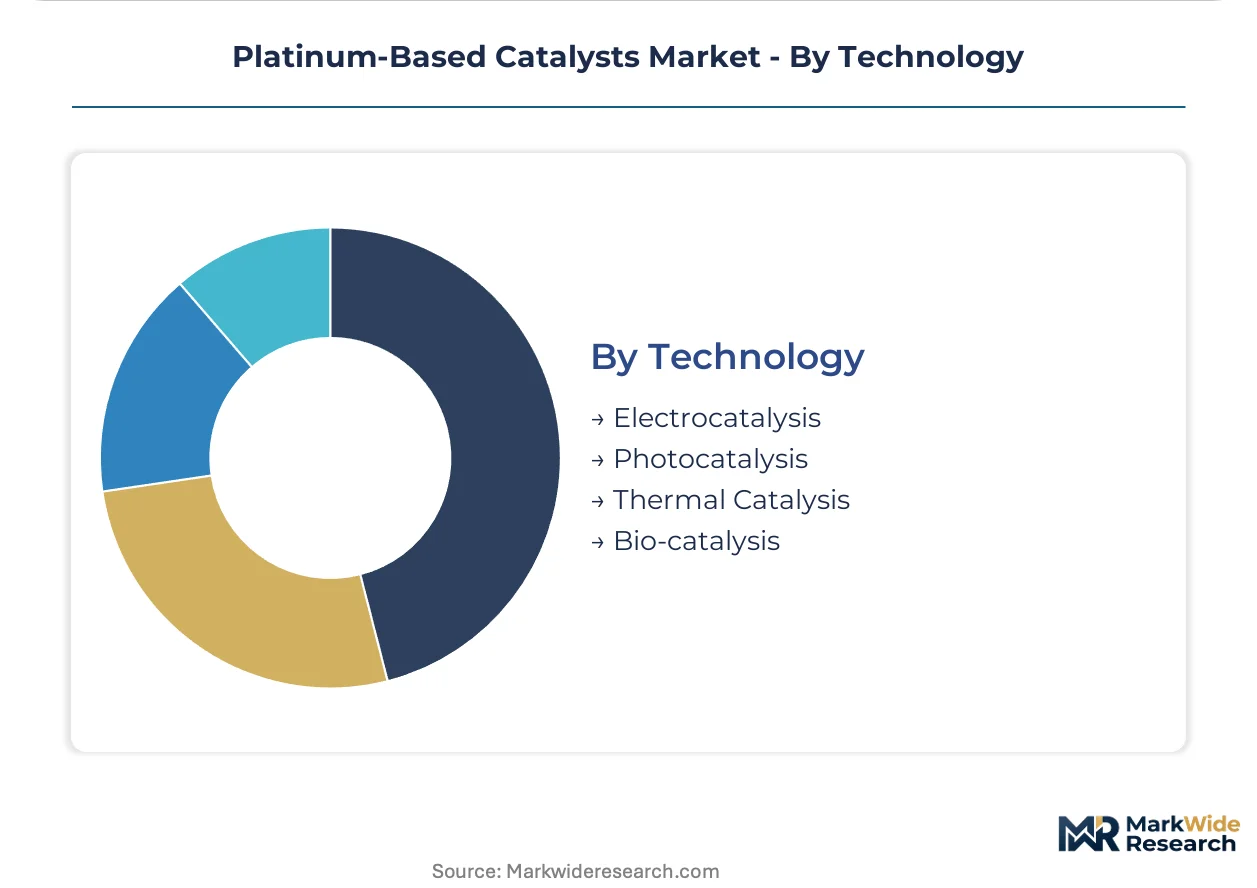
Technology:
Process intensification trajectories diverge across catalytic mechanisms, with electrocatalysis demanding the most advanced materials characterization capabilities.
- Electrocatalysis:Electron transfer reactions at electrode surfaces govern fuel cell and electrolyzer performance. Thin-film deposition and particle size control expertise shortages in Germany and Japan are constraining membrane electrode assembly manufacturing expansion.
- Thermal Catalysis:Temperature-activated surface reactions dominate automotive and petrochemical applications, with established supply chains and qualification protocols.
- Photocatalysis:Light-driven platinum-mediated reactions serve niche environmental remediation and organic synthesis applications.
- Bio-catalysis:Platinum-containing artificial metalloenzymes and hybrid catalysts remain experimental, with limited commercial penetration outside academic research partnerships.
Thermal catalysis retains the deepest installed capacity. Electrocatalysis is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr industrial corridor concentrates European platinum catalyst demand through automotive catalytic converter manufacturing and emerging electrolyzer supply chains. Japanese and South Korean industrial clusters anchor Asia-Pacific procurement for fuel cell stack production. German chemical complexes and Gulf Coast refineries sustain bulk catalyst consumption across hydrogenation and petrochemical processes.
Germany
Automotive OEMs in Stuttgart and Wolfsburg are recalibrating platinum loading specifications for Euro 7 compliance. The EU Green Deal tailpipe mandates through the KBA extend catalyst replacement cycles while increasing per-vehicle platinum intensity. The Ruhr Valley petrochemical cluster around Duisburg and Leverkusen sustains heterogeneous catalyst demand for hydrogenation processes.
Japan
Fuel cell stack manufacturers in Nagoya and Tokyo are scaling proton exchange membrane electrode assembly production. METI hydrogen supply chain targets accelerate domestic platinum offtake for polymer electrolyte membrane systems. The Kansai industrial corridor around Osaka concentrates electrocatalyst procurement for automotive and stationary fuel cell deployments.
United States
Gulf Coast refineries in Texas and Louisiana utilize bulk platinum catalysts in catalytic reforming and hydrocracking units. EPA and NHTSA emissions thresholds tighten permissible nitrogen oxide outputs from heavy-duty diesel applications. The Detroit automotive cluster maintains catalytic converter demand despite palladium substitution pressures in gasoline segments.
South Korea
Gyeonggi Province fuel cell bus procurement programs anchor stationary and mobility electrocatalyst demand. Domestic energy conglomerates are locking long-term platinum supply agreements with integrated refiners. The Ulsan petrochemical complex sustains heterogeneous catalyst consumption for paraxylene and propylene oxide production.
India
National Hydrogen Mission targets and PLI scheme incentives are creating captive catalyst demand for domestic electrolyzer manufacturing. The Gujarat chemical corridor around Vadodara and Bharuch concentrates hydrogenation catalyst procurement for specialty chemical production. Maharashtra's emerging fuel cell component ecosystem is absorbing supported catalyst imports for pilot stack assembly.
Platinum-Based Catalysts Market Vendor Landscape
Long-term offtake contracting dominates the current landscape as electrolyzer manufacturers secure feedstock price certainty for project finance requirements. The vendor base stratifies across integrated precious metals refiners with captive mining relationships, specialized electrocatalyst formulators with thin-film deposition expertise, and regional chemical companies with commodity-scale production assets. Three archetypes occupy distinct positions: vertically integrated European refiners controlling closed-loop recycling channels, Japanese precision materials specialists with membrane electrode assembly qualification capabilities, and diversified chemical conglomerates leveraging cross-product precious metals trading desks. Competitive moves center on strategic partnerships for recycling network access and technology licensing agreements for fuel cell stack integration.
Among integrated European refiners, BASF SE and Umicore exemplify the archetype combining precious metals trading with catalyst manufacturing infrastructure. Johnson Matthey occupies a position within the electrocatalyst specialization tier, anchoring proton exchange membrane fuel cell electrode development through deep R&D intensity. Heraeus Precious Metals represents the closed-loop recycling control model, securing secondary platinum supply channels that lower net procurement costs for industrial buyers.
| Leading Market Players |
|---|
| BASF SE |
| Johnson Matthey |
| Heraeus Precious Metals |
| Evonik Industries AG |
| Umicore |
| TANAKA Precious Metals |
| Clariant AG |
| Albemarle Corporation |
| Haldor Topsoe A/S |
| Others |
Supply Flow & Price Mechanics
London Metal Exchange platinum price benchmarks cascade through catalyst supply chains, compressing margins at supported catalyst tiers while electrocatalyst premiums widen on fuel cell stack qualification requirements. German refiners and Japanese electrocatalyst specialists absorb volatility through long-term offtake contracting that locks feedstock costs for electrolyzer project finance.
Pricing Analysis
Input-cost pass-through from South African and Russian concentrate supply governs catalyst pricing, with platinum sponge premiums feeding directly into supported catalyst quotations. Three-tier pricing structure across fuel cell-grade, automotive emissions-grade, and industrial bulk-grade separates membrane electrode assembly manufacturers from catalytic converter OEMs and petrochemical buyers. Pricing pressure stems from palladium substitution in gasoline three-way catalysts, forcing platinum loadings downward in light-duty applications. Petrochemical refiners exhibit highest price sensitivity due to commodity-margin exposure, while fuel cell stack manufacturers accept premium pricing for electrocatalyst qualification certainty.
Supply Chain Analysis
Platinum concentrate supply rests on South African Bushveld Complex operations and Russian Norilsk mining, with secondary recovery from German and Japanese automotive catalyst recycling channels. Critical inputs span platinum sponge, high-surface-area carbon black supports, and ceria-zirconia oxide carriers. Single-source vulnerability concentrates in Russian primary supply, triggering European refiner diversification into South African concentrate offtake and closed-loop recycling expansion. Distribution runs through integrated precious metals traders with captive refining capacity, delivering to catalyst formulators and direct industrial buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play between EU REACH compliance costs and Indian PLI scheme manufacturing incentives, with catalyst production cost differentials exceeding fifteen percent across jurisdictions.
For Market Incumbents: To counter palladium-rhodium substitution in gasoline catalytic converters, BASF SE and Umicore should deepen backward integration into South African concentrate offtake while expanding closed-loop recycling networks in Germany and Japan. Electrocatalyst specialization through membrane electrode assembly qualification investment anchors premium positioning against commodity catalyst commoditization.
For New Entrants and Emerging Players: Launch via toll manufacturing partnerships with Indian electrolyzer stack producers under National Hydrogen Mission procurement programs. White-space targets include pharmaceutical homogeneous catalyst segments demanding enantioselective synthesis capabilities, and Saudi Arabian green hydrogen export hub catalyst supply where project finance mandates long-term contracting. Direct technical service engagement with fuel cell bus fleet operators in Gyeonggi Province offers qualification pathway acceleration.
For Investors and Strategic Acquirers: Asymmetric upside sits with Japanese precision materials specialists possessing thin-film deposition expertise and membrane electrode assembly durability testing infrastructure. Long-term viability over the next decade hinges on fuel cell deployment scaling and electrolyzer manufacturing cost curves. Watch Japanese METI hydrogen subsidy disbursement velocity as inflection indicator for electrocatalyst demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Concentrate Offtake | Secures South African platinum supply against Russian concentrate disruption risk for European refiners. |
| Closed-Loop Recycling Network Expansion | Captures German automotive catalyst scrap for secondary fuel cell electrocatalyst feedstock security. |
| Membrane Electrode Assembly Qualification Investment | Accelerates Johnson Matthey fuel cell stack integration with Japanese OEM platform engineering. |
| Long-Term Supply Agreement Structuring | Locks Korean energy conglomerate platinum pricing for NEOM hydrogen hub project finance compliance. |
| Electrocatalyst Synthesis Skill Development | Addresses German and Japanese thin-film deposition expertise shortages constraining stack manufacturing expansion. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fuel cell stack procurement managers, automotive catalyst specification engineers, precious metals trading desk heads, electrolyzer project developers, and petrochemical process technology directors with secondary validation. Trade data from customs authorities, SEC filings from integrated refiners, hydrogen project development databases, and automotive production statistics anchored volume estimates. Bottom-up catalyst consumption modeling and top-down precious metals flow analysis triangulated market sizing.
Comparable-period anchoring linked historical automotive catalyst loadings to emerging fuel cell and electrolyzer demand trajectories across the projection horizon. Segmentation dimensions spanned product architecture, end-use industry, application technology, and regional manufacturing hub concentration. CAGRs derived from installed base turnover analysis and new capacity deployment schedules, with fuel cell stack power density improvements and electrolyzer manufacturing scale-up curves as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Russian supply disruption or accelerated palladium substitution scenarios. Forecasts reflect documented assumptions on platinum loading specifications, membrane electrode assembly durability testing timelines, and REACH authorization pathways for novel alloy compositions. A small set of triggers—METI subsidy disbursement rates, EU Green Deal tailpipe mandate enforcement timing, and Indian PLI scheme allocation velocity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Europe PGM Catalyst Market
Catalysts
Refining Catalysts Market
Catalysts
Photocatalyst Market
Catalysts
Precious Metal Catalysts Market
Catalysts
Phosphorus Based Catalyst Market
Catalysts
Catalyst Handling Services Market
Catalysts
Biodiesel Catalyst Market
Catalysts
Industrial Catalytic Converters Market
Catalysts
Syngas to Ethylene Glycol Catalyst Market
Catalysts
Asia-Pacific Refining Catalysts Market
Catalysts
Hydrodeoxygenation [HDO] Catalysts Market
Catalysts
Global Emission Control Catalyst (ECC) Market
Catalysts
Catalyst Carrier Market
Catalysts
Polymer Catalyst Market
Catalysts
Asia and Middle East FCC Catalyst Market
Catalysts
Polymerization Catalysts Market