
 Stylus Pen Market | 2026-2036
Stylus Pen Market Size, Share, and Industry Trends Forecast 2026-2036
Stylus Pen Market Intelligence
Professional illustrators and industrial designers are redrawing demand patterns away from casual note-takers. Wacom Co. Ltd. anchors premium digital art workflows through specialized EMR tablet integration. Apple Inc. leverages its captive ecosystem to control stylus-tablet pairing architecture. Samsung Electronics Co. Ltd. competes across multiple price tiers with S Pen variants bundled across Galaxy device lines.
A stylus pen is a handheld input instrument employing active or passive electromagnetic, capacitive, or optical sensing mechanisms to register position, pressure, and tilt data on compatible display surfaces, typically manufactured with conductive elastomer or fine-point plastic composite tips. Its primary commercial purpose is to enable precision annotation, creative production, and gesture-controlled human-computer interaction on touch-enabled devices. Active stylus and EMR technology segments lead in margin capture due to complex chipset integration and patent-protected digitizer protocols, while Bluetooth stylus variants represent the fastest-expanding category as latency reduction and wireless pairing standards improve. Digital art application demand concentrates around pressure-sensitive technology stacks where artists require granular line-weight control.
FCC equipment authorization governs radio-frequency stylus models in the United States, while CE marking and RoHS substance restrictions shape European market access requirements for electronic pen assemblies. REACH chemical compliance further constrains material selection for conductive elastomer tips and circuit board substrates. Stakeholders must monitor evolving IEC touch-performance standards and dual carbon goals from China's MIIT, as these frameworks will determine which stylus architectures qualify for large-scale OEM procurement contracts.
Market Dynamics
Pressure-sensitive EMR digitizer protocols are compressing technical differentiation across mid-tier and premium stylus segments, forcing vendors to compete on software integration depth rather than hardware specifications alone.
Growth Catalysts
- ISO/IEC touch-performance standards:Unified certification protocols reduce OEM validation cycles and accelerate procurement decisions for enterprise tablet deployments.
- Digital art platform ecosystems:Professional illustrators and industrial designers now demand granular pressure response, pulling hardware upgrades across creative software subscriptions.
- South Korean hardware-software clusters:Dense supplier networks around Samsung Electronics and domestic display panel manufacturers compress R&D-to-production timelines for active stylus variants.
Market Restraints
- Conductive elastomer input volatility:Silicone and conductive polymer prices fluctuate with electronics-grade chemical feedstock markets, squeezing tip assembly margins.
- Patent-thicket concentration:Core EMR digitizer IP remains controlled by a narrow set of licensing entities, elevating royalty burdens for new market entrants.
- Capacitive passive stylus substitution:Low-cost rubber-tipped alternatives satisfy casual note-taking demand, capping price realization at the economy tier.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Production-linked incentives attract stylus assembly and component sourcing away from legacy East Asian hubs.
- Healthcare annotation workflows:Electronic health record digitization creates demand for HIPAA-compliant stylus input on medical-grade tablets and diagnostic displays.
- Bluetooth Low Energy convergence with UWB positioning:Wireless pairing standards enable spatial-aware stylus tracking for augmented reality design applications.
Industry Challenges
- FCC equipment authorization timelines:Radio-frequency stylus models face extended certification queues for electromagnetic interference testing, delaying product launches.
- Firmware integration complexity:OEMs struggle to optimize latency across heterogeneous tablet chipsets from Qualcomm, MediaTek, and in-house silicon teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stylus Pen Market |
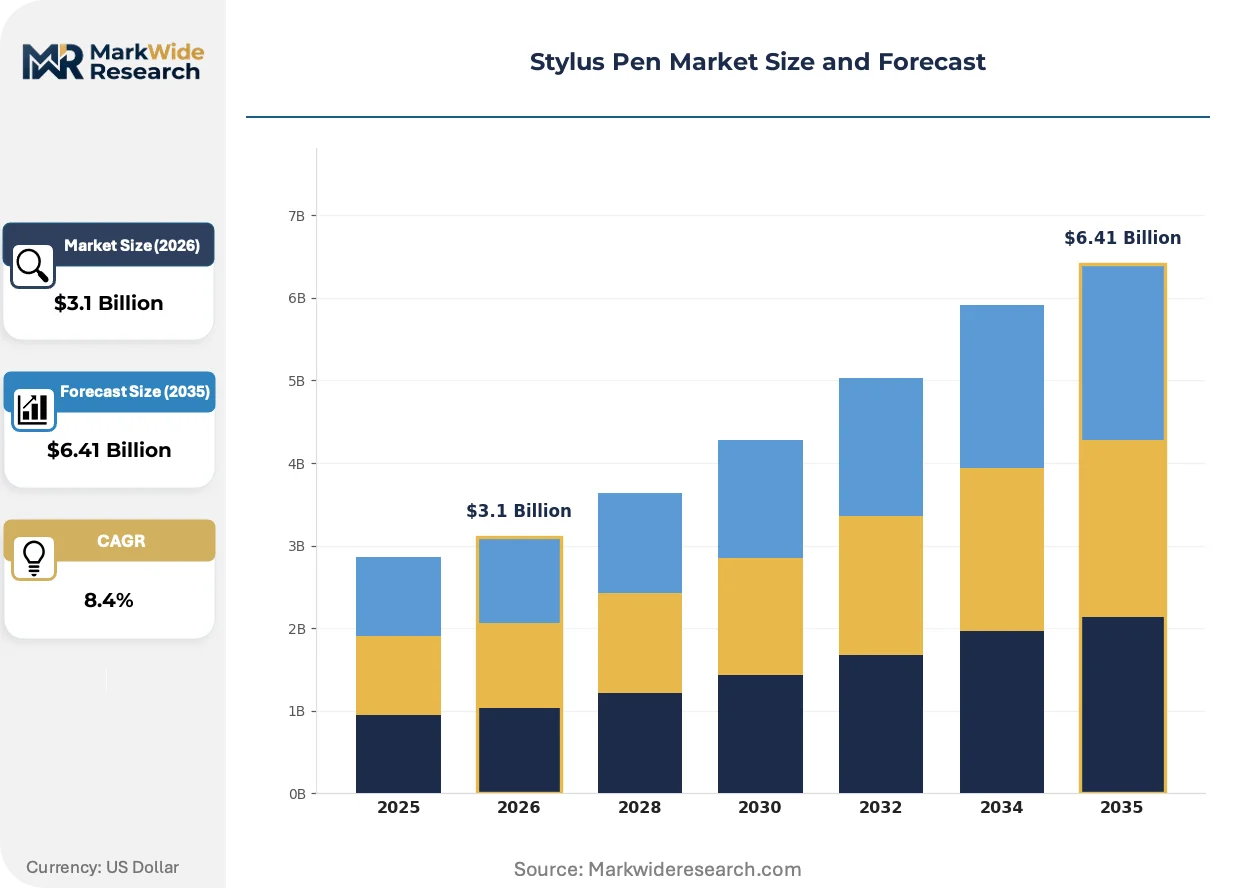
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.41 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Stylus, Passive Stylus, Digital Pen, Bluetooth Stylus Application: Graphic Design, Note-Taking, Education, Digital Art End User: Students, Artists, Professionals, Designers Technology: EMR, Capacitive, Optical, Pressure-Sensitive |
| Companies Covered | Wacom Co. Ltd., HP Inc., Apple Inc., Logitech, Lenovo Group Limited, Samsung Electronics Co. Ltd., Adonit, Seiko Epson Corporation, Microsoft Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stylus Pen Market Strategic Shifts & Innovations
Latency reduction architectures and wireless pairing standards are redrawing competitive boundaries between active stylus categories, while regulatory chemical compliance tightens material selection constraints.
Electromagnetic resonance digitizers with sub-10ms latency are supplanting legacy capacitive active stylus designs in professional creative workflows. Industrial designers and architectural visualization studios now specify EMR-native tablets for precision line-weight control. This shift compresses addressable volume for Bluetooth-dependent alternatives that rely on software-side prediction algorithms.
REACH chemical restrictions from ECHA constrain conductive elastomer formulation choices for European market access. Substance restrictions on phthalates and heavy metals force reformulation of tip assemblies and circuit board substrates. Vendors serving EU procurement channels now maintain dual material bills to segregate compliant and non-compliant production lots.
Enterprise buyers now unbundle stylus-tablet purchasing decisions from hardware OEM bundles, issuing separate RFPs for input device specifications. This procurement fragmentation elevates specialist stylus vendors in North American and European education and healthcare verticals. Channel partners with dedicated peripheral distribution agreements capture margin previously retained by tablet manufacturers.
Stylus Pen Market Segmentation
Technology differentiation and user workflow requirements fragment the stylus pen landscape into distinct margin pools. Procurement patterns diverge sharply between creative professionals demanding pressure precision and casual users prioritizing cost accessibility.
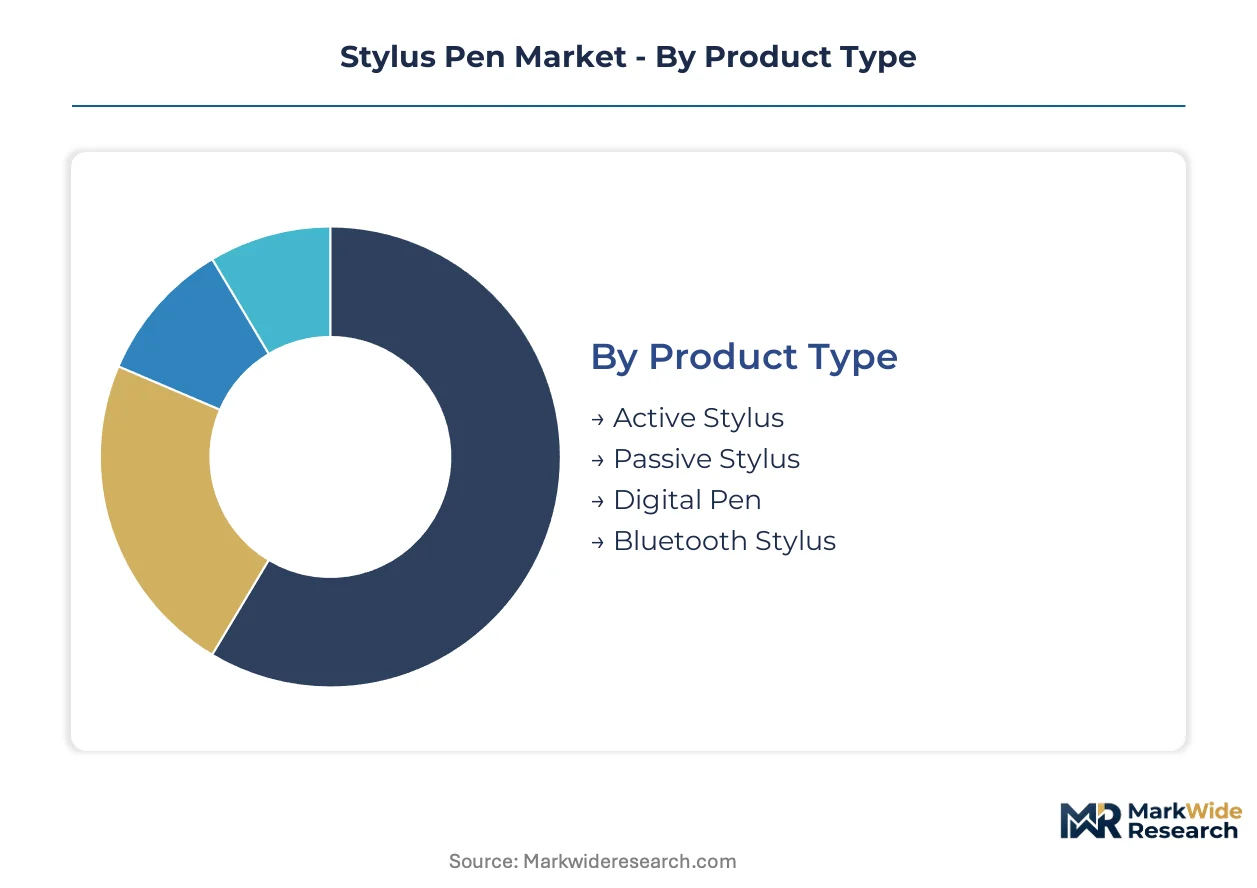
Product Type:
Margin capture concentrates in chip-integrated active variants where patent-protected digitizer protocols create licensing barriers.
- Active Stylus:Electromagnetic resonance or capacitive sensing chipsets enable pressure, tilt, and hover detection. Professional illustrators in South Korea and Japan drive specification requirements through Wacom and Samsung EMR tablet ecosystems.
- Bluetooth Stylus:Wireless pairing architectures with sub-20ms latency are gaining traction among architects and industrial designers requiring spatial tracking. FCC authorization timelines constrain launch velocity for new entrants.
- Digital Pen:Self-contained storage and offline handwriting capture serve enterprise documentation workflows.
- Passive Stylus:Conductive rubber or elastomer tips without electronic components dominate economy-tier education procurement.
The dominant share belongs to Active Stylus, while Bluetooth Stylus is closing the gap fastest.
Application:
Workflow complexity determines price realization, with production-grade creative tasks commanding multiples over annotation utilities.
- Digital Art:Granular pressure response requirements pull hardware upgrades across subscription-based creative software platforms. Professional illustrators specify ISO-compliant pressure sensitivity tiers above 4,096 levels.
- Graphic Design:Vector precision and gesture-controlled navigation dominate agency and in-house creative team procurement. Adobe Creative Cloud integration requirements shape vendor selection criteria.
- Education:K-12 and higher-ed bulk purchasing prioritizes durability and replaceable tip economics over performance specifications.
- Note-Taking:Handwriting-to-text conversion and cloud synchronization drive enterprise tablet accessory decisions.
Digital Art commands premium positioning, though Education delivers the steepest volume expansion trajectory.
End User:
Professional segments extract value through software-locked feature activation, while student price sensitivity sustains passive stylus manufacturing scale.
- Artists:Pressure-sensitive EMR-native tablets are non-negotiable for studio and freelance illustration workflows. REACH-compliant tip materials are mandatory for EU market access.
- Designers:Industrial and architectural visualization studios specify latency benchmarks below 10ms for real-time rendering feedback.
- Professionals:Healthcare, legal, and financial services demand HIPAA-compliant or audit-trail-enabled annotation systems.
- Students:Mass-market education deployments favor bundled passive stylus configurations with replaceable consumables.
Artists retain the highest per-unit spending, while Professionals are expanding most quickly across enterprise verticals.
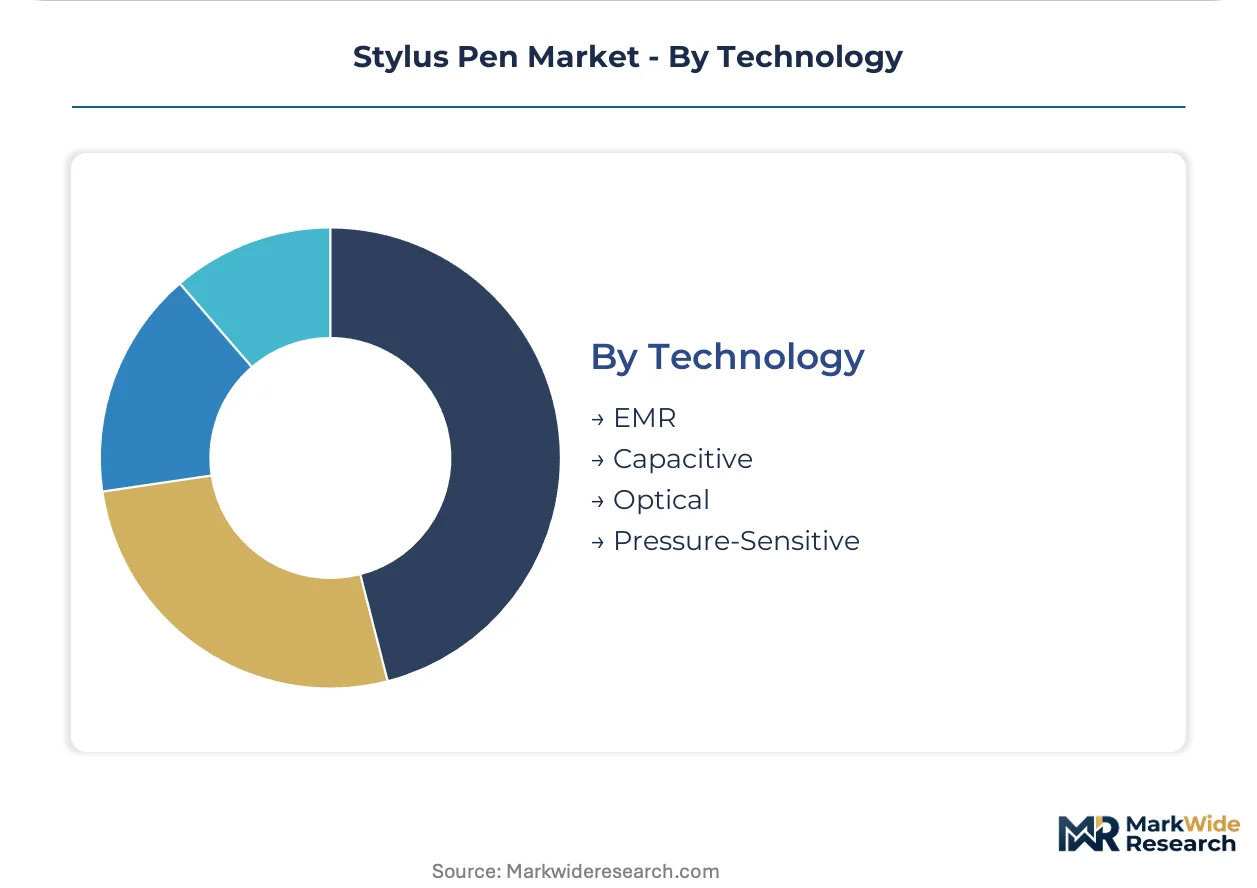
Technology:
Patent concentration in electromagnetic resonance digitizers constrains competitive entry and sustains royalty structures.
- EMR:Electromagnetic resonance digitizers with dedicated tablet-integrated sensor layers deliver superior pressure granularity and battery-free pen operation. Samsung Electronics and Wacom control core IP licensing.
- Pressure-Sensitive:Force-sensing resistor or strain gauge architectures enable variable line-weight control in capacitive active designs. Capacitive passive alternatives lack dynamic response capability.
- Capacitive:Broad compatibility with unmodified touchscreens sustains economy-tier volume, though precision limitations exclude professional workflows.
- Optical:Camera-based position tracking enables stylus operation on non-touch surfaces, serving specialized industrial and presentation applications.
EMR holds entrenched leadership in premium tiers, with Pressure-Sensitive designs gaining share fastest in mid-market creative tablets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component fabrication clusters in South Korea and Taiwan anchor active stylus chipset supply, while software-locked ecosystems in the United States and Japan concentrate premium demand. Regulatory divergence across FCC, CE marking, and MIIT frameworks fragments certification pathways for multi-region product launches.
United States
Enterprise healthcare and education procurement drives volume for HIPAA-compliant annotation devices. FCC equipment authorization timelines for radio-frequency stylus models extend electromagnetic interference validation queues. Austin and Seattle tech corridors host tablet OEM engineering teams optimizing latency across Qualcomm and Apple silicon architectures.
South Korea
Samsung Electronics bundles S Pen variants across Galaxy device lines, compressing R&D-to-production cycles through domestic display panel supplier networks. MFDS medical device guidelines shape stylus-tablet combinations for diagnostic imaging workflows. Seoul Capital Area suppliers concentrate EMR digitizer protocol development and patent licensing operations.
Japan
Professional illustration studios specify Wacom EMR-native tablets for pressure-sensitive creative production. METI industrial standards and JIS touch-performance certifications constrain import qualification for foreign stylus vendors. Nagoya and Osaka manufacturing bases produce precision force-sensing resistor components for mid-tier capacitive active designs.
Germany
Industrial designers and architectural visualization studios demand sub-10ms latency benchmarks for real-time rendering feedback. REACH chemical restrictions from ECHA and RoHS substance limits constrain conductive elastomer tip formulations for EU market access. Bavaria and Baden-Württemberg host automotive design centers pulling precision stylus input for CAD workflows.
China
Domestic tablet OEMs source passive stylus assemblies for K-12 education bulk purchasing at economy-tier price points. MIIT dual carbon goals and GB standards for electronic waste shape material selection for circuit board substrates. Yangtze River Delta component suppliers concentrate capacitive touch controller fabrication for Bluetooth stylus variants.
Stylus Pen Market Key Industry Players
Concentration sits with ecosystem-integrated technology conglomerates controlling captive stylus-tablet pairing architectures. The vendor base stratifies across three tiers: premium EMR specialists licensing patent-protected digitizer protocols, mid-range Bluetooth stylus fabricators competing on wireless latency reduction, and economy-tier passive stylus assemblers serving education procurement. Strategic moves center on backward integration into conductive elastomer tip production and software-side feature activation locks.
Among ecosystem-anchored technology conglomerates, Apple Inc. and Samsung Electronics Co. Ltd. exemplify platform-control archetypes through captive hardware-software integration, while Wacom Co. Ltd. occupies a specialist position licensing EMR digitizer IP across third-party tablet OEMs. These three entities represent divergent competitive postures: vertical ecosystem lock-in versus horizontal technology licensing.
| Leading Market Players |
|---|
| Wacom Co. Ltd. |
| HP Inc. |
| Apple Inc. |
| Logitech |
| Lenovo Group Limited |
| Samsung Electronics Co. Ltd. |
| Adonit |
| Seiko Epson Corporation |
| Microsoft Corporation |
| Others |
Cost & Logistics Intelligence
Sixty-day inventory cycles for EMR digitizer chipsets tether pricing power to Seoul-based supplier reliability, compressing margin buffers for Bluetooth stylus assemblers when conductive elastomer feedstock costs spike. Patent-locked licensing fees for electromagnetic resonance protocols anchor premium tier pricing, while passive stylus margins fluctuate with spot silicone markets.
Pricing Analysis
REACH chemical compliance dictates the pricing tier structure across European procurement channels, forcing dual material bills that segment production lots. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with ISO-compliant pressure sensitivity tiers commanding multiples over uncertified alternatives. Cost compression in the passive stylus tier is intensifying because education bulk purchasing consolidates volume discounts. Students exhibit highest price sensitivity, while professional illustrators demonstrate lowest elasticity due to software-locked feature dependencies.
Supply Chain Analysis
Busan-to-Yokohama maritime corridors anchor conductive polymer shipments, creating single-source vulnerability when port congestion disrupts just-in-time tip assembly schedules. Component fabrication concentrates in South Korea, Taiwan, and Japan, drawing from conductive elastomer, EMR sensor layers, and capacitive touch controllers. Tariff exposure on electronics-grade silicone imports from China threatens margin stability for tip manufacturers. Distribution runs through dedicated peripheral channel partners capturing margin previously retained by tablet OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stylus pen adoption sits in early-cycle expansion as healthcare digitization creates HIPAA-compliant annotation demand across medical-grade tablet deployments. Professional creative software subscriptions pull hardware upgrade cycles, extending replacement frequency beyond consumer electronics norms.
For Market Incumbents: Fortify patent licensing positions through backward integration into EMR digitizer protocol development, defending against emerging capacitive active stylus entrants exploiting open wireless standards. Secure captive supply of conductive elastomer tip formulations to offset silicone price volatility. Channel control through education procurement GPO contracts represents the critical lever for volume retention. For New Entrants and Emerging Players: Differentiate on sub-10ms latency benchmarks for industrial design workflows, exploiting firmware optimization gaps across heterogeneous tablet chipsets. India's PLI scheme for electronics manufacturing offers the most penetrable geography for assembly cost advantages. Go-to-market positioning through architectural visualization software partnerships bypasses incumbent ecosystem lock-in. For Investors and Strategic Acquirers: Carve-out targets emerge from display panel manufacturers seeking downstream integration into stylus-tablet bundled offerings. Long-term viability hinges on software-side feature activation revenue streams rather than hardware margin capture alone. Watch FDA medical device classification rulings on diagnostic display stylus input as inflection signal for healthcare vertical expansion.| Strategic Initiative | Industry Significance |
|---|---|
| EMR Protocol Licensing Expansion | Wacom and Samsung IP licensing to third-party tablet OEMs broadens addressable hardware base. |
| Bluetooth Low Energy Integration | Sub-20ms latency architectures displace legacy capacitive designs in architectural visualization workflows. |
| Conductive Elastomer Backward Integration | In-house tip production insulates margins from silicone feedstock price volatility. |
| Healthcare Compliance Certification | HIPAA-compliant annotation systems unlock medical-grade tablet procurement verticals. |
| India PLI Manufacturing Relocation | Production-linked incentives attract assembly capacity away from East Asian cost structures. |
Research Approach
The analysis maps active stylus, Bluetooth stylus, digital pen, and passive stylus segments, each validated through tablet OEM procurement managers, conductive elastomer suppliers, and creative software platform engineers. Primary interviews with EMR digitizer licensing specialists, education technology distributors, and healthcare IT administrators combined with secondary validation from FCC equipment authorization filings, REACH substance restriction databases, and MIIT electronics manufacturing standards. Bottom-up shipment modeling and top-down ecosystem revenue triangulation anchored volume estimates.
Consistency checks against external benchmarks validated projections across the analysis window. Segmentation dimensions modeled include technology tier, application workflow complexity, end-user professional classification, and regional regulatory cluster. CAGRs derived from adoption curve analysis of pressure-sensitive creative software subscriptions and enterprise tablet deployment cycles. Forecast inputs incorporated ISO/IEC touch-performance standard implementation timelines and PLI scheme manufacturing capacity announcements.
Decision-makers should treat outputs as directional under stable patent licensing structures and sustained creative software subscription growth; material deviation would warrant model refresh. Specific risk factors include REACH chemical restriction expansion, FCC authorization queue extensions, and capacitive passive stylus substitution acceleration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Global Smart Outdoor TV Market
Consumer Electronics
Mobile Phone Accessories Market
Consumer Electronics
Wet Wipes Market
Consumer Electronics
Watch Market
Consumer Electronics
Pet Monitoring Camera Market
Consumer Electronics
Consumer Electronics Repair and Maintenance Market
Consumer Electronics
Kid's Wired Earphone and Headphone Market
Consumer Electronics
Bluetooth Speakers Market
Consumer Electronics
Digital Accessories Market
Consumer Electronics
Global Earphones and Headphones Market
Consumer Electronics
Learning Remote Controls Market
Consumer Electronics
Silicone Sex Doll Market
Consumer Electronics
Airport Retailing Consumer Electronics Market
Consumer Electronics
Education PC Market
Consumer Electronics
Wireless Mouse Market
Consumer Electronics
North America Mobile Phone Accessories Market