
 Kid's Wired Earphone and Headphone Market | 2026-2036
Kid's Wired Earphone and Headphone Market Size, Share, and Industry Trends Forecast 2026-2036
Kid's Wired Earphone and Headphone Market Insights
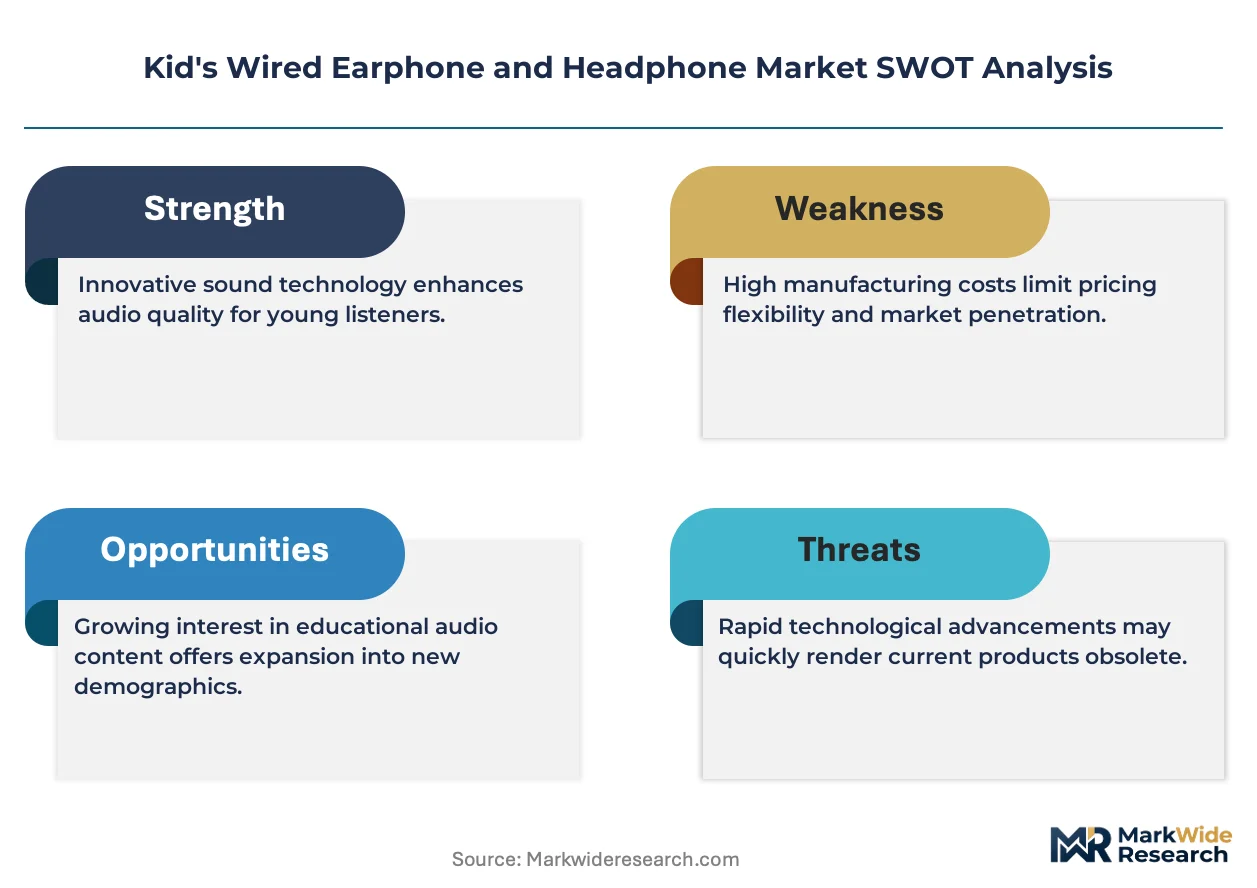
REACH compliance is broadening the cost-of-entry calculus for European suppliers of children's wired audio equipment. Sony leverages its in-house driver manufacturing to sustain margin control across premium over-ear models. Puro Sound Labs anchors its competitive stance through specialized volume-limiting circuitry engineered for pediatric hearing protection. Koss competes on domestic manufacturing scale, maintaining assembly operations that bypass certain tariff-exposed import categories.
Kid's wired earphone and headphone denotes audio transducer assemblies with cable-tethered signal paths, typically integrating 32-ohm dynamic drivers, PVC-jacketed copper conductors, and passive volume-limiting resistors or active circuitry capped at 85 decibels, designed to deliver age-appropriate sound reproduction for juvenile users in educational, entertainment, and travel contexts. Over-ear configurations with padded adjustable headbands dominate institutional procurement channels where durability and shared-use hygiene predominate, while character-themed designs command premium shelf positioning in retail environments targeting preschoolers and early elementary buyers. In-ear and earbud formats remain structurally constrained by parental safety concerns around choking hazards and canal insertion, limiting their addressable share within toddler and infant age brackets despite lower unit production costs.
FDA guidance on pediatric noise exposure, France's ANSM juvenile audio device standards, and the EU's RoHS substance restrictions collectively constrain material selection, maximum output levels, and market access documentation for manufacturers serving transatlantic channels. The EU Green Deal's extending requirements for repairability and recycled content incorporation are pressuring cable-integrated designs toward detachable architectures that simplify component replacement. Stakeholders must monitor regulatory divergence between North American decibel-limit recommendations and binding European output caps, as this gap determines whether single-SKU global strategies remain viable or force regional product fragmentation.
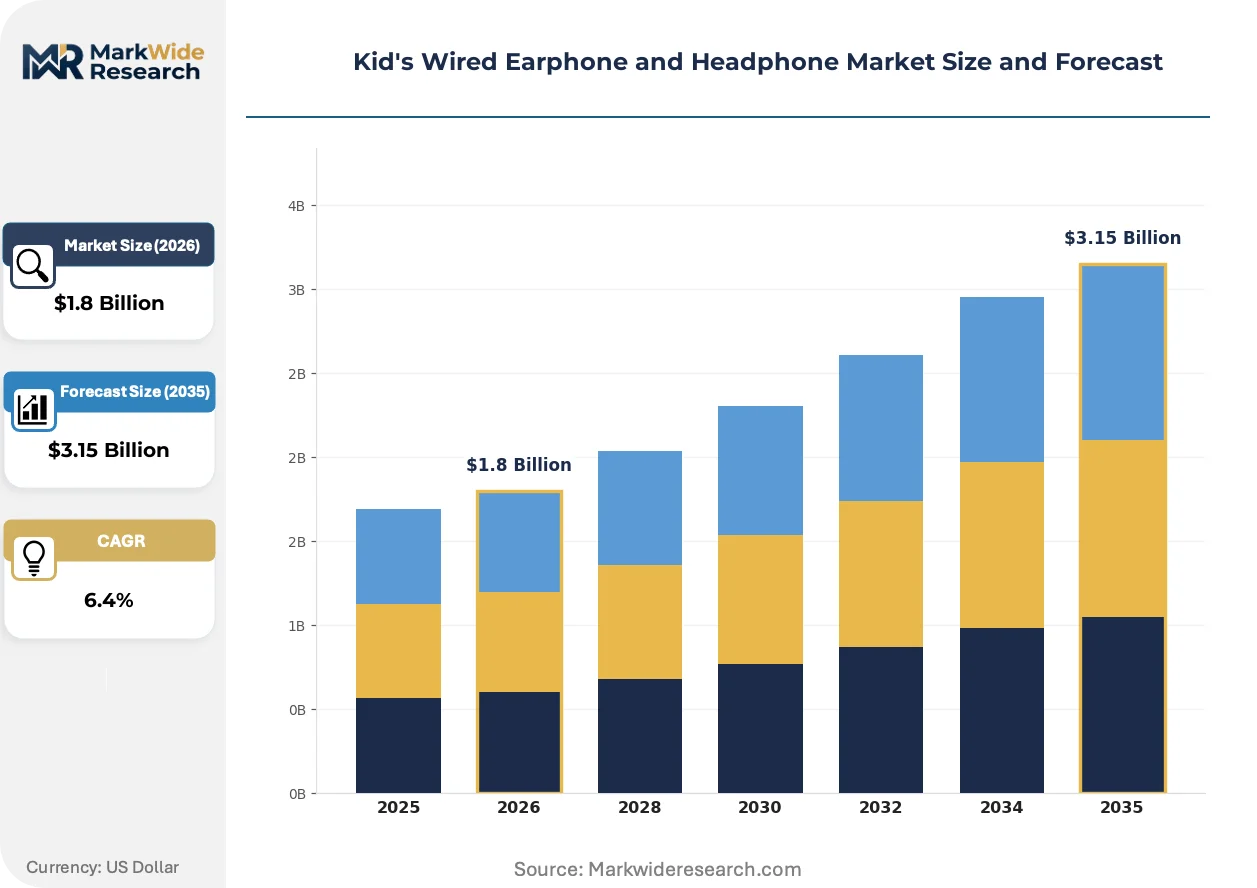
Market Dynamics
France's ANSM volume-limiting mandate is restructuring manufacturer design priorities, forcing passive resistor networks to yield to active output circuitry that caps juvenile exposure at 85 decibels across all export-bound SKUs.
Growth Catalysts
- K-12 EdTech Procurement:US school districts are consolidating annual headphone purchases into multi-year volume contracts, creating predictable offtake for over-ear configurations with antimicrobial padding and shared-use durability ratings.
- REACH Substance Restrictions:ECHA's expanding phthalate and heavy metal prohibitions are accelerating PVC jacket replacement with TPE and bio-based cable sheathing in European-bound production lines.
- Pediatric Hearing Conservation:Parental safety consciousness in the United States is driving premiumization toward volume-certified products, with FDA guidance on noise-induced hearing loss informing retail merchandising decisions.
Market Restraints
- Copper Conductor Volatility:LME copper price swings are compressing margin on low-ASP entry-level SKUs where cable length and gauge cannot be reduced without violating IEC 60228 conductivity standards.
- Driver Supplier Concentration:Dynamic driver manufacturing clusters in Guangdong and Jiangsu provinces create single-source exposure for brands lacking captive transducer production or qualified secondary vendors.
- Choking Hazard Limitations:CPSC small-parts regulations structurally constrain earbud penetration in toddler segments, locking over-ear formats as the only viable architecture for ages under three despite higher unit costs.
Strategic Opportunities
- EU Green Deal Repairability:Detachable cable architectures that simplify component replacement are qualifying for extended producer responsibility credits in France and Germany, opening premium positioning.
- Character Licensing Convergence:Entertainment IP holders are consolidating preschool property rights, creating exclusive co-development windows for headphones featuring streaming-native animated franchises.
- Travel Retail Recovery:Airport duty-free and family hospitality channels are restocking child-specific electronics assortments, with Singapore Changi and Dubai International anchoring Asia-Pacific and Middle East trial markets.
Industry Challenges
- Acoustic Engineering Talent Scarcity:Pediatric-focused transducer tuning requires rare combinations of audiology training and consumer electronics manufacturing experience, extending R&D cycle times for volume-limited driver optimization.
- Multi-Jurisdiction Certification Overlap:Simultaneous ANSM, FDA, and RoHS compliance testing creates redundant documentation burdens, with divergent decibel measurement methodologies forcing SKU fragmentation or conservative global design defaults.
- Legacy School Infrastructure Compatibility:K-12 institutions maintaining analog audio jacks require continued 3.5mm termination support despite USB-C and Lightning adoption in consumer segments, complicating connector strategy and inventory segmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kid's Wired Earphone and Headphone Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Over-Ear, On-Ear, In-Ear, Earbuds Age Group: Infants, Toddlers, Preschoolers, School-Aged Connectivity Type: Wired, Detachable Cable, Inline Control, Noise Isolation Design Feature: Adjustable Headband, Lightweight, Foldable, Character-Themed |
| Companies Covered | Sony, JBL, iClever, Puro Sound Labs, Koss, Sennheiser, Kidz Gear, Snug, Belkin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kid's Wired Earphone and Headphone Market Trends and Innovations
Active volume-limiting circuitry is displacing passive resistor networks as the dominant pediatric safety architecture, while regulatory divergence between binding European caps and advisory North American guidance is forcing modular design platforms.
MEMS-based output monitoring is integrating real-time decibel tracking with automatic gain reduction algorithms. K-12 institutional buyers are specifying this technology in RFPs for shared classroom sets. The shift is compressing warranty exposure for school districts while raising BOM costs that manufacturers are offsetting through extended service contract bundling.
France's ANSM guidelines are mandating maximum 85 dB output with tamper-evident sealing for all juvenile audio devices marketed domestically. Manufacturers serving transatlantic channels must maintain dual firmware profiles or hardware-limiting circuits. This regulatory friction is advantaging European-anchored brands with established ANSM testing relationships and compliant supply chains.
Bulk purchasing consortia are aggregating demand from US school districts into centralized procurement platforms that bypass traditional distributor markups. Regional education service cooperatives in Texas and California are negotiating direct manufacturer relationships. This disintermediation is most advanced in states with permissive public procurement statutes and established cooperative purchasing frameworks.
Kid's Wired Earphone and Headphone Market Segmentation
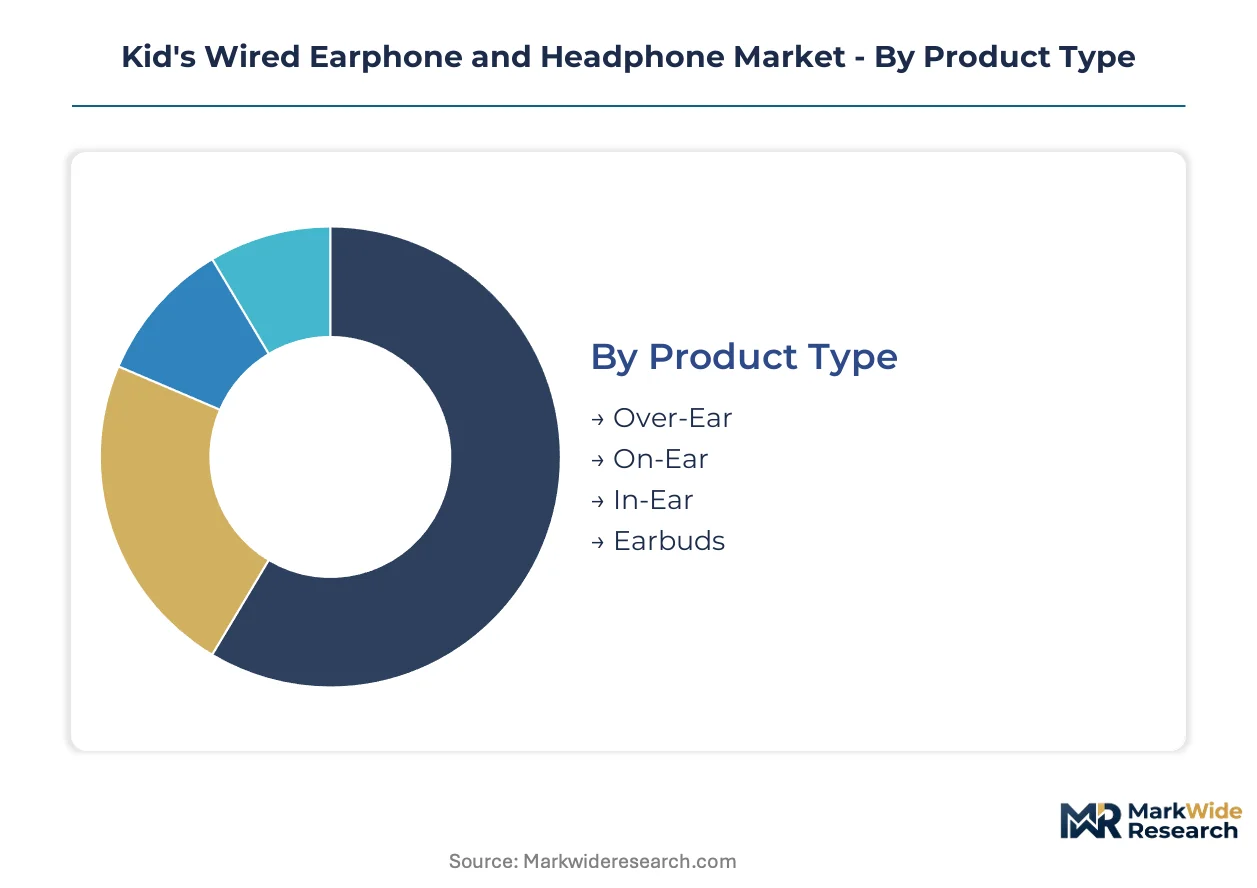
Segmentation in the Kid's Wired Earphone and Headphone Market reveals how institutional procurement patterns, safety regulations, and developmental psychology shape product architecture. Each dimension carries distinct margin profiles and certification burdens that determine manufacturer portfolio strategy.
Product Type:
Institutional buyers prioritize durability and hygiene compliance over retail aesthetics, concentrating procurement in formats that withstand shared classroom use.
- Over-Ear:Padded circumaural designs with antimicrobial foam and reinforced headbands dominate K-12 bulk purchasing. Texas and California education cooperatives specify these for standardized testing environments where noise isolation and all-day comfort reduce student distraction.
- On-Ear:Supra-aural configurations with lower clamping force appeal to travel retail and parental purchasers seeking portable alternatives. Singapore Changi and Dubai International duty-free channels stock these for family vacation segments.
- In-Ear:Canal-insertion designs face structural constraints from CPSC small-parts regulations limiting toddler exposure.
- Earbuds:Low-profile formats remain peripheral in pediatric markets due to choking hazard concerns and parental resistance to canal insertion for juvenile users.
Over-Ear leads on scale; On-Ear leads on momentum.
Age Group:
Neurodevelopmental milestones determine acoustic exposure limits and physical interface requirements, with regulatory thresholds tightening for younger cohorts.
- Infants:Products for this bracket emphasize passive noise reduction without active electronics, as FDA guidance discourages direct audio stimulation for children under 12 months.
- Toddlers:Volume-limited circuitry capped at 85 decibels becomes mandatory for France-bound SKUs under ANSM guidelines, with tamper-evident sealing preventing caregiver override.
- Preschoolers:Character-themed industrial designs command premium shelf positioning in retail environments, with entertainment IP licensing driving differentiation.
- School-Aged:Multi-year district contracts aggregate demand for standardized configurations with 3.5mm analog compatibility, antimicrobial ratings, and shared-use durability certifications.
School-Aged dominates procurement volume; Toddlers concentrates regulatory innovation.
Connectivity Type:
Cable architecture decisions balance legacy infrastructure compatibility against emerging repairability mandates under EU Green Deal frameworks.
- Wired:Fixed-cable designs persist in entry-level SKUs where unit cost minimization outweighs replacement economics, though REACH substance restrictions are accelerating PVC jacket substitution with TPE sheathing.
- Detachable Cable:Modular architectures qualify for extended producer responsibility credits in France and Germany, with 3.5mm or USB-C termination options accommodating mixed infrastructure environments.
- Inline Control:Passive volume wheels and play/pause buttons integrate without active electronics, simplifying compliance across multiple jurisdiction certification regimes.
- Noise Isolation:Acoustic damping through physical seal design avoids powered cancellation circuitry, reducing BOM cost and battery-related safety concerns for juvenile applications.
Detachable Cable gains share fastest on regulatory tailwinds; Wired retains cost-driven volume.
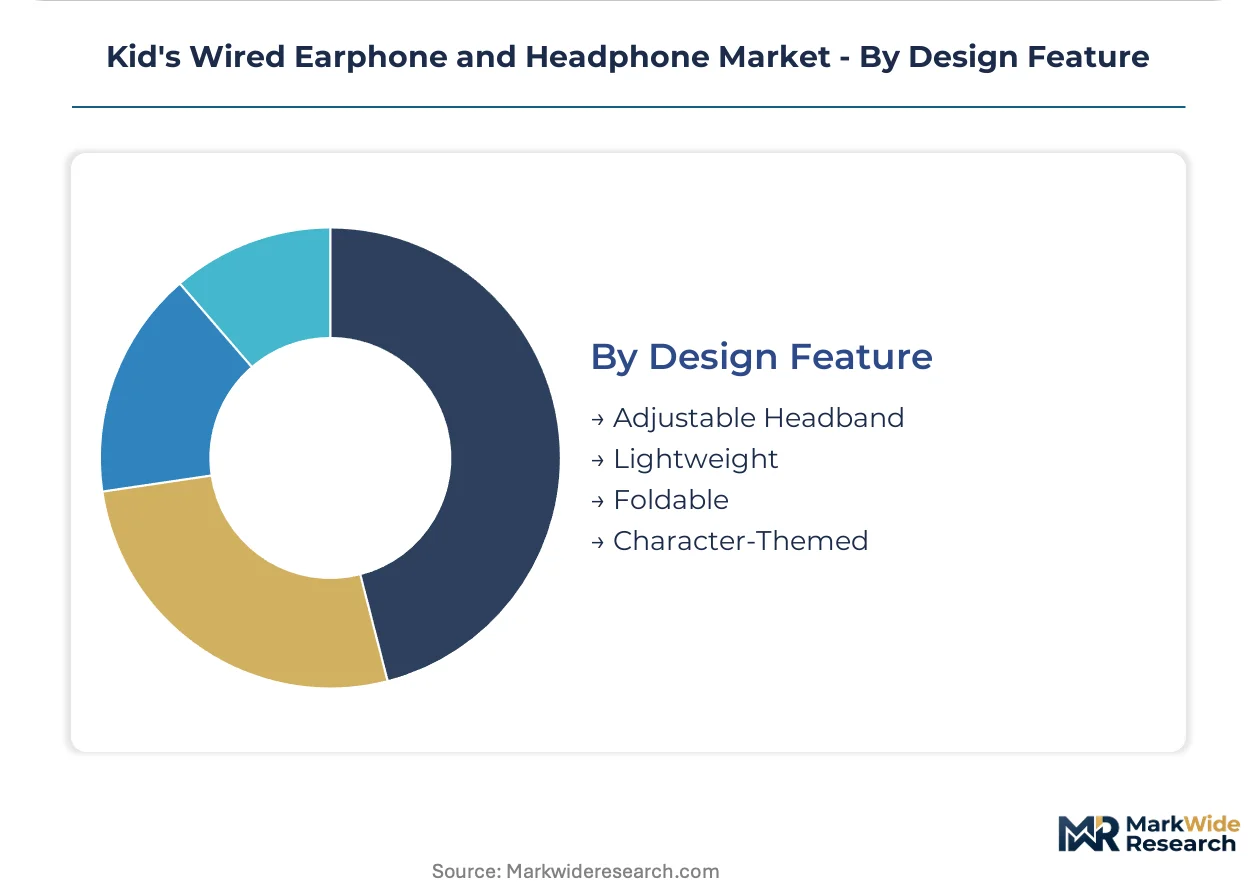
Design Feature:
Physical adjustability and visual differentiation compete as value drivers, with institutional and retail channels diverging on priority hierarchies.
- Adjustable Headband:Ratcheted or sliding mechanisms accommodate growth spans from preschool through early elementary, reducing replacement frequency in district procurement cycles.
- Lightweight:Sub-150 gram constructions minimize cervical strain during extended wear, with material selection constrained by RoHS substance restrictions on lead and cadmium in structural components.
- Foldable:Hinged architectures target travel and hospitality channels where storage density influences assortment decisions, though hinge durability remains a warranty exposure point.
- Character-Themed:Licensed industrial designs from streaming-native animated franchises anchor premium positioning in retail, with exclusive co-development windows consolidating around major entertainment IP holders.
Adjustable Headband leads on institutional penetration; Character-Themed leads on margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Acoustic engineering talent clusters in Shenzhen, Dongguan, and Boston shape regional competitive advantages for juvenile audio device development.
United States
K-12 education cooperatives in Texas and California aggregate bulk procurement through centralized platforms, bypassing traditional distributor channels. FDA guidance on pediatric noise-induced hearing loss informs retail merchandising and district purchasing specifications. Greater Boston anchors audiology-focused R&D operations where university-linked engineering programs supply specialized talent.
China
Guangdong and Jiangsu provinces concentrate dynamic driver manufacturing, creating single-source exposure for brands lacking captive transducer production. The country's national quality regulator enforces GB standards for electronic products while export-bound production lines adapt to REACH substance restrictions. Shenzhen's electronics corridor integrates MEMS-based output monitoring with automatic gain reduction algorithms for institutional buyers.
Germany
EU Green Deal repairability mandates are accelerating detachable cable architectures that qualify for extended producer responsibility credits. KBA-adjacent testing infrastructure supports ECHA compliance documentation for phthalate and heavy metal restrictions. Bavaria's precision manufacturing base supplies TPE and bio-based cable sheathing alternatives to PVC-jacketed conductors.
France
ANSM volume-limiting guidelines mandate 85 decibel maximum output with tamper-evident sealing for all juvenile audio devices marketed domestically. This regulatory friction advantages domestic-anchored brands with established testing relationships and compliant supply chains. Île-de-France hosts specialized certification laboratories serving transatlantic export documentation requirements.
Japan
METI standards for electronic product safety align with IEC 60228 conductivity requirements, preserving 3.5mm analog termination support for legacy school infrastructure. Kanto region manufacturing clusters emphasize lightweight sub-150 gram constructions minimizing cervical strain during extended juvenile wear. Osaka-based suppliers provide antimicrobial foam padding for shared-use institutional configurations.
Kid's Wired Earphone and Headphone Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation pressures are mounting as bulk purchasing consortia disintermediate traditional distribution channels. Three archetypes dominate: entertainment IP licensors leveraging character-themed industrial designs, acoustic engineering specialists with captive driver manufacturing, and contract manufacturers serving private-label retail programs. Strategic moves concentrate on M&A for entertainment property rights and capacity expansion in TPE cable sheathing production lines.
Among diversified electronics conglomerates, Sony and JBL exemplify scale-driven positions with in-house component manufacturing and established institutional procurement relationships. Puro Sound Labs occupies a focused specialist tier, representing pure-play engineering approaches centered on pediatric hearing protection architectures. These three anchors demonstrate how competitive positioning diverges between integrated conglomerates with entertainment licensing leverage and specialized independents with regulatory compliance depth.
| Leading Market Players |
|---|
| Sony |
| JBL |
| iClever |
| Puro Sound Labs |
| Koss |
| Sennheiser |
| Kidz Gear |
| Snug |
| Belkin |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between ANSM-compliant and non-compliant SKUs splits the market into premium and commodity tiers, with French-bound production lines commanding higher unit economics due to active circuitry BOM inflation while standard configurations compete on copper conductor efficiency and PVC substitution economics.
Pricing Analysis
Bundled service contracts with K-12 districts are displacing transactional unit sales as the dominant pricing structure, with extended warranty and replacement provisioning bundled into multi-year offtake agreements. Price differentiation rests on certification tier—ANSM-compliant active limiting circuits versus passive resistor networks—and volume scale through education cooperative purchasing. Pricing pressure stems from LME copper volatility compressing margins on entry-level SKUs where gauge standards prevent conductor reduction. School districts exhibit highest price sensitivity, while travel retail channels absorb premium positioning for character-themed configurations.
Supply Chain Analysis
Regional distribution centers in Texas and California anchor hub-and-spoke patterns serving consolidated K-12 procurement platforms, bypassing traditional distributor markups. Manufacturing concentrates in China, Vietnam, and Mexico, with dynamic driver production clustering in Guangdong and Jiangsu provinces. Raw material dependencies center on copper conductors, neodymium driver magnets, and TPE cable sheathing alternatives to REACH-restricted PVC. Single-source vulnerability in Guangdong transducer manufacturing creates exposure for brands lacking captive production or qualified secondary vendors. Distribution runs through education service cooperatives, duty-free travel retail, and mass-market big-box channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between France's binding ANSM output caps and the United States' advisory FDA guidance creates margin expansion opportunities for dual-SKU strategies, with European-anchored testing relationships commanding premium positioning while North American volume scales through district procurement consolidation.
For Market Incumbents: Anticipate MEMS-based output monitoring displacement of passive limiting architectures by accelerating firmware development partnerships with Shenzhen engineering clusters. Defensive consolidation should prioritize captive driver manufacturing capacity in Jiangsu province to offset single-source exposure, while certification investment in ANSM testing relationships preserves European market access against emerging pure-play specialists. For New Entrants and Emerging Players: Launch via direct-to-district sales models targeting Texas and California education cooperatives with antimicrobial over-ear configurations and detachable cable architectures qualifying for EU Green Deal repairability credits. White-space targets include toddler-focused travel retail at Singapore Changi and Dubai International, plus TPE cable sheathing supply contracts to German manufacturers facing REACH substance restrictions. For Investors and Strategic Acquirers: Consolidation pressure builds where bulk purchasing consortia disintermediate traditional distribution channels, compressing mid-tier brand economics. Long-term viability favors pure-play pediatric hearing protection specialists with ANSM-compliant supply chains and entertainment IP licensing leverage over diversified conglomerates with conflicting portfolio priorities. Acquisition target archetype: European-anchored brands with established testing relationships and modular design platforms. Signal to watch: district RFP specification of MEMS-based real-time decibel tracking as mandatory versus preferred.| Strategic Initiative | Industry Significance |
|---|---|
| ANSM Certification Investment | Active volume-limiting circuitry development secures French market access against binding output caps. |
| Captive Driver Manufacturing | In-house Guangdong or Jiangsu transducer production reduces single-source exposure from concentrated supplier clusters. |
| Education Cooperative Direct Sales | Texas and California district bypass of distributor markups demands dedicated institutional account infrastructure. |
| TPE Cable Sheathing Transition | REACH-compliant alternatives to PVC jacketing qualify for extended producer responsibility credits in Germany. |
| Entertainment IP Licensing | Exclusive co-development windows with streaming-native franchises anchor premium retail shelf positioning. |
Research Methodology
Direct dialogue with K-12 procurement officers, audiology-focused acoustic engineers, education cooperative administrators, and TPE material suppliers grounded qualitative insights, cross-referenced with ANSM certification databases, ECHA substance restriction filings, district RFP documentation, and customs trade records for copper conductor and driver component flows. Bottom-up demand modeling from institutional procurement volumes triangulated against top-down market sizing from retail channel audits and manufacturer shipment disclosures.
Segmentation outputs across product type, age cohort, connectivity architecture, and design feature dimensions structured the analytical framework over the projection horizon. CAGRs derived from regression analysis of historical education technology procurement cycles and parental safety consciousness trend indicators, with copper price elasticity and regulatory compliance cost trajectories as pediatric audio-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt REACH substance restriction expansion or LME copper price spike scenarios. Decision-makers should treat outputs as directional within the stated assumption set, recognizing that divergent decibel measurement methodologies between ANSM and FDA regimes may force SKU fragmentation beyond modeled scenarios.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Global Smart Earbuds Market
Consumer Electronics
Digital Cloud Picture Frame Market
Consumer Electronics
Pillow Holder for Tablets Market
Consumer Electronics
Portable Smart Speaker Market
Consumer Electronics
In-Ear-Monitors (Iems) Market
Consumer Electronics
Smartphone Console Market
Consumer Electronics
Action Camera Market
Consumer Electronics
Middle East and Africa Mobile Phone Accessories Market
Consumer Electronics
Ereader Market
Consumer Electronics
Mini Bluetooth Shower Speaker Market
Consumer Electronics
Global Earphones and Headphones Market
Consumer Electronics
Global Smart Outdoor TV Market
Consumer Electronics
Global Beauty Camera Apps Market
Consumer Electronics
True Wireless Stereo Market
Consumer Electronics
TV Mirror Market
Consumer Electronics
China Refurbished Smartphone Market