
 Wireless Mouse Market | 2026-2036
Wireless Mouse Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Mouse Market Outlook
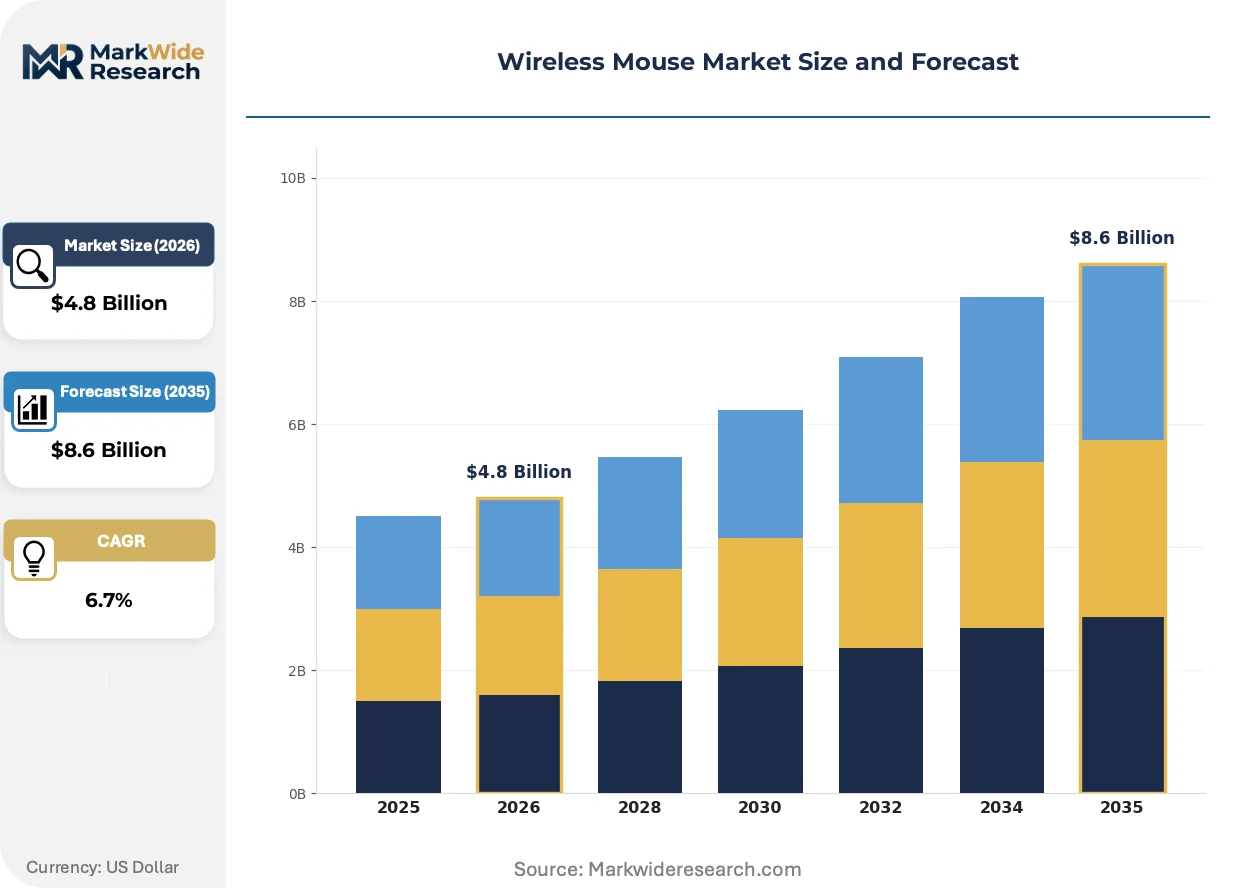
Enterprise procurement teams are redrawing the Wireless Mouse Market as hybrid work policies permanently alter peripheral refresh cycles. Logitech leverages its enterprise channel partnerships to sustain recurring volume from Fortune 500 IT departments. Razer Inc. anchors the gaming sub-segment with high-DPI sensor specialization that commands premium positioning. Microsoft competes through Surface ecosystem integration, controlling cross-device compatibility as a switching cost.
A wireless mouse is a cordless human interface device that translates hand motion into cursor control through optical or laser sensors, typically operating via Bluetooth or radio frequency protocols with polling rates from 125 Hz to 1000 Hz. Its primary commercial purpose is to eliminate cable clutter while enabling precise cursor manipulation across computing environments from cubicles to esports arenas. RF Mouse units still dominate enterprise bulk purchasing due to plug-and-play reliability with legacy workstations, though Bluetooth Mouse configurations are capturing share as USB-C native laptops proliferate. Multi-Device Mouse offerings concentrate margin pools among mobile professionals who switch between laptops and tablets, while Ergonomic Mouse designs deepen penetration among office workers with repetitive strain concerns.
The FCC governs radio frequency emissions for wireless peripherals sold in the United States, while the EU Radio Equipment Directive mandates interoperability and spectrum efficiency across member states, and China's MIIT certifies transmission protocols for devices entering its domestic channels. These frameworks shape product development roadmaps by dictating transmitter power limits, frequency bands, and labeling requirements that determine market access timelines. Stakeholders must monitor evolving energy efficiency mandates and right-to-repair regulations that could alter battery design and product lifecycle strategies.
Market Dynamics
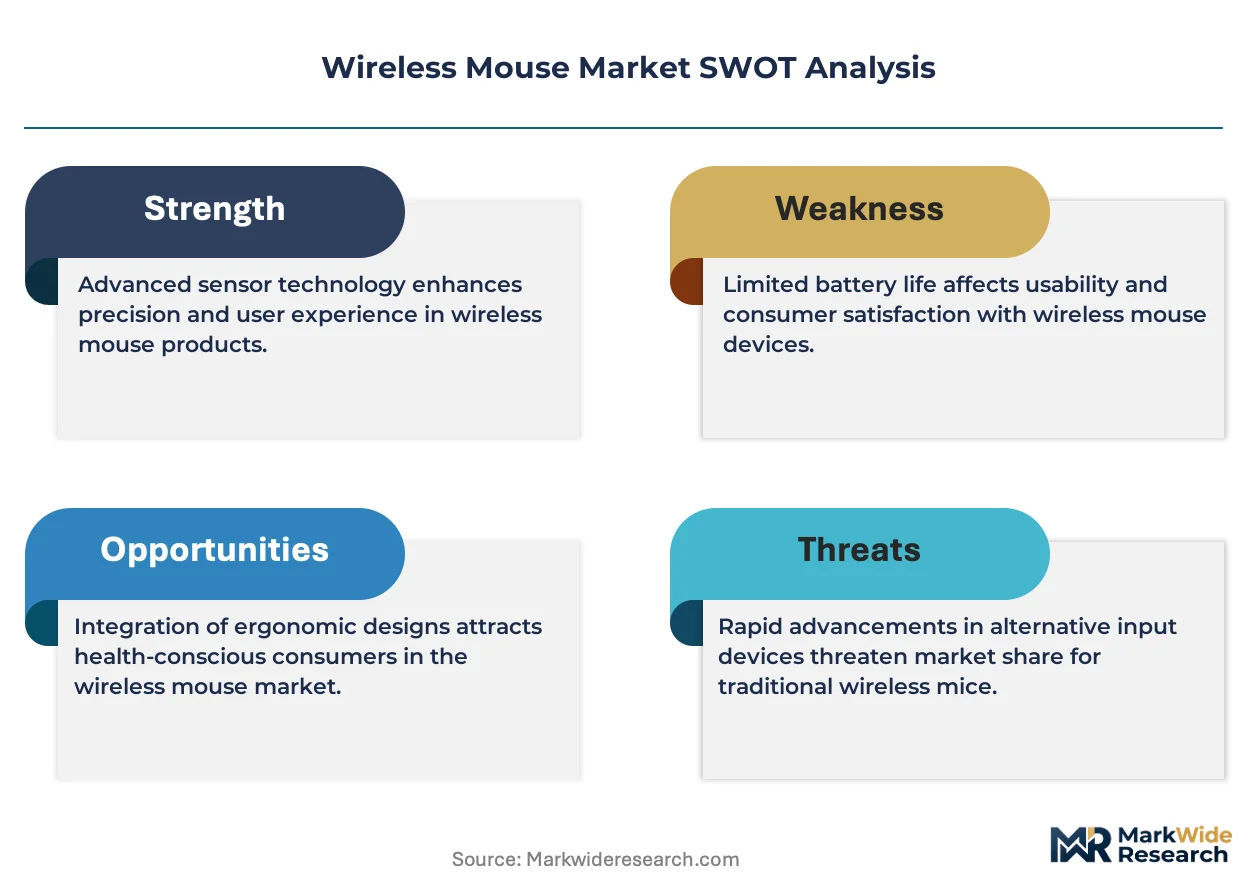
Bluetooth Low Energy is bifurcating the connectivity stack as enterprise IT departments mandate wireless peripherals compatible with USB-C native laptops, forcing RF-only suppliers toward dual-protocol hardware redesigns.
Growth Catalysts
- EU Right-to-Repair mandates:Battery replacement requirements extend product lifecycles and create recurring aftermarket revenue streams for peripheral manufacturers serving sustainability-conscious procurement teams.
- Hybrid work infrastructure:Enterprise IT departments in the United States, China, and Germany are standardizing multi-device peripherals for employees rotating between home offices and corporate facilities.
- Ergonomic certification programs:Workplace safety regulators in Germany and Japan are incentivizing employers to procure RSI-preventive input devices through tax-advantaged wellness spending categories.
Market Restraints
- Lithium-ion cell volatility:Battery raw material cost swings and supply concentration in Chinese processing facilities compress margin predictability for rechargeable wireless mouse portfolios.
- FCC transmitter certification timelines:Radio frequency device approval queues in the United States extend product launch windows by four to eight months versus Bluetooth alternatives.
- Touchscreen substitution:Direct-manipulation interfaces on tablets and convertible laptops erode addressable demand for traditional pointing devices among casual productivity users.
Strategic Opportunities
- India's PLI scheme for electronics:Manufacturing incentive programs attract assembly investment for export-oriented peripheral production serving Middle East and African markets.
- Gaming-ergonomic convergence:Esports athletes and remote professionals share demand for precision sensors and wrist-supportive form factors, collapsing previously separate SKU strategies.
- Healthcare IT modernization:Hospital system procurement of antimicrobial-surface peripherals creates a specialized channel with premium pricing tolerance and multi-year replacement contracts.
Industry Challenges
- Firmware security certification:Enterprise buyers now require SBOM documentation and CVE response SLAs that strain development resources at mid-tier peripheral vendors.
- Legacy workstation compatibility:IT departments maintaining Windows 7 and USB-A hardware fleets demand RF dongle inclusion that conflicts with streamlined Bluetooth-only BOM targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Mouse Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bluetooth Mouse, RF Mouse, Multi-Device Mouse, Ergonomic Mouse End User: Office Workers, Gamers, Graphic Designers, Students Connectivity: Bluetooth, RF, USB-C, Infrared Design: Compact, Adjustable, Ambidextrous, Stylish |
| Companies Covered | Logitech, Razer Inc., Microsoft, Hewlett Packard Enterprise Development LP, Apple, Inc., Dell Inc., Anker Innovations Ltd., Lenovo, SAMSUNG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Mouse Market Strategic Shifts
Sensor architecture and connectivity standards are fragmenting into parallel development tracks as gaming performance requirements diverge from enterprise sustainability mandates.
Optical sensor technology is bifurcating into two performance tiers. High-DPI laser arrays above 25,000 CPI now serve esports professionals and creative workstations requiring sub-pixel precision. Standard optical sensors below 8,000 CPI dominate enterprise bulk purchasing where battery longevity outweighs sensitivity. This technical split is compressing mid-range sensor demand and forcing component suppliers to specialize rather than serve both segments.
REACH substance restrictions are compelling material transitions across European supply chains. Phthalate-free cable sheathing and brominated flame retardant elimination now apply to wireless mouse charging cables and internal PCBs. Vendors serving EU enterprise channels are accelerating TCO-certified and EPEAT-registered product lines to preempt procurement exclusion risks.
Enterprise buying committees are consolidating peripheral vendor relationships into single-source framework agreements. IT departments at Fortune 500 firms now negotiate three-year global contracts covering mice, keyboards, and video conferencing hardware rather than category-specific tenders. This pattern is most visible in United States technology and financial services sectors where procurement centralization reduces supplier management overhead.
Wireless Mouse Market Segmentation
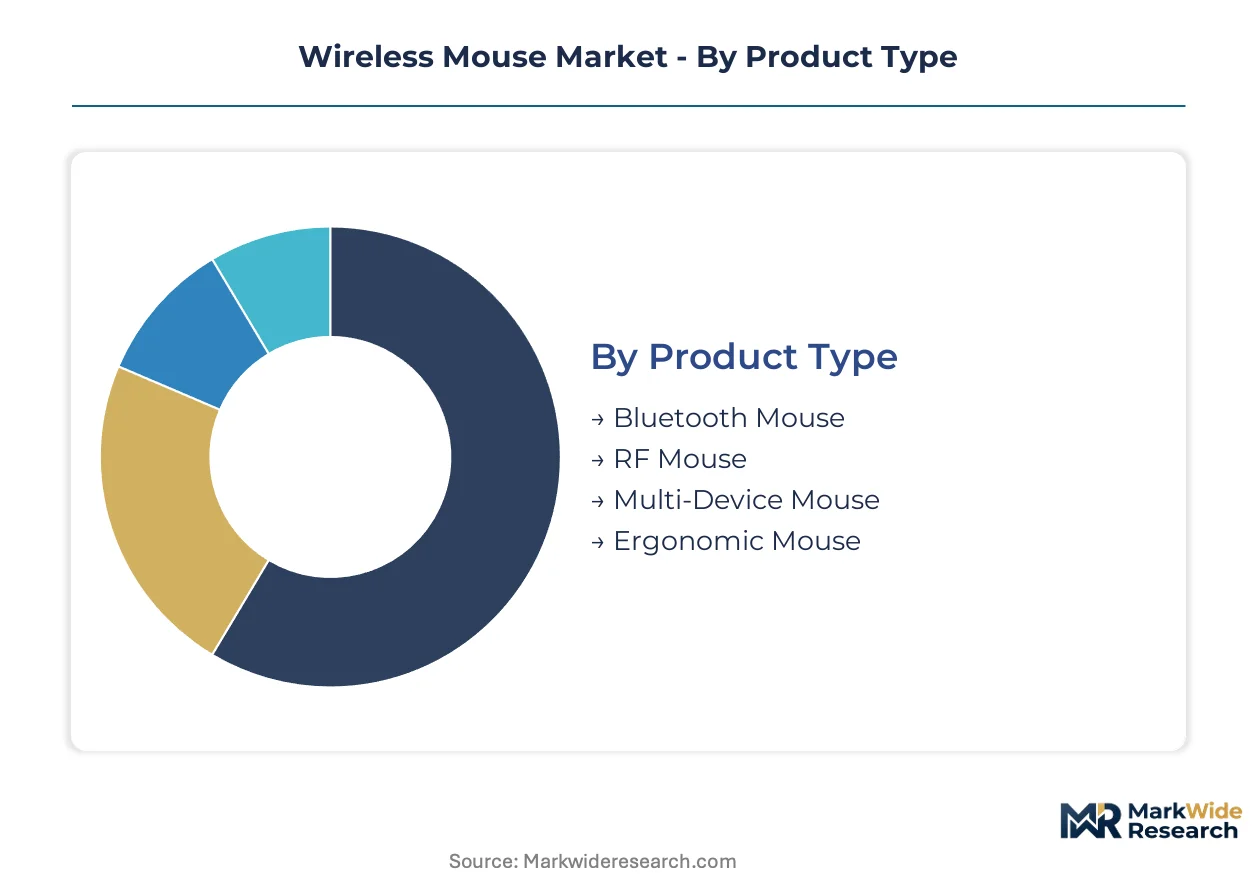
Wireless mouse segmentation reveals divergent channel strategies across enterprise procurement, retail gaming, and direct-to-consumer wellness verticals. Component sourcing and certification requirements vary sharply between Bluetooth-native corporate SKUs and RF-dongle legacy compatibility lines.
Product Type:
Enterprise distributors push RF and ergonomic variants through IT reseller channels, while consumer electronics retailers favor Bluetooth and multi-device configurations for laptop accessory bundles.
- Bluetooth Mouse:USB-C native laptops from Dell, HP, and Lenovo mandate Bluetooth Low Energy compatibility, displacing RF dongles in corporate refresh cycles across United States and German enterprise accounts.
- RF Mouse:2.4 GHz radio frequency protocols with proprietary USB-A dongles maintain plug-and-play reliability for legacy workstation fleets in government and healthcare IT environments where driver installation is restricted.
- Multi-Device Mouse:Channel flow concentrates through mobile-first retailers serving remote professionals.
- Ergonomic Mouse:Vertical and trackball designs deepen penetration among repetitive strain injury prevention programs.
RF Mouse dominates installed base. Bluetooth Mouse is where expansion concentrates.
End User:
Cost tier stratification separates premium sensor specifications for creative professionals from economy optical units for institutional education purchasing.
- Office Workers:Bulk procurement through framework agreements with Fortune 500 IT departments standardizes on TCO-certified peripherals with three-year replacement cycles and centralized firmware management.
- Gamers:Esports and streaming communities drive demand for sub-1ms latency, 25,000+ CPI sensors, and customizable weight systems through specialty retailers and team sponsorship channels.
- Graphic Designers:Adobe Creative Cloud workflows demand precision scroll wheels and programmable buttons.
- Students:Education sector volume concentrates in back-to-school retail promotions and institutional laptop bundles.
Office Workers anchor volume commitments. Gamers command the steepest expansion trajectory.
Connectivity:
Application environment dictates protocol selection, with electromagnetic interference tolerance and pairing speed becoming critical differentiators.
- Bluetooth:Windows, macOS, iPadOS, and ChromeOS native stack compatibility eliminates dongle inventory management for IT departments supporting heterogeneous device fleets.
- RF:Dedicated spectrum avoids Bluetooth congestion in dense cubicle environments and maintains connection stability for financial trading floors where latency sensitivity exceeds consumer norms.
- USB-C:Charging and data through single-cable docks aligns with modern laptop port reduction.
- Infrared:Legacy conference room and kiosk applications persist in controlled line-of-sight installations.
RF retains legacy infrastructure lock-in. Bluetooth is climbing the fastest.
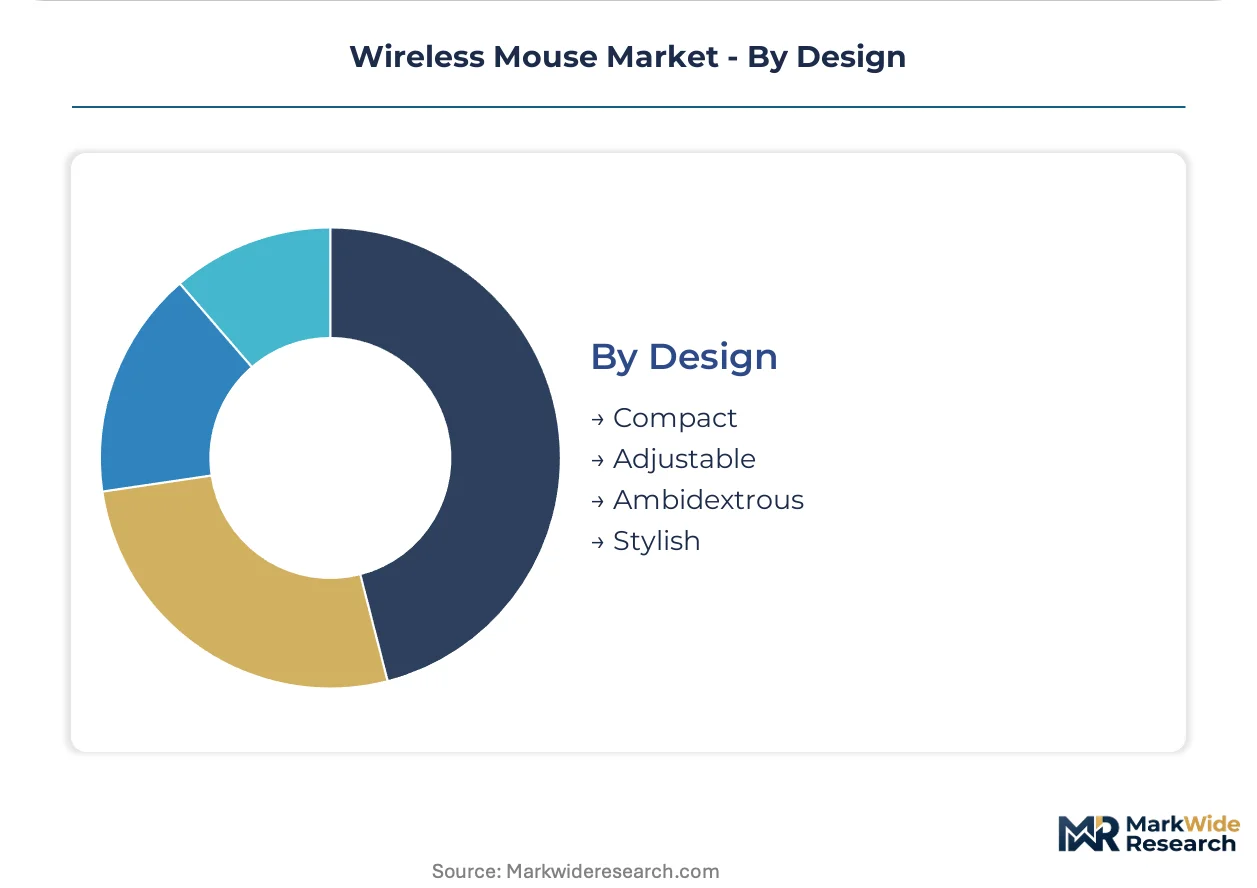
Design:
Customer type and usage mobility determine form factor trade-offs between portability and extended-session comfort.
- Compact:Road warriors and co-working space users prioritize pocketable dimensions under 100mm length, sacrificing palm support for bag-friendly profiles.
- Adjustable:Modular palm rests and interchangeable side panels accommodate hand size variation across shared workstation deployments in call centers and hot-desking corporate environments.
- Ambidextrous:Symmetrical shells serve left-handed users and institutional purchasing standardization.
- Stylish:Material finishes and colorway differentiation target consumer aesthetic preferences.
Compact and adjustable variants split volume between mobile and fixed applications. Ambidextrous designs are gaining share fastest in institutional procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Assembly capacity clusters in Chinese coastal provinces serving export demand, while consumption concentrates in North American and European enterprise corridors where IT refresh cycles drive replacement volume.
United States
FCC transmitter certification queues and enterprise framework agreements dominate procurement dynamics for IT departments refreshing hybrid work peripherals. The Inflation Reduction Act's domestic manufacturing incentives are reshaping assembly location decisions for brands serving federal accounts. Austin and Seattle tech corridors anchor software-integrated peripheral development teams.
Germany
REACH substance restrictions and TCO certification requirements filter supplier access to public sector and corporate procurement channels. Ergonomic workplace regulations incentivize RSI-preventive input device spending through tax-advantaged wellness categories. Bavaria's industrial automation cluster drives precision sensor engineering for premium peripheral lines.
China
MIIT transmission protocol certification governs domestic market entry while Shenzhen and Dongguan manufacturing zones supply global volume for Bluetooth and RF mouse assembly. The dual carbon goals policy pressures battery supplier selection and charging efficiency specifications. Yangtze River Delta electronics corridors concentrate ODM capacity for multinational brand sourcing.
Japan
METI energy efficiency standards and workplace ergonomics guidelines shape enterprise peripheral specifications for precision manufacturing and creative professional segments. JIS certification requirements create compliance thresholds for domestic channel access. Osaka-Kansai industrial districts maintain specialized component supply chains for high-DPI sensor modules.
India
PLI scheme electronics manufacturing incentives attract assembly investment targeting Middle East and African export markets from Tamil Nadu and Karnataka production zones. BIS quality certification mandates filter import channels for organized retail and enterprise procurement. Mumbai and Delhi-NCR distribution hubs serve domestic IT reseller and e-commerce channels.
Wireless Mouse Market Competitive Environment
Concentration sits with diversified electronics conglomerates controlling enterprise procurement relationships and integrated software-hardware ecosystems. The vendor base spans three functional tiers: ecosystem-integrated platform owners, specialized gaming peripheral developers, and contract-manufacturing-dependent value brands. Strategic moves center on multi-year framework agreement capture and sensor technology licensing rather than capacity expansion.
Within the ecosystem-integrated tier, Logitech, Microsoft, and Apple occupy positions defined by cross-device compatibility lock-in and enterprise channel density. Logitech exemplifies the peripheral-specialist archetype sustained by Fortune 500 IT procurement relationships. Microsoft anchors platform-integrated positioning through operating system-native optimization. Apple represents closed-ecosystem premium positioning tethered to Mac and iPad hardware refresh cycles.
| Leading Market Players |
|---|
| Logitech |
| Razer Inc. |
| Microsoft |
| Hewlett Packard Enterprise Development LP |
| Apple, Inc. |
| Dell Inc. |
| Anker Innovations Ltd. |
| Lenovo |
| SAMSUNG |
| Others |
Value Chain & Pricing Dynamics
REACH substance restrictions gate supplier qualification while simultaneously stratifying price tiers across European enterprise channels, compelling vendors to absorb certification costs or exit premium procurement pools entirely. This regulatory filter compresses mid-market positioning and concentrates margin capture among TCO-certified and EPEAT-registered product lines.
Pricing Analysis
REACH substance restrictions dictate the pricing tier structure across European enterprise channels, separating phthalate-free certified peripherals from uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects sensor performance grades and ergonomic certification status. Cost compression in economy optical units is intensifying because education sector procurement consolidates volume into framework agreements. Students and institutional buyers exhibit highest price sensitivity; esports professionals and creative workstations demonstrate lowest sensitivity to premium positioning.
Supply Chain Analysis
Strategic stockpile preferences dominate component procurement for high-DPI sensor modules and lithium-ion cells, buffering against raw material volatility. Assembly draws from China, Vietnam, and Malaysia for final peripheral production, with precision sensor engineering concentrated in Japan and Germany. Single-source vulnerability sits with Chinese rare earth processing for magnet components in scroll wheel assemblies. Distribution runs through enterprise IT resellers, consumer electronics retailers, and direct-to-consumer wellness channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise firmware security certification and multi-protocol hardware design capabilities are scarce assets that determine framework agreement capture, with mid-tier vendors lacking SBOM documentation expertise facing procurement exclusion.
For Market Incumbents: Consolidate enterprise channel relationships through three-year global framework agreements covering mice, keyboards, and video conferencing hardware. Deepen backward integration into precision sensor module production to defend margin position against component cost volatility. Threat substitution from touchscreen interfaces on convertible laptops demands sensor performance differentiation as switching cost reinforcement. For New Entrants and Emerging Players: BIS fast-track certification for India's PLI scheme electronics manufacturing incentives unlocks assembly investment targeting Middle East and African export markets. Healthcare IT modernization for antimicrobial-surface peripherals represents the most penetrable white-space, with hospital system procurement tolerating premium pricing for multi-year replacement contracts. Direct-to-occupational-health channel partnerships bypass established retail gatekeepers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across multi-protocol hardware redesigns as enterprise IT departments mandate Bluetooth Low Energy compatibility with USB-C native laptops. Long-term viability favors acquisition targets with captive firmware development resources and existing FCC transmitter certification queues. Signal to watch: enterprise buyer SBOM documentation requirements crossing threshold from preference to mandatory procurement filter.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Protocol Hardware Redesign | Bluetooth Low Energy and RF dual-stack compatibility captures USB-C laptop refresh cycles across Fortune 500 accounts. |
| Ergonomic Certification Investment | TCO and EPEAT registration preempts procurement exclusion from sustainability-conscious German enterprise buyers. |
| Firmware Security Documentation | SBOM and CVE response SLAs satisfy enterprise IT requirements that strain mid-tier vendor development resources. |
| Healthcare Channel Partnership | Antimicrobial-surface peripherals access premium pricing tolerance through hospital system multi-year replacement contracts. |
| India PLI Assembly Investment | Tamil Nadu and Karnataka production zones serve Middle East and African export markets with BIS quality certification. |
Study Parameters
Operator-level perspectives from IT procurement directors, enterprise firmware security officers, ODM production planners, and channel distribution managers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against FCC filing databases, EU Radio Equipment Directive certification registries, MIIT transmission protocol approvals, and enterprise framework agreement disclosures. Bottom-up unit volume estimates triangulated with top-down market sizing from customs trade data and retail audit channels.
Sensitivity analysis tested forecast robustness across alternative adoption scenarios for Bluetooth versus RF protocol penetration. Segmentation dimensions modeled include connectivity standard, end-user vertical, design form factor, and regional regulatory cluster. CAGRs were derived from logistic diffusion curves fitted to historical replacement cycle data and projected enterprise refresh timelines. Industry-specific inputs incorporated polling rate specification trends and battery chemistry transition assumptions.
Underlying assumptions cover hybrid work policy permanence, lithium-ion cell supply stability, and transmitter certification queue durations, with deviation risk concentrated in regulatory acceleration of right-to-repair mandates. Forecasts reflect these conditions without scenario-weighted probability assignments. Revision becomes warranted when Bluetooth Low Energy adoption crosses thresholds that render RF-dongle inventory economically stranded.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
DVD Remote Controls Market
Consumer Electronics
United States Gaming Peripherals Market
Consumer Electronics
Portable Media Player Market
Consumer Electronics
Instant Camera Market
Consumer Electronics
Ultra HD Action Camera Market
Consumer Electronics
Noise Cancelling Headphones Market
Consumer Electronics
Dive Computer Market
Consumer Electronics
Smart Mirror TV Market
Consumer Electronics
Pillow Holder for Tablets Market
Consumer Electronics
Portable Laptop Stands Market
Consumer Electronics
Wireless Earphone Market
Consumer Electronics
Refurbished Computer and Laptop Market
Consumer Electronics
Mechanical Keyboard Market
Consumer Electronics
True Wireless Stereo Market
Consumer Electronics
Vertical Ergonomic Optical Mouse Market
Consumer Electronics
United States Soundbar Market