
 Smart Pet Camera Market | 2026-2036
Smart Pet Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Pet Camera Market Insights
Online retail channels for smart pet cameras is fragmenting as direct-to-consumer brands bypass traditional electronics distributors and specialty pet retailers. Furbo leverages its subscription-based cloud storage model to sustain recurring revenue alongside hardware sales. Wyze Labs competes through aggressive price positioning in the entry-level segment while maintaining feature parity with premium alternatives. Eufy anchors its presence through Anker's established consumer electronics supply chain and brand recognition in home security adjacent categories.
A smart pet camera constitutes a networked visual monitoring device incorporating image sensors, motion processors, and bidirectional audio codecs designed for remote observation and interaction with companion animals. These devices typically operate at 1080p resolution with infrared night vision capability and integrate with mobile applications for real-time streaming and alert delivery. Indoor cameras dominate unit volume as apartment-dwelling pet owners prioritize space-appropriate form factors, while treat dispensers command premium pricing through motorized food delivery mechanisms that differentiate hardware value. Wi-Fi connectivity leads installation preference due to existing home network ubiquity, though cellular-enabled variants are gaining traction among rural property owners managing livestock or outdoor kennel operations.
The FCC governs radio frequency emissions for Wi-Fi and cellular-connected devices in the United States, requiring SAR testing and equipment authorization that extends time-to-market for new entrants. The EU AI Act imposes algorithmic transparency obligations on devices employing machine learning for pet behavior recognition or anomaly detection, affecting feature development roadmaps for manufacturers serving European consumers. Stakeholders must monitor evolving data privacy frameworks governing cloud-stored pet imagery and voice recordings as jurisdictions expand biometric and household surveillance regulations beyond human subjects.
Market Dynamics
Subscription-based cloud storage models are restructuring revenue architecture across the smart pet camera industry, decoupling hardware margins from long-term profitability and forcing manufacturers to build recurring revenue infrastructure alongside device engineering.
Growth Catalysts
- Remote Work Normalization:Urban pet owners now maintain regular absences from home offices, creating sustained demand for real-time visual monitoring and bidirectional interaction capabilities with companion animals.
- FCC Equipment Authorization Pathways:Established regulatory frameworks for Wi-Fi-enabled devices in the United States provide predictable compliance timelines that accelerate market entry for connectivity-focused hardware innovators.
- Shenzhen Electronics Cluster:Concentrated component sourcing and vertically integrated assembly operations compress production cycles and enable rapid feature iteration cycles for camera hardware.
Market Restraints
- Image Sensor Supply Concentration:Dependence on specialized CMOS sensor foundries in East Asia creates vulnerability to capacity constraints and geopolitical trade friction affecting hardware availability.
- Cloud Infrastructure Costs:Recurring data storage and streaming bandwidth expenses erode subscription margins and complicate free-tier customer acquisition strategies.
- EU AI Act Algorithmic Transparency:Machine learning-based pet behavior recognition features face disclosure obligations and documentation burdens that extend development timelines for European market variants.
Strategic Opportunities
- Livestock and Outdoor Kennel Applications:Cellular-enabled camera variants address connectivity gaps among rural property owners managing animals beyond Wi-Fi range, opening agricultural adjacent demand.
- Veterinary Telemedicine Integration:Bidirectional audio and high-resolution video streams enable remote clinical observation, positioning hardware as diagnostic infrastructure for distributed animal healthcare.
- Direct-to-Consumer Channel Expansion:Bypassing electronics distributors and specialty pet retailers captures margin otherwise surrendered to wholesale intermediaries in traditional retail structures.
Industry Challenges
- Embedded Firmware Security Expertise:Shortage of engineers capable of hardening IoT device architectures against botnet recruitment and unauthorized access attempts complicates product development.
- Cross-Jurisdictional Data Privacy Compliance:Cloud-stored pet imagery and voice recordings trigger divergent household surveillance and biometric regulations across state and national boundaries, multiplying legal review requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Pet Camera Market |
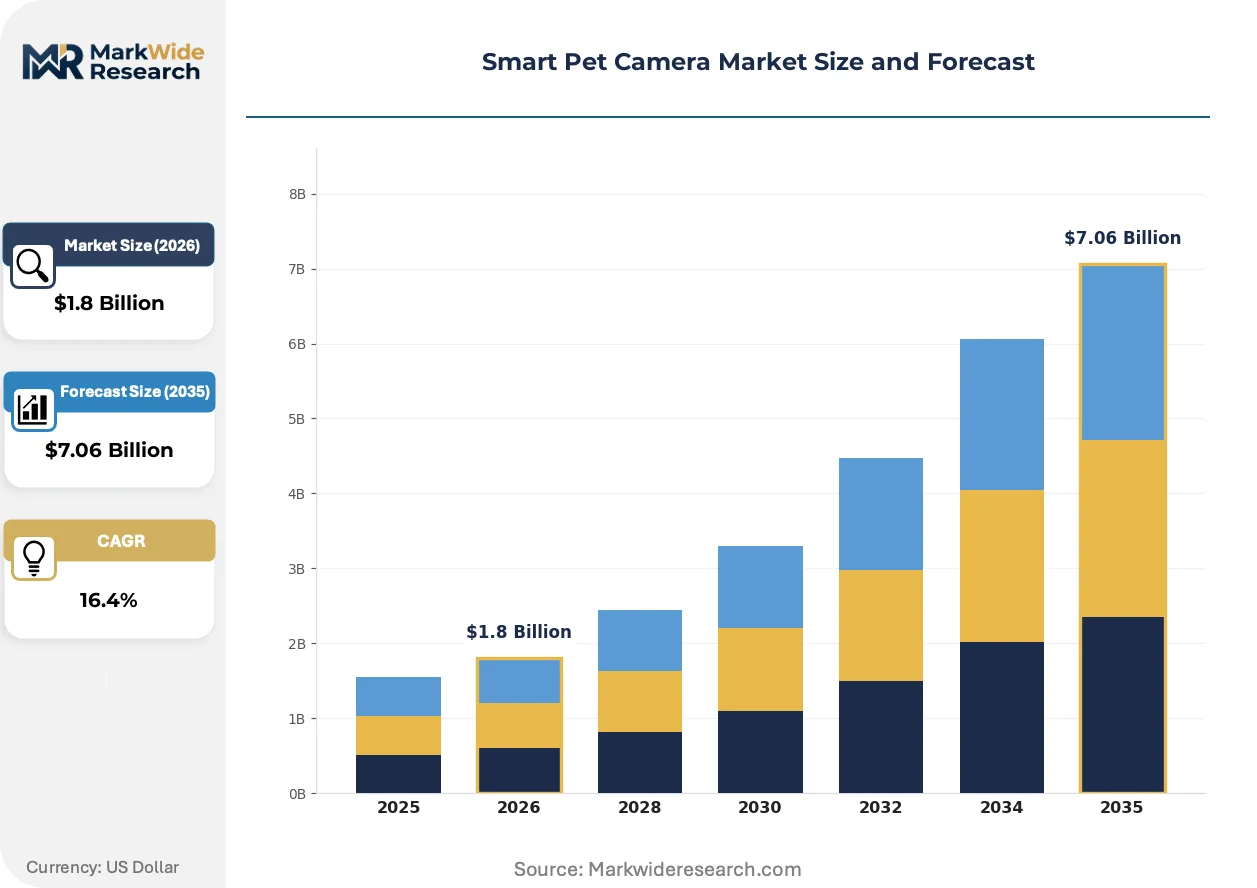
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Cameras, Outdoor Cameras, Treat Dispensers, Interactive Cameras Connectivity: Wi-Fi, Bluetooth, Ethernet, Cellular Feature: Night Vision, Two-Way Audio, Motion Detection, App Integration End User: Pet Owners, Pet Sitters, Veterinary Clinics, Animal Shelters |
| Companies Covered | Petcube, Furbo, Wyze Labs, Skymee, Pawbo, Zmodo, Eufy, SpotCam, PetChatz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Pet Camera Market Trends and Innovations
Hardware differentiation is compressing as software-defined features and AI-powered analytics assume primary competitive positioning, shifting engineering investment toward cloud infrastructure and algorithm development.
Edge-based motion detection is migrating from server-side processing to on-device inference using dedicated neural processing units. Apartment-dwelling pet owners with limited bandwidth prioritize local preprocessing that reduces upload volumes and improves alert latency. This architecture shift is enabling offline functionality during network interruptions and reducing cloud infrastructure costs for manufacturers.
The EU AI Act imposes documentation and transparency obligations on machine learning models employed for pet behavior classification or anomaly detection. European manufacturers must maintain technical files demonstrating algorithmic decision logic and performance validation. Smart pet camera variants serving EU consumers now require dedicated compliance engineering resources and extended certification timelines.
Subscription unbundling is fragmenting traditional hardware-plus-service bundles into componentized offerings. Buyers increasingly select tiered cloud storage, advanced analytics, or veterinary integration as separate purchases rather than accepting monolithic annual contracts. This pattern is most visible in North American direct-to-consumer channels where price transparency tools enable comparison shopping across feature combinations.
Smart Pet Camera Market Segmentation
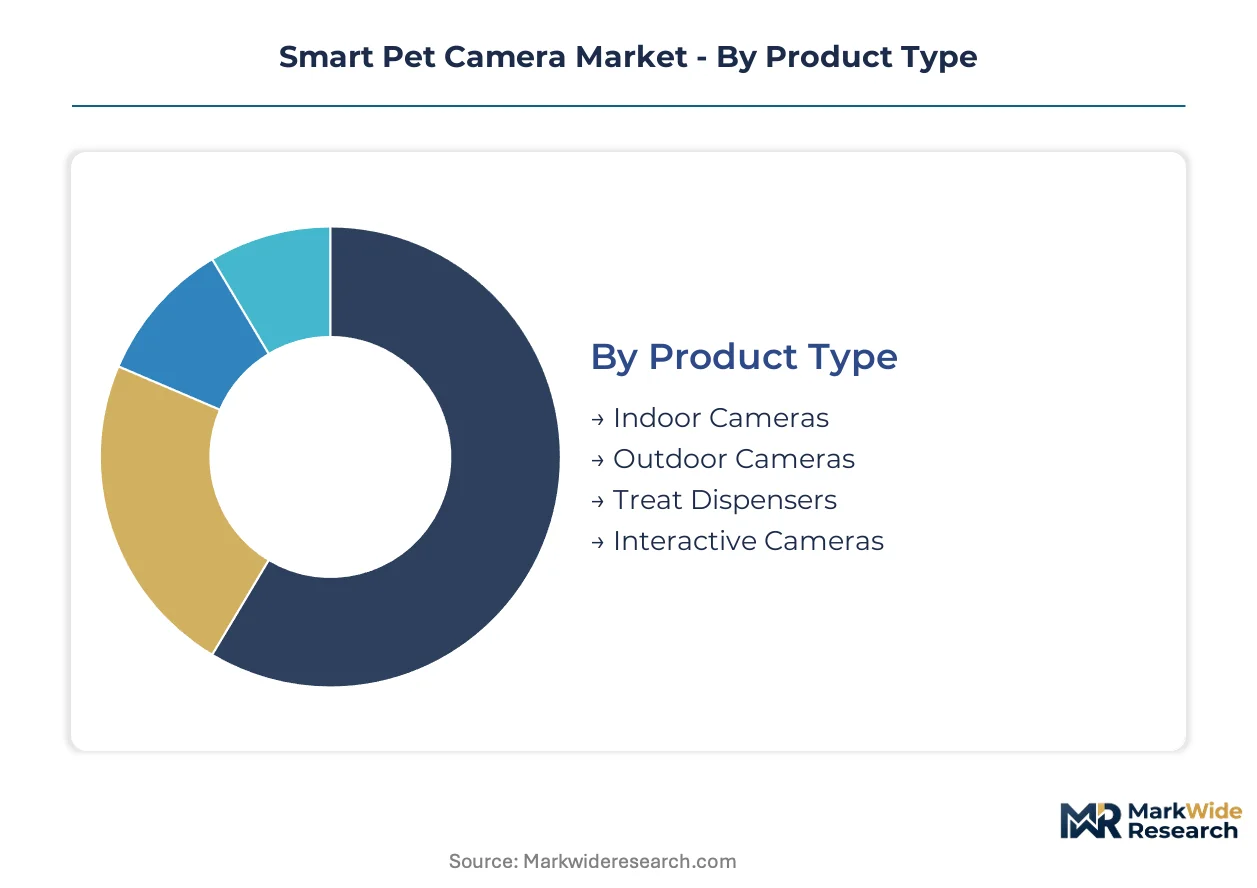
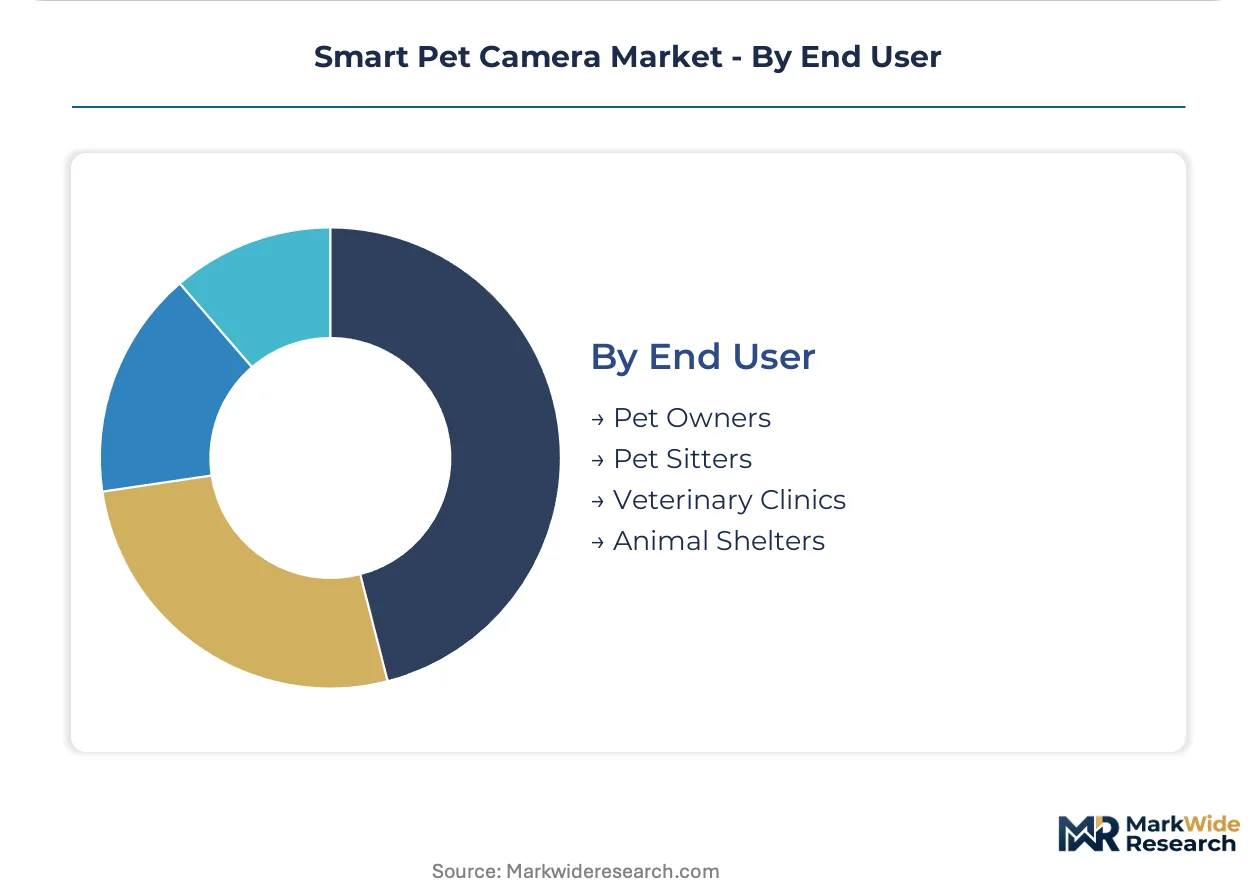
Smart pet camera segmentation reveals distinct hardware replacement cycles and feature adoption velocities across product architectures. Understanding these temporal patterns enables manufacturers to align inventory planning with demand pulsation across connectivity standards and end-use scenarios.
Product Type:
Indoor cameras turn over fastest as apartment dwellers upgrade for slimmer profiles and improved night vision, while outdoor units persist longer due to weatherproofing durability and installation friction.
- Indoor Cameras:Compact dome and cube form factors dominate urban apartment installations where space constraints dictate minimal footprint. Shenzhen manufacturers compress refresh cycles through rapid sensor upgrades. Demand concentrates in Chinese metropolitan areas where pet ownership rates climb fastest among millennial renters.
- Treat Dispensers:Motorized food delivery mechanisms integrate precision stepper motors with anti-jam auger designs for kibble consistency. These units command hardware premiums. North American households with separation-anxious dogs drive replacement demand as motor wear accelerates obsolescence.
- Outdoor Cameras:IP65-rated enclosures withstand temperature extremes and precipitation exposure for backyard and kennel monitoring. Rural property owners in the United States favor these for livestock applications beyond companion animals.
- Interactive Cameras:Pan-tilt-zoom actuators and laser pointer modules enable remote play engagement. Early adopters in Japan prioritize these features for working households with indoor cats.
Indoor cameras dominate installed base. Treat dispensers are where expansion concentrates.
Connectivity:
Cost tier stratification separates subscription-dependent cloud architectures from offline-capable local storage systems, with cellular commanding premium positioning for infrastructure-agnostic deployment.
- Wi-Fi:802.11ac and Wi-Fi 6 radios leverage existing residential network infrastructure for zero incremental connectivity cost. FCC equipment authorization pathways provide predictable certification timelines for United States market entry.
- Cellular:LTE-M and NB-IoT modems enable deployment beyond router range for rural properties and mobile veterinary units. Monthly data plans erode margins but unlock agricultural adjacent demand.
- Bluetooth:Low-energy protocols support proximity-based setup and local device pairing without internet dependency. European consumers favor these for GDPR-aligned data minimization strategies.
- Ethernet:Wired RJ45 connections eliminate wireless interference and bandwidth contention in multi-device smart home environments. Security-conscious buyers in Germany prefer physical network isolation.
Wi-Fi anchors volume shipments. Cellular is climbing the fastest among connectivity modes.
Feature:
Application-driven bundling concentrates engineering investment toward veterinary diagnostic capabilities and behavioral analytics, displacing basic streaming as the primary value proposition.
- Motion Detection:On-device neural processing units enable edge-based inference that reduces cloud upload volumes and alert latency. Apartment dwellers with bandwidth constraints prioritize this architecture.
- Two-Way Audio:Full-duplex codecs with echo cancellation support real-time voice interaction for separation anxiety mitigation. Veterinary telemedicine platforms in the United States integrate these streams for remote clinical observation.
- Night Vision:Infrared LED arrays and starlight sensors maintain visibility in zero-illumination conditions. Nocturnal pet owners and breeders of crepuscular species drive specification demands.
- App Integration:SDK-enabled connectivity with smart home ecosystems and third-party veterinary services creates platform stickiness. North American direct-to-consumer brands compete through API breadth.
Motion detection dominates feature prioritization. Two-way audio is gaining share fastest for telemedicine integration.
End User:
Customer type segmentation maps to divergent procurement patterns, with institutional buyers emphasizing fleet management and durability against individual consumer preference for aesthetic integration.
- Pet Owners:Individual consumers purchase single units through direct-to-consumer channels and electronics retailers. Urban households in China represent the steepest expansion trajectory as remote work normalizes extended absences.
- Veterinary Clinics:Multi-camera deployments enable remote post-operative monitoring and behavioral assessment. Diagnostic infrastructure requirements in the United States drive demand for high-resolution streaming and HIPAA-aligned data handling.
- Pet Sitters:Independent contractors deploy portable units across client households for verification and owner communication. Gig economy growth in metropolitan France supports this segment.
- Animal Shelters:High-density kennel monitoring requires ruggedized hardware with centralized management dashboards. Municipal procurement in the United States favors cellular-enabled variants for facilities lacking IT infrastructure.
Pet owners dominate installed base. Veterinary clinics are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shenzhen electronics cluster anchors Asia-Pacific production capacity through vertically integrated camera module assembly and compressed logistics cycles to the Port of Shenzhen.
United States
Remote work normalization in metropolitan corridors drives sustained demand for real-time pet monitoring solutions. FCC equipment authorization requirements govern Wi-Fi and cellular device certification timelines. San Francisco Bay Area engineering talent pools concentrate cloud infrastructure development for subscription-based camera platforms.
China
Millennial pet ownership rates in Shanghai and Beijing accelerate faster than any other urban cohort globally. MIIT radio transmission regulations shape product compliance for domestic connectivity standards. Shenzhen's Huaqiangbei electronics marketplace enables same-day component sourcing for camera hardware iteration cycles.
Germany
Security-conscious households in Berlin and Munich prioritize Ethernet-connected devices for network isolation. GDPR and EU AI Act obligations impose algorithmic transparency requirements on behavior recognition features. Bavarian industrial automation suppliers provide precision stepper motors for treat dispenser mechanisms.
Japan
Working households in Tokyo and Osaka drive interactive camera adoption with pan-tilt-zoom actuators for remote cat engagement. METI standards govern IoT device cybersecurity certification. Nagoya's precision manufacturing base supplies compact optical lens assemblies for space-constrained apartment installations.
United Kingdom
London's gig economy pet sitters deploy portable verification cameras across client households. The Information Commissioner's Office guidelines shape data handling for cloud-stored pet imagery. Cambridge technology clusters incubate edge-based motion detection algorithm development.
Smart Pet Camera Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct competitive tiers. Premium positioning relies on subscription-based cloud storage and veterinary telemedicine integration. Mid-market players compete through direct-to-consumer channel efficiency and aggressive price positioning. Entry-level specialists leverage Shenzhen manufacturing partnerships to compress hardware costs. Dominant competitive moves include strategic partnerships with smart home ecosystems and portfolio diversification into adjacent pet technology categories.
Within the subscription-anchored tier, Furbo exemplifies recurring revenue architecture through cloud storage bundling. Wyze Labs occupies a position among price-positioned hardware specialists competing on feature parity at entry-level price points. Eufy anchors the home security adjacent segment, leveraging established consumer electronics supply chain relationships for distribution scale.
| Leading Market Players |
|---|
| Petcube |
| Furbo |
| Wyze Labs |
| Skymee |
| Pawbo |
| Zmodo |
| Eufy |
| SpotCam |
| PetChatz |
| Others |
Pricing and Supply Chain Analysis
Single-source CMOS image sensor dependency in East Asian foundries compresses pricing tier spreads while simultaneously dictating supply chain geography. FCC equipment authorization timelines and EU AI Act compliance costs feed directly into premium-tier markups, forcing mid-market manufacturers to absorb certification burdens or surrender margin to Shenzhen-integrated competitors.
Pricing Analysis
Volume-discount tiering structures separate subscription-anchored premium offerings from transactional hardware-only sales. Three-tier pricing stratification across premium, standard, and economy levels reflects cloud storage bundling, veterinary telemedicine integration, and algorithmic feature depth. Pricing pressure stems from Wyze Labs' aggressive entry-level positioning that forces feature parity at compressed hardware margins. Individual pet owners in urban China exhibit highest price sensitivity, while veterinary clinics in the United States demonstrate lowest sensitivity due to diagnostic infrastructure requirements.
Supply Chain Analysis
Supplier-financing facilities from Shenzhen component distributors enable extended payment terms that compress working capital cycles for camera assemblers. Manufacturing concentrates in China, South Korea, and Taiwan, drawing from specialized CMOS sensors, precision stepper motors, and neural processing units. Single-source vulnerability in image sensor foundries threatens hardware availability during capacity constraints. Distribution runs through direct-to-consumer platforms and consumer electronics retail chains, bypassing traditional pet specialty wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where subscription-based cloud storage creates network effects that entrench incumbent positions. Switching costs compound as pet owners accumulate stored video archives and integrate veterinary telemedicine workflows.
For Market Incumbents: Harden firmware security architectures against botnet recruitment threats that erode brand trust and trigger regulatory scrutiny. Deepen backward integration into cloud infrastructure to capture subscription margins otherwise surrendered to third-party hosting providers. Prioritize FCC pre-certification investments to accelerate product launch cadence against emerging competitors. For New Entrants and Emerging Players: Establish a beachhead in cellular-enabled outdoor camera segments serving rural livestock applications where Wi-Fi-dependent incumbents hold weak positions. Target veterinary clinic procurement channels in the United States with HIPAA-aligned data handling as the primary go-to-market wedge. Agricultural adjacent demand remains underpenetrated relative to urban companion animal saturation. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors subscription-revenue platforms with established cloud infrastructure over pure hardware specialists. Long-term viability across the next decade hinges on recurring revenue architecture rather than transactional device margins. Watch for EU AI Act enforcement intensity as the signal indicating compliance-cost barriers that favor scaled incumbents over capital-constrained entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Telemedicine Integration | Positions hardware as diagnostic infrastructure for distributed animal healthcare delivery. |
| Edge-Based Motion Detection Migration | Reduces cloud upload volumes and latency for bandwidth-constrained apartment dwellers. |
| Direct-to-Consumer Channel Expansion | Captures margin surrendered to electronics distributors and pet specialty retailers. |
| Cellular Connectivity Variant Development | Unlocks agricultural adjacent demand among rural property owners beyond Wi-Fi range. |
| EU AI Act Compliance Engineering | Extends certification timelines but creates regulatory moats against under-resourced competitors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade databases, and industry association publications. Interviews with smart pet camera product managers, veterinary clinic procurement officers, consumer electronics retail buyers, and cloud infrastructure engineers informed demand-side assumptions. Secondary sources include FCC equipment authorization databases, MIIT radio transmission records, EU AI Act technical documentation, and Shenzhen customs export statistics. Bottom-up unit shipment estimates triangulate against top-down market value reconstructions.
Forecast inputs incorporate product type replacement cycles, connectivity mode adoption velocities, and end-user procurement patterns across the projection horizon. Segmentation dimensions span hardware architecture, connectivity standard, feature bundle, and customer type. CAGRs derive from fitted growth curves calibrated to observed technology diffusion patterns in adjacent consumer electronics categories. Veterinary telemedicine integration rates and subscription attach ratios serve as industry-specific demand modifiers.
Stress conditions across image sensor supply disruptions, FCC certification timeline extensions, and EU AI Act enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about remote work persistence and pet ownership demographic shifts. Macroeconomic contraction, regulatory deviation, or breakthrough battery technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Modern Cat Furniture Market
Pet Care Products
Bird Toy Market
Pet Care Products
Dog Nail Clippers Market
Pet Care Products
Cat Diets Market
Pet Care Products
Asia-Pacific Pet Travel Services Market
Pet Care Products
Dog Dental Chews Market
Pet Care Products
Cat Condos and Indoor Houses Market
Pet Care Products
Cat Bed Market
Pet Care Products
Pet Smart Tracker Market
Pet Care Products
Pet Stairs Market
Pet Care Products
Dog Seat Belt Market
Pet Care Products
Paw Plunger Market
Pet Care Products
Pet Molar Bite Toy Market
Pet Care Products
Freeze Dried Dog Food Market
Pet Care Products
Dog Clothing and Accessories Market
Pet Care Products
Dog Perfume Market