
 Education PC Market | 2026-2036
Education PC Market Size, Share, and Industry Trends Forecast 2026-2036
Education PC Market Analysis
ENERGY STAR certification for computers is collapsing as a baseline requirement, pushing vendors toward stricter efficiency and recyclability standards. Dell leverages its direct institutional sales channel to sustain large-volume contracts with U.S. public school systems. Lenovo dominates the K-12 Chromebook segment through aggressive pricing and Google partnership depth. HP anchors its education portfolio with service bundles that include device management and repair coverage.
Education PCs comprise computing hardware purpose-built for instructional environments, typically featuring reinforced chassis, spill-resistant keyboards, all-day battery endurance exceeding eight hours, and fleet management compatibility for centralized IT administration. These devices serve primary commercial purposes in structured learning, administrative operations, and remote instruction delivery. Chromebooks lead volume shipments among product types due to low acquisition cost and seamless Google Workspace integration, while cloud-based deployment models are displacing on-premises infrastructure as districts prioritize scalability and reduced IT overhead. Laptops command stronger margins than tablets among higher education institutions where full keyboard productivity remains essential.
FCC E-Rate program rules shape U.S. district purchasing timelines and technology refresh cycles, while EU RoHS and REACH directives constrain material composition for hardware sold across European member states. India's BIS certification mandates safety and electromagnetic compatibility testing for imported electronics, affecting vendor market entry pathways. Stakeholders must monitor evolving procurement centralization at state versus district levels, as this determines whether volume discounts or localized vendor relationships win contract awards.
Market Dynamics
Cloud-native deployment models are compressing traditional on-premises infrastructure refresh cycles, forcing vendors to restructure hardware margins around recurring service revenue rather than device sales alone.
Growth Catalysts
- FCC E-Rate Modernization:Expanded broadband infrastructure eligibility accelerates district-level procurement timelines and enables larger-volume student device contracts.
- India's State Digital Literacy Programs:State-level procurement centralization creates predictable demand pipelines for hardware vendors targeting government education tenders.
- Google Workspace Integration:Seamless cloud productivity suites reduce IT administration overhead and drive Chromebook preference among K-12 technology coordinators.
Market Restraints
- Semiconductor Input Volatility:Memory and processor component pricing fluctuations compress hardware margins during contract bidding periods.
- EU REACH Compliance Costs:Material composition testing and documentation requirements add fixed overhead for vendors distributing across European member states.
- Tablet Substitution Pressure:Lower-cost touchscreen devices capture budget-conscious segments where keyboard productivity is not mandatory.
Strategic Opportunities
- India's BIS Certification Pathways:Pre-certified hardware platforms enable faster market entry for vendors targeting state government education tenders.
- Device-as-a-Service Models:Subscription-based hardware provisioning shifts capital expenditure to operational budgets, appealing to cash-constrained districts.
- AI-Assisted Classroom Analytics:Convergence of edge computing and machine learning enables real-time student engagement monitoring as a premium feature tier.
Industry Challenges
- Fleet Management Certification Complexity:Multi-platform compatibility testing delays product launches for vendors supporting heterogeneous district IT environments.
- Legacy Infrastructure Integration:Hybrid cloud deployments require sustained engineering resources to bridge on-premises authentication systems with modern endpoint management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Education PC Market |
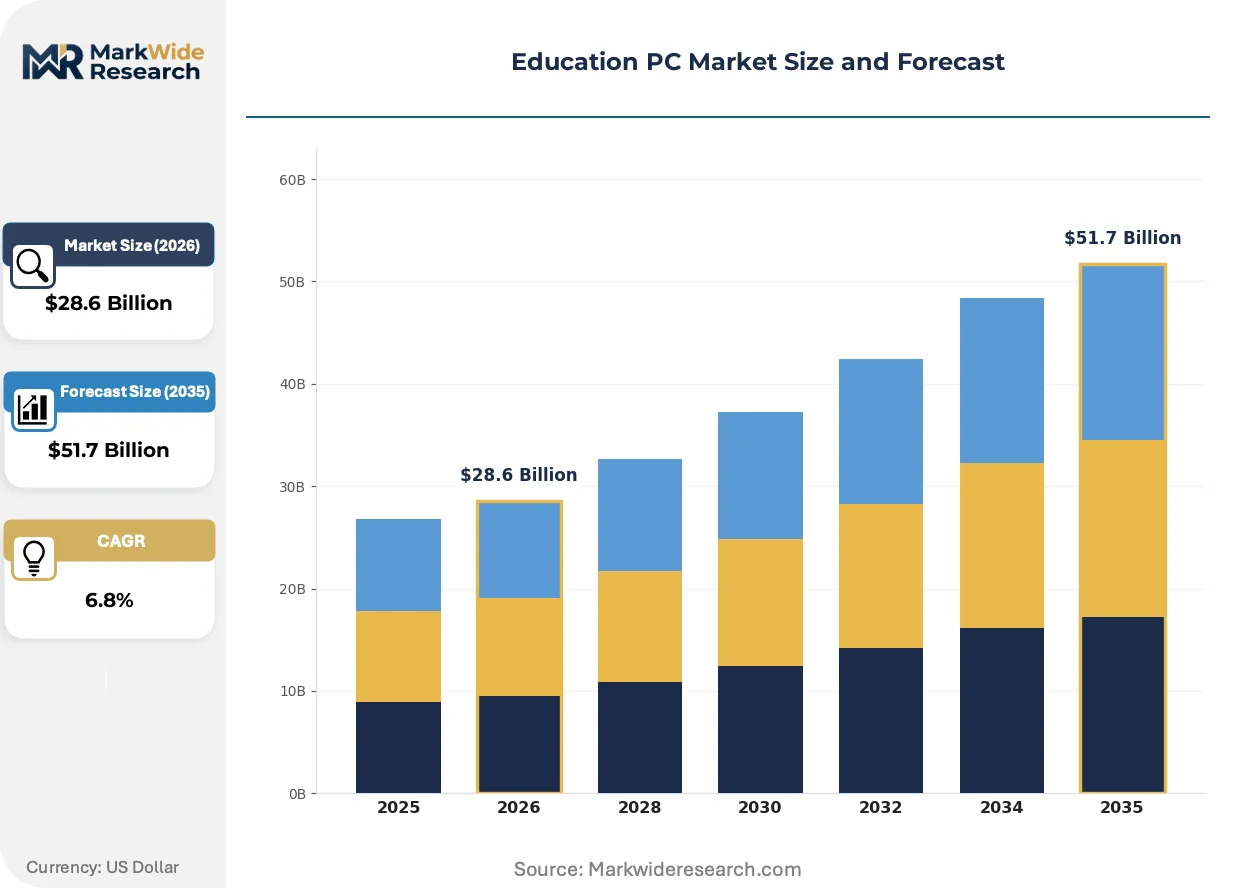
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktops, Laptops, Tablets, Chromebooks End User: K-12 Students, Higher Education Institutions, Educators, Administrative Staff Deployment: On-Premises, Cloud-Based, Hybrid, Remote Technology: Windows, macOS, Chrome OS, Linux |
| Companies Covered | Apple, Samsung, Dell, Microsoft, Acer, HP, ASUS, Elitegroup Computer Systems, Lenovo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Education PC Market Emerging Trajectories
Hardware architectures are fragmenting between low-cost cloud-dependent endpoints and premium locally-capable devices, creating divergent R&D investment requirements for vendors serving both segments simultaneously.
Modular component design is decomposing traditional monolithic laptop construction in education hardware. K-12 districts with limited IT staffing are adopting field-replaceable keyboard, battery, and port modules to extend device lifecycles. This modularity is decomposing the three-year refresh norm into five-to-six year replacement cycles, compressing unit volume growth while expanding per-unit service attach rates.
EU Ecodesign regulations are mandating repairability scoring and standardized component access for computers sold across member states. Hardware vendors must redesign chassis architectures to accommodate screwdriver-accessible internals and publish spare parts availability timelines. Higher education procurement teams in Germany and France are incorporating these repairability indices into tender evaluation criteria ahead of full regulatory enforcement.
District purchasing behavior is consolidating around cooperative procurement vehicles and state-level master contracts. Individual school IT directors are losing autonomy to centralized state technology offices that negotiate volume pricing and standardize device specifications. Texas and California education agencies now control hardware selection for the majority of their constituent districts, compressing vendor sales cycles but intensifying price competition at the contract level.
Education PC Market Segmentation
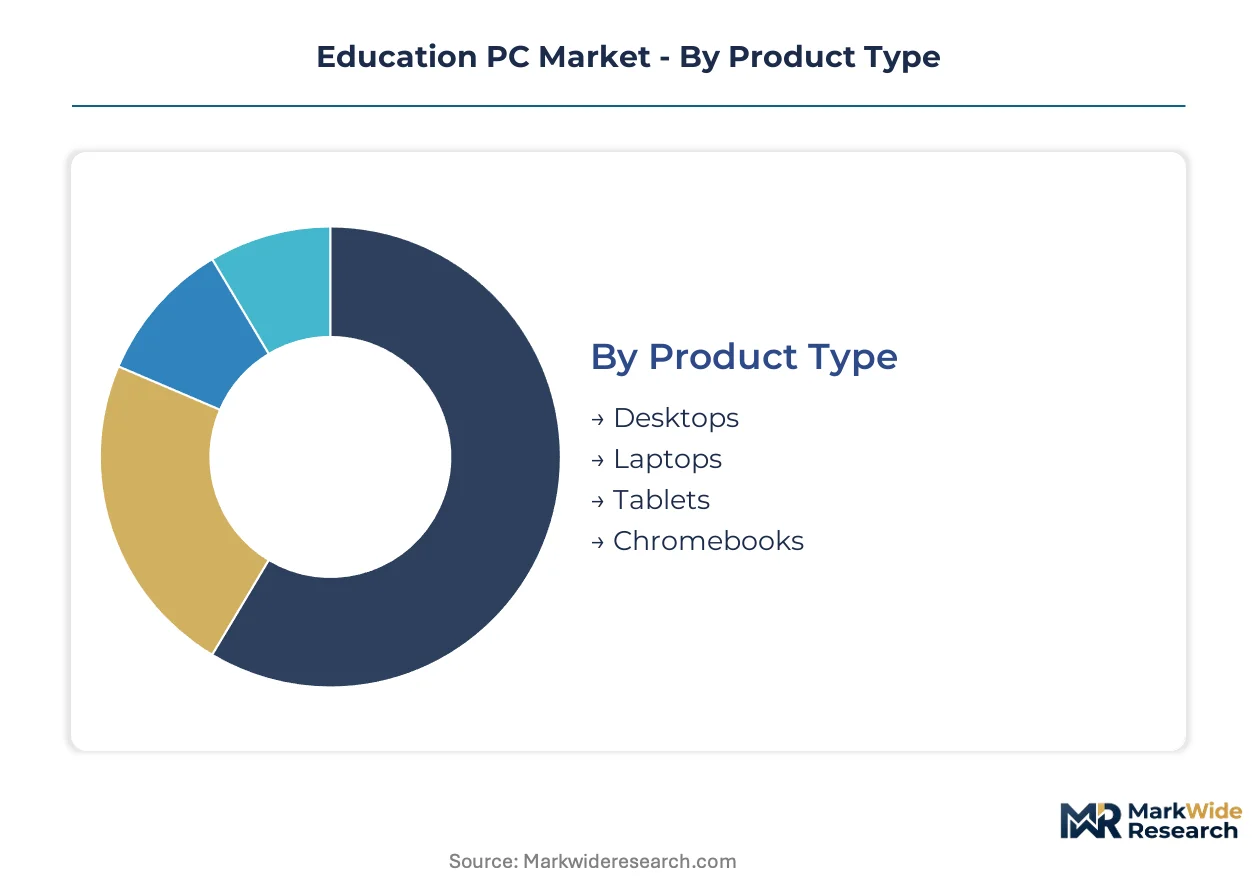
Education PC procurement patterns diverge sharply across institutional tiers, with K-12 districts prioritizing fleet manageability and total cost of ownership while higher education emphasizes computational performance and software ecosystem depth. Understanding these segment boundaries enables vendors to align hardware specifications with distinct funding mechanisms and refresh cycles.
Product Type:
Regulatory differentiation in energy efficiency and material composition standards reshapes competitive positioning across form factors, with EU Ecodesign repairability mandates and FCC E-Rate eligibility rules creating divergent compliance pathways.
- Chromebooks:Cloud-dependent architecture with minimal local storage and automatic OS updates reduces IT administration overhead. K-12 districts in Texas and California concentrate procurement through state master contracts, driven by Google Workspace integration and sub-$300 unit pricing that fits E-Rate subsidy structures.
- Laptops:Full-featured mobile computing with x86 processor architectures, expandable memory slots, and enterprise-grade security modules. Higher education institutions in Germany and France prioritize these for engineering and creative disciplines where local processing power remains essential, with procurement teams incorporating EU repairability indices into tender evaluations.
- Desktops:Stationary computing hardware deployed primarily in computer labs and administrative offices where portability is unnecessary.
- Tablets:Touchscreen-centric devices capturing budget-conscious segments in early primary grades where keyboard input is not yet required.
Chromebooks handle the majority of throughput; Laptops is the fastest mover on share.
End User:
Cost tier stratification separates capital-rich university systems from cash-constrained public school districts, with each tier demanding distinct service bundles and financing structures.
- K-12 Students:1:1 device programs requiring reinforced chassis, spill-resistant keyboards, and all-day battery endurance exceeding eight hours. India's state digital literacy programs in Uttar Pradesh and Maharashtra generate predictable demand pipelines through centralized government tenders, with BIS certification mandates filtering vendor participation.
- Higher Education Institutions:Research-intensive computing environments demanding discrete graphics, high-resolution displays, and virtualization support for specialized software licenses. U.S. R1 universities anchor this segment, with procurement offices negotiating enterprise agreements that bundle device management with multi-year refresh cycles.
- Educators:Instructor-facing hardware prioritizing presentation connectivity, stylus input for annotation, and seamless classroom display integration.
- Administrative Staff:Back-office computing needs centered on document processing, student information systems, and financial management platforms.
K-12 Students commands the largest unit volumes; Higher Education Institutions delivers the strongest per-unit margins.
Deployment:
Volume concentration in cloud-native architectures is displacing legacy on-premises infrastructure as districts prioritize scalability and reduced IT overhead.
- Cloud-Based:Fully managed endpoint provisioning with centralized application delivery, zero-touch enrollment, and automatic security patching. U.S. public school systems accelerating E-Rate-funded procurement favor this model for its operational budget alignment and minimal on-site technical staffing requirements.
- Hybrid:Mixed infrastructure preserving on-premises authentication systems while migrating productivity workloads to cloud platforms. European districts navigating GDPR data residency requirements concentrate here, with IT directors balancing accessibility against compliance constraints.
- On-Premises:Traditional local server dependency retaining sensitive student data within district-controlled facilities.
- Remote:Distributed learning configurations emphasizing home internet connectivity optimization and parental oversight features.
Cloud-Based dominates new procurement; Hybrid is expanding most quickly among districts with legacy infrastructure investments.
Technology:
Application-specific requirements in STEM disciplines and creative fields preserve platform diversity despite Chrome OS volume leadership in primary education.
- Windows:Dominant enterprise operating system supporting legacy educational software, Active Directory integration, and comprehensive endpoint management tools. Higher education engineering programs and U.S. district IT departments standardize here for compatibility with specialized simulation and design applications.
- Chrome OS:Lightweight browser-centric platform with seamless Google Workspace integration and automatic security updates. K-12 technology coordinators in California and Texas master contracts drive standardization, with fleet management simplicity outweighing offline functionality limitations.
- macOS:Unix-based platform concentrated in U.S. private schools and university creative arts departments where media production software ecosystems anchor purchasing decisions.
- Linux:Open-source alternative deployed in computer science curricula and research environments requiring custom kernel modifications.
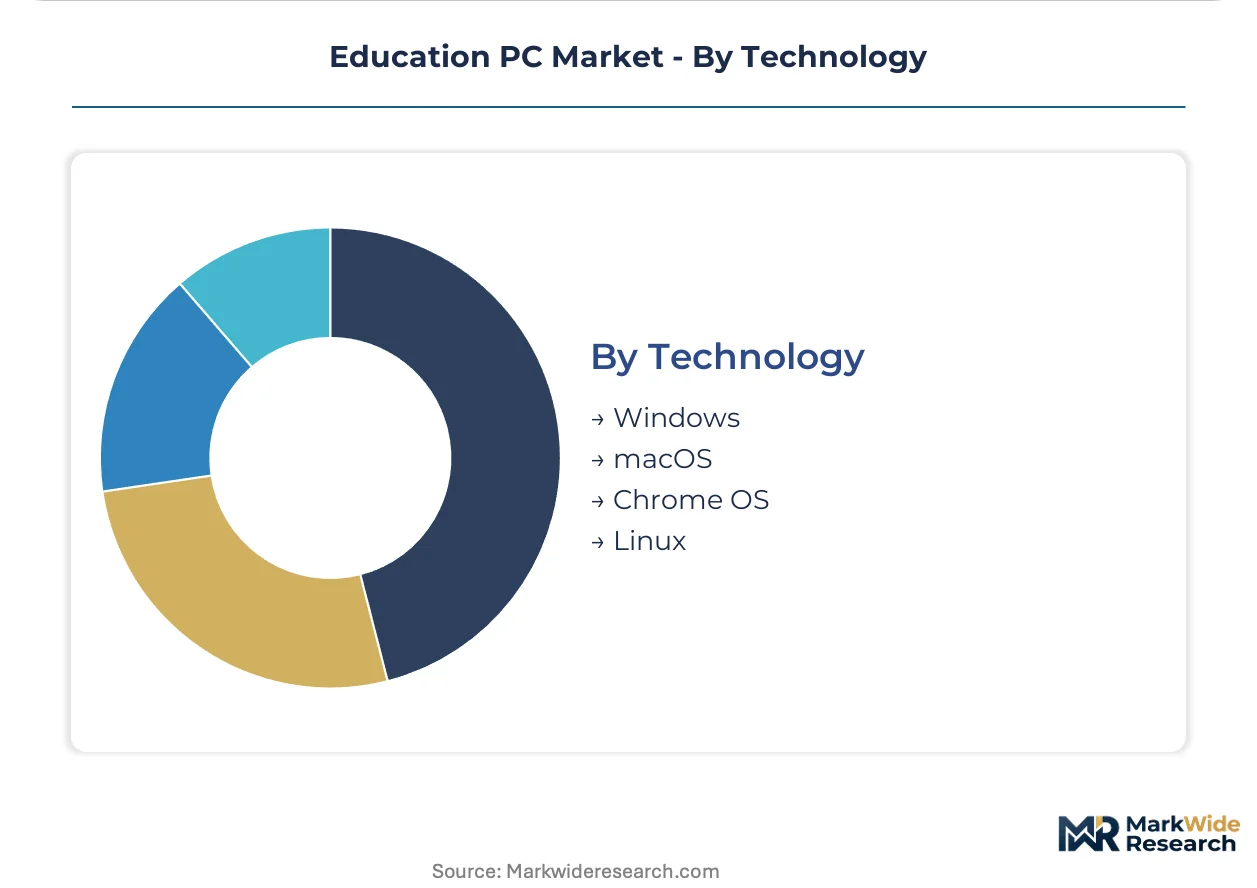
Windows maintains the broadest application compatibility; Chrome OS is climbing the fastest on shipment volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
District procurement offices and state technology agencies concentrate buying power, with FCC E-Rate funding in the United States, state digital literacy programs in India, and EU Ecodesign regulations in Germany and France reshaping vendor market entry pathways across distinct institutional contexts.
United States
K-12 districts in Texas and California now route procurement through centralized state master contracts, compressing vendor sales cycles. FCC E-Rate modernization expanded broadband infrastructure eligibility, accelerating device refresh timelines. Chicago Public Schools and Los Angeles Unified anchor volume concentration, with cooperative purchasing vehicles standardizing Chromebook specifications across constituent districts.
India
State governments in Uttar Pradesh and Maharashtra generate predictable demand pipelines through centralized digital literacy tenders. BIS certification mandates filter vendor participation, with electromagnetic compatibility testing requirements extending market entry timelines. Bangalore and Hyderabad host distribution clusters where vendors pre-configure fleet management software for government education contracts.
Germany
Higher education procurement teams incorporate EU Ecodesign repairability indices into tender evaluations ahead of full regulatory enforcement. Baden-Württemberg and Bavaria concentrate R1 university purchasing power, with engineering programs demanding discrete graphics and virtualization support. REACH compliance documentation adds fixed overhead for hardware distribution across federal states.
France
Île-de-France education agencies negotiate enterprise agreements bundling device management with multi-year refresh cycles. ANSM and CNIL oversight shapes data residency requirements for cloud-based deployments in hybrid infrastructure environments. Lyon and Toulouse clusters see concentrated procurement for creative arts departments where media production software ecosystems anchor purchasing decisions.
Japan
Tokyo and Osaka metropolitan school boards prioritize spill-resistant keyboards and all-day battery endurance exceeding eight hours for 1:1 student device programs. METI efficiency standards and JIS certification requirements constrain hardware specifications for institutional tenders. Kansai region districts concentrate demand for modular component designs that extend device lifecycles beyond traditional three-year norms.
Education PC Market Vendor Landscape
Player mix skews toward diversified electronics conglomerates with established education verticals, creating a tiered structure where direct institutional sales channels compete against distribution-heavy models. The vendor base separates into three strategic archetypes: direct-sales specialists leveraging large-volume contracts, ecosystem-integrated players bundling cloud productivity suites, and service-centric providers attaching repair coverage and fleet management. Dominant competitive moves include restructuring hardware margins around recurring service revenue and pursuing state-level master contract certifications.
Within the ecosystem-integrated tier, Google and Microsoft exemplify platform-centric positioning, while Dell and Lenovo anchor the direct-sales specialist archetype through sustained large-volume relationships with U.S. public school systems. HP occupies a service-centric position, with device management and repair coverage bundles differentiating its education portfolio against hardware-only competitors.
| Leading Market Players |
|---|
| Apple |
| Samsung |
| Dell |
| Microsoft |
| Acer |
| HP |
| ASUS |
| Elitegroup Computer Systems |
| Lenovo |
| Others |
Supply Flow & Price Mechanics
FCC E-Rate certification gates both vendor qualification and price tier eligibility for U.S. education contracts, compressing margins for non-certified suppliers while enabling premium positioning for E-Rate-compliant hardware bundles. State master contract centralization in Texas and California intensifies price competition at the volume tier, pushing vendors toward service-anchored pricing models that escape pure hardware commoditization.
Pricing Analysis
Cost-plus contracts with semiconductor indexation dominate large-volume district procurement, protecting vendors against memory and processor volatility while capping upside. Price differentiation hinges on E-Rate compliance tier and fleet management service bundling. Pricing pressure intensifies in the K-12 Chromebook segment where California and Texas master contracts drive sub-$300 unit targets. Higher education institutions show lowest price sensitivity, prioritizing repairability scores and virtualization support over acquisition cost.
Supply Chain Analysis
Taiwan and South Korea anchor processor and memory wafer fabrication for education PC components, while China concentrates motherboard assembly and battery cell production. Component sourcing draws from Malaysian printed circuit board facilities and Vietnamese chassis manufacturing. Single-source vulnerability in advanced node semiconductors creates procurement risk during contract bidding windows. Distribution runs through direct institutional sales channels for U.S. public school systems, bypassing traditional retail intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement centralization fragments vendor access, creating niche opportunities for specialized service providers and regional certification specialists. Cloud-native deployment preferences open white-space for subscription-native entrants outside established hardware incumbents.
For Market Incumbents: Consolidate position through backward integration into modular component supply, securing field-replaceable unit availability for extended lifecycle contracts. Lock in state master contract certifications ahead of E-Rate modernization implementation. Prioritize fleet management software R&D to defend against pure-hardware competitors.
For New Entrants and Emerging Players: Anchor in India's BIS pre-certification pathways, targeting Uttar Pradesh and Maharashtra state digital literacy tenders with localized configuration services. Exploit underpenetrated hybrid deployment demand in European districts navigating GDPR data residency requirements. Lead with Device-as-a-Service financing structures that convert capital expenditure barriers into recurring revenue relationships.
For Investors and Strategic Acquirers: EU Ecodesign repairability mandate enforcement reshapes the acquisition landscape toward modular design specialists and spare parts logistics platforms. Five-to-ten year viability favors vendors with service revenue exceeding fifty percent of total mix. Monitor BIS certification approval velocity as inflection indicator for India market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| State Master Contract Certification | Texas and California education agencies now control hardware selection for majority of constituent districts. |
| Device-as-a-Service Launch | Subscription provisioning shifts capital expenditure to operational budgets for cash-constrained districts. |
| Modular Component Platform Development | Field-replaceable designs extend replacement cycles from three years to five-to-six years in K-12 environments. |
| Fleet Management Software Integration | Zero-touch enrollment and automatic patching reduce IT administration overhead for district technology coordinators. |
| BIS Pre-Certification Investment | Electromagnetic compatibility testing completion accelerates market entry for India's state government education tenders. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FCC E-Rate program documentation, vendor SEC filings, and state procurement database records. Interviews with K-12 technology coordinators, higher education procurement officers, and education hardware sales directors informed demand-side dynamics. Secondary sources include Google Workspace deployment statistics, BIS certification registries, and EU Ecodesign regulatory filings. Bottom-up shipment modeling triangulates against top-down education IT budget allocations.
Segmentation dimensions modeled span product type, end user tier, deployment architecture, and operating system platform across the projection horizon. Chromebook versus laptop mix, cloud-native adoption velocity, and state-level procurement centralization patterns inform volume and value trajectories. CAGRs derive from enrollment-adjusted device penetration rates and refresh cycle compression analysis. India BIS approval timelines and EU repairability index implementation schedules serve as geography-specific forecast inputs.
Material uncertainties — semiconductor input volatility, E-Rate funding appropriation shifts, and EU regulatory enforcement timing — sit outside the modeled envelope. Forecasts reflect assumptions regarding district budget continuity and cloud platform vendor pricing stability. Recalibration cycles align with material shifts in procurement centralization policy and certification regime enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Middle East Radio Headset Market
Consumer Electronics
United States Smart TV Market
Consumer Electronics
Global Automated Laundromat Services Market
Consumer Electronics
Zipline Kits Market
Consumer Electronics
Consumer Electronics Electric Motor Market
Consumer Electronics
Smart Connected Speaker Market
Consumer Electronics
Chromebook Market
Consumer Electronics
Screen Privacy Protectors Market
Consumer Electronics
Asia-Pacific Refurbished and Used Mobile Phones Market
Consumer Electronics
Armenia Consumer Goods Market
Consumer Electronics
Gaming Computer Market
Consumer Electronics
Mechanical Keyboard Market
Consumer Electronics
Gaming PC Market
Consumer Electronics
Tablet Market
Consumer Electronics
United States Stylus Pen Market
Consumer Electronics
Europe Refurbished and Used Mobile Phones Market