
 Global Earphones and Headphones Market | 2026-2036
Global Earphones and Headphones Market Size, Share, and Industry Trends Forecast 2026-2036
Global Earphones and Headphones Market Analysis
Silicone ear tips and bio-based plastics are pivoting away from petroleum-derived housings as brands chase lighter, more sustainable product economics. Apple Inc. leverages its custom silicon ecosystem to lock in hardware-software integration across AirPods and Beats portfolios. Sony Group Corporation anchors its premium positioning through proprietary active noise cancellation algorithms and high-resolution audio codec support. Samsung Electronics competes by bundling Galaxy Buds with smartphone purchases, tightening ecosystem switching costs.
Earphones and headphones are electroacoustic transducers converting electrical audio signals into sound waves, typically employing dynamic drivers with neodymium magnets, voice coils, and polymer or metalized diaphragms ranging from 6mm to 50mm in diameter, designed for personal listening across music, communication, gaming, and professional monitoring applications. Wireless Bluetooth models lead volume shipments as smartphone manufacturers eliminate 3.5mm jacks, while bone conduction variants capture fastest growth among fitness enthusiasts seeking situational awareness during outdoor training. Active noise control technology concentrates margin pools in the professional and premium consumer tiers where engineering complexity justifies price premiums over passive isolation alternatives.
The Federal Communications Commission governs radio frequency emissions from Bluetooth and NFC-enabled devices in the United States, while the EU Radio Equipment Directive mandates interoperability and electromagnetic compatibility across European Economic Area markets, and China's Ministry of Industry and Information Technology certifies wireless transmission protocols through SRRC approval processes. These frameworks shape demand by dictating which codec implementations and power thresholds manufacturers may deploy in each jurisdiction. Stakeholders must monitor evolving codec licensing terms and right-to-repair mandates that could force design standardization and compress proprietary differentiation windows.
Market Dynamics
Bluetooth Low Energy Audio codec standardization by the Bluetooth SIG is compressing power budgets and enabling broadcast audio sharing, forcing incumbent manufacturers to redesign RF architectures and opening entry paths for semiconductor specialists without legacy analog audio expertise.
Growth Catalysts
- Fitness-optimized wearables:Workout-integrated biometric monitoring drives replacement cycles among gym members and outdoor athletes seeking heart-rate-synced audio coaching.
- EU Radio Equipment Directive harmonization:Streamlined electromagnetic compatibility certification across the European Economic Area reduces time-to-market for multi-country product launches.
- Neodymium magnet supply concentration:China's dominance in rare-earth processing enables domestic brands to source dynamic driver components at scale-advantaged cost structures.
Market Restraints
- Polymer diaphragm input volatility:Petrochemical-derived housing materials face price pressure from crude oil fluctuations and bio-based plastic substitution R&D costs.
- 3.5mm jack elimination:Smartphone OEMs' removal of analog ports forces consumers into wireless upgrade cycles they may delay during economic uncertainty.
- Codec licensing fragmentation:Proprietary high-resolution audio formats from Dolby, Sony, and Qualcomm create royalty stacking that inflates bill-of-materials for mid-tier products.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Production-linked incentives attract contract manufacturers seeking alternatives to sole-source China dependency for export markets.
- Bone conduction for situational awareness:Open-ear transducer designs capture cyclists and runners in Germany and Japan where traffic safety regulations discourage isolation.
- Right-to-repair mandates:EU and US state-level legislation forcing modular battery and driver replacement creates aftermarket service revenue streams and brand loyalty mechanisms.
Industry Challenges
- ANC algorithm talent scarcity:Proprietary active noise cancellation firmware development requires rare combinations of acoustic physics and DSP engineering expertise concentrated in Tokyo, Seoul, and Silicon Valley.
- SRRC certification timelines:China's Ministry of Industry and Information Technology radio transmission approval processes extend product launch windows by 8-14 weeks for foreign entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Earphones and Headphones Market |
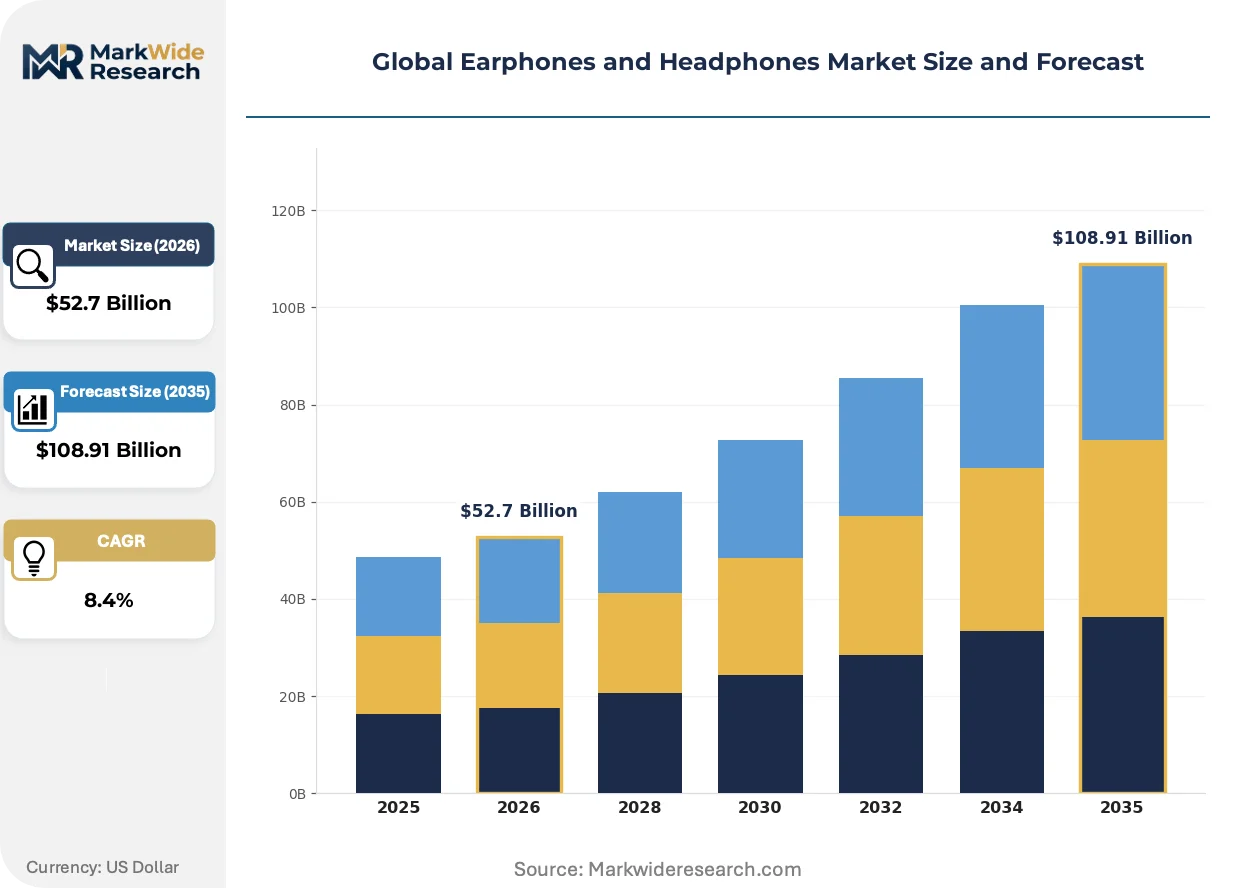
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $108.91 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired, Wireless, Noise Cancelling, Bone Conduction End User: Consumers, Professionals, Gamers, Fitness Enthusiasts Technology: Bluetooth, NFC, Active Noise Control, Codec Support Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Electronics Retailers |
| Companies Covered | Apple Inc., Sony Group Corporation, Samsung Electronics, Bose Corporation, Sennheiser Electronic GmbH & Co. KG, Skullcandy Inc., Harman International Industries, Xiaomi Corporation, JVC Kenwood Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Earphones and Headphones Market Emerging Trajectories
Codec efficiency wars and transducer material science are redrawing competitive boundaries between audio specialists and consumer electronics conglomerates. Sustainability mandates and broadcast audio architectures are forcing simultaneous hardware and software reinvention.
Silicone ear tips and bio-based plastic housings are expanding into premium product tiers as brands chase ESG-compliant supply chains and weight reduction targets. Outdoor athletes and corporate procurement departments are adopting these materials fastest, valuing sweat resistance and carbon footprint disclosures over petroleum-derived alternatives. The shift is expanding into manufacturing location decisions as brands relocate molding operations to regions with renewable energy grids.
EU RoHS substance restrictions and REACH chemical registration requirements are tightening permissible materials in driver voice coils and PCB solder joints. Manufacturers must reformulate neodymium magnet coatings and diaphragm adhesives to maintain European Economic Area market access. High-end professional monitoring equipment faces the steepest compliance costs due to legacy material dependencies in transducer assemblies.
Direct-to-consumer channel migration is compressing retail margin extraction as brands bypass electronics superstores and carrier shops. Urban millennials in South Korea and coastal China cities are purchasing flagship earbuds through live-stream commerce and brand-owned apps, disintermediating traditional distributors. After-sales support unbundling follows, with warranty claims handled through chatbot triage rather than physical service centers.
Global Earphones and Headphones Market Segmentation
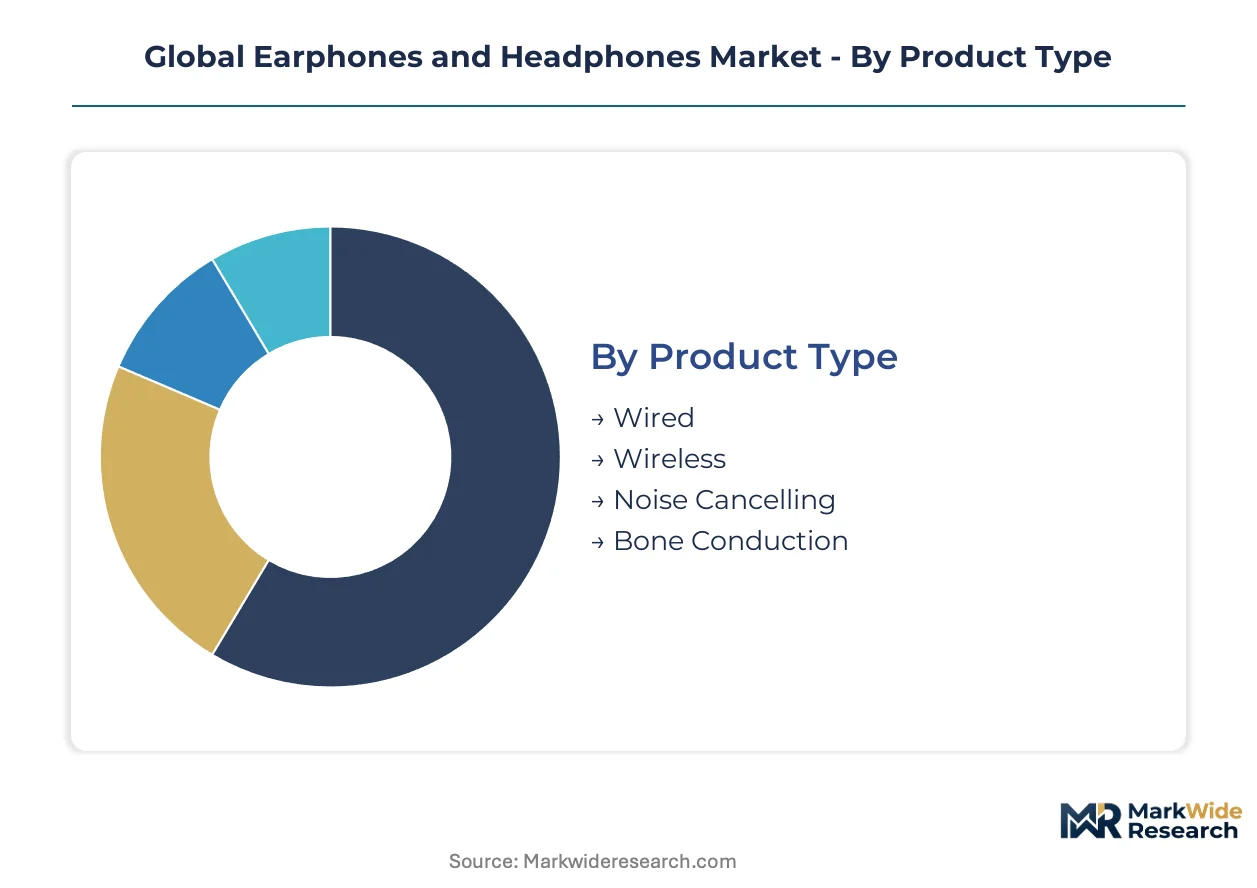
Transducer architecture and connectivity protocols create distinct margin pools across the earphones and headphones market. Each segmentation axis reveals divergent R&D intensities, certification burdens, and channel economics that shape manufacturer positioning.
Product Type:
Driver configuration and signal transmission method determine acoustic performance ceilings and battery dependency profiles.
- Wireless:Bluetooth RF architectures with integrated power management dominate volume shipments as smartphone OEMs eliminate analog ports. Demand concentrates in China where domestic brands leverage MIIT certification scale and e-commerce distribution dominance to compress price points.
- Noise Cancelling:Hybrid feedforward-feedback microphone arrays with DSP firmware command premium positioning. Professional monitoring studios in Germany and Japan absorb the steepest price tiers where ANC algorithm precision justifies hardware costs over passive isolation alternatives.
- Wired:Analog 3.5mm and USB-C connections persist in latency-sensitive gaming and audiophile applications. Musicians and audio engineers in Nashville and London sustain residual demand despite connector elimination trends.
- Bone Conduction:Transducers bypass the eardrum through temporal bone vibration, enabling situational awareness. Cyclists and runners in German and Japanese urban centers adopt these designs where traffic safety regulations discourage acoustic isolation.
Wireless leads on scale; bone conduction leads on momentum.
End User:
Usage intensity and performance requirements segment procurement behavior across replacement cycles and price elasticity.
- Consumers:General music and communication applications drive baseline volume with compressed replacement intervals. Urban millennials in Seoul and Shenzhen purchase through live-stream commerce, disintermediating traditional electronics retailers.
- Fitness Enthusiasts:Sweat-resistant IP ratings and biometric integration command specialized industrial design. Gym chains and marathon training programs in California and Tokyo drive heart-rate-synced audio coaching adoption.
- Professionals:Broadcast monitoring, studio engineering, and remote work applications demand flat frequency response and comfort over extended sessions. Post-production facilities in Burbank and Mumbai specify driver matching tolerances within 1dB.
- Gamers:Spatial audio positioning and low-latency wireless protocols prioritize competitive performance. Esports tournament organizers in Seoul and Los Angeles mandate sub-20ms transmission delay for official peripherals.
Consumers anchor volume throughput; fitness enthusiasts are expanding most quickly.
Technology:
Protocol standardization and codec licensing shape interoperability margins and royalty stacking burdens.
- Bluetooth:LE Audio codec standardization by the Bluetooth SIG reduces power consumption and enables broadcast audio sharing. Smartphone ecosystem vendors in Cupertino and Seoul leverage proprietary silicon to lock in hardware-software integration advantages.
- Active Noise Control:Proprietary DSP firmware requires rare combinations of acoustic physics and signal processing expertise concentrated in Tokyo, Seoul, and Silicon Valley. ANC algorithm talent scarcity limits vendor proliferation in premium tiers.
- Codec Support:High-resolution audio format licensing from Dolby, Sony, and Qualcomm creates royalty stacking that inflates bill-of-materials for mid-tier products. Streaming service partnerships in Stockholm and Los Angeles drive codec inclusion decisions.
- NFC:Near-field pairing simplifies device association for non-technical users. Corporate procurement departments in London and Singapore value touch-to-connect workflows for fleet deployment standardization.
Bluetooth commands installed base; active noise control captures margin concentration.
Distribution Channel:
Channel selection determines working capital requirements and after-sales support bundling economics.
- Online Retail:Direct-to-consumer migration compresses retail margin extraction as brands bypass electronics superstores. Flagship earbuds move fastest through brand-owned apps and live-stream commerce in coastal Chinese cities.
- Electronics Retailers:Carrier shops and big-box chains sustain tactile evaluation for first-time wireless adopters. Suburban demographics in Texas and Florida rely on in-store demonstration for fit verification.
- Specialty Stores:Audiophile boutiques and pro-audio dealers serve enthusiast segments with personalized fitting services. High-end dynamic driver configurations in Munich and New York sell through trained staff consultation.
- Supermarkets:Impulse purchase placement and promotional bundling reach price-sensitive replacement cycles. Value-tier wireless models in São Paulo and Jakarta leverage checkout aisle visibility.
Online retail leads on volume velocity; specialty stores lead on average transaction value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors transducer manufacturing clusters where contract assemblers serve both domestic brands and international OEMs. The report identifies distinct regulatory and demand patterns across five countries where earphone and headphone procurement concentrates.
United States
Fitness-integrated audio coaching drives replacement cycles among gym chains and marathon training programs. The FCC governs Bluetooth RF emissions and power thresholds for wireless devices. Austin and Los Angeles host audio engineering talent pools where ANC algorithm development concentrates.
Germany
Professional monitoring studios absorb premium tiers where flat frequency response specifications command hardware investments. The EU Radio Equipment Directive mandates electromagnetic compatibility certification across the European Economic Area. Munich audiophile boutiques sustain tactile evaluation channels for high-end dynamic driver configurations.
China
Domestic brands leverage manufacturing scale and e-commerce distribution dominance to compress price points. The MIIT certifies wireless transmission protocols through SRRC approval processes extending launch windows for foreign entrants. Shenzhen and Dongguan clusters integrate neodymium magnet sourcing with polymer diaphragm molding operations.
Japan
Traffic safety regulations in urban centers encourage bone conduction adoption among cyclists and runners seeking situational awareness. METI oversees industrial standards for wireless audio equipment interoperability. Tokyo hosts rare combinations of acoustic physics and DSP engineering expertise for proprietary ANC firmware development.
South Korea
Esports tournament organizers mandate sub-20ms wireless transmission delay for official peripherals. The MFDS regulates biometric sensor integration in fitness-optimized wearables. Seoul's live-stream commerce channels disintermediate traditional electronics retailers for flagship earbud purchases.
Global Earphones and Headphones Market Vendor Landscape
Global majors compete with regional champions across silicon integration and transducer manufacturing dimensions. The vendor base stratifies between ecosystem-locked smartphone OEMs, acoustic heritage specialists, and contract manufacturing scale players. Three archetypes dominate: custom silicon integrators, ANC algorithm licensors, and component-scale fabricators. M&A activity targets DSP firmware capabilities while capacity expansion concentrates in India and Vietnam.
Within the ecosystem-locked tier, Apple Inc. and Samsung Electronics exemplify hardware-software integration strategies. Sony Group Corporation occupies a position among acoustic heritage specialists with proprietary codec and noise cancellation intellectual property. Xiaomi Corporation represents the scale-driven contract manufacturing archetype leveraging domestic supply chain proximity.
| Leading Market Players |
|---|
| Apple Inc. |
| Sony Group Corporation |
| Samsung Electronics |
| Bose Corporation |
| Sennheiser Electronic GmbH & Co. KG |
| Skullcandy Inc. |
| Harman International Industries |
| Xiaomi Corporation |
| JVC Kenwood Corporation |
| Others |
Supply Flow & Price Mechanics
Acoustic engineering talent concentration in Shenzhen and Dongguan compresses labor-cost differentials between premium and economy tiers, widening price spreads as brands arbitrage firmware development costs against transducer material grades.
Pricing Analysis
Input-cost pass-through from neodymium magnet and polymer diaphragm volatility drives three-tier pricing structure across premium, standard, and economy levels. Certification grade under MIIT SRRC and ANC algorithm precision separate premium positioning from mid-tier alternatives, while brand premium and volume scale differentiate standard from economy offerings. Pricing pressure stems from codec licensing royalty stacking that inflates bill-of-materials for mid-tier products. Fitness enthusiasts and esports gamers show least price sensitivity; supermarket impulse buyers in emerging markets show most.
Supply Chain Analysis
Freight cost escalation from Asia-Pacific manufacturing hubs to European and North American distribution centers compresses margin buffers on low-ASP products. Supply concentrates in China, Vietnam, and India where contract assemblers cluster around neodymium magnet processors and bio-based plastic molders. Raw material dependencies span rare-earth magnet alloys, lithium-polymer cells, and silicone ear tip compounds. Single-source vulnerability in Bluetooth silicon from Qualcomm and MediaTek creates procurement risk. Distribution runs through direct-to-consumer brand apps and live-stream commerce channels fastest, though carrier shops sustain tactile evaluation for first-time wireless adopters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Earphones and Headphones Market functions as a stable compounder where replacement cycle compression from smartphone ecosystem lock-in generates predictable revenue streams regardless of macro volatility.
For Market Incumbents: Deploy proprietary silicon integration as the primary defensive lever. Deepen hardware-software integration through custom Bluetooth codecs that increase ecosystem switching costs against emerging entrants with off-the-shelf Qualcomm or MediaTek reference designs. Add ANC algorithm development capacity in Tokyo and Seoul where acoustic physics and DSP engineering expertise concentrates, insulating premium tier positioning from algorithm commoditization.
For New Entrants and Emerging Players: Specialty audiophile boutiques offer the most penetrable channel wedge for unproven brands seeking tactile evaluation access without carrier shop slotting fees. Target bone conduction designs for German and Japanese cyclists where traffic safety regulations discourage acoustic isolation and incumbent coverage remains thin. Pursue white-label manufacturing partnerships with Dongguan contract assemblers to compress time-to-market before establishing owned-brand recognition.
For Investors and Strategic Acquirers: Smartphone ecosystem vendors are the most active acquirer in this space, seeking DSP firmware capabilities to complete hardware-software integration stacks. The market supports long-term viability through decade-long replacement cycle visibility tied to smartphone upgrade cadences. Acquisition target archetype: ANC algorithm specialists with proprietary feedforward-feedback microphone array IP. Watch for Bluetooth SIG codec standardization announcements as inflection indicators that could compress proprietary differentiation windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Silicon Development | Apple and Samsung lock in hardware-software integration advantages through custom Bluetooth codecs. |
| ANC Algorithm Acquisition | Sony and Bose defend premium positioning through feedforward-feedback microphone array IP concentration. |
| India PLI Manufacturing Expansion | Contract manufacturers diversify beyond China dependency to capture export market share. |
| Direct-to-Consumer Channel Migration | Urban millennials in Seoul and Shenzhen purchase flagship earbuds through brand-owned apps. |
| Bio-Based Plastic Transition | EU RoHS and REACH compliance drives neodymium magnet coating and diaphragm adhesive reformulation. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged product managers at audio OEMs, procurement leads at smartphone ecosystem vendors, acoustic engineering directors, live-stream commerce platform operators, and regulatory affairs specialists at MIIT and FCC. Secondary validation drew from Bluetooth SIG technical specifications, MIIT SRRC certification databases, EU Radio Equipment Directive implementation guidance, customs trade records for neodymium magnet alloys, and SEC filings from consumer electronics conglomerates. Bottom-up transducer shipment modeling and top-down consumer electronics spending allocation triangulated market sizing.
Segment-weighting approaches distributed volume and value across product type, end user, technology protocol, and distribution channel dimensions throughout the forecast period. CAGRs derived from replacement cycle analysis, smartphone jack elimination penetration curves, and fitness wearable attachment rate projections. Industry-specific inputs included Bluetooth LE Audio codec adoption timelines, ANC algorithm talent pool growth rates, and right-to-repair mandate implementation schedules across EU member states.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to smartphone ecosystem vendor platform decisions and rare-earth magnet supply policy shifts in China. Forecasts reflect documented assumptions on codec licensing cost trajectories and e-commerce channel share evolution. A model refresh is warranted upon material change in Bluetooth SIG standardization timelines or MIIT certification procedure revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Professional Headset Market
Consumer Electronics
Kindle E-Reader Accessories Market
Consumer Electronics
Stress Ball Market
Consumer Electronics
Ultra HD Action Camera Market
Consumer Electronics
Wrist Dive Computer Market
Consumer Electronics
Global Tablet Keyboards Market
Consumer Electronics
Smart Mirror TV Market
Consumer Electronics
Mobile Cases and Covers Market
Consumer Electronics
Global Office and Contact Center Headset Market
Consumer Electronics
Smart Audio Devices Market
Consumer Electronics
Sports Electronics Market
Consumer Electronics
Laptop Accessories Market
Consumer Electronics
Mobile Phone Accessories Market
Consumer Electronics
Middle East and Africa Refurbished and Used Mobile Phones Market
Consumer Electronics
Nanopresso Market
Consumer Electronics
Portable Media Player Market