
 North America Mobile Phone Accessories Market | 2026-2036
North America Mobile Phone Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
North America Mobile Phone Accessories Market Analytics
Specialty store distribution is narrowing as direct-to-consumer platforms capture premium accessory transactions. Apple Inc. leverages its proprietary connector ecosystem to sustain captive demand for first-party cables and adapters. Anker Technology competes through aggressive R&D intensity in gallium nitride charging architectures. Belkin International anchors shelf presence across Best Buy and Target electronics aisles with licensed MagSafe-compatible portfolios.
Mobile phone accessories encompass protective enclosures, power delivery devices, audio peripherals, and display safeguarding films engineered from polycarbonate, thermoplastic polyurethane, lithium-ion cells, and tempered alkali-aluminosilicate glass. These products extend device operational lifespan, enable wireless communication enhancement, and support continuous power autonomy for smartphones in consumer and enterprise settings. Chargers and earphones represent the fastest-expanding product type segment as USB-C standardization and true wireless stereo adoption accelerate replacement cycles. The distribution channel dimension shows online platforms capturing margin pools previously held by retail stores, while specialty stores retain high-touch premium transactions. Price tier stratification concentrates volume in mid-range SKUs and value in premium certified accessories.
The FCC governs radio frequency emissions and electromagnetic interference standards for wireless charging accessories sold across the United States. Health Canada and the PMRA coordinate cross-border product safety notifications for polymer-based cases and lithium-containing power banks entering Canadian retail channels. California's Proposition 65 labeling requirements and the EU-aligned RoHS substance restrictions on heavy metals in electronics accessories shape material selection and compliance costs for manufacturers serving North American buyers. Stakeholders must monitor pending harmonization between FCC Part 15 rules and emerging Energy Star efficiency criteria for wireless power systems.
Market Dynamics
USB-C standardization across the United States and Canada is compressing proprietary connector margins while elevating third-party certification requirements for power delivery accessories.
Growth Catalysts
- Enterprise hybrid work stabilization:Corporate procurement of wireless charging infrastructure for distributed offices is expanding device-per-employee ratios across California and Texas tech corridors.
- FCC Part 15 electromagnetic compatibility updates:Revised wireless power transfer certification standards are filtering uncertified competitors from retail channels, benefiting compliant manufacturers.
- Gallium nitride semiconductor maturation:Higher switching frequencies in charger architectures are reducing thermal mass and enabling compact form factors for travel-oriented accessories.
Market Restraints
- Lithium-ion cell supply concentration:Battery pack production for power banks depends heavily on Asian cell suppliers, exposing North American assemblers to input cost volatility and logistics bottlenecks.
- California Proposition 65 compliance burden:Warning label requirements for polymer-based cases containing trace phthalates add per-unit regulatory overhead without differentiation value.
- True wireless stereo replacement saturation:Extended replacement cycles for Bluetooth earphones in mature urban markets are constraining volume growth in the audio peripheral segment.
Strategic Opportunities
- Canadian retail channel underpenetration:Specialty electronics distribution in Toronto and Vancouver remains fragmented relative to US coastal density, creating shelf expansion potential for certified accessory portfolios.
- MagSafe ecosystem licensing:Apple's proprietary magnetic alignment standard creates captive aftermarket demand for certified wireless charging mounts and automotive holders.
- Energy Star wireless power efficiency criteria:Pending federal efficiency designations for charging pads will advantage early-certified products in enterprise and government procurement channels.
Industry Challenges
- FCC certification timeline compression:Radio frequency testing backlogs for new wireless charging SKUs delay product launches by 8-14 weeks, compressing seasonal revenue windows.
- RoHS substance restriction complexity:Heavy metal compliance documentation for cross-border US-Canada shipments requires dedicated regulatory staff, raising fixed costs for mid-tier manufacturers.
- USB-IF certification queue congestion:Power delivery specification testing bottlenecks are forcing accessory makers to sequence product launches around available lab capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Mobile Phone Accessories Market |
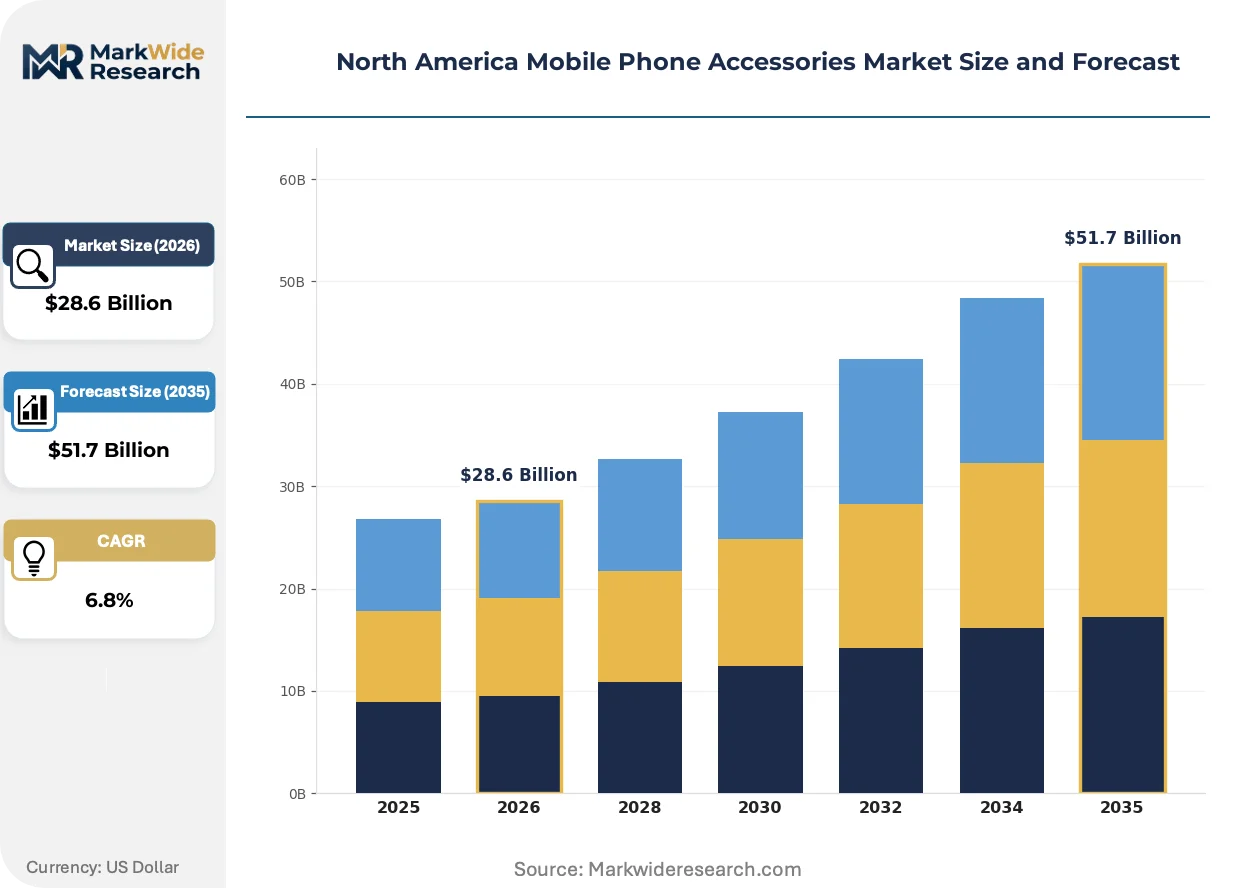
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cases, Screen Protectors, Chargers, Earphones End User: Consumers, Retailers, Enterprises, Wholesalers Distribution Channel: Online, Retail Stores, Supermarkets, Specialty Stores Price Tier: Premium, Mid-Range, Economical, Discounted |
| Companies Covered | Apple Inc., Samsung Electronics Co., Ltd., Belkin International, Anker Technology, OtterBox (Otter Products LLC), Sony Corporation, Bose Corporation, JBL, Logitech, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Mobile Phone Accessories Market Evolving Landscape
Wireless power architectures and magnetic alignment systems are redefining physical interface standards across the accessory stack, while regulatory efficiency mandates reshape certification priorities.
Gallium nitride power semiconductors are virtualizing traditional silicon-based charger designs by enabling higher frequency switching at reduced thermal loads. Enterprise buyers in Texas distribution hubs are specifying GaN-based adapters for employee device fleets. The technology is virtualizing brick-style charger form factors into compact cubes that displace legacy laptop power supplies.
The FCC's updated Part 15 rules for radio frequency devices are tightening electromagnetic interference thresholds for wireless charging pads sold in US retail channels. Manufacturers must now submit expanded test data for harmonic emissions and spurious radiation. California-based design houses are absorbing additional 6-10 week certification cycles into product roadmaps.
Direct-to-consumer platform migration is consolidating premium accessory transactions away from Best Buy and Target electronics aisles. Specialty stores retain high-touch sales for MagSafe-certified portfolios and enterprise bulk orders. The shift concentrates most visible in San Francisco and Austin metropolitan corridors where same-day delivery infrastructure supports impulse replacement purchases.
North America Mobile Phone Accessories Market Segmentation
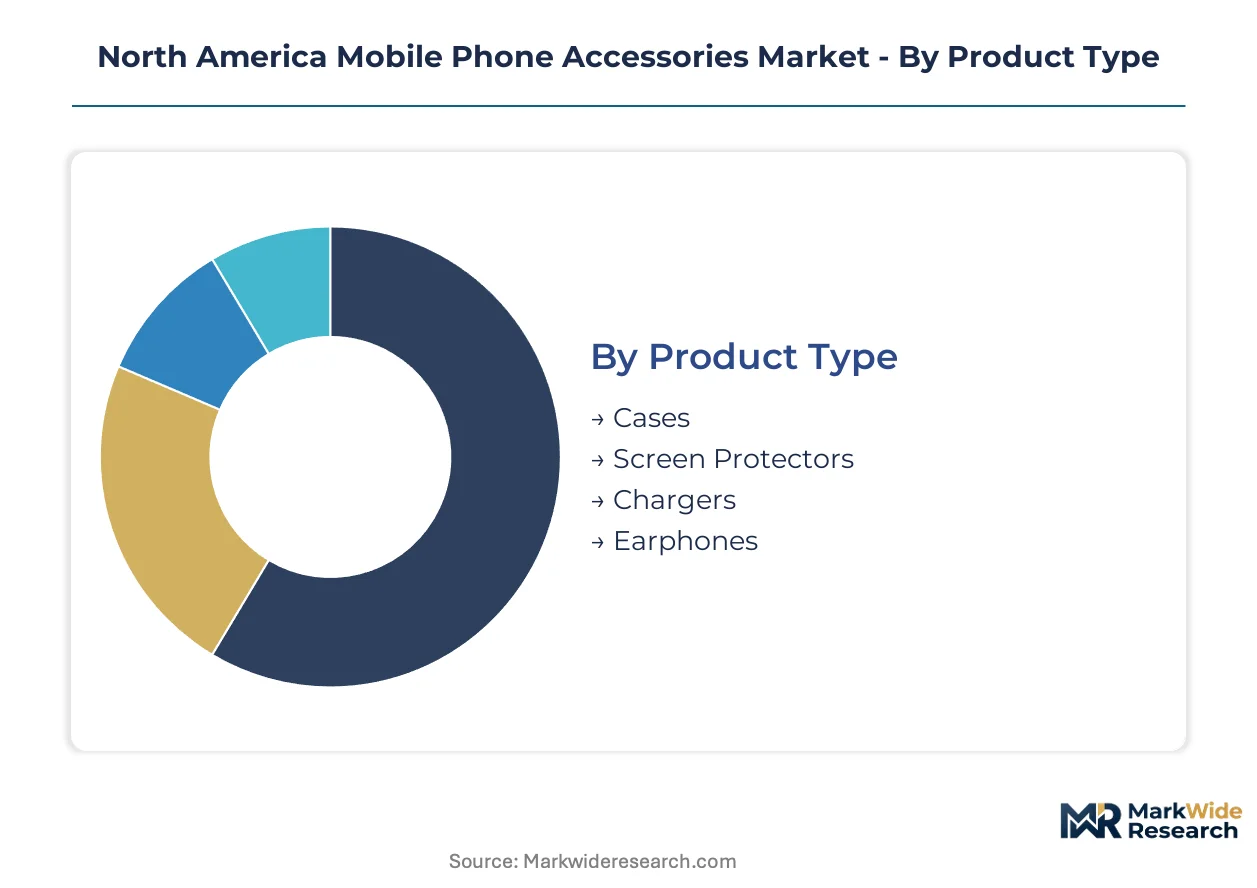
Accessory manufacturers must align production configurations with distinct service intensity requirements across product categories. Warranty claim rates and replacement frequency vary sharply between protective enclosures and power delivery devices, dictating inventory positioning and channel partnerships throughout California and Texas logistics corridors.
Product Type:
After-sales-service intensity diverges substantially across physical protection versus power management accessories, with warranty event rates and technical support demands shaping margin structures.
- Cases:Polycarbonate and thermoplastic polyurethane enclosures absorb impact energy and resist abrasion across consumer handling patterns. Demand clusters in California's urban corridors where device replacement costs drive premium protective investments, constrained by Proposition 65 compliance overhead for polymer formulations containing trace phthalates.
- Chargers:Gallium nitride semiconductor architectures enable higher switching frequencies with reduced thermal mass in USB-C and wireless power delivery devices. Texas distribution hubs specify these adapters for enterprise device fleets, accelerated by FCC Part 15 electromagnetic compatibility certification requirements filtering uncertified competitors.
- Screen Protectors:Tempered alkali-aluminosilicate glass films and polyethylene terephthalate laminates prevent display fracture propagation.
- Earphones:True wireless stereo Bluetooth peripherals with lithium-ion cell integration face extended replacement cycles in mature metropolitan markets.
Cases hold the largest share; momentum sits with chargers as USB-C standardization and GaN maturation compress replacement cycles.
End User:
Procurement scale and specification authority separate fragmented individual purchasers from consolidated institutional buyers with formal vendor qualification processes.
- Enterprises:Corporate IT departments specify certified wireless charging infrastructure and protective accessories for distributed workforces under hybrid policies. Bulk purchasing agreements with direct-to-consumer platforms and specialty distributors concentrate in Austin and San Francisco metropolitan corridors where same-day delivery infrastructure supports fleet refresh programs.
- Consumers:Individual purchasers drive impulse replacement transactions through online platforms and retail electronics aisles, with price sensitivity elevated in post-pandemic discretionary environments.
- Retailers:Best Buy and Target electronics merchandisers curate licensed MagSafe-compatible portfolios and certified third-party alternatives.
- Wholesalers:Volume distributors supply independent mobile repair shops and regional electronics chains across fragmented Canadian markets.
Consumers dominate transaction volume; enterprises are expanding most quickly as device-per-employee ratios stabilize under permanent hybrid work configurations.
Distribution Channel:
Margin capture and customer acquisition economics shift dramatically between high-touch physical environments and algorithmically optimized digital storefronts.
- Online:Direct-to-consumer platforms consolidate premium accessory transactions with same-day delivery infrastructure in dense metropolitan markets. Amazon and manufacturer-direct storefronts displace retail margin pools through dynamic pricing and subscription replenishment models for consumable accessories like charging cables.
- Specialty Stores:High-touch electronics retailers retain complex sales requiring physical inspection and technical consultation for MagSafe-certified wireless charging mounts.
- Retail Stores:Mass merchandisers anchor shelf presence for mid-range SKUs with impulse purchase visibility.
- Supermarkets:Convenience-oriented distribution captures emergency replacement demand for basic protective accessories and charging cables.
Online channels command the steepest expansion trajectory; specialty stores retain defensive positioning in premium certified transactions.
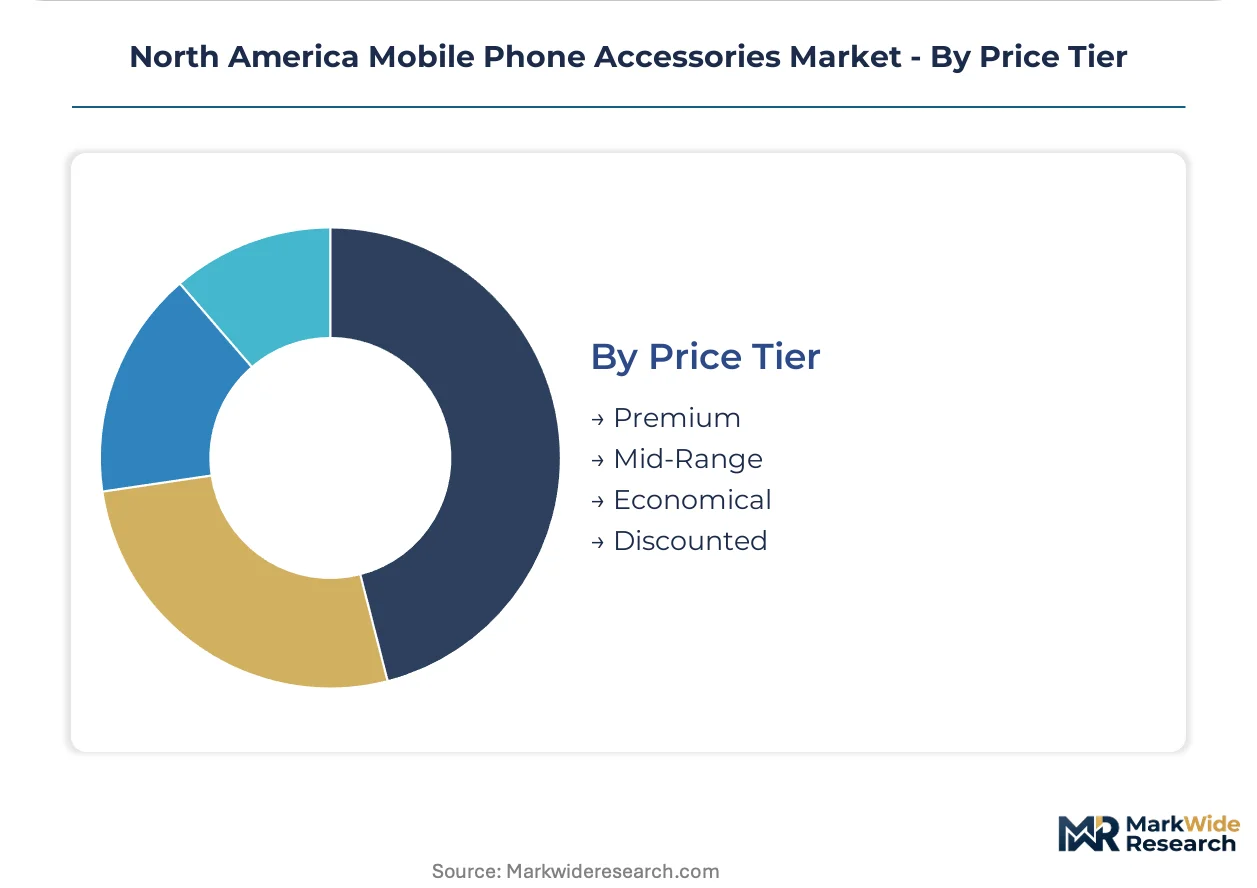
Price Tier:
Certification grade and material specification separate accessible entry points from performance-optimized premium positioning.
- Premium:Apple-certified MagSafe-compatible accessories and GaN-based chargers with USB-IF Power Delivery certification command price multiples through guaranteed compatibility and extended warranty terms. FCC and Energy Star efficiency designations further segment this tier in enterprise procurement channels.
- Mid-Range:Third-party certified alternatives with comparable technical specifications and shorter warranty periods capture volume concentration.
- Economical:Non-certified basic protective cases and legacy silicon chargers serve price-sensitive replacement demand.
- Discounted:Closeout inventory and grey-market imports without warranty support occupy peripheral retail placement.
Mid-Range captures the greatest unit volume; Premium is climbing the fastest as certification requirements and enterprise procurement standards elevate baseline specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in California's tech corridors where enterprise procurement premiums exceed Midwest retail benchmarks by substantial margins. Canadian distribution networks absorb cross-border compliance costs that compress margin structures relative to US counterparts.
United States
Enterprise hybrid work policies drive wireless charging infrastructure deployment across Austin and San Francisco metropolitan corridors. FCC Part 15 electromagnetic compatibility standards filter uncertified competitors from retail channels, benefiting compliant manufacturers. Texas distribution hubs specify gallium nitride adapters for device fleets at scale.
Canada
Toronto and Vancouver specialty electronics distribution remains fragmented relative to US coastal density, creating shelf expansion potential for certified accessory portfolios. Health Canada and PMRA coordinate cross-border product safety notifications for polymer-based cases and lithium-containing power banks entering retail channels. Ontario logistics corridors absorb Proposition 65 documentation requirements for US-origin shipments.
California
Proposition 65 warning label mandates add per-unit regulatory overhead for polymer formulations containing trace phthalates without differentiation value. San Francisco Bay Area design houses absorb additional 6-10 week FCC certification cycles into product roadmaps. Los Angeles retail channels anchor licensed MagSafe-compatible portfolios for premium consumer segments.
Texas
Austin metropolitan enterprise procurement concentrates bulk purchasing agreements for wireless charging infrastructure under permanent hybrid configurations. Dallas-Fort Worth distribution hubs specify GaN-based adapters for corporate device fleets seeking thermal efficiency. Houston retail channels serve emergency replacement demand through mass merchandiser placement.
New York Metro
Same-day delivery infrastructure supports impulse replacement purchases across Manhattan and Brooklyn consumer corridors. Specialty electronics retailers retain high-touch sales for complex wireless charging mounts requiring physical inspection. Upstate distribution networks channel mid-range SKU volume into Northeast retail chains.
North America Mobile Phone Accessories Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in charging semiconductor and protective materials. The vendor base organizes around three distinct strata: ecosystem captives leveraging proprietary connector standards, third-party certification specialists competing on USB-IF and Energy Star compliance, and value-oriented assemblers serving price-sensitive replacement cycles. Strategic moves concentrate on MagSafe licensing acquisitions and gallium nitride supply chain partnerships rather than vertical manufacturing integration.
Within the ecosystem captive tier, Apple Inc. and Samsung Electronics Co., Ltd. represent proprietary standard-setters whose connector architectures generate aftermarket demand. Anker Technology exemplifies the certification specialist archetype competing through aggressive R&D positioning in power delivery architectures. Belkin International occupies a position bridging licensed portfolio access with mass retail shelf presence across Best Buy and Target electronics aisles.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics Co., Ltd. |
| Belkin International |
| Anker Technology |
| OtterBox (Otter Products LLC) |
| Sony Corporation |
| Bose Corporation |
| JBL |
| Logitech |
| Others |
Value Network & Pricing Analysis
Shenzhen manufacturing clusters anchor global charger and power bank assembly capacity, with their output fluctuations transmitting directly into North American wholesale pricing benchmarks for USB-C and wireless charging accessories.
Pricing Analysis
The customization-premium spread separates configured-to-order enterprise fleet specifications from standard retail SKUs by substantial margins. Pricing stratifies across premium MagSafe-certified tiers, USB-IF certified mid-range alternatives, and non-certified economy replacements. Price differentiation hinges on certification grade and volume scale, with enterprise procurement commanding favorable unit economics. Cost compression in the economy tier is intensifying because of Asian cell supplier consolidation, while premium segments show pricing resilience due to captive Apple ecosystem demand.
Supply Chain Analysis
Supplier-financing facilities from Asian cell manufacturers extend 90-120 day payment terms to North American assemblers, easing working capital constraints for power bank producers. Manufacturing concentrates in China, Vietnam, and South Korea for lithium-ion cells, gallium nitride semiconductors, and polycarbonate resin formulations. Raw material dependencies center on cobalt cathode chemistry, GaN-on-silicon wafers, and thermoplastic polyurethane pellets. Single-source vulnerability in cylindrical cell supply creates structural risk. Distribution runs through Texas and California logistics hubs into direct-to-consumer platforms and retail electronics aisles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise hybrid work stabilization positions this market in early-cycle recovery, with device-per-employee ratio expansion driving replacement demand across corporate procurement channels.
For Market Incumbents: Harden FCC Part 15 certification capabilities to filter uncertified competitors from retail channels. Deepen backward integration into gallium nitride semiconductor sourcing to secure thermal efficiency advantages against emerging Asian charger specialists. Channel control through Best Buy and Target shelf presence remains critical for volume defense.
For New Entrants and Emerging Players: Pursue fragmented Canadian specialty electronics distribution in Toronto and Vancouver corridors where certified accessory portfolios remain underrepresented. Enterprise wireless charging infrastructure offers the most penetrable white-space target as hybrid policies stabilize. A direct-to-consumer launch with same-day delivery partnerships in Austin and San Francisco metropolitan clusters provides viable go-to-market positioning.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors USB-IF certification specialists with established GaN supply partnerships over ecosystem-dependent licensing plays. Long-term viability across the analysis window rests on regulatory compliance capabilities rather than brand equity alone. Energy Star efficiency designation progress for wireless charging portfolios signals acquisition target quality.
| Strategic Initiative | Industry Significance |
|---|---|
| MagSafe Licensing Acquisition | Apple's proprietary magnetic standard generates captive aftermarket demand for certified automotive and desktop mounts. |
| GaN Supply Partnership | Gallium nitride semiconductor access enables compact thermal-efficient chargers displacing legacy silicon designs. |
| Direct-to-Consumer Platform Launch | Amazon and manufacturer storefronts consolidate premium transactions away from retail margin pools. |
| Canadian Distribution Expansion | Toronto and Vancouver specialty electronics channels remain fragmented relative to US coastal density. |
| Energy Star Certification Investment | Federal efficiency designations advantage early-certified products in government and enterprise procurement. |
Research Methodology
A standing panel of accessory product managers, FCC certification consultants, enterprise IT procurement officers, and retail category buyers provided ongoing calibration across the study. Primary interviews with these stakeholders combined with secondary validation from FCC equipment authorization databases, USB-IF certification registries, SEC 10-K filings, and customs import records. Bottom-up volume estimates triangulated against top-down market sizing.
Scenario-bracketing framed analytical outputs across the projection horizon, with segmentation modeling across product type, end user archetype, distribution channel, and price tier dimensions. CAGRs derived from regression analysis against historical replacement cycle data and enterprise procurement trend indicators. Forecast inputs incorporated gallium nitride adoption curves and FCC regulatory timeline assumptions.
Sensitivities concentrate around lithium-ion cell supply disruptions, FCC certification backlog extensions, and USB-C standardization acceleration. Forecasts reflect documented assumptions about hybrid work policy permanence and MagSafe ecosystem expansion. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Wireless Speakers Market
Consumer Electronics
Portable Media Player Market
Consumer Electronics
FMCG Market
Consumer Electronics
Android TV Box Market
Consumer Electronics
Mini Bluetooth Shower Speaker Market
Consumer Electronics
Pet Cameras Market
Consumer Electronics
Electric Water Bottle Market
Consumer Electronics
Gaming Laptop Market
Consumer Electronics
Portable Speaker Market
Consumer Electronics
Nail Art Printer Market
Consumer Electronics
Vibrating Alarm Clock Market
Consumer Electronics
United States Gaming Peripherals Market
Consumer Electronics
Global Office and Contact Center Headset Market
Consumer Electronics
Smart Home Projector Market
Consumer Electronics
Global Smart Earbuds Market
Consumer Electronics
UAE Consumer Electronics Market