
 Consumer Electronics Repair and Maintenance Market | 2026-2036
Consumer Electronics Repair and Maintenance Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer Electronics Repair and Maintenance Market Analysis
The pricing and service model for consumer electronics repair is decoupling sharply between premium authorized channels and commodity aftermarket operations. Asurion, LLC sustains its position through insurance-backed repair ecosystems that lock in recurring customer relationships. iFixit, Inc. differentiates by publishing open-source repair documentation and selling OEM-grade component kits directly to technicians and retail users. Best Buy Co., Inc. leverages its Geek Squad infrastructure to control in-store traffic and capture high-margin warranty work.
Consumer electronics repair and maintenance encompasses the diagnosis, component-level replacement, firmware restoration, and cosmetic refurbishment of devices including smartphones, laptops, tablets, and smartwatches, typically performed at the board or sub-assembly level using soldering stations, diagnostic software, and electrostatic discharge protocols to restore functional performance and extend operational lifespan. Screen replacement services anchor revenue for most independent shops due to high incident frequency and standardized part availability across major brands. Mail-in repair operations are expanding fastest among corporate users managing distributed device fleets, while DIY kits represent a margin-challenged but growing segment driven by enthusiast communities and component cost transparency.
The US Federal Trade Commission scrutinizes repair restriction practices under antitrust frameworks, while the European Union's Ecodesign for Sustainable Products Regulation and national right-to-repair laws in France and Germany mandate spare part availability timelines and diagnostic access for independent technicians. India's BIS certification requirements for replacement components create compliance barriers that favor organized service networks over informal operators. Stakeholders must monitor how regulatory fragmentation across jurisdictions reshapes sourcing strategies and service delivery models.
Market Dynamics
The Consumer Electronics Repair and Maintenance Market is being fundamentally restructured by right-to-repair legislation that forces OEMs to release proprietary diagnostic tools and spare parts to independent technicians, eroding decades of closed repair ecosystems.
Growth Catalysts
- EU Ecodesign Mandates:France and Germany now require manufacturers to supply replacement parts for minimum ten-year windows, directly expanding the addressable market for independent repair networks.
- Corporate IT Asset Recovery:Enterprise fleet managers are formalizing refurbishment programs to meet ESG reporting requirements under CSRD, creating contracted service volume.
- India's Organized Service Expansion:Tier-one cities Mumbai, Delhi, and Bangalore are seeing branded repair chains displace informal bazaar operators through BIS-certified component sourcing.
Market Restraints
- Component Authentication Costs:OEMs are deploying serialized parts and firmware locks that require proprietary activation tools, raising input costs for non-authorized channels.
- Skill Pipeline Constraints:Surface-mount soldering and board-level diagnostics demand training programs that remain underdeveloped outside manufacturer-certified academies.
- Substitution by Replacement:Entry-tier smartphone price compression in emerging markets reduces the economic rationale for repair versus device replacement.
Strategic Opportunities
- Mail-in Corporate Fleets:Distributed enterprise device management is creating demand for centralized refurbishment hubs with chain-of-custody documentation.
- DIY Component Kits:Open-source repair documentation paired with OEM-grade part bundles is capturing enthusiast segments previously served by gray-market channels.
- India's Tier-Two Penetration:Organized networks are replicating Delhi and Mumbai service density in Pune, Hyderabad, and Chennai through standardized technician training.
Industry Challenges
- Diagnostic Tool Fragmentation:Each OEM maintains proprietary software ecosystems, forcing multi-brand repair shops to license multiple expensive platforms.
- ESD Protocol Compliance:Electrostatic discharge-safe workspaces require capital investment in flooring, wrist straps, and climate control that squeezes independent operator margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Electronics Repair and Maintenance Market |
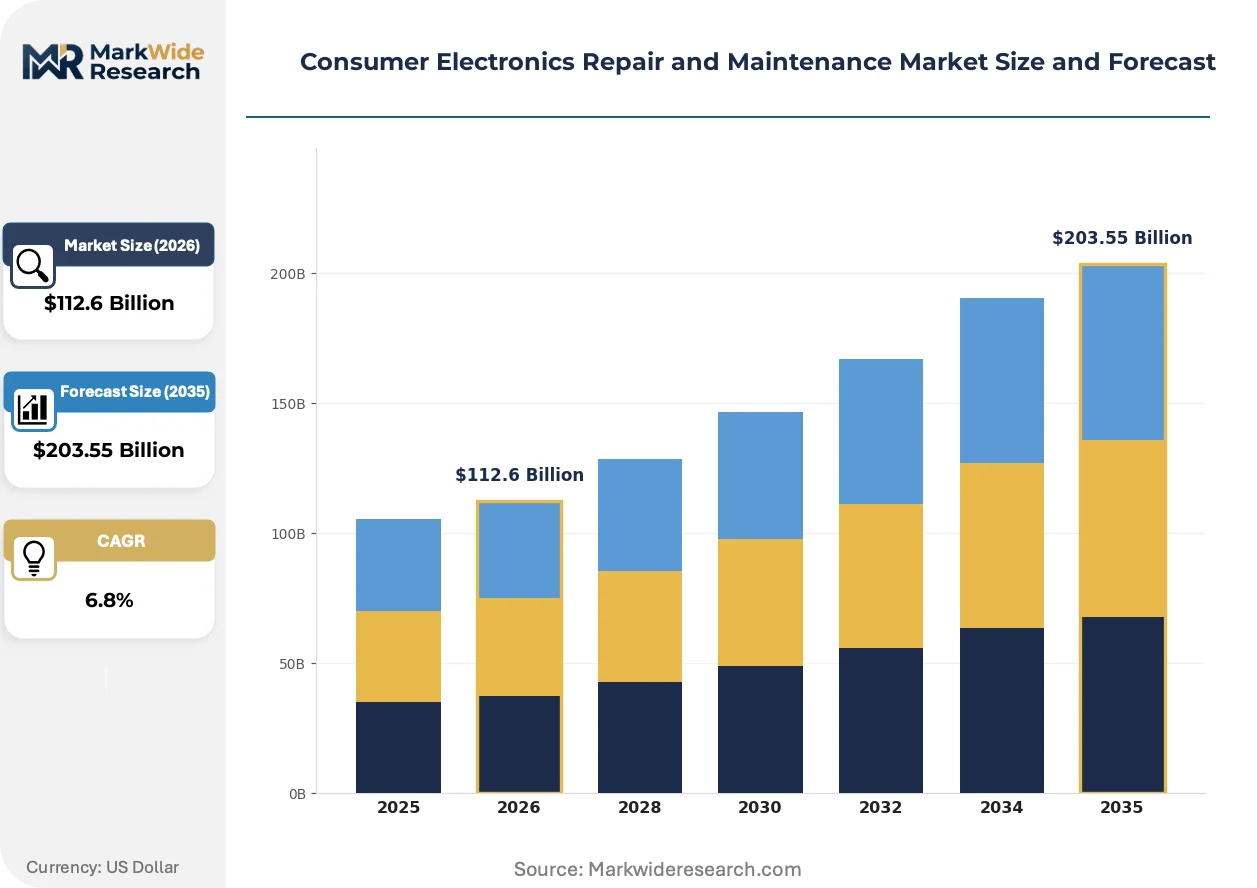
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $203.55 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Screen Replacement, Battery Replacement, Water Damage Repair, Software Troubleshooting Product Type: Smartphones, Laptops, Tablets, Smartwatches Customer Type: Retail Users, Corporate Users, Educational Institutions, Technicians Repair Method: In-Store Repair, On-Site Service, Mail-In Repair, DIY Kits |
| Companies Covered | iCracked, Electronix Services, Asurion, LLC, iFixit, Inc., B2X Care Solutions, Best Buy Co., Inc., Encompass Supply Chain Solutions, CPR Cell Phone Repair, LLC, uBreakiFix, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Electronics Repair and Maintenance Market Emerging Trajectories
Repair methodology is converging with data recovery and cybersecurity services as devices store sensitive biometric and financial information, forcing technicians to expand competency beyond hardware replacement.
Automated optical inspection systems are integrating into high-volume repair workflows to detect microfractures and solder joint defects invisible to manual inspection. Large refurbishment chains in the United States and Germany are adopting these systems to reduce return rates on warranty work. The technology is integrating quality assurance processes previously reserved for manufacturing into post-market service operations.
The EU's Ecodesign for Sustainable Products Regulation is mandating repairability index scoring for smartphones and laptops sold in member states. Manufacturers must publish disassembly sequences and parts availability timelines, enabling independent technicians to compete on speed and cost. French enforcement through ADEME is already pressuring OEMs to redesign adhesive-heavy assemblies that previously prevented non-destructive opening.
Enterprise procurement teams are unbundling repair services from original equipment warranties, negotiating direct contracts with third-party maintenance providers. Financial services and healthcare verticals in North America are leading this shift due to data security requirements that conflict with OEM remote diagnostic access. The behavior is most visible among HIPAA-covered entities that cannot permit cloud-based device telemetry.
Consumer Electronics Repair and Maintenance Market Segmentation
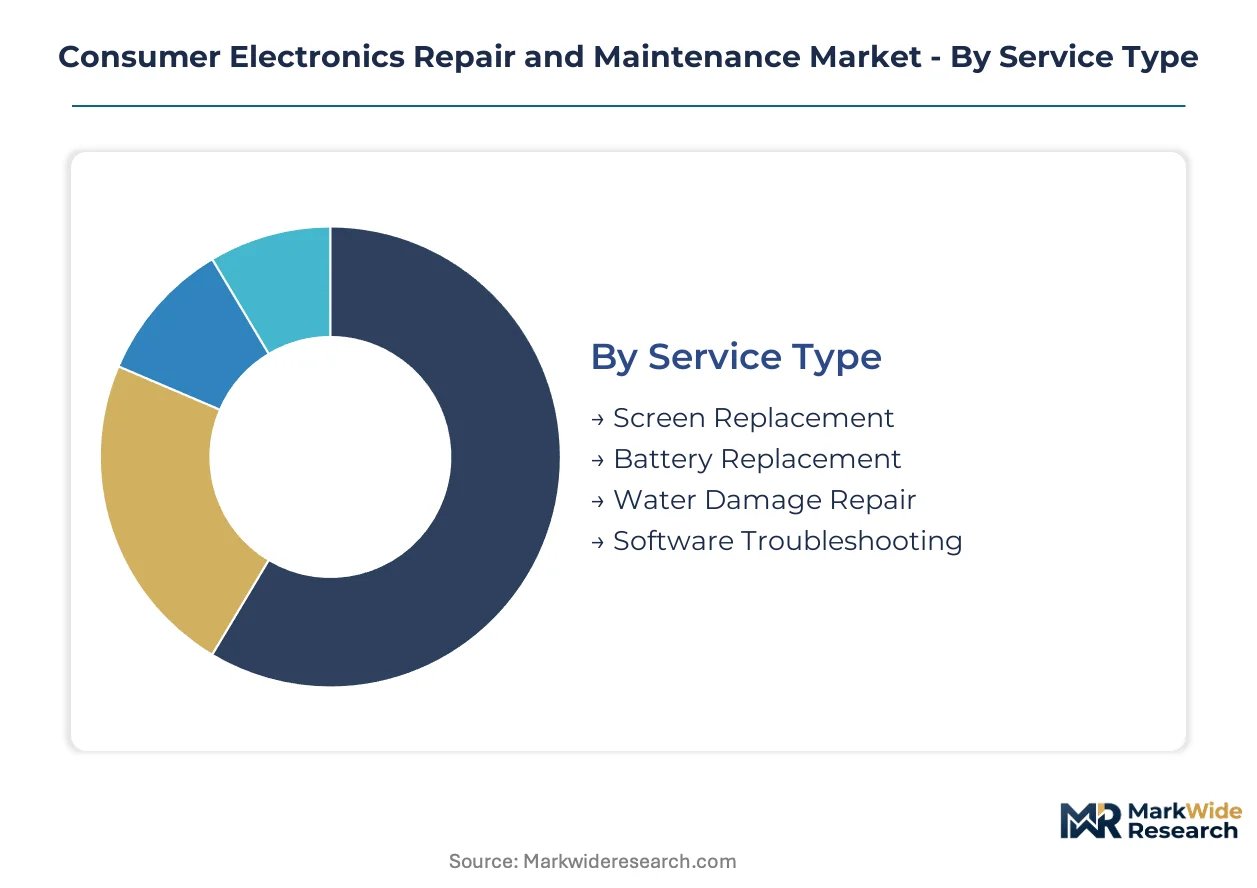
Repair service providers configure operations around damage frequency, device value thresholds, and customer urgency tolerance. Segmentation reveals where margin concentrates versus where volume scales, guiding capital allocation across technician training, inventory stocking, and service format deployment.
Service Type:
Cost tier drives customer channel selection, with premium authorized pricing coexisting alongside commodity aftermarket alternatives.
- Screen Replacement:Glass and OLED panel swaps constitute the highest-frequency repair event across all device categories. Demand clusters in urban India and tier-one Chinese cities where high smartphone penetration meets dense informal repair infrastructure.
- Battery Replacement:Lithium-ion cell swaps address capacity degradation, a functional failure mode distinct from physical damage. Corporate fleet managers in Germany and France are formalizing scheduled battery refresh programs under ESG reporting frameworks.
- Water Damage Repair:Ultrasonic cleaning and corrosion mitigation services target liquid ingress events. Component-level recovery rates vary sharply by immersion duration and water chemistry.
- Software Troubleshooting:Firmware restoration, boot loop resolution, and data recovery services expand technician competency requirements beyond hardware replacement.
Volume sits with screen replacement; growth tilts toward battery replacement.
Product Type:
Application context determines repair economics, with mobility-constrained devices commanding premium pricing for same-day resolution.
- Smartphones:Pocket-carried devices experience the highest damage incidence rates from drops and liquid exposure. India's organized service networks in Mumbai and Delhi are displacing informal bazaar operators through BIS-certified component sourcing.
- Laptops:Higher average selling prices extend repair viability windows versus replacement decisions. Enterprise procurement teams in the United States are unbundling laptop repair from OEM warranties under HIPAA data security constraints.
- Tablets:Shared-use environments in education and healthcare drive demand for screen and charging port repairs. Repair frequency lags smartphones due to lower mobility and protective case adoption.
- Smartwatches:Miniaturized assemblies challenge technician skill requirements, with adhesive-heavy constructions complicating non-destructive opening. French ADEME enforcement is pressuring OEMs to redesign for improved repairability index scores.
Smartphones capture the largest service volume; smartwatches are climbing the fastest as wrist-worn computing expands.
Customer Type:
Volume scale separates individual transactions from contracted fleet management, with procurement sophistication dictating terms negotiation leverage.
- Retail Users:Individual consumers prioritize convenience and speed over cost optimization, driving traffic to mall-based service kiosks and mail-in programs. Price sensitivity intensifies for devices beyond warranty coverage.
- Corporate Users:Distributed enterprise fleets require chain-of-custody documentation and data sanitization protocols. Financial services and healthcare verticals in North America lead third-party maintenance contracting due to telemetry access restrictions.
- Educational Institutions:K-12 and university device deployments generate seasonal repair surges around academic calendar damage events. Bulk pricing negotiations favor standardized device models to simplify parts inventory.
- Technicians:Professional repair operators purchase diagnostic tools, component kits, and training materials as a distinct procurement segment. iFixit and similar suppliers serve this channel with open-source documentation and OEM-grade parts bundles.
Retail users dominate transaction count; corporate users are expanding most quickly through formalized fleet refurbishment programs.
Repair Method:
Margin structure varies by real estate intensity, with physical presence commanding premium pricing against remote and self-service alternatives.
- In-Store Repair:Immediate component replacement at dedicated service locations captures highest customer willingness-to-pay for urgency. Best Buy's Geek Squad infrastructure exemplifies traffic-driven warranty work capture.
- On-Site Service:Technician dispatch to customer locations serves corporate campuses and high-value individual clients. Travel time and vehicle stocking requirements compress margins versus fixed-location operations.
- Mail-In Repair:Centralized refurbishment hubs achieve scale economies for corporate fleet management. Chain-of-custody documentation meets ESG reporting requirements under the EU's CSRD framework.
- DIY Kits:Component bundles paired with repair documentation serve enthusiast communities and cost-sensitive users. Open-source documentation from iFixit reduces information asymmetry previously exploited by gray-market channels.
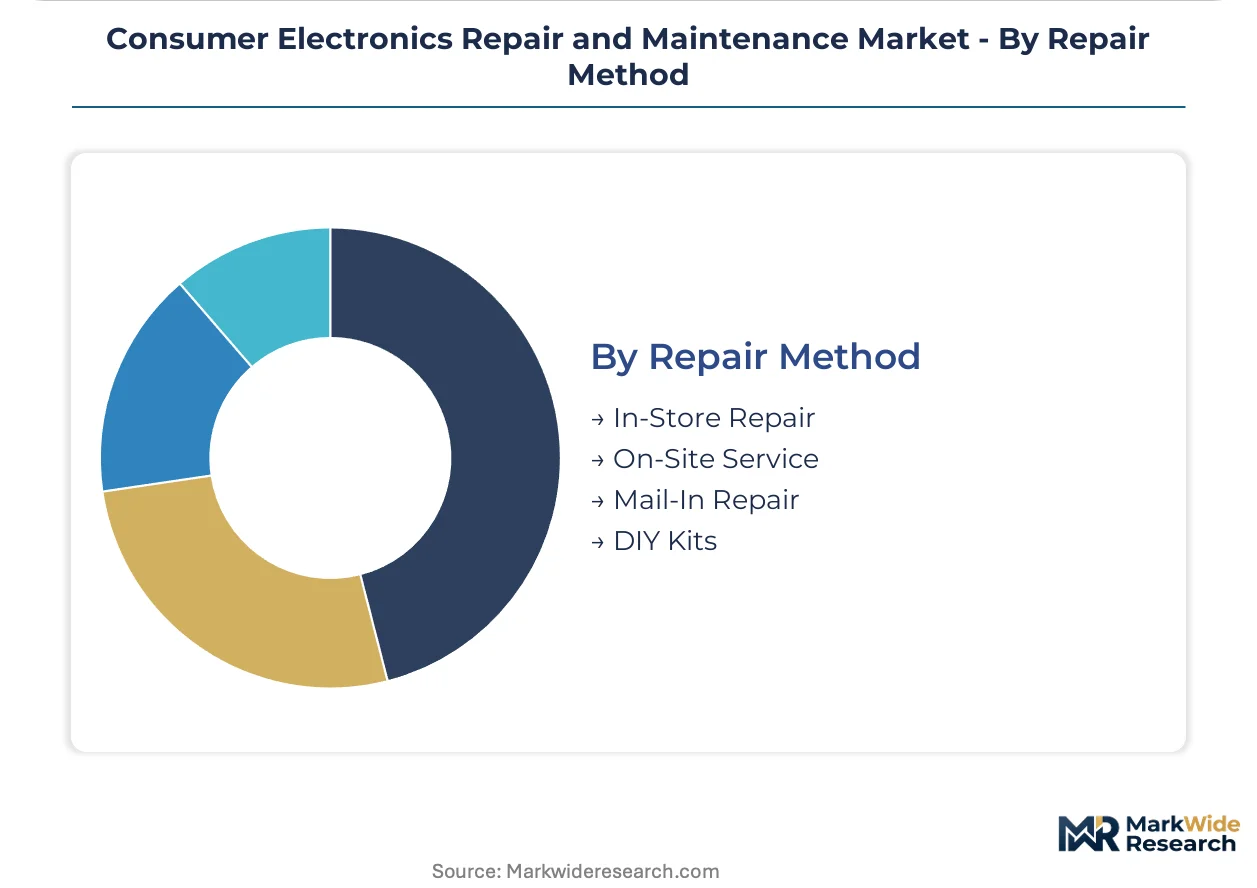
In-store repair holds the revenue base; mail-in repair is gaining share fastest among enterprise procurement teams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Delhi and Mumbai anchor the industry's densest repair infrastructure, where informal bazaar networks compete with organized service chains for smartphone refurbishment volume.
United States
Enterprise fleet managers in financial services and healthcare verticals are unbundling repair services from OEM warranties due to HIPAA data security constraints. The FTC scrutinizes repair restriction practices under antitrust frameworks. Best Buy's Geek Squad infrastructure in suburban retail corridors captures high-margin warranty work through traffic-driven service models.
Germany
Corporate IT asset recovery programs are formalizing refurbishment operations to meet CSRD reporting requirements for ESG compliance. National right-to-repair laws mandate ten-year spare part availability windows for manufacturers. Berlin and Munich host centralized refurbishment hubs serving distributed enterprise device fleets across the DACH region.
France
ADEME enforcement is pressuring OEMs to redesign adhesive-heavy smartphone assemblies that previously prevented non-destructive opening. The repairability index scoring mandate under EU Ecodesign regulation requires published disassembly sequences. Paris-based independent repair networks are expanding technician training programs to exploit newly available diagnostic access.
India
Tier-one cities Mumbai, Delhi, and Bangalore are seeing branded repair chains displace informal bazaar operators through BIS-certified component sourcing. BIS certification requirements for replacement components create compliance barriers favoring organized networks. Organized service providers are replicating Delhi and Mumbai service density in Pune, Hyderabad, and Chennai through standardized technician training.
China
Mail-in repair operations are scaling for corporate users managing distributed device fleets across manufacturing and technology sectors. MIIT standards govern aftermarket component quality and technician certification requirements. Shenzhen's electronics manufacturing ecosystem is spawning vertically integrated repair service providers with captive component supply chains.
Consumer Electronics Repair and Maintenance Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification status and warranty backing. The market structures around three tiers: insurance-backed repair ecosystems, retail-anchored service networks, and independent shop aggregators. Strategic archetypes include warranty-captive operators, open-source documentation publishers, and component-kit suppliers. Competitive moves concentrate on technician certification program expansion and proprietary diagnostic tool licensing.
Within the insurance-backed tier, Asurion, LLC and Best Buy Co., Inc. exemplify recurring-revenue models that lock customer relationships through warranty ecosystems. iFixit, Inc. occupies a distinct position as an open-source documentation publisher serving technician and enthusiast segments directly with OEM-grade component kits. These three entities represent the primary competitive vectors: warranty-captive service integration, retail traffic monetization, and information-asymmetry reduction through transparent repair guidance.
| Leading Market Players |
|---|
| iCracked |
| Electronix Services |
| Asurion, LLC |
| iFixit, Inc. |
| B2X Care Solutions |
| Best Buy Co., Inc. |
| Encompass Supply Chain Solutions |
| CPR Cell Phone Repair, LLC |
| uBreakiFix, LLC |
| Others |
Supply Flow & Price Mechanics
Surface-mount soldering specialists concentrated in Shenzhen and Guangzhou anchor labor-cost differentials that spread pricing-tier spreads between premium authorized channels and commodity aftermarket operations. India's BIS certification requirements for replacement components compress margins for informal bazaar operators while organized networks capture premium pricing through compliance-backed warranty terms.
Pricing Analysis
Outcome-based pricing tied to device uptime guarantees anchors premium service tiers, separating authorized repair networks from transactional aftermarket alternatives. Certification grade and geographic delivery cost drive price differentiation, with BIS-certified components in India and ADEME-compliant services in France commanding substantial premiums over gray-market equivalents. Pricing pressure stems from serialized parts and firmware locks requiring proprietary activation tools, raising input costs for non-authorized channels. Corporate fleet managers show least price sensitivity due to ESG reporting requirements, while retail users beyond warranty coverage exhibit highest cost consciousness.
Supply Chain Analysis
India's domestic-content mandates through BIS certification requirements are reshaping sourcing patterns for replacement components, displacing unverified imports. Supply concentrates in China, South Korea, and Taiwan for OLED panels, lithium-ion cells, and semiconductor-grade solder. Raw material dependencies span rare-earth magnets, cobalt-based battery chemistries, and high-purity copper for flex cables. Single-source vulnerability around proprietary diagnostic tools creates structural risk as each OEM maintains isolated software ecosystems. Distribution runs through authorized distributor networks, gray-market component bazaars, and direct-to-technician platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a technology-transition phase as automated optical inspection systems displace manual quality assurance in high-volume refurbishment workflows.
For Market Incumbents: Acquire technician training infrastructure to lock in certified labor pipelines before skill scarcity intensifies. Consolidate diagnostic tool licensing agreements across multiple OEM ecosystems to reduce platform fragmentation costs. Defend against mail-in corporate fleet specialists by embedding chain-of-custody documentation into existing service workflows. For New Entrants and Emerging Players: Corporate procurement teams unbundling repair from OEM warranties represent the most penetrable channel partner type for third-party maintenance contracts. Target financial services and healthcare verticals in North America where HIPAA constraints block cloud-based OEM telemetry. Lead with data sanitization protocols and ESG-compliant refurbishment documentation as the primary go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated refurbishment hubs given CSRD-driven enterprise demand expansion. Long-term viability over the next decade favors operators combining captive component supply with standardized technician certification programs. Watch ADEME enforcement intensity in France as the inflection indicator for broader EU repairability mandate adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Technician Certification Program Expansion | BIS-compliant training pipelines in India displace informal bazaar labor pools. |
| Diagnostic Tool Licensing Agreement | Multi-OEM platform access reduces fragmentation costs for independent repair networks. |
| Mail-in Refurbishment Hub Scale-Up | Centralized operations capture corporate fleet volume under CSRD reporting frameworks. |
| Component Authentication Technology Investment | Serialized parts tracking satisfies OEM firmware lock requirements for warranty-backed services. |
| Open-Source Documentation Platform Development | Transparent repair guidance reduces information asymmetry previously exploited by gray-market channels. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with repair network operators, OEM service executives, corporate IT asset managers, and BIS certification auditors. Secondary sources encompassed FTC antitrust dockets, EU Ecodesign regulatory texts, ADEME enforcement bulletins, MIIT standards documentation, and India DGFT import classification records. Bottom-up service volume estimates triangulated against top-down market value reconstructions.
Data-stream reconciliation across shipment volumes, service transaction frequencies, and average revenue per repair yielded consistent trajectory signals across the projection horizon. Segmentation dimensions modeled encompassed service type, product category, customer archetype, and repair method, with additional stratification by certification tier and geographic regulatory cluster. CAGRs derived from fitted growth curves applied to baseline volume estimates, incorporating right-to-repair legislative passage timelines and corporate ESG program adoption curves as industry-specific forecast inputs.
Caveats apply where right-to-repair enforcement intensity, OEM parts pricing strategies, or substitution thresholds between repair and replacement could materially shift the outlook. Forecasts embed assumptions regarding regulatory harmonization pace and technician training pipeline development. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Smart Television and Set-Top Box Market
Consumer Electronics
Streaming Devices Market
Consumer Electronics
China Refurbished Smartphone Market
Consumer Electronics
Consumer Electronics Market
Consumer Electronics
Waterproof Bathroom TV Market
Consumer Electronics
Tattoo Stencil Printer Market
Consumer Electronics
Consumer Electronic Accessories Market
Consumer Electronics
Baby Monitor Market
Consumer Electronics
Global Automated Laundromat Services Market
Consumer Electronics
Universal Remote Controls Market
Consumer Electronics
Mechanical Keyboard Market
Consumer Electronics
Notebook Market
Consumer Electronics
Smartphone Console Market
Consumer Electronics
Kids Tablet Market
Consumer Electronics
Refurbished Electronics Market
Consumer Electronics
Airport Retailing Consumer Electronics Market