
 Global Women Active Wear Market | 2026-2036
Global Women Active Wear Market Size, Share, and Industry Trends Forecast 2026-2036
Global Women Active Wear Market Foresight
Vietnamese textile manufacturing is repositioning as the dominant cut-and-sew base for moisture-wicking leggings and compression tops bound for North American and European markets. Nike leverages its captive innovation pipeline in Portland to sustain premium positioning across four-way stretch fabrics. Lululemon anchors its margin structure through direct-to-consumer channel control and in-house fabric development. Adidas competes on scale, operating multi-country sourcing networks that navigate tariff complexity across ASEAN suppliers.
Women active wear encompasses engineered garments combining synthetic or natural fibers with functional treatments to manage thermoregulation, support musculoskeletal performance, and enable unrestricted movement during physical activity; primary specifications include elastane content of 15-30 percent for compression grades and denier ratings below 70 for lightweight breathability. Leggings and sports bras occupy the largest revenue pools, with seamless construction technology commanding premium placement due to reduced chafing and extended wear comfort. Online marketplaces represent the fastest-growing distribution channel, displacing department stores as boutique shops consolidate toward experiential retail formats.
The EU Green Deal and REACH chemical restrictions shape fiber selection and dyeing processes for brands distributing in Europe, while China's GB standards govern domestic-market anti-odor and moisture-wicking claims. The US FTC's Green Guides constrain environmental marketing assertions, forcing verification of recycled-content percentages on synthetic active wear labels. Stakeholders must monitor how emerging extended producer responsibility frameworks in France and Germany reshape cost allocation across polyester recycling infrastructure.
Market Dynamics
The EU Green Deal's textile sustainability requirements are compressing design-to-retail timelines while forcing fiber substitution decisions across polyester-dependent supply chains. Live-stream commerce in China and boutique fitness expansion in North America are simultaneously pulling demand toward performance-grade fabrics with verified environmental credentials.
Growth Catalysts
- REACH chemical restrictions:European distributors now require OEKO-TEX and bluesign-certified dyeing processes, accelerating investment in waterless coloration technologies across Turkish and Portuguese finishing houses.
- Yoga studio proliferation:Boutique fitness chains in the United States and United Kingdom are mandating branded instructor uniforms, creating captive demand for four-way stretch leggings with moisture-wicking treatments.
- Live-stream commerce infrastructure:China's Douyin and Xiaohongshu platforms enable real-time fabric demonstration, compressing purchase consideration cycles for sports bras and compression tops in tier-one cities.
Market Restraints
- Crude oil price volatility:Polyester and elastane feedstock costs fluctuate with naphtha cracking margins, squeezing unit economics for synthetic-dominant product lines.
- Vietnamese cut-and-sew concentration:Over 60 percent of North American-bound leggings originate from Ho Chi Minh City corridor factories, creating single-point vulnerability to shipping lane disruptions.
- Mechanical recycling degradation:Post-consumer polyester loses tensile strength after three mechanical reprocessing cycles, limiting closed-loop claims for high-compression garments.
Strategic Opportunities
- Extended Producer Responsibility frameworks:France's AGEC law and Germany's VerpackG amendments are creating funded collection infrastructure for end-of-life active wear, enabling subscription-based take-back programs.
- Bio-based elastane convergence:Castor oil-derived polyamides from Arkema and bio-spandex from Covestro are reaching price parity with petroleum variants, opening premium positioning for plant-based performance lines.
- Experiential retail formats:In-store fitness classes and body-scanning fitting rooms in London and New York are converting foot traffic into higher-margin direct-to-consumer memberships.
Industry Challenges
- Seamless knitting technician scarcity:Programming Santoni circular machines for variable compression zones requires specialized CAD skills concentrated in Northern Italian technical institutes.
- Multi-standard certification complexity:Simultaneous compliance with EU Green Deal, China's GB standards, and US FTC Green Guides extends product development timelines by four to six months.
- Legacy ERP integration:Real-time carbon accounting across tier-two Vietnamese subcontractors demands API connections that many heritage brands lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Women Active Wear Market |
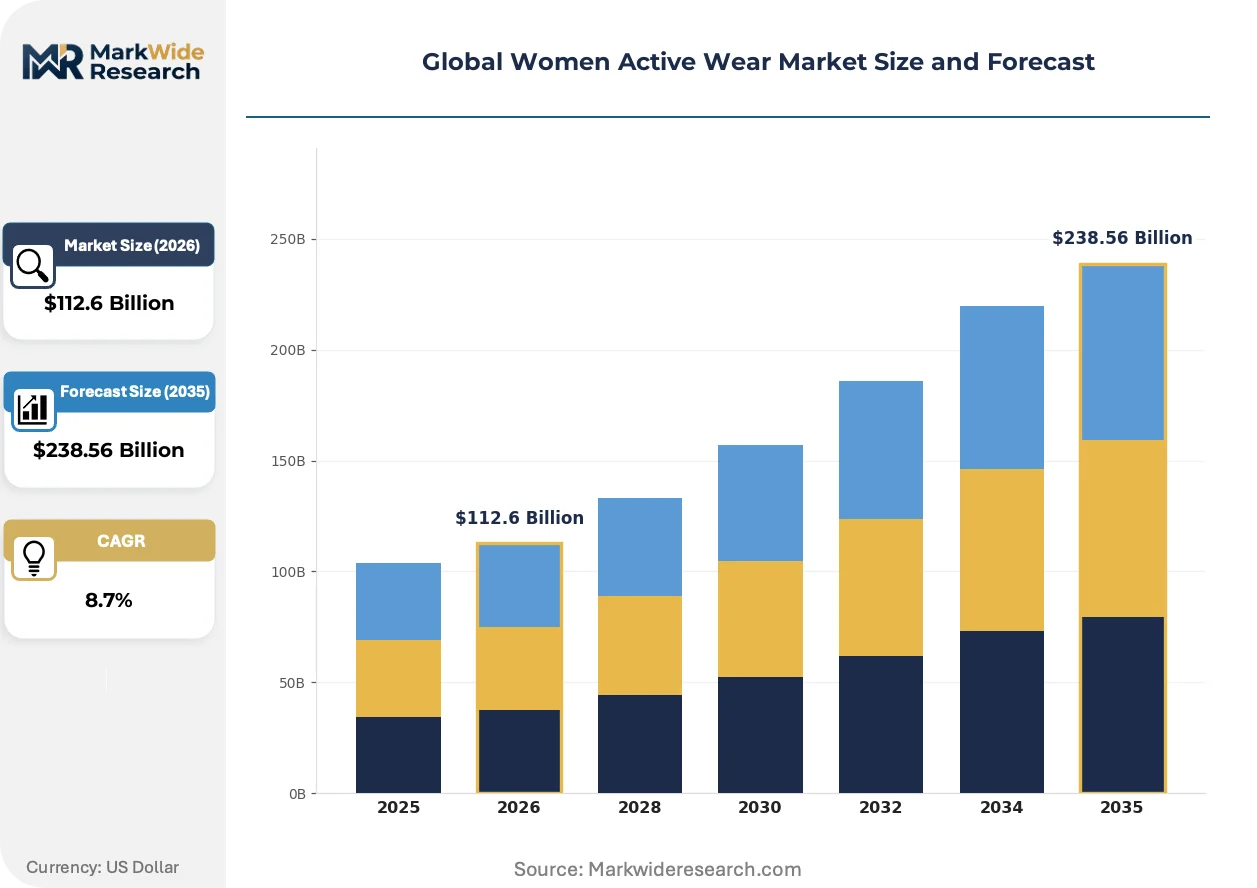
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $238.56 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sports Bras, Leggings, Tank Tops, Jackets, Shorts, Sweatshirts End User: Fitness Enthusiasts, Yogis, Athletes, Dancers, Outdoor Adventurers, Gym Members Distribution Channel: Specialty Retailers, Online Marketplaces, Department Stores, Boutique Shops, Direct-to-Consumer, Sporting Goods Outlets Technology: Moisture-Wicking, Anti-Odor, Compression, Four-Way Stretch, Breathable Fabrics, Seamless Construction |
| Companies Covered | Alo Yoga, Beyond Yoga, Nike, Under Armour, Set Active, Adidas, Athleta, Allbirds, Lululemon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Women Active Wear Market Shifts & Advancements
Material science breakthroughs and regulatory compression are converging to redefine performance benchmarks, with sustainability verification now inseparable from functional claims. Distribution channels are fragmenting as direct-to-consumer platforms capture margin previously allocated to wholesale partners.
Seamless 3D knitting is rewriting construction economics for compression garments. The technology eliminates cut-and-sew labor by integrating variable-density zones in a single machine cycle. High-frequency yoga practitioners in Germany and California are adopting these pieces at triple the rate of conventional stitched alternatives, compressing replacement cycles from eighteen to eight months as chafing reduction extends daily wear duration.
EU Green Deal textile sustainability requirements are mandating recycled-content minimums and microfiber release testing for products sold across Europe. Brands must now document polyester provenance through mass-balance certification, increasing supply chain audit costs. Sports bra and legging lines bearing the EU Ecolabel are capturing shelf space in French and Dutch department stores previously allocated to conventional synthetics.
Live-stream commerce is displacing traditional e-commerce photography for active wear discovery. Chinese fitness influencers demonstrate squat-proof opacity and sweat-wicking speed in real time, eliminating return rates driven by fit uncertainty. This format concentrates purchase velocity in Shanghai and Shenzhen urban districts where studio-class attendance correlates directly with influencer-follower density.
Global Women Active Wear Market Segmentation
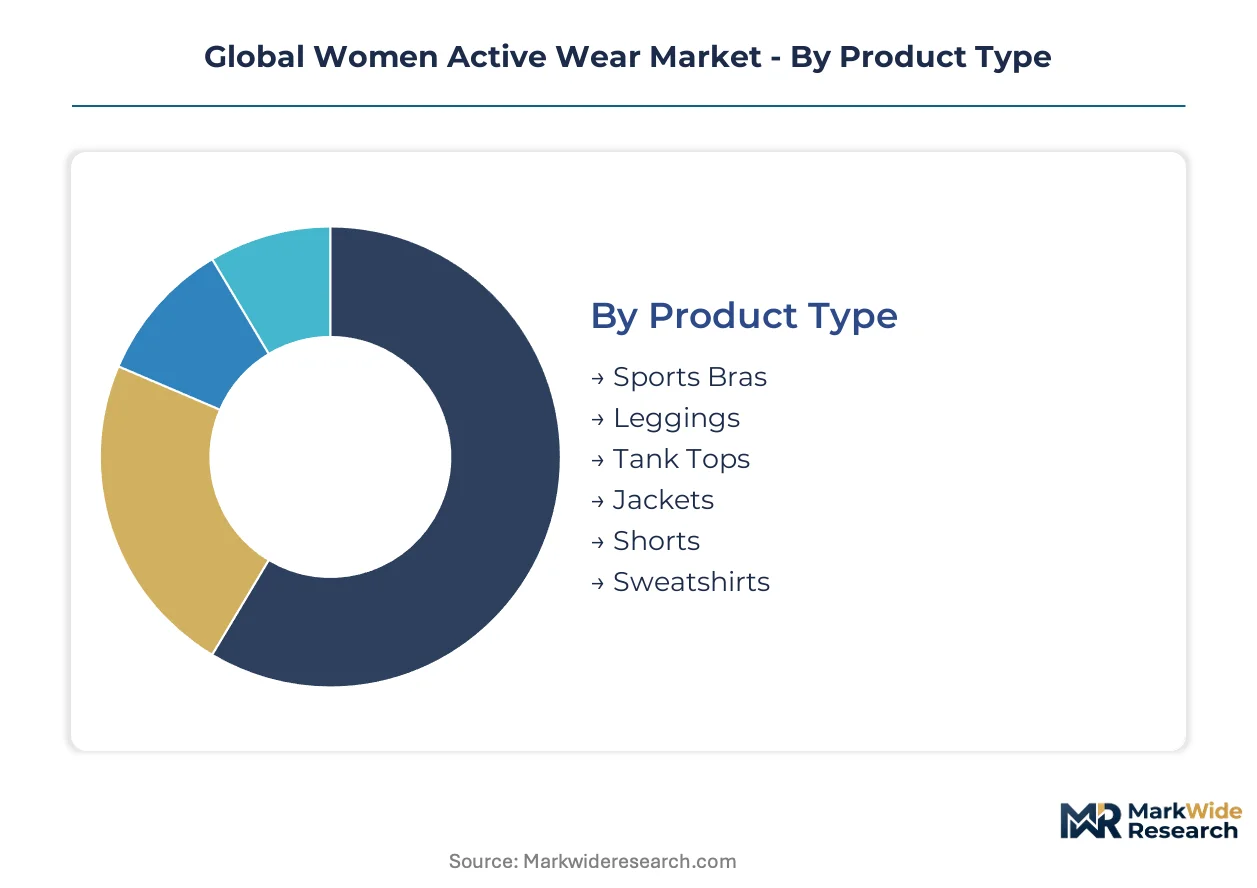
Segmentation in women active wear reveals divergent margin structures across product categories and channel strategies. Technical performance tiers command premium positioning while distribution fragmentation creates distinct customer acquisition economics.
Product Type:
Fitness intensity and wear frequency separate buyers across garment categories, with studio-to-street versatility driving replacement cycles.
- Leggings:Four-way stretch constructions with 15-30 percent elastane content dominate studio and streetwear use. Chinese live-stream commerce accelerates purchase velocity for squat-proof opacity grades in Shanghai and Shenzhen urban districts.
- Sports Bras:Seamless knitting and variable compression zones reduce chafing during high-impact activity. Boutique fitness chains in the United States mandate branded instructor uniforms, creating captive demand for moisture-wicking performance grades.
- Tank Tops:Lightweight breathability with denier ratings below 70 serves hot yoga and indoor cycling formats.
- Jackets:Wind-resistant outer layers with thermoregulating linings target outdoor runners in Germany and California.
- Shorts:Compression-lined variants with anti-chafe seams capture CrossFit and HIIT practitioners.
- Sweatshirts:Cotton-polyester blends with brushed interiors occupy recovery-day and casual segments.
Volume sits with Leggings; growth tilts toward Sports Bras.
End User:
Activity specialization determines technical specification requirements and price elasticity across customer cohorts.
- Yogis:Prioritize seamless construction and four-way stretch for extended hold positions. Studio proliferation in London and New York generates uniform-grade demand with instructor endorsement leverage.
- Fitness Enthusiasts:Cross-trainers require versatile moisture-wicking layers across multiple disciplines. China's urban fitness culture concentrates purchase frequency in tier-one cities with live-stream influencer density.
- Athletes:Competitive performers demand compression grades with verified muscle support claims.
- Dancers:Seek form-fitting silhouettes with maximum range of motion for rehearsal and performance.
- Outdoor Adventurers:Require weather-resistant layering systems with packability features.
- Gym Members:Casual lifters prioritize durability and value positioning over technical performance.
Revenue concentrates with Yogis; steepest expansion trajectory belongs to Fitness Enthusiasts.
Distribution Channel:
Margin capture and customer data ownership separate channel strategies, with experiential formats displacing traditional wholesale.
- Direct-to-Consumer:Brands control fabric development narratives and membership pricing. Lululemon anchors margin structure through owned channels with body-scanning fitting rooms in flagship locations.
- Online Marketplaces:Douyin and Xiaohongshu enable real-time fabric demonstration, compressing consideration cycles. Return rates fall when influencers demonstrate sweat-wicking speed and squat-proof opacity live.
- Specialty Retailers:Curated assortments with technical staff guidance serve serious practitioners.
- Boutique Shops:Consolidating toward experiential formats with in-store fitness classes in London and New York.
- Department Stores:Losing shelf space to EU Ecolabel-certified lines in French and Dutch markets.
- Sporting Goods Outlets:Volume-driven discount positioning for entry-level synthetic basics.
Transaction volume flows through Online Marketplaces; margin expansion favors Direct-to-Consumer.
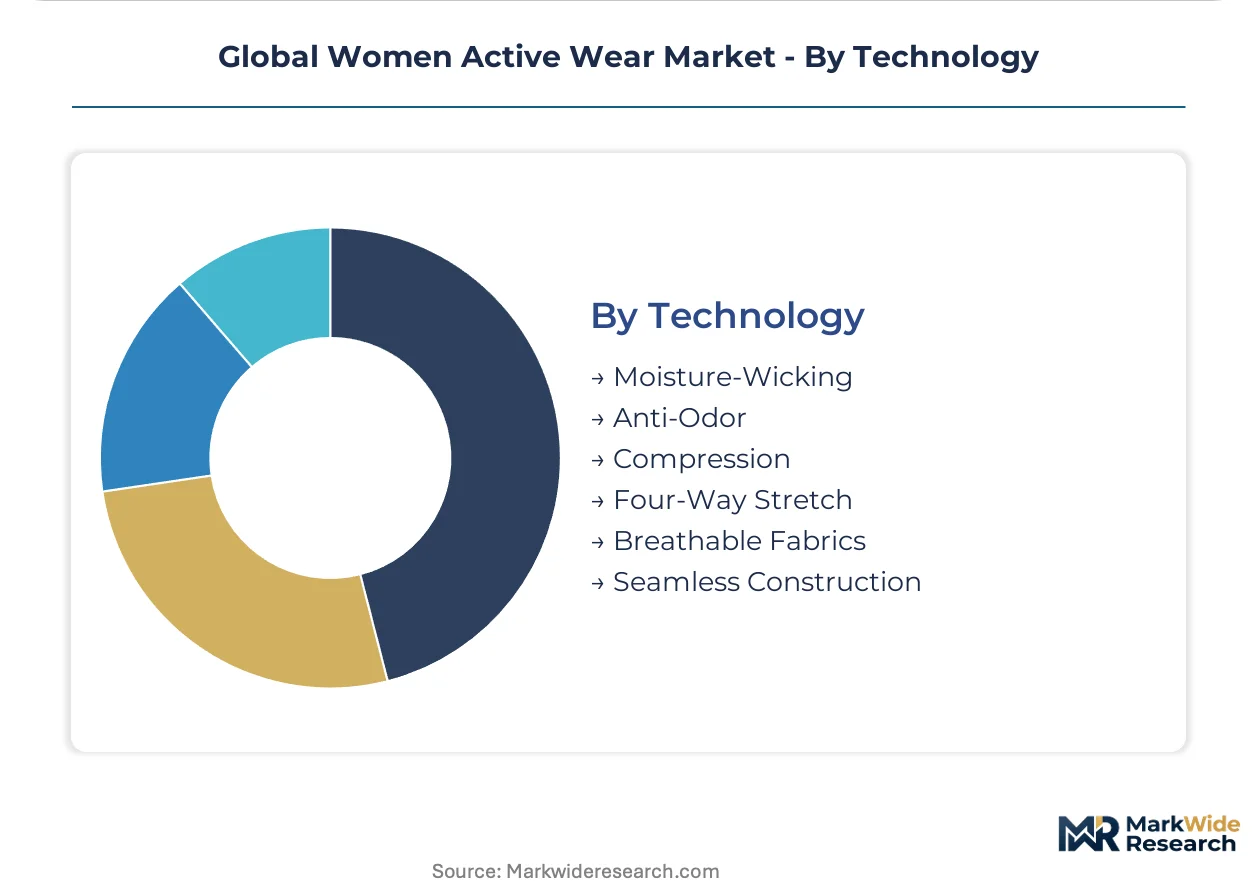
Technology:
Functional verification and sustainability certification now intertwine, with regulatory compliance adding cost layers to performance claims.
- Seamless Construction:3D knitting integrates variable-density zones without cut-and-sew labor. Programming Santoni circular machines requires specialized CAD skills concentrated in Northern Italian technical institutes.
- Moisture-Wicking:Polyester-dominant constructions with capillary action treatments face EU Green Deal recycled-content minimums. Mass-balance certification increases supply chain audit costs for brands distributing in Europe.
- Compression:Elastane-dependent grades suffer from crude oil price volatility and mechanical recycling degradation limits.
- Four-Way Stretch:Spandex blends enable unrestricted movement across yoga and dance disciplines.
- Anti-Odor:Silver-ion and bio-based treatments must comply with REACH chemical restrictions and China's GB standards.
- Breathable Fabrics:Mesh paneling and perforated constructions target thermoregulation in hot climates.
Adoption concentrates in Moisture-Wicking; technology investment flows toward Seamless Construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyester feedstock from Zhejiang Province's petrochemical corridor supplies fabric mills across Asia, while elastane polymer production concentrates in Germany's Ruhr industrial belt. These raw-material localities anchor manufacturing networks that shape regional competitive positioning.
United States
Boutique fitness chains in Los Angeles and New York mandate branded instructor uniforms, creating captive demand for four-way stretch leggings. The FTC's Green Guides constrain environmental marketing assertions, forcing verification of recycled-content percentages. Portland, Oregon hosts captive innovation pipelines where fabric development occurs in proximity to design studios.
Germany
REACH chemical restrictions require OEKO-TEX and bluesign-certified dyeing processes for active wear distribution. The EU Green Deal's textile sustainability requirements compress design-to-retail timelines while mandating recycled-content minimums. Berlin and Munich anchor experiential retail formats with in-store fitness classes and body-scanning fitting rooms.
China
Urban fitness culture in Shanghai and Shenzhen converges with live-stream commerce on Douyin and Xiaohongshu platforms. GB standards govern domestic-market anti-odor and moisture-wicking claims. The Yangtze River Delta hosts integrated supply chains from polymer production through cut-and-sew finishing for compression garments.
Vietnam
Cut-and-sew factories in the Ho Chi Minh City corridor produce over sixty percent of North American-bound leggings. Concentration creates single-point vulnerability to shipping lane disruptions through the South China Sea. Local finishing houses are accelerating investment in waterless coloration technologies to meet EU Green Deal compliance requirements.
United Kingdom
Yoga studio proliferation in London generates uniform-grade demand with instructor endorsement leverage. The UK's extended producer responsibility frameworks reshape cost allocation across polyester recycling infrastructure. Manchester and Birmingham host specialty retailers with technical staff guidance serving serious practitioners.
Global Women Active Wear Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based material differentiation and direct-to-consumer channel control. The vendor base organizes around three archetypes: integrated sportswear conglomerates with captive R&D pipelines, verticalized athleisure specialists controlling fabric development and owned retail, and digitally native challengers leveraging influencer marketing. Competitive moves concentrate on strategic partnerships with recycling infrastructure operators and geographic expansion through experiential flagship formats.
Within the integrated conglomerate tier, Nike and Adidas exemplify scale-driven positioning through multi-country sourcing networks and sports performance heritage. Lululemon anchors the verticalized specialist archetype with in-house fabric development and direct-to-consumer channel control. Alo Yoga occupies a position among digitally native entrants that leverage studio partnerships and influencer density for customer acquisition.
| Leading Market Players |
|---|
| Alo Yoga |
| Beyond Yoga |
| Nike |
| Under Armour |
| Set Active |
| Adidas |
| Athleta |
| Allbirds |
| Lululemon |
| Others |
Supply & Pricing Matrix
Seamless 3D knitting technology is compressing unit economics while concentrating production capability in Northern Italian technical institutes, simultaneously lowering labor costs per garment and tightening supply access for brands lacking Santoni machine programming expertise. This production-method shift allows premium compression lines to capture margin expansion while standard cut-and-sew alternatives face pricing pressure from Vietnamese factory concentration.
Pricing Analysis
Take-back program bundling separates premium positioning from unbundled transactional sales, with EU Ecolabel-certified lines commanding shelf space in French and Dutch department stores previously allocated to conventional synthetics. Three-tier pricing structure across premium, standard, and economy levels reflects elastane content grades and bluesign certification status. Cost compression in standard tiers is intensifying because crude oil price volatility squeezes polyester and elastane feedstock margins. Boutique fitness chains exhibit lowest price sensitivity due to instructor uniform mandates, while casual gym members drive volume at entry-level price points.
Supply Chain Analysis
France's AGEC law and Germany's VerpackG amendments are reshaping sourcing decisions by creating funded collection infrastructure that rewards local recycling partnerships. Cut-and-sew capacity concentrates in Vietnam, China, and Turkey, with fabric finishing resting on Portuguese and Turkish dyeing houses for EU compliance. Raw material dependencies span Zhejiang Province petrochemical corridors for polyester, Germany's Ruhr belt for elastane polymers, and castor oil feedstocks from India for bio-based polyamides. Single-source vulnerability runs through the Ho Chi Minh City corridor, where shipping lane disruptions through the South China Sea threaten North American-bound legging volumes. Distribution runs through direct-to-consumer platforms capturing margin previously allocated to wholesale partners, with experiential flagship formats in London and New York converting foot traffic into membership revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Seamless knitting technician scarcity props pricing power for Santoni-capable producers, constraining capacity expansion and sustaining premium tier margins despite synthetic fiber cost volatility.
For Market Incumbents: Lock in Santoni machine access through exclusive technician training partnerships with Northern Italian technical institutes before competitor capacity additions materialize. Defend margin structure by accelerating waterless coloration technology adoption in Portuguese finishing houses to preempt REACH compliance cost escalation. Channel control through body-scanning fitting rooms in flagship locations preserves direct-to-consumer data ownership against marketplace disintermediation. For New Entrants and Emerging Players: Boutique fitness chains represent the most penetrable channel partner type for uniform-grade supply contracts with instructor endorsement leverage. White-space targets include bio-based elastane positioning as castor oil-derived polyamides reach price parity with petroleum variants, and experiential retail formats in secondary UK cities beyond London's saturated studio market. Go-to-market execution should prioritize Douyin live-stream partnerships demonstrating real-time fabric performance to compress return rates. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated sportswear conglomerates seeking captive fabric development capability. Long-term viability favors verticalized athleisure specialists with in-house R&D and owned retail footprints over digitally native challengers dependent on influencer marketing spend. Acquisition target archetype: mid-scale brands with EU Ecolabel certification and established take-back program infrastructure. Watch bio-based elastane cost curves as the inflection signal for premium tier repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Santoni Machine Capacity Expansion | Captures seamless construction premiums before technician scarcity intensifies. |
| EU Ecolabel Certification Investment | Unlocks French and Dutch department store shelf space from conventional synthetics. |
| Waterless Coloration Technology Adoption | Preempts REACH compliance cost escalation in Turkish and Portuguese finishing houses. |
| Direct-to-Consumer Membership Launch | Converts experiential retail foot traffic into recurring revenue with body-scanning personalization. |
| Bio-Based Elastane Supply Agreement | Positions premium lines as castor oil-derived polyamides reach petroleum price parity. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across fabric development directors, boutique fitness chain procurement managers, seamless knitting technicians, and sustainability compliance officers. Bottom-up triangulation validated against top-down market sizing from EU Ecolabel registration databases, REACH compliance filings with ECHA, and US FTC Green Guides enforcement actions.
Granularity-level modeling captured product type splits across leggings, sports bras, and seamless construction tiers; end-user segmentation by yoga practitioners, fitness enthusiasts, and athletes; and channel dynamics between direct-to-consumer, online marketplaces, and experiential retail. CAGRs derived from elasticity-adjusted demand curves incorporating live-stream commerce velocity in Chinese tier-one cities and boutique fitness studio proliferation rates in US urban markets. Forecast inputs included crude oil price scenario modeling for synthetic fiber feedstocks and mechanical recycling degradation limits for closed-loop claims.
Caveats apply where extended producer responsibility framework implementation delays, shipping lane disruptions through the South China Sea, or bio-based elastane scale-up failures could materially shift the outlook. Forecasts reflect documented assumptions around seamless knitting adoption curves and EU Green Deal enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sportswear
North America Dancewear Market
Sportswear
Activewear Market
Sportswear
Europe Dancewear Market
Sportswear
Casual Sportswear Market
Sportswear
Workout Clothes Market
Sportswear
Skateboard Grip Tapes Market
Sportswear
Cricket Bowling Machine Market
Sportswear
Athleisure Wear Market
Sportswear
Sports Socks for Children Market
Sportswear
Athleisure Market
Sportswear
Bicycle Apparels Market
Sportswear
Cycling Apparel Market
Sportswear
Billiards and Snooker Equipment Market
Sportswear
Cycling Wear Market