
 Bluetooth Wearable Scanner Market | 2026-2036
Bluetooth Wearable Scanner Market Size, Share, and Industry Trends Forecast 2026-2036
Bluetooth Wearable Scanner Market Insights
Bluetooth Low Energy is rewriting the power-performance tradeoff for wearable scanning hardware, enabling continuous barcode capture across eight-hour shifts without recharge cycles. Honeywell leverages its vertical integration into imager module production to sustain margin control against Asian competitors. Zebra Technologies anchors North American distribution through direct enterprise sales teams and certified reseller networks. UROVO competes aggressively on price in Southeast Asian logistics markets while building local service capabilities.
A Bluetooth wearable scanner is a body-worn data capture device incorporating a linear or 2D imager, Bluetooth radio module, and rechargeable power cell, designed to transmit decoded barcode or RFID data to a host system without tethered cable constraints. Industrial-grade units typically withstand multiple drops to concrete from 1.5 meters and operate across temperature ranges from -20°C to 50°C for cold-chain warehouse environments. The inventory management application segment leads current shipment volumes as e-commerce fulfillment centers replace handheld guns with ring or glove-mounted alternatives that free both hands for package handling. Medical diagnostics represents the fastest-growing application area as hospitals deploy wearable scanners for bedside medication verification and specimen tracking workflows. Smartwatches within the product type category carry the highest average selling prices but face steeper clinical validation requirements for healthcare deployment.
The Federal Communications Commission governs radio frequency emissions for Bluetooth wearable scanners sold in the United States, while the European Union's Radio Equipment Directive mandates CE marking and electromagnetic compatibility testing for market access across member states. China's Ministry of Industry and Information Technology enforces SRRC certification for wireless transmission modules, creating a multi-jurisdictional compliance burden for vendors pursuing cross-border sales. Stakeholders must monitor evolving battery transport regulations from the International Air Transport Association, as lithium-cell shipping restrictions directly impact aftermarket parts logistics and field replacement programs.
Market Dynamics
Bluetooth Low Energy protocol refinements are compressing the power-performance tradeoff for wearable scanning hardware, enabling continuous eight-hour shift operation without recharge cycles while warehouse operators across North America and Europe accelerate replacement of tethered handheld devices.
Growth Catalysts
- E-commerce fulfillment velocity mandates:Third-party logistics providers in the United States are deploying ring-mounted scanners to achieve sub-two-hour order turnaround times, driving hardware refresh cycles in automated distribution centers.
- CE marking harmonization:The European Union's Radio Equipment Directive streamlines electromagnetic compliance testing across member states, reducing time-to-market for vendors pursuing cross-border sales within the trading bloc.
- RFID-barcode convergence:Hybrid imager modules capable of simultaneous optical and radio-frequency capture are eliminating the need for separate device categories in inventory management workflows.
Market Restraints
- Lithium-cell supply concentration:Cylindrical battery cell production concentrates among East Asian suppliers, exposing vendors to shipping restrictions from the International Air Transport Association that constrain aftermarket logistics.
- SRRC certification timelines:China's Ministry of Industry and Information Technology enforces extended wireless transmission module approval periods, creating regulatory friction for vendors prioritizing rapid product launches.
- Smartphone substitution threat:Consumer-grade mobile devices with integrated barcode applications are displacing dedicated hardware in light-use retail environments, compressing addressable market scope at the low end.
Strategic Opportunities
- Bedside medication verification:Hospital systems in Germany are piloting glove-mounted scanners for specimen tracking workflows, opening clinical validation pathways for industrial-grade hardware platforms.
- Device-as-a-service models:Subscription-based procurement structures are displacing capital expenditure cycles among mid-sized warehouse operators, enabling vendors to capture recurring revenue streams and reduce customer churn.
- India's logistics automation:The country's Production Linked Incentive scheme for electronics manufacturing is attracting component assembly investments, creating localized supply bases for Southeast Asian market penetration.
Industry Challenges
- Multi-jurisdictional compliance engineering:Vendors must simultaneously satisfy FCC emissions rules for the United States, CE marking for Europe, and SRRC certification for China, fragmenting product variant strategies and lengthening development cycles.
- Cold-chain durability validation:Warehouse environments operating at -20°C for frozen inventory require extended temperature testing protocols that compress development timelines and elevate qualification costs.
- Legacy warehouse management system integration:Older enterprise resource planning platforms lack native Bluetooth pairing protocols, forcing middleware development or hardware firmware customization that extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bluetooth Wearable Scanner Market |
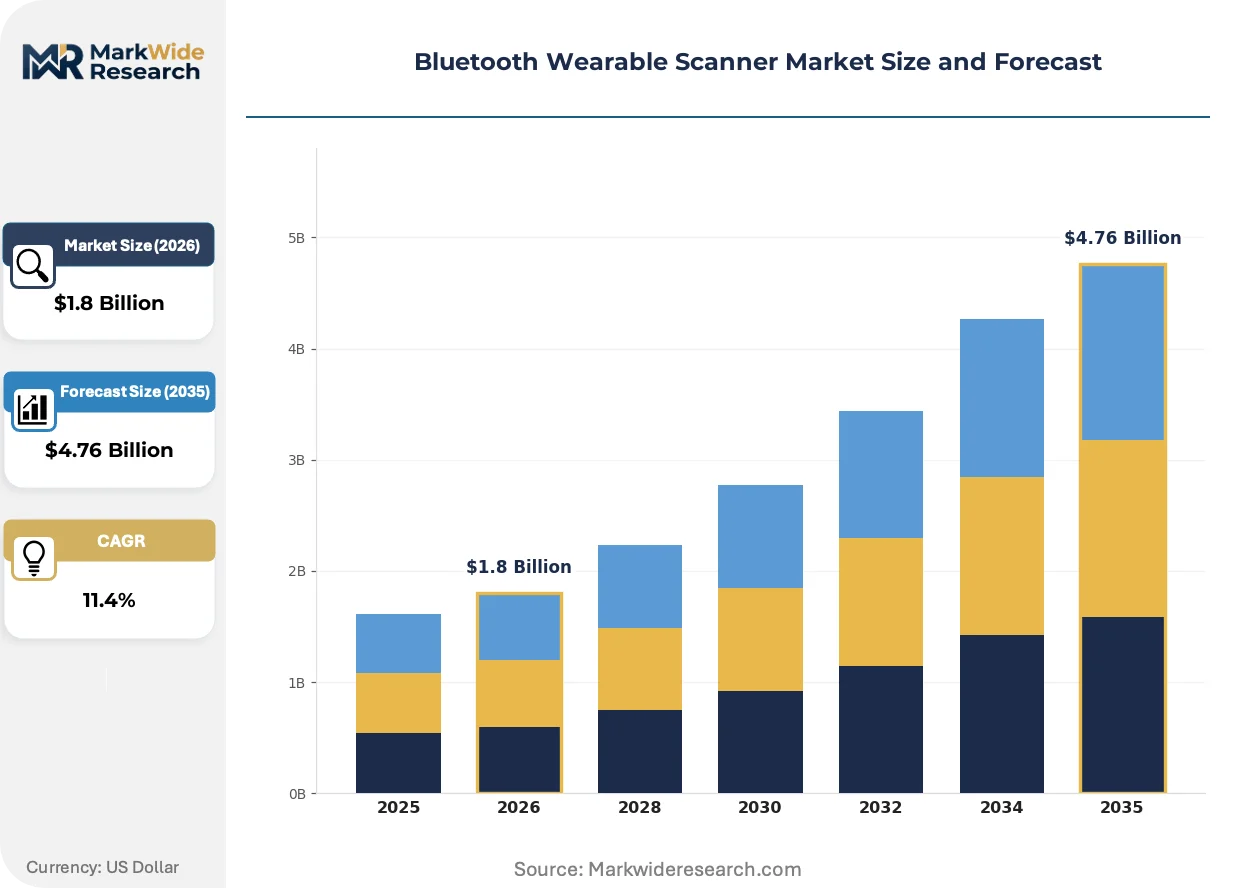
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Health Monitors, Fitness Trackers, Smartwatches, Wearable Cameras End User: Healthcare Providers, Fitness Enthusiasts, Retail Staff, Industrial Workers Connectivity: Wi-Fi, Bluetooth Low Energy, NFC, Zigbee Application: Personal Wellness, Inventory Management, Medical Diagnostics, Sports Training |
| Companies Covered | Honeywell, Zebra Technologies, Bluebird, Unitech, Newland, UROVO, Epson, Vuzix, Generalscan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bluetooth Wearable Scanner Market Trends and Innovations
Wearable scanning hardware is undergoing rapid functional convergence as power efficiency gains, regulatory harmonization pressures, and procurement model evolution simultaneously reshape vendor strategies and buyer expectations across industrial and clinical settings.
Ring-mounted scanner form factors are hybridizing linear imager and 2D matrix capabilities into single optical engines that decode both traditional barcodes and QR formats without hardware switching. Cold-chain warehouse operators in Germany are adopting these unified devices to eliminate worker hesitation during mixed-symbology picking workflows. This convergence is compressing the premium-mid-economy pricing stratification that previously separated dedicated 1D and 2D hardware categories.
REACH substance restrictions are forcing imager module manufacturers to reformulate solder compositions and eliminate legacy flame retardants from circuit board assemblies. The European Chemicals Agency's enforcement timelines are compressing component qualification windows, accelerating supplier consolidation among compliant vendors. Medical-grade scanner variants face the steepest reformulation costs due to extended biocompatibility testing requirements under the EU's Medical Device Regulation.
Outcome-based service contracts are displacing traditional break-fix maintenance arrangements among large North American third-party logistics providers. Procurement teams now negotiate guaranteed uptime thresholds with financial penalties, transferring operational risk to hardware vendors. This shift is most visible in United States e-commerce fulfillment networks where scanner downtime directly correlates with labor cost inflation and missed delivery commitments.
Bluetooth Wearable Scanner Market Segmentation
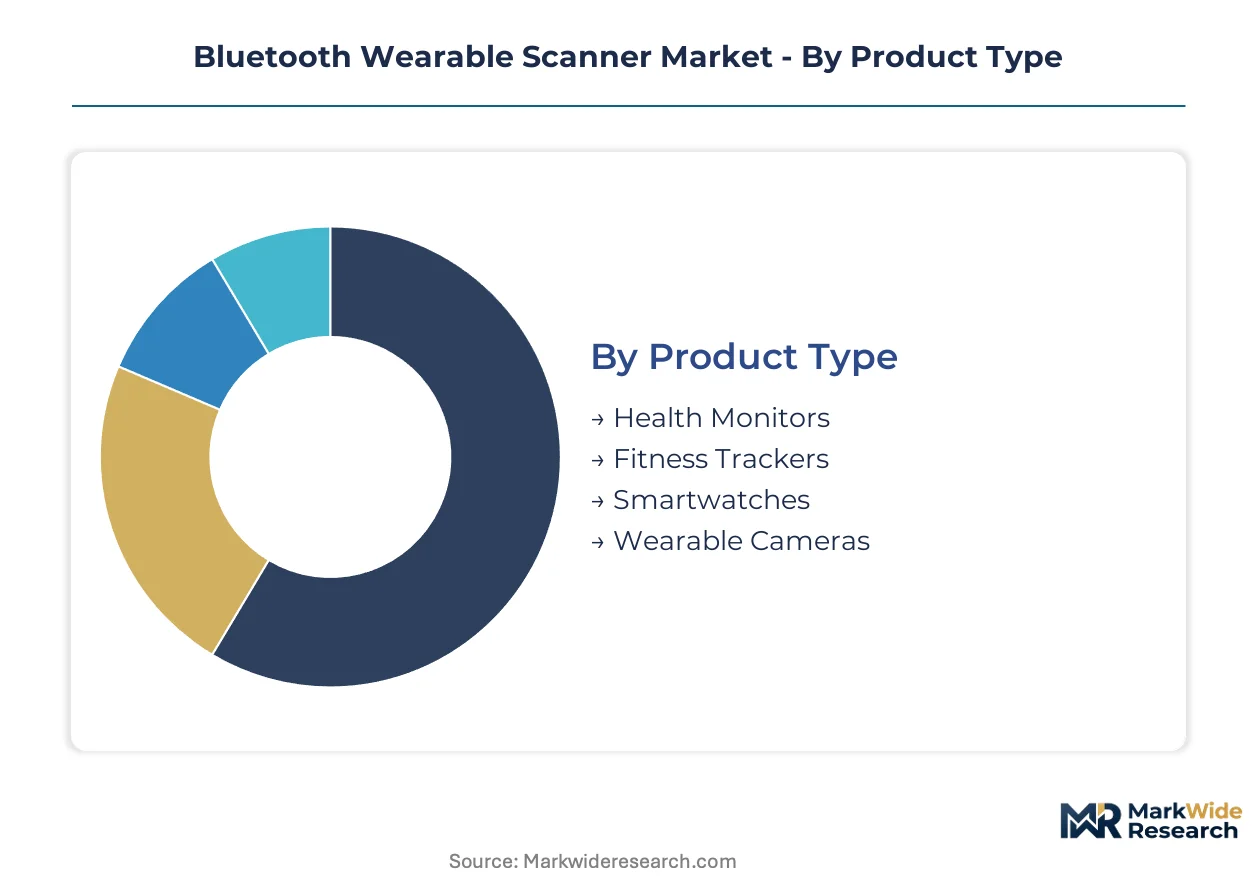
Bluetooth wearable scanner segmentation reveals divergent hardware requirements across clinical precision workflows and industrial throughput environments. Form factor durability, wireless protocol selection, and application-specific certification tiers fragment procurement criteria across buyer categories.
Product Type:
Mature ring-mounted imagers coexist with emerging glove-integrated platforms as warehouse operators pilot next-generation ergonomic configurations.
- Smartwatches:These wrist-worn units integrate 2D imager modules with touchscreen interfaces and rechargeable lithium cells rated for eight-hour shifts. Demand concentrates in German hospital systems deploying bedside medication verification workflows driven by EU Medical Device Regulation compliance requirements. Smartwatches carry premium average selling prices but face extended clinical validation timelines before procurement authorization.
- Health Monitors:Compact body-worn devices combining biometric sensors with barcode capture capability for patient identification and specimen tracking. United States healthcare networks are standardizing on these units for emergency department triage protocols where simultaneous vital sign monitoring and wristband scanning accelerates admission throughput.
- Fitness Trackers:Lightweight consumer-grade hardware with basic linear imager functionality for recreational inventory applications and personal asset management.
- Wearable Cameras:Head-mounted or chest-worn units with integrated optical character recognition and barcode decoding for hands-free documentation in quality assurance workflows.
Ring-mounted form factors handle the majority of throughput; smartwatches are climbing the fastest on share as clinical validation pathways mature.
End User:
Procurement authority concentrates with enterprise IT departments in logistics verticals while clinical buyers prioritize biocompatibility certification tiers.
- Industrial Workers:Warehouse associates and distribution center operators utilizing ring-mounted or glove-integrated scanners for continuous picking workflows. United States third-party logistics providers are mandating these deployments to achieve sub-two-hour order fulfillment commitments in e-commerce networks.
- Healthcare Providers:Nurses, laboratory technicians, and pharmacy staff employing wrist-worn or finger-mounted devices for medication administration and specimen chain-of-custody tracking. German hospital systems are piloting glove-mounted configurations for sterile field compatibility.
- Retail Staff:Floor associates and backroom inventory clerks replacing tethered handheld guns with wearable alternatives for shelf replenishment and cycle counting.
- Fitness Enthusiasts:Individual consumers utilizing basic wearable scanners for personal library management and home organization applications.
Industrial workers generate the highest shipment volumes; healthcare providers are expanding most quickly as clinical procurement frameworks standardize.
Connectivity:
Protocol selection hinges on power-performance tradeoffs and existing infrastructure compatibility across deployment environments.
- Bluetooth Low Energy:Dominant wireless standard enabling continuous eight-hour operation on single-cell configurations without recharge cycles. North American warehouse operators are standardizing on BLE 5.0 and 5.2 implementations for multi-shift coverage across automated fulfillment centers.
- Wi-Fi:Direct-to-enterprise network connectivity bypassing host device pairing for real-time data synchronization in high-density scanning environments. United States distribution networks favor Wi-Fi for centralized fleet management and over-the-air firmware updates.
- NFC:Short-range contactless protocols for tap-to-pair initialization and secure credential exchange in healthcare authentication workflows.
- Zigbee:Mesh networking capability for facility-wide sensor integration in smart warehouse deployments requiring environmental monitoring alongside barcode capture.
Bluetooth Low Energy anchors the installed base; Wi-Fi is gaining share fastest among large-scale enterprise refresh cycles.
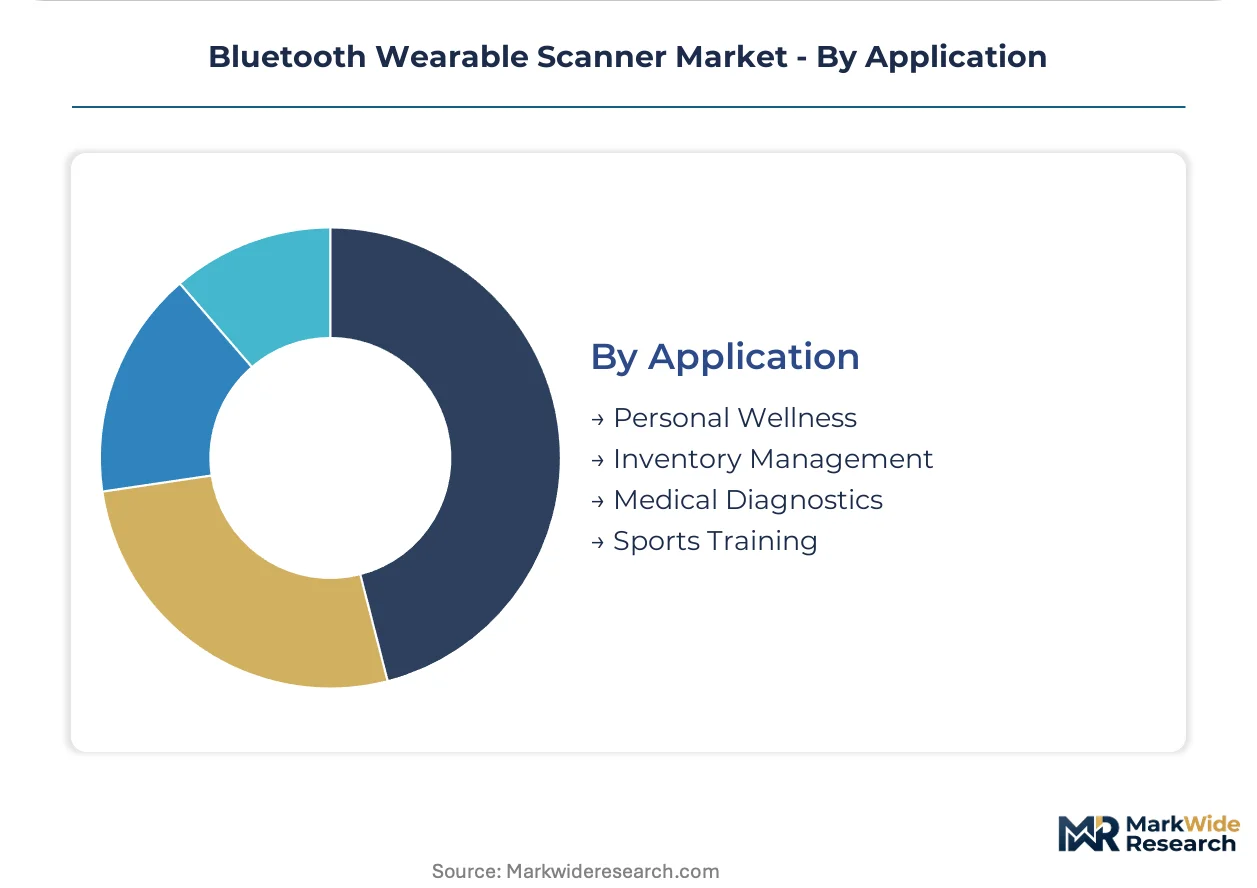
Application:
Volume concentration sits with logistics automation while regulatory tailwinds accelerate clinical adoption curves.
- Inventory Management:Order picking, cycle counting, and shipping verification workflows in warehouse and distribution environments. E-commerce fulfillment centers across the United States and Germany are replacing handheld scanners with wearable alternatives to free both hands for package handling and reduce repetitive strain injuries.
- Medical Diagnostics:Specimen collection tracking, blood product verification, and point-of-care test result association. Hospital systems are deploying these workflows to satisfy Joint Commission patient safety mandates and reduce laboratory specimen misidentification rates.
- Personal Wellness:Individual health monitoring combined with nutritional supplement tracking and medication adherence applications.
- Sports Training:Athletic equipment inventory and performance metric correlation for professional and collegiate program management.
Inventory management commands the dominant share of unit shipments; medical diagnostics represents the steepest expansion trajectory as clinical validation requirements harmonize across jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision imager modules to United States distribution networks, while Chinese component suppliers feed assembly operations across Southeast Asian logistics hubs.
United States
Third-party logistics providers mandate wrist-mounted scanners to achieve sub-two-hour e-commerce fulfillment commitments. FCC emissions regulations govern Bluetooth radio certification for cross-state deployment. Chicago and Dallas-Fort Worth distribution clusters anchor hardware refresh cycles as automated fulfillment centers replace tethered handheld devices.
Germany
Hospital systems pilot glove-mounted scanners for sterile-field medication verification workflows. REACH substance restrictions force imager module solder reformulation and flame retardant elimination. Bavarian industrial automation clusters drive cold-chain warehouse adoption of unified 1D-2D optical engines.
China
MIIT enforces SRRC certification timelines that extend wireless module approval periods for domestic manufacturers. Shenzhen and Dongguan electronics assembly corridors concentrate Bluetooth module production for regional export. Local vendors compete aggressively on price while building service capabilities across Southeast Asian markets.
India
Production Linked Incentive schemes attract component assembly investments for Southeast Asian market penetration. BIS standards govern electronics manufacturing quality certifications. Maharashtra and Karnataka logistics automation projects drive pilot deployments of ring-mounted scanning devices in emerging e-commerce fulfillment networks.
Japan
METI industrial efficiency programs promote wearable automation in precision manufacturing workflows. JIS standards govern electromagnetic compatibility for Bluetooth industrial equipment. Kanto region distribution operators evaluate hybrid imager modules for mixed-symbology inventory management.
Bluetooth Wearable Scanner Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered procurement segments. The vendor base clusters around three strategic archetypes: diversified electronics conglomerates with captive distribution networks, dedicated auto-ID specialists with vertical integration into imager production, and emerging Asian fabricators competing on cost-adjusted value. Consolidation pressures favor players with backward integration into optical engine manufacturing. Geographic expansion and outcome-based service contracting represent the dominant competitive vectors reshaping procurement relationships.
Among diversified technology conglomerates, Honeywell and Epson occupy positions anchored by upstream control over critical component supply. Zebra Technologies exemplifies the auto-ID specialist archetype with established North American enterprise sales infrastructure. UROVO represents the cost-competitive Asian fabricator segment, situating itself within Southeast Asian logistics markets through localized service capabilities.
| Leading Market Players |
|---|
| Honeywell |
| Zebra Technologies |
| Bluebird |
| Unitech |
| Newland |
| UROVO |
| Epson |
| Vuzix |
| Generalscan |
| Others |
Pricing and Supply Chain Analysis
Cylindrical lithium-cell production concentrates among South Korean and Japanese suppliers, anchoring margin capture at the battery module tier while scanner OEMs compete downstream on service bundling and firmware customization. This upstream concentration forces hardware vendors to absorb cell price volatility or push subscription-based procurement models that transfer operational risk to end users.
Pricing Analysis
Bleeding-edge Bluetooth 5.3 implementations command 40-60% premiums over legacy 4.2 configurations, while next-generation ultra-wideband hybrid units are pricing at 2.5x standard ring-mounted scanners in pilot deployments. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service intensity. Cost compression in economy-tier ring scanners is intensifying because Chinese vendors are flooding Southeast Asian logistics markets with unbundled hardware. Third-party logistics providers in the United States show least price sensitivity due to downtime cost exposure, while Indian e-commerce fulfillment startups represent the most margin-constrained buyer segment.
Supply Chain Analysis
Tariff exposure between the United States and China dominates strategic planning for imager module sourcing, forcing vendors to qualify alternative assembly corridors. Component manufacturing concentrates in China, Vietnam, and Mexico, with optical engine fabrication anchored in German precision engineering clusters. Raw material dependencies span rare-earth magnet substrates for vibration motors, sapphire glass for scan windows, and flame-retardant PCB laminates facing REACH reformulation deadlines. Single-source vulnerability persists at the Bluetooth radio chipset tier where Qualcomm and Nordic Semiconductor control premium-tier supply. Distribution runs through certified reseller networks in North America and direct enterprise sales teams in European hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation across clinical validation tiers, regional certification regimes, and procurement model preferences creates specialized entry points for differentiated players. Hospital systems in Germany and the United States are diverging on biocompatibility requirements, splitting what appeared to be a converging global standard.
For Market Incumbents: Pre-empt smartphone substitution in light-use retail by accelerating BLE 5.3 rollout with guaranteed eight-hour shift coverage that consumer devices cannot match. Deepen backward integration into optical engine production to defend margin position against Chinese cost competitors. Secure FCC and CE marking harmonization ahead of SRRC timeline convergence to lock in cross-border procurement contracts with multinational logistics operators. For New Entrants and Emerging Players: Mid-market warehouse operators in India and Southeast Asia represent the most penetrable entry point due to PLI scheme localization incentives and underserviced aftermarket support infrastructure. Glove-mounted scanner configurations for German hospital sterile-field workflows offer premium pricing escape from commodity ring-scanner competition. Partner with established enterprise mobility software vendors to bypass direct channel development costs and embed hardware into existing warehouse management system integrations. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed auto-ID specialists that consolidated regional distribution networks but lack imager module manufacturing capabilities. Five-to-ten-year viability hinges on regulatory harmonization rather than technology disruption, favoring targets with certification engineering depth over pure hardware innovators. Watch FDA breakthrough device designation timelines for wrist-worn medication verification scanners as the inflection signal for clinical market acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Engines | In-house imager production insulates Honeywell and Zebra from Asian module price volatility. |
| Device-as-a-Service Launch | Subscription models shift capital expenditure burden from mid-sized warehouse operators to vendor balance sheets. |
| CE-MDR Dual Certification Pathway | Simultaneous European medical device marking accelerates German hospital procurement authorization timelines. |
| Southeast Asian Service Center Buildout | Localized repair capabilities in Vietnam and Indonesia defend UROVO's price-positioned market share. |
| Hybrid RFID-Barcode Module Introduction | Unified capture engines eliminate separate hardware categories in United States e-commerce fulfillment networks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with warehouse operations directors, hospital biomedical engineering managers, third-party logistics procurement leads, and Bluetooth module hardware architects. Secondary validation drew from FCC equipment authorization databases, EMA medical device registration filings, MIIT SRRC certification bulletins, and customs trade flow records for lithium-cell imports. Bottom-up shipment estimates by form factor and application were triangulated against top-down addressable market calculations derived from e-commerce fulfillment center automation spend disclosures.
Calibration against historical adoption curves for handheld-to-wearable scanner transitions in North American distribution networks anchored the analytical framework. Segmentation dimensions modeled include product type, end-user vertical, connectivity protocol, and application workflow across the projection horizon. CAGRs were computed from installed base replacement cycles and greenfield automation project pipelines rather than extrapolated linear trends. Industry-specific inputs incorporated IATA lithium battery shipping restriction enforcement patterns and EU Medical Device Regulation clinical validation timeline data.
Stress conditions across SRRC approval delays, REACH substance restriction acceleration, and BLE protocol obsolescence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about hospital procurement standardization velocity and warehouse labor cost inflation trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Technology
Europe Watch Market
Wearable Technology
Electronic Underwear Market
Wearable Technology
Smart Pet Wearable Product Market
Wearable Technology
Pet Wearable Market
Wearable Technology
Global Smartwatch Battery Market
Wearable Technology
Smart Necklace Market
Wearable Technology
Kids Smart Watch Market
Wearable Technology
Adult Smartwatch Market
Wearable Technology
Wearable Camera Market
Wearable Technology
Kids Watch Market
Wearable Technology
Wearable Gaming Technology Market
Wearable Technology
Europe Smart Watches Market
Wearable Technology
Asia-Pacific Wearable Technology Market
Wearable Technology
Global Smart Wearable Market
Wearable Technology
Global Smart Wearable Lifestyle Devices Market
Wearable Technology
APAC Smart Watch Market