
 Mobile Phone Accessories Market | 2026-2036
Mobile Phone Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Phone Accessories Market Intelligence
Dongguan's electronics manufacturing belt is pivoting toward higher-margin wireless charging modules and eco-grade silicone formulations. Apple Inc. leverages its proprietary MagSafe ecosystem to control premium attach rates and accessory margins. Anker Innovations Co. Ltd. anchors the mid-market with GaN charger technology and broad Amazon channel presence. Samsung Electronics Co. Ltd. extends its Galaxy ecosystem strategy to bundled cases and earbuds, competing directly with first-party rivals.
Mobile phone accessories comprise protective enclosures, power delivery devices, audio peripherals, and display shields engineered from polymers, elastomers, and conductive composites to extend device lifespan, enhance usability, and enable wireless functionality. Cases and screen protectors dominate unit volume as replacement-cycle hedges against glass-slab fragility, while chargers capture disproportionate margin pools as GaN and Qi2 architectures displace legacy silicon. Earbuds represent the fastest-expanding category as Bluetooth LE Audio and Auracast broadcast protocols redefine personal audio attachment rates.
The EU's common charger directive under ECHA and REACH substance restrictions compel redesigns of cable assemblies and port configurations, while the FCC in the United States governs RF emissions for wireless charging pads and Bluetooth accessories. China's SAMR enforces GB standards for lithium-ion safety in power banks, constraining import eligibility for uncertified suppliers. Stakeholders must monitor regulatory divergence between interoperability mandates and material compliance to avoid SKU fragmentation and market access delays.
Market Dynamics
Qi2 magnetic alignment and USB-C standardization are compressing legacy connector architectures while forcing portfolio rationalization across Dongguan manufacturing clusters.
Growth Catalysts
- Eu's Common Charger Directive:Mandates universal USB-C ports across all mobile devices by 2024, eliminating proprietary cable fragmentation and standardizing accessory compatibility.
- GaN Semiconductor Adoption:Gallium nitride power ICs enable 40% smaller charger footprints and higher wattage density, driving replacement cycles in premium power delivery segments.
- India:Domestic manufacturing incentives under PLI schemes attract assembly operations for cases and cables, reducing import dependency and expanding local supplier ecosystems.
Market Restraints
- Silicone and Lithium Price Volatility:Raw material cost swings for eco-grade elastomers and battery cells compress margin predictability in power banks and protective cases.
- Dongguan Supplier Concentration:Over 60% of global cable and case production clusters in Guangdong province, creating geographic vulnerability to regional logistics disruptions or energy rationing.
- Qi1 Legacy Interoperability Gaps:Inconsistent coil alignment tolerances in first-generation wireless charging pads limit charging efficiency and frustrate cross-brand compatibility.
Strategic Opportunities
- Auracast Broadcast Audio:Bluetooth LE Audio public broadcast protocols enable assistive listening and venue audio streaming, opening institutional sales channels beyond consumer retail.
- Modular Repairable Design Mandates:France's repairability index requirements incentivize detachable case architectures and swappable battery accessories with documented disassembly scores.
- Direct-to-Consumer Subscription Bundling:Recurring case-and-screen-protector replacement programs bypass Amazon marketplace fees and capture lifetime value through warranty-integrated logistics.
Industry Challenges
- RF Emissions Certification Timelines:FCC Part 15 testing for wireless charging pads and Bluetooth accessories extends product launch windows by 8-14 weeks, delaying seasonal inventory positioning.
- Cross-Platform Magnetic Standard Fragmentation:Apple MagSafe, Qi2, and proprietary Android magnetic ring configurations force SKU multiplication and inventory hedging across incompatible ecosystem attachments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Phone Accessories Market |
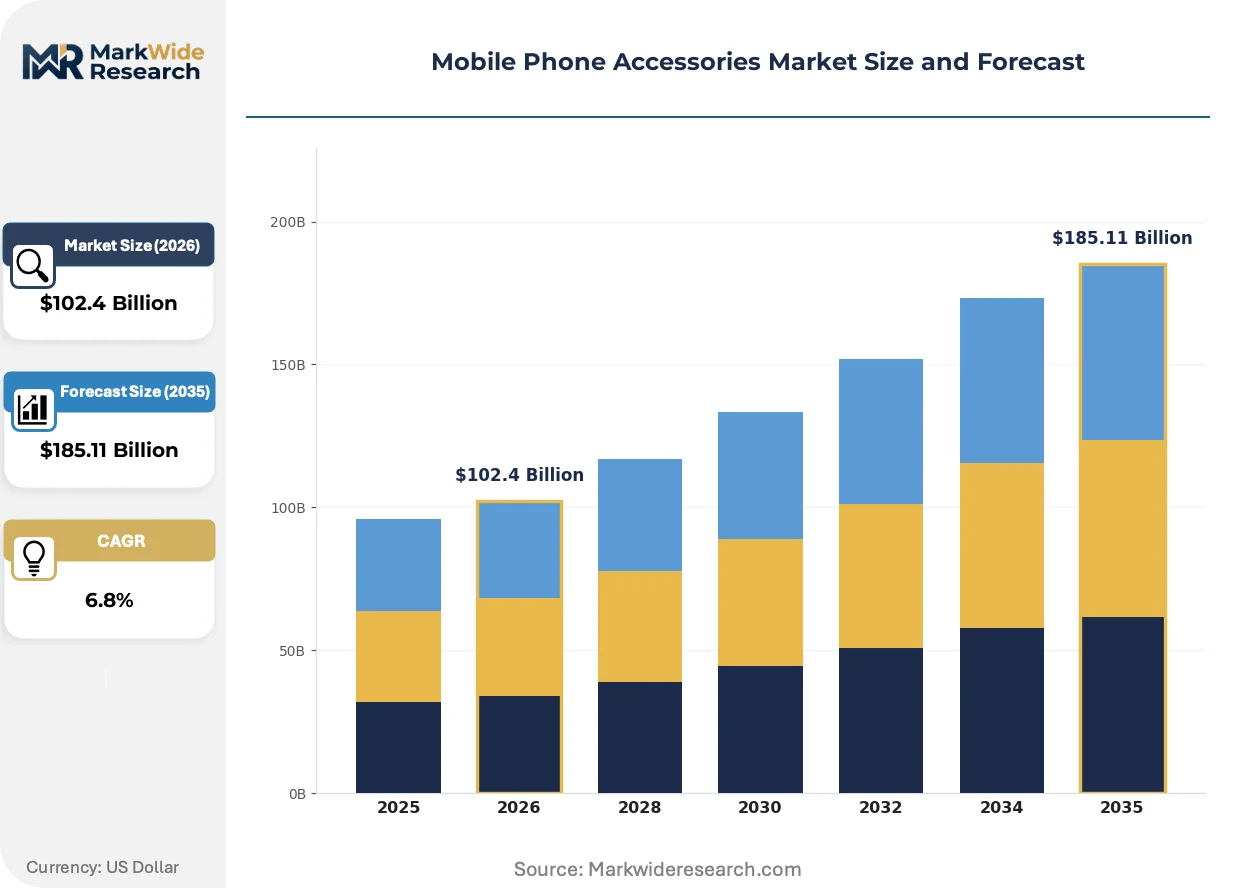
| Market Size in 2026 | $102.4 Billion |
| Market Size in 2035 | $185.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cases, Chargers, Screen Protectors, Earbuds Material: Plastic, Leather, Silicone, Metal Installation: DIY, Professional, Magnetic, Adhesive Customer Type: Retail Consumers, Businesses, Educators, Resellers |
| Companies Covered | Belkin International Inc., Spigen Inc., Apple Inc., Harman International, Logitech International S.A., Samsung Electronics Co. Ltd., OtterBox, ZAGG Inc., Anker Innovations Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Phone Accessories Market Strategic Shifts & Innovations
Accessory architectures are pivoting from passive protection to active power management and audio processing, embedding semiconductor intelligence into formerly commoditized enclosures.
Gallium nitride power stages are expanding into mid-tier charger SKUs previously dominated by silicon MOSFET designs. Third-party brands now source 65W and 100W GaN modules from Navitas and Infineon at volumes matching premium laptop adapter production. This semiconductor migration compresses physical charger volumes by half while enabling multi-port configurations that cannibalize single-device legacy SKUs.
REACH substance restrictions and ECHA candidate list updates are forcing reformulation of PVC cable jackets and phthalate-laden TPU cases. Suppliers in Zhejiang and Jiangsu provinces now certify halogen-free TPE compounds to maintain EU market access. The regulatory pressure accelerates bio-based polymer pilot programs using castor oil-derived polyamides for premium case lines.
Retail buyers now prioritize MFi and Qi2 certification badges over raw price points in procurement decisions. Amazon's marketplace algorithm surfaces certified listings higher, displacing uncertified white-label sellers from search results. This preference shift concentrates volume with suppliers maintaining active certification retainer contracts with Apple and WPC, particularly visible in North American and Western European e-commerce channels.
Mobile Phone Accessories Market Segmentation
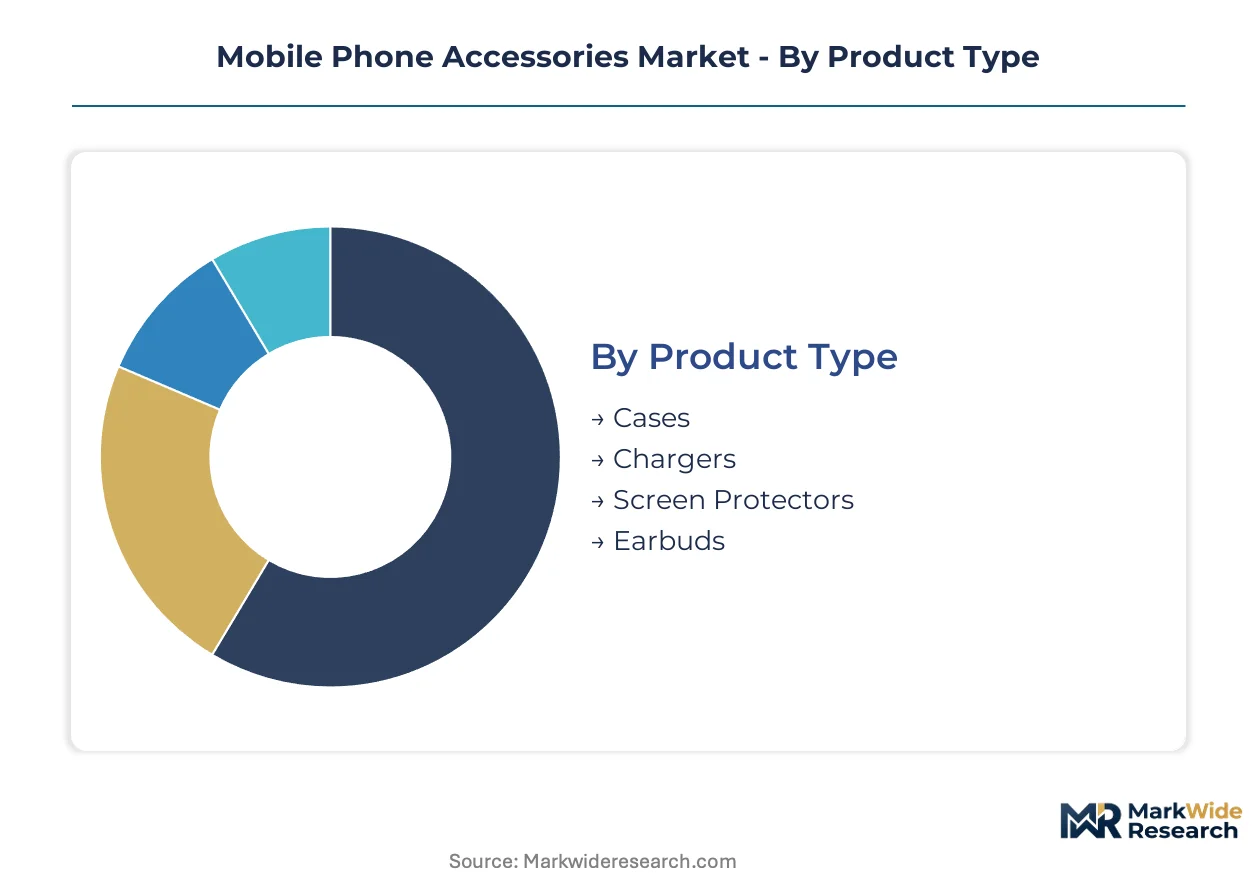
Mobile phone accessories segment along four intersecting dimensions that determine manufacturing location, margin capture, and channel strategy. Product type and material composition drive supply chain configuration, while installation method and customer type dictate pricing architecture and go-to-market investments.
Product Type:
Supply concentrates in Dongguan and Shenzhen clusters for cases and chargers, with earbuds shifting toward Vietnam and India under tariff diversification.
- Cases:Polycarbonate, TPU, and leather-wrapped enclosures engineered for drop protection and MagSafe/Qi2 magnetic compatibility. Volume concentrates in China and India as smartphone replacement-cycle hedges against glass-slab fragility, with GaN and wireless charging module integration now penetrating premium tiers.
- Chargers:GaN semiconductor power delivery devices ranging from 20W single-port to 140W multi-port configurations. Demand clusters in North America and Western Europe as USB-C standardization and higher wattage density drive replacement cycles, with Navitas and Infineon silicon displacing legacy MOSFET architectures.
- Screen Protectors:Tempered glass and TPU film layers with oleophobic coatings.
- Earbuds:Bluetooth LE Audio peripherals with Auracast broadcast capability.
Today's leader: Chargers. Tomorrow's challenger: Earbuds.
Material:
Cost tier stratification runs from commodity plastics through premium leather, with regulatory pressure on halogen-free formulations reshaping supplier qualification.
- Plastic:Polycarbonate and ABS shells dominating unit economics in entry-level SKUs, with recycled-content variants gaining procurement share under EU Green Deal sourcing mandates.
- Silicone:Eco-grade elastomer formulations certified to REACH substance restrictions, produced in Zhejiang and Jiangsu for EU market access.
- Leather:Genuine and PU leather wraps commanding premium positioning.
- Metal:Aluminum and stainless steel structural elements.
Silicone holds volume leadership. Bio-based polyamides from castor oil derivatives represent the steepest expansion trajectory.
Installation:
Application context determines margin structure, with professional installation capturing service attach rates in enterprise channels.
- DIY:Consumer-applied cases and screen protectors with alignment tooling.
- Magnetic:Qi2 and MagSafe ring architectures enabling snap-fit attachment.
- Professional:Retail technician-applied screen protection and case fitting.
- Adhesive:Film-based protectors requiring precision application.
Magnetic attachment dominates design roadmaps. Professional installation is climbing fastest in B2B fleet deployments.
Customer Type:
Volume distributes across consumer retail and institutional procurement with divergent certification and logistics requirements.
- Retail Consumers:Individual purchasers through Amazon, direct-to-consumer subscription programs, and carrier retail.
- Businesses:Corporate fleet procurement with standardized case and charger specifications.
- Educators:K-12 and higher education volume purchasing with durability and repairability priorities.
- Resellers:White-label and private-label distributors sourcing from Dongguan manufacturing clusters.
Retail consumers anchor current revenue. Businesses are gaining share fastest through Auracast broadcast audio deployments and modular repairable design mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands manufacturing density for cables and cases while the United States drives premium charger replacement cycles through USB-C standardization mandates. India and Germany concentrate distinct regulatory pressures and industrial policy incentives that reshape supplier qualification requirements.
China
Dongguan and Shenzhen clusters produce over sixty percent of global cable and enclosure volumes as smartphone penetration sustains replacement-cycle hedging. SAMR enforces GB standards for lithium-ion safety in power banks, constraining uncertified export eligibility. Zhejiang and Jiangsu provinces now certify halogen-free TPE compounds under REACH substance restrictions to maintain EU market access.
United States
Retail consumers prioritize MFi and Qi2 certification badges over raw price points in procurement decisions across Amazon and carrier channels. FCC Part 15 testing for wireless charging pads and Bluetooth accessories extends product launch windows by eight to fourteen weeks. GaN semiconductor adoption concentrates in North American premium segments as Navitas and Infineon silicon displaces legacy MOSFET architectures.
India
Domestic manufacturing incentives under PLI schemes attract assembly operations for cases and cables, reducing import dependency from Guangdong suppliers. BIS certification requirements for electronics imports create compliance barriers for uncertified white-label sellers. Tamil Nadu and Karnataka states host expanding supplier ecosystems serving both local consumption and re-export markets.
Germany
EU Green Deal sourcing mandates accelerate procurement share for recycled-content plastic variants in entry-level SKUs. ECHA candidate list updates force reformulation of PVC cable jackets and phthalate-laden TPU cases. Bavaria-based distributors concentrate volume for premium leather-wrapped enclosures and GaN charger modules across Western European e-commerce channels.
South Korea
Bluetooth LE Audio and Auracast broadcast protocols redefine personal audio attachment rates as earbuds represent the fastest-expanding category. MFDS coordinates with international standards bodies on RF emissions harmonization for wireless charging interoperability. Seoul Capital Area electronics distributors anchor regional procurement for magnetic attachment architectures compatible with Qi2 and proprietary ecosystem specifications.
Mobile Phone Accessories Market Key Industry Players
Dongguan producers anchor one tier; Cupertino and Seoul specialists hold premium ecosystem control through proprietary magnetic standards and certification gatekeeping. The vendor base stratifies across three tiers: first-party device manufacturers capturing attach-rate economics, third-party certified specialists commanding Amazon algorithm preference, and white-label assemblers competing on cost without interoperability badges. Strategic moves concentrate on portfolio rationalization around Qi2 and USB-C architectures, plus direct-to-consumer subscription bundling to bypass marketplace fees.
Within the first-party ecosystem tier, Apple Inc. and Samsung Electronics Co. Ltd. exemplify proprietary magnetic standard strategies that force SKU multiplication across incompatible attachment configurations. Anker Innovations Co. Ltd. occupies the certified third-party position where GaN technology and active certification retainer contracts with Apple and WPC concentrate volume. Among case and protection specialists, OtterBox and Spigen Inc. sit within the durability-focused archetype serving replacement-cycle hedging demand.
| Leading Market Players |
|---|
| Belkin International Inc. |
| Spigen Inc. |
| Apple Inc. |
| Harman International |
| Logitech International S.A. |
| Samsung Electronics Co. Ltd. |
| OtterBox |
| ZAGG Inc. |
| Anker Innovations Co. Ltd. |
| Others |
Cost & Logistics Intelligence
GaN semiconductor migration into mid-tier charger production compresses unit economics while concentrating procurement leverage among certified module suppliers. Dongguan manufacturing clusters now face margin bifurcation between MFi-retainer contract holders and uncertified assemblers competing on spot-market silicon.
Pricing Analysis
Capacity additions in Vietnam and India are reshaping price floors for cases and cables as PLI-subsidized assembly displaces Guangdong-origin imports. Three-tier pricing structure across premium, standard, and economy levels separates MFi-certified SKUs from Qi2-badge holders from uncertified white-label alternatives. Price differentiation hinges on certification tier and volume scale, with Amazon algorithm preference concentrating procurement among badge-holding suppliers. Pricing pressure stems from silicone and lithium raw material volatility compressing margin predictability in power banks and eco-grade enclosures. Retail consumers exhibit highest price sensitivity in entry-level SKUs, while corporate fleet buyers prioritize durability ratings and repairability scores over unit cost.
Supply Chain Analysis
Certification retainer contracts with Apple and WPC now gate supplier eligibility for North American and Western European volume. Manufacturing concentrates in China, Vietnam, and India as tariff diversification and domestic content incentives reshape assembly geography. Raw material dependencies span gallium nitride wafers from Navitas and Infineon, halogen-free TPE compounds from Zhejiang and Jiangsu, and lithium-ion cells from CATL and BYD supply chains. Single-source vulnerability concentrates in Dongguan cable and case production clusters exposed to regional energy rationing or logistics disruption. Distribution runs through Amazon marketplace algorithms, direct-to-consumer subscription platforms, and carrier retail channels with divergent certification and logistics requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GaN cost-down curves and Qi2 premium-tier adoption create margin-expansion headroom for suppliers maintaining active certification contracts. Portfolio rationalization around USB-C and magnetic alignment standards separates viable participants from commoditized assemblers.
For Market Incumbents: Anchor certification investments as defensive moats against uncertified entrants flooding Amazon with non-Qi2 SKUs. Deepen backward integration into GaN module sourcing from Navitas and Infineon to defend charger margin structure. Prioritize direct-to-consumer subscription bundling to bypass marketplace fee compression and capture replacement-cycle lifetime value through warranty-integrated logistics. For New Entrants and Emerging Players: Corporate fleet buyers represent underserved procurement archetypes with standardized durability specifications and repairability index requirements. Auracast-enabled assistive listening deployments in education and venue audio open institutional sales channels beyond saturated consumer retail. Target B2B fleet procurement with modular case architectures scoring above threshold on France's repairability index documentation. For Investors and Strategic Acquirers: Valuations sit cheapest among white-label assemblers lacking MFi or Qi2 certification retainers but possessing Dongguan manufacturing infrastructure convertible to certified production. Long-term viability favors suppliers with backward integration into GaN semiconductor sourcing and active WPC algorithm preference contracts. Monitor USB-C mandate enforcement velocity and Qi2 adoption rates in North American Amazon search rankings as inflection indicators for certification-badge value capture.| Strategic Initiative | Industry Significance |
|---|---|
| Qi2 Certification Investment | Amazon algorithm preference concentrates volume with WPC retainer contract holders displacing uncertified listings. |
| GaN Module Backward Integration | Navitas and Infineon silicon sourcing secures cost position as 65W and 100W configurations cannibalize legacy SKUs. |
| Direct-to-Consumer Subscription Launch | Recurring case-and-protector programs bypass marketplace fees and capture replacement-cycle lifetime value. |
| Repairability Index Documentation | France's modular design mandates open corporate fleet procurement to suppliers scoring above threshold on disassembly metrics. |
| Auracast Audio Capability Integration | Bluetooth LE Audio broadcast protocols enable institutional sales channels in education and venue assistive listening deployments. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window combining primary fieldwork with secondary validation. Primary sources included accessory product managers at first-party OEMs, procurement leads at Amazon marketplace sellers, certification directors at WPC and MFi program administrators, and Dongguan manufacturing cluster operations heads. Secondary data drew from FCC Part 15 equipment authorization databases, ECHA REACH substance restriction updates, SAMR GB standard filings, and Amazon search ranking algorithm documentation. Bottom-up SKU-level volume builds triangulated against top-down category spend estimates from retail audit channels.
Historical reference periods anchored growth rate derivation to pre-USB-C mandate baseline and post-Qi2 launch inflection windows across the modeling period. Segmentation dimensions modeled include product type, material composition, installation method, and customer archetype with cross-cutting geographic regulatory cluster overlays. CAGRs reflect unit shipment trajectories weighted by average selling price migration from silicon to GaN architectures and from adhesive to magnetic attachment mechanisms. Forecast inputs incorporated PLI scheme uptake rates in India and EU Green Deal recycled-content procurement mandates.
Underlying measurement precision varies by segment; charger and earbud categories carry tighter precision than case and screen protector volumes given certification database granularity. Forecasts reflect documented assumptions on USB-C enforcement timelines and Qi2 adoption velocity subject to revision upon regulatory delay or magnetic standard fragmentation persistence. A model refresh is warranted upon material change in Amazon algorithm certification-badge weighting or Dongguan cluster logistics disruption severity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
North America Gaming Accessories Market
Consumer Electronics
Mexico Smart TV Market
Consumer Electronics
Sports Electronics Market
Consumer Electronics
Screen Privacy Protectors Market
Consumer Electronics
Waterproof Headphones Market
Consumer Electronics
Speakerphones Market
Consumer Electronics
Consumer Electronics Repair and Maintenance Market
Consumer Electronics
US Refurbished and Used Mobile Phones Market
Consumer Electronics
Refurbished Electronics Market
Consumer Electronics
Global Used Smartphones Market
Consumer Electronics
PC Accessories Market
Consumer Electronics
Smart Aquarium Devices Market
Consumer Electronics
LAMEA Refurbished and Used Mobile Phones Market
Consumer Electronics
Smartphone Sanitizer Market
Consumer Electronics
Middle East and Africa Refurbished and Used Mobile Phones Market
Consumer Electronics
Gun Care Products Market