
 Learning Remote Controls Market | 2026-2036
Learning Remote Controls Market Size, Share, and Industry Trends Forecast 2026-2036
Learning Remote Controls Market Analytics
Silicone rubber keypad assemblies are expanding their share over traditional thermoplastic elastomer interfaces in mid-tier learning remotes due to superior tactile durability and lower per-unit molding costs. Logitech leverages its Swiss hardware engineering heritage to sustain premium positioning in programmable universal remotes with cloud-based code databases. Universal Electronics Inc. anchors North American OEM supply relationships through its QuickSet platform, while Sony Corporation differentiates via proprietary infrared learning algorithms embedded in Bravia-compatible controllers.
Learning remote controls are handheld human interface devices that capture, store, and replicate infrared or radio-frequency command sequences from original equipment remotes, typically employing EEPROM memory banks, multi-protocol transceivers, and capacitive or membrane input surfaces to enable single-device operation of heterogeneous consumer electronics ecosystems. Their primary commercial purpose is to reduce device clutter and simplify user interaction in multi-component entertainment and automation installations. Smart remotes command the widest margin pools as voice-assistant integration and touchscreen interfaces justify price premiums over basic infrared learning units. Wi-Fi-enabled models represent the fastest-expanding technology segment as over-the-air firmware updates and cloud-based device libraries extend functional longevity beyond traditional code-learning architectures. Residential end users still occupy the largest volume share, though hospitality procurement is shifting toward centralized property management system integration.
The Federal Communications Commission governs RF spectrum allocation for learning remotes operating in the 2.4 GHz band, while the EU Radio Equipment Directive mandates interoperability testing and CE marking for all wireless control devices sold in member states. The EPA's Energy Star specifications for consumer electronics indirectly shape remote control standby power thresholds, pushing manufacturers toward Bluetooth Low Energy and wake-on-radio architectures. Stakeholders must monitor evolving smart home protocol fragmentation as Matter, Zigbee, and proprietary mesh networks compete for integration priority in next-generation learning remote firmware roadmaps.
Market Dynamics
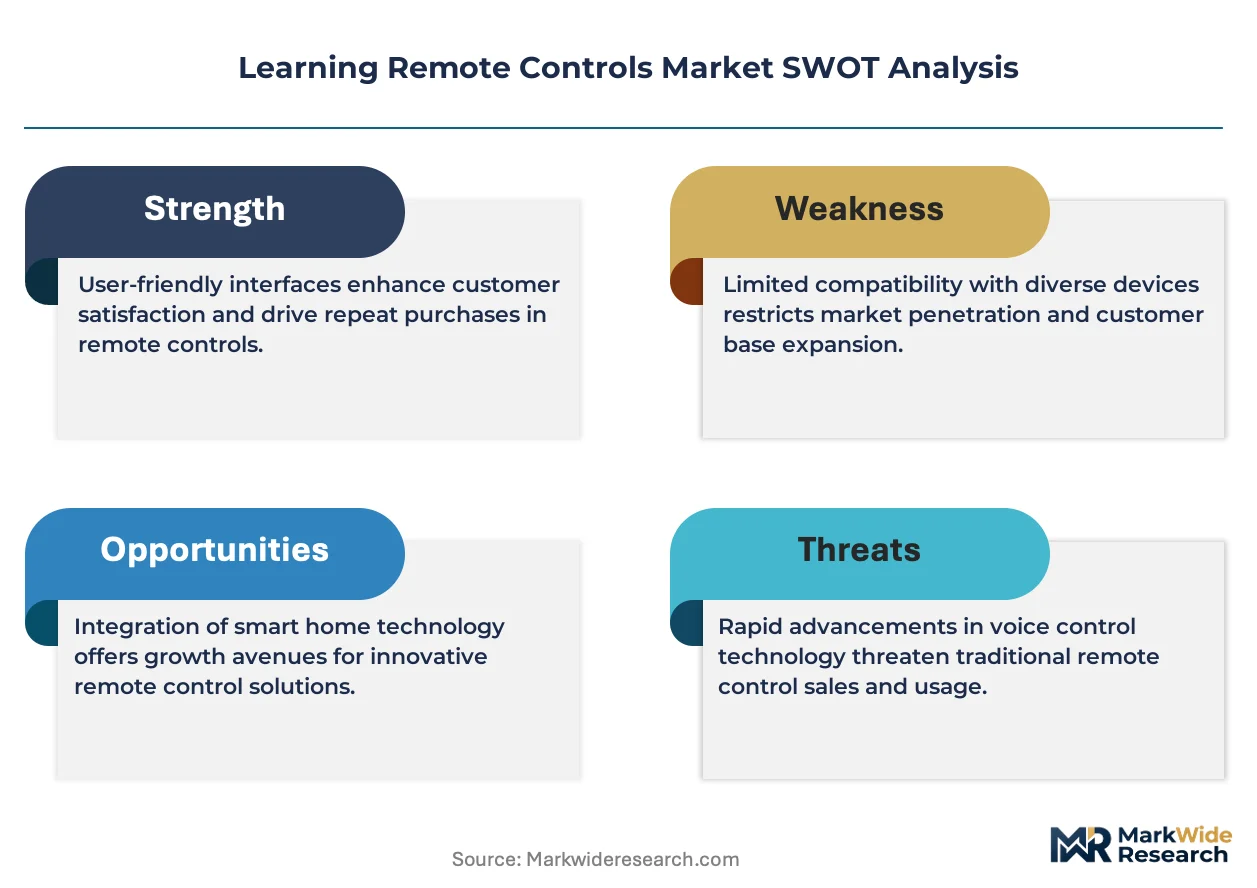
The learning remote controls market is experiencing structural pressure from protocol fragmentation as Matter, Zigbee, and proprietary mesh networks compete for integration priority in next-generation firmware architectures. This technological divergence is forcing manufacturers to place larger bets on which connectivity standard will dominate whole-home automation ecosystems.
Growth Catalysts
- Smart home integrators:Whole-home automation becoming standard in new construction is pulling demand from professional installation channels that specify programmable universal remotes as standard equipment in premium residential projects.
- EU Ecodesign Directive:Regulatory pressure to reduce standby power consumption in connected devices is accelerating adoption of Bluetooth Low Energy and wake-on-radio architectures that extend battery life.
- Silicone rubber keypads:Superior tactile durability and lower per-unit molding costs versus thermoplastic elastomer interfaces are expanding share in mid-tier remote manufacturing.
Market Restraints
- Semiconductor supply concentration:RF transceiver and EEPROM memory chip sourcing remains concentrated among a limited supplier base in East Asian foundries, creating vulnerability to capacity constraints.
- Protocol incompatibility:Technical limitations in cross-platform signal learning between infrared legacy devices and radio-frequency smart home endpoints restrict functional universality.
- Substitution by voice control:Smart speaker and display integration directly into televisions and streaming devices threatens standalone remote utility in price-sensitive segments.
Strategic Opportunities
- Hospitality procurement centralization:Property management system integration is opening white space in hotel and serviced apartment chains seeking unified control platforms across room categories.
- Over-the-air firmware architecture:Wi-Fi-enabled models with cloud-based device libraries represent an emerging application layer that extends functional longevity beyond traditional code-learning architectures.
- German retail density:Strong consumer electronics retail presence combined with Bauhaus-inspired design preferences creates favorable conditions for premium learning remote positioning in European markets.
Industry Challenges
- Firmware engineering talent scarcity:Shortage of developers skilled in multi-protocol transceiver integration and low-power embedded systems design is constraining product roadmap velocity.
- CE marking timeline compression:EU Radio Equipment Directive interoperability testing requirements are extending certification cycles for wireless control devices entering member states.
- Legacy infrared integration:Maintaining backward compatibility with aging consumer electronics inventories while advancing RF-native architectures adds hardware cost and complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Learning Remote Controls Market |
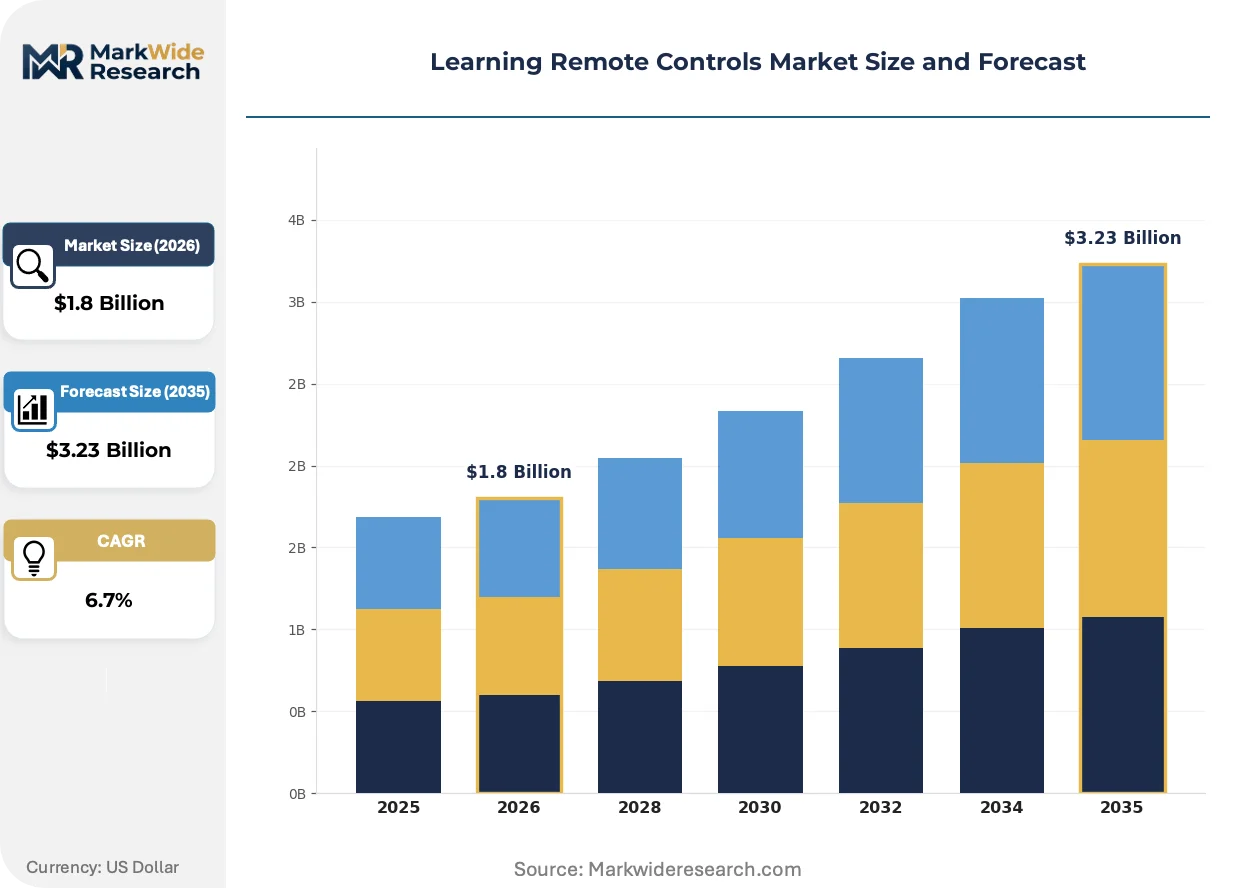
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Universal Remotes, Smart Remotes, Learning Remotes, Keypad Remotes End User: Residential, Commercial, Hotels, Educational Institutions Technology: Infrared, Bluetooth, Wi-Fi, RF Application: Television, Home Theater Systems, Smart Homes, Gaming Consoles |
| Companies Covered | Logitech, Universal Electronics Inc., Sony Corporation, Samsung Electronics, LG Electronics, Panasonic, Crestron, AMX, RTI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Learning Remote Controls Market Evolving Landscape
Touchscreen interfaces and voice-assistant integration are actively reshaping competitive positioning in learning remotes, justifying price premiums that basic infrared units cannot command. This interface evolution is compressing the addressable market for membrane-keypad designs while expanding margin pools for programmable platforms.
Silicone rubber keypad assemblies are expanding into mid-tier learning remotes as manufacturers seek superior tactile durability and lower per-unit molding costs versus thermoplastic elastomer alternatives. Hospitality procurement teams and smart home integrators are adopting these interfaces at accelerating pace for high-touch environments. This material shift is enabling cost structure compression that supports competitive positioning against voice-native control alternatives.
The EPA's Energy Star specifications for consumer electronics are indirectly shaping remote control standby power thresholds, pushing manufacturers toward Bluetooth Low Energy and wake-on-radio architectures. Industrial consequence includes accelerated R&D allocation away from always-on infrared receivers toward event-driven radio activation. North American OEM supply relationships are most affected, with vendors reconfiguring power management firmware to meet indirect regulatory pressure.
Buyer concentration among smart home integrators is compressing traditional retail distribution for learning remotes in premium residential segments. Professional installation channels are displacing big-box electronics retail as the primary specification path for whole-home automation projects. This channel rotation is most visible in Germany, where Bauhaus-inspired minimalist hardware design preferences align with integrator-specified premium positioning.
Learning Remote Controls Market Segmentation
Learning remote controls fragment across four distinct dimensions that shape procurement patterns and margin structures. Product architecture determines whether manufacturers compete on hardware durability or software extensibility. End-use concentration and technology selection further stratify vendor positioning across professional installation versus retail channels.
Product Type:
The customization-standardization spectrum runs from fully programmable platforms with cloud-based code libraries to fixed-function hardware with pre-mapped command sets.
- Smart Remotes:Voice-assistant integration and touchscreen interfaces define these programmable platforms, with demand concentrating among smart home integrators specifying whole-home automation in premium residential projects across Germany. The EPA's Energy Star standby power thresholds push manufacturers toward Bluetooth Low Energy architectures.
- Universal Remotes:Multi-device infrared code databases enable single-remote operation of heterogeneous consumer electronics ecosystems. Hospitality procurement teams in hotel chains favor these for standardized room deployments where property management system integration reduces front-desk support burden.
- Learning Remotes:EEPROM memory banks capture and replicate command sequences from original equipment remotes without cloud dependency. Residential end users in price-sensitive segments select these for legacy device compatibility.
- Keypad Remotes:Silicone rubber membrane interfaces deliver tactile durability at lower per-unit molding costs than thermoplastic elastomer alternatives. Mid-tier manufacturers source these for high-touch commercial environments.
Leading the category by volume: Universal Remotes. Growing fastest: Smart Remotes.
End User:
Volume concentration shifts from individual consumers toward institutional procurement with centralized specification authority and recurring replacement schedules.
- Residential:Individual consumers purchasing through retail channels or smart home integrators. German retail density supports premium positioning for Bauhaus-inspired minimalist hardware designs.
- Hotels:Property management system integration requirements drive demand for unified control platforms across room categories. Chains specify Wi-Fi-enabled models with over-the-air firmware update capability.
- Commercial:Corporate installations in conference facilities and executive suites require programmable universal remotes compatible with heterogeneous meeting room electronics.
- Educational Institutions:K-12 and university AV departments prioritize durability and theft resistance over advanced feature sets, favoring keypad remotes with physical button feedback.
Dominant by procurement volume: Residential. Expanding most quickly: Hotels.
Technology:
Power architecture and protocol selection determine battery life, interoperability range, and regulatory compliance burden across regional markets.
- Wi-Fi:Cloud-based device libraries and over-the-air firmware updates extend functional longevity beyond traditional code-learning architectures. The FCC governs 2.4 GHz spectrum allocation for these models in the United States.
- Bluetooth:Low-energy variants satisfy EU Ecodesign Directive standby power requirements while enabling direct pairing with smartphones and tablets for configuration.
- Infrared:Legacy compatibility with aging consumer electronics inventories maintains relevance despite RF-native architecture advancement. Adds hardware cost for dual-protocol transceivers.
- RF:Radio-frequency protocols including proprietary mesh networks compete with Matter and Zigbee for integration priority in next-generation firmware roadmaps.
Widest installed base: Infrared. Steepest expansion trajectory: Wi-Fi.
Application:
Use-case complexity ranges from single-device television control to multi-zone automation orchestrating lighting, climate, and entertainment systems.
- Smart Homes:Whole-home automation installations require programmable platforms with multi-protocol transceiver integration. Matter protocol fragmentation forces manufacturers toward larger standardization bets.
- Home Theater Systems:Multi-component entertainment installations demand infrared learning capability for legacy AV receivers and disc players alongside RF control for streaming devices.
- Television:Basic volume and channel navigation represents the most price-commoditized segment, threatened by voice control substitution in smart displays.
- Gaming Consoles:Low-latency Bluetooth pairing requirements and specialized button mapping distinguish this niche from general entertainment control.
Highest unit volume: Television. Gaining share fastest: Smart Homes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Dongguan concentrate contract manufacturing capacity for learning remote electronics, drawing component suppliers into clustered logistics corridors that reduce per-unit assembly costs.
United States
Smart home integrators in California and Texas drive specification demand for programmable universal remotes in premium residential construction. The FCC governs 2.4 GHz spectrum allocation for Wi-Fi-enabled models, creating compliance checkpoints for firmware architectures. Greater Boston hosts AV control engineering clusters where hospitality procurement teams source property management system integrations.
Germany
Bauhaus-inspired minimalist hardware design preferences concentrate demand for premium learning remotes in Berlin and Munich retail channels. The EU Ecodesign Directive mandates standby power reductions that accelerate Bluetooth Low Energy adoption. Baden-Württemberg's consumer electronics retail density supports integrator-specified positioning in whole-home automation projects.
China
Shenzhen's special economic zone anchors global contract manufacturing for silicone rubber keypad assemblies and multi-protocol transceiver modules. MIIT standards govern radio equipment certification for domestic market entry. Dongguan molding facilities supply mid-tier manufacturers seeking lower per-unit costs than thermoplastic elastomer alternatives.
Japan
METI efficiency regulations push domestic manufacturers toward wake-on-radio power architectures that extend battery life in learning remotes. Tokyo and Osaka metropolitan areas concentrate smart home integrator demand for voice-assistant-enabled programmable platforms. Nagoya's industrial corridor hosts precision molding suppliers serving premium hardware design requirements.
South Korea
Seoul Capital Area smart apartment developments specify Wi-Fi-enabled learning remotes with over-the-air firmware update capability. MFDS radio equipment standards align with EU interoperability testing frameworks for export-oriented manufacturers. Busan-Ulsan logistics hubs handle component imports for domestic assembly of multi-device infrared code database units.
Learning Remote Controls Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium programmable platforms concentrating among Swiss and Japanese hardware engineering houses while mid-tier volume flows through Shenzhen assembly networks. The vendor base organizes into three strategic archetypes: cloud-code-database platforms, OEM supply relationship anchors, and proprietary algorithm developers. Consolidation pressure is building through strategic partnerships between firmware developers and hospitality property management system providers, alongside geographic expansion by German design-led brands into Nordic smart home markets.
Within the premium hardware tier, Logitech and Sony Corporation exemplify engineering heritage positioning, while Universal Electronics Inc. anchors North American OEM supply relationships. These three companies represent distinct competitive vectors: cloud-based code libraries, proprietary infrared learning algorithms, and platform integration partnerships respectively. Each occupies a definable position in the segmentation matrix without overlapping functional claims.
| Leading Market Players |
|---|
| Logitech |
| Universal Electronics Inc. |
| Sony Corporation |
| Samsung Electronics |
| LG Electronics |
| Panasonic |
| Crestron |
| AMX |
| RTI |
| Others |
Value Network & Pricing Analysis
The EU Ecodesign Directive gates qualified supply and premium-tier pricing access by mandating standby power thresholds that only Bluetooth Low Energy and wake-on-radio architectures satisfy. Manufacturers investing in compliant firmware engineering capture pricing premiums from German smart home integrators and hospitality procurement teams, while non-compliant suppliers face margin compression in price-sensitive residential segments.
Pricing Analysis
Lead-time-driven pricing stratifies across fulfillment velocity, with integrator-specified projects commanding premiums for accelerated delivery while spot inventory in retail channels clears at discounted rates. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by certification grade and customization depth. Pricing pressure stems from voice-control substitution in television-centric applications. Residential end users exhibit highest price sensitivity; smart home integrators and hospitality procurement teams show lowest.
Supply Chain Analysis
Warehouse-distribution layer concentration in Shenzhen and Dongguan special economic zones feeds hub-and-spoke patterns radiating through regional distribution centers in Germany, the United States, and Japan. Component sourcing draws from Taiwan for RF transceivers, South Korea for EEPROM memory, and China for silicone rubber keypad assemblies. Single-source vulnerability in East Asian foundry capacity presents structural risk. Distribution runs through professional installation channels displacing traditional retail in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Radio Equipment Directive creates a cost-of-compliance barrier that entrenches incumbents with established CE marking pathways while filtering speculative entrants lacking certification infrastructure.
For Market Incumbents: Hedge protocol fragmentation risk by maintaining dual-architecture firmware roadmaps supporting both Matter and Zigbee alongside legacy infrared. Invest in backward integration into silicone rubber keypad molding to defend margin position against Dongguan cost competition. Prioritize hospitality property management system certification as channel control lever against voice-control substitution. For New Entrants and Emerging Players: Launch via direct-to-integrator distribution bypassing retail margin stack. Target German Bauhaus-inspired design segment as most penetrable white space where aesthetic differentiation commands pricing power. Pursue white-label supply relationships with hotel chains seeking unified control platforms as fastest path to volume scale. For Investors and Strategic Acquirers: Hospitality procurement centralization into property management system-integrated platforms is the leading indicator that firmware-engineering talent scarcity will drive acquisition premiums for specialist developers. Long-term viability favors targets with established QuickSet-class platform partnerships and multi-protocol transceiver integration capabilities. Monitor CE marking timeline compression as inflection signal for regulatory-capability valuation gaps.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Protocol Firmware Development | Matter and Zigbee integration capability captures specification priority from smart home integrators in Germany. |
| Silicone Rubber Keypad Backward Integration | In-house molding capacity compresses per-unit costs against Dongguan contract manufacturers in mid-tier segments. |
| Hospitality Property Management System Certification | Unified control platform integration opens recurring replacement revenue in hotel and serviced apartment chains. |
| Bluetooth Low Energy Architecture Transition | EU Ecodesign Directive compliance sustains premium positioning in European retail channels. |
| Cloud-Based Code Database Expansion | Over-the-air firmware update capability extends functional longevity and reduces replacement cycle compression. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews conducted with smart home integrators, hospitality procurement directors, firmware engineering leads, and consumer electronics retail buyers. FCC spectrum allocation databases, EU CE marking registries, and EPA Energy Star certification lists provided regulatory boundary conditions. Bottom-up demand modeling triangulated against top-down manufacturer shipment estimates.
Granularity-level modeling disaggregated volume and value across product architecture, end-use concentration, technology selection, and application complexity throughout the forecast period. CAGRs derived from logistic adoption curves fitted to protocol penetration data and integrator specification rates. Standby power regulation timelines and smart home construction permit trajectories informed regional divergence assumptions.
Protocol standardization wars, semiconductor foundry capacity constraints, and voice-control substitution acceleration are the dominant revision risks to modeled outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Smartphone Sanitizer Market
Consumer Electronics
US Mobile Phone Accessories Market
Consumer Electronics
Subwoofer Market
Consumer Electronics
Smartphone Console Market
Consumer Electronics
United States Soundbar Market
Consumer Electronics
Nail Art Printer Market
Consumer Electronics
Global Monitor Headphones (in-Ear Monitors) Market
Consumer Electronics
Electric Water Bottle Market
Consumer Electronics
Global Polaroid Market
Consumer Electronics
Gaming Keyboard Market
Consumer Electronics
Chromebook Market
Consumer Electronics
Asia-Pacific Professional Audio-Visual Systems Market
Consumer Electronics
Smart Phones Market
Consumer Electronics
Digital Cloud Picture Frame Market
Consumer Electronics
Armenia Consumer Goods Market
Consumer Electronics
North America Wireless Anc Headphone Market