
 Bluetooth Speakers Market | 2026-2036
Bluetooth Speakers Market Size, Share, and Industry Trends Forecast 2026-2036
Bluetooth Speakers Market Intelligence
Outdoor leisure applications is expanding as consumers prioritize rugged, waterproof audio gear for camping, hiking, and poolside use. Sony Corporation leverages its acoustic engineering heritage to sustain premium positioning across portable and party speaker lines. Bose Corporation anchors its reputation in noise-rejection technology and spatial audio for personal listening scenarios. Samsung Electronics Co., Ltd. competes through ecosystem integration with its broader device portfolio.
Bluetooth speakers are wireless audio reproduction devices operating on short-range radio protocols, typically incorporating Class 2 power amplifiers delivering 2.5 mW output for ten-meter indoor coverage and lithium-ion cell arrays enabling four-to-twenty-four hours of untethered playback. Their primary commercial purpose spans personal entertainment, ambient sound reinforcement, and mobile public address across consumer and light-commercial environments. Portable product types dominate volume shipments due to travel-friendly form factors, while smart speakers with voice-assistant integration capture expanding margin pools as households adopt connected home infrastructure. LDAC and AptX codec technologies attract audiophile customer segments seeking high-resolution wireless transmission without tethered connections.
FCC certification governs radio-frequency emissions for US-bound Bluetooth speakers, while CE marking mandates electromagnetic compatibility and safety compliance across European markets. REACH restrictions on phthalates and flame retardants directly influence enclosure material selection and supply chain qualification for manufacturers serving EU consumers. China's GB standards and MIIT radio-type approval requirements shape product architecture for the world's largest production base. Stakeholders must monitor evolving battery transport regulations and right-to-repair legislation as these frameworks increasingly determine design constraints and aftermarket service obligations.
Market Dynamics
Shenzhen's electronics manufacturing cluster concentrates Bluetooth speaker production, creating supply-side leverage that shapes component sourcing, assembly economics, and firmware development cycles across the entire category.
Growth Catalysts
- REACH compliance mandates:EU restrictions on hazardous substances in electronics are accelerating enclosure material innovation toward bio-based polymers and recycled aluminum alloys.
- Outdoor recreation vertical:Camping and hiking enthusiasts are driving demand for IP67-rated portable audio with extended battery endurance and ruggedized chassis designs.
- LDAC codec adoption:High-resolution wireless transmission standards are attracting audiophile segments previously tethered to wired connections.
Market Restraints
- Lithium-ion cell volatility:Battery raw material price swings and transport classification restrictions constrain margin flexibility and logistics planning.
- Shenzhen supply concentration:Over-reliance on a single manufacturing basin creates geopolitical and pandemic-disruption exposure for global brands.
- Codec licensing fragmentation:Proprietary audio compression patents from Qualcomm, Sony, and others impose royalty stacking on mid-tier manufacturers.
Strategic Opportunities
- India manufacturing incentives:PLI scheme benefits and tariff rationalization are drawing assembly migration away from sole China dependency.
- Voice-assistant integration:Smart speaker architectures converging with portable form factors open recurring revenue streams through service subscriptions.
- Right-to-repair legislation:EU and US state-level mandates for battery replaceability and spare parts availability favor modular design specialists.
Industry Challenges
- Acoustic engineering talent scarcity:DSP firmware optimization and transducer tuning expertise concentrates at legacy audio houses, constraining new entrant R&D velocity.
- FCC certification timelines:Radio-frequency emission testing queues and documentation revisions delay product launches by four-to-six months.
- Legacy Bluetooth interoperability:Backward compatibility maintenance across five protocol generations consumes firmware engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bluetooth Speakers Market |
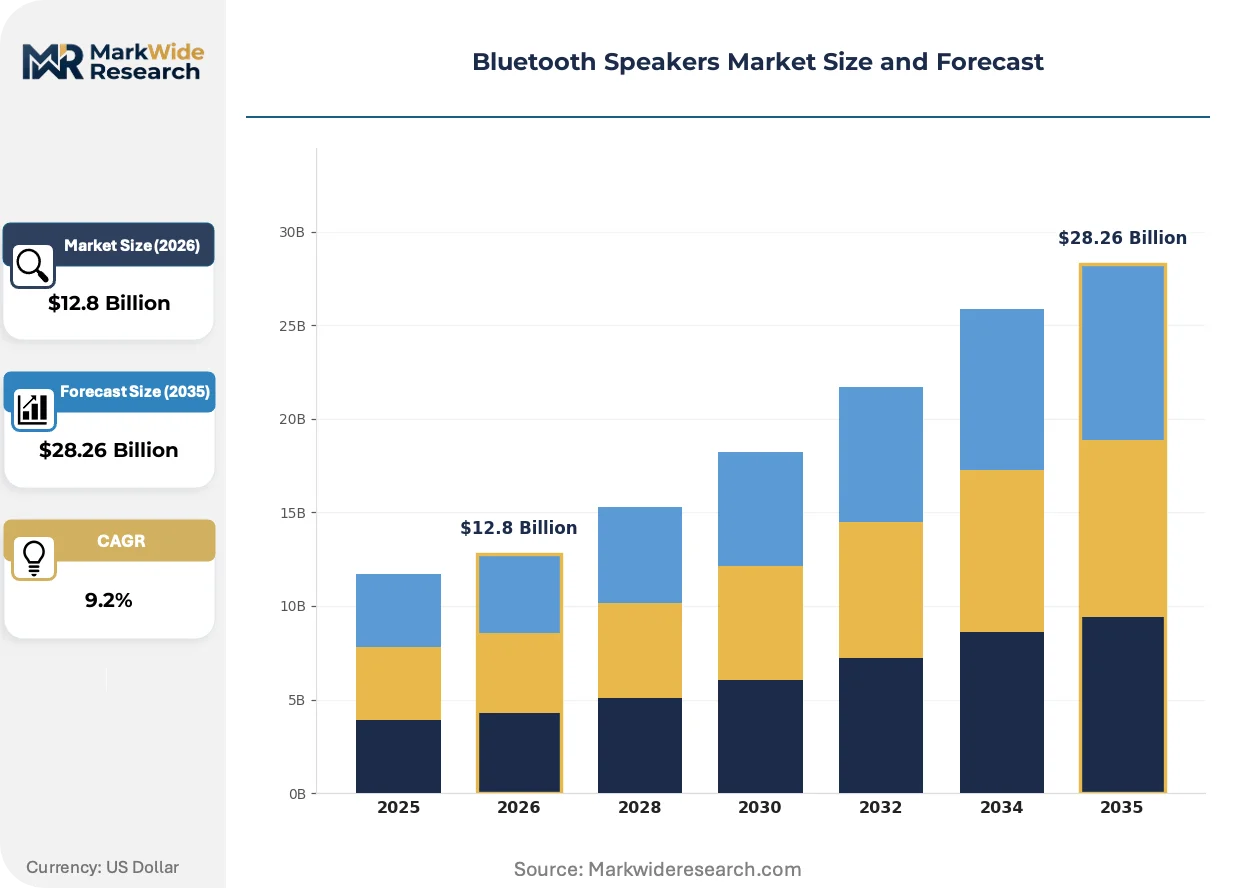
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $28.26 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Smart, Party, Outdoor, Bookshelf Technology: Bluetooth 5.0, Bluetooth 4.2, NFC, AptX, LDAC Application: Personal Audio, Corporate Events, Fitness, Public Address, Leisure Customer Type: Individual Users, Event Organizers, Fitness Trainers, Retail Outlets, Content Creators |
| Companies Covered | Apple Inc., Bose Corporation, Sony Corporation, Harman International Industries Inc., JBL Inc., Samsung Electronics Co., Ltd., Sonos Inc., Logitech, Bang & Olufsen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bluetooth Speakers Market Strategic Shifts & Innovations
Codec evolution and regulatory material mandates are restructuring competitive differentiation away from pure acoustic performance toward transmission fidelity and circular design credentials.
Graphene-enhanced diaphragm materials are absorbing mechanical stress more efficiently than traditional cellulose or PET constructions, enabling thinner driver profiles without sacrificing excursion limits. Boutique outdoor audio brands are adopting these composites for weight-critical applications. The technology is absorbing premium positioning from conventional driver engineering, compressing R&D differentiation cycles to twelve-to-eighteen months.
EU Ecodesign Directive requirements for repairability and recycled content thresholds are forcing enclosure redesign toward snap-fit architectures and standardized screw patterns. Manufacturers serving European markets must requalify supply chains for post-consumer recycled plastics. Party speaker and premium portable categories face the steepest compliance cost escalation, with some brands exiting sub-two-hundred-euro price bands entirely.
Direct-to-consumer channel expansion is displacing traditional retail distribution for established audio brands, with subscription bundling and trade-in programs capturing repeat purchase loyalty previously held by big-box electronics chains. This pattern concentrates in North American and Western European markets where e-commerce penetration in consumer electronics exceeds forty percent. After-sales service unbundling—separating warranty claims from retail touchpoints—is creating specialized logistics providers focused solely on audio equipment refurbishment.
Bluetooth Speakers Market Segmentation
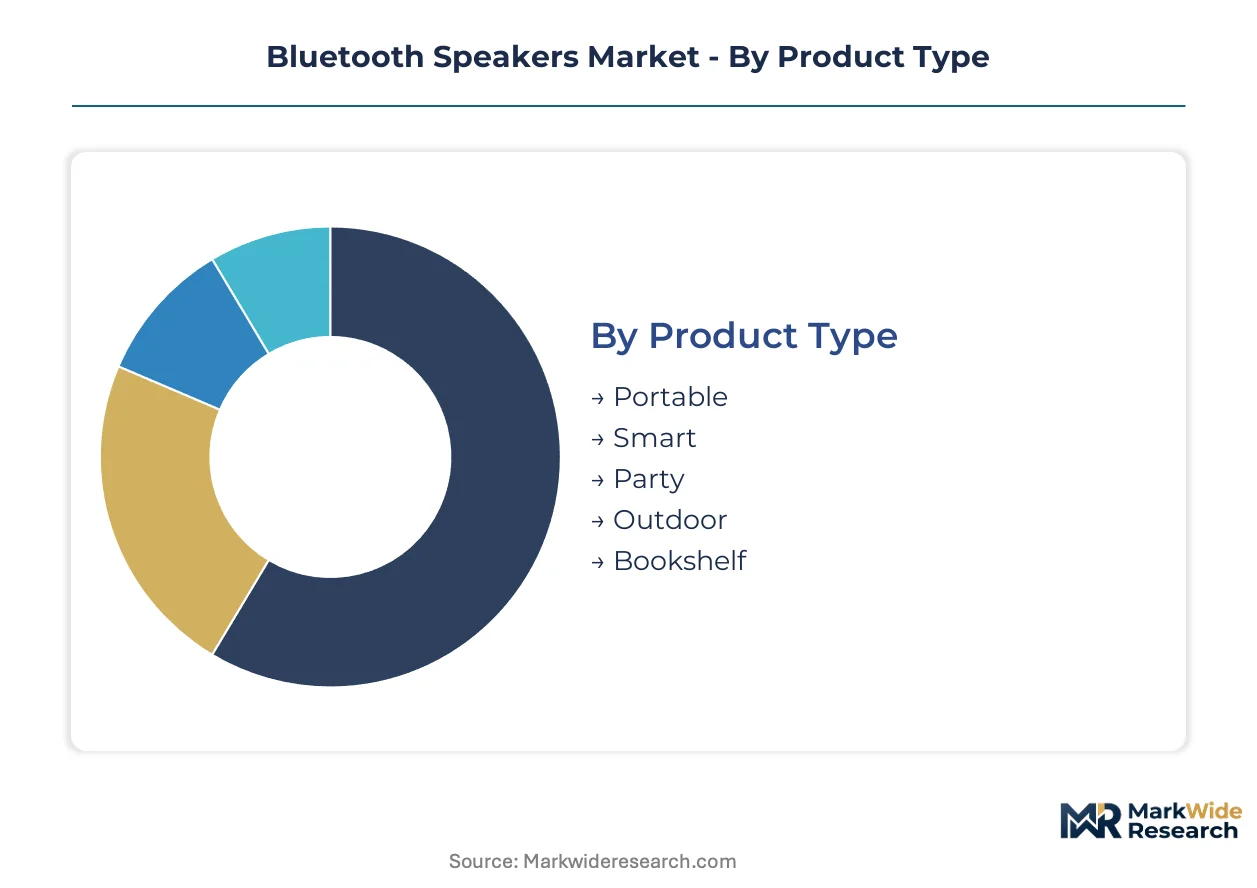
Bluetooth speaker buyers fragment across usage intensity, acoustic fidelity expectations, and ecosystem integration needs. Segmentation reveals where margin pools concentrate and which technical specifications command premium positioning.
Product Type:
Buyers in this category differentiate by mobility requirements, acoustic output needs, and social versus solitary listening contexts.
- Portable:Compact lithium-ion powered units with 10-20 hour battery endurance dominate travel and daily commuting use cases. Demand concentrates in urban China and Western European metropolitan corridors where public transit use necessitates personal audio isolation.
- Smart:Voice-assistant enabled architectures with far-field microphone arrays and Wi-Fi bridging capabilities. North American households adopting connected home infrastructure drive replacement cycles as these units displace standalone smart speakers.
- Party:High-output Class D amplification with multi-unit pairing and LED synchronization features. Event rental operators in Brazil and Mexico favor these for mobile DJ applications where mains power availability varies.
- Outdoor:IP67-rated enclosures with shock-absorbing bumpers and extended temperature operating ranges. Camping specialty retailers in Germany and Australia report climbing attachment rates with tent and gear purchases.
- Bookshelf:AC-powered stationary designs emphasizing stereo imaging and larger driver complements. Japanese and South Korean audiophile communities sustain niche demand for these as desktop monitor replacements.
Volume sits with Portable; growth tilts toward Smart.
Technology:
Transmission protocol selection separates price-insensitive fidelity seekers from convenience-oriented mainstream buyers.
- Bluetooth 5.0:Current baseline protocol with 2 Mbps throughput and LE Audio readiness. Shenzhen assembly lines have standardized on this chipsets, collapsing cost premiums versus legacy 4.2 variants.
- Bluetooth 4.2:Legacy protocol maintaining backward compatibility with older source devices. Sub-$30 retail price bands in India and Southeast Asia continue specifying these chipsets for cost containment.
- NFC:Tap-to-pair functionality eliminating manual discovery sequences. Corporate procurement specifications in France and Germany increasingly mandate NFC for conference room deployment efficiency.
- AptX:Qualcomm's proprietary low-latency codec preserving CD-quality transmission. Android device penetration rates directly correlate with AptX demand concentration across European markets.
- LDAC:Sony-developed 990 kbps codec enabling hi-res audio wireless transmission. Japanese and Chinese streaming service subscribers with lossless tier subscriptions drive adoption in premium portable categories.
Bluetooth 5.0 commands current volume; LDAC exhibits the steepest expansion trajectory among audiophile tiers.
Application:
End-use context determines durability specifications, acoustic tuning priorities, and connectivity redundancy requirements.
- Personal Audio:Individual listening scenarios emphasizing vocal clarity and extended wear comfort. Commuter rail systems in the United Kingdom and Netherlands create concentrated demand for noise-isolating designs.
- Corporate Events:Rental fleet requirements prioritizing rapid deployment, daisy-chain scalability, and ruggedized transit cases. Hotel and convention center operators in Dubai and Singapore specify these for breakout room audio.
- Fitness:Sweat-resistant constructions with secure mounting options and motivational bass emphasis. Boutique studio chains across Australia and California drive replacement cycles with 18-24 month equipment refresh schedules.
- Public Address:Battery-powered megaphone alternatives with microphone inputs and siren functions. Municipal emergency management agencies in Japan procure these for disaster response kit standardization.
- Leisure:Poolside, patio, and recreational vehicle applications demanding weather resilience and casual aesthetic integration. Seasonal purchasing patterns in Mediterranean coastal markets create Q2 demand spikes.
Personal Audio sustains volume leadership; Fitness applications are climbing the fastest as boutique wellness infrastructure expands.
Customer Type:
Procurement authority and technical specification involvement separate consumer self-selection from institutional buying processes.
- Individual Users:Direct-to-consumer purchasers prioritizing brand recognition, color options, and review aggregation scores. Amazon and Tmall platforms capture the majority of these transactions across North America and China.
- Event Organizers:Rental house and wedding planner procurement with insurance compliance and rapid replacement requirements. These buyers concentrate in Florida, California, and the French Riviera where destination event density is highest.
- Fitness Trainers:Independent contractors and boutique studio owners selecting gear for client experience differentiation. Certification body partnerships in the United Kingdom influence equipment recommendations.
- Retail Outlets:Background music system operators requiring commercial licensing compliance and extended duty cycles. Coffee shop chains in South Korea and Italy specify these for acoustic zoning without construction.
- Content Creators:YouTube and podcast producers needing monitor accuracy and camera-friendly industrial design. Los Angeles and London creator economy hubs drive demand for reference-grade portable options.
Individual Users dominate transaction volume; Content Creators represent the fastest-growing customer acquisition target for premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of Bluetooth speaker units while the United States and Western European markets absorb the highest-value consumption. Shenzhen's electronics ecosystem supplies components and finished goods to brands worldwide. Demand fragmentation across geographies creates divergent regulatory compliance burdens for exporters.
United States
Fitness studio chains and outdoor recreation retailers drive procurement of ruggedized portable audio equipment. FCC certification requirements govern radio-frequency emissions for all imported wireless devices. Austin and Los Angeles host content creator communities that sustain demand for reference-grade monitoring speakers with camera-friendly industrial design.
Germany
REACH restrictions on phthalates and flame retardants reshape enclosure material specifications for EU-bound products. Camping specialty retailers in Bavaria and Baden-Württemberg report climbing attachment rates for IP67-rated outdoor speakers alongside tent purchases. Berlin's electronics distributors serve as consolidation points for Scandinavian and Eastern European re-export.
China
MIIT radio-type approval and GB standards compliance requirements shape product architecture for domestic and export manufacturing. Shenzhen's component markets supply Bluetooth 5.0 chipsets, lithium-ion cells, and driver assemblies to assembly operations across Guangdong Province. Shanghai and Beijing consumers demonstrate willingness to pay premiums for LDAC-enabled hi-res audio transmission.
Japan
Lossless streaming service subscribers in Tokyo and Osaka sustain demand for premium portable categories with high-resolution codec support. METI energy efficiency guidelines influence standby power consumption specifications. Nagoya's precision manufacturing base supplies transducer components to domestic and export audio brands.
India
PLI scheme incentives and tariff rationalization are drawing assembly migration from sole China dependency. BIS certification requirements for electronic goods create compliance hurdles for imported finished products. Maharashtra and Karnataka host emerging contract manufacturing operations serving Middle Eastern and African export markets.
Bluetooth Speakers Market Key Industry Players
Top-tier vendors anchor premium positioning through acoustic engineering heritage and ecosystem integration, while mid-tier specialists compete on ruggedized outdoor features and aggressive price positioning. The vendor base spans diversified consumer electronics conglomerates, dedicated audio houses, and contract manufacturing brands. Two strategic archetypes dominate: heritage acoustic engineering firms leveraging transducer expertise, and platform-integrated technology companies exploiting device ecosystem lock-in. Competitive moves concentrate on voice-assistant integration partnerships and direct-to-consumer channel expansion displacing traditional retail distribution.
Within the heritage engineering tier, Bose Corporation and Sony Corporation exemplify sustained premium positioning through noise-rejection technology and spatial audio capabilities respectively. Samsung Electronics Co., Ltd. occupies a position leveraging ecosystem integration with its broader device portfolio. These three entities represent contrasting strategic anchors: acoustic specialization, high-resolution transmission standards, and cross-device platform convergence.
| Leading Market Players |
|---|
| Apple Inc. |
| Bose Corporation |
| Sony Corporation |
| Harman International Industries Inc. |
| JBL Inc. |
| Samsung Electronics Co., Ltd. |
| Sonos Inc. |
| Logitech |
| Bang & Olufsen |
| Others |
Cost & Logistics Intelligence
EU Ecodesign Directive repairability mandates gate qualified supply access for premium-tier positioning, forcing enclosure redesign costs that compress margins below two-hundred-euro price bands while rewarding modular architecture specialists with pricing power in compliant tiers.
Pricing Analysis
Margin tightening in sub-$50 economy tiers reflects Shenzhen chipset commoditization and royalty stacking from Qualcomm AptX and Sony LDAC licensing. Three-tier pricing structure across premium, standard, and economy levels separates LDAC-enabled audiophile units from Bluetooth 5.0 baseline models and legacy 4.2 entry products. Price differentiation hinges on codec certification grade and volume procurement scale. Fitness studio chains exhibit highest price sensitivity due to eighteen-to-twenty-four month refresh cycles; Japanese lossless streaming subscribers show least sensitivity.
Supply Chain Analysis
Direct-to-consumer channels displace traditional retail distribution for established audio brands in North American and Western European markets. Component sourcing concentrates in China, South Korea, and Japan for Bluetooth chipsets, lithium-ion cells, and precision transducers. Raw material dependencies include neodymium magnets, graphene-enhanced diaphragm composites, and post-consumer recycled aluminum alloys. Supply chain risk centers on single-source vulnerability from Shenzhen manufacturing concentration. Distribution runs through e-commerce platforms, camping specialty retailers, and fitness equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bluetooth speaker technology is transitioning from passive wireless playback to voice-assistant integrated architectures, with smart speaker convergence replacing standalone portable units as the dominant household configuration.
For Market Incumbents: Deepen acoustic engineering talent retention through DSP firmware specialization and transducer tuning expertise concentration. Defend premium positioning by accelerating LDAC and spatial audio R&D investment. Counter ecosystem lock-in threats from Samsung and Apple through certification differentiation and modular repairability compliance.
For New Entrants and Emerging Players: Capture white-space opportunity in India's PLI-driven manufacturing migration and Middle Eastern export markets. Target fitness boutique studio chains with sweat-resistant designs and motivational bass tuning. Penetrate through direct-to-consumer subscription bundling with trade-in program mechanics.
For Investors and Strategic Acquirers: Right-to-repair legislation passage in EU member states is the leading indicator that modular design specialists will command acquisition premiums. Long-term viability favors contract manufacturers with backward integration into lithium-ion cell assembly and post-consumer recycled plastic qualification. Monitor FCC certification queue lengths as inflection signal for new entrant launch velocity constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| Voice-Assistant Platform Integration | Smart speaker architectures from Amazon Alexa and Google Assistant enable recurring service revenue streams. |
| Direct-to-Consumer Channel Expansion | Trade-in programs and subscription bundling displace big-box electronics chain loyalty in North America. |
| Sustainability Repositioning | EU REACH compliance and Ecodesign Directive repairability mandates restructure competitive differentiation toward circular credentials. |
| Geographic Manufacturing Footprint | India PLI scheme incentives draw assembly migration from sole China dependency for tariff rationalization. |
| High-Resolution Codec Licensing | Sony LDAC and Qualcomm AptX adoption attracts audiophile segments previously tethered to wired connections. |
Research Approach
SEC filings, MIIT radio-type approval databases, and EU ECHA REACH restriction updates formed the secondary backbone for supply chain and regulatory mapping. Primary interviews with audio brand product managers, Shenzhen contract manufacturing executives, and camping specialty retail buyers validated component cost structures and demand patterns. Bottom-up shipment estimates triangulated against top-down consumer electronics spending data.
Bottom-up modeling aggregated unit economics across portable, smart, party, outdoor, and bookshelf product types. Segmentation dimensions included transmission protocol tier, application context, and customer procurement authority. CAGR derivation incorporated lithium-ion cell price elasticity, codec licensing royalty schedules, and voice-assistant integration attach rates. Forecast inputs weighted FCC certification timeline delays and right-to-repair legislative passage probability.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to battery transport regulation changes and geopolitical disruption in Shenzhen manufacturing concentration. Forecasts reflect documented assumptions on protocol adoption curves and regulatory compliance cost trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Consumer Electronics Market
Consumer Electronics
Global Smart Earbuds Market
Consumer Electronics
Middle East and Africa Mobile Phone Accessories Market
Consumer Electronics
Personal Computer Market
Consumer Electronics
Pet Cameras Market
Consumer Electronics
Headset Market
Consumer Electronics
Global Bluetooth Mono Earpieces Market
Consumer Electronics
Smartphone Sanitizer Market
Consumer Electronics
Kid's Wired Earphone and Headphone Market
Consumer Electronics
Adult Sex Dolls Market
Consumer Electronics
Air Tube Headset Market
Consumer Electronics
Europe Gaming Headset Market
Consumer Electronics
Tattoo Stencil Printer Market
Consumer Electronics
Global Smart Outdoor TV Market
Consumer Electronics
Silicone Sex Doll Market
Consumer Electronics
Electronics Accessories Market