
 Europe Stylus Pen Market | 2026-2036
Europe Stylus Pen Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Stylus Pen Market Intelligence
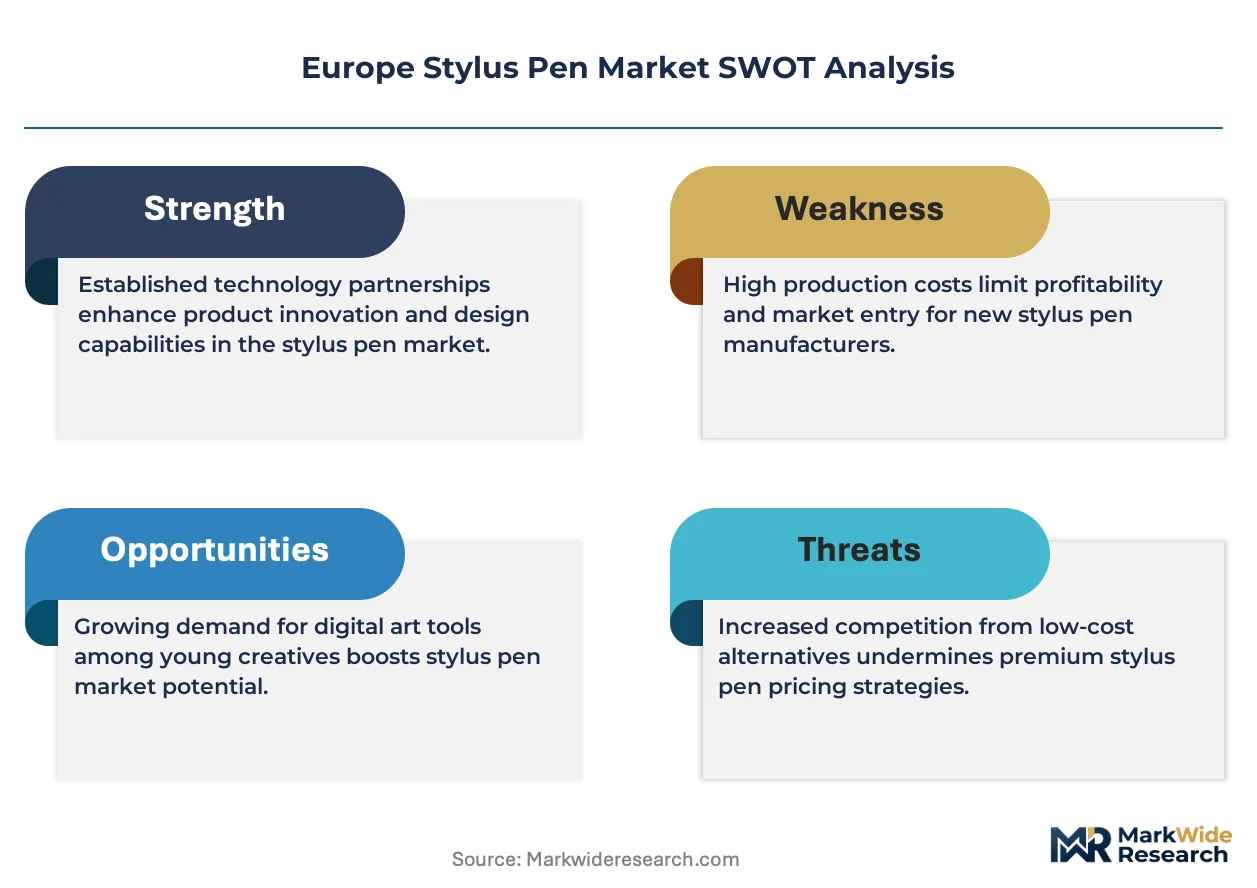
Subscription-based hardware leasing and device-as-a-service models are rewriting how stylus pens reach end users across Europe, lowering upfront barriers for educational institutions and small design studios. Wacom Co., Ltd. anchors its position through deep R&D intensity in electromagnetic resonance technology. Samsung Electronics Co., Ltd. leverages its Galaxy ecosystem to bundle active stylus solutions. Microsoft Corporation competes through Surface Pen integration with enterprise productivity workflows.
A stylus pen is a handheld input device featuring a conductive or powered tip, typically with pressure sensitivity levels exceeding 4,000 distinct gradations, designed to emulate natural writing or drawing on capacitive touchscreens for digital content creation and annotation. Active stylus variants, incorporating Bluetooth and palm rejection protocols, command the dominant margin pool due to their precision and interoperability demands. Passive stylus products occupy the volume-heavy educational segment where cost minimization outweighs feature depth. Distribution through online retail channels is accelerating fastest, reflecting direct-to-consumer preferences among freelance designers and remote professionals.
REACH compliance and RoHS substance restrictions shape material selection for European stylus manufacturers, while CE marking mandates govern electromagnetic compatibility and user safety for active variants with integrated batteries. The EU Green Deal's circular economy requirements are pressuring brands to design for disassembly and battery replaceability. Stakeholders must monitor how Ecodesign for Sustainable Products Regulation implementation affects product lifecycle obligations and refurbishment economics across member states.
Market Dynamics
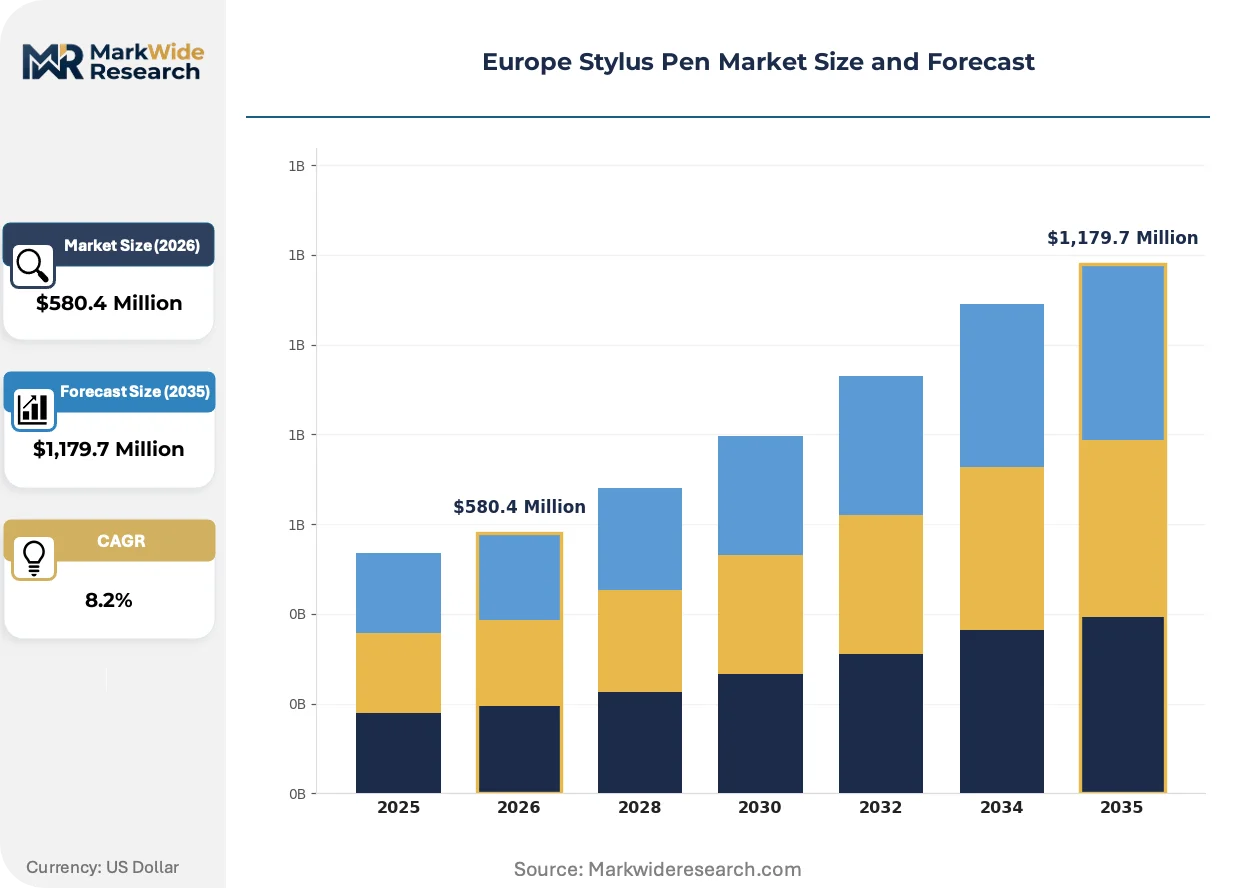
The EU's Ecodesign for Sustainable Products Regulation is forcing stylus manufacturers toward modular, repairable designs with replaceable batteries, compressing margins for sealed-unit producers while opening refurbishment economics for circular-first brands.
Growth Catalysts
- Digital Art Education:French and British universities are mandating pressure-sensitive tablets for design curricula, creating institutional procurement pipelines for active stylus bundles.
- REACH Material Compliance:Restrictions on hazardous substances in electronics are accelerating adoption of bio-based conductive polymers in premium pen tips.
- Enterprise Tablet Deployment:Financial services firms in Frankfurt and London are standardizing annotation workflows for compliance documentation, driving fleet purchases of palm-rejection enabled devices.
Market Restraints
- Lithium Supply Concentration:Active stylus battery cells depend on cathode materials sourced through concentrated Asian processing chains, exposing European assemblers to input volatility.
- Technical Latency Limitations:Bluetooth protocol stacks introduce perceptible lag in cross-platform use cases, constraining adoption among professional animators requiring sub-10ms response.
- RoHS Substance Friction:Exemptions for certain lead alloys in precision sensor components are narrowing, forcing costly retooling of electromagnetic resonance coil assemblies.
Strategic Opportunities
- Underpenetrated Eastern Europe:Polish and Romanian creative agencies remain reliant on passive styluses, presenting upgrade conversion potential as EU digital skills funding expands.
- Regulatory Tailwind:The EU Green Deal's circular economy requirements are creating preferential procurement scoring for devices with documented disassembly protocols and spare parts availability.
- Healthcare Annotation Convergence:German hospital systems are piloting stylus-based electronic health record markup, merging clinical workflow digitization with existing tablet infrastructure.
Industry Challenges
- Electromagnetic Compatibility Certification:CE marking timelines for active variants with integrated RF modules are extending due to backlog at notified bodies, delaying product launches.
- Skill Gap in Modular Design:European engineering talent with expertise in repairable electronics architecture remains scarce relative to sealed-unit consumer electronics experience.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Stylus Pen Market |
| Market Size in 2026 | $580.4 Million |
| Market Size in 2035 | $1,179.7 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Stylus, Passive Stylus, Capacitive Stylus, Digital Pen End User: Students, Professionals, Designers, Artists Technology: Bluetooth, Pressure Sensitivity, Palm Rejection, Touchscreen Compatibility Distribution Channel: Online Retail, Offline Retail, Wholesale, Direct Sales |
| Companies Covered | Adonit Co. Ltd., Dell Technologies Inc., Apple Inc., ASUS Tek Computer Inc., Lenovo Group Limited, Samsung Electronics Co., Ltd., Wacom Co., Ltd., Hewlett-Packard Development Company, L.P., Microsoft Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Stylus Pen Market Strategic Shifts & Innovations
Hybrid input technologies are dissolving boundaries between active and passive stylus categories, while regulatory pressure on material circularity and procurement model experimentation are compressing traditional product lifecycles.
Electromagnetic resonance technology is hybridizing with capacitive touch protocols to enable dual-mode pens that switch between powered precision and battery-free operation. German automotive design studios are piloting these hybrid units for factory-floor markup and presentation-room sketching without pairing overhead. This convergence is compressing the addressable market for single-mode passive products in professional segments.
The EU Ecodesign for Sustainable Products Regulation is mandating digital product passports and repairability scoring for electronics with integrated batteries. Manufacturers must now document disassembly sequences and spare parts availability for active stylus variants sold in member states. French retailers are already displaying repairability indices at point-of-sale, steering consumer preference toward modular designs.
Device-as-a-service contracting is displacing outright purchase in educational and mid-market creative segments. Dutch design academies and Belgian animation cooperatives are leasing stylus-tablet bundles with bundled maintenance and upgrade rights. This model concentrates buyer power among leasing aggregators while shifting inventory risk back to manufacturers and their financing partners.
Europe Stylus Pen Market Segmentation
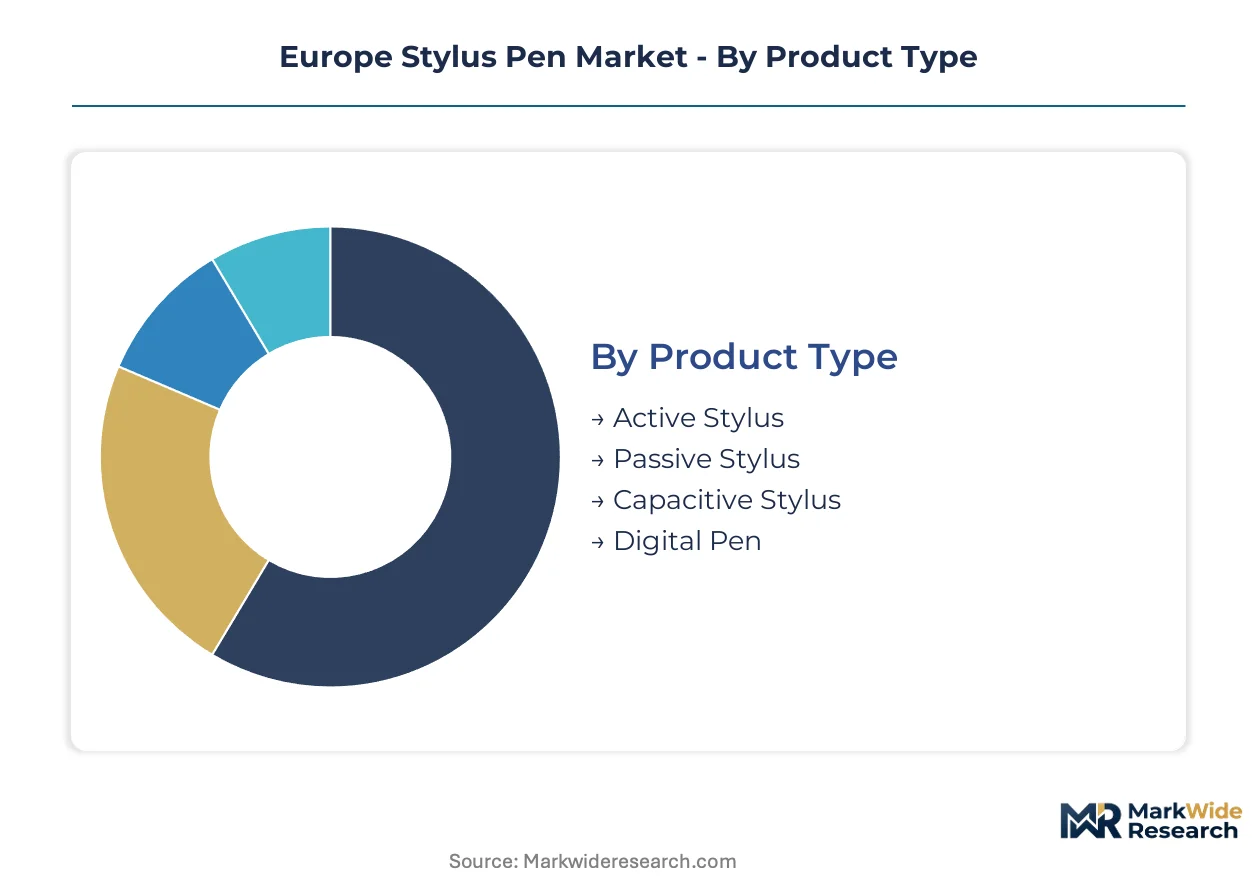
Segmentation in the Europe stylus pen market reveals divergent replacement cycles and margin structures across product architectures. Understanding these patterns enables manufacturers to align inventory planning with institutional procurement calendars and consumer upgrade behaviors.
Product Type:
Active stylus variants command 18-24 month replacement cycles among professionals, while passive products turn over faster in volume-driven educational settings. Digital pens exhibit the longest useful life due to embedded storage and cross-device compatibility.
- Active Stylus:Electromagnetic resonance or Bluetooth-enabled units with pressure sensitivity exceeding 4,000 levels and sub-20ms latency. German automotive design studios and French animation houses drive premium demand as these users require palm rejection and tilt recognition for precision workflows.
- Passive Stylus:Conductive rubber or fabric-tipped devices without internal power, relying on capacitive coupling. Polish and Romanian educational institutions absorb volume shipments where cost minimization outweighs feature requirements, though EU digital skills funding is accelerating upgrade timelines.
- Capacitive Stylus:Battery-free conductive designs optimized for basic touchscreen navigation. British primary schools deploy these for introductory tablet literacy programs before migrating students to active variants.
- Digital Pen:Self-contained input devices with onboard memory and cross-platform pairing protocols. Italian architectural firms and Dutch engineering consultancies favor these for field documentation where cloud connectivity remains unreliable.
Passive stylus anchors the volume base while active stylus gains share at the steepest rate.
End User:
Procurement authority and budget scale vary dramatically across user categories, with institutional buyers negotiating fleet pricing and individual professionals prioritizing specification over cost.
- Students:Price-sensitive adopters in secondary and tertiary education, often receiving styluses through bundled tablet programs. French universities mandate pressure-sensitive tools for design curricula, compressing replacement cycles as curricula update.
- Professionals:Enterprise users in financial services, healthcare, and legal sectors requiring annotation compliance. Frankfurt banking consortiums and London insurance underwriters standardize palm-rejection devices for document markup workflows.
- Designers:Commercial creative practitioners balancing precision requirements with software ecosystem compatibility. Belgian packaging design studios and Spanish architectural visualization firms drive mid-tier specification demand.
- Artists:Fine art and illustration practitioners demanding maximum pressure gradation and tilt sensitivity. Independent creators in Berlin and Paris gravitate toward modular, repairable designs under EU Ecodesign pressure.
Students generate the highest unit volumes while professionals deliver the strongest margin contribution.
Technology:
Feature integration determines pricing tiers and interoperability boundaries, with proprietary protocols creating ecosystem lock-in that complicates cross-platform deployment.
- Bluetooth:Wireless pairing protocols enabling shortcut buttons, tilt detection, and device-specific optimization. Nordic creative agencies encounter latency friction when pairing across mixed tablet fleets, constraining adoption in heterogeneous environments.
- Pressure Sensitivity:Capacitive or electromagnetic sensors registering 2,048 to 8,192 distinct pressure levels. German medical illustrators and British forensic reconstruction specialists require maximum gradation for anatomical accuracy.
- Palm Rejection:Algorithmic or hardware-based filtering distinguishing intentional stylus contact from hand resting. Enterprise tablet deployments in Dutch logistics and Swiss pharmaceutical quality control mandate this feature for standing-use scenarios.
- Touchscreen Compatibility:Universal capacitive operation across device brands without driver installation. Eastern European small businesses and Italian freelance consultants favor this flexibility for multi-client engagements.
Touchscreen compatibility spans the broadest installed base while Bluetooth integration expands most quickly among premium users.
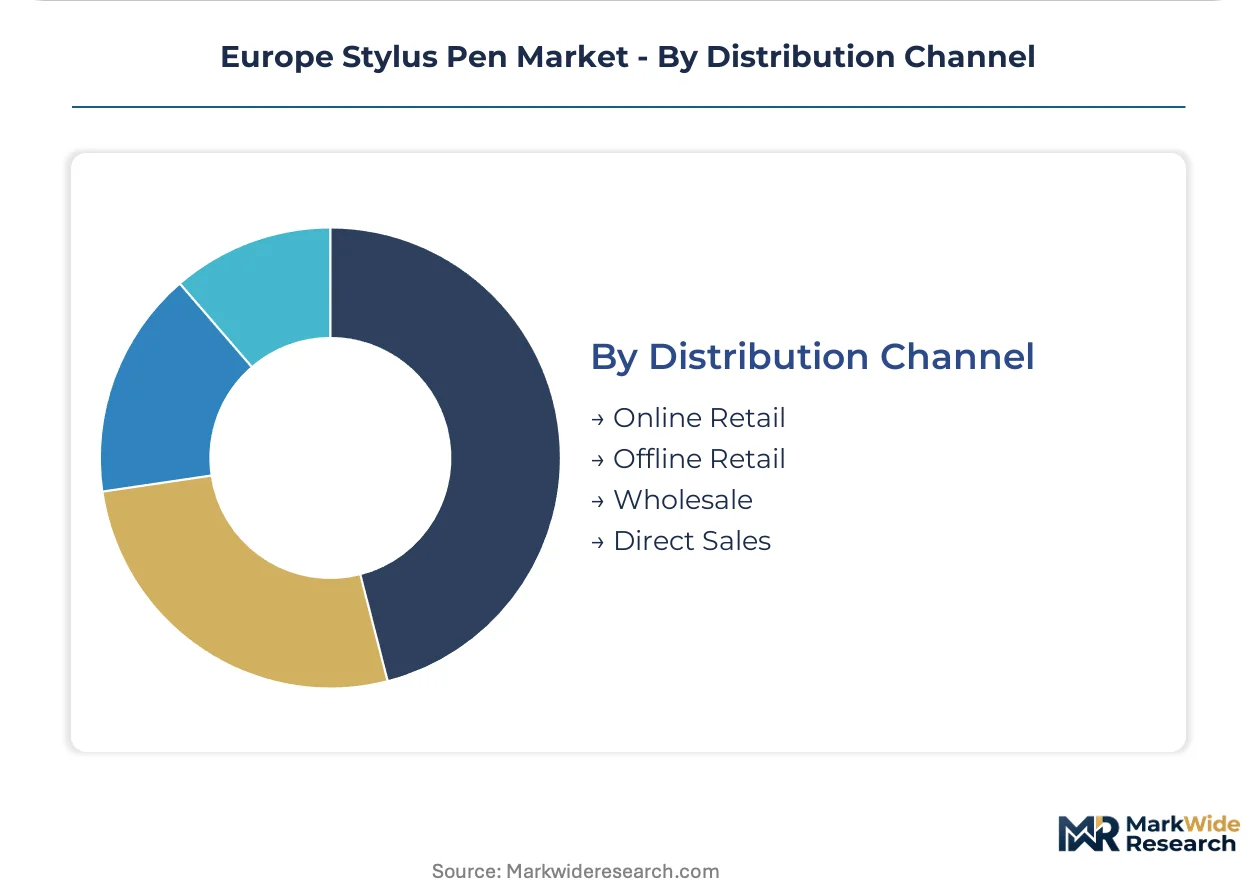
Distribution Channel:
Channel selection reflects buyer sophistication and purchase scale, with direct relationships dominating institutional procurement and digital platforms capturing individual professionals.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators serving remote professionals and small studios. Freelance designers across Portugal and Austria prefer this channel for specification comparison and rapid delivery.
- Offline Retail:Physical electronics and specialty art supply stores offering hands-on evaluation. French retailers now display repairability indices at point-of-sale, steering preference toward modular designs under Ecodesign mandates.
- Wholesale:Volume distributors supplying educational resellers and enterprise IT integrators. Belgian animation cooperatives and Dutch design academies source through these channels for bundled leasing arrangements.
- Direct Sales:Manufacturer-owned channels for enterprise fleet contracts and institutional partnerships. British university procurement offices and German hospital systems negotiate directly for standardized annotation deployments.
Wholesale channels anchor educational volume while direct sales capture the steepest expansion in enterprise segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's stylus pen trade flows reflect a structural deficit in battery cell and precision sensor manufacturing, with finished devices imported from Asian assembly hubs while design and software integration competencies concentrate in Western European headquarters. The regional market fragments across national procurement patterns shaped by educational funding regimes, enterprise digitization timelines, and circular economy compliance burdens.
Germany
Automotive design studios in Munich and Stuttgart drive premium active stylus demand for clay modeling digitization and factory-floor markup workflows. REACH substance restrictions on conductive polymers are accelerating supplier audits for pen tip materials. Berlin's creative technology cluster hosts multiple device-as-a-service leasing platforms serving freelance illustrators and animation cooperatives.
United Kingdom
London financial services firms standardize palm-rejection styluses for compliance documentation annotation, creating fleet procurement pipelines. The UKCA marking transition from CE certification is extending electromagnetic compatibility testing timelines for active variants. Manchester's digital health innovation zone pilots stylus-based electronic health record markup in hospital tablet deployments.
France
Parisian design academies mandate pressure-sensitive tablets for curricula, compressing institutional replacement cycles to 18-24 months. Ecodesign for Sustainable Products Regulation implementation is forcing retailers to display repairability indices at point-of-sale, steering consumer preference toward modular pen architectures. Lyon hosts a growing cluster of circular economy refurbishment specialists serving enterprise tablet fleets.
Netherlands
Dutch logistics and pharmaceutical quality control operations mandate palm-rejection features for standing-use tablet scenarios in warehouse and cleanroom environments. The EU Green Deal's circular economy requirements are creating preferential procurement scoring for devices with documented disassembly protocols. Eindhoven's hardware engineering ecosystem supports several stylus-tablet bundle leasing platforms for design education.
Poland
Polish creative agencies and secondary schools remain reliant on passive styluses, presenting upgrade conversion potential as EU digital skills funding expands. RoHS substance exemptions for precision sensor components are narrowing, forcing costly supply chain adjustments for distributors serving the mid-market. Warsaw's emerging technology procurement offices are piloting active stylus bundles for public sector tablet deployments.
Europe Stylus Pen Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in electromagnetic resonance and pressure sensor architectures. Market structure tilts toward ecosystem lock-in, with tablet and laptop manufacturers bundling proprietary active stylus variants while independent suppliers compete on cross-platform compatibility. Three archetypes dominate: ecosystem-locked hardware divisions of consumer electronics conglomerates; specialist input device manufacturers with deep R&D in pen technologies; and component-tier suppliers of capacitive tips and coil assemblies. Competitive moves concentrate on technology licensing for interoperability protocols and circular economy certification to secure public sector procurement preference.
Among Asia-headquartered electronics conglomerates, Samsung Electronics Co., Ltd. and Wacom Co., Ltd. exemplify contrasting strategic positions. Samsung anchors ecosystem-locked distribution through Galaxy tablet bundling, while Wacom occupies the specialist tier with concentrated expertise in electromagnetic resonance architectures. Microsoft Corporation represents the productivity-platform vector, integrating stylus functionality with enterprise software workflows. These three entities illustrate how competitive positioning fragments across hardware bundling, component specialization, and software-ecosystem integration.
| Leading Market Players |
|---|
| Adonit Co. Ltd. |
| Dell Technologies Inc. |
| Apple Inc. |
| ASUS Tek Computer Inc. |
| Lenovo Group Limited |
| Samsung Electronics Co., Ltd. |
| Wacom Co., Ltd. |
| Hewlett-Packard Development Company, L.P. |
| Microsoft Corporation |
| Others |
Cost & Logistics Intelligence
The Rotterdam-Frankfurt rail corridor's freight cost volatility is compressing margins for European stylus distributors while amplifying price differentiation between modular repairable designs and sealed-unit imports. REACH compliance burdens and lithium cell sourcing concentration feed directly into landed cost structures, forcing buyers to absorb tiered premiums or downgrade specification tiers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Certification grade under EU Ecodesign repairability scoring and volume scale drive price differentiation, with fleet purchasers commanding 15-20 point discounts. Pricing pressure stems from sealed-unit Asian imports undercutting modular European designs. Educational institutions exhibit highest price sensitivity; enterprise healthcare and automotive design studios show lowest.
Supply Chain Analysis
Extended payment terms from Asian battery cell suppliers are tightening working capital requirements for European assemblers. Manufacturing concentrates in China, South Korea, and Vietnam for precision sensors and lithium-ion cells. Conductive polymer tips and electromagnetic resonance coils draw from concentrated Asian processing chains. Single-source vulnerability in cathode material refining exposes assemblers to input volatility. Distribution runs through wholesale aggregators serving educational leasing platforms and direct enterprise fleet contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Dutch and Belgian design academy leasing consortia, fragmenting procurement authority away from individual institutions toward aggregated purchasing platforms that dictate terms to manufacturers.
For Market Incumbents: Entrench ecosystem lock-in through deeper Galaxy and Surface software integration while accelerating backward integration into electromagnetic resonance coil production to offset RoHS retooling costs. Defend against cross-platform interoperability startups by certifying repairability scores ahead of Ecodesign enforcement waves.
For New Entrants and Emerging Players: Polish and Romanian creative agencies reliant on passive styluses represent the most penetrable entry point for upgrade conversion as EU digital skills funding expands. Target healthcare annotation pilots in German hospital systems with palm-rejection devices bundled to existing tablet infrastructure. Pursue device-as-a-service financing partnerships to bypass incumbent distribution chokepoints.
For Investors and Strategic Acquirers: Carve-out targets emerge from consumer electronics conglomerates' neglected input device divisions lacking circular economy certification roadmaps. Long-term viability hinges on repairability compliance and refurbishment economics rather than sealed-unit volume scale. Watch for Ecodesign enforcement variance across member states as early inflection signal for margin compression winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Design Certification | Ecodesign repairability scoring unlocks preferential procurement in French and Dutch public tenders. |
| Battery Replaceability Program | CE marking timelines shorten for active variants with documented disassembly protocols. |
| Cross-Platform Interoperability | Bluetooth latency reduction captures professional animators requiring sub-10ms response. |
| Device-as-a-Service Launch | Leasing aggregators concentrate buyer power among Belgian and Dutch design education clusters. |
| Refurbishment Partnership | Lyon circular economy specialists extend enterprise fleet lifecycles under EU Green Deal pressure. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across product design, procurement, and distribution functions. Primary interviews captured tablet OEM procurement directors, design academy IT managers, hospital biomedical engineers, and wholesale distributor account leads. Secondary validation drew from ECHA substance restriction filings, CE marking notification body records, EU digital skills funding disbursements, and trade flow customs data. Bottom-up unit shipment estimates triangulated against top-down addressable device installed base calculations.
Calibration against historical replacement cycle data and institutional procurement pipeline visibility anchored volume projections across the analysis window. Segmentation dimensions modeled include product architecture, end-user category, technology integration level, and national regulatory compliance burden. CAGRs derived from fitted adoption curves incorporating Ecodesign implementation phasing and digital education policy momentum. Forecast inputs included EU digital skills funding allocation trajectories and hospital tablet deployment schedules.
Practitioners should monitor Ecodesign enforcement variance and lithium supply chain disruption for early signals of forecast deviation. Projections reflect assumptions on regulatory timeline adherence and substitution technology latency improvement. Macroeconomic contraction, REACH substance restriction expansion, or breakthrough passive stylus performance would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
LAMEA Refurbished and Used Mobile Phones Market
Consumer Electronics
Camera Case Market
Consumer Electronics
Wet Wipes Market
Consumer Electronics
Zipline Kits Market
Consumer Electronics
Digital Accessories Market
Consumer Electronics
Consumer Electronic Biometrics Market
Consumer Electronics
Smart Speaker Market
Consumer Electronics
Computing Mouse Market
Consumer Electronics
Smart DJ Controller Market
Consumer Electronics
Pool Speakers Market
Consumer Electronics
Electric Water Bottle Market
Consumer Electronics
Smart Television and Set-Top Box Market
Consumer Electronics
Smart Connected TV Market
Consumer Electronics
Smartphone Screen Protector Market
Consumer Electronics
Latin America Consumer Electronics Market
Consumer Electronics
North America Gaming Accessories Market