
 Electronic Cigarette Atomizer Market | 2026-2036
Electronic Cigarette Atomizer Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Cigarette Atomizer Market Insights
Ceramic coil heating technology is tilting the engineering baseline away from traditional wire-wick configurations toward more consistent vaporization profiles. Smoore leverages its vertically integrated ceramic manufacturing to supply downstream brands with proprietary heating elements. GeekVape differentiates through ruggedized, IP-rated chassis designs that target outdoor and military-adjacent user segments. Innokin anchors European distribution through TPD-compliant tank capacities and localized compliance documentation.
An electronic cigarette atomizer is a vaporization component comprising a heating element, liquid-absorbent wicking material, and airflow channel, typically constructed with stainless steel or glass housings and engineered to aerosolize nicotine or non-nicotine e-liquids at controlled temperatures. The rebuildable product type occupies the enthusiast tier where coil-building culture sustains premium pricing and aftermarket accessory ecosystems, while the disposable segment accelerates volume through convenience-store channels and reduced maintenance requirements. Sub-ohm coil resistance dominates the direct-to-lung inhalation style preferred by experienced users, whereas standard ohm configurations retain significance in mouth-to-lung systems mimicking conventional cigarette draw behavior.
The US FDA evaluates atomizers through the Center for Tobacco Products, requiring premarket authorization that constrains flavor availability and marketing claims; China's NMPA and national standards under SAMR govern domestic manufacturing quality and export certification. The EU Tobacco Products Directive mandates child-resistant packaging, emission testing, and notification protocols that fragment product configurations across member states. Stakeholders must monitor evolving synthetic nicotine classification debates and battery safety standard harmonization efforts that could force hardware redesigns or supply chain restructuring.
Market Dynamics
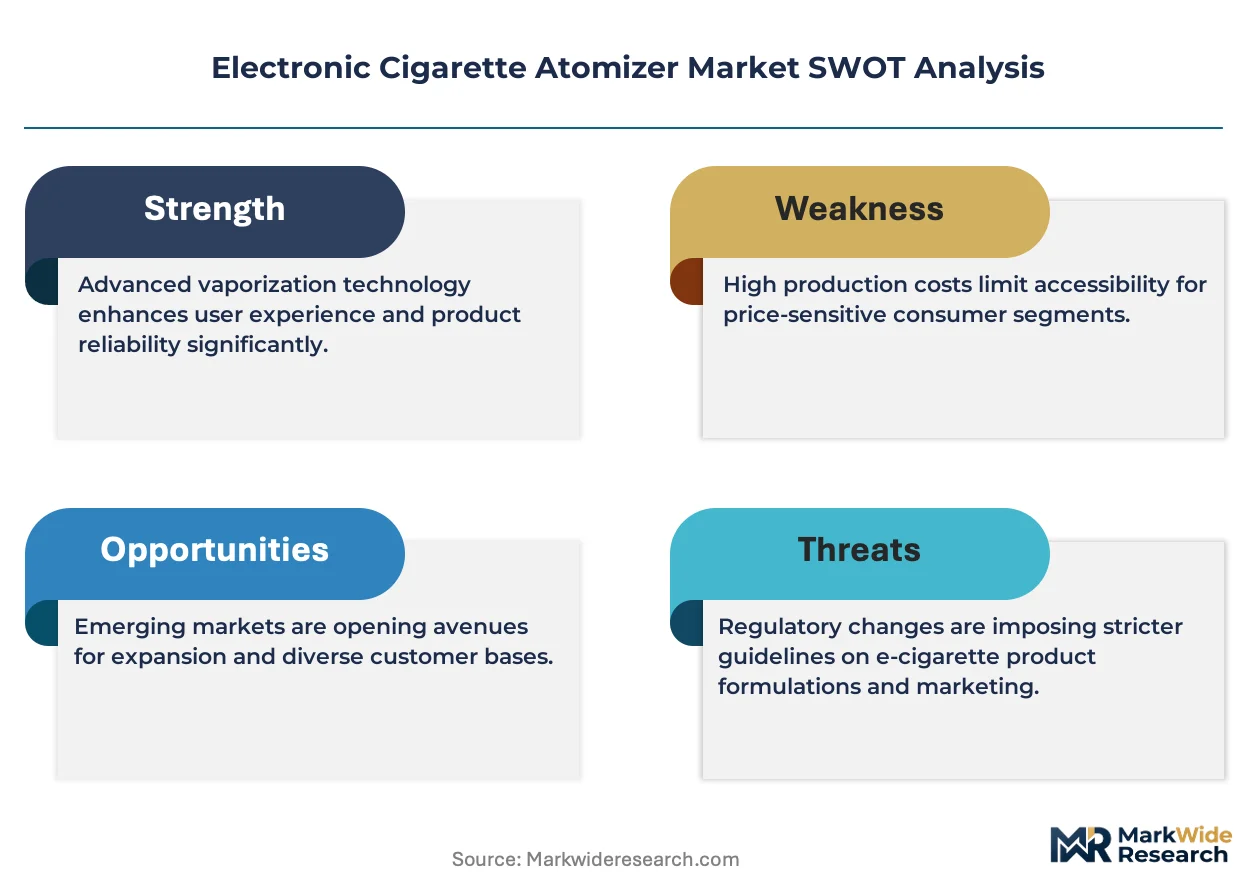
Ceramic coil heating technology is compressing wire-wick legacy architectures while FDA premarket authorization requirements force portfolio rationalization across flavor and nicotine strength configurations.
Growth Catalysts
- Adult Tobacco Transition:Combustible cigarette smokers seeking reduced-harm alternatives drive hardware refresh cycles and tank system upgrades.
- TPD-Compliant Tank Engineering:EU notification protocols and emission testing standards create compliant product lines that unlock member state distribution.
- Synthetic Nicotine Classification Debates:Evolving regulatory frameworks in the US expand addressable hardware markets beyond traditional tobacco-derived nicotine constraints.
Market Restraints
- Stainless Steel Price Volatility:Atomizer chassis and coil housing materials face commodity input cost swings that compress margin structures.
- Guangdong Supply Concentration:Shenzhen-centered manufacturing clusters create single-region dependency risk for global brand supply security.
- FDA Authorization Timelines:Premarket tobacco product application review periods extend product launch windows and tie up R&D capital.
Strategic Opportunities
- India Distribution Expansion:Underpenetrated retail channels and emerging vape shop networks offer first-mover positioning ahead of formal regulatory codification.
- Pod-Mod Convergence:Hybrid form factors blending disposable convenience with rebuildable customization capture dual user segment demand.
- Battery Safety Standard Harmonization:UN 38.3 and IEC 62133 certification alignment enables cross-border shipment simplification and warehouse consolidation.
Industry Challenges
- Ceramic Sintering Expertise Gap:Specialized porous substrate engineering talent concentrates in Smoore-adjacent supply chains, constraining competitor R&D velocity.
- Flavor Ban Compliance Complexity:State-level restrictions in Massachusetts and California force SKU proliferation and inventory fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Cigarette Atomizer Market |
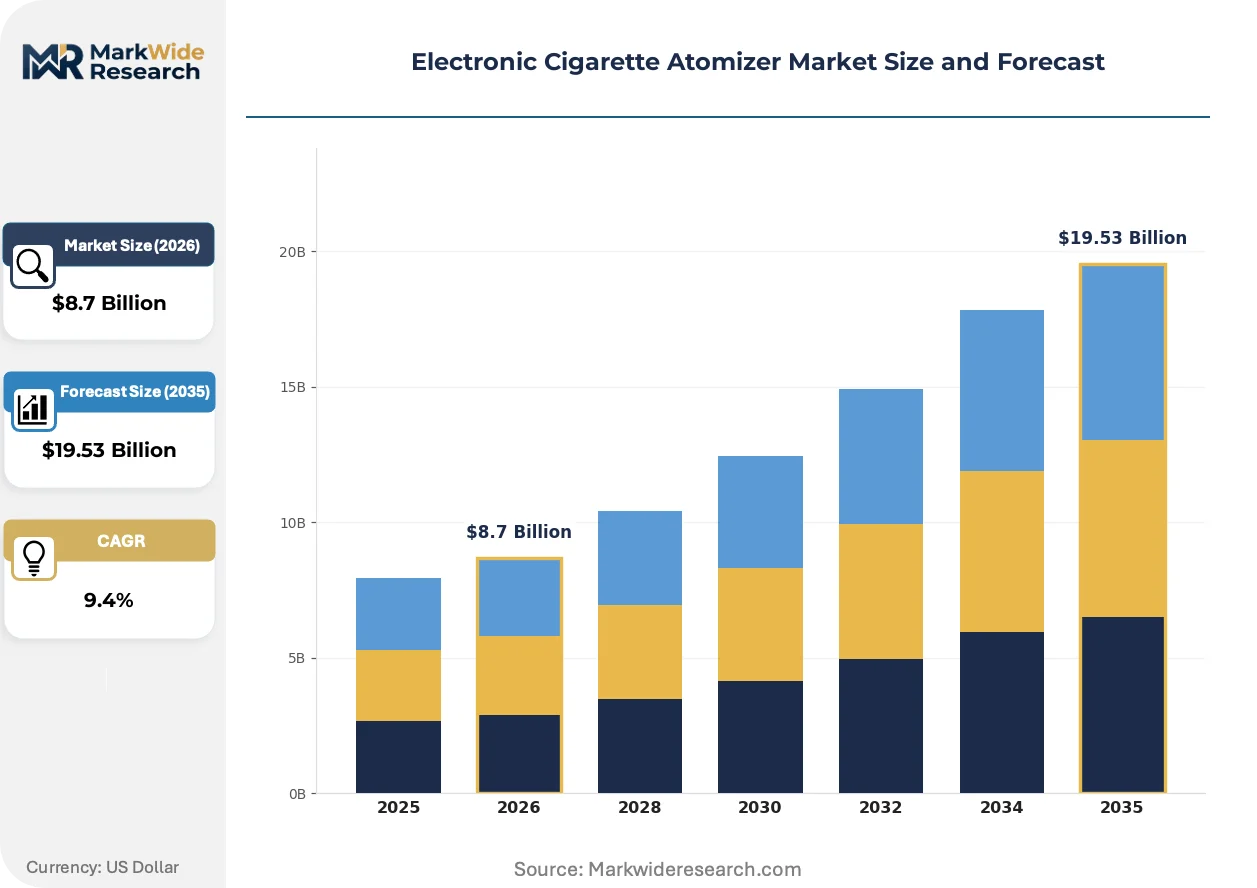
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rebuildable, Disposable, Tank, Drip Tip Material: Glass, Stainless Steel, Aluminum, Plastic Connection Type: Screw, Magnetic, Push-fit, Threaded Coil Resistance: Low Ohm, High Ohm, Sub-Ohm, Standard Ohm |
| Companies Covered | SMOK, Innokin, Smoore, GeekVape, Voopoo, Shenzhen First Union Technology, Hangsen Group, Shenzhen KangerTech Technology, Shenzhen IVPS Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Cigarette Atomizer Market Trends and Innovations
Heating element materials, regulatory testing protocols, and distribution channel structures are undergoing simultaneous transformation that redefines competitive differentiation.
Ceramic coil substrates with engineered porosity gradients deliver thermal consistency across e-liquid viscosity ranges. Premium device manufacturers are migrating from traditional kanthal wire-wick assemblies toward these sintered structures. The shift compresses aftermarket coil replacement revenue while locking users into proprietary pod ecosystems.
REACH substance restrictions and EU Tobacco Products Directive emission thresholds now govern heavy metal leaching and thermal degradation byproduct testing. Hardware vendors must redesign airflow geometries and wicking densities to meet notified body certification. Sub-ohm tank configurations face disproportionate compliance burden given higher power outputs and aerosol volumes.
Convenience store chains now account for accelerating disposable segment volume as vape shops consolidate under multi-state operators. Direct-to-consumer online channels face payment processor restrictions and age verification mandates that favor brick-and-mortar expansion. California and New York metro areas exhibit the most pronounced channel mix rotation toward retail gas station networks.
Electronic Cigarette Atomizer Market Segmentation
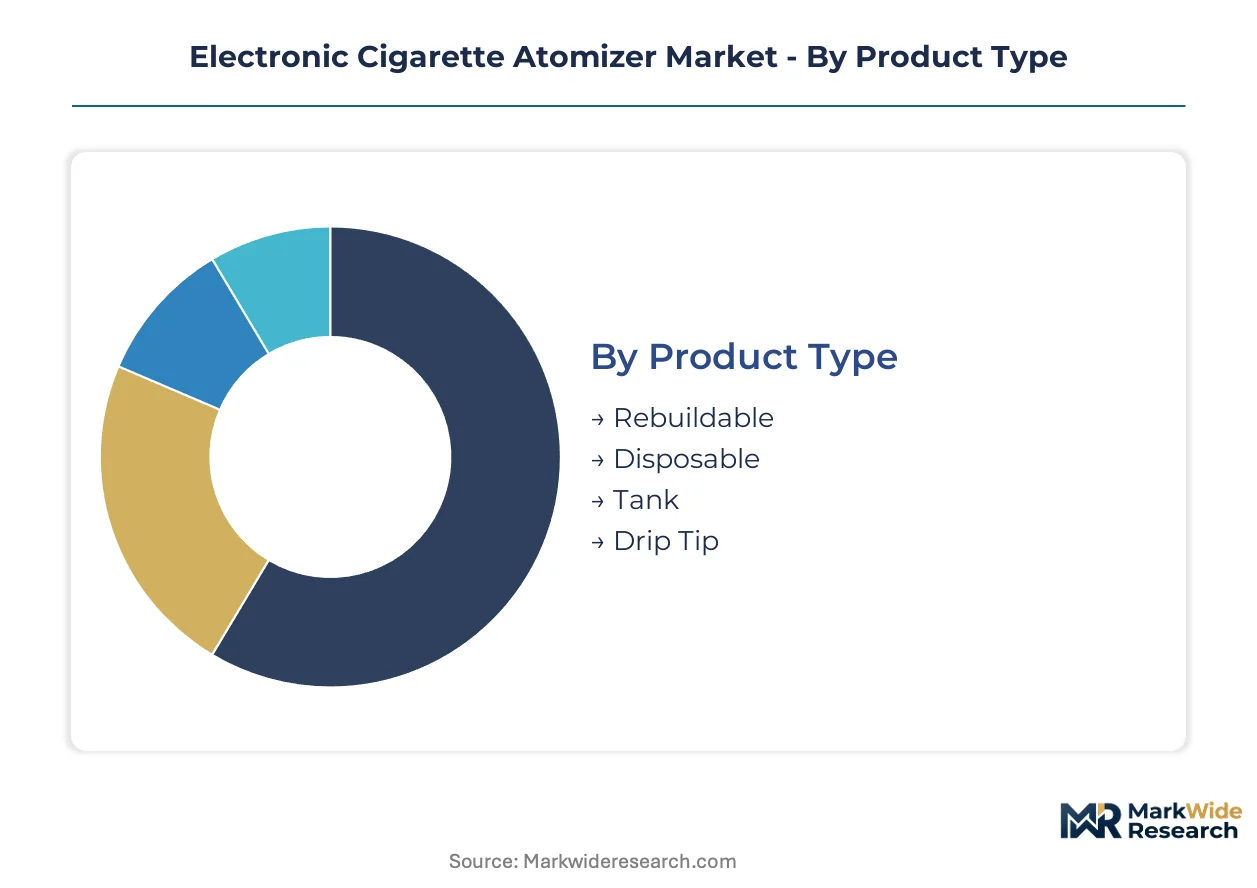
Atomizer segmentation determines regulatory compliance pathways, manufacturing cost structures, and distribution channel strategies. Each dimension—product architecture, material composition, connection mechanism, and coil specification—creates distinct margin profiles and user loyalty patterns.
Product Type:
Use-case spectrum spans enthusiast customization through convenience-driven disposability, with tank systems occupying the mainstream commercial volume.
- Rebuildable:Coil-building culture sustains premium pricing through aftermarket accessory ecosystems and user-generated content communities. Demand concentrates in North American and European vape shops where hands-on education drives hardware attachment rates.
- Disposable:Convenience-store channel acceleration reduces maintenance barriers for transitioning smokers. Volume clusters in California and New York metro gas station networks facing payment processor restrictions on online alternatives.
- Tank:Refillable reservoir systems balance customization with operational simplicity for intermediate users.
- Drip Tip:Direct-dripping configurations serve flavor-purist segments prioritizing immediate wick saturation control.
The dominant share belongs to Disposable, while Rebuildable is closing the gap fastest through enthusiast community amplification.
Material:
Cost tier stratification separates premium thermal performance from mass-market durability requirements.
- Stainless Steel:Chassis and coil housing standard with commodity input cost exposure compressing margin structures. Guangdong supply concentration creates single-region dependency risk for global brand security.
- Glass:Pyrex and borosilicate reservoirs dominate visibility-prioritized segments with thermal shock resistance specifications. EU TPD emission testing protocols favor glass over plastic for heavy metal leaching compliance.
- Aluminum:Lightweight chassis target portable and outdoor use cases with anodized finish differentiation.
- Plastic:Polycarbonate and PCTG variants serve entry-price tiers with impact resistance trade-offs.
Stainless Steel commands the installed base, though Glass is expanding most quickly through regulatory compliance premiums.
Connection Type:
Volume concentration favors standardized threading for cross-brand compatibility, while proprietary mechanisms lock users into ecosystem captivity.
- Screw:Traditional 510-threading maintains universal compatibility across battery mods and atomizer bases. Demand persists in enthusiast rebuildable segments valuing hardware interchangeability.
- Magnetic:Snap-fit mechanisms accelerate pod-system adoption in convenience channels with reduced mechanical failure modes.
- Push-fit:Friction-based insertion dominates disposable and closed-pod architectures for manufacturing simplicity.
- Threaded:Precision-machined connections serve sub-ohm tank segments requiring airtight seals at high wattage outputs.
Screw connections retain the largest installed base, yet Magnetic is gaining share fastest through pod-mod convergence form factors.
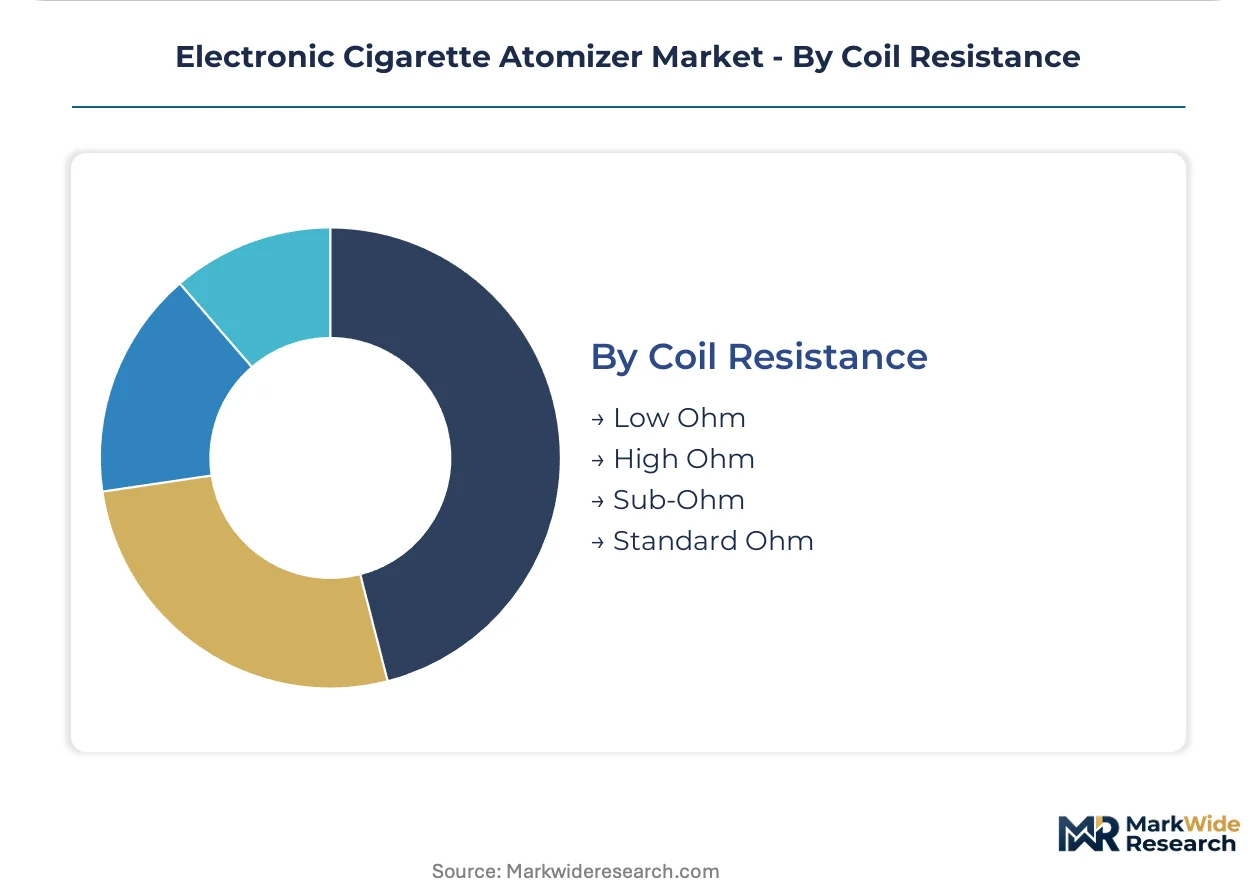
Coil Resistance:
Application-driven segmentation separates mouth-to-lung cigarette mimicry from direct-to-lung vapor density optimization.
- Sub-Ohm:Below-1.0-ohm configurations dominate direct-to-lung inhalation with ceramic coil migration displacing wire-wick legacy architectures. FDA premarket authorization burdens fall disproportionately on high-power output systems.
- Standard Ohm:1.0-ohm-plus resistances retain significance in mouth-to-lung systems mimicking conventional cigarette draw behavior. China NMPA domestic standards and SAMR export certification favor conservative power specifications.
- Low Ohm:Ultra-low resistance serves competitive cloud-chasing segments with thermal management complexity.
- High Ohm:Elevated resistance extends battery life for portable pod systems with reduced vapor volume priorities.
Sub-Ohm holds the revenue concentration, while Standard Ohm is climbing the fastest through TPD-compliant tank engineering and smoker transition demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports atomizer hardware to the United States and European Union, with Shenzhen-centered manufacturing clusters supplying branded distributors and contract manufacturers across both destination markets.
United States
Adult smokers transitioning from combustible tobacco drive hardware refresh demand, particularly in California and New York metro retail networks. The FDA's premarket tobacco product application pathway constrains flavor availability and extends authorization timelines for new atomizer submissions. Los Angeles and New York City gas station chains now dominate disposable segment volume as online payment processors restrict direct-to-consumer alternatives.
China
Domestic manufacturing capacity expansion and export certification requirements sustain dual-market positioning for Shenzhen-based producers. The NMPA and SAMR national standards govern quality benchmarks and overseas shipment documentation. The Pearl River Delta concentration of ceramic sintering expertise and coil housing fabrication creates supply security dependencies for global brand procurement.
Germany
Mouth-to-lung system preferences among smoker transition demographics sustain standard-ohm tank demand across vape shop and retail pharmacy channels. REACH substance restrictions and EU Tobacco Products Directive emission thresholds force airflow geometry redesigns for heavy metal leaching compliance. The North Rhine-Westphalia industrial corridor hosts distribution warehousing serving Benelux and Scandinavian re-export markets.
United Kingdom
Rebuildable enthusiast communities in London and Manchester sustain premium coil-building accessory ecosystems through specialized retail. The Medicines and Healthcare products Regulatory Agency notification protocols align with EU TPD child-resistant packaging and emission testing standards. Midlands-based logistics hubs consolidate pan-European distribution for TPD-compliant tank capacities.
India
Emerging vape shop networks in Mumbai and Delhi-NCR offer first-mover positioning ahead of formal regulatory codification for electronic nicotine delivery systems. The Central Drugs Standard Control Organization and BIS standards create compliance uncertainty that fragments import channel structures. Karnataka and Maharashtra retail channels show accelerating hardware penetration among urban adult smoker demographics.
Electronic Cigarette Atomizer Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a fragmented vendor base where no single entity commands dominant share. Shenzhen-centered manufacturing clusters supply branded downstream distributors while European and North American entities focus on compliance documentation and retail network penetration. Three archetypes define competitive positioning: vertically integrated ceramic substrate producers, ruggedized chassis specialists, and TPD-compliance engineering houses. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms secure sintering expertise or distribution channel control.
Among China-based fabricators, Smoore and GeekVape occupy positions within the integrated manufacturing tier, with Shenzhen First Union Technology representing the contract manufacturing archetype. These entities exemplify the Pearl River Delta concentration where ceramic coil engineering and metal chassis fabrication capabilities cluster. Innokin anchors European-facing compliance engineering through TPD-aligned product configurations. The competitive dynamic pits captive supply chain control against regulatory documentation specialization across geographically segmented demand pools.
| Leading Market Players |
|---|
| SMOK |
| Innokin |
| Smoore |
| GeekVape |
| Voopoo |
| Shenzhen First Union Technology |
| Hangsen Group |
| Shenzhen KangerTech Technology |
| Shenzhen IVPS Technology |
| Others |
Pricing and Supply Chain Analysis
Shenzhen-centered ceramic sintering capacity concentrates upstream margin capture with Smoore-adjacent supply chains, leaving downstream brands to compete on chassis differentiation and compliance documentation rather than heating element technology. This concentration transfers pricing power toward substrate producers while atomizer assemblers absorb stainless steel commodity volatility and FDA authorization cost burdens.
Pricing Analysis
Ceramic coil generation pricing gaps separate legacy wire-wick assemblies from sintered substrate systems and emerging porous-metal hybrid architectures. Three-tier pricing structure across premium ceramic, standard wire-wick, and economy plastic-reservoir configurations dominates transactional markets. Price differentiation rests on FDA premarket authorization tier and REACH emission certification grade. Pricing pressure stems from Guangdong manufacturing cluster competition compressing entry-tier margins. Convenience-store disposable buyers exhibit highest price sensitivity; rebuildable enthusiasts demonstrate lowest sensitivity due to coil-building accessory attachment.
Supply Chain Analysis
Stainless steel feedstock and ceramic powder inputs anchor atomizer cost structures with nickel-chromium alloy pricing transmitting directly to coil housing expenses. Manufacturing concentrates in China, Malaysia, and Indonesia with Shenzhen maintaining dominant ceramic substrate fabrication. Raw material dependencies include nickel ore, zirconium dioxide, and borosilicate glass. Single-source vulnerability concentrates in Smoore-adjacent sintering expertise. Distribution runs through branded OEM procurement, contract manufacturing arrangements, and European compliance-engineering intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronic cigarette atomizers face substitution defense imperatives against heated tobacco products and nicotine pouch formats that bypass vaporization hardware entirely. Incumbents must navigate this threat while securing ceramic substrate supply and regulatory authorization pathways.
For Market Incumbents: Insulate core revenue through backward integration into ceramic sintering capacity or exclusive substrate supply agreements with Shenzhen producers. Deepen FDA premarket authorization portfolios to defend against flavor-restriction-driven product obsolescence. Prioritize TPD-compliant tank engineering for European market retention against heated tobacco incursion. For New Entrants and Emerging Players: Build out India distribution infrastructure ahead of CDSCO regulatory codification, targeting Mumbai and Delhi-NCR vape shop networks with mouth-to-lung standard-ohm configurations. Capture smoker transition demographics underserved by incumbent pod-system saturation. Deploy compliance-documentation partnerships as primary go-to-market mechanism. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European TPD-compliance engineering houses possessing notified body relationships and member-state distribution licenses. Long-term viability hinges on ceramic technology lock-in duration and FDA authorization portfolio breadth. Watch synthetic nicotine classification rulings as hardware demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Substrate Backward Integration | Captures margin pool concentrated in Shenzhen sintering expertise. |
| FDA Premarket Authorization Portfolio Expansion | Secures commercial viability against flavor-ban regulatory fragmentation. |
| TPD-Compliant Tank Capacity Engineering | Unlocks Benelux and Scandinavian re-export distribution channels. |
| India Distribution Network Buildout | Positions ahead of CDSCO regulatory codification and vape shop consolidation. |
| Battery Safety Certification Harmonization | Enables UN 38.3 and IEC 62133 cross-border shipment consolidation. |
Research Methodology
The analysis maps rebuildable enthusiast, disposable convenience, and tank system segments, each validated through hardware procurement managers at vape shop chains, ceramic substrate engineers at Shenzhen fabricators, and regulatory affairs leads navigating FDA premarket pathways. Primary interviews with European TPD compliance consultants and US convenience-store category buyers combined with secondary validation against SAMR export certification databases, EU TPD notification registries, and FDA Center for Tobacco Products submission records. Bottom-up volume triangulation across product architectures reconciled with top-down value estimates from trade flow documentation.
Assumptions held FDA authorization timeline distributions and ceramic coil adoption curves fixed while varying stainless steel price scenarios and India regulatory codification timing across sensitivity runs. Segmentation dimensions modeled include product architecture, coil resistance specification, material composition tier, and regional regulatory cluster. CAGRs derived from installed base refresh cycle analysis and smoker transition rate projections. Forecast inputs incorporated REACH substance restriction phase-in schedules and China NMPA domestic quality standard enforcement intensity.
Practitioners should monitor FDA synthetic nicotine classification rulings and India CDSCO enforcement discretion for early signals of hardware demand revision. Cross-checking against customs export data from Guangdong ports and EU TPD notification volume trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco Products
Handmade Cigars Market
Tobacco Products
E-Cigarette and Vaping Market
Tobacco Products
GCC Cigarette Lighter Market
Tobacco Products
Disposable E-Cigarettes Market
Tobacco Products
West Africa Cigarettes Market
Tobacco Products
Luxury Cigarette Market
Tobacco Products
Middle East and Africa E-Cigarettes Market
Tobacco Products
Roll-Your-Own Tobacco Products Market
Tobacco Products
Flavored Cigar Market
Tobacco Products
Liquor Flavored Cigars Market
Tobacco Products
Cigar Tubes Market
Tobacco Products
Japan Heated Tobacco Products Market
Tobacco Products
Global E-Cigarettes Market
Tobacco Products
Philippines E-Cigarette and Vape Market
Tobacco Products
United States Pipe Tobacco Market
Tobacco Products
Global Flavor Capsule Cigarette Market