
 Watch Market | 2026-2036
Watch Market Size, Share, and Industry Trends Forecast 2026-2036
Watch Market Intelligence
Chronometer certification under ISO 3159 is redrawing competitive boundaries in precision timekeeping. Rolex leverages its in-house foundry capacity to sustain vertical integration across gold alloys and movement components. Seiko anchors Japanese mechanical watch production with proprietary Spring Drive technology, while Omega competes through Master Chronometer resistance to magnetic fields up to 15,000 gauss.
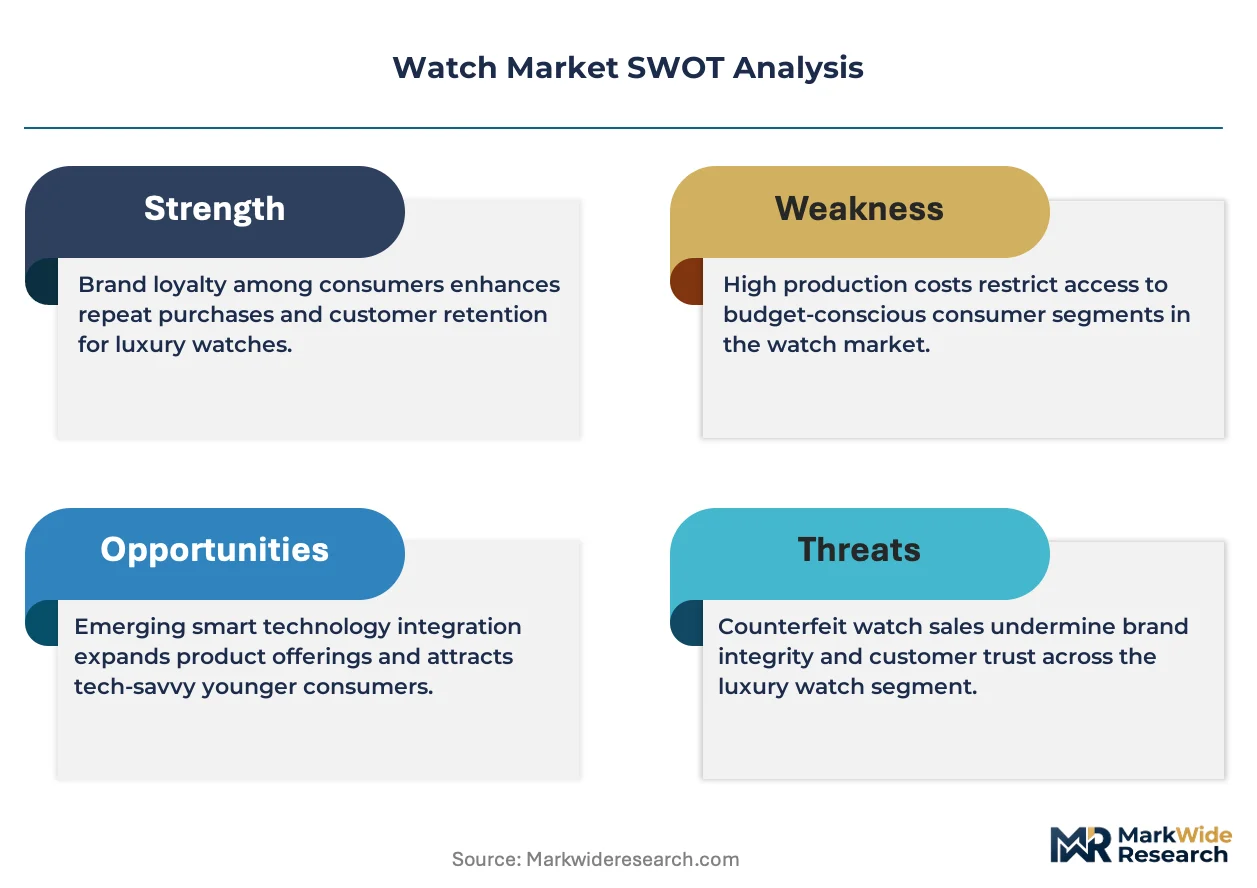
A watch is a portable timekeeping instrument comprising a mainspring or quartz oscillator, gear train, escapement, and display mechanism, engineered to maintain accuracy within defined tolerances for commercial, ceremonial, or professional synchronization purposes. Stainless steel cases dominate volume manufacturing for everyday users, while ceramic materials penetrate luxury sports segments due to scratch resistance and hypoallergenic properties. Smart features with GPS and heart rate monitoring represent the fastest-expanding margin pool, though analog movements retain collector premiums.
Swissmedic oversees medical-grade wearable claims, while EU REACH restricts nickel and cadmium in watch components, forcing material substitutions across European distribution channels. The Swiss Federal Institute of Metrology enforces chronometer testing protocols that gate premium positioning. Stakeholders must monitor how FDA device classification criteria apply to biometric-enabled smartwatches entering health-adjacent channels.
Market Dynamics
Chronometer certification and smart sensor integration are compressing traditional boundaries between mechanical heritage and digital functionality, forcing manufacturers to maintain dual competency in Swiss precision engineering and Shenzhen electronics miniaturization.
Growth Catalysts
- EU REACH nickel restrictions:Material substitution mandates are accelerating ceramic and titanium adoption in luxury sports models, creating premium positioning for compliant manufacturers.
- Medical-grade wearable claims:Swissmedic oversight of biometric-enabled devices is opening health-adjacent distribution channels for chronometer-certified smart hybrids.
- Shenzhen electronics corridors:Concentrated sensor manufacturing capacity is reducing smart module procurement costs for mid-tier Swiss brands.
Market Restraints
- Swiss movement supply concentration:ETA and Sellita control dominant share of mechanical calibers, creating bottlenecks for independent brands seeking volume.
- Rare earth magnet vulnerability:Neodymium supply chain exposure to processing concentration in China threatens Master Chronometer anti-magnetic component sourcing.
- Chronometer testing capacity:COSC and METAS certification queue times extend 8-14 months, constraining new model launch velocity.
Strategic Opportunities
- India PLI scheme extension:Manufacturing incentive frameworks for precision engineering could attract Swiss assembly operations to reduce import duties.
- Biometric-FDA convergence:FDA device classification clarity for arrhythmia detection creates pathway for medical-grade smartwatch reimbursement channels.
- Direct-to-collector platforms:Auction houses and certified pre-owned digital marketplaces are disintermediating traditional authorized dealer networks.
Industry Challenges
- Horological skill attrition:Swiss watchmaking schools graduate fewer movement assemblers than retirement rates, compressing specialist labor pools.
- Dual certification complexity:Brands pursuing both COSC chronometer and METAS Master Chronometer credentials face overlapping test protocol reconciliation.
- Legacy system integration:Analog manufacturers embedding smart modules struggle with battery life optimization against traditional case dimension constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Watch Market |
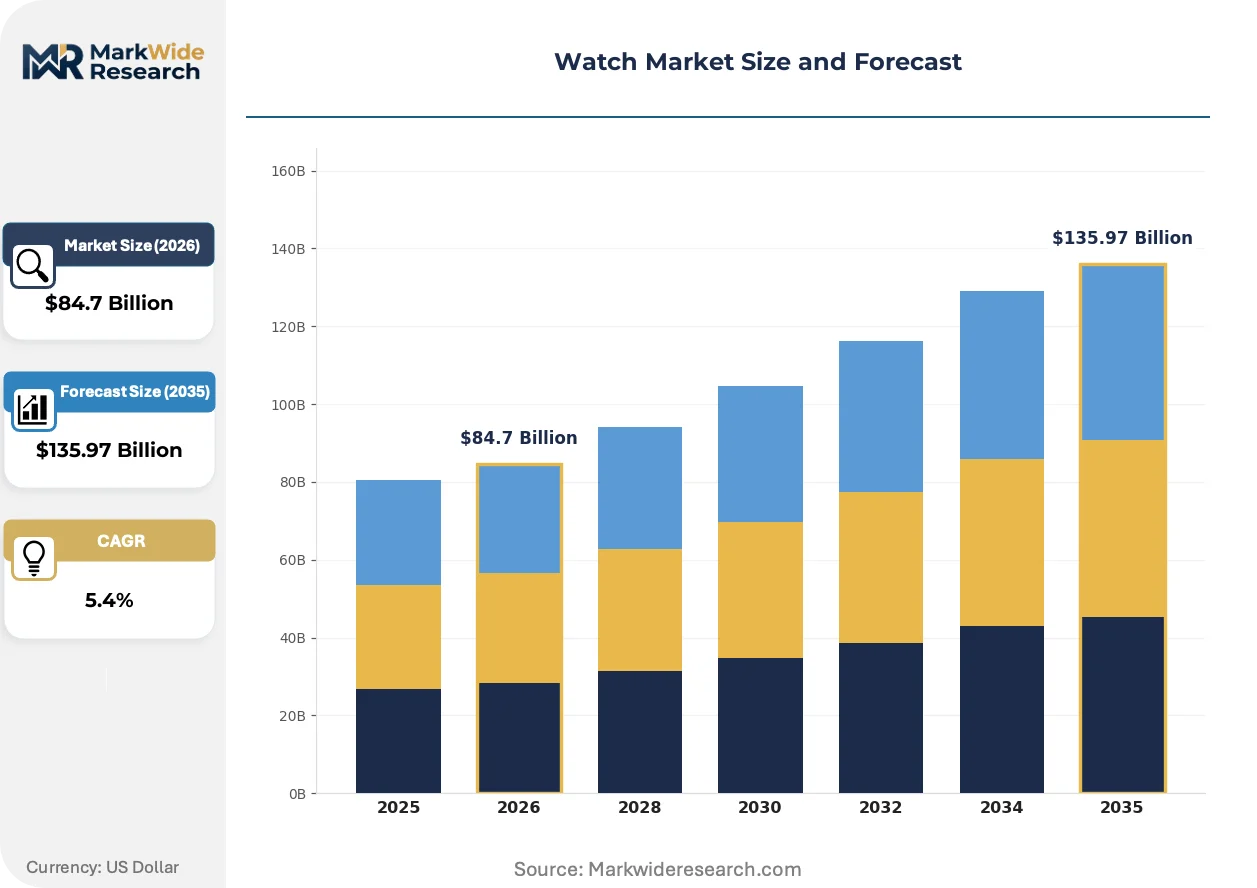
| Market Size in 2026 | $84.7 Billion |
| Market Size in 2035 | $135.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog, Digital, Smart, Hybrid Material: Stainless Steel, Leather, Plastic, Ceramic Feature: Water Resistant, GPS, Heart Rate Monitor, Bluetooth Connectivity Customer Type: Luxury Buyers, Everyday Users, Fitness Enthusiasts, Collectors |
| Companies Covered | Vacheron Constantin, Omega, Rolex, Tissot, Longines, Patek Philippe, Cartier, Seiko, Audemars Piguet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Watch Market Strategic Shifts & Innovations
Silicon escapement components and solid-state battery chemistry are redefining durability benchmarks, while regulatory fragmentation across medical device classification is forcing parallel certification strategies.
Silicon hairsprings and escape wheels are eliminating magnetic sensitivity and lubrication dependency in mechanical movements. High-horology manufacturers are adopting this material for tourbillon and perpetual calendar complications. The technology is miniaturizing traditional escapement geometries while maintaining isochronism across temperature ranges.
EU REACH Annex XVII nickel release limits are forcing caseback and buckle material substitutions across European distribution. Manufacturers are migrating to grade 5 titanium and ceramic composites for skin-contact components. Swiss brands with in-house foundry capacity are accelerating proprietary alloy development to maintain EU market access.
Collector purchasing has migrated toward certified pre-owned platforms and auction-based price discovery. Authorized dealer networks are losing price-setting power to transparent transaction databases. This channel rotation is most pronounced in Geneva, Hong Kong, and Dubai trading centers where secondary market liquidity concentrates.
Watch Market Segmentation
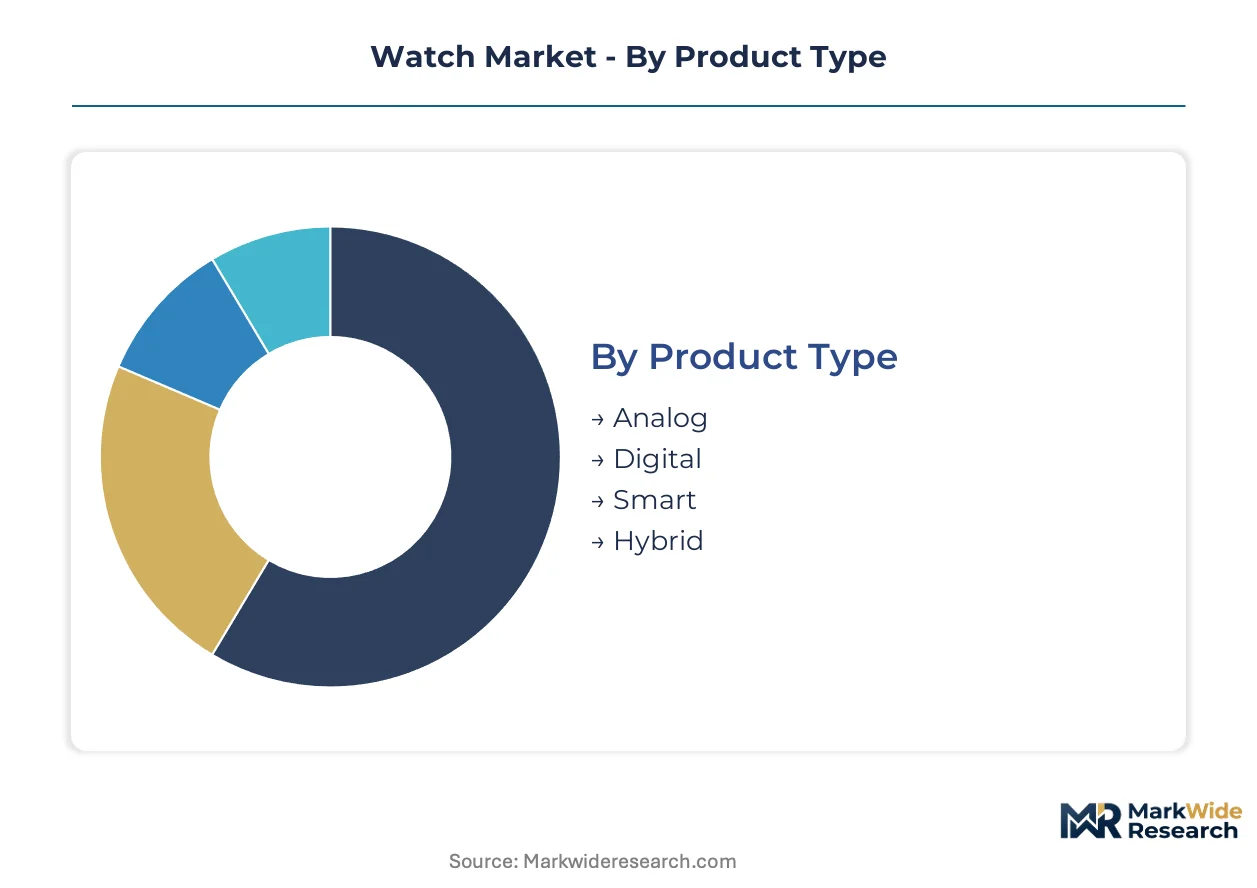
Segmentation in the watch market separates volume manufacturing from premium positioning, revealing how Swiss precision engineering and Shenzhen electronics miniaturization serve divergent customer bases. Material choices and certification tiers determine distribution channel access and margin capture across domestic and export markets.
Product Type:
Analog and smart variants dominate export flows to Swiss and East Asian collector markets, while digital and hybrid formats serve price-sensitive domestic consumption in emerging economies.
- Analog:Mechanical movements with mainspring power reserves and gear train escapements define this category. Demand concentrates in Geneva and Hong Kong trading centers where COSC chronometer certification gates premium positioning. Swiss movement supply bottlenecks from ETA and Sellita constrain independent brand volume expansion.
- Smart:GPS-enabled and biometric-sensor modules integrate with solid-state battery chemistry. Shenzhen electronics corridors supply concentrated sensor manufacturing capacity, reducing procurement costs for mid-tier brands seeking health-adjacent distribution channels under Swissmedic oversight.
- Digital:Quartz oscillator timekeeping with LCD or LED displays serves everyday utility segments. Battery replacement cycles and module standardization drive aftermarket service revenue.
- Hybrid:Analog display faces conceal smart connectivity and notification functions. Legacy system integration challenges persist around battery optimization against traditional case dimensions.
Analog holds the largest share; momentum sits with smart variants as FDA device classification clarity opens reimbursement channels.
Material:
Cost tier stratification separates luxury sports positioning from mass-market accessibility, with EU REACH compliance mandates forcing substitution patterns across skin-contact components.
- Stainless Steel:Austenitic grades dominate volume manufacturing for everyday users due to corrosion resistance and machining compatibility. Grade 316L remains the reference standard for case and bracelet production.
- Ceramic:Zirconium dioxide composites deliver scratch resistance and hypoallergenic properties for luxury sports segments. EU REACH Annex XVII nickel release limits accelerate adoption as manufacturers abandon non-compliant caseback and buckle alloys.
- Leather:Calfskin and alligator straps serve dress watch applications where formal aesthetics override sport durability. Vegetable tanning processes face sustainability scrutiny from EU Green Deal supply chain disclosure requirements.
- Plastic:Polycarbonate and resin cases enable sub-$50 price points for children's and disposable fashion segments. Margins compress under petroleum feedstock volatility.
Stainless steel commands volume leadership; ceramic gains share fastest among compliant manufacturers targeting European distribution.
Feature:
Application-driven segmentation maps functional requirements to customer willingness-to-pay, with medical-grade claims requiring parallel regulatory strategies across Swissmedic and FDA jurisdictions.
- Water Resistant:ISO 22810 depth ratings from 30 to 200 meters segment recreational diving from splash-proof dress applications. Gasket material selection determines long-term seal integrity under thermal cycling.
- Heart Rate Monitor:Photoplethysmography sensors enable arrhythmia detection claims that trigger FDA device classification scrutiny. Biometric-FDA convergence creates reimbursement pathway potential for chronometer-certified smart hybrids.
- GPS:Multi-band satellite reception supports activity tracking and emergency location services. Antenna integration challenges persist in metal case environments.
- Bluetooth Connectivity:Low-energy protocol stacks enable smartphone notification relay and firmware updates. Shenzhen module suppliers concentrate BLE chipset sourcing.
Water resistance remains the baseline specification; heart rate monitoring climbs fastest as health-adjacent channels expand.
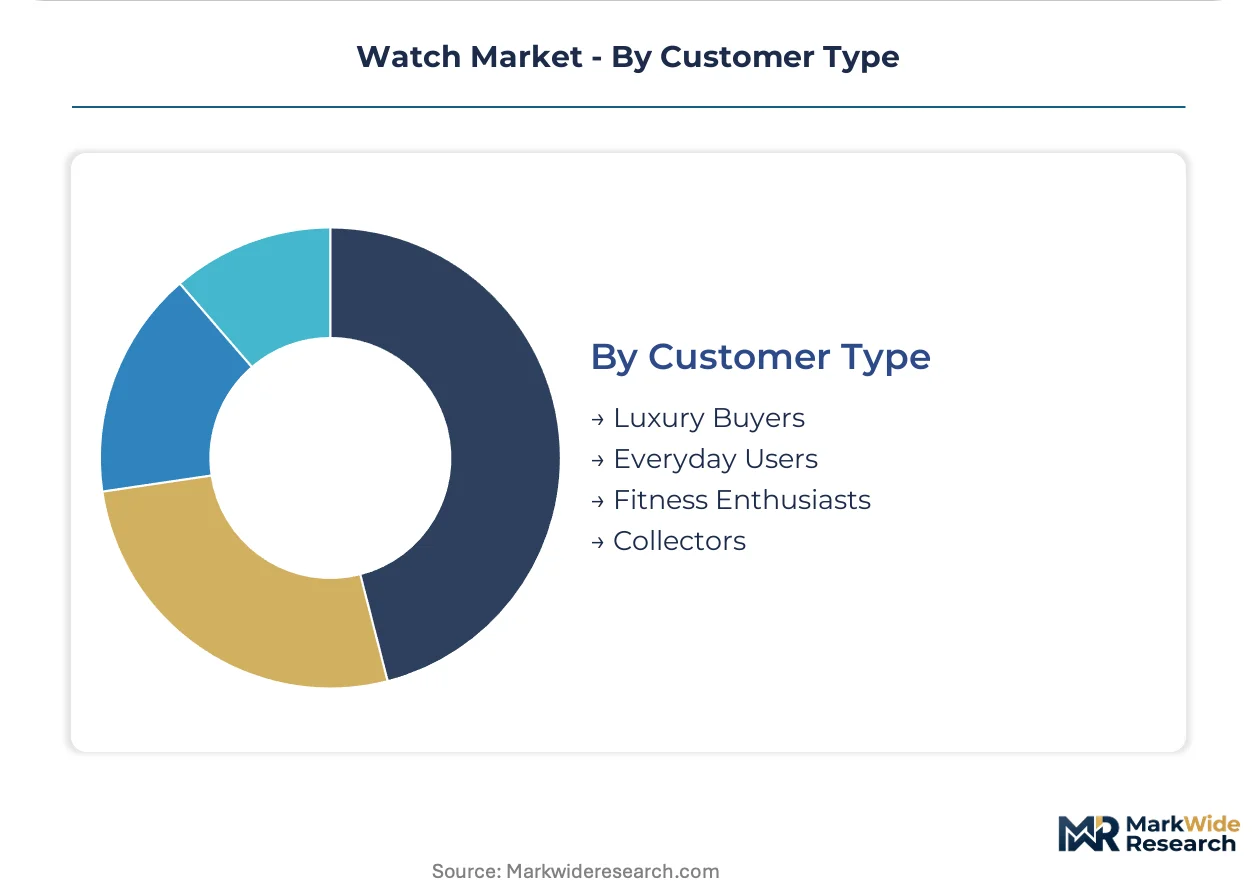
Customer Type:
Volume scale and margin concentration diverge sharply across collector premiums versus fitness enthusiast procurement patterns, with certified pre-owned platforms disintermediating traditional authorized dealer networks for luxury segments.
- Luxury Buyers:Brand heritage and vertical integration into in-house foundry capacity sustain positioning. Geneva, Hong Kong, and Dubai trading centers concentrate secondary market liquidity and price discovery.
- Collectors:Limited editions and complications command auction premiums independent of retail pricing. Horological skill attrition in Swiss watchmaking schools compresses specialist labor availability for servicing vintage pieces.
- Everyday Users:Reliability and service network accessibility drive purchase decisions. Volume manufacturing in Asian assembly operations serves price-sensitive demand.
- Fitness Enthusiasts:Training load metrics and recovery tracking prioritize sensor accuracy over mechanical heritage. Replacement cycles accelerate versus traditional ownership patterns.
Everyday users generate the highest unit volumes; collectors capture the steepest margin expansion through direct-to-consumer platform migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme extension for precision engineering is attracting Swiss assembly operations seeking tariff relief. Manufacturing incentive frameworks reshape assembly location decisions across the sector.
Switzerland
Geneva and Biel concentrate high-horology production where COSC chronometer certification gates premium positioning. Swissmedic oversees medical-grade wearable claims entering health-adjacent distribution. The Swiss Federal Institute of Metrology enforces testing protocols that sustain the country's precision engineering reputation.
China
Shenzhen electronics corridors supply concentrated sensor manufacturing capacity for smart module procurement. MIIT standards govern telecommunications-enabled wearables while GB standards apply to battery safety in consumer devices. Dongguan assembly clusters serve mid-tier brands seeking cost-optimized production.
United States
FDA device classification scrutiny applies to arrhythmia detection claims in biometric-enabled smartwatches. FCC authorization governs GPS and Bluetooth connectivity modules. California and Texas concentrate health-tech wearable development teams targeting reimbursement channels.
Japan
Spring Drive technology anchors Japanese mechanical watch production against Swiss competition. METI industrial policy supports precision manufacturing clusters in the Nagoya region. Seiko's proprietary movement development exemplifies domestic horological capability retention.
Germany
EU REACH Annex XVII nickel release limits force material substitutions in caseback and buckle components distributed across European channels. Glashütte's watchmaking tradition represents eastern German precision engineering heritage. KBA-equivalent consumer protection standards apply to product safety claims.
Watch Market Key Industry Players
Player mix skews toward heritage Swiss manufacturers with in-house movement production capability. Market structure concentrates around vertically integrated specialists controlling alloy foundries and caliber assembly. Three archetypes dominate: chronometer-certified mechanical houses, sensor-integrated smart hybrid developers, and volume quartz assemblers. Competitive moves center on foundry capacity expansion and dual-certification pursuit of both COSC and METAS credentials.
Among Geneva-based heritage manufacturers, Vacheron Constantin and Patek Philippe exemplify high-horology positioning through complications and limited editions. Rolex occupies a position as the scale leader in chronometer-certified mechanical production. Seiko represents Japanese vertical integration into proprietary escapement technologies. These anchors illustrate how geographic origin and production depth stratify competitive tiers.
| Leading Market Players |
|---|
| Vacheron Constantin |
| Omega |
| Rolex |
| Tissot |
| Longines |
| Patek Philippe |
| Cartier |
| Seiko |
| Audemars Piguet |
| Others |
Cost & Logistics Intelligence
Long-term movement supply contracts between Swiss independents and ETA/Sellita lock in caliber access while capping price volatility for mechanical tiers. These arrangements bind assembly capacity to chronometer certification timelines, creating parallel visibility into both component flows and finished goods pricing across Geneva and Biel manufacturing clusters.
Pricing Analysis
Certification level creates the primary spread between mass-market quartz and COSC-validated mechanical pieces. Three-tier pricing structure across chronometer-certified, standard automatic, and entry quartz levels reflects divergent labor intensity and testing queue investments. Pricing pressure stems from Shenzhen smart module cost compression bleeding into hybrid segments. Everyday users exhibit highest price sensitivity, while collectors absorb premiums for METAS Master Chronometer credentials.
Supply Chain Analysis
Switzerland and China anchor watch production through divergent specialization patterns. Swiss foundries supply gold alloys and mechanical calibers; Shenzhen electronics corridors feed sensor modules and solid-state batteries. Rare earth magnet processing concentration in China threatens Master Chronometer anti-magnetic component sourcing. Distribution runs through authorized dealer networks facing disintermediation from certified pre-owned platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Movement assembler retirement rates exceeding Swiss watchmaking school graduation volumes compress specialist labor availability, constraining expansion capacity for heritage manufacturers and servicing networks alike.
For Market Incumbents: Fortify chronometer certification pipelines by expanding METAS testing partnerships to bypass COSC queue bottlenecks. Secure captive titanium and ceramic foundry capacity to ensure EU REACH compliance without supplier dependency. Smart hybrid entrants threaten traditional analog margins through health-adjacent channel capture. For New Entrants and Emerging Players: Anchor in India PLI scheme jurisdictions to access tariff relief on precision assembly operations. Target fitness enthusiast segments where sensor accuracy outweighs mechanical heritage premiums. Pursue Swissmedic biometric claims pathway to unlock reimbursement channel access ahead of FDA convergence clarity. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated specialists with in-house caliber production and foundry control. Long-term viability hinges on backward integration depth that insulates against movement supply concentration. Monitor COSC and METAS certification queue length divergence as inflection signal for launch velocity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Pursuit | Simultaneous COSC and METAS credentials compress competitive differentiation timelines for precision positioning. |
| Ceramic Foundry Investment | In-house zirconium dioxide capacity secures EU REACH compliance while capturing luxury sports segment premiums. |
| Smart Module Integration | Shenzhen-sourced biometric sensors enable health-adjacent distribution under Swissmedic oversight. |
| Direct-to-Collector Platform Launch | Certified pre-owned marketplaces disintermediate authorized dealer networks in Geneva and Hong Kong trading centers. |
| India PLI Assembly Expansion | Precision engineering incentives attract Swiss operations seeking import duty reduction on finished mechanical pieces. |
Research Approach
Two parallel data streams informed the analysis: structured interviews with movement assemblers, brand heritage directors, and Swissmedic regulatory leads; and secondary validation against COSC certification statistics, EU REACH enforcement bulletins, and Shenzhen customs sensor export records. Bottom-up assembly capacity modeling triangulated against top-down trade flow analysis.
Across the projection horizon, forecasts segment by product type, material compliance tier, and customer archetype to capture divergence between collector premiums and fitness enthusiast replacement cycles. CAGR derivation incorporated chronometer testing queue dynamics and smart module procurement cost curves from Shenzhen electronics corridors.
Material uncertainties — Swiss watchmaking school graduation shortfalls, rare earth magnet supply disruption, and FDA device classification timing — sit outside the modeled envelope. Forecasts reflect documented assumptions around certification capacity expansion and regulatory convergence patterns. Recalibration cycles align with material shifts in movement supply concentration and biometric claims pathway clarity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Sleep Headphones Market
Consumer Electronics
Zipline Kits Market
Consumer Electronics
Russia Gaming Gadgets Market
Consumer Electronics
Gun Care Products Market
Consumer Electronics
Refurbished Computer and Laptop Market
Consumer Electronics
Ultraman Peripheral Market
Consumer Electronics
Electronics Accessories Market
Consumer Electronics
Smart Headphones Market
Consumer Electronics
Middle East and Africa Smartphones Market
Consumer Electronics
Chromebook Market
Consumer Electronics
Shoe Shining Machine Market
Consumer Electronics
Smart Speaker Market
Consumer Electronics
In-Ear-Monitors (Iems) Market
Consumer Electronics
Waterproof Headphones Market
Consumer Electronics
Nail Art Printer Market
Consumer Electronics
Global Digital Watch Market