
 Digital Accessories Market | 2026-2036
Digital Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Accessories Market Analysis
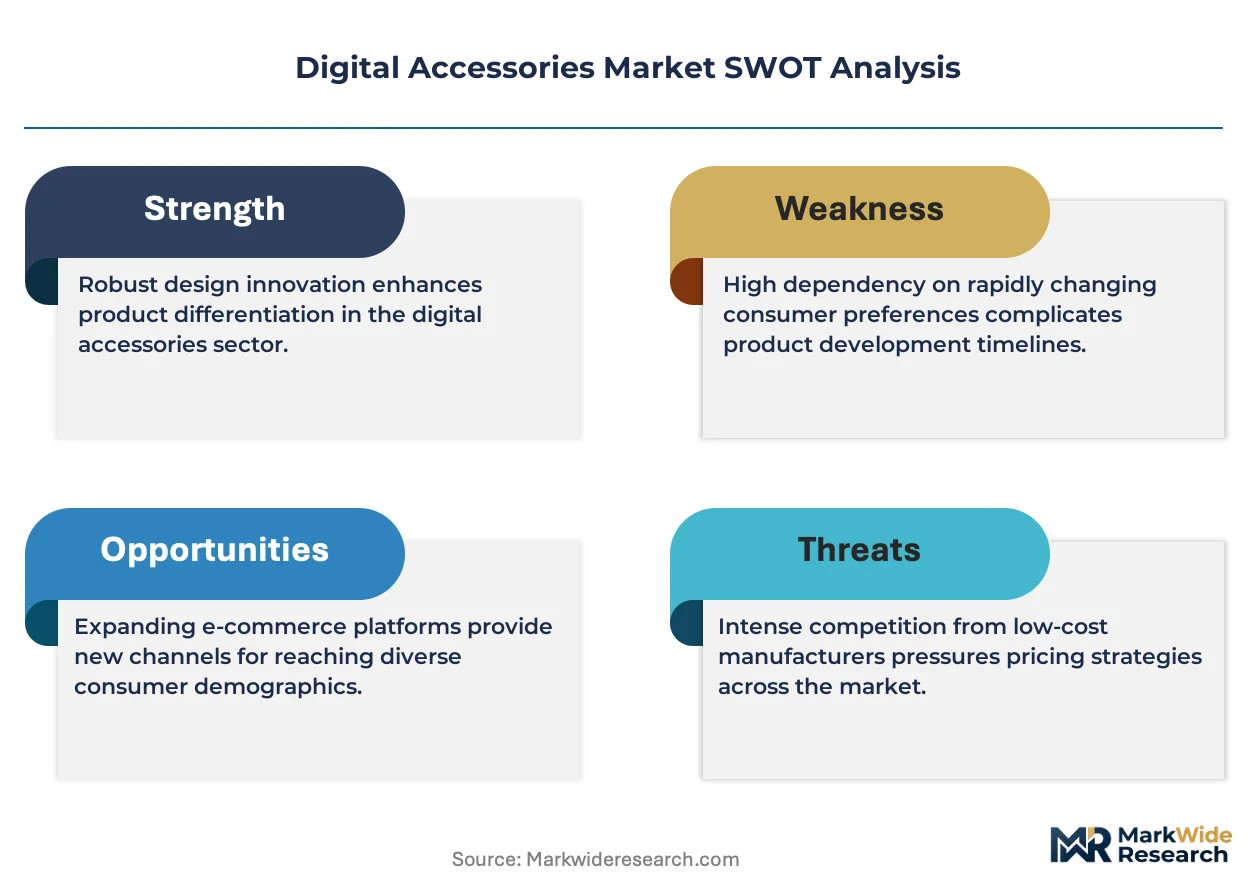
The price-performance gap between premium and commodity tiers is hardening as materials science diverges. Apple Inc. sustains its position through proprietary ecosystem lock-in and magnetic alignment architectures. Anker Innovations Co. Ltd. competes on gallium nitride charging density and multi-port output configurations. Logitech International S.A. dominates enterprise peripherals through unified communication certifications and fleet management software.
Digital accessories comprise electromechanical and electronic peripherals that extend, protect, or power consumer and enterprise computing devices, typically incorporating lithium-polymer cells, copper coil arrays, or tempered aluminosilicate glass rated to specific Mohs hardness thresholds. Their commercial purpose centers on device longevity, connectivity standardization, and user productivity augmentation. Headphones and chargers capture the dominant share of current revenue, with wireless and USB-C technology segments expanding fastest as legacy 3.5mm and Micro-USB interfaces phase out of active production. Screen protectors remain a high-volume, low-margin category where specialty stores extract value through installation services rather than unit economics.
The EU's Radio Equipment Directive and CE marking requirements enforce electromagnetic compatibility and safety testing for all wireless accessories sold in member states. The EPA's Energy Star specifications and California's CEC appliance efficiency regulations constrain standby power draw for charging equipment sold in the United States. China's GB standards and MIIT radio transmission certifications govern domestic production and export eligibility from Shenzhen and Dongguan manufacturing bases. Stakeholders must monitor interoperability certification timelines for the next-generation Qi2 wireless power standard and assess whether to backward-integrate into GaN semiconductor sourcing or maintain outsourced power electronics procurement.
Market Dynamics
The transition from legacy copper-based charging to gallium nitride architectures is compressing form factors while multiplying power density, forcing incumbents to retool Shenzhen and Dongguan production lines or cede the premium tier to semiconductor-integrated specialists.
Growth Catalysts
- Qi2 Wireless Standard Mandate:The Wireless Power Consortium's magnetic alignment specification is absorbing engineering resources across ODMs in China, creating interoperability lock-in that favors certified ecosystem vendors over unbranded alternatives.
- EU Energy-Efficiency Labeling:The European Commission's standby power regulations for external power supplies are eliminating sub-85% efficiency designs from import eligibility, accelerating GaN adoption in export-bound production.
- Enterprise Fleet Refresh Cycles:Hybrid work stabilization in North America and Western Europe is driving USB-C docking station procurement through IT channel partners, with volume discounts displacing consumer retail as the dominant revenue stream.
Market Restraints
- Raw Material Concentration:Lithium-polymer cell production depends on cathode precursor refining concentrated in China's Hunan and Fujian provinces, exposing margins to export quota volatility.
- Regulatory Fragmentation:Divergent electromagnetic compatibility testing between the EU's Radio Equipment Directive and the FCC's Part 15 rules forces dual certification runs, adding 8-12 weeks to product launch timelines.
- Silicon Carbide Substitution Threat:Automotive-grade SiC MOSFETs are migrating into industrial power electronics, potentially absorbing GaN's cost-performance advantage in non-consumer segments.
Strategic Opportunities
- India Local Assembly Incentives:The PLI scheme for electronics manufacturing offers tariff relief for power adapter and cable assembly, attracting contract manufacturers to Noida and Sri City industrial corridors.
- Matter Protocol Convergence:Smart home accessory vendors can leverage Thread and Wi-Fi interoperability to displace proprietary bridge hardware, capturing the connected device middleware layer.
- Repair-Right Regulatory Tailwind:France's reparability index mandates and pending EU battery passport requirements are creating certified spare parts markets for screens, batteries, and charging ports.
Industry Challenges
- RF Engineering Talent Scarcity:Qi2 coil array optimization and NFC antenna integration require specialized electromagnetic simulation expertise that Shenzhen contract manufacturers struggle to retain.
- Certification Pipeline Bottlenecks:UL and TÜV Rheinland testing backlogs for GaN-based fast chargers are extending time-to-revenue by 6-10 weeks for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Accessories Market |
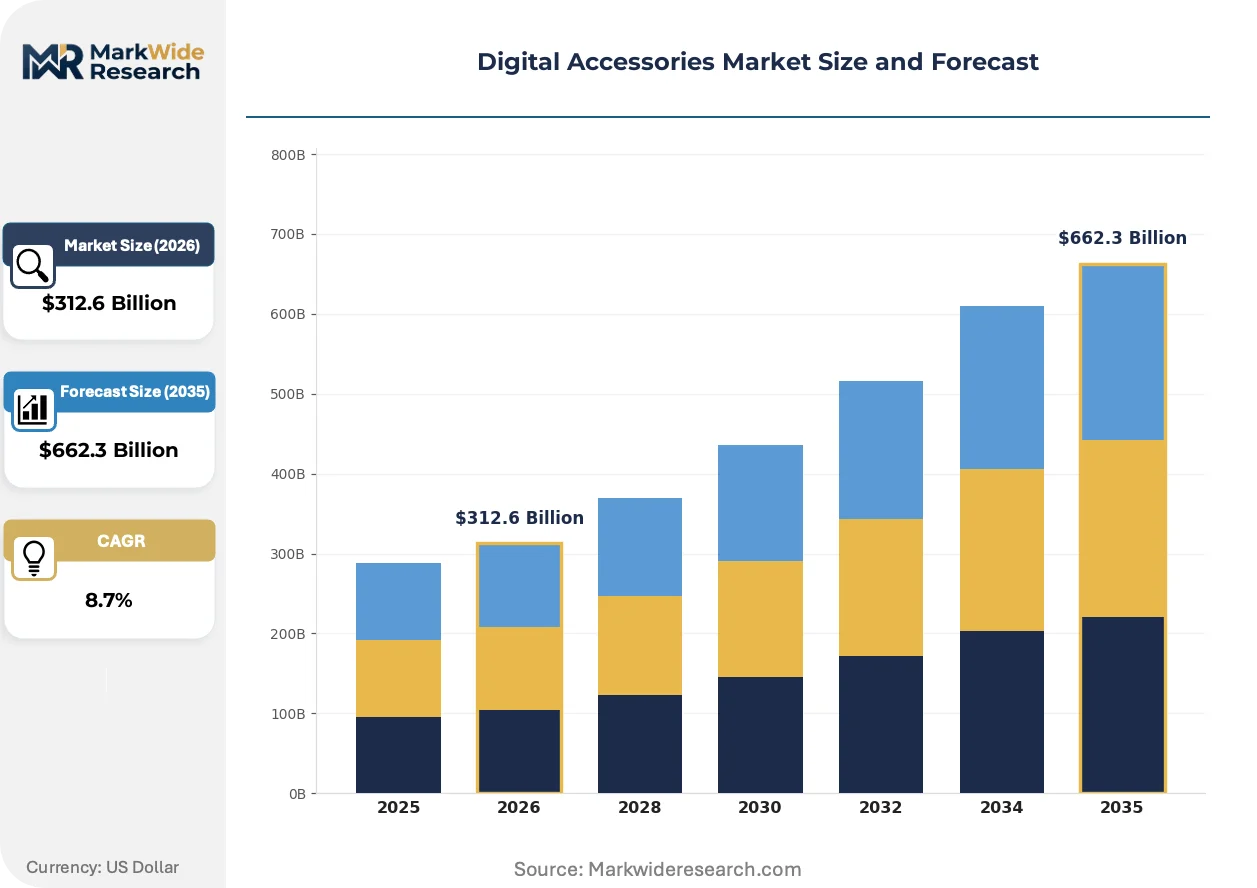
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $662.3 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headphones, Chargers, Cases, Screen Protectors Technology: Bluetooth, USB-C, Wireless, NFC Customer Type: Consumers, Businesses, Educational Institutions, Government Distribution Channel: Online Retailers, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Logitech International S.A., Anker Innovations Co. Ltd., Apple Inc., Spigen Inc., Belkin International Inc., Samsung Electronics Co. Ltd., Bose Corporation, OtterBox, Sony Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Accessories Market Emerging Trajectories
Material substitution and regulatory convergence are compressing product lifecycles while opening white space in aftermarket repair and enterprise fleet management. Vendors must now integrate semiconductor sourcing, certification engineering, and circular economy compliance into core capabilities.
Gallium nitride power ICs are absorbing the function of discrete MOSFETs, controllers, and gate drivers into single-package solutions. Tier-one ODMs in Dongguan are adopting these integrated designs for 65W and above multi-port chargers, collapsing bill-of-materials costs while enabling palm-sized form factors that displace traditional silicon-based brick adapters in premium retail channels.
REACH substance restrictions and the EU's impending USB-C common charger mandate are forcing cable and adapter redesigns across the supply base. The elimination of PVC jacketing and brominated flame retardants is accelerating TPE and bio-based polymer adoption, with Shenzhen compounders retooling extrusion lines to maintain CE marking eligibility for export-bound production.
Corporate IT procurement teams are consolidating peripheral purchasing through managed service providers, unbundling device provisioning from hardware ownership. CDW and Insight Enterprises are absorbing fleet configuration, warranty management, and end-of-life recovery functions that OEMs previously controlled, compressing direct vendor relationships and shifting margin capture to channel intermediaries in North America and Western Europe.
Digital Accessories Market Segmentation
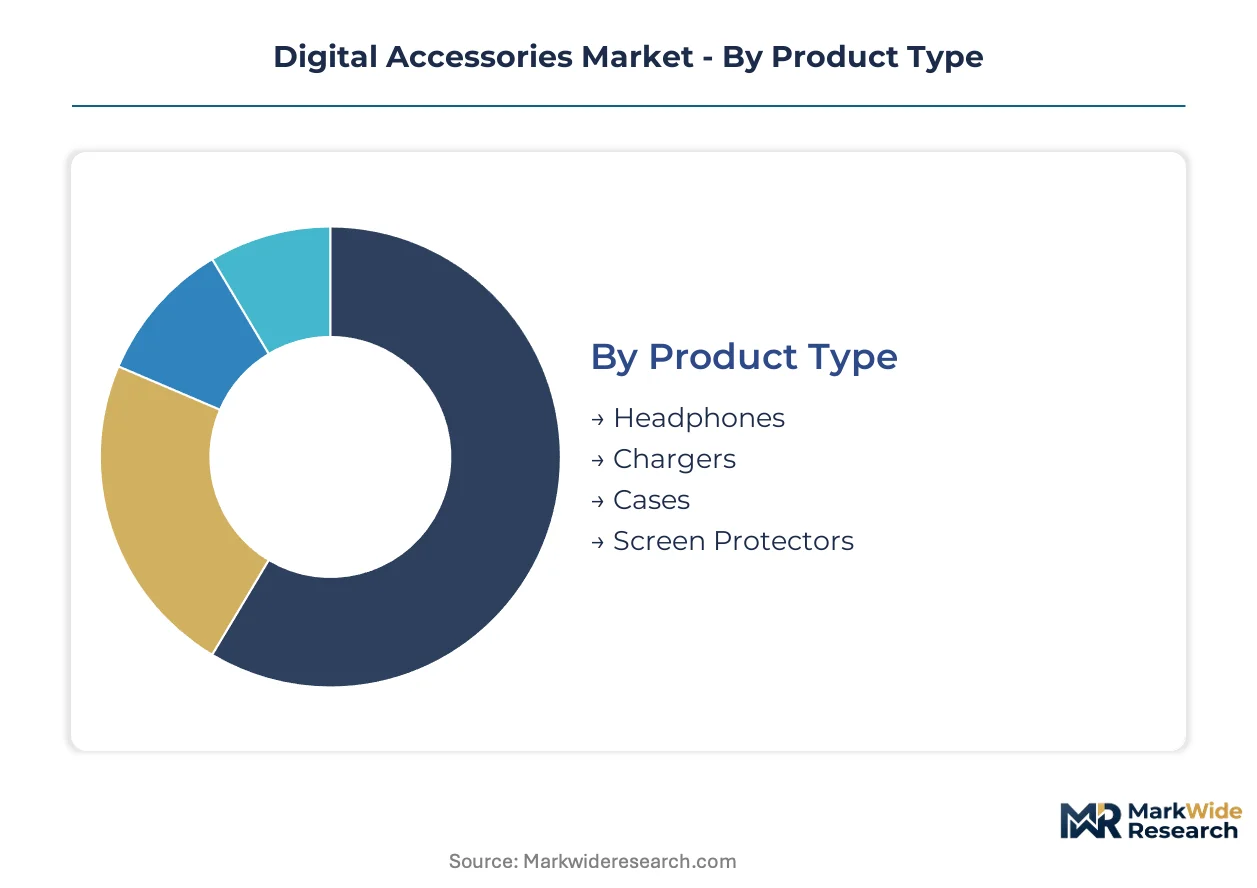
Segmentation in digital accessories reveals how procurement patterns diverge between impulse-driven consumer channels and contract-negotiated enterprise fleets. Understanding these splits exposes where margin pools concentrate and which technology transitions command pricing power.
Product Type:
Buyers differentiate primarily by replacement frequency and damage risk exposure rather than absolute price sensitivity.
- Headphones:Active noise cancellation and spatial audio codecs now define premium tiers. Enterprise procurement through CDW and Insight Enterprises for unified communications certifications is displacing consumer retail in revenue concentration.
- Chargers:Gallium nitride power density and multi-port output configurations separate premium from commodity tiers. Shenzhen ODMs are retooling Dongguan lines for integrated GaN ICs that collapse form factors while maintaining CE marking eligibility under EU energy-efficiency rules.
- Cases:Tempered aluminosilicate glass rated to specific Mohs hardness thresholds protects against drop damage. Specialty retailers extract value through installation services rather than unit economics.
- Screen Protectors:High-volume, low-margin category where TPE and bio-based polymer adoption accelerates under REACH substance restrictions.
Chargers lead volumes today; headphones are gaining share fastest.
Technology:
Interoperability certification timelines and backward compatibility obligations shape vendor R&D allocation across interface standards.
- Bluetooth:Low-energy audio codecs and LE Audio broadcast capabilities now permeate mid-tier and premium headphone segments. The EU's Radio Equipment Directive electromagnetic compatibility testing adds 8-12 weeks to product launch timelines for export-bound manufacturers.
- USB-C:The European Commission's common charger mandate is eliminating legacy Micro-USB from active production. Enterprise fleet refresh cycles through IT channel partners now dominate docking station and adapter procurement in North America and Western Europe.
- Wireless:Qi2 magnetic alignment specification absorbs engineering resources across Shenzhen ODMs, creating interoperability lock-in favoring certified ecosystem vendors.
- NFC:Pairing automation and payment authentication integration requires specialized electromagnetic simulation expertise that contract manufacturers struggle to retain.
USB-C anchors current revenue; wireless charging expands most quickly as Qi2 certification pipelines mature.
Customer Type:
Procurement authority and total cost of ownership calculations determine whether sales flow through retail or direct vendor relationships.
- Consumers:Impulse purchases through online retailers and supermarkets dominate, with price-performance gaps hardening between premium and commodity tiers.
- Businesses:Managed service providers now absorb fleet configuration, warranty management, and end-of-life recovery functions. CDW and Insight Enterprises compress direct OEM relationships while capturing margin as channel intermediaries.
- Educational Institutions:Volume discounts and multi-year procurement contracts prioritize durability and standardized charging infrastructure over feature differentiation.
- Government:Compliance with EPA Energy Star specifications and California CEC appliance efficiency regulations constrains standby power draw for charging equipment.
Consumer channels dominate unit volumes; business procurement climbs the fastest as hybrid work stabilizes.
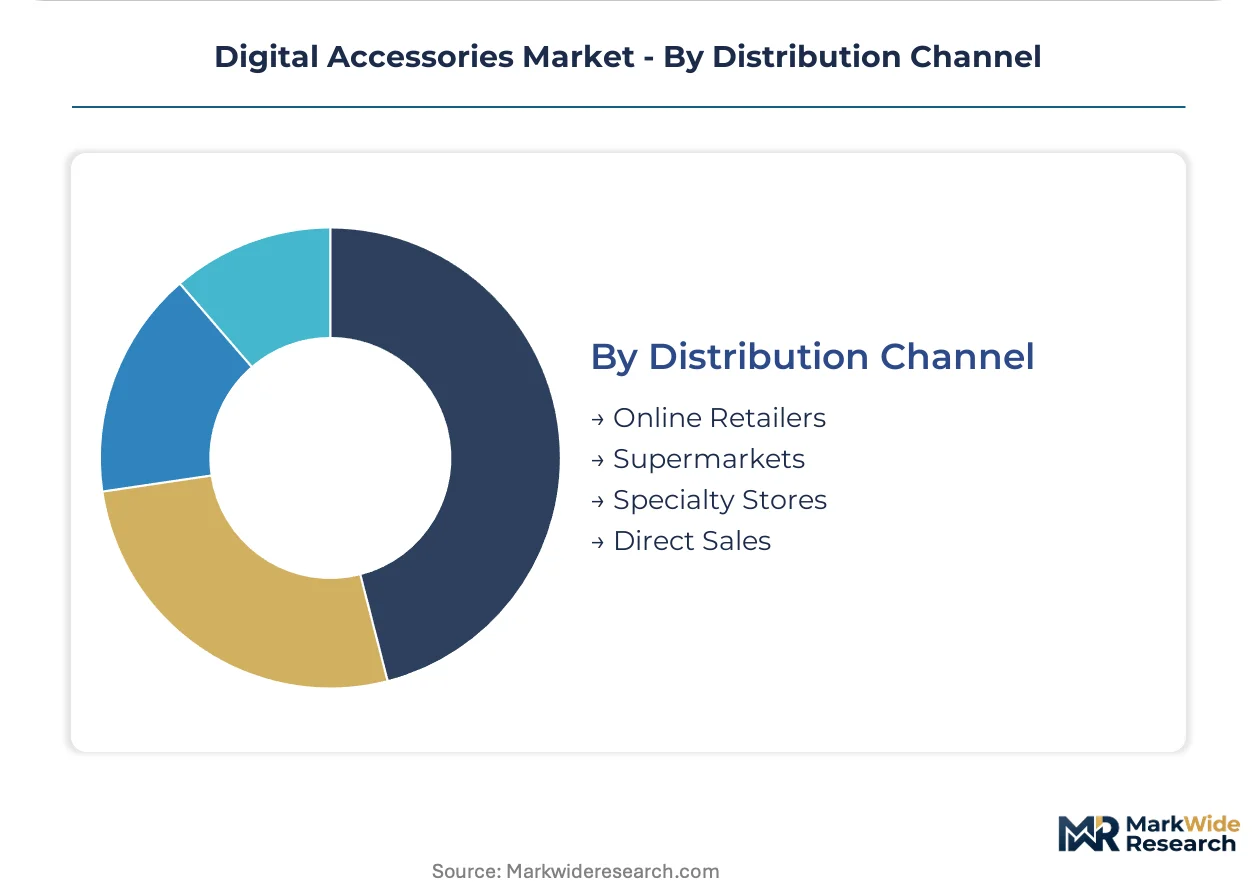
Distribution Channel:
Margin capture and customer acquisition costs diverge sharply between self-service digital platforms and assisted retail environments.
- Online Retailers:Amazon and direct-to-consumer sites absorb the majority of headphone and charger volumes. Unbranded alternatives from Shenzhen struggle against certified ecosystem vendors under Qi2 interoperability mandates.
- Supermarkets:Impulse-accessory placement drives high-velocity, low-margin transactions for cables and basic cases. REACH-compliant TPE jacketing now required for CE marking eligibility.
- Specialty Stores:Installation services for screen protectors and technical consultation for enterprise docking configurations justify premium pricing. Expertise scarcity in RF engineering and electromagnetic simulation supports margin retention.
- Direct Sales:Corporate IT procurement teams negotiate volume discounts for USB-C docking stations and wireless charging infrastructure, displacing consumer retail as the dominant revenue stream.
Online retailers lead transaction volumes; direct sales channels show the steepest expansion trajectory as enterprise fleets consolidate purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's RF engineering talent pools anchor global digital accessories production, with contract manufacturers clustering around component ecosystems that feed assembly lines across three continents.
China
Enterprise procurement of USB-C docking stations and Qi2 wireless chargers drives volume demand. MIIT radio transmission certifications and GB standards govern export eligibility from Shenzhen and Dongguan manufacturing bases. Dongguan production lines retool for integrated gallium nitride ICs that collapse charger form factors while maintaining CE marking eligibility.
United States
Hybrid work stabilization fuels IT channel procurement of wireless charging infrastructure and fleet-managed peripherals. EPA Energy Star specifications and California CEC appliance efficiency regulations constrain standby power draw for charging equipment. Austin and Seattle tech corridors concentrate enterprise sales operations for docking station vendors.
Germany
Industrial automation and automotive electronics sectors generate demand for ruggedized charging solutions and EMI-shielded accessories. REACH substance restrictions and CE marking requirements under the Radio Equipment Directive enforce electromagnetic compatibility testing. Stuttgart engineering clusters specialize in automotive-grade wireless power integration for connected vehicle programs.
India
Local assembly incentives attract power adapter and cable manufacturing to serve domestic consumer electronics growth. The PLI scheme for electronics manufacturing offers tariff relief for contract manufacturers establishing operations in Noida and Sri City industrial corridors. Karnataka's Bangalore electronics cluster hosts R&D centers optimizing charging protocols for tropical climate conditions.
Japan
Premium audio accessory demand concentrates in Tokyo and Osaka metropolitan markets with exacting quality specifications. METI efficiency standards and JIS certification requirements shape product design for domestic and export-bound production. Nagoya industrial corridors maintain precision manufacturing capabilities for high-reliability connector and coil array components.
Digital Accessories Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the digital accessories value chain, creating a tiered structure where semiconductor-integrated specialists capture premium pricing while contract manufacturers compete on volume scale. The vendor base separates into ecosystem-locked incumbents, GaN-integrated charging specialists, and enterprise fleet management intermediaries. Consolidation pressures concentrate around certification engineering capabilities and Qi2 interoperability mandates. Dominant competitive moves include backward integration into GaN semiconductor sourcing and strategic partnerships with IT channel intermediaries absorbing fleet configuration functions.
Within the ecosystem-locked tier, Apple Inc. and Samsung Electronics Co. Ltd. exemplify proprietary architecture strategies that magnetic alignment specifications reinforce. Anker Innovations Co. Ltd. occupies a position among charging density specialists competing on multi-port output configurations and gallium nitride integration. These three entities represent contrasting archetypes: closed ecosystem control, open-standard premium positioning, and semiconductor-integrated specialist scale.
| Leading Market Players |
|---|
| Logitech International S.A. |
| Anker Innovations Co. Ltd. |
| Apple Inc. |
| Spigen Inc. |
| Belkin International Inc. |
| Samsung Electronics Co. Ltd. |
| Bose Corporation |
| OtterBox |
| Sony Corporation |
| Others |
Supply Flow & Price Mechanics
GaN-integrated premium tiers and silicon-based commodity chargers diverge sharply in margin structure, with Shenzhen ODMs commanding pricing power through certification engineering while unbranded alternatives face cost compression from EU energy-efficiency mandates and REACH compliance burdens.
Pricing Analysis
Bundled installation services for screen protectors and unbundled transactional sales for cables create distinct margin pools across distribution channels. Three-tier pricing structure across premium, standard, and economy levels separates Qi2-certified ecosystem vendors from CE-marked mid-tier producers and unbranded Shenzhen generics. Pricing pressure stems from gallium nitride IC cost compression forcing retooling investments. Enterprise procurement through CDW and Insight Enterprises shows lowest price sensitivity; supermarket impulse purchases face highest elasticity.
Supply Chain Analysis
Dual-sourcing requirements for lithium-polymer cells and GaN semiconductors now dominate procurement policies among tier-one ODMs seeking to mitigate Hunan cathode precursor quota volatility. Production concentrates in China, Vietnam, and India, drawing from copper coil arrays, tempered aluminosilicate glass, and TPE polymer compounds. Single-source vulnerability in RF engineering talent pools threatens Qi2 certification timelines. Distribution runs through IT channel partners consolidating enterprise fleet procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where hybrid work stabilization shifts procurement authority toward IT channel partners demanding unified communications certifications and fleet management integration.
For Market Incumbents: Deepen backward integration into gallium nitride semiconductor sourcing to defend margin position against SiC substitution threats in industrial power electronics. Invest in captive Qi2 certification engineering capabilities to bypass UL and TÜV Rheinland testing backlogs that extend time-to-revenue. For New Entrants and Emerging Players: Enter via India's PLI scheme for electronics manufacturing to capture tariff relief for power adapter assembly serving domestic consumer electronics growth. Target Noida and Sri City industrial corridors with TPE cable production optimized for REACH-compliant CE marking eligibility. For Investors and Strategic Acquirers: Consolidation pressure builds where certification pipeline bottlenecks and RF engineering talent scarcity constrain new product introduction velocity. Long-term viability favors semiconductor-integrated specialists with in-house GaN IC design capabilities. Watch Qi2 interoperability mandate enforcement as inflection indicator for ecosystem lock-in intensity.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Semiconductor Backward Integration | In-house GaN IC production collapses charger form factors while protecting margins from silicon carbide substitution. |
| Qi2 Certification Pipeline Investment | Captive electromagnetic simulation expertise bypasses UL and TÜV Rheinland backlogs extending product launch timelines. |
| Enterprise Channel Partnership | Strategic alliances with CDW and Insight Enterprises absorb fleet configuration functions shifting margin to intermediaries. |
| India PLI Manufacturing Localization | Noida and Sri City assembly operations capture tariff relief for power adapter production serving domestic demand. |
| Repair-Right Spare Parts Certification | France's reparability index mandates and EU battery passport requirements create certified aftermarket revenue streams. |
Methodological Framework
Multiple input streams — procurement directors at enterprise IT channel partners, RF engineering leads at Shenzhen ODMs, regulatory affairs specialists, and compound materials sourcing managers — were reconciled against secondary validation from MIIT certification databases, EU Radio Equipment Directive filings, and customs trade records. Bottom-up volume modeling across charger, headphone, case, and screen protector categories was cross-referenced with top-down spend analysis from enterprise fleet refresh disclosures.
Historical shipment data was cross-referenced against panel input from contract manufacturers and semiconductor distributors to derive expansion trajectories across the projection horizon. Segmentation dimensions modeled include product type, interface technology, customer procurement authority, and distribution channel structure. CAGRs were synthesized from unit economics trajectories in gallium nitride power density and wireless charging adoption curves.
Inputs from Shenzhen and Dongguan manufacturing clusters were available through the study window; gaps in Qi2 certification pipeline velocity and RF engineering labor market data introduce uncertainty bands around new product introduction timelines. Deviation in EU energy-efficiency mandate enforcement or India PLI scheme renewal terms would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Digital Voice Recorder Market
Consumer Electronics
Smartphone Screen Protector Market
Consumer Electronics
4K Television Market
Consumer Electronics
FMCG Market
Consumer Electronics
Mechanical Keyboard Market
Consumer Electronics
Global Monitor Headphones (in-Ear Monitors) Market
Consumer Electronics
Instant Camera's Consumable Market
Consumer Electronics
Mannequin Head Market
Consumer Electronics
Mini Bluetooth Shower Speaker Market
Consumer Electronics
Tattoo Machine Market
Consumer Electronics
Digital Writing Instruments Market
Consumer Electronics
Speakerphones Market
Consumer Electronics
United States Smart TV Market
Consumer Electronics
Ultraman Peripheral Market
Consumer Electronics
Smart TV Sticks Market
Consumer Electronics
Noise Cancelling Headphones Market