
 Elastomer Gel in Personal Care Market | 2026-2036
Elastomer Gel in Personal Care Market Size, Share, and Industry Trends Forecast 2026-2036
Elastomer Gel in Personal Care Market Intelligence
Silicone elastomer is shifting away from traditional petrolatum in high-end moisturizers and primers as brands seek non-comedogenic, silky textures with superior spreadability. Dow Silicones Corporation leverages its Midland, Michigan manufacturing complex to anchor North American supply for skin care formulators. Evonik Industries competes through specialized silicone-organic hybrid technologies that extend tactile performance across climate zones. BASF Care Chemicals differentiates by controlling key emollient precursors that integrate with elastomer gel matrices.
Elastomer gel in personal care denotes cross-linked silicone polymer networks, typically with particle sizes of 1–50 microns, that deliver velvet-like skin feel, optical blurring, and sebum absorption without occlusivity. Skin Care applications dominate current volume as elastomer gels function as rheology modifiers and sensory agents in serums and creams. Makeup represents the fastest-expanding segment, where foundations deploy these materials for long-wear comfort and pore-smoothing effects. Hair Care remains comparatively mature, with elastomer gels limited to niche conditioning and frizz-control formats.
FDA cosmetic ingredient scrutiny under the Modernization of Cosmetics Regulation Act and REACH substance restrictions through ECHA jointly elevate compliance costs for silicone-based inputs. ISO 16128 natural origin standards create additional formulation constraints as brands navigate green positioning claims. Stakeholders must monitor evolving biodegradability assessments and regional labeling requirements to align R&D pipelines with divergent regulatory timelines.
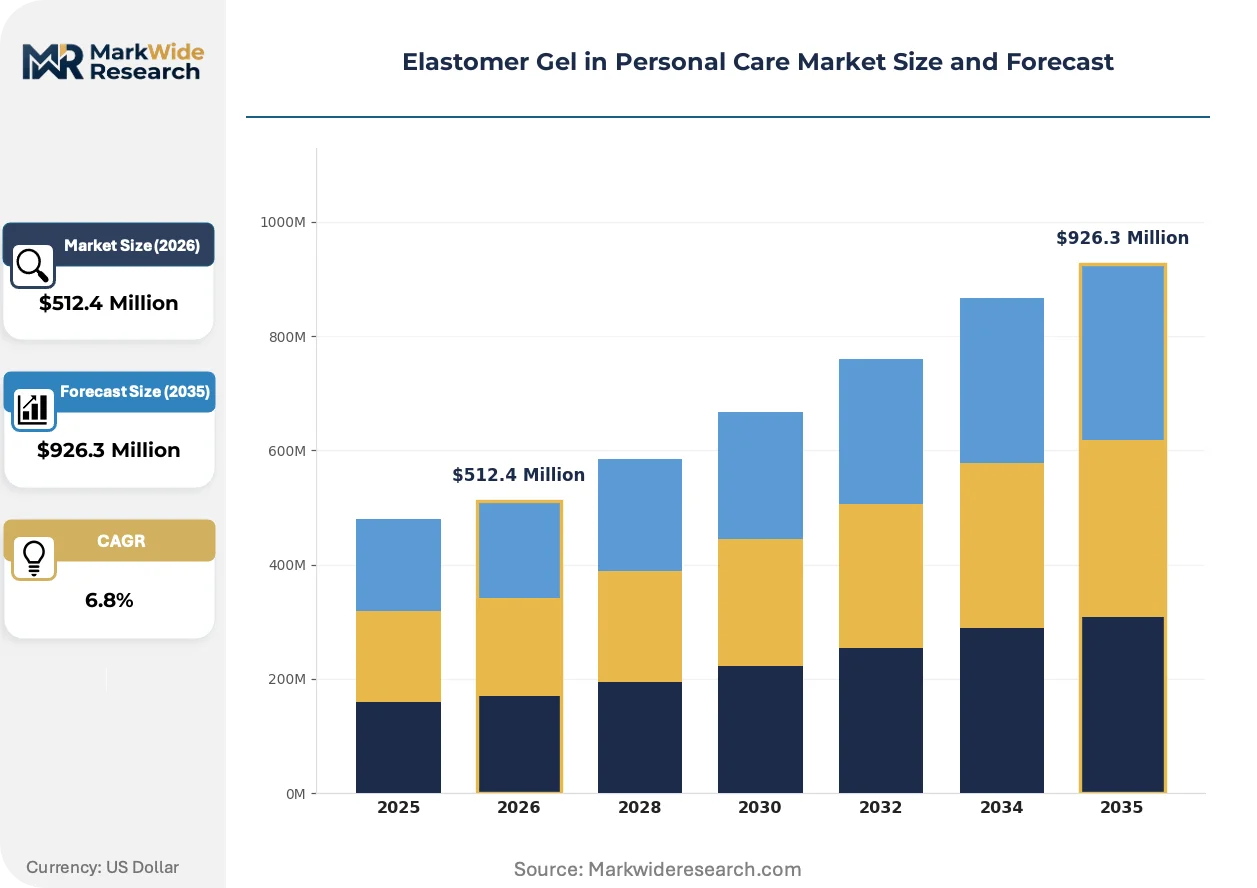
Market Dynamics
Silicone elastomer gel suppliers face mounting pressure from REACH substance restrictions and FDA cosmetic ingredient reviews, forcing simultaneous reformulation investments across multiple regulatory jurisdictions while premium skincare brands accelerate sensory-driven procurement.
Growth Catalysts
- Modernization of Cosmetics Regulation Act:FDA's expanded safety authority is elevating documentation standards that favor established elastomer gel suppliers with robust toxicology dossiers over commodity alternatives.
- ISO 16128 natural origin standards:Brands seeking green positioning claims are driving demand for silicone-organic hybrid elastomer gels that satisfy both performance and origin requirements.
- South Korean beauty innovation clusters:Advanced domestic formulation capabilities in Seoul and Incheon are accelerating elastomer gel adoption for K-beauty export formulations.
Market Restraints
- Siloxane D4/D5/D6 restrictions:ECHA's rolling substance evaluations under REACH are constraining feedstock availability and forcing costly precursor substitutions for European formulators.
- Specialty silicone concentration:Production of cross-linked elastomer networks concentrates among three global chemical conglomerates, creating supply vulnerability during force majeure events.
- Petrolatum displacement ceiling:Occlusive mineral oil alternatives retain cost advantages in mass-market moisturizers, limiting elastomer gel penetration below premium tier.
Strategic Opportunities
- Chinese domestic beauty brands:Rising local champions in Shanghai and Hangzhou seek differentiated sensory profiles for anti-pollution and blue-light protection formats.
- Biodegradability assessment protocols:Early alignment with OECD testing frameworks positions suppliers favorably ahead of anticipated EU microplastic restrictions.
- Hair styling elastomers:Frizz-control and heat-protection applications remain underdeveloped versus skin care, offering white space for texture innovation.
Industry Challenges
- Formulation chemist scarcity:Cross-disciplinary expertise spanning silicone chemistry, rheology, and cosmetic stability commands premium compensation and extends R&D timelines.
- Dual regulatory certification:Parallel FDA notification and EU cosmetic product notification portal submissions create administrative burden and launch delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elastomer Gel in Personal Care Market |
| Market Size in 2026 | $512.4 Million |
| Market Size in 2035 | $926.3 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizers, Sunscreens, Foundations, Cleansers End User: Women, Men, Children, Seniors Application: Skin Care, Hair Care, Makeup, Body Care Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | Momentive Performance Materials, Evonik Industries, Dow Silicones Corporation, The Lubrizol Corporation, BASF Care Chemicals, Wacker Chemie AG, Elkem Silicones, Grant Industries, Shin-Etsu Chemical Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elastomer Gel in Personal Care Market Strategic Shifts & Innovations
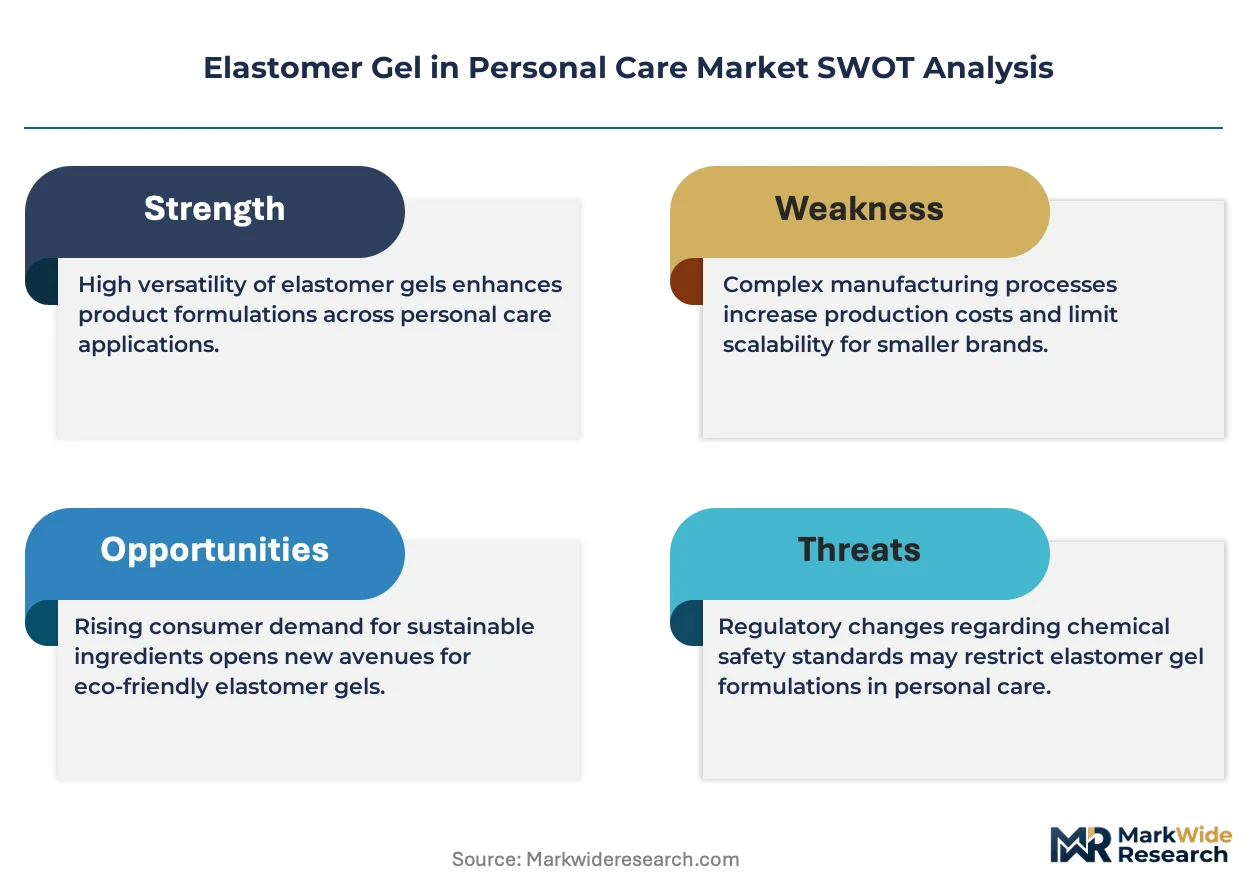
Formulation science is pivoting toward hybrid architectures that merge silicone performance with bio-based credentials, while regulatory pressure and procurement sophistication reshape competitive requirements.
Water-dispersible elastomer gel powders are rewriting formulation flexibility for anhydrous and water-light serums. Indie and direct-to-consumer brands are adopting these materials fastest, compressing development cycles from 18 months to under 8 months. The technology is rewriting conventional wisdom that superior skin feel requires heavy silicone oil loads.
REACH authorization requirements for cyclic siloxanes are tightening substance control obligations across European supply chains. Manufacturers must now maintain extensive exposure assessments and downstream communication protocols. Color cosmetics with long-wear claims face the steepest compliance burden, driving reformulation toward linear and volatile-free elastomer alternatives.
Beauty brands now require full supply chain transparency through raw material passports and carbon intensity disclosures. Direct relationships with silicone manufacturers are displacing traditional distributor intermediaries for strategic inputs. This pattern concentrates most visibly in German and French premium skincare procurement, where sustainability scorecards determine supplier qualification.
Elastomer Gel in Personal Care Market Segmentation
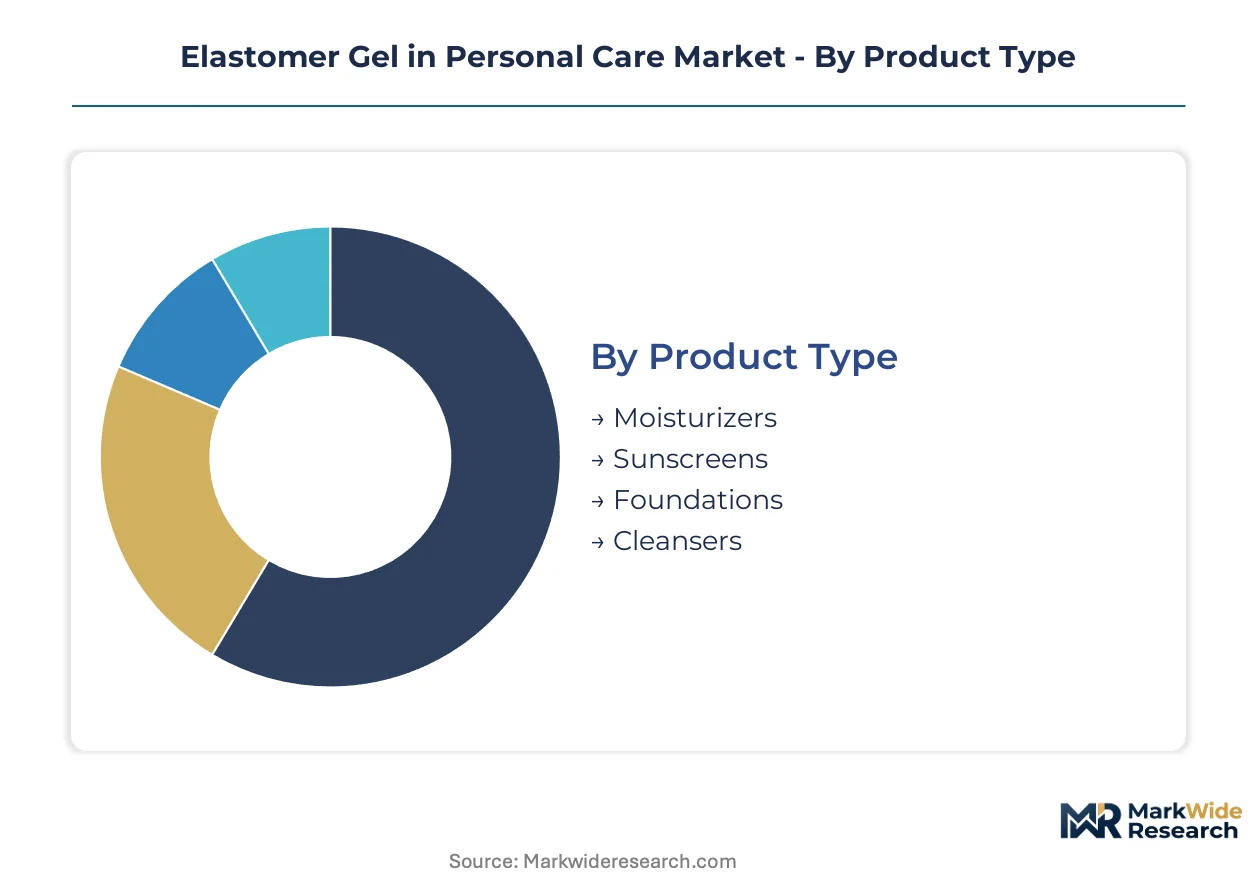
Elastomer gel integration depth varies sharply across personal care formulations. Standalone applications in primers and serums exploit full sensory performance, while embedded systems in mass-market moisturizers dilute elastomer loading to hit price points.
Product Type:
Standalone elastomer gels dominate premium positioning where texture differentiation commands margin; embedded formulations serve cost-constrained mass tiers.
- Moisturizers:Cross-linked silicone networks at 2-5% loading replace traditional petrolatum in day creams and night repair formulations. Demand clusters in Seoul's K-beauty export houses and Milan's luxury skincare laboratories, driven by non-comedogenic positioning requirements.
- Foundations:Elastomer gel matrices deliver optical blurring and sebum absorption for long-wear comfort. Expansion concentrates in Shanghai's domestic beauty champions seeking anti-pollution format differentiation.
- Sunscreens:Water-dispersible elastomer powders enhance spreadability in mineral UV filters without white cast residue.
- Cleansers:Limited elastomer incorporation for texture modification in oil-to-milk transformation systems.
Volume placements concentrate in Moisturizers; the faster expansion belongs to Foundations.
End User:
Gender-targeted formulation architectures drive divergent elastomer specifications across skin physiology and grooming ritual differences.
- Women:Multi-step routines sustain highest elastomer gel consumption across serums, primers, and color cosmetics. South Korean and Japanese formulation houses lead texture innovation for this segment.
- Men:Simplified regimens favor single-application elastomer hybrids combining mattification with light hydration. Demand is climbing fastest in China's tier-one cities.
- Seniors:Mature skin elasticity concerns drive elastomer loading for immediate optical smoothing effects.
- Children:Minimal elastomer use restricted to gentle cleansing formats with stringent safety dossier requirements.
Current volume leadership sits with Women; Men is gaining share fastest on grooming category expansion.
Application:
Functional role determines elastomer gel specification—rheology modification versus sensory delivery versus optical performance.
- Skin Care:Elastomer gels function as primary sensory agents and viscosity builders in serums and creams. German and French premium brands mandate full supply chain transparency for these inputs.
- Makeup:Long-wear foundations and pore-minimizing primers deploy elastomer networks for comfort persistence. Color cosmetics face steepest REACH compliance burdens for cyclic siloxane restrictions.
- Hair Care:Niche applications in frizz-control serums and heat-protection sprays remain underdeveloped versus skin categories.
- Body Care:Limited penetration in body lotions where cost economics favor conventional emollients.
Skin Care dominates absolute volume; Makeup follows the steepest expansion trajectory on color cosmetic innovation cycles.
Distribution Channel:
Channel format dictates packaging, price positioning, and consequently elastomer gel grade selection.
- Specialty Stores:Prestige beauty retail in Paris, New York, and Tokyo showcases high-elastomer formulations with demonstrable texture differentiation. Consultants educate consumers on skin-feel benefits.
- Online Retail:Direct-to-consumer brands compress development cycles and adopt water-dispersible elastomer powders fastest for flexible formulation platforms.
- Pharmacies:Dermocosmetic positioning requires clinical validation of elastomer safety profiles, favoring established suppliers with robust toxicology dossiers.
- Supermarkets:Mass-market moisturizers limit elastomer loading to maintain competitive price points against petrolatum alternatives.
Specialty Stores anchor premium volume; Online Retail is expanding most quickly on indie brand proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for elastomer gel in personal care concentrates in three innovation clusters spanning East Asia, Western Europe, and North America, with each geography driving distinct formulation specifications and regulatory compliance requirements.
United States
Premium skincare brands in New York and Los Angeles drive elastomer gel procurement for sensory differentiation in primers and serums. FDA's Modernization of Cosmetics Regulation Act elevates documentation standards that favor established suppliers with robust toxicology dossiers. Midland, Michigan anchors North American silicone manufacturing for skin care formulators seeking domestic supply security.
China
Domestic beauty champions in Shanghai and Hangzhou seek differentiated sensory profiles for anti-pollution and blue-light protection formats. NMPA cosmetic ingredient reviews tighten safety assessment protocols for silicone-based inputs entering the market. The Yangtze River Delta houses advanced formulation laboratories accelerating elastomer adoption for local brand export strategies.
Germany
Dermocosmetic positioning in Berlin and Hamburg mandates clinical validation of elastomer safety profiles and full supply chain transparency. ECHA's REACH substance evaluations constrain feedstock availability and force costly precursor substitutions for European formulators. The Rhine-Ruhr industrial corridor concentrates specialty chemical production serving premium skincare procurement.
South Korea
K-beauty export houses in Seoul and Incheon accelerate elastomer gel adoption for multi-step skincare routines emphasizing texture innovation. MFDS cosmetic regulations align with evolving international standards while supporting domestic silicone innovation ecosystems. Advanced domestic formulation capabilities drive regional sensory performance benchmarks.
France
Luxury skincare laboratories in Paris showcase high-elastomer formulations with demonstrable texture differentiation through prestige retail channels. ANSM enforces stringent cosmetic product notification requirements that extend launch timelines for new silicone-based ingredients. Sustainability scorecards determine supplier qualification for premium brand procurement decisions.
Elastomer Gel in Personal Care Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with premium skincare procurement concentrating among established silicone chemistry conglomerates while indie brands access water-dispersible elastomer powders through specialized distributors. Three strategic archetypes dominate: integrated petrochemical giants controlling feedstock-to-formulation value chains, hybrid technology specialists bridging silicone-organic boundaries, and regional manufacturing anchors serving geographic procurement preferences. Competitive moves center on backward integration into emollient precursors and strategic partnerships for biodegradability assessment protocols.
Within the integrated petrochemical tier, Dow Silicones Corporation and Momentive Performance Materials occupy positions defined by captive manufacturing infrastructure and North American supply security. Evonik Industries exemplifies the hybrid technology archetype, developing specialized silicone-organic matrices that extend tactile performance across climate zones. Wacker Chemie AG anchors European production capabilities serving REACH-compliant formulation requirements. BASF Care Chemicals sits within the precursor control segment, managing key emollient inputs that integrate with elastomer gel matrices.
| Leading Market Players |
|---|
| Momentive Performance Materials |
| Evonik Industries |
| Dow Silicones Corporation |
| The Lubrizol Corporation |
| BASF Care Chemicals |
| Wacker Chemie AG |
| Elkem Silicones |
| Grant Industries |
| Shin-Etsu Chemical Co Ltd |
| Others |
Cost & Logistics Intelligence
Cyclic siloxane feedstock costs cascade through three distinct pricing tiers, with REACH-compliant European supply commanding premiums over standard-grade Asian material and economy-tier petrolatum alternatives anchoring mass-market moisturizers. This cost architecture concentrates margin leverage among integrated silicone manufacturers while forcing reformulation trade-offs at independent compounders.
Pricing Analysis
Volume placements cluster in standard-grade elastomer gels for mass-market skin care, while margin capture concentrates in premium-grade silicone-organic hybrids certified for K-beauty export formulations. Price differentiation hinges on REACH dossier completeness and ISO 16128 natural origin verification, with German and French premium brands least sensitive to cost. Pricing pressure stems from ECHA's rolling D4/D5/D6 restrictions forcing precursor substitutions, compressing margins for European formulators dependent on cyclic siloxane feedstocks.
Supply Chain Analysis
Single-source vulnerability sits with Midland, Michigan and the Rhine-Ruhr corridor for specialty cross-linked silicone production, with South Korean and Japanese facilities providing secondary capacity. Raw material flows draw from quartz-derived silicon metal, methyl chloride precursors, and platinum catalyst systems. Supply chain risk centers on regulatory restriction cascades from ECHA substance evaluations disrupting European feedstock availability. Distribution runs through direct manufacturer relationships displacing traditional chemical distributors for strategic elastomer gel inputs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with upstream control over emollient precursors and downstream formulation partnerships determining competitive durability. Players are pursuing captive supply of silicone-organic hybrid technologies to lock in margin capture.
For Market Incumbents: To counter REACH-driven feedstock disruption, Dow Silicones Corporation and Evonik Industries should deepen backward integration into linear siloxane precursors while securing long-term offtake agreements with Seoul-based K-beauty export houses. Certification investment in OECD biodegradability protocols will preempt EU microplastic restrictions. For New Entrants and Emerging Players: The premium-economy price-point gap in Chinese domestic beauty brands offers the most penetrable entry vector, with Hangzhou and Shanghai formulators seeking differentiated anti-pollution formats. A go-to-market angle through water-dispersible elastomer powder platforms enables rapid formulation iteration for direct-to-consumer indie brands. For Investors and Strategic Acquirers: Distressed-cycle entries favor hybrid technology specialists with silicone-organic patent portfolios in Germany and South Korea, where regulatory compliance burdens have compressed independent valuations. The signal to watch is NMPA cosmetic ingredient review acceleration in China, which would trigger consolidation among regional formulators lacking robust toxicology dossiers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Linear Siloxane Precursors | Secures REACH-compliant feedstock for European elastomer gel production. |
| OECD Biodegradability Protocol Alignment | Positions suppliers ahead of anticipated EU microplastic restrictions. |
| Direct Manufacturer Relationships | Displaces distributor intermediaries for German and French premium brand procurement. |
| Water-Dispersible Elastomer Powder Platforms | Compresses indie brand development cycles from 18 months to under 8 months. |
| K-Beauty Export House Partnerships | Locks in volume placement for multi-step skincare texture innovation. |
Research Approach
Multi-period observation of silicone feedstock pricing, REACH substance evaluation timelines, and K-beauty formulation patent filings anchored the trend analysis, supplemented by interviews with silicone plant managers, cosmetic R&D directors at premium brands, chemical distribution channel partners, and regulatory affairs leads at ECHA-notified bodies. Secondary validation drew from ECHA substance evaluation reports, FDA cosmetic ingredient guidance documents, NMPA cosmetic registration databases, and customs trade data for silicone elastomer imports. Bottom-up volume estimates from individual formulation facilities were triangulated against top-down market sizing from chemical industry associations.
Segment-weighting applied product type, application function, and end-user gender targeting as primary dimensions across the analysis window, with regional regulatory cluster intensity as a cross-cutting modifier. CAGRs were derived from elasticity-adjusted demand projections incorporating substitution dynamics between elastomer gels and petrolatum alternatives. Industry-specific forecast inputs included cyclic siloxane restriction rollout schedules and K-beauty export growth trajectories.
Inputs from ECHA substance evaluation databases and NMPA cosmetic registration portals were available through the study window; gaps in real-time formulation facility capacity utilization introduce uncertainty bands around volume projections. Forecasts reflect assumptions about regulatory implementation timelines and brand procurement stickiness. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Cosmetics Face Serum Market
Beauty & Personal Care
Hair Wig Market
Beauty & Personal Care
Natural and Organic Personal Care Market
Beauty & Personal Care
Global Organic Hair Color Market
Beauty & Personal Care
UK Sustainable Personal Care Market
Beauty & Personal Care
US Personal Care Products Market
Beauty & Personal Care
Personal Care Wipes Market
Beauty & Personal Care
Sun Protection Spray Market
Beauty & Personal Care
Cosmetics and Personal Care Products Direct Selling Market
Beauty & Personal Care
UV Nail Gel Market
Beauty & Personal Care
Saudi Arabia Beauty and Personal Care Market
Beauty & Personal Care
Zero-Waste Shampoo Market
Beauty & Personal Care
Vanity Mirror Market
Beauty & Personal Care
Over-Night Hair Treatment Products Market
Beauty & Personal Care
North America Setting Spray Market
Beauty & Personal Care
GCC Male Grooming Products Market