
 Global Smart Outdoor TV Market | 2026-2036
Global Smart Outdoor TV Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Outdoor TV Market Outlook
The premium-commodity split in outdoor display technology is rebalancing around brightness tolerance, ingress protection grades, and thermal management architectures. Samsung Electronics leverages semiconductor-to-display vertical integration to sustain pricing power in full-sun QLED tiers. SunBriteTV anchors its position through specialized all-weather engineering that dominates commercial installation channels. Sylvox competes aggressively on cost-engineered LED formats for residential patio applications.
Smart outdoor televisions integrate IP-rated enclosures, ambient light sensors, and wide-temperature electronics to deliver streaming-capable viewing in exterior environments. These units typically operate across temperature ranges from negative twenty to fifty degrees Celsius while maintaining minimum one-thousand-nit brightness for direct-sun readability. LED product types occupy the volume tier due to manufacturing scale and backlight modularity, while QLED segments capture margin pools through quantum dot color enhancement and premium positioning. Wall-mounted installation types lead commercial deployments in hospitality settings, whereas freestanding configurations gain traction in residential poolside and deck environments where structural modification is constrained.
FCC equipment authorization shapes RF connectivity compliance for Wi-Fi and Bluetooth modules in US-bound units, while CE marking governs electromagnetic compatibility and safety standards for European market access. REACH and RoHS frameworks restrict hazardous substance content in display assemblies and power supply components, elevating material compliance costs for manufacturers serving multiple regulatory zones. Stakeholders must monitor divergence between regional IP rating interpretations and emerging energy efficiency labeling requirements that threaten to fragment product certification pathways.
Market Dynamics
The outdoor display sector faces mounting pressure from tightening IP enclosure standards and thermal management requirements that favor vertically integrated manufacturers with captive semiconductor capabilities over assembly-only competitors.
Growth Catalysts
- Resort and restaurant infrastructure expansion:Hospitality operators across the United States are deploying weatherproof entertainment systems to extend usable outdoor square footage and capture incremental food-and-beverage revenue streams.
- FCC equipment authorization framework:The United States regulatory body is streamlining RF module certification pathways for Wi-Fi and Bluetooth connectivity, accelerating product launch cycles for compliant manufacturers.
- Quantum dot color enhancement:QLED architectures are penetrating premium residential installations through improved direct-sun readability and extended color gamut performance.
Market Restraints
- Indium and rare-earth supply concentration:Quantum dot phosphor materials depend on processing capacity concentrated in Chinese refining operations, exposing margin structures to export restriction volatility.
- All-weather engineering capex barriers:Specialized thermal management and ingress protection R&D requires sustained capital commitment that excludes mid-tier electronics assemblers from commercial certification tiers.
- REACH substance restriction compliance:The European framework is elevating material substitution costs for display assemblies and power supply components, compressing returns on multi-regional product lines.
Strategic Opportunities
- Indian hospitality infrastructure buildout:The country's resort and restaurant sectors are accelerating outdoor entertainment deployments ahead of BIS certification harmonization with international IP rating standards.
- CE marking pathway expansion:The European conformity framework is creating first-mover advantages for manufacturers achieving dual FCC-CE certification, unlocking cross-Atlantic distribution efficiency.
- Ambient light sensor integration:Convergence between adaptive brightness algorithms and low-power wide-area connectivity is enabling predictive maintenance service models for commercial installation fleets.
Industry Challenges
- Thermal engineering talent scarcity:The specialized skill set combining display physics with outdoor enclosure design concentrates within a limited pool of experienced engineers, constraining R&D velocity for new entrants.
- Multi-regional certification timeline compression:Divergent IP rating interpretations between FCC, CE marking, and emerging energy efficiency labeling requirements are fragmenting product development roadmaps and delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Outdoor TV Market |
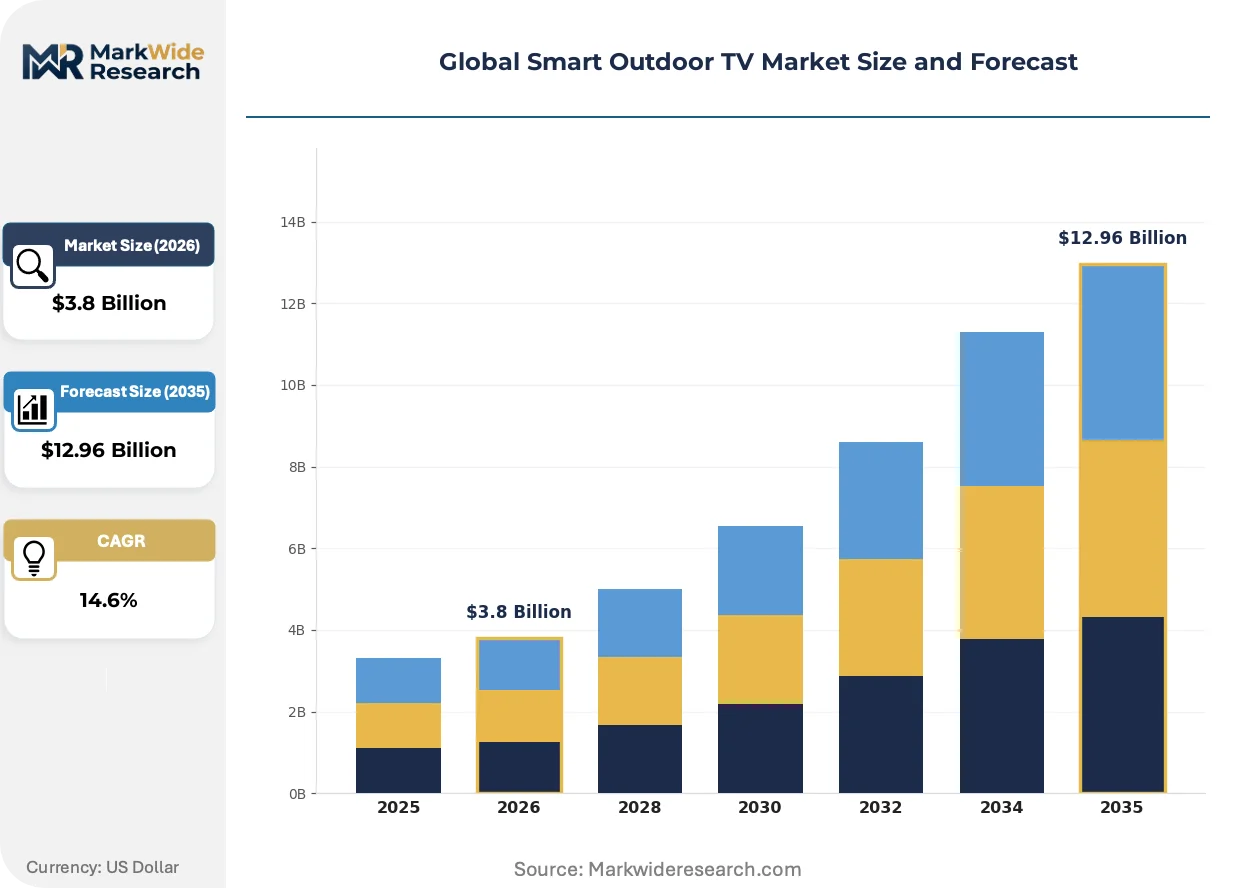
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, OLED, QLED, LCD Installation Type: Wall-Mounted, Freestanding, Portable, Built-in Connectivity: Wi-Fi, Bluetooth, Ethernet, Miracast End User: Residential, Commercial, Hospitality, Public Spaces |
| Companies Covered | Samsung Electronics, LG Electronics, SunBriteTV, Sony, Hisense, Sylvox, Séura, Furrion, Peerless-AV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Outdoor TV Market Strategic Shifts
Outdoor display technology is undergoing fundamental restructuring around adaptive environmental response systems and modular thermal architectures that separate premium positioning from commodity volume tiers.
Mini-LED backlighting with zone-dimming control is rewriting brightness tolerance economics for full-sun applications. High-end residential installers are specifying these configurations for poolside and deck environments where direct exposure exceeds conventional LCD performance thresholds. The technology is compressing the performance gap between cost-engineered LED formats and quantum dot premium tiers, forcing manufacturers to accelerate QLED cost reduction roadmaps.
REACH and RoHS frameworks are tightening hazardous substance restrictions across European market access pathways. Display manufacturers serving multiple regulatory zones face elevated material compliance costs for lead-free solder alternatives and restricted flame retardant substitutions. Commercial installation channels in Germany and France are prioritizing pre-certified component suppliers to avoid customs detention and project delay penalties.
Certification-driven procurement preferences are displacing specification-based buying in United States hospitality deployments. Resort operators in Florida and Arizona are mandating FCC-authorized units with documented IP65+ ratings to secure property insurance coverage and reduce liability exposure. This behavioral shift is consolidating specification influence among national installation contractors with direct regulatory compliance verification capabilities, marginalizing regional dealers without certification documentation infrastructure.
Global Smart Outdoor TV Market Segmentation
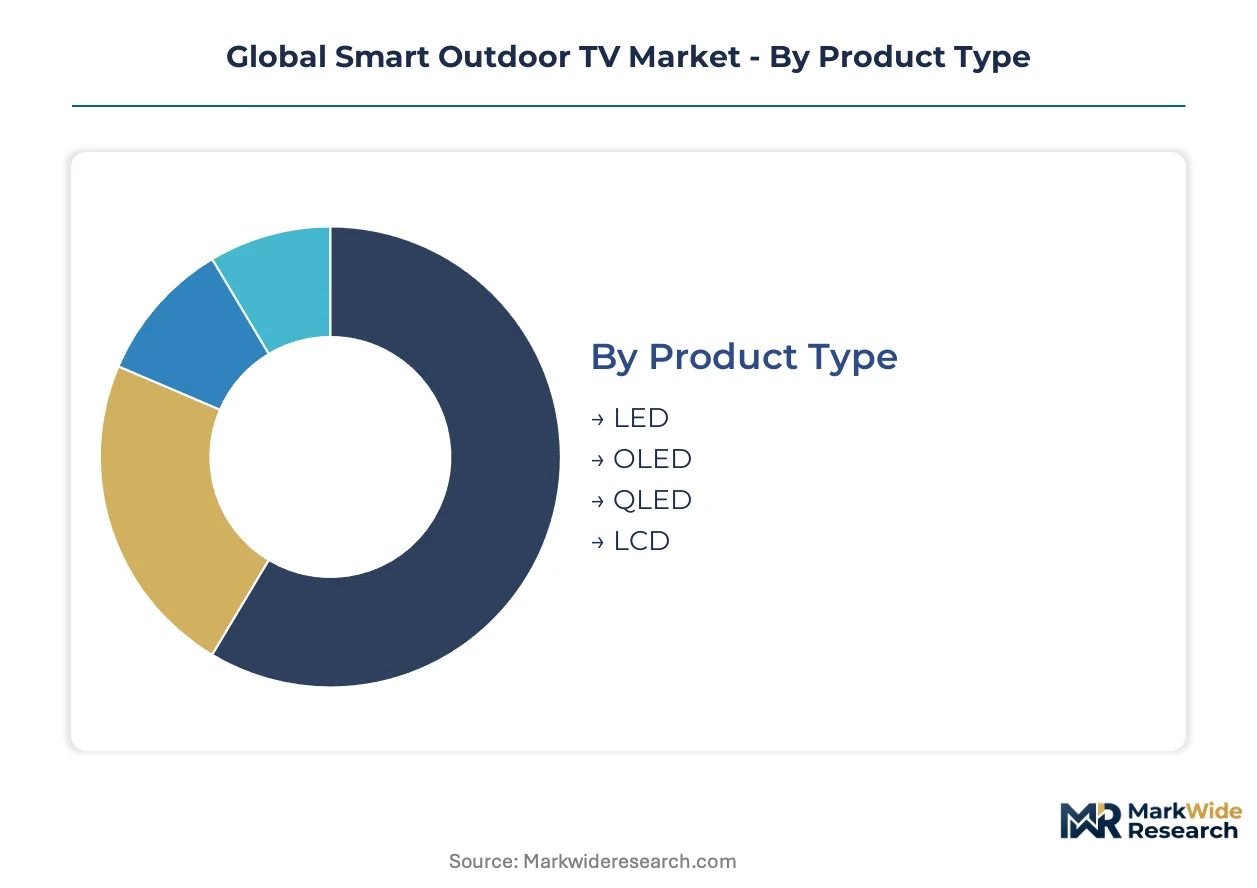
Smart outdoor television segmentation reflects divergent engineering requirements across thermal tolerance, ingress protection grades, and installation permanence. Product architecture choices cascade into distinct regulatory compliance pathways and margin structures that reshape competitive positioning across residential and commercial channels.
Product Type:
Display technology selection determines brightness economics, color gamut performance, and semiconductor supply chain exposure.
- QLED:Quantum dot phosphor layers enhance direct-sun readability through expanded color volume and sustained luminance above one-thousand nits. Resort operators in Florida and Arizona specify these configurations for poolside installations where ambient light rejection determines guest experience quality.
- LED:Direct backlighting with zone-dimming control delivers cost-engineered brightness tolerance for residential patio applications. Manufacturers serving the United States and Germany leverage manufacturing scale to compress pricing gaps against premium tiers.
- OLED:Self-emissive pixel architecture eliminates backlight thermal load but faces luminance degradation risks under sustained full-sun exposure.
- LCD:Mature edge-lit configurations dominate replacement cycles in budget-conscious commercial deployments.
Mature deployment sits with LCD. Newer deployment is concentrated in QLED.
Installation Type:
Mounting permanence shapes structural engineering requirements, insurance liability exposure, and channel access patterns.
- Wall-Mounted:Fixed enclosures with integrated thermal management dominate hospitality specifications in the United States where property insurance mandates documented IP65+ ratings. National installation contractors consolidate specification influence through direct FCC compliance verification capabilities.
- Freestanding:Modular pedestal configurations with weatherized housing gain traction in residential poolside and deck environments where structural modification is constrained. Demand concentrates in Germany and France where rental property regulations limit permanent fixture installation.
- Portable:Battery-integrated units with wheeled transport enable temporary event deployments in United States sports venues and European festival circuits.
- Built-in:Custom enclosure integration with architectural elements serves high-end residential new construction in the United Arab Emirates and Saudi Arabia.
Volume concentration sits with Wall-Mounted. Margin expansion is concentrated in Built-in.
Connectivity:
Wireless protocol selection determines FCC equipment authorization pathways and RF interference resilience in dense commercial deployments.
- Wi-Fi:Dual-band modules with DFS channel support enable streaming-capable throughput in hospitality environments with high client density. United States resort operators mandate documented FCC authorization to secure property coverage.
- Bluetooth:Low-energy protocols support peripheral pairing for outdoor audio systems and mobile device control in residential patio settings across the United States and United Kingdom.
- Ethernet:Hardwired connectivity eliminates RF certification complexity for permanent commercial installations in Germany where CE marking electromagnetic compatibility requirements are stringent.
- Miracast:Direct screen-mirroring protocols reduce network infrastructure dependency for temporary event deployments in Indian hospitality infrastructure buildout.
Regulatory complexity sits with Wi-Fi. Deployment simplicity is concentrated in Ethernet.
End User:
Customer category determines specification authority, procurement cycle length, and service model requirements.
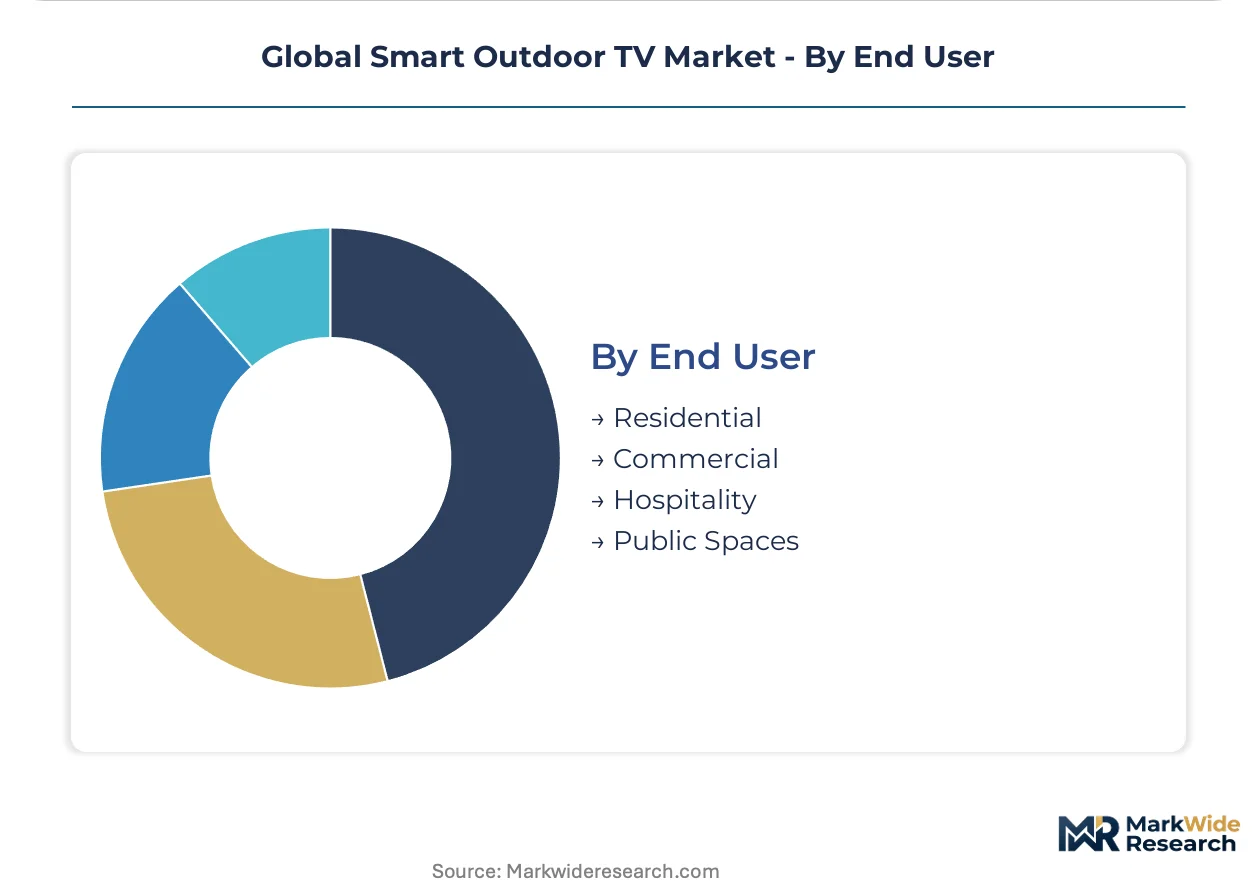
- Hospitality:United States resort and restaurant operators drive premium tier absorption through revenue-per-square-foot optimization of outdoor dining and entertainment spaces. FCC-authorized units with predictive maintenance service models capture specification influence.
- Residential:Patio and deck installations in the United States and Germany favor cost-engineered LED formats with freestanding flexibility to avoid structural modification constraints.
- Commercial:Corporate campus and retail deployments in France and the United Kingdom prioritize CE marking pre-certification to avoid customs detention penalties.
- Public Spaces:Municipal and transportation applications in India accelerate ahead of BIS certification harmonization with international IP rating standards.
Procurement maturity sits with Commercial. Steepest expansion trajectory is concentrated in Hospitality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orlando, Florida anchors hospitality-driven outdoor display procurement as resort operators expand poolside entertainment infrastructure ahead of peak tourism seasons. The city's concentration of theme park adjacent properties creates specification density unmatched elsewhere. This cluster pattern repeats across four additional national markets with distinct regulatory and demand profiles.
United States
Resort operators in Arizona and Florida mandate FCC-authorized units with IP65+ ratings to secure property insurance coverage for outdoor dining expansions. FCC equipment authorization streamlines RF module certification for Wi-Fi and Bluetooth connectivity. Installation contractors in Orlando and Phoenix consolidate specification influence through direct compliance verification capabilities.
Germany
Commercial campus deployments prioritize CE marking pre-certification to avoid electromagnetic compatibility penalties under stringent federal enforcement. REACH substance restrictions elevate material substitution costs for lead-free solder alternatives in display assemblies. Industrial clusters in Bavaria and Baden-Württemberg concentrate procurement specification authority among national installation contractors.
India
Resort infrastructure buildout accelerates outdoor entertainment deployments ahead of BIS certification harmonization with international IP rating standards. The Bureau of Indian Standards is developing convergence timelines for enclosure testing protocols. Hospitality development corridors in Maharashtra and Karnataka absorb preliminary volume as operators anticipate regulatory alignment.
United Arab Emirates
High-end residential new construction in Dubai and Abu Dhabi drives built-in custom enclosure integration with architectural elements. MOHAP medical device adjacent standards influence thermal management expectations for extreme climate operation. Luxury property developments along the Palm Jumeirah corridor specify adaptive brightness systems for sustained full-sun exposure.
United Kingdom
Residential patio installations favor freestanding configurations to avoid structural modification constraints under rental property regulations. CE marking governs market access with particular emphasis on electromagnetic compatibility for dense urban wireless environments. Installation demand concentrates in Greater London and the Southeast where outdoor living space premiums justify weatherized entertainment investment.
Global Smart Outdoor TV Market Competitive Environment
Capital-heavy producers compete with asset-light designers across a bifurcated structure where captive semiconductor capabilities separate premium positioning from assembly-only commodity tiers. The vendor base concentrates around three strategic archetypes: vertically integrated electronics conglomerates, specialized all-weather engineering houses, and cost-optimized residential specialists. M&A activity targets thermal management IP portfolios while geographic expansion focuses on dual FCC-CE certification pathways for cross-Atlantic distribution efficiency.
Among Korean and Japanese electronics conglomerates, Samsung Electronics and LG Electronics exemplify the vertically integrated archetype through in-house semiconductor production. Sony occupies a position bridging professional display heritage with consumer outdoor adaptation. Specialized all-weather engineering is represented by SunBriteTV, which anchors commercial installation channel relationships through dedicated enclosure R&D. Sylvox sits within the cost-engineered tier competing on LED format accessibility for residential patio applications.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| SunBriteTV |
| Sony |
| Hisense |
| Sylvox |
| Séura |
| Furrion |
| Peerless-AV |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between FCC-authorized commercial tiers and uncertified residential alternatives manifests in both pricing premiums and supply chain sourcing strategies. QLED configurations with documented IP65+ ratings command substantial markups through captive semiconductor supply chains, while cost-engineered LED formats compress margins through commoditized backlight module procurement.
Pricing Analysis
Uptime-guaranteed performance anchors value-based pricing for hospitality deployments where revenue-per-square-foot optimization justifies premium outlays. Three-tier pricing structure across premium, standard, and economy levels stratifies by brightness tolerance, thermal management architecture, and after-sales service bundling. Cost compression in LED residential tiers intensifies because manufacturing scale advantages concentrate among Asian panel suppliers. Commercial hospitality operators exhibit lowest price sensitivity due to insurance mandate compliance requirements, whereas residential patio buyers in Germany and the United Kingdom demonstrate acute sensitivity to freestanding configuration costs.
Supply Chain Analysis
IP rating certification gating concentrates qualified enclosure manufacturing in China, Taiwan, and South Korea where thermal management engineering capabilities have matured. Quantum dot phosphor materials draw from Chinese rare-earth refining operations, while LED backlight modules source from vertically integrated Korean display conglomerates. Single-source vulnerability in indium processing exposes margin structures to export restriction volatility. Distribution runs through national installation contractors in the United States and certified system integrators in Germany rather than traditional consumer electronics retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained thermal engineering talent pools prop pricing power for incumbent manufacturers with captive R&D capabilities. Specialized enclosure design expertise functions as the binding capacity bottleneck preventing rapid competitive entry.
For Market Incumbents: Lock in specification influence through predictive maintenance service models tied to FCC-authorized installation fleets. Deepen backward integration into quantum dot phosphor supply to offset Chinese rare-earth export volatility. Acquire thermal management IP portfolios from distressed mid-tier engineering houses before BIS certification harmonization accelerates Indian market entry. For New Entrants and Emerging Players: Direct-to-residential digital channels bypass entrenched contractor networks that dominate United States hospitality procurement. Target freestanding LED configurations for German rental property regulations where permanent fixture restrictions create white-space demand. Pursue CE marking pre-certification to unlock cross-Atlantic distribution without competing head-to-head with SunBriteTV's commercial channel lock. For Investors and Strategic Acquirers: Re-rating potential sits with specialized all-weather engineering houses given ambient light sensor convergence enabling recurring service revenue streams. Long-term viability favors targets with dual FCC-CE certification infrastructure spanning the analysis window. Watch BIS-IP rating harmonization timelines as the inflection signal for Indian hospitality infrastructure buildout acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | FCC-CE pathway convergence unlocks cross-Atlantic distribution efficiency for enclosure manufacturers. |
| Predictive Maintenance Platform | Ambient light sensor integration enables recurring revenue from commercial installation fleet servicing. |
| Quantum Dot Supply Security | Backward integration into phosphor materials mitigates Chinese rare-earth export restriction exposure. |
| Indian Market Pre-Positioning | BIS harmonization anticipation captures resort infrastructure buildout ahead of regulatory alignment. |
| Thermal Engineering Talent Acquisition | Specialized display-physics expertise constraints R&D velocity for competitors without captive pools. |
Study Parameters
Trade publications, customs filings, and SEC 10-K disclosures formed the secondary backbone for supply chain mapping and pricing tier validation. Primary interviews with hospitality procurement directors, commercial installation contractors, display panel procurement managers, and thermal engineering specialists combined with secondary validation through bottom-up and top-down triangulation. FCC equipment authorization databases and CE marking registries provided regulatory compliance verification across jurisdictions.
Historical trendline analysis of enclosure manufacturing capacity, brightness tolerance adoption curves, and hospitality capital expenditure patterns informed the analytical framework across the projection horizon. Segmentation dimensions modeled include display technology type, installation permanence, connectivity protocol, and end-user category alongside regional regulatory cluster differentiation. CAGRs derived from unit shipment trajectories correlated with average selling price evolution and input cost indices for quantum dot materials and IP-rated enclosure components.
Inputs from hospitality procurement databases and commercial installation contractor surveys were available through the study window; gaps in Indian BIS certification timeline specificity introduce uncertainty bands around subcontinent penetration assumptions. Forecasts reflect documented assumptions regarding thermal management cost reduction curves and rare-earth supply stability. A model refresh is warranted upon material change in FCC equipment authorization pathway streamlining or REACH substance restriction expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
US Refurbished and Used Mobile Phones Market
Consumer Electronics
Speakerphones Market
Consumer Electronics
IoT in Consumer Electronics Market
Consumer Electronics
Global Polaroid Market
Consumer Electronics
Shoe Shining Machine Market
Consumer Electronics
Smart Phones Market
Consumer Electronics
DVD Remote Controls Market
Consumer Electronics
Asia-Pacific Professional Audio-Visual Systems Market
Consumer Electronics
Streaming Devices Market
Consumer Electronics
Airport Retailing Consumer Electronics Market
Consumer Electronics
Global Hearable Devices Market
Consumer Electronics
Silicone Sex Doll Market
Consumer Electronics
Gaming Laptops and Desktops Market
Consumer Electronics
Foldable Phone Market
Consumer Electronics
True Wireless Stereo Market
Consumer Electronics
Keycap Market