
 Pet Monitoring Camera Market | 2026-2036
Pet Monitoring Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Monitoring Camera Market Analysis
Shenzhen's consumer electronics manufacturing base is consolidating as the dominant production hub for connected pet hardware. PETKIT leverages integrated app ecosystems to sustain recurring revenue beyond device sales. Wyze Labs, Inc. anchors its position through aggressive pricing and direct-to-consumer channel control. Shenzhen Skymee Technology Co., Ltd. specializes in OEM partnerships that extend its reach into private-label retail across North America and Europe.
Pet monitoring cameras are network-connected imaging devices equipped with Wi-Fi transceivers, infrared LEDs for night vision, and CMOS sensors typically ranging from 1080p to 4K resolution, designed to transmit real-time video and audio streams to mobile applications for remote animal observation. Indoor cameras dominate unit shipments due to apartment-dwelling demographics, while smart cameras with integrated treat dispensers and AI bark detection capture premium margin pools. Motion detection technology leads feature differentiation, though cloud storage subscriptions increasingly determine lifetime customer value across all product tiers.
FCC Part 15 rules in the United States and CE marking under the EU Radio Equipment Directive govern wireless transmission compliance, while China's MIIT issues network access licenses that determine domestic market eligibility. These frameworks elevate testing costs for new entrants but also create compliance-based segmentation between certified premium channels and uncertified gray-market imports. Stakeholders must weigh hardware margin compression against software subscription attach rates when allocating R&D budgets across sensor upgrades versus platform development.
Market Dynamics
Remote work normalization has permanently altered daily absence patterns for pet owners, creating sustained baseline demand for real-time video monitoring and two-way audio interaction with companion animals left in residential spaces.
Growth Catalysts
- FCC Part 15 Certification:Wireless device approval in the United States opens retail distribution through Best Buy, Amazon, and Chewy, channelizing volume through certified premium tiers rather than gray-market imports.
- Apartment-Dwelling Demographics:Urban household concentration in Shanghai, New York, and London restricts pet mobility and amplifies owner anxiety during workday separations, driving camera installation rates.
- CMOS Sensor Cost Curves:1080p to 4K imaging module price declines enable manufacturers to upgrade resolution specifications without passing full cost increases to end consumers.
Market Restraints
- Silicon Supply Concentration:Taiwan Semiconductor Manufacturing Company and Samsung Foundry control advanced node production for image signal processors, exposing hardware roadmaps to foundry allocation decisions.
- CE Marking Complexity:EU Radio Equipment Directive testing protocols for 2.4 GHz and 5 GHz Wi-Fi transceivers extend product launch timelines by four to six months for new entrants.
- Smartphone Substitution:Repurposed old phones with free pet-monitoring apps capture price-sensitive demand in emerging markets, compressing addressable volume for dedicated hardware.
Strategic Opportunities
- India Pet Care Expansion:Bengaluru and Mumbai register double-digit annual growth in registered companion animals, yet penetration of connected pet hardware remains below five percent of addressable households.
- Veterinary Telehealth Integration:Cameras with AI symptom detection enabling remote clinical consultations create subscription revenue streams beyond basic cloud storage.
- EU Green Deal Alignment:Repairability requirements and recycled plastic content mandates favor modular designs that extend product lifecycles and reduce return rates.
Industry Challenges
- Embedded Firmware Talent Scarcity:Real-time video streaming optimization for low-latency mobile delivery requires specialized engineers concentrated in Shenzhen and Taipei, inflating compensation costs.
- Cloud Infrastructure Capex:AWS and Azure storage commitments for multi-year video retention impose fixed cost burdens that scale unevenly with subscriber acquisition volatility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Monitoring Camera Market |
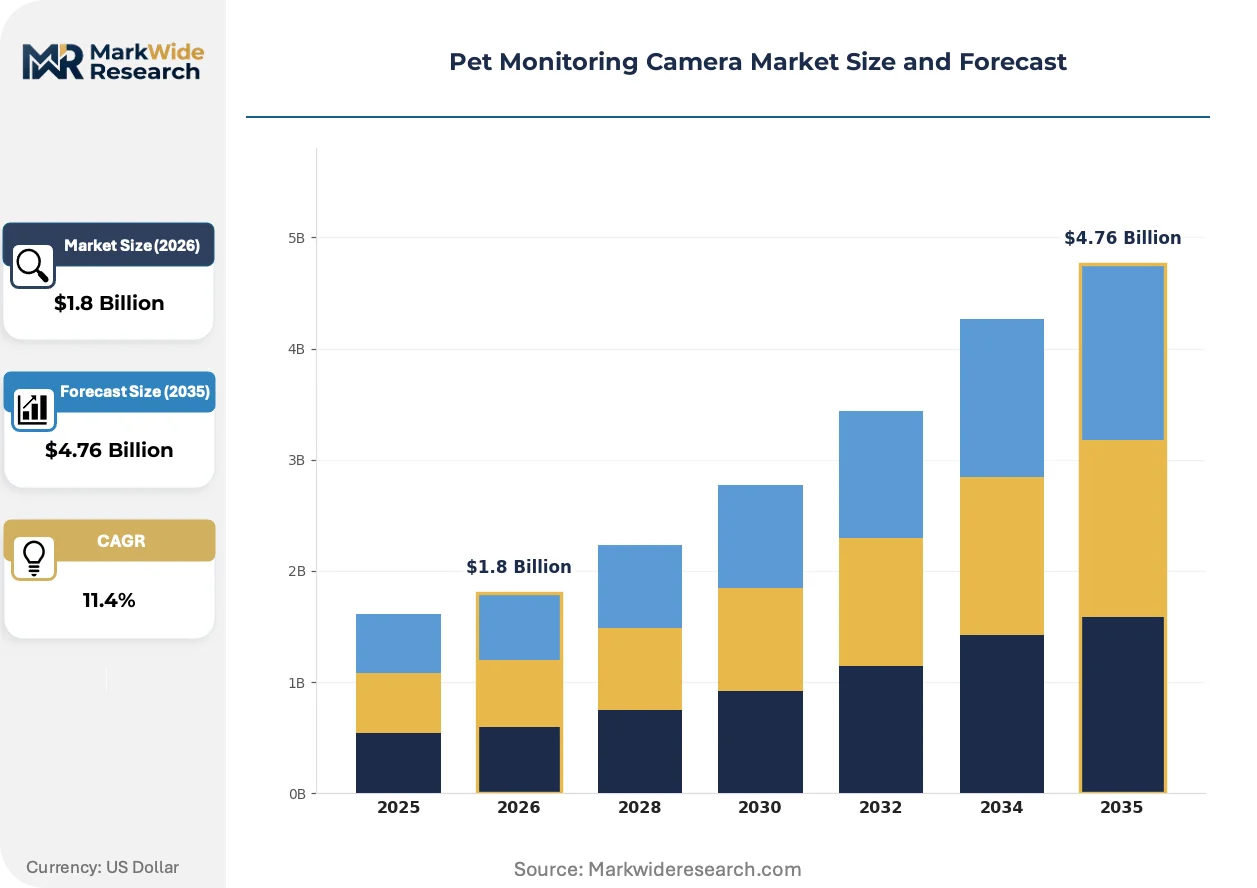
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Camera, Outdoor Camera, Smart Camera, HD Camera Technology: Wi-Fi, Bluetooth, Night Vision, Motion Detection End User: Pet Owners, Pet Sitters, Veterinary Clinics, Animal Shelters Feature: Two-Way Audio, Cloud Storage, Remote Access, Video Recording |
| Companies Covered | PETKIT, Wyze Labs, Inc., PetChatz, Shenzhen Skymee Technology Co., Ltd., Xiaomi, Zmodo, SpotCam Co., Ltd., Petcube, Inc., Direct Smart Home, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Monitoring Camera Market Emerging Trajectories
Edge AI inference is migrating from cloud servers to device silicon, enabling bark detection and motion classification without continuous bandwidth consumption or subscription dependencies.
On-device machine learning accelerators are decentralizing video analytics from centralized cloud pipelines. Premium camera lines from Shenzhen manufacturers now embed neural processing units capable of pet behavior recognition without frame transmission. Apartment owners in Tokyo and Seoul adopt these units to reduce monthly cloud storage fees. The shift compresses recurring revenue for platform operators while lowering total cost of ownership for end users.
EU AI Act risk classification rules are reshaping feature development roadmaps for biometric identification capabilities. Cameras with pet facial recognition now face conformity assessment obligations in European markets, extending certification timelines. Manufacturers are responding by segmenting product lines: basic motion detection for EU distribution, advanced AI features for North American and Asian markets where regulatory thresholds remain higher.
Subscription unbundling is fragmenting the traditional hardware-plus-service bundle. Chewy and Amazon now list cameras with optional cloud tiers rather than mandatory annual commitments. This pattern is most visible in United States direct-to-consumer channels, where buyers compare total three-year ownership costs across competing platforms. Hardware margins compress as subscription attach rates become the primary profitability determinant.
Pet Monitoring Camera Market Segmentation
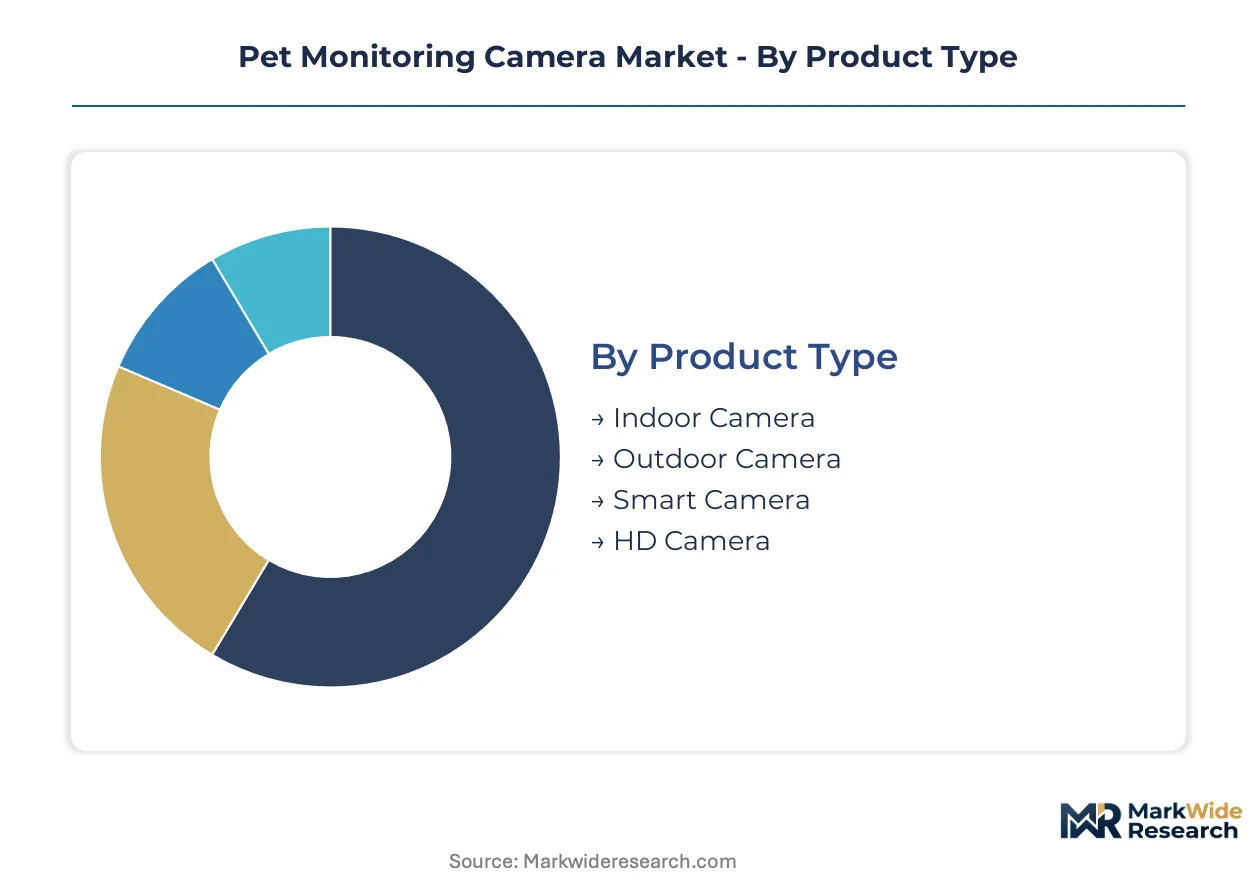
Pet monitoring camera segmentation reveals how hardware specifications, connectivity protocols, and user workflows fragment addressable demand. Manufacturers must align sensor investments, certification pathways, and subscription architectures to specific buyer profiles rather than pursuing undifferentiated volume.
Product Type:
Capital intensity varies sharply across housing designs, with weatherproofing and thermal management driving outdoor unit costs substantially above indoor equivalents.
- Indoor Camera:Compact enclosures with CMOS sensors ranging from 1080p to 4K resolution dominate unit economics. Shanghai and New York apartment complexes generate concentrated demand as remote work normalizes extended pet absences in confined residential spaces.
- Smart Camera:Integrated treat dispensers, AI bark detection, and neural processing units command premium positioning. Shenzhen manufacturers embed edge inference chips to reduce cloud dependency and monthly subscription burdens for Tokyo and Seoul owners.
- Outdoor Camera:IP65+ ingress protection and extended temperature tolerances elevate bill-of-materials costs. Demand concentrates in suburban United States households with yard access.
- HD Camera:2K and 4K imaging modules leverage declining CMOS cost curves for specification upgrades without proportional price increases. Adoption tracks bandwidth infrastructure quality in target markets.
Most installed capacity flows through Indoor Camera. Expansion is steepest in Smart Camera.
Technology:
Wireless protocol selection determines regulatory compliance burden and interoperability with existing smart home ecosystems.
- Wi-Fi:Dual-band 2.4 GHz and 5 GHz transceivers enable real-time streaming to mobile applications. FCC Part 15 certification in the United States and CE marking under the EU Radio Equipment Directive govern market access, with testing timelines extending four to six months for new entrants.
- Motion Detection:Passive infrared and pixel-change algorithms trigger recording and mobile alerts without continuous bandwidth consumption. Shenzhen firmware teams optimize detection sensitivity for pet-versus-human classification.
- Night Vision:Infrared LED arrays and low-light CMOS sensitivity specifications enable 24-hour monitoring. Demand correlates with owner work schedules in Northern European markets.
- Bluetooth:Low-energy pairing for initial setup and local device management. Secondary to Wi-Fi for primary video transmission due to bandwidth constraints.
Wi-Fi carries the majority of connected volume. Motion Detection is climbing the fastest as edge AI reduces cloud dependency.
End User:
Procurement authority and subscription willingness diverge across owner-operated versus institutional deployment contexts.
- Pet Owners:Direct purchasers seeking emotional reassurance and behavioral monitoring for companion animals. Urban apartment dwellers in London and Mumbai show elevated installation rates correlating with workday separation anxiety.
- Veterinary Clinics:Post-operative observation and remote symptom assessment drive clinical adoption. Cameras with AI-enabled anomaly detection support telehealth subscription revenue streams.
- Pet Sitters:Gig-economy caregivers use client-installed devices for verification and communication rather than owning dedicated hardware.
- Animal Shelters:Non-profit budget constraints favor refurbished or donated equipment over new procurement cycles.
Pet Owners account for dominant unit absorption. Veterinary Clinics are gaining share fastest through telehealth integration.
Feature:
Software-enabled capabilities increasingly determine lifetime customer value and platform stickiness beyond initial hardware margins.
- Cloud Storage:Subscription-based video retention generates recurring revenue that often exceeds device profit over three-year ownership horizons. AWS and Azure infrastructure commitments impose fixed cost scaling challenges for platform operators.
- Two-Way Audio:Full-duplex voice communication allows remote interaction with pets during owner absences. Apartment complexes in dense Asian cities show highest feature utilization rates.
- Remote Access:Mobile application streaming with sub-500ms latency requirements drives firmware optimization investment in Shenzhen and Taipei engineering centers.
- Video Recording:Local SD card and network-attached storage options appeal to privacy-conscious buyers avoiding subscription dependencies.
Cloud Storage anchors recurring revenue architecture. Two-Way Audio shows steepest expansion as emotional engagement features differentiate competing platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials between certification regimes are redistributing production capacity toward jurisdictions with streamlined compliance pathways. Shenzhen's electronics cluster captures disproportionate hardware assembly volume as FCC Part 15 and CE marking timelines impose four-to-six-month delays on new entrants elsewhere.
United States
Urban apartment concentration in New York and Los Angeles sustains baseline demand for indoor monitoring solutions. FCC Part 15 certification governs wireless device market access, channelizing retail distribution through Best Buy, Amazon, and Chewy. Silicon Valley firmware engineering centers concentrate real-time video streaming optimization talent.
China
MIIT network access licenses determine domestic eligibility for Wi-Fi-enabled devices. Shenzhen's manufacturing ecosystem enables rapid hardware iteration and cost-efficient production at scale. Yangtze River Delta component suppliers feed CMOS sensor and infrared LED module demand.
Germany
EU Green Deal repairability requirements favor modular camera designs extending product lifecycles. CE marking under the Radio Equipment Directive governs 2.4 GHz and 5 GHz transceiver compliance. Bavaria-based smart home integrators distribute premium-tier hardware through specialized retail channels.
Japan
METI energy efficiency standards shape power consumption specifications for always-connected devices. Tokyo and Osaka apartment dwellers show elevated adoption of edge AI cameras reducing cloud subscription dependencies. Kanto region engineering centers specialize in low-latency mobile application development.
United Kingdom
London household concentration drives installation rates correlating with workday pet separation anxiety. GDPR compliance obligations elevate data processing transparency requirements for cloud storage providers. Southeast England logistics hubs handle EU-UK distribution following post-Brexit customs realignment.
Pet Monitoring Camera Market Vendor Landscape
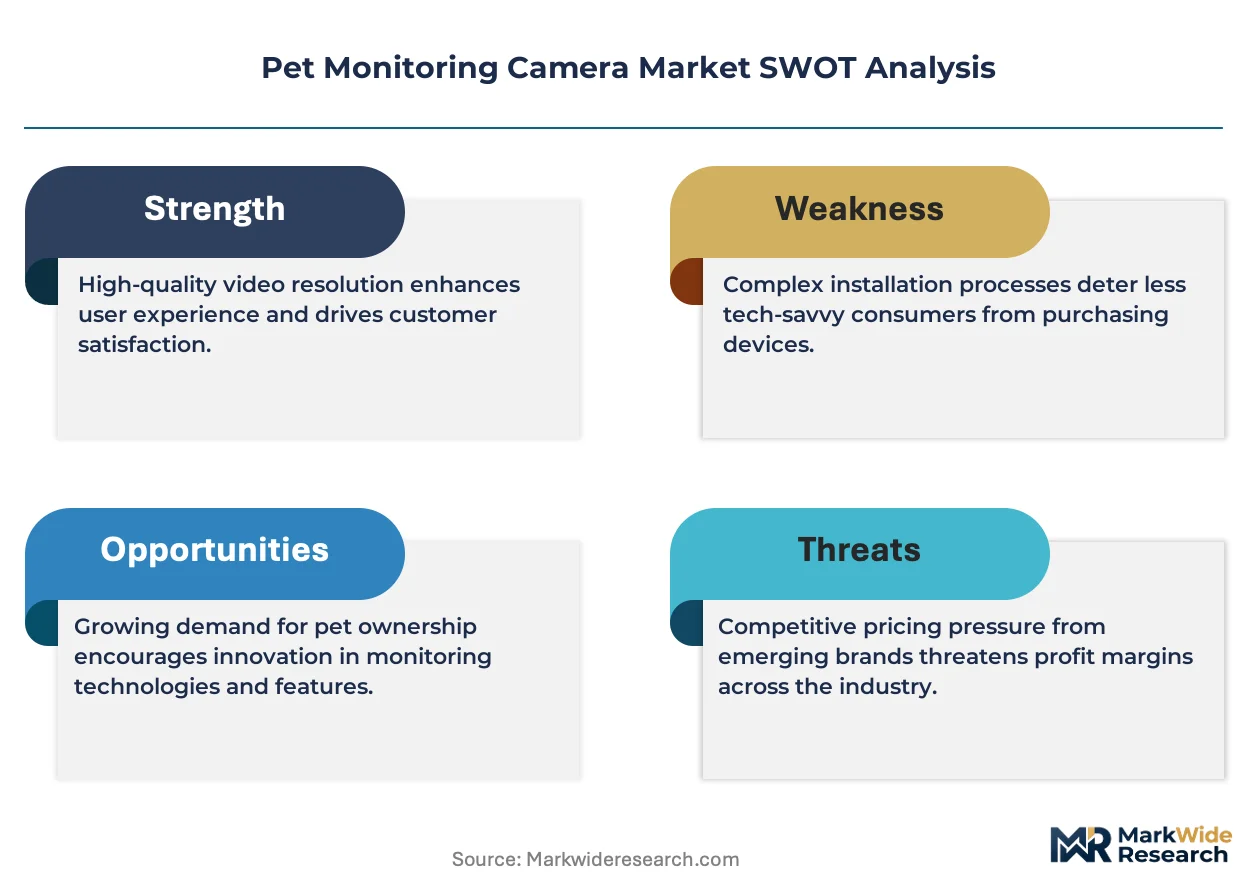
Shenzhen-based producers anchor the volume tier; California and Taipei specialists hold premium positioning. Market structure fragments across hardware OEMs, integrated platform operators, and direct-to-consumer brands. Three archetypes dominate: vertically integrated electronics manufacturers, app-ecosystem builders, and price-focused channel disrupters. Capacity expansion and strategic partnership formation represent the dominant competitive moves as firms balance hardware margin compression against software subscription attach rates.
Within the integrated platform tier, PETKIT exemplifies recurring revenue architecture through captive app ecosystems. Wyze Labs, Inc. occupies a position among direct-to-consumer disrupters leveraging aggressive pricing and channel control. Shenzhen Skymee Technology Co., Ltd. represents the OEM partnership archetype extending reach into private-label retail across North America and Europe.
| Leading Market Players |
|---|
| PETKIT |
| Wyze Labs, Inc. |
| PetChatz |
| Shenzhen Skymee Technology Co., Ltd. |
| Xiaomi |
| Zmodo |
| SpotCam Co., Ltd. |
| Petcube, Inc. |
| Direct Smart Home |
| Others |
Supply Flow & Price Mechanics
Captive CMOS sensor sourcing from Yangtze River Delta suppliers anchors Shenzhen manufacturers' cost position and pricing power against North American and European competitors facing four-to-six-month certification delays. This backward integration into imaging module procurement compresses bill-of-materials variance while enabling aggressive specification upgrades at stable price points.
Pricing Analysis
Retailer markup layers at Best Buy and Chewy compress hardware margins while subscription attach rates determine lifetime profitability. Three-tier pricing structure across premium smart cameras with edge AI, standard Wi-Fi units with cloud storage, and economy indoor models without subscription bundling separates buyer segments. Cost compression in the economy tier intensifies as repurposed smartphone apps capture price-sensitive demand in emerging markets. Pet owners in urban apartments show lowest price sensitivity for emotional reassurance features, while animal shelters operate under severe budget constraints favoring donated equipment.
Supply Chain Analysis
Dual-sourcing requirements for Wi-Fi transceivers and image signal processors are rarely met given Taiwan Semiconductor Manufacturing Company and Samsung Foundry dominance at advanced nodes. Component procurement draws from China for CMOS sensors and infrared LEDs, Taiwan for neural processing units, and South Korea for memory modules. Single-source vulnerability at the foundry level exposes hardware roadmaps to allocation decisions during capacity constraints. Distribution runs through direct-to-consumer channels controlled by Shenzhen OEMs and Amazon marketplace listings rather than traditional electronics distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pet monitoring camera market compounds steadily as remote work permanence sustains baseline demand for real-time companion animal observation across apartment-dwelling demographics globally.
For Market Incumbents: Anticipate margin compression from edge AI migration that reduces cloud subscription dependencies among Tokyo and Seoul owners. Defend position by deepening firmware optimization investment in Shenzhen engineering centers and securing FCC Part 15 certification moats that delay new entrant retail access. Channel control through Chewy and Amazon exclusive arrangements remains critical as subscription unbundling fragments traditional hardware-plus-service bundles. For New Entrants and Emerging Players: Begin with veterinary telehealth integration as the most penetrable white-space target, where AI symptom detection enables subscription revenue beyond basic cloud storage. India pet care expansion offers geographic entry with connected hardware penetration below five percent of addressable households in Bengaluru and Mumbai. Direct-to-consumer positioning through specialized pet wellness platforms avoids head-to-head competition with established electronics brands. For Investors and Strategic Acquirers: Roll-up economics work for integrated platform operators because recurring app ecosystem revenue generates lifetime value multiples exceeding pure hardware manufacturers. Five-to-ten-year viability hinges on subscription attach rate sustainability as edge AI displaces cloud dependency. Target acquisition archetype: Shenzhen-based OEMs with private-label retail relationships across North America and Europe. Watch for inflection when EU AI Act enforcement accelerates product line segmentation between basic motion detection and advanced biometric features.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Chip Integration | Neural processing units in Shenzhen-manufactured cameras reduce AWS storage commitments for Tokyo owners. |
| Veterinary Telehealth Partnership | AI symptom detection capabilities create clinical subscription streams beyond consumer cloud storage tiers. |
| EU Green Deal Compliance | Modular repairable designs extend product lifecycles for German smart home integrators and reduce return rates. |
| Direct-to-Consumer Channel Control | Wyze Labs bypasses retailer markup layers through owned e-commerce, preserving margin for R&D reinvestment. |
| FCC Certification Investment | Part 15 approval opens Best Buy and Amazon distribution while imposing four-to-six-month delays on uncertified competitors. |
Methodological Framework
Bottom-up pet owner and veterinary clinic demand modeling reconciled against top-down Shenzhen manufacturing capacity tracking forms the analytical core. Primary interviews with connected pet hardware product managers, FCC certification consultants, Chewy category buyers, and AWS cloud infrastructure planners combined with secondary validation from MIIT network access license filings, CE marking databases under the EU Radio Equipment Directive, and App Annie mobile application download metrics. Triangulation between installation rate surveys in Shanghai and New York apartments and component procurement data from Yangtze River Delta suppliers ensures demand-supply consistency.
Input-output matrices map CMOS sensor cost curves, Wi-Fi module pricing, and cloud storage infrastructure commitments against segment-specific adoption rates across the projection horizon. Segmentation dimensions include product type (indoor, smart, outdoor, HD), technology protocol (Wi-Fi, Bluetooth, edge AI), end user (pet owners, veterinary clinics, pet sitters, shelters), and feature tier (cloud storage, two-way audio, remote access, local recording). CAGRs derive from regression analysis of historical penetration rates correlated with remote work normalization indices and apartment household formation data. Neural processing unit cost decline trajectories and FCC certification timeline distributions serve as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including abrupt foundry allocation disruptions at Taiwan Semiconductor Manufacturing Company, sudden EU AI Act enforcement escalations, and smartphone substitution acceleration in price-sensitive markets. Forecasts reflect documented assumptions regarding remote work permanence and cloud subscription willingness across urban demographics. Deviation in edge AI adoption velocity or veterinary telehealth reimbursement policy would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
North America Mobile Phone Accessories Market
Consumer Electronics
Android TV Box Market
Consumer Electronics
Global Hearable Devices Market
Consumer Electronics
Sleep Headphones Market
Consumer Electronics
Headset Market
Consumer Electronics
Used and Refurbished Smartphone Market
Consumer Electronics
US Mobile Phone Accessories Market
Consumer Electronics
Gaming Laptop Market
Consumer Electronics
Consumer Electronic Biometrics Market
Consumer Electronics
Middle East Radio Headset Market
Consumer Electronics
Global Monitor Headphones (in-Ear Monitors) Market
Consumer Electronics
Watch Market
Consumer Electronics
North America Wireless Anc Headphone Market
Consumer Electronics
Air Tube Headset Market
Consumer Electronics
Foldable Phone Market
Consumer Electronics
DIY PC Gaming Chassis Market