
 Stretch Sleeve Labels Market | 2026-2036
Stretch Sleeve Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Stretch Sleeve Labels Market Analytics
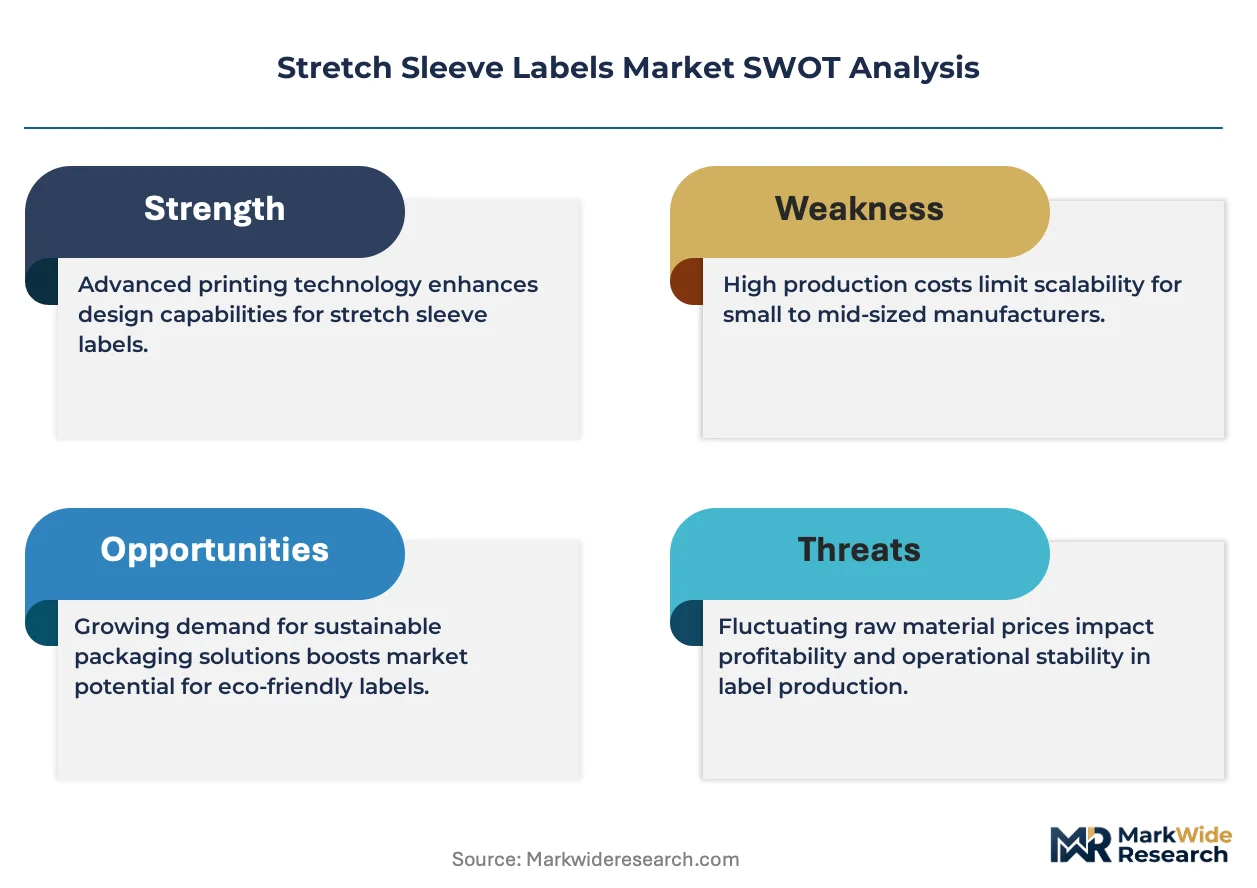
The EU Green Deal is realigning stretch sleeve label specifications across European beverage packaging. CCL Industries dominates printed shrink sleeve production through backward integration into film extrusion. Berry Global leverages its plastics manufacturing scale to supply pre-formed sleeve substrates. Avery Dennison competes with adhesive-free sleeve solutions that eliminate label removal steps in recycling streams.
Stretch sleeve labels are heat-shrinkable or stretchable polymeric sleeves applied over containers to provide full-body decoration, tamper evidence, and product information. These labels typically utilize oriented polyethylene or polypropylene films with thicknesses ranging from 30 to 50 microns, applied through mechanical stretching or steam tunnel shrinking. Polyethylene leads product type demand due to its compatibility with existing recycling infrastructure and lower shrink force requirements. Flexographic printing anchors technology deployment for long-run beverage applications, while digital printing is displacing analog methods in personal care and craft beverage segments requiring shorter runs and versioning.
The EPA guides container recycling standards in the United States, while REACH and the EU Packaging and Packaging Waste Regulation govern substance restrictions and recyclability mandates in Europe. FDA food-contact regulations additionally shape material selection for beverage and food end uses. ISO 18601 and related packaging environment standards provide voluntary frameworks that major brand owners increasingly embed in procurement specifications. Stakeholders must monitor evolving extended producer responsibility schemes and decide whether to invest in mono-material sleeve platforms or multi-layer barrier constructions.
Market Dynamics
The EU Green Deal's packaging waste directives are forcing a structural pivot toward mono-polymer sleeve constructions, rewiring material specifications across European beverage bottling lines and reshaping supplier qualification criteria.
Growth Catalysts
- Beverage Industry 360-Degree Decoration Demand:Brand owners in carbonated soft drinks and craft beer segments specify stretch sleeves for full-body graphic coverage and tamper-evident closure integration.
- REACH-Compliant Material Innovation:Film extruders reformulate polyethylene substrates to eliminate restricted phthalates while maintaining shrink performance for food-contact applications.
- German Equipment Ecosystem Concentration:Krones and Sidel bottling line installations in Bavaria and Baden-Württemberg create captive demand for compatible sleeve label formats.
Market Restraints
- Oriented Polypropylene Film Supply Concentration:European resin supply chains cluster around Rotterdam and Antwerp petrochemical corridors, exposing converters to force majeure disruptions.
- Steam Tunnel Energy Intensity:Shrinking operations require 150-200°C saturated steam, constraining adoption in facilities with carbon-neutral commitments or limited boiler capacity.
- Multi-Layer Barrier Substitution Threat:Direct-container printing technologies bypass sleeve application entirely for short-run premium SKUs.
Strategic Opportunities
- Underpenetrated Personal Care Segment:Shampoo and conditioner bottles in France and Italy remain dominated by pressure-sensitive labels, presenting white space for sleeve conversion.
- Digital-Flexographic Hybrid Workflows:Convergence of inkjet versioning for variable data with flexographic base decoration enables economical run-length flexibility.
- Extended Producer Responsibility Schemes:Germany's Verpackungsgesetz mandates higher recycling quotas, rewarding mono-material sleeve designs with fee reductions.
Industry Challenges
- Print-to-Shrink Registration Tolerance:Maintaining graphic alignment across 40-70% shrink ratios demands closed-loop vision systems and skilled press operators.
- Food-Contact Migration Certification:FDA and EFSA compliance timelines for new additive packages extend 18-24 months, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stretch Sleeve Labels Market |
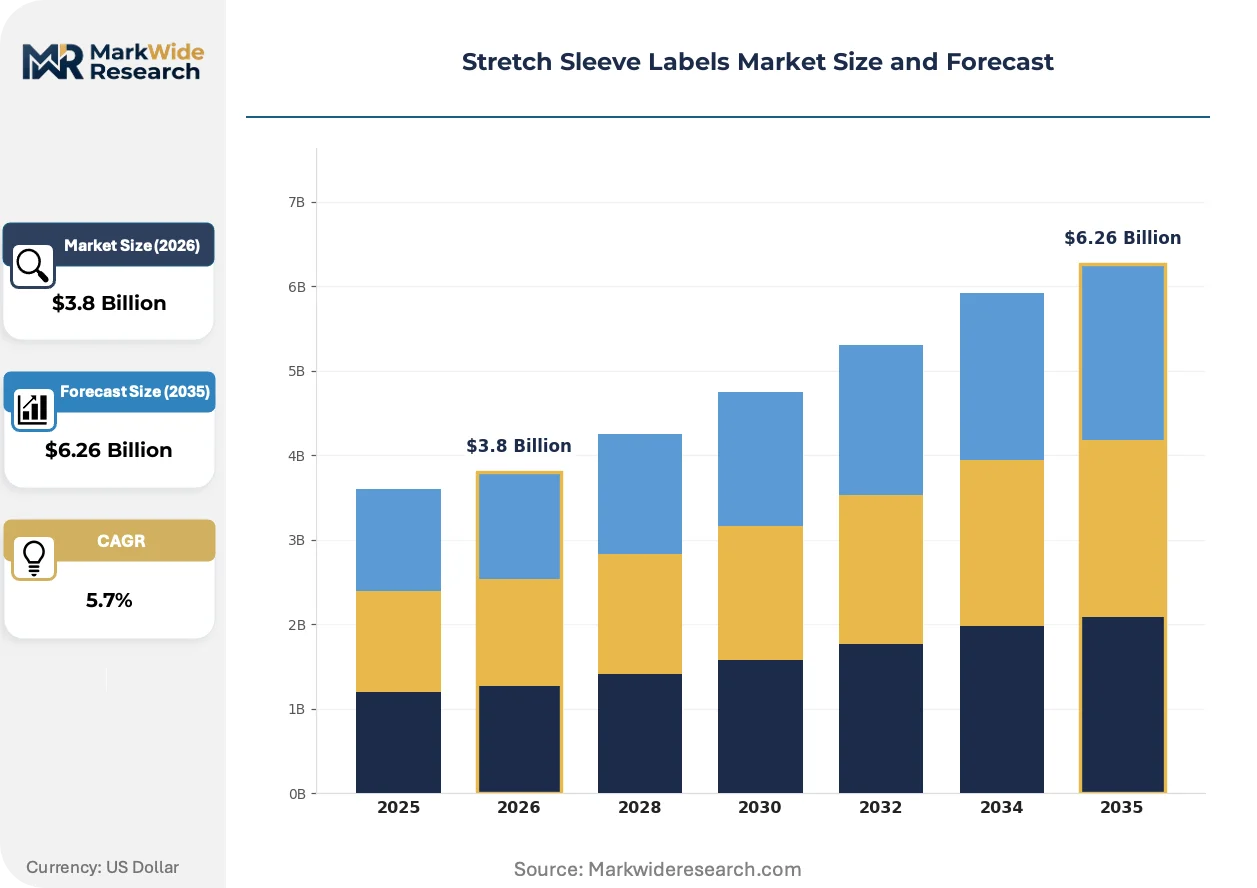
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, PVC, Others End User: Beverage Industry, Food Sector, Personal Care, Household Products Technology: Digital Printing, Flexographic Printing, Gravure Printing, Offset Printing Application: Containers, Bottles, Jars, Cans |
| Companies Covered | Klöckner Pentaplast, Amcor PLC, CCL Industries Inc., Avery Dennison Corporation, Taghleef Industries, Berry Global Inc., Fuji Seal International, Coveris, Huhtamaki Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stretch Sleeve Labels Market Evolving Landscape
Material science advances and regulatory compliance automation are restructuring how sleeve labels are specified, produced, and recovered across the value chain.
Digitally printed shrink sleeves are modularizing production economics for craft beverage and personal care segments. Small-batch distilleries and indie cosmetics brands adopt inkjet-enabled versioning for seasonal and limited-edition releases. This technology is modularizing converter capacity into cell-based manufacturing footprints that compress minimum order quantities from 50,000 to 5,000 units.
REACH substance restrictions are tightening phthalate and heavy metal thresholds in European film formulations. Compounders reformulate plasticizer packages to maintain optical clarity and shrink curves under stricter ECHA scrutiny. Beverage exporters to the EU are retrofitting supply chains to meet these specifications regardless of origin facility location.
Brand-owner sustainability scorecards are embedding ISO 18601 packaging environment standards into procurement RFPs. Major retailers in Germany and France now require recyclability certifications as table-stakes for shelf placement. This behavioral shift compresses supplier qualification cycles and disqualifies multi-material constructions from premium channel access.
Stretch Sleeve Labels Market Segmentation
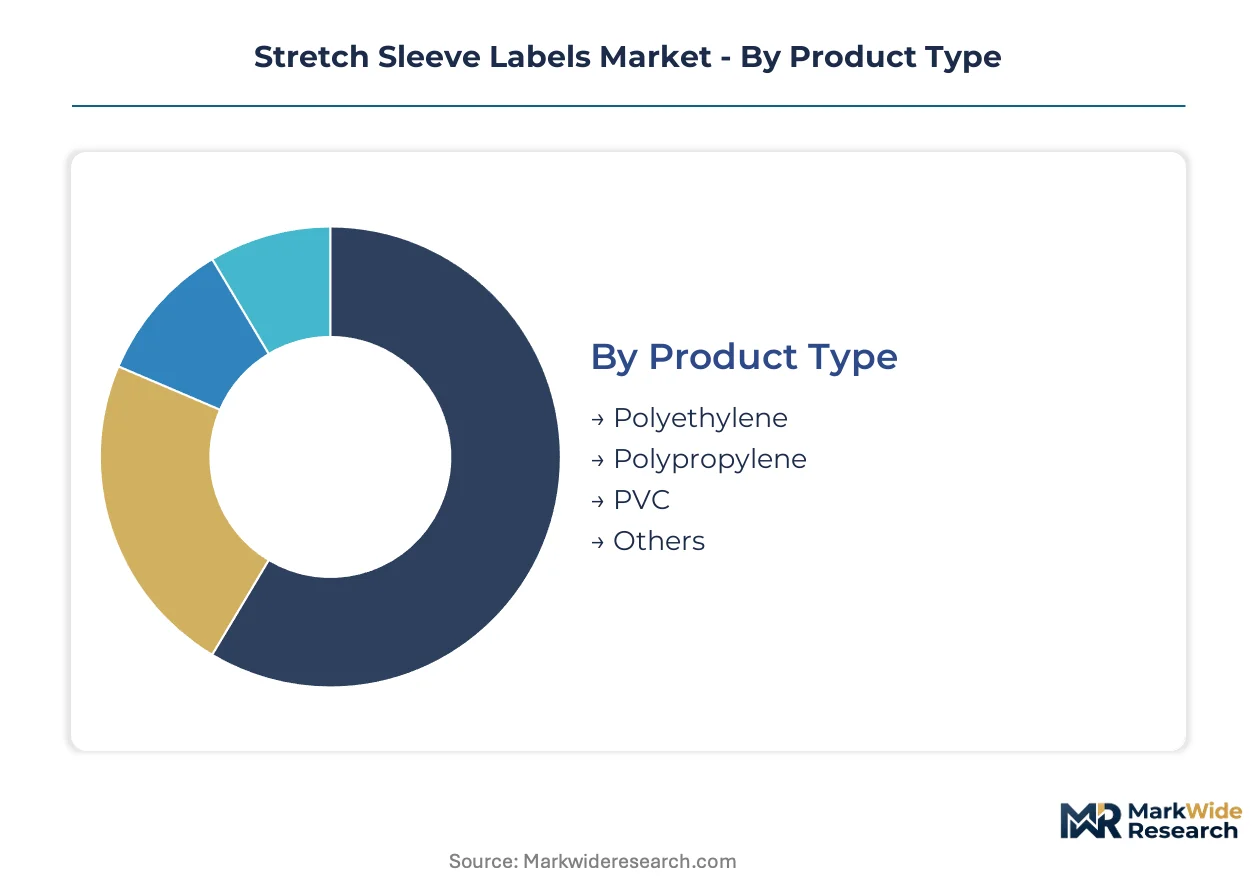
Stretch sleeve label specifications diverge sharply across material chemistry, end-use performance requirements, and production scale economics. Procurement teams weight recyclability credentials against shrink force tolerances and print resolution demands when qualifying supplier portfolios.
Product Type:
Material selection spans a customization-vs-standardization spectrum, with commodity polyethylene dominating high-volume beverage runs while specialty grades address niche performance thresholds.
- Polyethylene:Linear low-density and medium-density grades provide 30-50 micron substrates with controlled shrink curves for full-body bottle decoration. German beverage bottlers specify mono-polymer polyethylene sleeves to satisfy Verpackungsgesetz recycling quotas and avoid EPR fee penalties.
- Polypropylene:Oriented polypropylene delivers higher clarity and dimensional stability for premium cosmetic applications requiring 360-degree graphic precision. Rotterdam-Antwerp petrochemical corridors supply European converters, exposing the segment to force majeure disruptions during refinery maintenance cycles.
- PVC:Legacy material retains niche position in industrial chemical labeling where chemical resistance trumps recyclability mandates.
- Others:Bio-based and recycled-content films emerge for brand-owner sustainability scorecards targeting ISO 18601 compliance.
Most installed capacity flows through Polyethylene. Expansion is steepest in Polypropylene.
End User:
Application intensity correlates with container geometry complexity and regulatory scrutiny depth across consumer sectors.
- Beverage Industry:Carbonated soft drinks and craft beer segments drive specification standards for tamper-evident closure integration and 40-70% shrink ratios. Krones and Sidel bottling line ecosystems in Bavaria and Baden-Württemberg create format-locked demand for compatible sleeve dimensions.
- Food Sector:Condiment jars and ready-meal containers require FDA and EFSA food-contact migration certification, extending additive qualification timelines to 18-24 months.
- Personal Care:Shampoo and conditioner bottles in France and Italy present conversion white space from legacy pressure-sensitive labels.
- Household Products:Cleaning chemical containers prioritize chemical resistance over optical clarity, tolerating lower-grade substrates.
Beverage Industry commands the dominant share of sleeve label procurement volume. Personal Care is climbing the fastest as brand owners retrofit packaging for shelf differentiation.
Technology:
Capital deployment splits between high-throughput analog infrastructure and agile digital cells serving run-length fragmentation.
- Digital Printing:Inkjet and toner systems enable versioning for seasonal releases and variable data integration. Craft distilleries compress minimum order quantities from 50,000 to 5,000 units through cell-based manufacturing footprints.
- Flexographic Printing:Central impression drum presses anchor long-run beverage production with 150+ meter-per-minute speeds and solvent-based or UV-cured ink systems.
- Gravure Printing:Cylinder-engraved technology persists for ultra-long runs where amortized tooling costs justify 500,000+ unit campaigns.
- Offset Printing:Sheet-fed systems serve pre-formed sleeve applications requiring lithographic resolution for photographic imagery.
Flexographic Printing retains the broadest installed base. Digital Printing is gaining share fastest as run lengths fragment across craft and personal care segments.
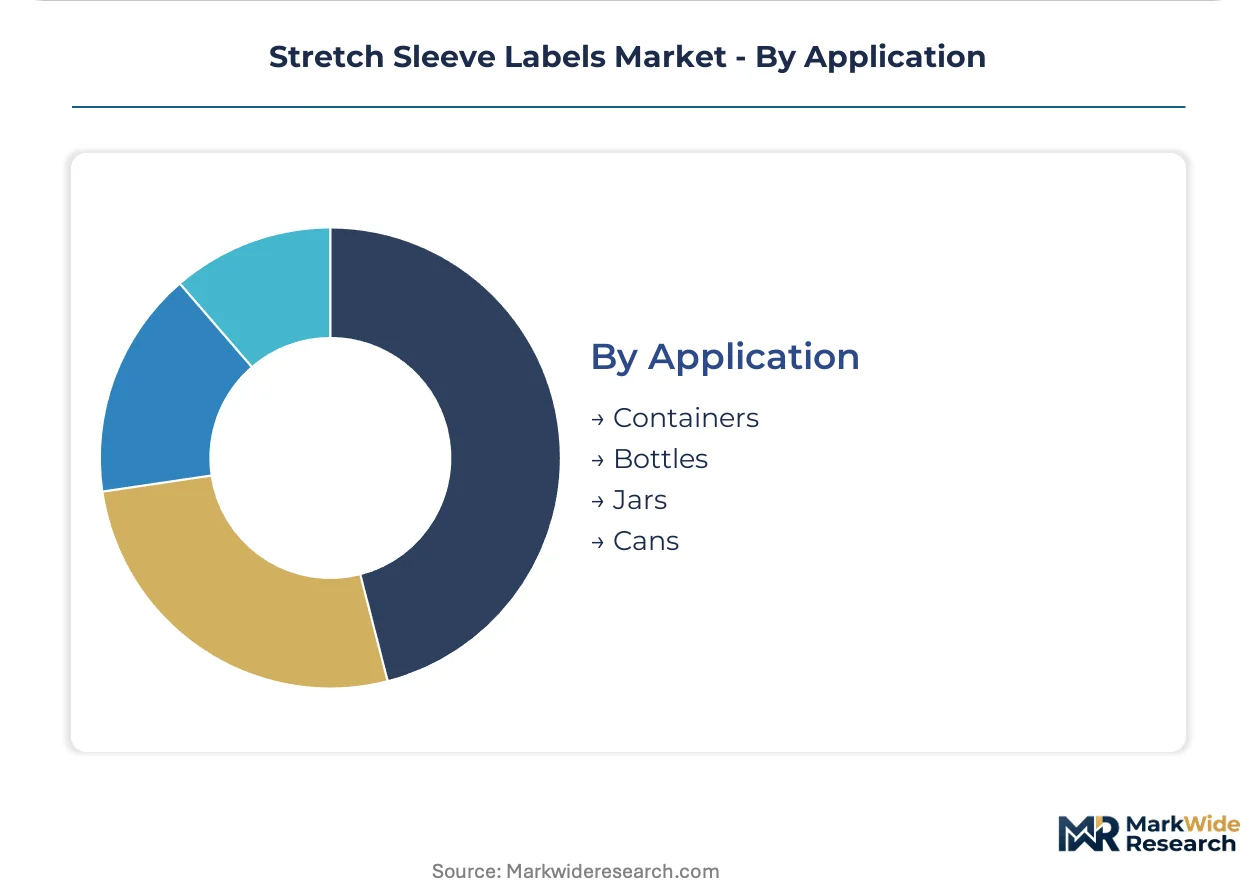
Application:
Container geometry dictates sleeve thickness, shrink ratio, and application method selection across packaging formats.
- Containers:Rectangular and oval profiles demand precise shrink curve control to avoid corner whitening and graphic distortion.
- Bottles:Carbonated beverage and spirits bottles represent the volume core, with 28mm neck finish standards driving format convergence.
- Jars:Wide-mouth food containers require higher shrink force films to accommodate shoulder geometry without tail lifting.
- Cans:Aluminum beverage cans adopt sleeves for seasonal branding where direct printing changeover costs prove prohibitive.
Bottles absorb the majority of sleeve label throughput. Cans are expanding most quickly as aluminum packaging adopts sleeve-based seasonal versioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stretch sleeve label technology first achieved commercial scale in German beverage bottling corridors during the 1990s. Bavarian equipment manufacturers refined steam tunnel application systems for carbonated soft drink lines. This engineering heritage continues concentrating procurement decisions and supplier qualification standards across European packaging markets.
Germany
Krones and Sidel bottling ecosystems in Bavaria and Baden-Württemberg generate format-locked demand for compatible sleeve dimensions. The Verpackungsgesetz mandates escalating recycling quotas that reward mono-polymer polyethylene designs with extended producer responsibility fee reductions. Stuttgart-area compounders reformulate plasticizer packages to maintain shrink performance under REACH substance restrictions.
United States
Craft distilleries and regional beverage brands adopt digitally printed sleeves for seasonal versioning and limited-edition releases. FDA food-contact regulations shape material selection timelines, extending additive qualification to 18-24 months for new formulations. Chicago and Milwaukee packaging corridors host converter capacity serving carbonated soft drink bottlers throughout the Midwest.
China
Domestic beverage brands specify sleeve labels for 360-degree decoration on PET bottle lines serving tier-one cities. GB standards and MIIT circular economy directives pressure converters toward recyclable mono-material structures. Yangtze River Delta film extruders supply oriented polyethylene substrates to Shanghai and Jiangsu bottling facilities.
France
Personal care brands in Île-de-France and Provence-Alpes-Côte d'Azur present conversion white space from legacy pressure-sensitive labels on shampoo and conditioner bottles. ANSM and CNIL frameworks govern cosmetic packaging substance disclosures and consumer data handling. Lyon-area converters develop hybrid digital-flexographic workflows for mid-volume cosmetic runs.
India
Domestic beverage and personal care brands accelerate sleeve adoption for shelf differentiation in modern trade channels. FSSAI food-contact regulations and BIS material standards shape import substitution strategies for film substrates. Maharashtra and Gujarat packaging clusters expand converter capacity to serve Mumbai and Ahmedabad bottling operations.
Stretch Sleeve Labels Market Competitive Landscape
Capital-heavy film extruders compete with asset-light design houses across the stretch sleeve label value chain. The market structure consolidates around integrated material suppliers with captive resin access, while specialist converters occupy versioning-intensive segments. Three archetypes dominate: backward-integrated film producers controlling substrate supply, equipment-tied converters locked to Krones and Sidel bottling ecosystems, and agile digital shops serving fragmented craft and personal care demand. Competitive moves center on mono-material platform investments and geographic expansion into underpenetrated personal care corridors.
Among integrated material suppliers, CCL Industries Inc., Berry Global Inc., and Avery Dennison Corporation exemplify contrasting strategic positions. CCL Industries occupies the extrusion-integrated archetype with captive film production. Berry Global represents scale-driven substrate supply to converter networks. Avery Dennison sits within the adhesive-free solution segment, positioning for recycling-stream compatibility. These three anchors illustrate how supplier qualification criteria diverge between beverage volume contracts and personal care versioning requirements.
| Leading Market Players |
|---|
| Klöckner Pentaplast |
| Amcor PLC |
| CCL Industries Inc. |
| Avery Dennison Corporation |
| Taghleef Industries |
| Berry Global Inc. |
| Fuji Seal International |
| Coveris |
| Huhtamaki Oyj |
| Others |
Value Network & Pricing Analysis
Skilled press operators in the Stuttgart-Baden-Württemberg corridor command wage premiums that widen spreads between premium-mid-economy pricing tiers. Labor-cost differentials between German technical specialists and Eastern European converter staff feed directly into sleeve label procurement stratification across beverage and personal care segments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates mono-polymer polyethylene sleeves with full REACH compliance from multi-layer constructions and basic PVC alternatives. Price differentiation hinges on certification grade—ISO 18601-aligned designs versus uncertified commodity grades—and volume scale, with beverage bottlers locking annual offtake contracts. Cost compression in the standard tier is intensifying because Rotterdam-Antwerp resin supply volatility forces compounders to absorb margin hits. Craft distilleries and indie cosmetics brands exhibit highest price sensitivity, while multinational beverage groups prioritize specification compliance over unit cost.
Supply Chain Analysis
Oriented polyethylene terephthalate and polypropylene resin supply rests on German petrochemical compounders, Belgian film extruders, and Chinese substrate producers serving Asia-Pacific bottling lines. Raw material dependencies include linear low-density polyethylene pellets, oriented polypropylene film rolls, and specialty plasticizer packages reformulated for EFSA compliance. Single-source vulnerability concentrates around steam tunnel equipment spares from Bavarian engineering houses, constraining converter expansion timelines. Distribution runs through converter-direct relationships with Krones and Sidel bottling line operators, bypassing traditional distribution intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The stretch sleeve labels market reads as a late-cycle quality story. Beverage brand owners are redirecting procurement specifications toward mono-polymer sleeves with full-body 360-degree decoration capabilities, compressing demand for legacy multi-material constructions.
For Market Incumbents: Cement backward integration into film extrusion to secure substrate supply against Rotterdam-Antwerp force majeure disruptions. Lock equipment-tied converter relationships with Krones and Sidel bottling ecosystem operators in Bavaria and Baden-Württemberg. Direct-container printing technologies threaten sleeve volumes in short-run premium SKUs—defend by investing in digital-flexographic hybrid workflows that match agility with scale economics. For New Entrants and Emerging Players: Begin with personal care white space in France and Italy, where shampoo and conditioner bottles remain dominated by pressure-sensitive labels. Target mid-volume cosmetic runs in the Île-de-France corridor where hybrid digital-flexographic capacity gaps exist. Lead with inkjet-enabled versioning capabilities that compress minimum order quantities below incumbent 50,000-unit floors. For Investors and Strategic Acquirers: Film extruders with captive resin access and REACH-compliant formulation libraries are the most active acquirer targets in this space. Over the medium-term horizon, mono-material platform investments will separate viable suppliers from stranded multi-layer capacity. Watch for inflection when Germany's Verpackungsgesetz recycling quota escalations trigger accelerated EPR fee restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | CCL Industries exemplifies how captive substrate supply insulates margin against resin volatility. |
| Mono-Material Platform Certification | ISO 18601-aligned designs unlock German Verpackungsgesetz EPR fee reductions for beverage clients. |
| Digital-Flexographic Hybrid Deployment | Lyon-area converters demonstrate mid-volume agility for French personal care versioning demands. |
| Equipment Ecosystem Partnership | Sidel and Krones bottling line compatibility locks in format-specific sleeve demand across Bavaria. |
| REACH-Compliant Formulation Investment | Stuttgart compounders reformulate plasticizer packages to maintain shrink performance under ECHA scrutiny. |
Research Methodology
Multiple input streams—conversations with film extrusion plant managers, procurement leads at German beverage bottlers, and technical R&D directors at sleeve converters—were reconciled against customs records, SEC filings from listed packaging groups, and EU Packaging and Packaging Waste Regulation compliance databases. Bottom-up capacity assessments at Rotterdam-Antwerp petrochemical corridors were triangulated with top-down demand modeling from beverage industry production data.
Historical shipment patterns from oriented film producers were cross-referenced against panel input from Krones and Sidel equipment sales teams across the analysis window. Segmentation dimensions modeled include material chemistry grade, end-use industry vertical, printing technology deployment, and regional regulatory cluster. CAGRs were derived from unit volume trajectories indexed to installed bottling line capacity, with shrink force tolerance specifications and food-contact migration certification timelines as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including force majeure disruptions at Antwerp petrochemical facilities and abrupt REACH substance restriction amendments. Forecasts reflect assumptions about Verpackungsgesetz quota enforcement intensity and steam tunnel energy cost trajectories. A small set of named triggers—including direct-container printing cost parity and EU Green Deal packaging waste directive acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Wash Off Labels Market
Labels
Printable Tags Market
Labels
Water Dissolvable Labels Market
Labels
Global Label Market
Labels
Hot Melt Glue Labeler Market
Labels
Tags Market
Labels
Global Thermal Transfer Label Market
Labels
Metallic Labels Market
Labels
Freshness Indicator Label Market
Labels
Global Security Labels Market
Labels
Waterproof and Weatherproof Label Market
Labels
Self-Laminating Labels Market
Labels
Shrink Sleeve Label Applicator Market
Labels
Pin Feed Labels Market
Labels
North America Self-Adhesive Labels Market
Labels
Wrap Around Labels Market