
 Wrap Around Labels Market | 2026-2036
Wrap Around Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Wrap Around Labels Market Outlook
Polypropylene film is consolidating share from paper substrates in beverage applications, driven by moisture resistance and downgauging potential. Avery Dennison Corporation leverages its adhesive technology portfolio to anchor premium pressure-sensitive positions in North American food packaging. CCL Industries Inc. sustains global shrink sleeve leadership through specialized extrusion capabilities and brand-owner partnerships. Mondi Group competes via integrated pulp-to-label operations that control fiber sourcing costs.
Wrap around labels are full-coverage decorative sleeves or adhesive-backed films applied circumferentially to cylindrical containers, typically achieving 360-degree graphics reproduction through gravure or flexographic printing at resolutions exceeding 120 lines per centimeter. Their primary commercial purpose is to maximize brand surface area on contoured packaging while enabling tamper-evident sealing and multi-layer promotional content. Shrink sleeve labels command the dominant value pool due to complex conversion requirements and premium positioning in personal care, though digital printing technology is gaining traction for short-run customization in craft beverage segments. Pressure-sensitive labels retain mature, high-volume positions in food and home care applications where application speed and line efficiency outweigh decoration intensity.
The EPA regulates volatile organic compound emissions from flexographic and gravure printing operations under Clean Air Act standards, directly influencing converter capital allocation toward water-based ink systems and regenerative thermal oxidizers. REACH compliance in Europe restricts phthalate plasticizers in PVC formulations, redirecting material development toward non-chlorinated alternatives. FDA food-contact substance notifications govern adhesive migration limits for labels applied directly to edible-product surfaces. Stakeholders must monitor evolving extended producer responsibility frameworks that will increasingly assign end-of-life collection costs to label and substrate specifications.
Market Dynamics
Migration from PVC to PET-G substrates is compressing converter margins while reshaping material procurement strategies across beverage and personal care packaging tiers. The EU F-Gas Regulation and extended producer responsibility frameworks are accelerating substrate substitution timelines faster than equipment amortization cycles permit.
Growth Catalysts
- Beverage bottler expansion in Latin America:Shrink sleeve adoption in Brazil and Mexico is pulling film extrusion capacity toward regional supply hubs. Brand owners specify 360-degree decoration for premium carbonated and functional drink launches.
- EU Green Deal substrate mandates:The F-Gas Regulation and REACH phthalate restrictions are eliminating PVC from food-contact applications. Converters are qualifying PET-G and PLA alternatives to maintain EU market access.
- Digital printing convergence:Short-run customization for craft beverages is reducing minimum order quantities from ten thousand to five hundred units. This enables test marketing without cylinder engraving costs.
Market Restraints
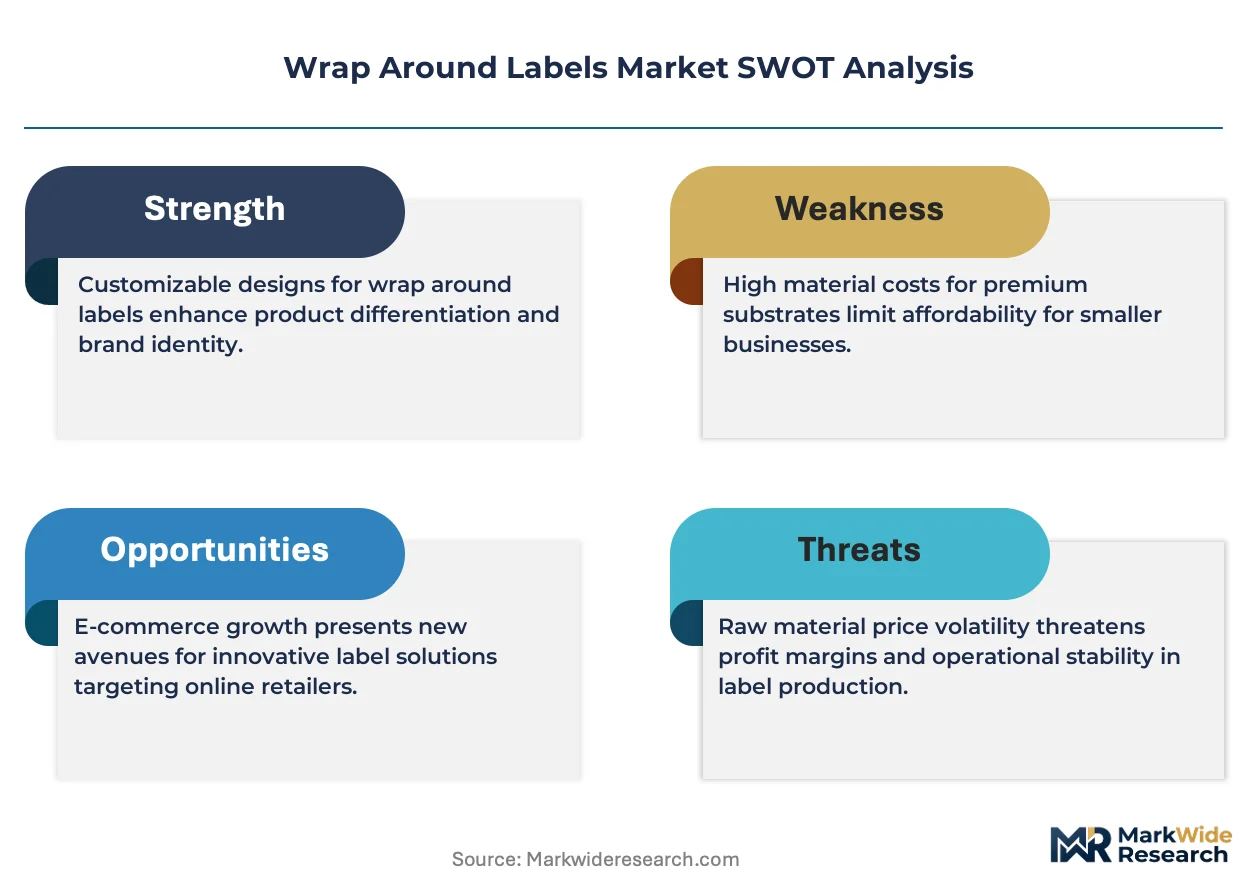
- Resin price volatility:PET-G and oriented polypropylene feedstock costs fluctuate with crude oil derivatives and polyester textile demand. Converters lack pass-through clauses in annual brand-owner contracts.
- Equipment concentration in Germany and Italy:Gravure press and seaming machinery supply concentrates among three European OEMs. Lead times for shrink sleeve lines now exceed fourteen months.
- Adhesive migration limits:FDA food-contact substance notifications restrict pressure-sensitive label use on direct-edible surfaces. This blocks penetration into fresh produce and bakery segments.
Strategic Opportunities
- Underpenetrated Southeast Asian beverage markets:Vietnam and Indonesia bottled water sectors use direct-print glass or simple paper labels. Shrink sleeve conversion offers differentiation against multinational entrants.
- Pharmaceutical compliance labeling:Serialization mandates under EU MDR and US DSCSA create demand for tamper-evident wrap-around formats with integrated track-and-trace codes.
- Chemical recycling feedstock partnerships:Brand owners with 2025-2030 recycled content pledges require label substrates from chemically recycled PET. Early converter alliances with pyrolysis operators secure offtake.
Industry Challenges
- Flexographic color management skill scarcity:Water-based ink systems for low-VOC compliance require press operators trained in viscosity control and anilox selection. Vocational programs have not scaled to converter hiring needs.
- Regenerative thermal oxidizer capex burden:EPA Clean Air Act enforcement demands abatement equipment purchases exceeding two million dollars per facility. Mid-size converters face financing constraints.
- Multi-substrate inventory complexity:Simultaneous qualification of PET-G, PLA, and recycled-content films strains warehouse segregation and changeover protocols. Lot traceability requirements compound operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wrap Around Labels Market |
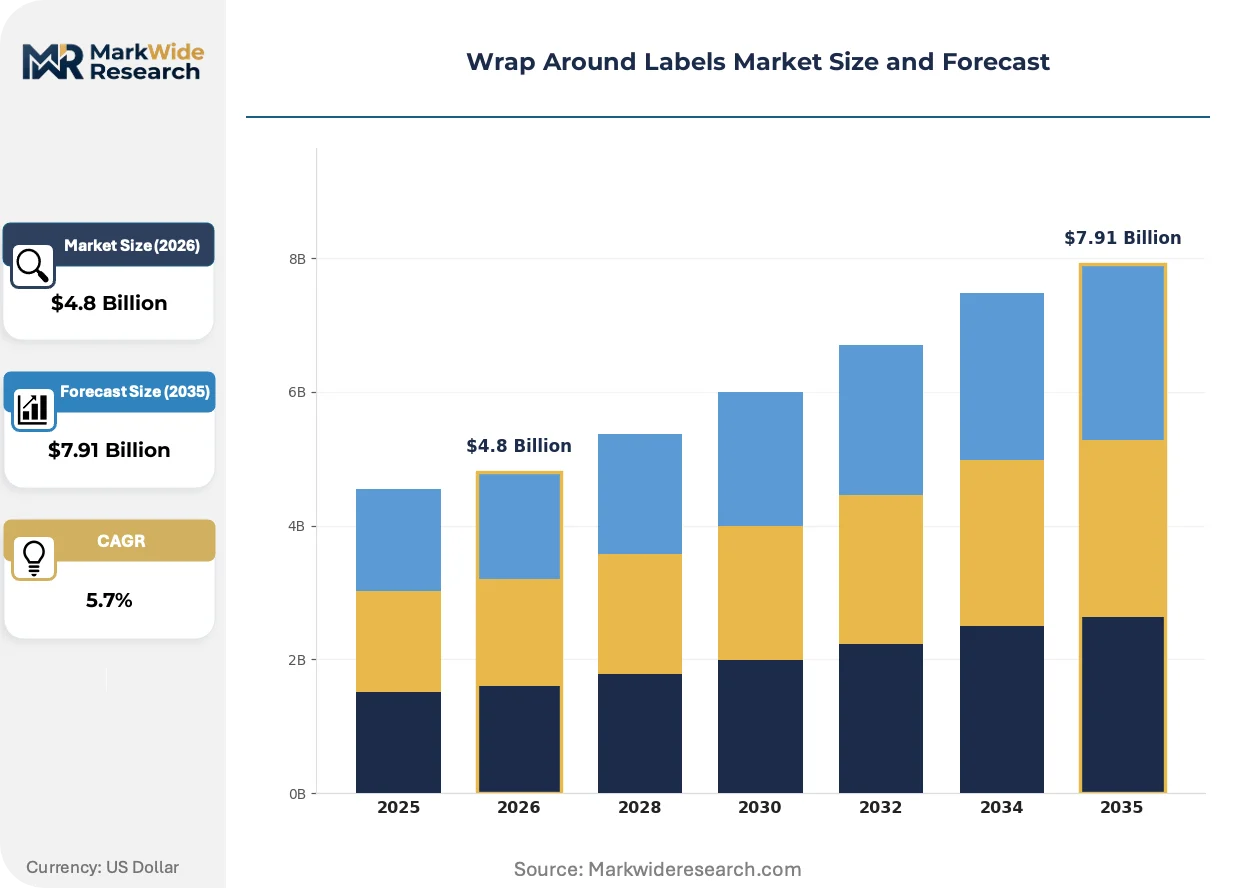
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure-Sensitive Labels, Shrink Sleeve Labels, In-Mold Labels, Adhesive Labels End User: Food & Beverage, Pharmaceuticals, Personal Care, Home Care Material: PVC, PE, Paper, Polypropylene Technology: Digital Printing, Flexographic Printing, Gravure Printing, Offset Printing |
| Companies Covered | UPM-Kymmene Corporation, Amcor plc, Avery Dennison Corporation, Cosmo Films, Klockner Pentaplast, CCL Industries Inc., Huhtamäki Oyj, Resource Label Group LLC, Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wrap Around Labels Market Strategic Shifts
Digital printing workflows and sustainable substrate chemistry are converging to compress lead times and expand decoration possibilities beyond traditional gravure limitations. Equipment modularity and regulatory chemistry restrictions are forcing simultaneous adaptation across converter operations.
Shrink sleeve label production is modularizing through digital hybrid presses that combine electrophotographic personalization units with flexographic base layers. Craft distillers and regional kombucha brands are adopting these systems for seasonal limited editions. The technology is modularizing converter service models from mass production to campaign-based fulfillment with twenty-four-hour turnaround commitments.
The EU F-Gas Regulation is banning hydrofluorocarbon blowing agents in shrink film expansion processes. European converters must reformulate or source imported PET-G with nitrogen-based expansion chemistry. Personal care and home care segments are absorbing the highest cost premiums as they lack beverage-scale volume leverage for supplier negotiation.
Brand-owner sustainability scorecards now weight end-of-life label separability alongside recycled content percentages. Retailers in France and Germany are rejecting packaging with non-detachable sleeve labels that contaminate PET bottle recycling streams. This procurement filter is compressing demand toward floatable polyolefin substrates and adhesive-free mechanical locking designs.
Wrap Around Labels Market Segmentation
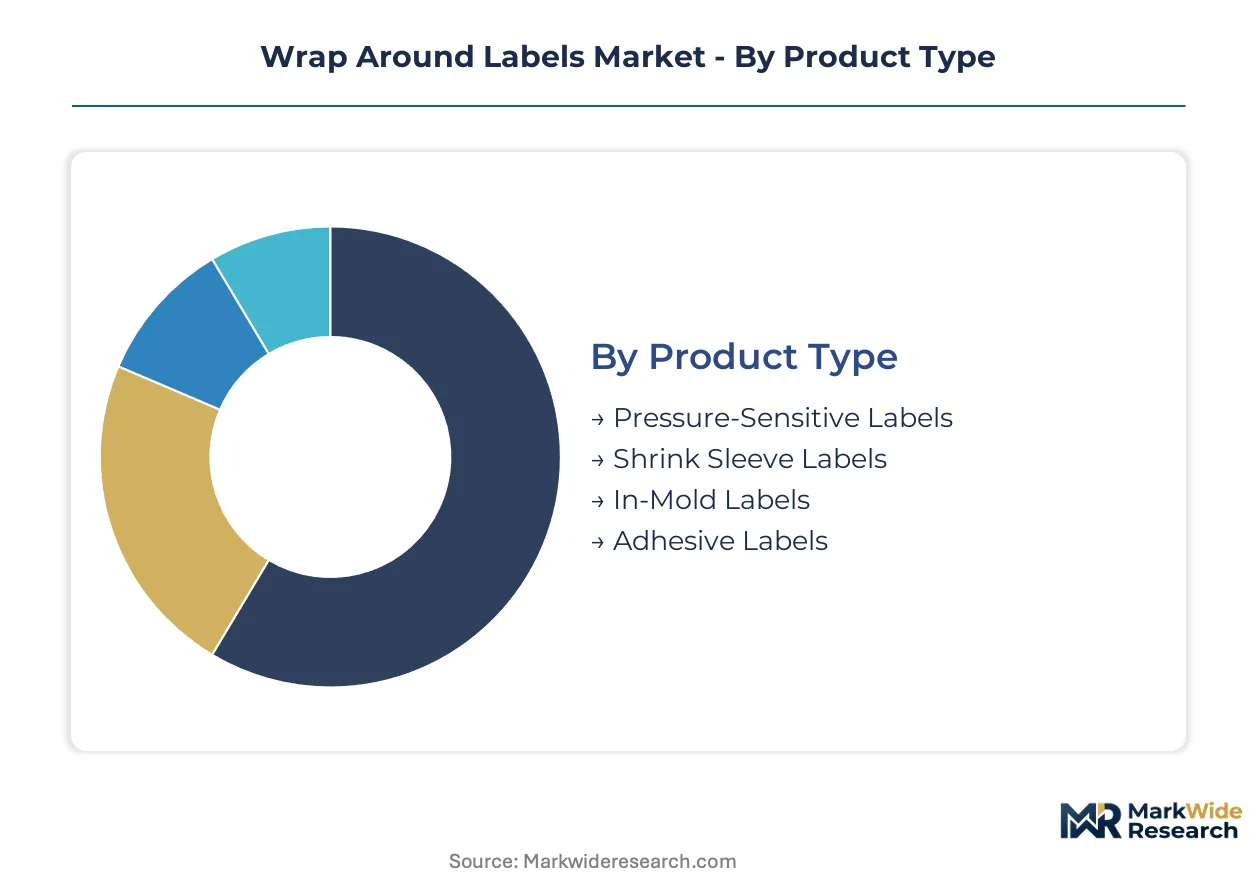
Label format selection determines equipment investment, substrate procurement, and regulatory compliance pathways for converters. Brand owners match product type to container geometry, decoration intensity, and end-of-life separability requirements.
Product Type:
Application speed and graphics coverage drive buyer selection between adhesive-backed and sleeve formats.
- Shrink Sleeve Labels:PET-G or PVC films expand through heat tunnel application to achieve full 360-degree container coverage. Beverage bottlers in Brazil and Mexico specify these for premium carbonated launches requiring tamper-evident sealing and promotional multi-layer content.
- Pressure-Sensitive Labels:Facestock-adhesive-liner laminates apply via high-speed rotary dispensers without heat. Food and home care manufacturers in North America favor these for line efficiency where decoration intensity remains secondary to throughput.
- In-Mold Labels:Polypropylene films fuse to container walls during blow molding or injection molding. Personal care brands use these for durable, scratch-resistant decoration on contoured bottles.
- Adhesive Labels:General-purpose wet-glue or self-adhesive formats serve cost-sensitive applications with lower graphics requirements. These retain positions in emerging market water bottling where equipment upgrade capital is constrained.
Shrink sleeve labels lead on scale; digital-ready pressure-sensitive formats lead on momentum.
End User:
Regulatory exposure and sustainability pledges reshape procurement specifications across consumer sectors.
- Food & Beverage:FDA food-contact substance notifications govern adhesive migration limits for labels applied to edible-product surfaces. Brand owners face retailer pressure in France and Germany to specify floatable polyolefin substrates that separate cleanly from PET bottle recycling streams.
- Personal Care:Complex container geometries and premium positioning drive shrink sleeve specification. EU F-Gas Regulation compliance costs concentrate here due to lack of beverage-scale volume leverage for supplier negotiation.
- Pharmaceuticals:EU MDR and US DSCSA serialization mandates create demand for tamper-evident wrap-around formats with integrated track-and-trace codes. Converters must validate print resolution exceeding 120 lines per centimeter for barcode legibility.
- Home Care:High-volume, low-decoration applications favor pressure-sensitive labels for application speed. REACH phthalate restrictions redirect material development toward non-chlorinated alternatives.
Food and beverage commands volume concentration; pharmaceuticals climbs fastest on compliance-driven specification upgrades.
Material:
Substrate chemistry determines recyclability compatibility and regulatory compliance cost exposure.
- Polypropylene:Oriented films consolidate share from paper in beverage applications through moisture resistance and downgauging potential. Biaxially oriented grades offer stiffness for high-speed application without liner tear.
- PVC:Legacy substrate faces elimination from food-contact applications under REACH phthalate restrictions. Remaining demand concentrates in personal care where EU F-Gas Regulation reformulation timelines lag beverage sector migration.
- PET-G:Glycol-modified polyester replaces PVC in shrink sleeve formats for EU market access. Resin price volatility tracks crude oil derivatives and polyester textile demand.
- Paper:Cellulosic substrates retain positions in dry-goods segments and craft beverage aesthetics. Integrated pulp-to-label operations control fiber sourcing costs for competitive positioning.
Polypropylene dominates current procurement; PET-G gains share fastest on regulatory displacement of chlorinated alternatives.
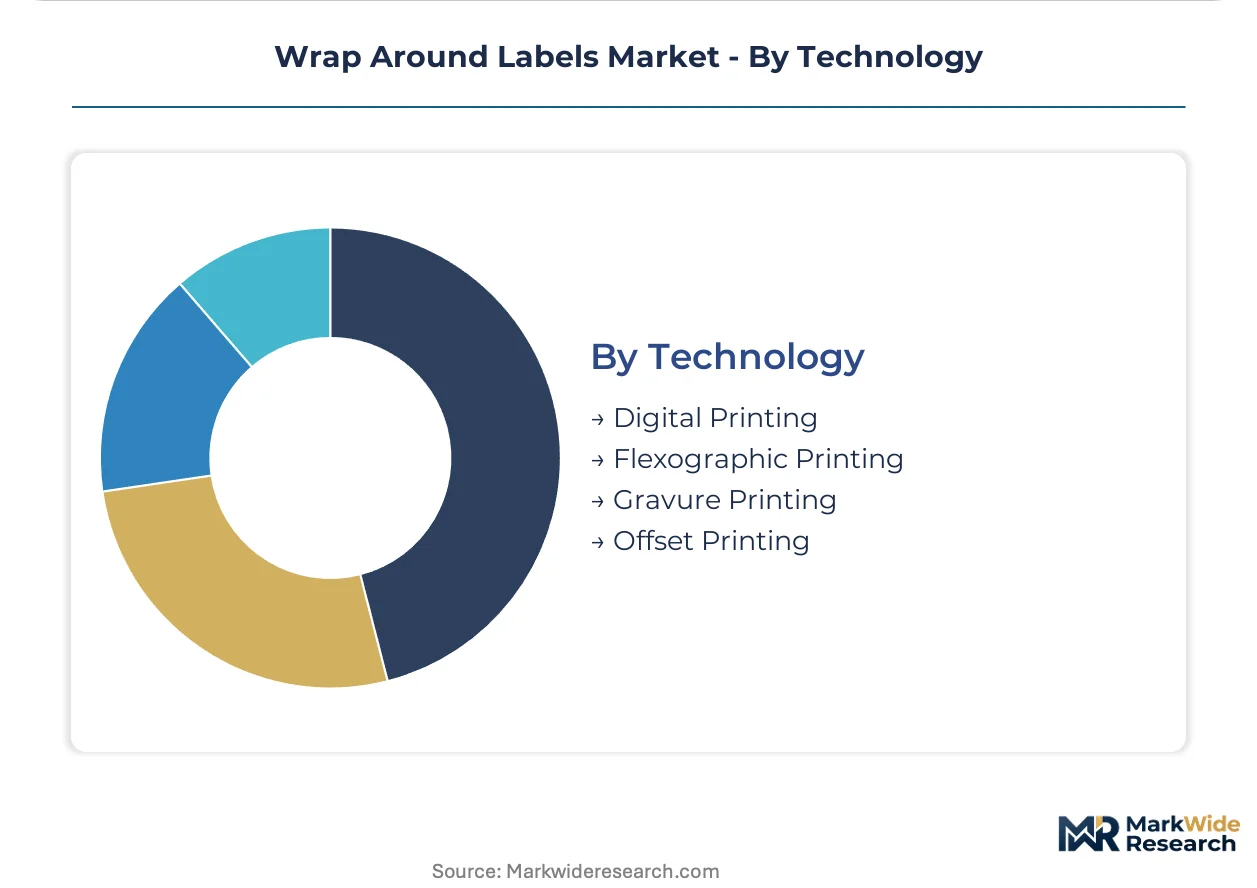
Technology:
Run length and customization requirements determine capital allocation between analog and digital press platforms.
- Flexographic Printing:Water-based ink systems serve high-volume beverage and home care production with low-VOC compliance. EPA Clean Air Act enforcement demands regenerative thermal oxidizer capital exceeding two million dollars per facility.
- Digital Printing:Electrophotographic and inkjet systems enable short-run customization from five hundred units for craft beverage test marketing. Hybrid presses combine personalization units with flexographic base layers for seasonal limited editions.
- Gravure Printing:Cylinder-engraved processes deliver resolution exceeding 120 lines per centimeter for premium shrink sleeve graphics. Equipment supply concentrates among three European OEMs with lead times now exceeding fourteen months.
- Offset Printing:Lithographic processes serve in-mold label production with consistent color matching. These require longer setup times that constrain suitability for short-run work.
Flexographic platforms anchor volume production; digital workflows expand most quickly on craft segment demand for campaign-based fulfillment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's gravure press manufacturing corridor supplies equipment to converters worldwide. Regional demand patterns diverge between mature markets prioritizing sustainability compliance and emerging markets expanding decoration-intensive beverage packaging.
United States
Food and home care manufacturers drive pressure-sensitive label consumption for high-speed line efficiency. EPA Clean Air Act enforcement pushes converters toward water-based ink systems and regenerative thermal oxidizer installations exceeding two million dollars per facility. Chicago and Milwaukee host dense clusters of flexographic converters serving Midwestern CPG brands.
Germany
EU F-Gas Regulation compliance costs concentrate in personal care shrink sleeve production lacking beverage-scale volume leverage. REACH phthalate restrictions eliminate PVC from food-contact applications, redirecting material development toward PET-G alternatives. The Düsseldorf-Cologne corridor anchors gravure press and seaming machinery supply among three dominant European OEMs.
Brazil
Beverage bottlers specify shrink sleeve formats for premium carbonated and functional drink launches requiring 360-degree decoration and tamper-evident sealing. ANVISA pharmaceutical regulations create demand for serialization-compliant wrap-around labels with integrated track-and-trace codes. São Paulo state concentrates film extrusion capacity serving Latin American brand owners.
China
MIIT industrial standards and dual carbon goals accelerate substrate substitution toward chemically recycled PET feedstocks. Yangtze River Delta converters supply both domestic beverage brands and export-oriented personal care manufacturers. The region's biaxial orientation lines produce polypropylene films consolidating share from paper in moisture-resistant applications.
Mexico
Nuevo León and Jalisco beverage bottlers adopt shrink sleeve decoration to differentiate against multinational entrants in carbonated and bottled water segments. Proximity to US brand owners enables just-in-time fulfillment for seasonal promotional campaigns. The Bajío Region's emerging converter base qualifies PET-G alternatives to maintain cross-border market access under evolving USMCA technical barriers.
Wrap Around Labels Market Competitive Environment
Capacity expansion dominates the current landscape as converters position for substrate transition timelines. The vendor base spans multinational materials conglomerates, specialized film extruders, and regional printing houses with hybrid digital-analog capabilities. Two strategic archetypes emerge: integrated pulp-to-label operators controlling fiber sourcing costs, and adhesive technology specialists anchoring premium pressure-sensitive positions. M&A activity concentrates in Southeast Asian supply hub consolidation, while equipment partnerships with German and Italian OEMs secure fourteen-month lead time allocations for shrink sleeve lines.
Within the integrated materials tier, UPM-Kymmene Corporation and Mondi Group exemplify backward control over pulp sourcing that insulates margin pressure from volatile resin markets. Avery Dennison Corporation occupies a distinct position anchoring adhesive technology portfolios for North American food packaging applications. CCL Industries Inc. represents the specialized extrusion archetype sustaining global shrink sleeve leadership through brand-owner partnership structures. These three entities collectively illustrate how substrate chemistry mastery and geographic proximity to beverage bottler clusters determine competitive positioning in a market forced to absorb simultaneous regulatory and technology transitions.
| Leading Market Players |
|---|
| UPM-Kymmene Corporation |
| Amcor plc |
| Avery Dennison Corporation |
| Cosmo Films |
| Klockner Pentaplast |
| CCL Industries Inc. |
| Huhtamäki Oyj |
| Resource Label Group LLC |
| Mondi Group |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal substrate mandates are forcing brand owners to specify PET-G and PLA alternatives ahead of converter equipment amortization cycles, compressing margins and redrawing procurement power toward resin suppliers with qualified sustainable grades.
Pricing Analysis
Input-cost pass-through limitations dominate converter economics as annual brand-owner contracts lack clauses for PET-G resin volatility tied to crude oil derivatives and polyester textile demand. Three-tier pricing structure across premium shrink sleeve, standard pressure-sensitive, and economy adhesive formats separates decoration-intensive beverage applications from high-throughput food labeling. Cost compression in personal care shrink sleeve tiers is intensifying because EU F-Gas Regulation reformulation absorbs cost premiums without beverage-scale volume leverage. Food and beverage manufacturers exhibit highest price sensitivity due to thin label-as-percentage-of-COGS ratios, while pharmaceutical serialization compliance creates inelastic demand for premium tamper-evident formats.
Supply Chain Analysis
Single-source vulnerability sits with German and Italian OEMs controlling gravure press and seaming machinery supply, where equipment lead times now stretch beyond fourteen months. Film extrusion capacity concentrates in Brazil, Mexico, and the Yangtze River Delta, while biaxial orientation lines for polypropylene feed from South Korea and China. Raw material dependencies span glycol-modified polyester resin, oriented polypropylene feedstock, and water-based ink pigment systems. Tariff exposure runs through USMCA technical barriers affecting Nuevo León and Jalisco converter qualification protocols. Distribution runs through regional supply hubs co-located with beverage bottler clusters in São Paulo state and the Bajío Region.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where sustainability scorecards and retailer procurement filters in France and Germany are elevating specification requirements toward floatable polyolefin substrates and adhesive-free mechanical locking designs.
For Market Incumbents: Acquire specialized extrusion capabilities in PET-G and chemically recycled PET substrates to anchor brand-owner partnership structures ahead of 2025-2030 recycled content pledge deadlines. Defend margin position by securing early alliances with pyrolysis operators for feedstock offtake, insulating against resin price volatility that lacks contract pass-through protection.
For New Entrants and Emerging Players: Capture underpenetrated Southeast Asian beverage markets in Vietnam and Indonesia where direct-print glass and simple paper labels still dominate bottled water sectors. Target craft beverage test marketing demand for digital hybrid press campaign fulfillment with twenty-four-hour turnaround commitments, bypassing gravure cylinder engraving cost barriers.
For Investors and Strategic Acquirers: Asymmetric upside sits with integrated pulp-to-label operators controlling fiber sourcing costs amid volatile resin markets. Long-term viability across the five-to-ten year window favors backward-integrated mid-cap specialists with regional proximity to Latin American beverage bottler expansion. Monitor ANVISA pharmaceutical serialization mandate implementation in Brazil as inflection indicator for tamper-evident wrap-around format demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Feedstock Partnership | Secures qualified PET-G supply for brand-owner 2025-2030 recycled content pledges. |
| Digital Hybrid Press Deployment | Enables five-hundred-unit minimum orders for craft beverage seasonal limited editions. |
| Gravure Equipment Reservation | Locks fourteen-month lead time allocation from Düsseldorf-Cologne corridor OEMs. |
| Floatable Polyolefin Substrate Qualification | Satisfies French and German retailer separability requirements for PET bottle recycling streams. |
| Serialization-Compliant Format Development | Captures EU MDR and US DSCSA pharmaceutical track-and-trace mandate demand. |
Study Parameters
Direct dialogue with film extrusion plant managers, beverage brand procurement leads, gravure press operators, and pharmaceutical packaging regulatory affairs specialists anchored qualitative fieldwork. Secondary validation drew from EPA Clean Air Act enforcement records, ECHA REACH substance restriction updates, FDA food-contact substance notification databases, and ANVISA pharmaceutical serialization guidance documents. Bottom-up converter capacity assessments and top-down brand-owner procurement spend estimates were triangulated to cross-check volume assumptions.
Bottom-up modeling tracked label format adoption by end-use sector, substrate chemistry migration timelines, and regional equipment installation patterns across the projection horizon. Segmentation dimensions included shrink sleeve versus pressure-sensitive versus in-mold formats, PVC-PET-G-polypropylene-paper material tiers, and flexographic-digital-gravure technology platforms. CAGRs were derived from equipment utilization rates and brand-owner specification shift velocities rather than macroeconomic extrapolation. Converter interview data on water-based ink system adoption and regenerative thermal oxidizer capex constraints informed cost structure assumptions.
Resin price volatility, regulatory timeline acceleration ahead of equipment amortization cycles, and vocational training program scaling shortfalls are the dominant revision risks to forecast assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Canning Labels Market
Labels
United States Print Label Market
Labels
Global Metal Detectable Tags and Labels Market
Labels
Laser Printable Wristbands Market
Labels
Shrink Sleeve Label Applicator Market
Labels
BOPP Labels Market
Labels
Global Label Adhesive Market
Labels
Global Tamper Evident Labels Market
Labels
GHS Labels Market
Labels
Hot Melt Glue Labeler Market
Labels
Wash Off Labels Market
Labels
Healthcare and Laboratory Labels Market
Labels
Foam Labels Market
Labels
Ampoule Sticker Labeling Machine Market
Labels
Hang Tags Market
Labels
Global Waterproof Labels Market