
 Pin Feed Labels Market | 2026-2036
Pin Feed Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Pin Feed Labels Market Analytics
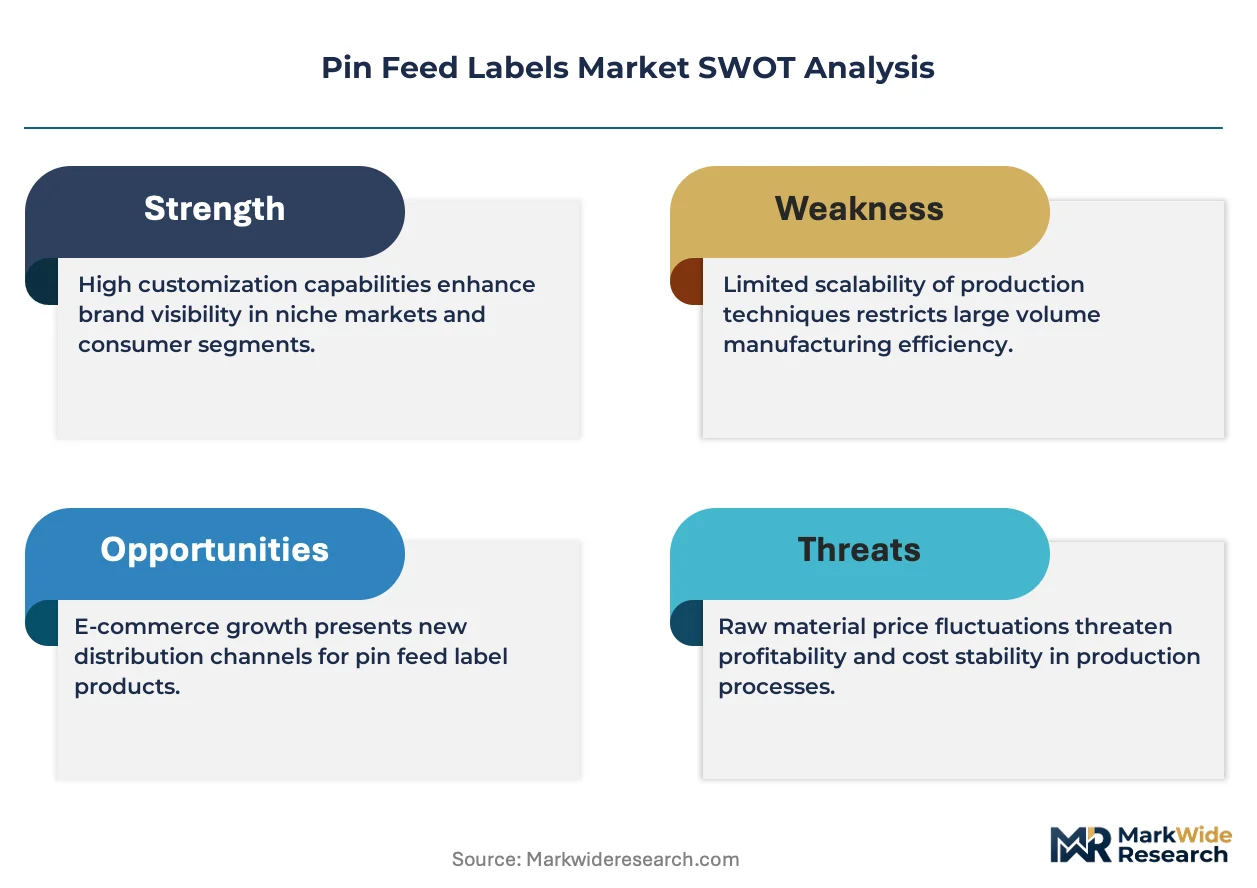
North American specialty paper producers is consolidating capacity around pin feed label substrates to secure tighter supply chain coordination. Avery Dennison Corporation leverages its adhesive science portfolio to dominate premium thermal transfer grades across industrial accounts. Zebra Technologies Corporation anchors its position through printer-label bundling programs that lock in recurring label volumes. CCL Industries sustains margin pools by specializing in multi-layer constructions for pharmaceutical serialization compliance.
Pin feed labels are continuous-form pressure-sensitive labels perforated along both edges with carrier pin holes, engineered for impact and line-matrix printers at speeds exceeding 500 characters per second in warehouse and back-office environments. The substrate typically combines top-coated thermal paper or synthetic facestock with hot-melt or acrylic adhesive systems formulated for adhesion to corrugated, polybag, and metal surfaces under variable humidity. Thermal transfer label types command the widest installed base in shipping applications, though direct thermal formats are displacing ribbon-dependent workflows in short-lifecycle inventory use cases. Paper materials still occupy the highest volume tier, yet polyester and polypropylene alternatives are extending share in retail and cold-chain segments where tear resistance and moisture immunity justify unit cost premiums.
FDA 21 CFR Part 11 requirements for electronic records in pharmaceutical distribution continue to shape label durability and print permanence specifications for domestic manufacturers. EPA guidelines on volatile organic compound emissions from adhesive coating operations are forcing solvent-based production lines toward waterborne or hot-melt system conversions. REACH compliance across the EU restricts certain phthalate plasticizers in vinyl facestocks, redirecting formulation R&D toward bio-based alternatives. Stakeholders must monitor how dual regulatory pressure from FDA traceability mandates and EPA emission thresholds will reshape domestic manufacturing economics and sourcing geography decisions.
Market Dynamics
E-commerce fulfillment velocity is compressing label procurement cycles as warehouse automation demands continuous-form media engineered for 500+ characters per second throughput in high-density sorting environments.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Material traceability mandates across member states are forcing adhesive-backed product suppliers to upgrade substrate documentation systems, expanding compliant pin feed label volumes.
- Thermal transfer to direct thermal migration:Short-lifecycle inventory operations are eliminating ribbon-dependent workflows, reducing total cost per label and accelerating format turnover in retail distribution centers.
- Rhine-Ruhr warehousing cluster expansion:Germany's automated sorting infrastructure buildout is concentrating procurement demand among logistics operators seeking high-speed continuous-form media.
Market Restraints
- Adhesive raw material volatility:Hot-melt and acrylic polymer feedstock costs fluctuate with petrochemical indices, squeezing converter margins on standard-grade shipments.
- REACH phthalate restrictions:ECHA's vinyl facestock limitations are redirecting R&D budgets toward bio-based plasticizer alternatives before commercial scale is proven.
- Laser and inkjet substitution:Cut-sheet laser printers in back-office environments are displacing pin feed hardware in document-intensive applications below 100 labels per batch.
Strategic Opportunities
- Pharmaceutical serialization compliance:FDA 21 CFR Part 11 durability specifications for electronic records are creating premium multi-layer construction demand that commands margin pools above commodity grades.
- Cold-chain logistics expansion:Polyester and polypropylene facestocks with moisture immunity are penetrating refrigerated pharmaceutical and fresh grocery distribution where paper substrates fail.
- Waterborne adhesive conversion:EPA volatile organic compound emission thresholds are accelerating solvent-to-hot-melt line conversions, rewarding early capital deployers with regulatory positioning.
Industry Challenges
- Print permanence certification timelines:Pharmaceutical manufacturers require 5-10 year archive-grade legibility validation, extending qualification cycles before volume procurement authorization.
- Legacy printer fleet integration:Impact and line-matrix hardware with 15-20 year service lives in installed warehouse bases constrains substrate innovation to backward-compatible perforation and thickness specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pin Feed Labels Market |
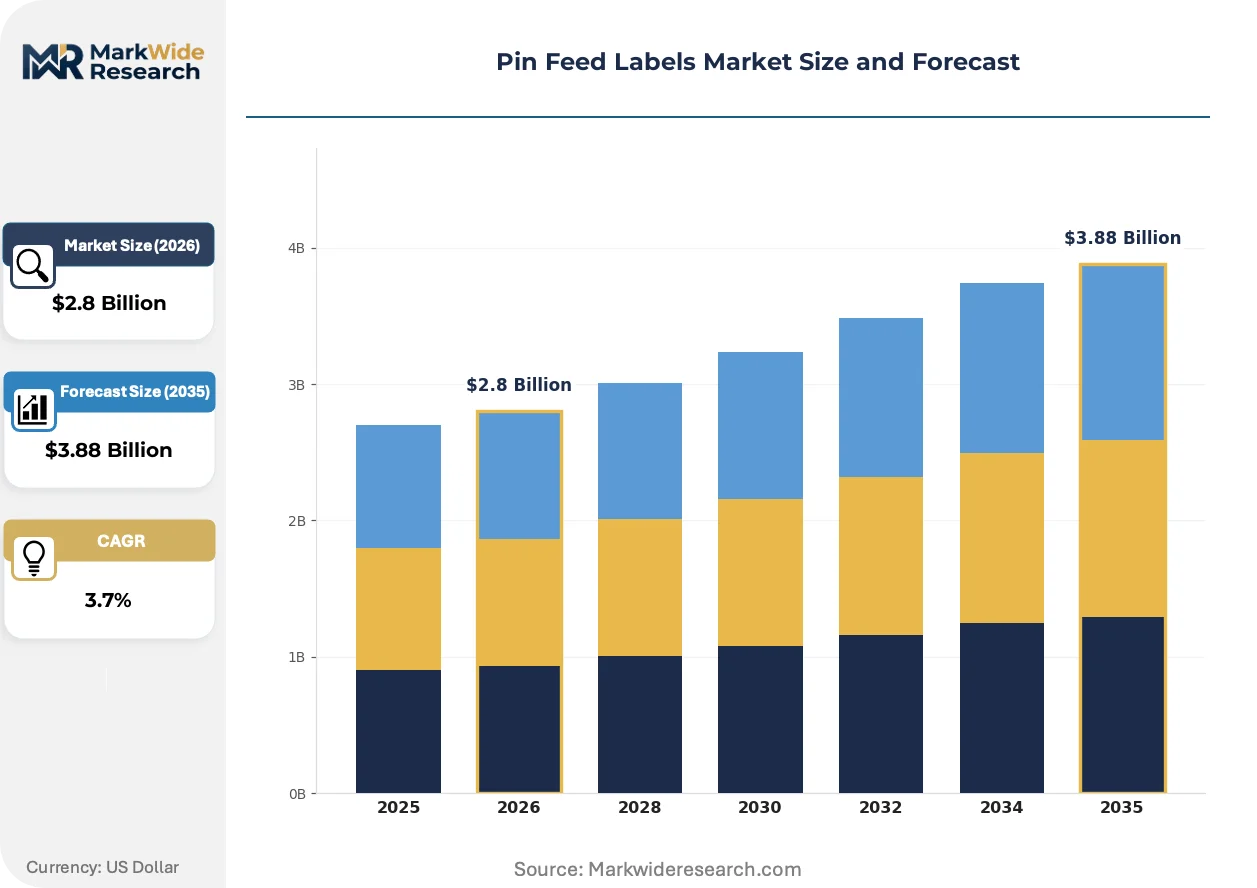
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $3.88 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Label Type: Thermal Transfer, Direct Thermal, Inkjet, Laser Material: Paper, Polyester, Polypropylene, Vinyl Application: Shipping, Inventory Management, Office Supplies, Retail Print Technology: Digital Printing, Flexographic Printing, Offset Printing, Gravure Printing |
| Companies Covered | Avery Dennison Corporation, Zebra Technologies Corporation, CCL Industries, SATO Holdings Corporation, UPM-Kymmene Corporation, Multi-Color Corporation, 3M Company, Lintec Corporation, Toshiba Tec Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pin Feed Labels Market Evolving Landscape
Substrate science and regulatory chemistry are converging to redefine performance benchmarks for continuous-form pressure-sensitive media in automated fulfillment infrastructure.
Direct thermal coatings with improved environmental stability are electrifying short-lifecycle inventory workflows. Third-party logistics operators operating same-day fulfillment networks are adopting ribbon-free formats at accelerating rates. This technology is electrifying total cost economics by eliminating consumable inventory and reducing printer maintenance intervals in high-throughput sorting environments.
REACH restrictions on phthalate plasticizers in vinyl facestocks are compelling formulation shifts across EU member states. ECHA's substance authorization requirements are redirecting R&D investment toward bio-based adhesive systems and synthetic paper alternatives. Pharmaceutical and retail labeling segments with extended product contact requirements are prioritizing compliant substrate qualification ahead of cost optimization.
Consolidated procurement contracts spanning printer hardware and label media are restructuring buyer-vendor relationships. Industrial accounts with 500+ printer deployments are negotiating bundled supply agreements that lock in recurring label volumes through multi-year service arrangements. This pattern concentrates most visibly in German and US e-commerce fulfillment networks where equipment standardization reduces operational complexity.
Pin Feed Labels Market Segmentation
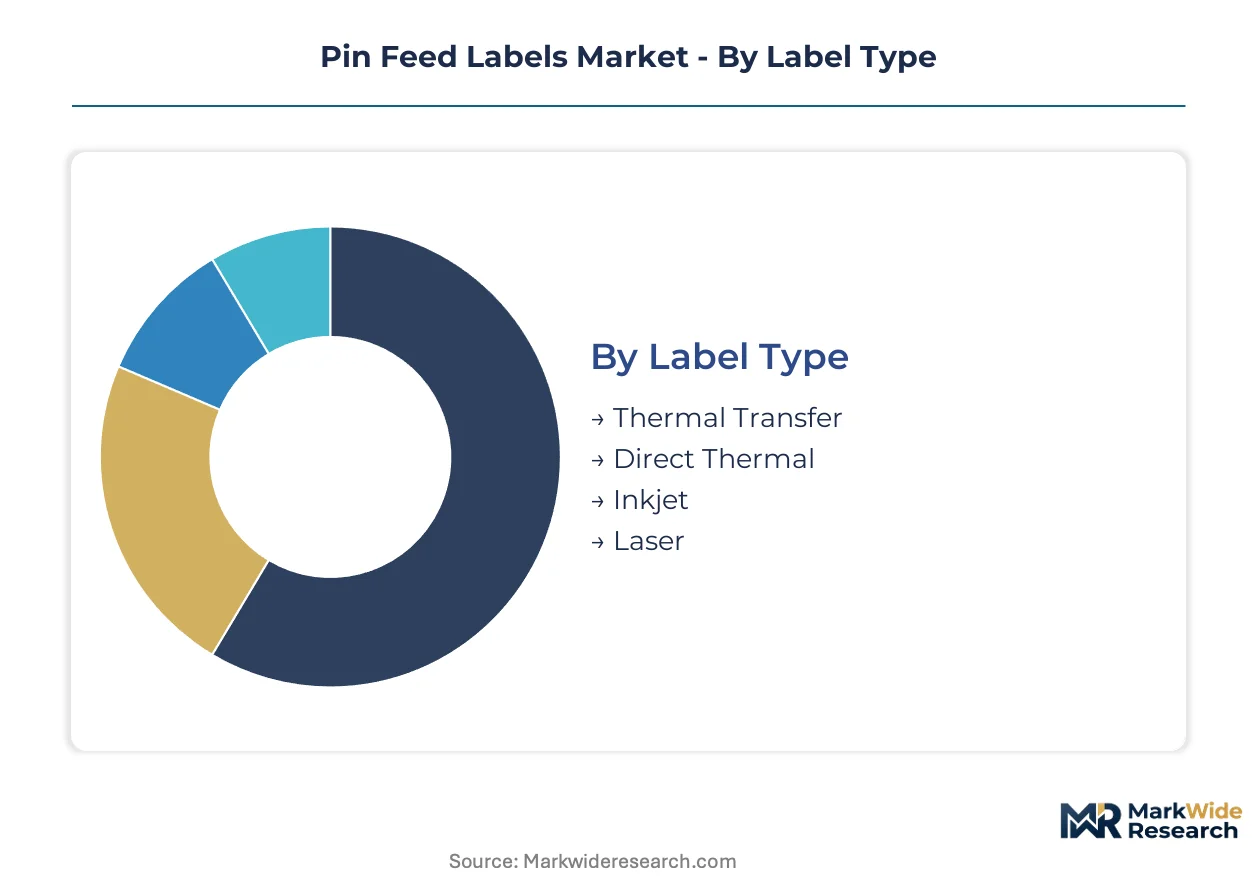
Pin feed label procurement patterns diverge sharply across substrate chemistry, print compatibility, and end-use durability requirements. Warehouse automation investments and regulatory compliance mandates are compressing specification windows, forcing buyers to match segment attributes precisely to operational throughput and archive obligations.
Label Type:
Capital intensity concentrates in thermal transfer grades requiring ribbon coating infrastructure and precision die-cutting lines for perforated edge consistency.
- Thermal Transfer:Ribbon-dependent imaging delivers archive-grade permanence for pharmaceutical serialization and multi-year barcode legibility. German pharmaceutical distributors specify these grades for EU traceability compliance, absorbing premium unit costs against regulatory penalty risk.
- Direct Thermal:Heat-sensitive coatings eliminate ribbon inventory and reduce printer maintenance intervals in high-velocity e-commerce sorting. Rhine-Ruhr logistics operators are migrating warehouse fleets to ribbon-free formats for same-day fulfillment economics.
- Inkjet:Aqueous and solvent ink compatibility serves short-run variable data applications in back-office document workflows.
- Laser:Toner-fused imaging accommodates heat-resistant synthetic facestocks in industrial asset tagging with extended outdoor exposure.
Thermal transfer absorbs the bulk of installed capacity; direct thermal is expanding most quickly.
Material:
Cost tier stratification separates commodity paper volumes from synthetic substrates commanding three-to-five-fold unit premiums in cold-chain and retail durability applications.
- Paper:Top-coated thermal papers dominate shipping and inventory volumes through corrugated adhesion and cost minimization. US e-commerce fulfillment networks consume standard-grade rolls in continuous-form high-speed printers exceeding 500 characters per second.
- Polyester:Tear-resistant films with moisture immunity penetrate pharmaceutical and fresh grocery distribution where paper substrate failure risks product loss. REACH phthalate restrictions are redirecting European converter capacity toward polyester alternatives.
- Polypropylene:Flexible olefin films balance durability and conformability for curved retail packaging surfaces.
- Vinyl:Plasticized PVC facestocks face ECHA authorization pressure, constraining growth in extended product-contact applications.
Paper commands the widest volume base; polyester is climbing the fastest on cold-chain logistics expansion.
Application:
Customer type fragmentation separates enterprise logistics procurement with multi-year bundled contracts from spot purchasing in small-format office environments.
- Shipping:Continuous-form labels with hot-melt adhesive systems adhere to corrugated and polybag surfaces across variable humidity. Automated sorting infrastructure in Germany and the United States is concentrating procurement among operators with 500-plus printer deployments.
- Inventory Management:Short-lifecycle stock rotation labels demand direct thermal formats with reduced total cost per imprint in retail distribution centers.
- Office Supplies:Cut-sheet laser and inkjet substitution is displacing pin feed hardware in document-intensive batches below 100 labels.
- Retail:Shelf-edge and promotional labeling requires moisture-resistant synthetics with tear resistance for high-touch consumer environments.
Shipping absorbs the bulk of installed capacity; inventory management is gaining share fastest on automation penetration.
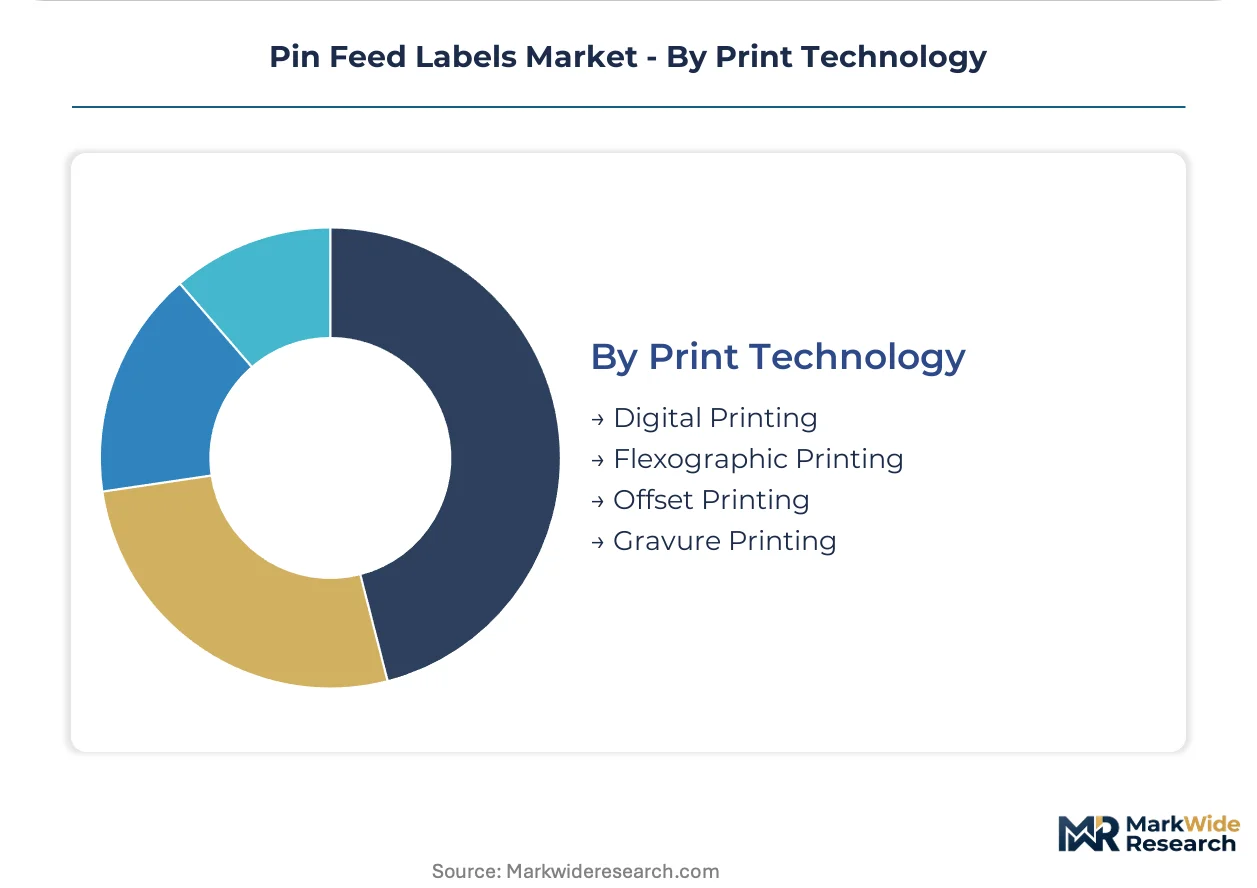
Print Technology:
Volume concentration favors flexographic and gravure lines for long-run continuous-form production, while digital assets serve short-run customization with lower makeready burden.
- Digital Printing:Toner and inkjet imaging enable variable data serialization for pharmaceutical compliance without plate costs. FDA 21 CFR Part 11 durability specifications are forcing digital press investments for archive-grade output validation.
- Flexographic Printing:Rotary letterpress analogs dominate high-volume shipping label production with rapid changeover between adhesive formulations.
- Offset Printing:Lithographic precision serves premium retail graphics with extended color gamut requirements.
- Gravure Printing:Cylinder-based intaglio delivers consistent ink density for long-run thermal transfer ribbon coatings.
Flexographic absorbs the bulk of installed capacity; digital printing is expanding most quickly on serialization compliance demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock availability in the US Gulf Coast and Germany's Rhine-Ruhr corridor anchors adhesive production for pin feed label substrates. Warehouse automation investments and e-commerce fulfillment density concentrate procurement demand in specific industrial clusters across four major economies.
United States
FDA 21 CFR Part 11 electronic record requirements drive pharmaceutical distributors toward archive-grade thermal transfer labels with multi-year legibility validation. EPA volatile organic compound emission thresholds accelerate solvent-to-hot-melt adhesive line conversions among domestic converters. The Chicago-Milwaukee warehousing corridor concentrates automated sorting infrastructure investment, compressing label procurement cycles for same-day fulfillment operators.
Germany
REACH phthalate restrictions in vinyl facestocks redirect converter R&D toward bio-based plasticizer alternatives and polyester substitutes. ECHA substance authorization timelines extend qualification cycles for pharmaceutical and retail labeling segments. The Rhine-Ruhr logistics cluster sustains Europe's densest automated sorting infrastructure, concentrating procurement among operators with 500-plus printer deployments.
China
GB standards for packaging traceability and MIIT industrial automation directives expand demand for high-speed continuous-form media in domestic e-commerce fulfillment. Dual carbon goals pressure adhesive coating operations toward waterborne system conversions. The Yangtze River Delta manufacturing belt hosts expanding converter capacity serving both domestic consumption and export-oriented pharmaceutical serialization.
Japan
METI supply chain resilience initiatives and PMDA pharmaceutical serialization mandates sustain premium multi-layer construction demand for cold-chain distribution. JIS durability specifications for electronic records shape label permanence requirements in domestic pharmaceutical distribution. The Kanto region around Tokyo anchors specialized converter operations serving precision inventory management applications.
India
CDSCO pharmaceutical traceability requirements and DGFT export documentation mandates expand compliant pin feed label volumes for domestic and international shipment. PLI scheme incentives for logistics infrastructure accelerate warehouse automation adoption. The Maharashtra-Gujarat industrial corridor concentrates pharmaceutical manufacturing and third-party logistics operator procurement for high-throughput sorting environments.
Pin Feed Labels Market Competitive Landscape
Global majors compete with regional champions across adhesive science portfolios and printer-label bundling capabilities. Market structure tilts toward consolidated leadership among diversified materials conglomerates with captive adhesive formulation expertise, while specialized converters occupy niche pharmaceutical and cold-chain segments. Three archetypes dominate: integrated adhesive-substrate producers, printer-hardware bundlers, and compliance-focused serialization specialists. Capacity expansion and strategic partnerships represent the dominant competitive vectors as EPA and REACH regulatory timelines compress.
Within the integrated materials tier, Avery Dennison Corporation and 3M Company exemplify global conglomerates with captive adhesive science capabilities spanning hot-melt and acrylic systems. Zebra Technologies Corporation anchors the hardware-bundling archetype through printer-label supply arrangements that lock in recurring media volumes. SATO Holdings Corporation occupies a position among Asia-Pacific-based specialists with concentration in high-durability synthetic facestocks for pharmaceutical and retail applications.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| Zebra Technologies Corporation |
| CCL Industries |
| SATO Holdings Corporation |
| UPM-Kymmene Corporation |
| Multi-Color Corporation |
| 3M Company |
| Lintec Corporation |
| Toshiba Tec Corporation |
| Others |
Value Network & Pricing Analysis
EPA volatile organic compound emission thresholds gate qualified supply access and premium-tier pricing power for converters serving pharmaceutical and industrial accounts. Compliance with waterborne adhesive conversion mandates separates certified producers commanding archive-grade thermal transfer premiums from standard-grade competitors facing margin compression.
Pricing Analysis
Printer-label bundling programs structure the dominant pricing model, with multi-year service arrangements including hardware maintenance, media replenishment, and technical support versus unbundled transactional spot purchasing. Three-tier pricing structure across premium, standard, and economy levels differentiates by FDA 21 CFR Part 11 certification grade and volume commitment scale, with pharmaceutical serialization compliance commanding the widest spreads. Cost compression in commodity paper grades intensifies because hot-melt polymer feedstock costs fluctuate with Gulf Coast petrochemical indices. Third-party logistics operators with 500-plus printer deployments demonstrate the lowest price sensitivity, while small-format office buyers below 100 labels per batch exhibit acute elasticity to per-roll differentials.
Supply Chain Analysis
FDA 21 CFR Part 11 print permanence certification and REACH phthalate compliance gate supplier qualification, extending onboarding timelines before volume procurement authorization. Raw material supply concentrates in the United States, Germany, and China, with adhesive formulation chemistry anchored in Gulf Coast petrochemical corridors and Rhine-Ruhr chemical clusters. Converter operations draw from acrylic and hot-melt polymer feedstocks, thermal paper facestocks, and synthetic film substrates. Single-source vulnerability in pharmaceutical-grade thermal transfer ribbon coatings concentrates risk among qualified suppliers. Distribution runs through converter-direct relationships with large enterprise accounts and industrial distribution channels serving mid-tier warehouse operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where REACH phthalate restrictions and EPA emission timelines are forcing sub-scale converters without captive adhesive science toward exit or acquisition.
For Market Incumbents: To counter laser and inkjet substitution in back-office document workflows, Avery Dennison Corporation and 3M Company should deepen backward integration into waterborne adhesive formulation chemistry and expand converter capacity in the Chicago-Milwaukee corridor to secure proximity to automated sorting infrastructure investments. Certification investment in FDA 21 CFR Part 11 archive-grade validation represents the critical lever for margin defense against commodity-grade competitors. For New Entrants and Emerging Players: CDSCO pharmaceutical traceability requirements in India open a window for specialized converters to establish serialization-compliant production serving the Maharashtra-Gujarat industrial corridor. Cold-chain logistics expansion in refrigerated pharmaceutical distribution offers the most penetrable white space, with polyester facestock qualification for moisture-immune applications representing the optimal go-to-market angle against entrenched paper-grade incumbents. For Investors and Strategic Acquirers: Consolidated procurement contract announcements from German e-commerce fulfillment networks with 500-plus printer deployments are the leading indicator that bundled supply economics are achieving scale sufficient to compress independent converter margins. The five-to-ten year viability window favors acquisition targets with captive adhesive formulation expertise and existing EPA waterborne conversion capital deployed, with ECHA substance authorization timeline delays serving as the critical signal to watch for distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Waterborne Adhesive Line Conversion | EPA VOC thresholds reward early capital deployers with regulatory positioning against solvent-dependent competitors. |
| Printer-Label Bundling Program Expansion | Zebra Technologies Corporation's hardware-media integration locks in recurring volumes across German logistics clusters. |
| Pharmaceutical Serialization Compliance Investment | FDA 21 CFR Part 11 durability specifications create premium multi-layer construction demand above commodity grades. |
| Rhine-Ruhr Converter Capacity Addition | Proximity to Europe's densest automated sorting infrastructure reduces logistics costs for same-day fulfillment operators. |
| Bio-Based Plasticizer R&D Partnership | REACH phthalate restrictions redirect formulation investment toward ECHA-compliant alternatives before commercial scale. |
Research Methodology
Multi-period observation of warehouse automation deployment rates, adhesive formulation patent filings, and pharmaceutical serialization compliance timelines anchored the trend analysis, supplemented by interviews with converter plant managers, logistics procurement leads at third-party operators, distribution channel partners, and technical R&D directors in adhesive science. Secondary validation incorporated customs and trade data from USITC and Eurostat, SEC 10-K disclosures from diversified materials conglomerates, EPA enforcement action records, and ECHA substance authorization databases. Bottom-up volume modeling across substrate chemistry tiers triangulated against top-down macroeconomic indicators for e-commerce fulfillment infrastructure investment.
Segment-weighting approaches distributed total market value across thermal transfer and direct thermal label types, paper and synthetic material grades, and shipping versus inventory management applications, with additional dimensioning by pharmaceutical serialization compliance tier. CAGRs were derived from regression analysis of historical procurement cycle compression and projected automation penetration rates across the analysis window. Forecast inputs included MIIT industrial automation directives in China, PLI scheme logistics infrastructure incentives in India, and METI supply chain resilience initiatives in Japan.
The model assumes a particular technology adoption path favoring direct thermal migration in short-lifecycle inventory workflows; alternative pathways for thermal transfer ribbon-dependent imaging would alter the outlook for archive-grade substrate demand. Forecasts reflect assumptions regarding REACH authorization timeline adherence and EPA enforcement consistency that could revise projections upon regulatory delay or acceleration. A model refresh is warranted upon material change in ECHA substance authorization schedules or FDA 21 CFR Part 11 durability specification amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Direct Thermal Labels Market
Labels
Domed Labels Market
Labels
BOPP Labels Market
Labels
Repositionable Labels Market
Labels
Barcode Label Market
Labels
Retro-Reflective Labels Market
Labels
Inventory Tags Market
Labels
Booklet Labels Market
Labels
Global Security Labels Market
Labels
Ripeness Indicator Labels Market
Labels
Self-Laminating Labels Market
Labels
Laser Printable Wristbands Market
Labels
Fiber Optic Labels Market
Labels
Heat Shrink Sleeve Market
Labels
Ampoule Sticker Labeling Machine Market
Labels
Cut and Stack Labels Market