
 Shrink and Stretch Sleeve Labels Market | 2026-2036
Shrink and Stretch Sleeve Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Shrink and Stretch Sleeve Labels Market Analytics
PETG is expanding its share in shrink sleeve formulations as brand owners phase out polyvinyl chloride for sustainability-aligned packaging economics. CCL Industries leverages vertical integration from film extrusion to printed sleeves, sustaining cost advantages across North American beverage accounts. Berry Global Group anchors its position through blown film capacity and healthcare-certified cleanroom operations. Fuji Seal International competes on gravure and digital print platforms across Asian manufacturing clusters.
Shrink and stretch sleeve labels are tubular polymer films—typically PETG, PVC, or oriented polystyrene—that conform to container contours through heat or mechanical tension, delivering full-body decoration, tamper evidence, and barrier protection. The application dimension shows beverage packaging commanding the largest volume pool, while pharmaceutical products generate the highest per-unit margin due to serialization and anti-counterfeiting requirements. Material-grade segmentation reveals PETG outpacing polyvinyl chloride growth as regulatory pressure and corporate sustainability targets reshape procurement specifications across FMCG end users.
The FDA governs indirect food contact substances for sleeve labels in the United States, while the EU Green Deal and REACH restrict persistent organic compounds in PVC-based formulations. EFSA guidelines on recycling stream compatibility are pushing converters toward mono-material polyethylene and polypropylene structures that sort cleanly in European mechanical recycling infrastructure. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to invest in solvent-free adhesive systems or aqueous ink platforms before compliance deadlines tighten.
Market Dynamics
The EU Green Deal and REACH restrictions on PVC formulations are forcing material transitions toward recyclable PETG and bio-based polyolefins across European beverage and pharmaceutical packaging lines.
Growth Catalysts
- Extended Producer Responsibility frameworks:The EU Green Deal mandates recyclability targets that favor mono-material sleeve structures. Beverage bottlers in Germany are retrofitting lines to meet these specifications.
- Pharmaceutical serialization requirements:Anti-counterfeiting and track-and-trace mandates from EMA and FDA are expanding tamper-evident sleeve adoption for high-margin drug packaging.
- 360-degree branding demand:CPG marketers are specifying full-body shrink sleeves to maximize shelf impact in competitive retail environments.
Market Restraints
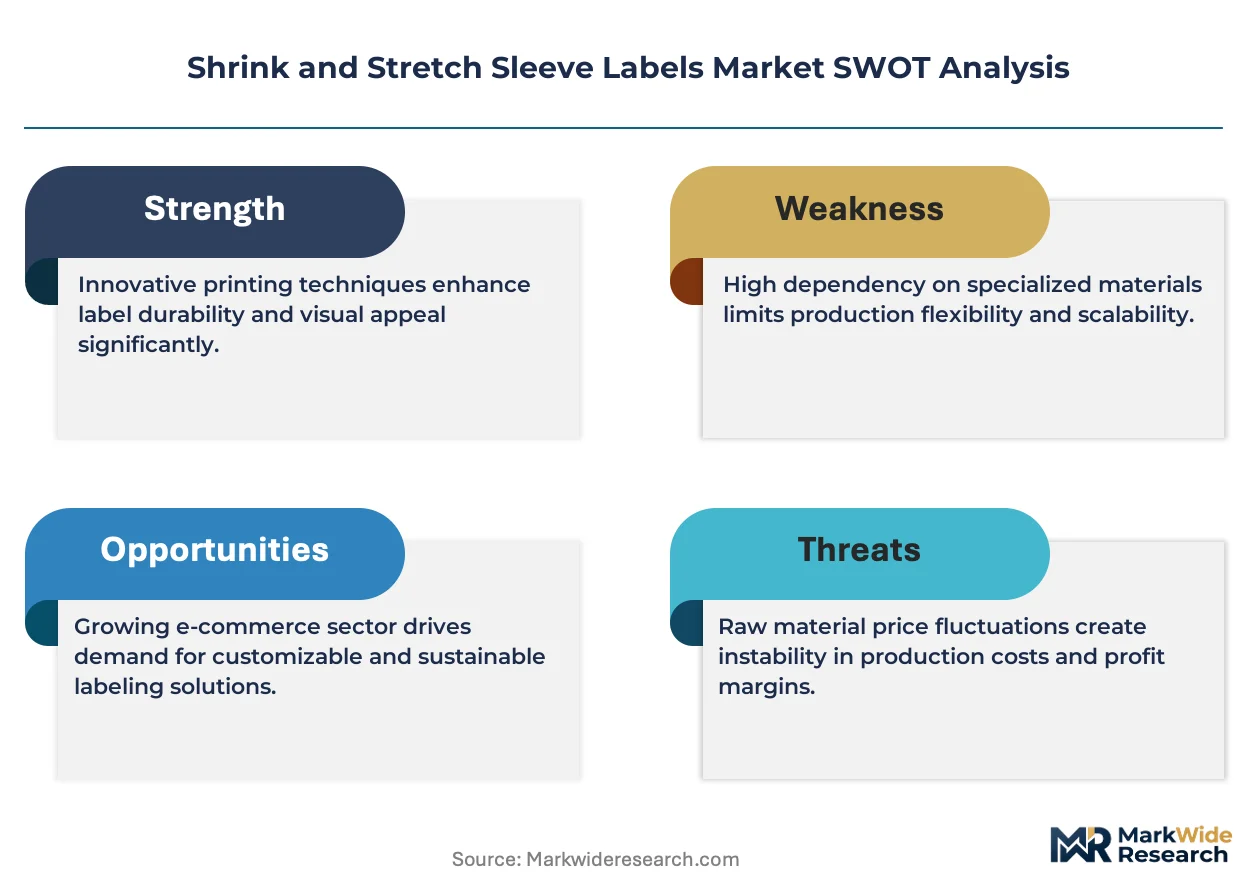
- Raw material cost volatility:PETG resin prices fluctuate with crude oil derivatives and polyester feedstock availability, compressing converter margins.
- Equipment capex barriers:High-speed sleeve application systems require substantial capital investment that mid-tier beverage bottlers cannot absorb.
- Sorting infrastructure gaps:Mixed-material sleeves contaminate mechanical recycling streams where municipal facilities lack near-infrared detection capabilities.
Strategic Opportunities
- Healthcare-certified cleanroom capacity:Pharmaceutical packaging demands ISO 14644 compliant sleeve production that few converters currently offer.
- Solvent-free adhesive platforms:EFSA guidelines on recycling stream compatibility are creating first-mover advantages for converters investing in aqueous ink systems.
- Digital gravure hybrid printing:Short-run customization for craft beverage brands is integrating digital platforms with traditional gravure economics.
Industry Challenges
- Skilled press operator shortages:Gravure and flexo sleeve printing requires specialized training that vocational programs in Germany and the United States are not producing at sufficient scale.
- Legacy line integration complexity:Retrofitting existing bottling equipment for heat-shrink tunnel compatibility demands extensive mechanical engineering and downtime coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shrink and Stretch Sleeve Labels Market |
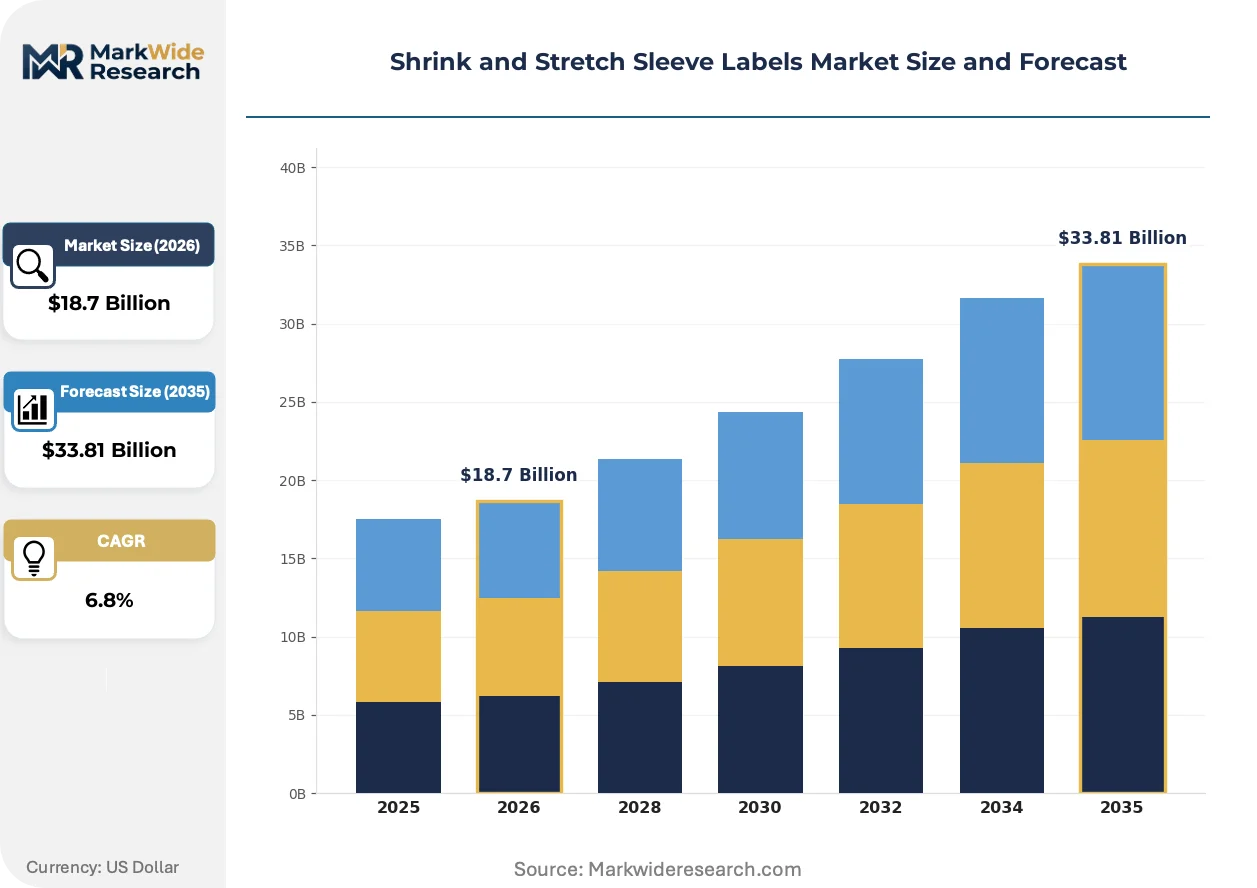
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sleeve Labels, In-Mold Labels, Pressure-Sensitive Labels, Peel-Off Labels Material: Polyvinyl Chloride, Polyethylene, Polypropylene, PETG Application: Beverage Packaging, Food Packaging, Personal Care Products, Pharmaceutical Products End User: FMCG, Food Industry, Beverage Manufacturers, Pharmaceutical Companies |
| Companies Covered | Berry Global Group, CCL Industries, Fuji Seal International, Amcor plc, Avery Dennison Corporation, Klockner Pentaplast, Huhtamaki, Multi-Color Corporation, Clondalkin Group Holdings BV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shrink and Stretch Sleeve Labels Market Evolving Landscape
Material science advances and regulatory pressure are converging to reshape sleeve label specifications, with sustainability metrics now embedded in procurement scorecards alongside print quality and application speed.
Digital printing technology is integrating with conventional gravure platforms to enable economical short runs and mass customization. Craft beverage producers and regional pharmaceutical marketers are adopting these hybrid systems for seasonal campaigns and limited-edition SKUs. The technology is integrating variable data capabilities that support serialization mandates while reducing plate costs and setup waste.
REACH restrictions on persistent organic compounds in PVC-based formulations are accelerating PETG and oriented polystyrene substitution across European supply chains. EFSA guidelines on recycling stream compatibility are pushing converters toward mono-material polyethylene structures that sort cleanly in mechanical recycling infrastructure. Pharmaceutical packagers in Germany are responding by qualifying PETG alternatives ahead of compliance deadlines.
Buyer consolidation among multinational beverage corporations is compressing supplier lists and extending contract durations. Procurement teams are unbundling sleeve supply from filling-line equipment packages to secure multi-year film supply agreements. This pattern is most visible in North American and Western European accounts where Coca-Cola, PepsiCo, and Nestlé have centralized packaging specifications.
Shrink and Stretch Sleeve Labels Market Segmentation
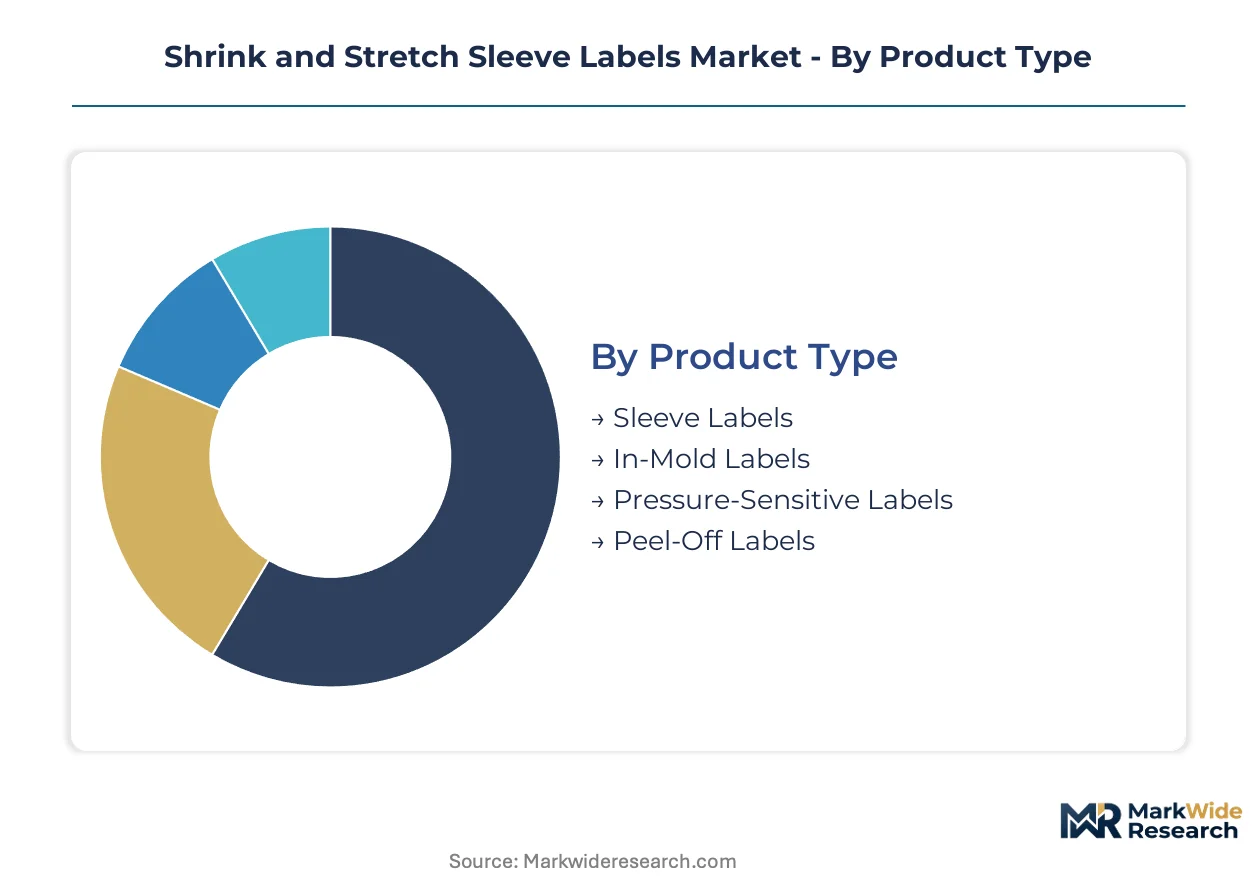
Sleeve label procurement varies sharply across container geometries and regulatory exposure, with beverage bottlers prioritizing heat-shrink compatibility while pharmaceutical packagers demand tamper-evident serialization. Material selection and application equipment requirements create distinct purchasing workflows that separate high-volume commodity buyers from specification-intensive healthcare accounts.
Product Type:
Standalone sleeve applications dominate high-speed bottling lines where heat tunnels operate as discrete process steps, while embedded label systems integrate directly with blow-molding or injection equipment for in-mold decoration.
- Sleeve Labels:Tubular polymer films applied post-forming through heat-shrink or mechanical stretch mechanisms, delivering 360-degree graphics coverage. Beverage bottlers in Germany specify these for carbonated soft drink containers where full-body branding and tamper-evident neck bands are mandatory. Heat-shrink tunnel retrofits remain a capital barrier for mid-tier producers.
- In-Mold Labels:Pre-printed films inserted into mold cavities prior to resin injection, fusing permanently with container walls during formation. Personal care marketers in France favor this approach for premium cosmetic bottles where label durability and scratch resistance justify higher mold complexity. The integration eliminates secondary labeling operations entirely.
- Pressure-Sensitive Labels:Adhesive-backed facestocks applied through mechanical pressure without heat activation, suited for temperature-sensitive pharmaceutical vials where heat exposure risks product degradation.
- Peel-Off Labels:Multi-layer constructions enabling coupon or promotional detachment, deployed by FMCG marketers for loyalty program integration on food packaging.
Sleeve Labels lead volumes today; In-Mold Labels is gaining share fastest.
Material:
Cost tier stratification separates commodity polyolefins from engineered polyesters, with sustainability premiums reshaping procurement scorecards across European beverage accounts.
- Polyvinyl Chloride:Legacy shrink film offering high shrink ratios and printability at lowest unit cost, now restricted under REACH persistent organic compound regulations. German converters are decommissioning PVC extrusion lines ahead of compliance deadlines.
- Polyethylene:Mono-material structures compatible with European mechanical recycling infrastructure, qualifying for extended producer responsibility credits under EU Green Deal targets. Food packagers specify these for stream-sortability where municipal near-infrared detection is operational.
- Polypropylene:High-clarity films with moisture resistance suited for refrigerated beverage applications, though lower shrink ratios limit conformability to complex container geometries.
- PETG:Glycol-modified polyester delivering optical clarity, controlled shrink behavior, and pharmaceutical-grade certification for serialization applications. EFSA recycling stream compatibility guidelines are accelerating substitution from PVC across healthcare packaging lines.
PETG climbs the fastest; Polyvinyl Chloride is losing position.
Application:
Volume concentration versus margin capture splits this dimension, with beverage packaging driving raw tonnage and pharmaceutical products commanding per-unit premiums for compliance-intensive specifications.
- Beverage Packaging:Carbonated soft drinks, bottled water, and craft beer represent the largest addressable volume pool, with 360-degree shrink sleeves replacing paper labels for shelf differentiation. Coca-Cola and PepsiCo centralized procurement specifications favor mono-material PETG structures.
- Food Packaging:Condiment bottles, dairy containers, and ready-meal trays utilize sleeve labels for brand blocking and regulatory information display. EFSA guidelines on food contact substances constrain adhesive and ink selections.
- Personal Care Products:Shampoo, conditioner, and cosmetic bottles demand high-definition gravure printing for premium aesthetics, with in-mold labels competing for share on luxury positioning.
- Pharmaceutical Products:Vial and bottle labeling with integrated tamper-evidence, anti-counterfeiting holograms, and serialization codes mandated by FDA and EMA track-and-trace regulations. ISO 14644 cleanroom production is required.
Beverage Packaging dominates tonnage; Pharmaceutical Products expands most quickly.
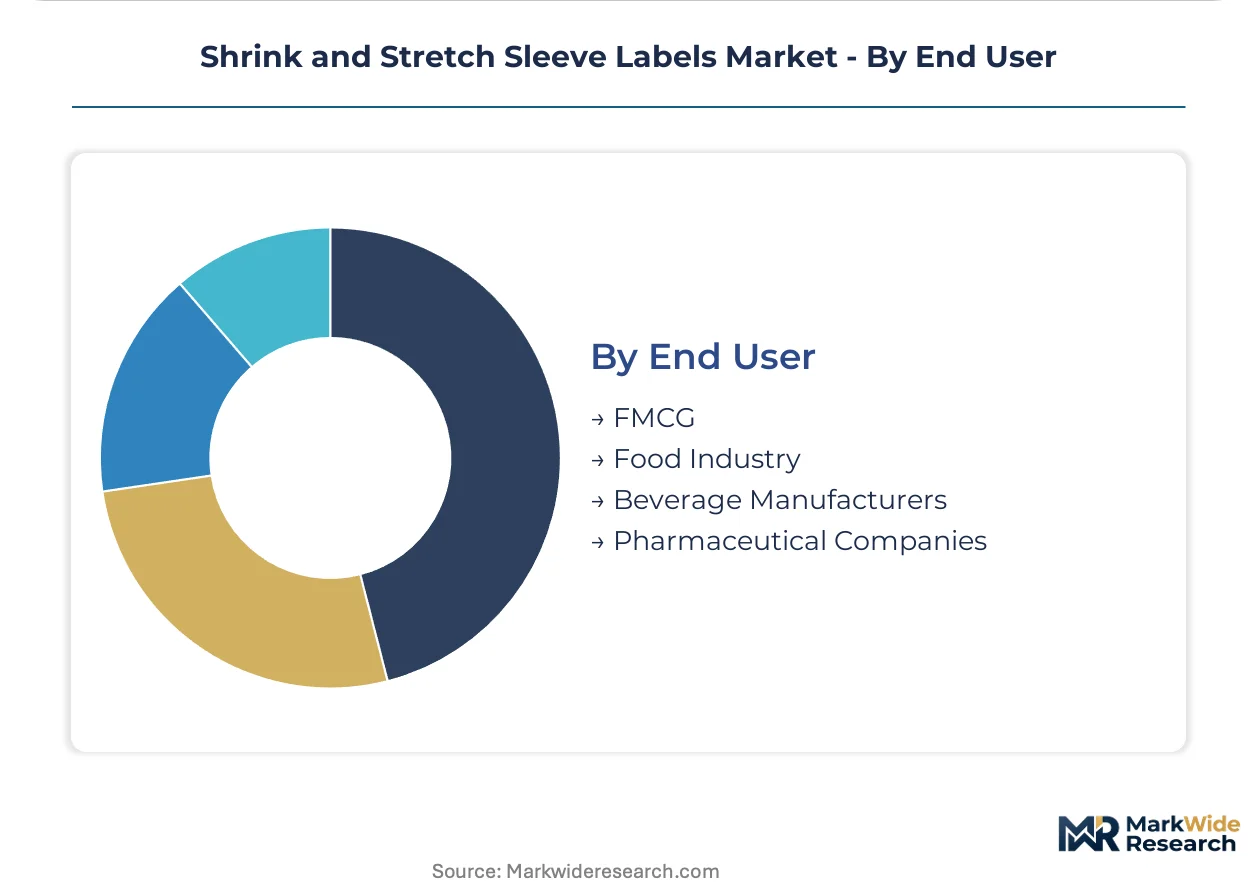
End User:
Customer type segmentation reveals procurement sophistication gaps, with multinational beverage corporations operating centralized specification committees while regional food producers rely on converter technical guidance.
- FMCG:Diversified consumer goods conglomerates managing cross-category packaging standardization, leveraging volume consolidation for multi-year film supply agreements.
- Food Industry:Processors and packagers prioritizing shelf-life extension and regulatory compliance labeling, with EFSA food contact notifications driving material qualification timelines.
- Beverage Manufacturers:Bottlers retrofitting lines for high-speed sleeve application, facing equipment capex barriers that favor outsourced contract labeling for mid-tier producers.
- Pharmaceutical Companies:Drug packagers demanding healthcare-certified cleanroom capacity, serialization integration, and anti-counterfeiting features that extend qualification cycles.
Beverage Manufacturers anchor demand; Pharmaceutical Companies is expanding fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German beverage bottlers in Bavaria and North Rhine-Westphalia are retrofitting lines for high-speed sleeve application systems ahead of EU Green Deal compliance deadlines.
Germany
Beverage manufacturers in Munich and Hamburg are converting PVC extrusion lines to PETG ahead of REACH persistent organic compound restrictions. The EU Green Deal mandates recyclability targets that favor mono-material sleeve structures. Stuttgart-area converters are qualifying pharmaceutical-grade PETG for serialization applications.
United States
FDA indirect food contact regulations govern sleeve label materials for carbonated soft drink bottlers in Atlanta and Chicago. Coca-Cola and PepsiCo centralized procurement specifications favor mono-material structures. California's extended producer responsibility framework is accelerating shifts toward recyclable polyethylene formulations.
China
NMPA pharmaceutical packaging standards are expanding tamper-evident sleeve adoption for drug manufacturers in Shanghai and Shenzhen. Dual carbon goals are pressuring converters toward bio-based polyolefins. Yangtze River Delta film extruders are scaling PETG capacity for export beverage accounts.
Japan
METI circular economy guidelines are reshaping material specifications for Tokyo and Osaka beverage packagers. PMDA serialization mandates are driving healthcare-certified cleanroom investments. Nagoya-area converters are integrating digital gravure hybrid platforms for short-run craft beverage customization.
India
CDSCO track-and-trace regulations are expanding pharmaceutical sleeve label demand in Mumbai and Hyderabad. FSSAI food contact notifications constrain adhesive selections for domestic beverage accounts. Gujarat film extruders are scaling pressure-sensitive and sleeve label capacity for FMCG exporters.
Shrink and Stretch Sleeve Labels Market Competitive Landscape
Capacity expansion dominates the current landscape as converters retrofit extrusion lines for PETG and bio-based polyolefins. The vendor base separates into three tiers: multinational film producers with captive resin supply, regional converters with healthcare certification, and specialized digital print shops serving craft beverage niches. Strategic partnerships between film extruders and bottling equipment manufacturers are accelerating, while backward integration into resin production is reshaping cost structures.
Among North American integrated producers, Berry Global Group and CCL Industries exemplify the scale-driven archetype with captive film extrusion through printed sleeve delivery. Fuji Seal International occupies a position within the Asia-Pacific gravure and digital print specialist tier. These three anchors represent divergent geographic and capability concentrations that define competitive positioning across beverage, pharmaceutical, and personal care end-use segments.
| Leading Market Players |
|---|
| Berry Global Group |
| CCL Industries |
| Fuji Seal International |
| Amcor plc |
| Avery Dennison Corporation |
| Klockner Pentaplast |
| Huhtamaki |
| Multi-Color Corporation |
| Clondalkin Group Holdings BV |
| Others |
Value Network & Pricing Analysis
The EU Green Deal's recyclability mandates gate qualified supply for sleeve label converters while stratifying pricing tiers between compliant and non-compliant material grades. German beverage bottlers now pay premiums for mono-material PETG structures that sort cleanly in municipal recycling streams, while PVC-dependent suppliers face margin compression from restricted market access.
Pricing Analysis
Input-cost pass-through from PETG resin volatility shapes converter pricing power across the value chain. Three-tier pricing structure across premium pharmaceutical-grade, standard beverage-grade, and economy polyolefin levels separates buyers by certification requirements and volume commitments. Cost compression in standard beverage-grade PETG is intensifying because Yangtze River Delta extruders are expanding capacity for export accounts. Mid-tier regional bottlers exhibit highest price sensitivity due to equipment retrofit capex burdens, while multinational pharmaceutical packagers show lowest sensitivity given serialization compliance premiums.
Supply Chain Analysis
Dual-sourcing requirements from Coca-Cola and PepsiCo procurement committees force converters to qualify secondary film extruders in Germany and the United States. Raw material supply draws from purified terephthalic acid feedstocks in China, glycol modifiers in Saudi Arabia, and specialty additives from Switzerland. Single-source vulnerability concentrates in pharmaceutical-grade PETG resin where healthcare-certified cleanroom production capacity remains limited. Distribution runs through converter-direct relationships with bottling line OEMs for integrated equipment-label packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU regulatory stringency creates premium pricing pools that Asian converters can capture through healthcare certification investments. The cost differential between REACH-compliant European production and NMPA-qualifying Chinese capacity exceeds the logistics burden for pharmaceutical-grade film.
For Market Incumbents: Hedge against PETG resin volatility through captive glycol-modified polyester production or long-term offtake agreements with Yangtze River Delta feedstock suppliers. Berry Global Group and CCL Industries should defend position by accelerating healthcare-certified cleanroom capacity additions in Stuttgart and Chicago to capture pharmaceutical serialization demand before EMA deadlines tighten. Backward integration into film extrusion remains the priority lever for margin defense against Asian import pressure. For New Entrants and Emerging Players: Digital gravure hybrid platforms offer the most penetrable wedge for craft beverage short-run customization in Japan and North America. Target Nagoya-area and Portland metropolitan clusters where seasonal SKU proliferation outpaces incumbent converter flexibility. White-space exists in ISO 14644 cleanroom sleeve production for Indian pharmaceutical exporters facing CDSCO track-and-trace mandates. Go-to-market should emphasize variable-data serialization integration bundled with tamper-evident design services. For Investors and Strategic Acquirers: Roll-up economics work for regional healthcare-certified converters because pharmaceutical qualification cycles create durable customer captivity and pricing power. The 5-10 year viability window favors platforms consolidating German and Midwestern US assets with existing FDA and EMA drug master files. Target acquisition archetype: single-film extrusion lines with cleanroom retrofit potential and established relationships with sterilized packaging distributors. The signal to watch is EFSA guidance tightening on recycling stream compatibility, which would accelerate PVC displacement and reward early PETG capacity positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Healthcare Cleanroom Certification | ISO 14644 compliance unlocks pharmaceutical serialization contracts with EMA-mandated track-and-trace requirements. |
| Backward Integration into PETG Resin | Captive glycol-modified polyester production insulates margins from crude oil derivative volatility in Asian feedstock markets. |
| Digital Gravure Hybrid Platform Deployment | Short-run customization capabilities capture craft beverage seasonal SKU proliferation in Japan and North American markets. |
| Mono-Material Polyethylene Qualification | EFSA recycling stream compatibility positions converters for EU Green Deal extended producer responsibility credits. |
| Strategic Equipment Manufacturer Partnership | Integrated sleeve-label and heat-tunnel packages reduce bottler capex barriers and secure multi-year film supply agreements. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture both volume trajectories and procurement decision dynamics. Primary fieldwork engaged film extrusion plant managers, beverage bottler procurement leads, pharmaceutical packaging engineers, and healthcare regulatory affairs specialists across Germany, the United States, China, and Japan. Secondary validation drew from FDA food contact notifications, EFSA recycling compatibility guidelines, NMPA pharmaceutical packaging standards, and customs trade data on polymer film imports. Bottom-up capacity modeling and top-down demand aggregation were triangulated against converter revenue disclosures.
Comparable-period anchoring tied projection assumptions to historical PETG substitution patterns and PVC regulatory phase-out timelines across European supply chains. The analytical framework segmented volume and value across material grade, application end-use, and regional regulatory cluster throughout the forecast period. CAGRs were derived from fitted growth curves calibrated to equipment installation rates and compliance deadline proximity. Industry-specific inputs included heat-shrink tunnel retrofit capex cycles and pharmaceutical serialization mandate implementation schedules.
The model holds under stable EU Green Deal enforcement and continued EMA serialization expansion; deviation in REACH restriction timing or NMPA standard harmonization would shift material substitution trajectories materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Barcode Label Market
Labels
Kraft Labels Market
Labels
Future-Proof Pharma Labels Market
Labels
HAZMAT Labels Market
Labels
Linerless Labels Market
Labels
Global Sensormatic Labels Market
Labels
Direct Thermal Labels Market
Labels
Pressure Sensitive Labels Market
Labels
Shrink Sleeve Labels Market
Labels
Water Dissolvable Labels Market
Labels
In-Mold Labeling (IML) Market
Labels
Freshness Indicator Label Market
Labels
Label Applicator Market
Labels
Sheeted Labels Market
Labels
Integrated Labeling System Market
Labels
Global Security Labels Market