
 Waterproof and Weatherproof Label Market | 2026-2036
Waterproof and Weatherproof Label Market Size, Share, and Industry Trends Forecast 2026-2036
Waterproof and Weatherproof Label Market Analysis
The gap between premium performance grades and commodity substitutes is repositioning procurement behavior across end-use sectors. Avery Dennison Corporation leverages its materials science portfolio to command the high-durability tier, while CCL Industries Inc anchors North American supply through specialized narrow-web converting. 3M Company competes on adhesive chemistry depth, particularly in heat-activated formulations for extreme-climate deployment.
Waterproof and weatherproof labels are pressure-sensitive or heat-activated constructions engineered from polyester, vinyl, or polypropylene substrates with polymer-based adhesives, designed to maintain legibility and adhesion across temperature swings, UV exposure, and moisture immersion. Their primary commercial purpose is to preserve traceability, branding, and regulatory marking on assets and products subjected to harsh environmental or handling conditions. Polyester-based labels lead on durability margins in outdoor and industrial applications, while pressure-sensitive adhesives dominate installation efficiency across logistics and manufacturing segments. Vinyl substrates represent the fastest-growing material category, driven by flexible packaging converters seeking cost-performance balance in cold-chain pharmaceutical labeling.
The US EPA regulates adhesive volatile organic compound content under architectural coatings rules, while REACH and RoHS frameworks in Europe restrict hazardous substances in label substrates and coatings, directly shaping material substitution patterns among converters. The FDA's unique device identification requirements for medical devices further tighten performance standards for labels exposed to sterilization and long-term storage. Stakeholders must monitor evolving extended producer responsibility laws across multiple geographies, as these will increasingly mandate recyclability and restrict single-use synthetic label constructions without equivalent performance alternatives.
Market Dynamics
EU Green Deal packaging sustainability mandates are forcing converters to abandon legacy synthetic substrates before recyclable polyester alternatives achieve cost parity, creating a supply bottleneck for industrial-grade weatherproof tagging systems.
Growth Catalysts
- Cold-chain pharmaceutical logistics:Temperature excursions in biologics distribution require labels that maintain adhesion from -80°C to +25°C. Vinyl substrates with cryogenic-grade adhesives are capturing this specification tier.
- REACH substance restrictions:European converters are reformulating adhesives to eliminate restricted phthalates and heavy metals, accelerating migration toward UV-curable acrylic systems that outperform legacy solvent-based chemistries.
- German automotive cluster demand:Stuttgart and Wolfsburg assembly plants require component labels surviving pressure-wash cycles, chemical exposure, and 15-year vehicle lifecycles. This specification intensity pulls premium substrate volumes.
Market Restraints
- Petrochemical input volatility:Polyester and polypropylene resin prices fluctuate with crude oil indices. Narrow-web converters lack hedging capacity, compressing margin stability during feedstock spikes.
- Adhesive supply concentration:Heat-activated formulation expertise concentrates among three specialty chemical suppliers in the US and Germany. Any disruption propagates through the converting tier within weeks.
- Recyclability-performance tradeoff:Current recyclable polyester substrates sacrifice 20-30% of moisture resistance versus virgin constructions. Food and chemical processors resist adoption where label failure risks batch contamination.
Strategic Opportunities
- India pharmaceutical export labeling:CDSCO traceability mandates for active pharmaceutical ingredients create demand for sterilization-resistant labels. Domestic converting capacity remains underdeveloped.
- Digital printing convergence with RFID inlay integration:Hybrid labels combining variable data print with embedded tracking are penetrating high-value agricultural equipment and aerospace component markets.
- Extended producer responsibility tailwinds:France's AGEC law and similar frameworks in Italy and Spain mandate recyclability disclosures. Early-compliant converters capture preferential supplier status with multinational brand owners.
Industry Challenges
- Adhesive formulation chemist scarcity:Polymer science expertise for extreme-climate performance is retiring faster than universities produce replacements. Training cycles exceed 18 months.
- FDA UDI compliance timeline compression:Medical device manufacturers face validation requirements for labels surviving gamma sterilization. Third-party testing backlogs extend qualification schedules by 4-6 months.
- Legacy ERP integration friction:Converters adopting print-on-demand workflows struggle to synchronize digital front-ends with existing inventory and job-scheduling systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waterproof and Weatherproof Label Market |
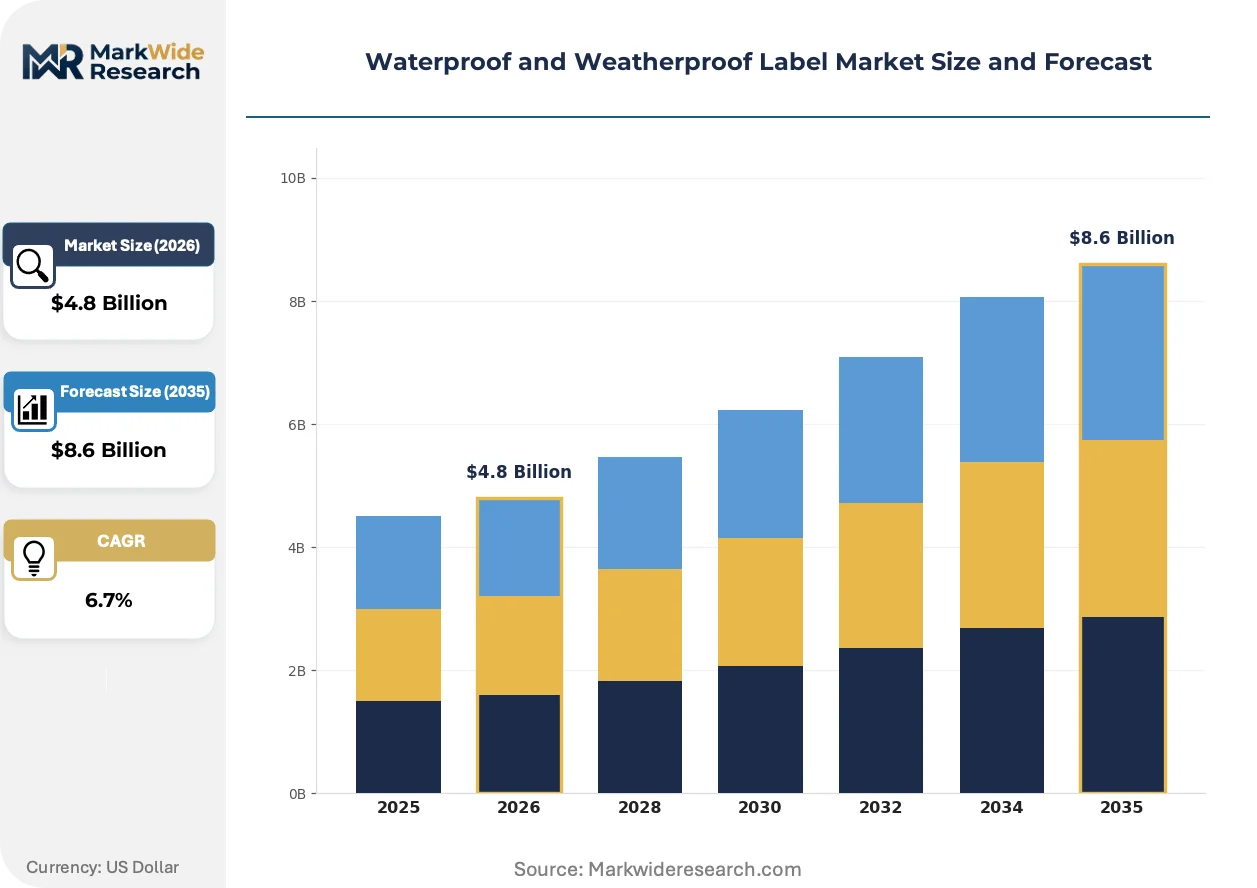
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyester, Vinyl, Polypropylene, Paper Adhesive Type: Permanent, Removable, Pressure-Sensitive, Heat-Activated Application: Outdoor Labels, Industrial Tags, Product Labels, Shipping Labels Market Segment: Consumer Goods, Manufacturing, Logistics, Pharmaceuticals |
| Companies Covered | Avery Dennison Corporation, CCL Industries Inc, UPM Raflatac, 3M Company, Lintec Corporation, Tesa SE, Brady Corporation, Fuji Seal International Inc, Schreiner Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waterproof and Weatherproof Label Market Emerging Trajectories
Laser die-cutting systems and AI-driven color management are compressing make-ready times while substrate innovations target specific climate stressors previously addressed through over-engineering.
Laser die-cutting technology is automating tool-free shape customization for short-run industrial label orders. Contract manufacturers serving aerospace maintenance, repair, and overhaul operations are adopting these systems to reduce 72-hour lead times toward same-day turnaround. This capability is automating the economics of batch-size-one production that previously required minimum order thresholds to justify steel-rule die investment.
REACH Annex XVII expansions are restricting per- and polyfluoroalkyl substances in label coatings and release liners. German and Belgian converters face reformulation deadlines that invalidate existing product qualifications with automotive OEMs. Pressure-sensitive adhesive suppliers are accelerating fluorine-free release coating development, with commercial availability concentrated among two specialty chemical producers through 2026.
Consolidated procurement functions at multinational logistics operators are unbundling label supply from packaging system contracts. Third-party logistics providers in the Netherlands and Singapore are establishing direct supplier relationships with narrow-web converters, bypassing traditional distribution intermediaries. This disintermediation is most visible in pharmaceutical cold-chain operations where traceability requirements demand direct technical dialogue between converter and end-user quality departments.
Waterproof and Weatherproof Label Market Segmentation
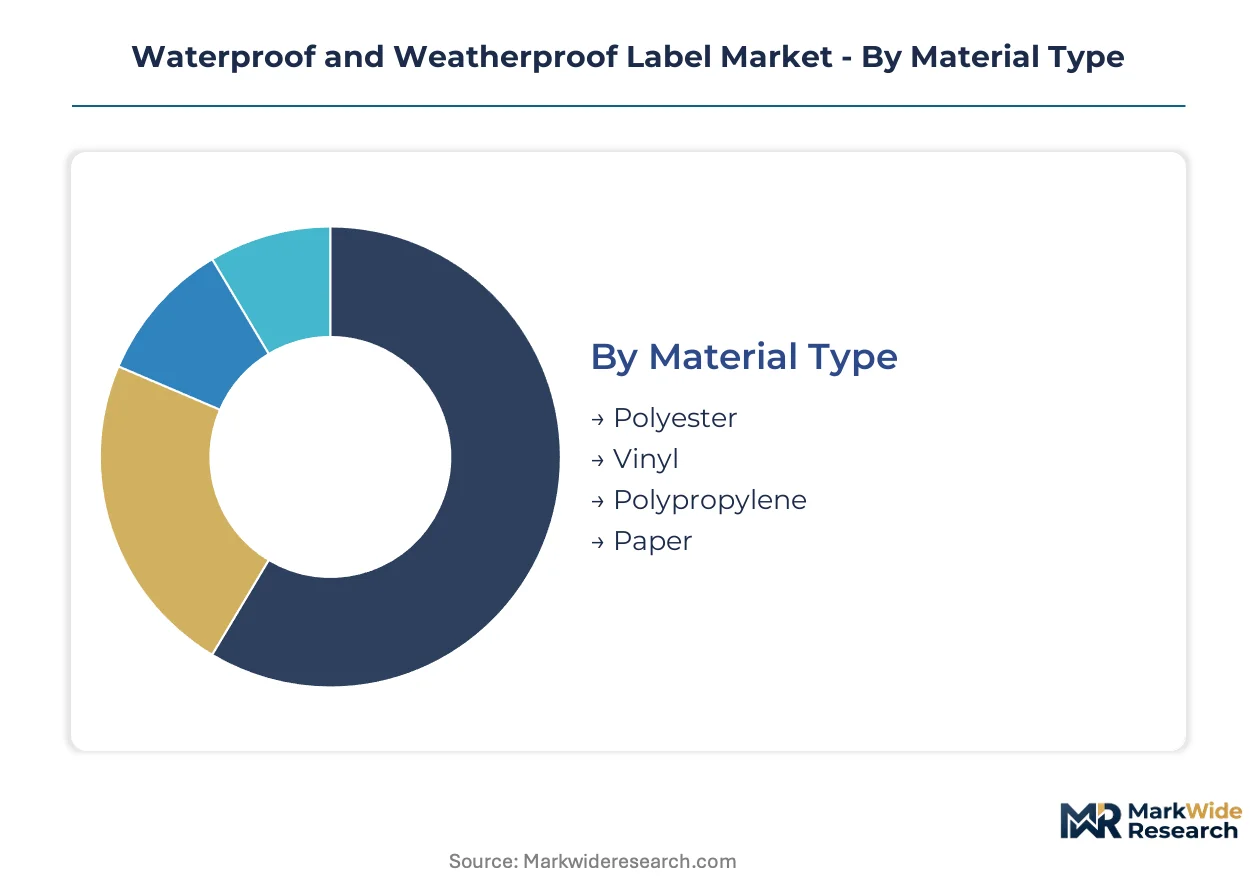
Waterproof and weatherproof label procurement pivots on material science tradeoffs between durability and sustainability compliance. Converters must align substrate selection with end-use environmental stressors and regional regulatory frameworks to avoid qualification failures.
Material Type:
Polymer crystallinity and surface energy determine adhesion performance across temperature and moisture extremes.
- Polyester:Biaxially oriented polyethylene terephthalate delivers tensile strength above 200 MPa and dimensional stability from -40°C to 150°C. German automotive OEMs specify this substrate for under-hood component tracking surviving 15-year service intervals and pressure-wash exposure.
- Vinyl:Plasticized polyvinyl chloride offers conformability to curved surfaces and cold-chain flexibility down to -80°C. Pharmaceutical logistics operators in the Netherlands and Singapore are specifying vinyl for biologics distribution where cryogenic storage transitions create thermal shock conditions.
- Polypropylene:Oriented polypropylene balances moisture resistance with lower density for weight-sensitive shipping applications.
- Paper:Synthetic paper substrates with polyethylene coatings serve indoor industrial environments where temporary water exposure resistance suffices.
Polyester leads on scale; vinyl leads on momentum.
Adhesive Type:
Formulation chemistry dictates activation energy requirements and removability characteristics.
- Pressure-Sensitive:Acrylic or rubber-based formulations bond on contact without thermal or solvent activation. Logistics hubs in Rotterdam and Hamburg deploy these adhesives for high-throughput automated label application where dwell time constraints eliminate heat-activation cycles.
- Heat-Activated:Thermoplastic resins require 120-180°C activation to achieve structural adhesion to low-surface-energy substrates. Aerospace component manufacturers in Toulouse and Hamburg specify heat-activated systems for carbon fiber and powder-coated metal marking where mechanical fastening is prohibited.
- Permanent:Cross-linked acrylics form irreversible bonds for asset identification and tamper-evidence.
- Removable:Low-tack formulations enable residue-free removal for temporary promotional labeling and reusable container tracking.
Pressure-sensitive dominates installation throughput; heat-activated commands specification premiums.
Application:
Environmental exposure severity separates application tiers from controlled indoor to uncontrolled outdoor deployment.
- Outdoor Labels:UV-stabilized constructions with aliphatic polyurethane overlaminate prevent photodegradation. Utility infrastructure operators in Texas and Queensland specify these for pole-mounted transformer identification where 20-year legibility is mandated.
- Industrial Tags:Metal-detectable and chemical-resistant formats survive caustic washdowns in food processing and pharmaceutical manufacturing. Belgian and Danish converters supply these to dairy processing clusters requiring daily sanitization compliance.
- Product Labels:Brand-preserving constructions balance aesthetic requirements with incidental moisture protection for cosmetics and beverage packaging.
- Shipping Labels:Cost-optimized polyester or polypropylene withstands condensation and abrasion through multimodal transit chains.
Industrial tags anchor premium pricing; outdoor labels are expanding most quickly.
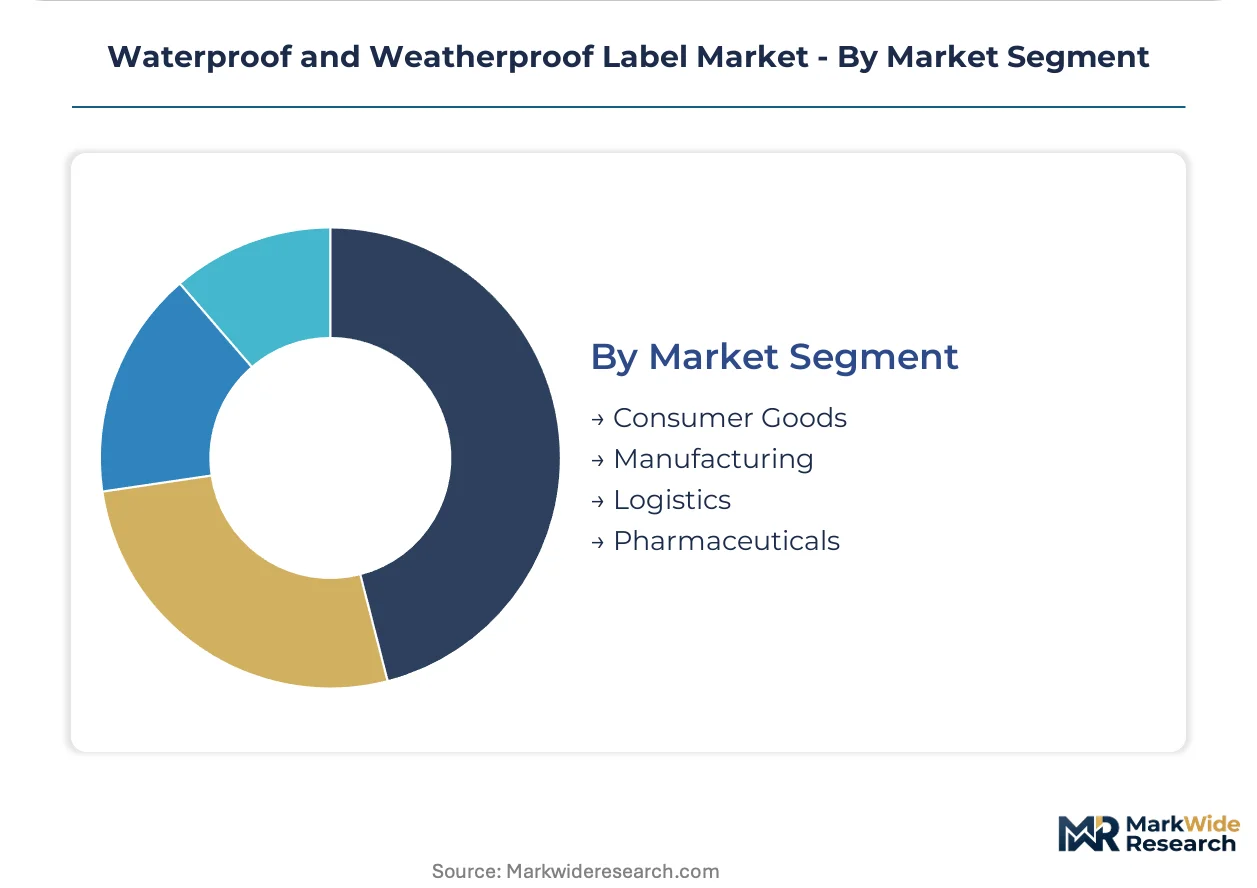
Market Segment:
End-use sector requirements drive specification divergence between traceability mandates and brand communication priorities.
- Logistics:E-commerce fulfillment and cold-chain distribution require scannable durability through temperature swings and mechanical handling. Third-party logistics operators in Singapore and the Netherlands are unbundling label procurement from packaging contracts to enforce direct quality dialogue with converters.
- Pharmaceuticals:FDA UDI and EMA serialization mandates require labels surviving gamma sterilization, ethylene oxide exposure, and long-term archival storage. Medical device manufacturers in Massachusetts and Minnesota face validation backlogs extending qualification schedules.
- Manufacturing:Work-in-process and asset tracking labels integrate with ERP and MES systems for real-time inventory visibility.
- Consumer Goods:Shelf-appeal and sustainability messaging compete with functional durability for household product and personal care applications.
Logistics commands volume concentration; pharmaceuticals drives specification intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized adhesive chemists and polymer scientists concentrate in Germany, the United States, and Japan, anchoring regional innovation capacity for extreme-climate label formulations.
United States
FDA UDI mandates for medical devices and EPA adhesive VOC regulations drive specification intensity. Massachusetts and Minnesota host medical device manufacturers facing gamma sterilization validation backlogs. Boston-area converters specialize in pharmaceutical cold-chain labels surviving temperature excursions from -80°C to +25°C.
Germany
Automotive OEMs in Stuttgart and Wolfsburg demand component labels surviving 15-year service intervals and pressure-wash cycles. REACH Annex XVII restrictions on per- and polyfluoroalkyl substances force adhesive reformulation. Belgian and Dutch converters supply chemical-resistant formats to Ruhr Valley processing clusters.
China
Domestic pharmaceutical export growth and SAMR traceability mandates create demand for sterilization-resistant labeling. Yangtze River Delta converting capacity serves biologics distribution networks. Shanghai-based logistics operators specify vinyl substrates for cryogenic storage transitions.
Japan
METI industrial standards and PMDA pharmaceutical regulations tighten performance requirements for long-term archival storage. Kansai region converters specialize in heat-activated systems for carbon fiber marking. Osaka-area aerospace component manufacturers demand labels surviving chemical exposure without mechanical fastening.
India
CDSCO traceability mandates for active pharmaceutical ingredients outpace domestic converting capacity development. Gujarat and Maharashtra pharmaceutical exporters rely on imported sterilization-resistant labels. Mumbai logistics hubs are unbundling procurement from packaging contracts to enforce direct quality dialogue.
Waterproof and Weatherproof Label Market Vendor Landscape
Top-tier vendors anchor high-durability specification tiers, while mid-scale converters compete on narrow-web specialization and regional logistics proximity. The vendor base separates into materials science conglomerates, specialized narrow-web converters, and adhesive chemistry specialists. Consolidation pressure intensifies as multinational brand owners consolidate procurement functions. Dominant competitive moves include capacity expansion in cryogenic-grade adhesive formulations and strategic partnerships bypassing traditional distribution intermediaries.
Among North American materials science conglomerates, Avery Dennison Corporation and 3M Company occupy positions defined by adhesive chemistry depth and substrate innovation capacity. CCL Industries Inc represents the specialized narrow-web converter archetype, anchoring regional supply relationships through technical dialogue with end-user quality departments. These three entities exemplify the tiered structure where materials portfolio breadth, formulation expertise, and converting specialization define competitive positioning.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| CCL Industries Inc |
| UPM Raflatac |
| 3M Company |
| Lintec Corporation |
| Tesa SE |
| Brady Corporation |
| Fuji Seal International Inc |
| Schreiner Group |
| Others |
Supply Flow & Price Mechanics
Multinational logistics operators consolidating procurement functions are unbundling label supply from packaging system contracts, forcing converters toward direct pricing models that eliminate distributor markups. This disintermediation concentrates price negotiation leverage with third-party logistics providers in Rotterdam and Singapore who demand volume-based contract structures.
Pricing Analysis
Bundled packaging-and-label service contracts are fragmenting into unbundled component procurement, with direct converter relationships commanding 15-20% premiums for technical compliance guarantees. Price differentiation rests on cryogenic-grade adhesive certification and REACH Annex XVII compliance status, with EU Green Deal mandates accelerating cost compression in legacy synthetic substrate tiers. Pharmaceutical cold-chain operators exhibit lowest price sensitivity due to batch contamination risks, while e-commerce fulfillment centers drive aggressive unit-cost negotiations.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and Japan anchor hub-and-spoke fulfillment patterns for extreme-climate adhesive formulations. Raw material flows draw from polyester resin producers in Belgium, specialty chemical formulators in the US, and release liner manufacturers in Japan. Single-source vulnerability concentrates in heat-activated adhesive expertise held by three specialty chemical suppliers. Distribution runs through narrow-web converters maintaining direct technical dialogue with end-user quality departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on converters capturing premium tiers through fluorine-free release coating qualifications ahead of regulatory deadlines, while automated laser die-cutting compresses make-ready labor costs.
For Market Incumbents: To counter adhesive formulation chemist scarcity and retiring polymer science expertise, Avery Dennison Corporation and 3M Company should deepen captive R&D pipelines in UV-curable acrylic systems and establish apprenticeship pipelines with German technical universities. Backward integration into polyester substrate production would defend margin position against petrochemical input volatility. For New Entrants and Emerging Players: Direct-to-converter digital platforms offer the lowest-friction entry path for narrow-web specialists targeting India's CDSCO-mandated pharmaceutical export labeling gap. Unbundled procurement trends in Mumbai logistics hubs create white-space for sterilization-resistant label specialists. Target cryogenic-grade vinyl substrates for biologics distribution networks where domestic converting capacity lags demand. For Investors and Strategic Acquirers: Materials science conglomerates are the most active acquirers in this space, seeking narrow-web converters with established automotive OEM qualifications. The five-to-ten year viability window favors targets with EU Green Deal-compliant substrate portfolios and laser die-cutting automation deployed. Watch for fluorine-free release coating commercial availability milestones as inflection indicators for qualification-driven premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Release Coating Development | REACH Annex XVII compliance unlocks automotive OEM supply contracts in Stuttgart and Wolfsburg. |
| Laser Die-Cutting Capacity Expansion | Same-day turnaround capability captures aerospace MRO batch-size-one orders in Toulouse. |
| Cryogenic-Grade Adhesive Qualification | FDA UDI validation for gamma sterilization survival opens Massachusetts medical device supply. |
| Backward Integration into Polyester Substrates | Captive resin supply hedges against crude oil-linked petrochemical price volatility. |
| Direct Converter-Logistics Partnerships | Unbundled procurement relationships with Rotterdam 3PLs bypass distributor margin extraction. |
Methodological Framework
Multiple input streams — converter production data, adhesive formulation patent filings, and automotive OEM qualification records — were reconciled against primary interviews with narrow-web converting plant managers, pharmaceutical quality assurance directors, and logistics procurement leads. Secondary validation drew from ECHA REACH substance restriction updates, EPA adhesive VOC regulatory filings, and customs trade data for polyester resin flows. Bottom-up capacity estimates and top-down demand projections were triangulated to anchor market sizing.
Historical shipment patterns were cross-referenced against expert panel inputs from polymer scientists and label application engineers to construct the analytical framework across the analysis window. Segmentation dimensions modeled include material type, adhesive chemistry, application severity tier, and end-use regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating EU Green Deal implementation pacing and FDA UDI compliance timeline compression.
The model assumes a particular technology adoption path; alternative pathways for UV-curable adhesive systems would alter the outlook if fluorine-free release coatings achieve cost parity ahead of schedule. Forecasts reflect documented assumptions regarding REACH Annex XVII enforcement intensity and pharmaceutical cold-chain expansion rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Metallic Labels Market
Labels
Global Pressure Labels Market
Labels
Freezer Label Market
Labels
Global Cryogenic Label Market
Labels
Inspection and Inventory Labels Market
Labels
Oxygen Indicator Labels Market
Labels
United States Print Label Market
Labels
Multi-Part Labels Market
Labels
Integrated Labeling System Market
Labels
Self-Adhesive Labels Market
Labels
Inventory Tags Market
Labels
HAZMAT Labels Market
Labels
Heat Shrink Sleeve Market
Labels
Thermal Labels Market
Labels
North America Self-Adhesive Labels Market
Labels
Global Laminated Labels Market