
 Hot Melt Glue Labeler Market | 2026-2036
Hot Melt Glue Labeler Market Size, Share, and Industry Trends Forecast 2026-2036
Hot Melt Glue Labeler Market Foresight
Contract packagers is collapsing as a buyer archetype while direct-to-consumer brands and pharmaceutical serialization programs capture larger equipment budgets. Krones anchors high-throughput rotary labeling systems for European beverage giants. H.B. Fuller Company leverages adhesive chemistry expertise to tighten integration between glue formulation and applicator mechanics. Henkel AG & Co. KGaA competes through specialized hot melt adhesive portfolios engineered for PET and glass substrate compatibility.
A hot melt glue labeler applies thermoplastic adhesive coatings to labels at temperatures between 130°C and 200°C, then bonds them to containers through controlled pressure and cooling cycles; the equipment serves industries requiring durable, moisture-resistant label attachment at line speeds exceeding 60,000 units per hour. Automatic labelers dominate capital expenditure as food and beverage producers replace legacy equipment with servo-driven systems that cut changeover times. Hot melt technology leads the technology segment due to lower per-label adhesive costs versus pressure-sensitive alternatives, though laser-guided alignment modules are gaining traction in cosmetics applications demanding precise placement on irregular geometries.
FDA cGMP guidelines and EU MDR traceability requirements shape equipment specifications by mandating permanent label adhesion through sterilization cycles and supply chain visibility. ISO 9001 and CE marking frameworks govern manufacturing quality and electrical safety for machinery sold across North America and Europe. Stakeholders must monitor how evolving EPR packaging laws in multiple jurisdictions alter substrate choices and adhesive recyclability requirements.
Market Dynamics
Beverage bottlers are consolidating procurement around servo-driven automatic systems that slash changeover windows, while FDA cGMP and EU MDR traceability mandates harden adhesion permanence requirements through sterilization cycles.
Growth Catalysts
- EU MDR Traceability Mandates:Pharmaceutical serialization programs in Germany and France are forcing permanent label adhesion through autoclave cycles, expanding equipment replacement cycles.
- High-Speed Line Retrofits:PET bottling facilities across Spain and Italy are retiring pneumatic legacy systems for electric servo architectures that sustain 60,000 units per hour.
- Hot Melt Chemistry Advances:Adhesive formulators have engineered PET-compatible thermoplastics that cut per-label costs below pressure-sensitive alternatives by eliminating liner waste.
Market Restraints
- Energy Input Volatility:Natural gas price swings in Germany directly compress operating margins for melt tank heating systems running at 130°C to 200°C.
- Component Supply Concentration:Precision servo motors and laser alignment modules depend on concentrated Asian electronics supply chains vulnerable to shipping disruptions.
- Pressure-Sensitive Substitution:Cosmetics brands with short-run SKUs favor liner-fed systems for rapid changeovers despite higher material costs.
Strategic Opportunities
- Polish Contract Packaging Hubs:Warsaw and Łódź logistics corridors are attracting beverage co-packers underserved by local hot melt service infrastructure.
- EPR Packaging Tailwinds:Extended producer responsibility laws in France and Italy are creating adhesive recyclability specifications that favor removable hot melt formulations.
- Vision-Guided Robotics Convergence:Integration of machine vision with glue pattern control is opening precision placement applications for irregular glass geometries in premium spirits.
Industry Challenges
- Servo-Electric Skill Gaps:Maintenance technicians trained on pneumatic legacy systems lack competency in closed-loop motion control diagnostics.
- CE Marking Timeline Compression:Machinery builders face extended conformity assessment periods for integrated laser safety systems under updated EN ISO 11553 standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hot Melt Glue Labeler Market |
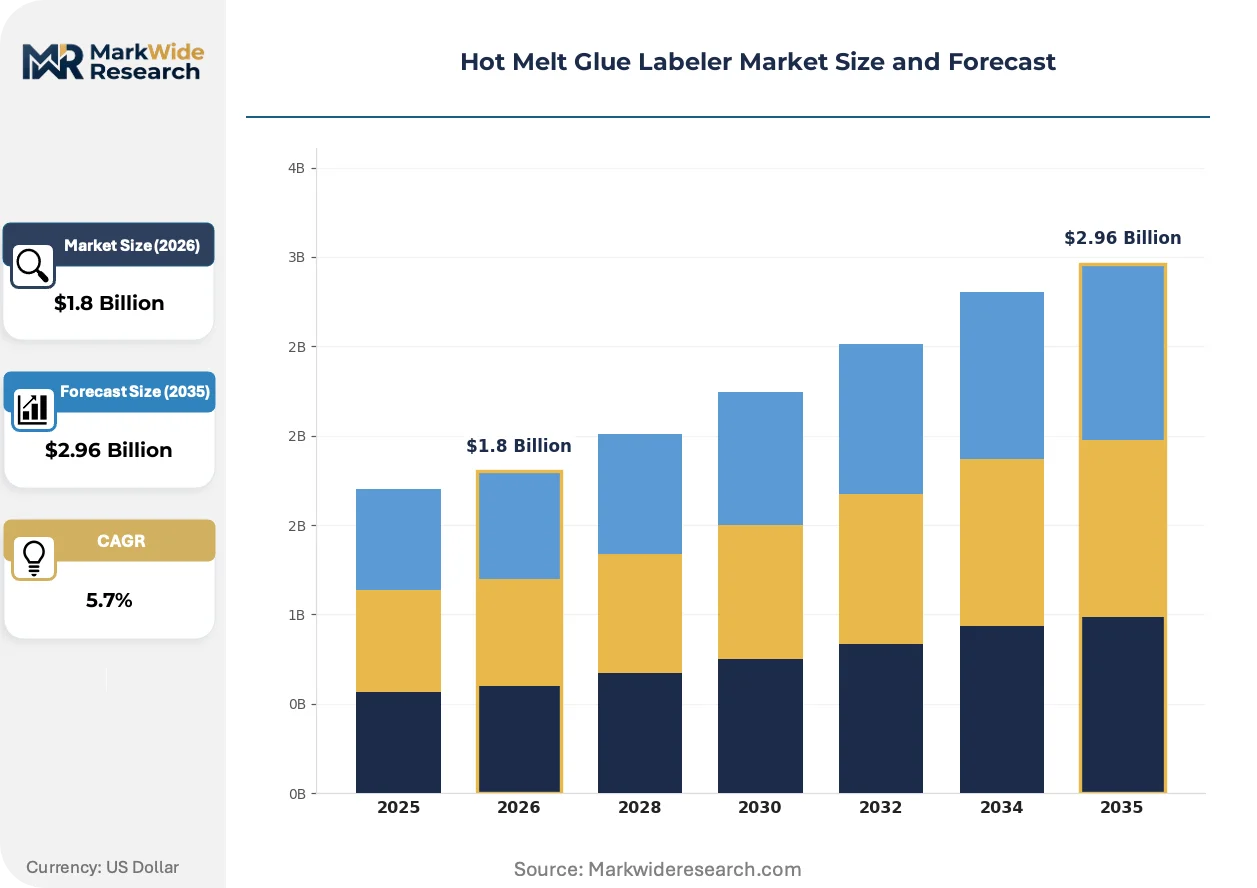
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Labelers, Automatic Labelers, Semi-Automatic Labelers, Portable Labelers End User: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Technology: Hot Melt Technology, Pressure Sensitive Technology, RF Technology, Laser Technology Distribution Channel: Online, Direct Sales, Distributors, Retail |
| Companies Covered | Multi-Tech Systems, Astro Packaging, Accutek Packaging Companies, H.B. Fuller Company, Henkel AG & Co. KGaA, Krones, Sidel Group, 3M Company, Sacmi Packaging & Chocolate, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hot Melt Glue Labeler Market Shifts & Advancements
Servo-electric architectures are displacing pneumatic actuation across European bottling lines, while regulatory adhesion mandates and procurement consolidation reshape equipment specifications and vendor relationships.
Laser-guided alignment modules are decomposing the traditional mechanical registration stack in rotary labelers. Premium cosmetics manufacturers in France and Switzerland are adopting these systems for 0.1 millimeter placement tolerance on tapered perfume bottles. The technology is decomposing legacy cam-driven mechanics into software-configurable motion profiles that compress format changeover from hours to minutes.
EU MDR Article 16 traceability requirements are mandating permanent label legibility through distribution and use cycles. Pharmaceutical contract packagers in Germany and Belgium must now validate adhesion through accelerated aging protocols before batch release. This regulatory pressure is compressing equipment qualification timelines and favoring suppliers with integrated validation documentation packages.
Direct-to-consumer beverage brands are consolidating procurement away from fragmented contract packaging networks. These buyers now specify equipment with remote diagnostics and predictive maintenance modules to minimize downtime across distributed production footprints. The shift is most visible in Nordic markets where craft distilleries operate single-shift bottling lines requiring maximum equipment availability.
Hot Melt Glue Labeler Market Segmentation
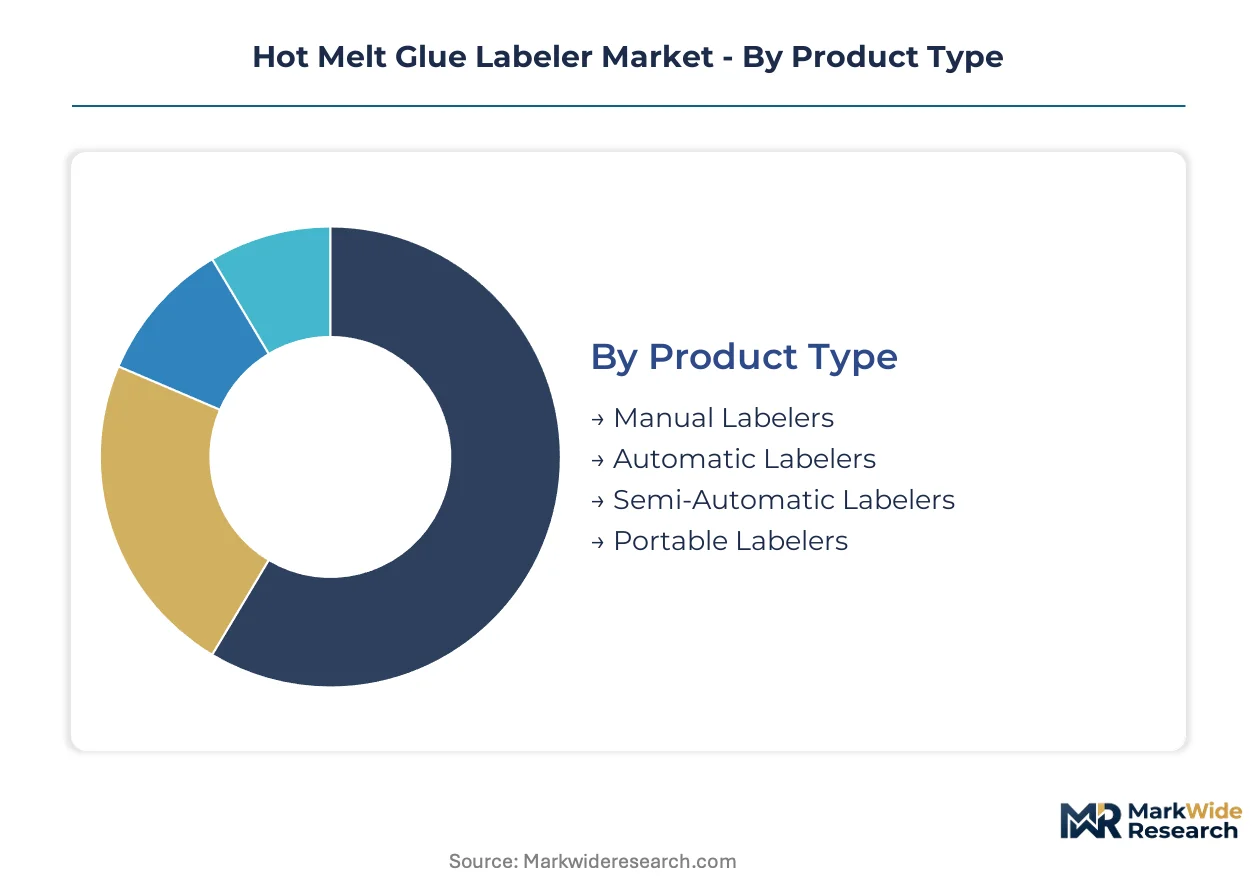
Hot melt glue labeler procurement patterns diverge sharply across automation levels and end-use compliance requirements. Equipment specifications must reconcile line speed demands with substrate compatibility and regulatory adhesion mandates.
Product Type:
Automatic labelers face the strongest substitution pressure from pressure-sensitive alternatives in short-run cosmetics applications, while manual systems confront ergonomic automation mandates.
- Manual Labelers:Hand-fed systems apply adhesive strips through lever-actuated pressure mechanisms for batch sizes below 500 units. Craft distilleries in Denmark and small-batch cosmetics formulators in Provence retain these units for seasonal SKU flexibility.
- Automatic Labelers:Servo-driven rotary architectures sustain 60,000 units per hour through continuous motion vacuum transfer drums. Major beverage bottlers in Germany and Spain are consolidating procurement around these systems to compress changeover windows from four hours to under thirty minutes.
- Semi-Automatic Labelers:Operator-fed systems with automatic adhesive application serve mid-volume contract packagers in Poland balancing flexibility with throughput.
- Portable Labelers:Battery-powered handheld units enable field labeling for agricultural cooperatives and mobile bottling operations.
Automatic labelers anchor the volume base while portable labelers gain share at the steepest rate among decentralized production networks.
End User:
Cost tier stratification separates pharmaceutical validation requirements from beverage throughput economics.
- Food & Beverage:PET bottling lines demand melt temperatures between 130°C and 200°C for moisture-resistant adhesion through cold chain distribution. EU MDR traceability spillover is now requiring lot code permanence through pasteurization cycles.
- Pharmaceuticals:Autoclave-compatible thermoplastic formulations must maintain legibility through sterilization protocols. Serialization programs in Germany and Belgium are mandating integrated vision verification systems.
- Cosmetics:Tapered glass geometries and premium positioning drive laser-guided alignment module adoption in French and Swiss facilities.
- Electronics:ESD-safe adhesive application for component labeling remains a niche specification.
Food and beverage commands the installed base while pharmaceuticals expand at the steepest trajectory on regulatory replacement cycles.
Technology:
Application-specific performance requirements fragment adoption across adhesive chemistry and registration mechanisms.
- Hot Melt Technology:Thermoplastic adhesives eliminate liner waste and cut per-label material costs below pressure-sensitive alternatives. Beverage giants in Spain and Italy are retrofitting legacy pneumatic systems for electric servo architectures running this chemistry.
- Pressure Sensitive Technology:Pre-coated labels with release liners enable rapid changeovers for short-run cosmetics SKUs despite higher material costs.
- RF Technology:Radio-frequency activated adhesives serve specialized security labeling applications.
- Laser Technology:Non-contact marking systems bypass adhesive entirely for certain traceability codes.
Hot melt technology dominates unit economics while laser systems expand most quickly in premium spirits traceability applications.
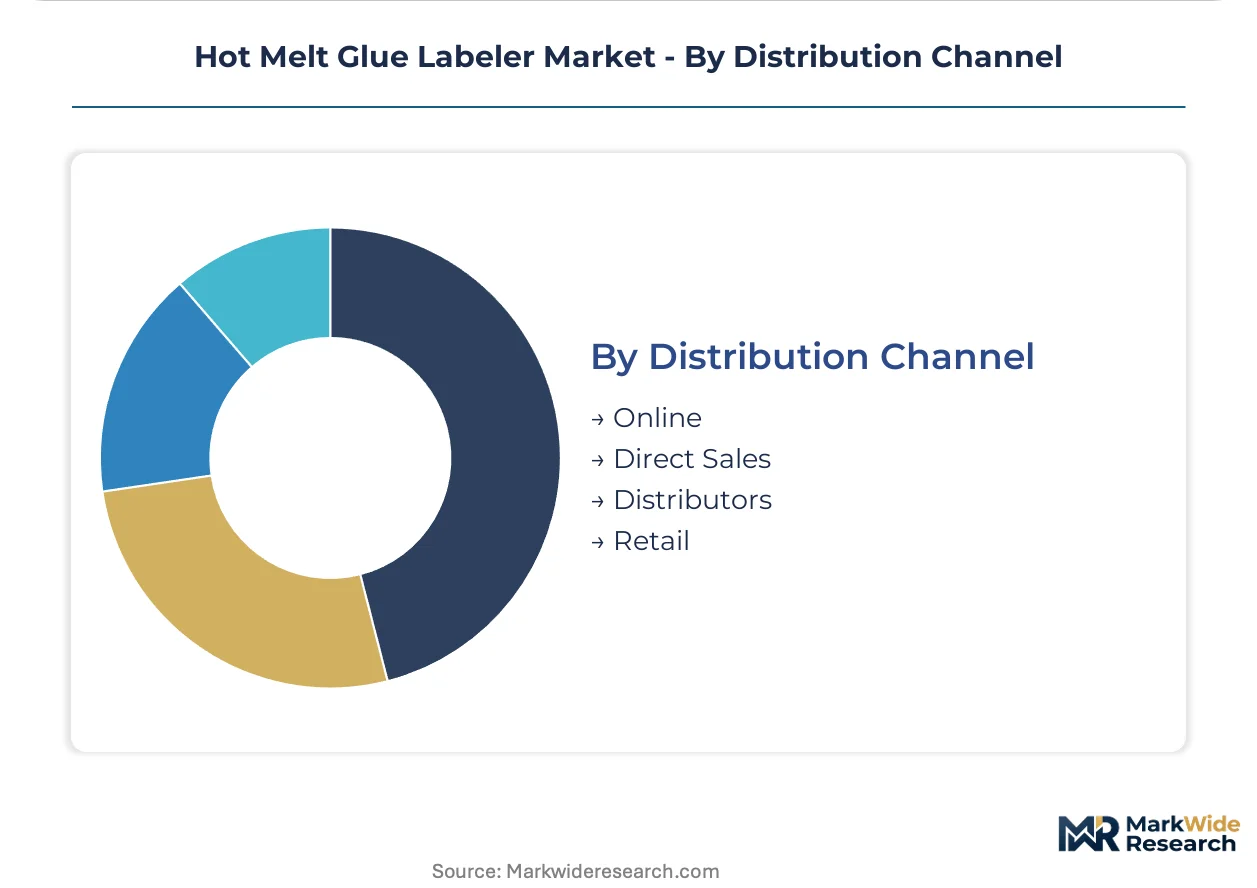
Distribution Channel:
Customer type fragmentation between multinational OEMs and regional integrators reshapes channel economics.
- Online:Digital procurement platforms serve spare parts and consumable adhesive replenishment for established installed bases.
- Direct Sales:Krones and Sidel Group maintain captive sales engineering teams for turnkey line integration with European beverage producers.
- Distributors:Regional machinery dealers provide local service infrastructure for mid-cap producers in Poland and Czechia.
- Retail:Limited to portable labeler accessories and adhesive cartridge replenishment.
Direct sales captures the capital equipment volume while online channels climb fastest for aftermarket recurring revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German machinery exporters dominate trade flows into French and Italian beverage bottling corridors, while Polish contract packaging hubs absorb spillover demand from Western European producers seeking cost-advantaged capacity.
Germany
Pharmaceutical serialization programs and autoclave-compatible adhesion standards drive equipment replacement cycles. EU MDR traceability mandates from EMA compel permanent label legibility through sterilization protocols. The Krones and Sidel Group machinery clusters in Bavaria and North Rhine-Westphalia anchor export-oriented production serving beverage giants across the continent.
France
Premium cosmetics manufacturers demand laser-guided alignment modules for 0.1 millimeter placement tolerance on tapered glass geometries. Extended producer responsibility laws from ANSM and environmental regulators create adhesive recyclability specifications favoring removable hot melt formulations. The Île-de-France and Provence-Alpes-Côte d'Azur corridors concentrate demand from luxury spirits and perfume bottlers.
Italy
PET bottling facilities are retiring pneumatic legacy systems for electric servo architectures sustaining 60,000 units per hour. CE marking frameworks under EN ISO 11553 govern integrated laser safety systems for machinery qualification. The Emilia-Romagna packaging machinery belt around Bologna and Modena hosts rotary labeler integration specialists serving Mediterranean beverage exporters.
Poland
Warsaw and Łódź logistics corridors attract beverage co-packers underserved by local hot melt service infrastructure. National conformity assessment procedures align with EU machinery directives for cross-border equipment certification. Mid-cap producers in Silesia and Greater Poland balance flexibility with throughput through semi-automatic operator-fed systems.
Spain
High-speed line retrofits accelerate as facilities replace aging equipment with servo-driven systems cutting changeover windows. FDA cGMP guideline spillover from pharmaceutical exports tightens adhesion permanence requirements through pasteurization cycles. The Catalonia and Madrid bottling clusters serve both domestic consumption and export markets into Latin America.
Hot Melt Glue Labeler Market Competitive Landscape
Player mix skews toward diversified adhesive-chemistry conglomerates and specialized packaging machinery builders. Consolidation pressure concentrates around turnkey line integration capabilities and validation documentation packages. Two strategic archetypes dominate: machinery OEMs with captive sales engineering teams and adhesive formulators tightening integration between glue chemistry and applicator mechanics. Competitive moves center on vertical integration into adhesive supply and geographic expansion into Polish contract packaging corridors.
Among German-based machinery builders, Krones and Sidel Group anchor the high-throughput rotary labeling segment. H.B. Fuller Company represents the adhesive-chemistry archetype, leveraging thermoplastic formulation expertise to tighten equipment-adhesive integration. These three entities exemplify the market's bifurcation between scale-driven machinery platforms and chemistry-specialized component suppliers.
| Leading Market Players |
|---|
| Multi-Tech Systems |
| Astro Packaging |
| Accutek Packaging Companies |
| H.B. Fuller Company |
| Henkel AG & Co. KGaA |
| Krones |
| Sidel Group |
| 3M Company |
| Sacmi Packaging & Chocolate |
| Others |
Supply & Pricing Matrix
Sixteen-week lead times for precision servo motors from Asian electronics hubs concentrate pricing power with machinery builders holding buffer inventory in Germany and Italy. This supply concentration shapes equipment pricing tiers while natural gas volatility in European melt tank operations feeds back into operating cost structures.
Pricing Analysis
Servo-electric architectures command 40-60% premiums over pneumatic legacy systems, while laser-guided alignment modules stratify into three distinct tiers: premium vision-integrated systems for cosmetics precision, standard rotary configurations for beverage throughput, and economy semi-automatic units for Polish contract packagers. Price differentiation hinges on CE marking tier and after-sales service bundling. Cost compression in the economy tier intensifies as Chinese component suppliers expand European distribution. Beverage giants demonstrate lowest price sensitivity, while Polish mid-cap producers negotiate aggressively on spare parts contracts.
Supply Chain Analysis
Shenzhen-Singapore shipping lanes for laser alignment modules and precision servo motors create chokepoint exposure for European machinery builders. Component sourcing draws from China, Japan, and South Korea for electronics, with adhesive resin supply anchored in Germany and Belgium. Single-source vulnerability concentrates in machine vision sensors. Distribution runs through direct sales engineering teams for turnkey lines, regional distributors for mid-cap service, and digital platforms for consumables replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hot melt glue labeler penetration sits at early-cycle expansion as EU MDR traceability mandates force pharmaceutical serialization investments across German and Belgian facilities.
For Market Incumbents: Compound installed base advantages through captive adhesive supply agreements and predictive maintenance module subscriptions. Pressure-sensitive substitution in cosmetics short-runs threatens margin pools. Priority lever: backward integration into thermoplastic formulation to tighten equipment-chemistry integration. For New Entrants and Emerging Players: Anchor in Polish contract packaging corridors where local hot melt service infrastructure remains undersupplied. Most penetrable segment: semi-automatic operator-fed systems for Warsaw and Łódź logistics hubs. Go-to-market angle: rapid-response service contracts with 24-hour technician dispatch. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because EU MDR and FDA cGMP mandates create durable replacement cycles through sterilization-grade adhesion requirements. Target acquisition archetype: adhesive formulators with equipment integration capabilities. Signal to watch: EPR packaging law evolution in France and Italy altering adhesive recyclability specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Formulation | H.B. Fuller and Henkel already control thermoplastic chemistry, tightening applicator-glue integration. |
| Predictive Maintenance Module Launch | Remote diagnostics capabilities address Nordic craft distillery demands for maximum single-shift equipment availability. |
| CE Marking Acceleration for Laser Systems | EN ISO 11553 compliance timelines compress competitive qualification windows for integrated safety architectures. |
| Polish Service Infrastructure Expansion | Warsaw and Łódź corridors lack local hot melt technician networks, creating first-mover service advantages. |
| Removable Hot Melt Formulation Development | EPR laws in France and Italy specify adhesive recyclability, favoring formulations that release cleanly from PET substrates. |
Research Methodology
Initial hypotheses were tested against primary input from packaging machinery procurement directors, adhesive formulation R&D leads, beverage bottling plant engineers, and pharmaceutical contract packaging quality managers, then refined through secondary validation against EU MDR guidance documents, FDA cGMP guidelines, CE marking technical files, and machinery trade flow data from German and Italian export statistics. Bottom-up equipment shipment analysis and top-down adhesive consumption estimates were triangulated to anchor market sizing.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects. Segmentation dimensions modeled include automation level, end-use compliance tier, adhesive chemistry type, and regional machinery cluster. CAGRs were derived from equipment replacement cycle analysis and regulatory mandate timing. Forecast inputs incorporate servo-electric adoption curves and natural gas price sensitivity for melt tank operations.
Decision-makers should treat outputs as directional under assumptions of sustained EU MDR enforcement and stable Asian electronics supply chains; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as EPR packaging law implementation timelines and laser safety standard updates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Time Temperature Indicator Labels Market
Labels
Direct Thermal Labels Market
Labels
APAC on-Demand Color Labels Market
Labels
Global Thermal Transfer Label Market
Labels
Europe Self Adhesives Label Market
Labels
Wash Off Labels Market
Labels
Label Applicator Market
Labels
Barcode Label Market
Labels
India Print Label Market
Labels
Indicative Seals Market
Labels
Cut and Stack Labels Market
Labels
Safety Labels Market
Labels
Global Industrial Labels Market
Labels
Global Cryogenic Label Market
Labels
Non-Adhesive Tags Market
Labels
Screen Print Label Market