
 Global Thermal Transfer Label Market | 2026-2036
Global Thermal Transfer Label Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thermal Transfer Label Market Foresight
Aftermarket label engineering services are reshaping how value migrates from commodity substrate sales toward specification-driven consulting. CCL Industries leverages backward integration into resin-coated film manufacturing to capture margin upstream. Avery Dennison anchors its position through direct thermal and thermal transfer technology leadership across pharmaceutical serialization programs. Zebra Technologies dominates printer-ribbon-label bundling strategies that lock in enterprise warehousing accounts.
Thermal transfer labels rely on a wax, resin, or wax-resin ink ribbon melted onto paper, film, or synthetic substrates via a heated printhead, producing durable barcodes and variable-data markings resistant to heat, chemicals, and abrasion for industrial tracking. Film labels sustain the fastest structural expansion as pharmaceutical cold-chain and automotive under-hood applications demand polyester and polyimide durability over paper alternatives. Direct thermal technology competes aggressively in short-life logistics applications where ribbon cost elimination outweighs image longevity requirements.
The US FDA enforces unit-level traceability through DSCSA compliance deadlines that mandate scannable thermal transfer labels on prescription drug packaging. The EU EMA implements Falsified Medicines Directive serialization rules that require tamper-evident labels with unique identifiers across European distribution channels. REACH and RoHS frameworks from the ECHA restrict substrate chemistries, pushing converters toward halogen-free adhesive formulations. Stakeholders must monitor evolving barcode symbology standards and regional chemical compliance to avoid supply disqualification.
Market Dynamics
Pharmaceutical serialization mandates under the US DSCSA and EU FMD are compressing procurement cycles while forcing converters to engineer tamper-evident, scannable label architectures at scale. This regulatory compression is redistributing margin toward specification-driven consultative sales and away from commodity substrate transactions.
Growth Catalysts
- EU Falsified Medicines Directive:Serialization rules across European distribution channels mandate tamper-evident thermal transfer labels with unique identifiers, accelerating converter investments in track-and-trace infrastructure.
- Electronics manufacturing clusters:Shenzhen and Dongguan drive premium resin-coated synthetic label consumption for component traceability in high-density PCB assembly operations.
- Cold-chain logistics expansion:Polyester and polyimide film labels sustain barcode integrity through pharmaceutical distribution at sub-zero temperatures where paper substrates fail.
Market Restraints
- Petrochemical input volatility:Wax and resin ribbon formulations depend on paraffin and hydrocarbon feedstocks whose price swings compress converter margins unpredictably.
- East Asian film concentration:Polyester substrate supply clusters among Korean and Chinese petrochemical producers, creating geographic single-source vulnerability for European and North American converters.
- Direct thermal substitution:Short-life logistics applications increasingly eliminate ribbon costs entirely, capping thermal transfer penetration in e-commerce parcel tracking.
Strategic Opportunities
- Indian pharmaceutical export compliance:CDSCO alignment with EU FMD and US DSCSA standards creates demand for serialization-capable label engineering among Mumbai and Hyderabad drug manufacturers.
- Automotive under-hood durability:Polyimide thermal transfer labels withstand engine-bay thermal cycling and chemical exposure for component lifetime traceability.
- RFID-thermal convergence:Hybrid labels combining printed barcodes with embedded RFID inlays enable dual-mode tracking across pharmaceutical and luxury goods authentication.
Industry Challenges
- Serialization data architecture:Converters must integrate variable-data printing with enterprise ERP and national verification systems, requiring software engineering capabilities outside traditional substrate expertise.
- REACH compliance timelines:ECHA restrictions on halogenated adhesive chemistries force rapid reformulation cycles that strain R&D bandwidth at mid-scale converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thermal Transfer Label Market |
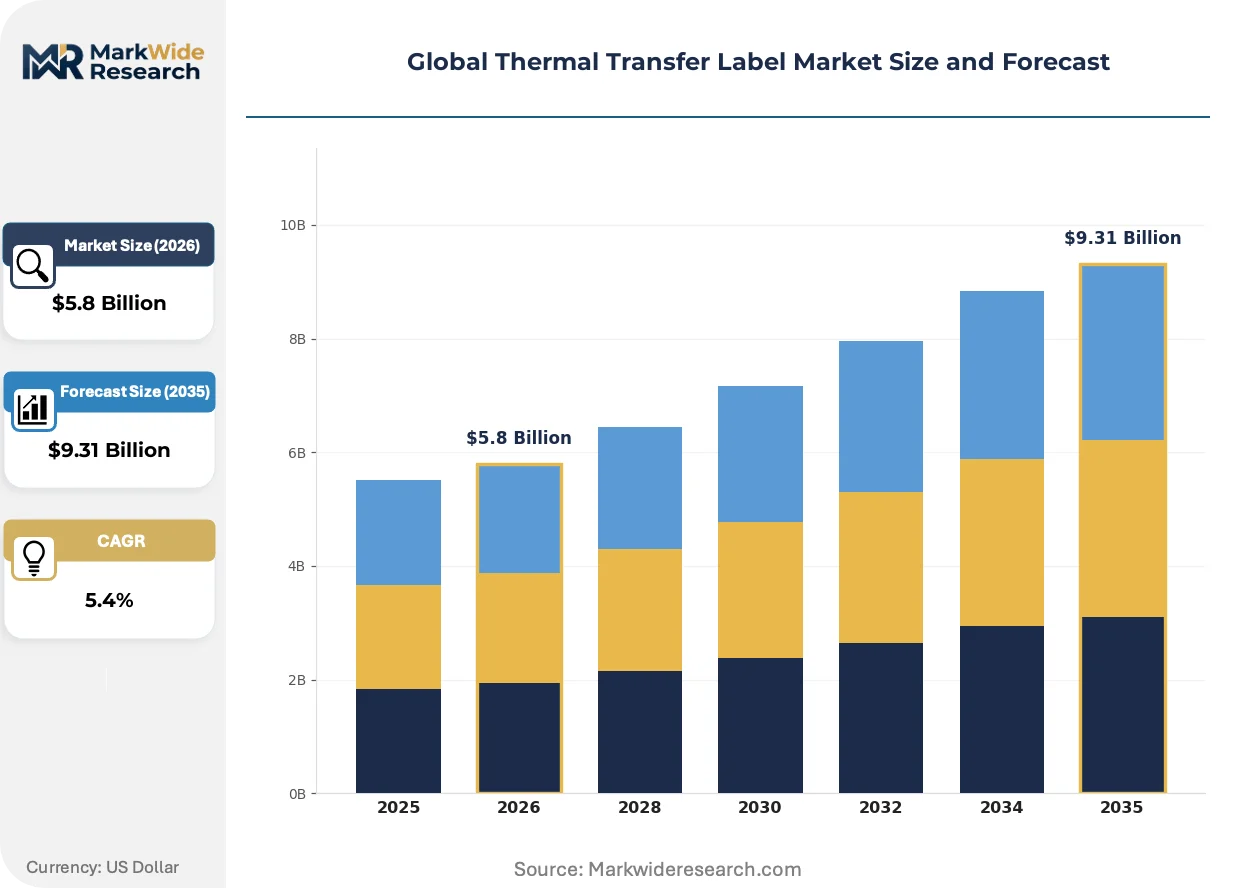
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $9.31 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paper Labels, Film Labels, Synthetic Labels, Resin Labels, Fabric Labels Technology: Direct Thermal, Thermal Transfer, Inkjet, Laser, Dot Matrix Application: Food & Beverage, Pharmaceuticals, Automotive Suppliers, Electronics Manufacturing, Logistics Providers End User: Retail Chains, Warehousing Facilities, Chemical Processors, Printing Services, Consumer Goods Producers |
| Companies Covered | CCL Industries Inc., Constantia Flexibles Group GmbH, Honeywell International Inc., UPM Raflatac Oy, LINTEC Corporation, 3M Company, Zebra Technologies Corporation, Brady Corporation, Avery Dennison Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thermal Transfer Label Market Shifts & Advancements
Wax-resin ribbon formulations are hybridizing with synthetic substrates to bridge cost-performance gaps, while regulatory deadlines compress technology adoption cycles across pharmaceutical packaging. These forces are simultaneously fragmenting procurement patterns and consolidating specification authority among engineering-capable converters.
Near-edge thermal transfer printheads are hybridizing with inkjet deposition modules to enable single-pass variable-data printing at pharmaceutical packaging line speeds. Bayer and Novartis packaging operations in Germany and Switzerland are piloting these hybrid systems for combined serialization and branding applications. The technology is hybridizing ribbon and inkjet economics, forcing incumbent ribbon suppliers to defend position through bundled service contracts rather than consumables margin alone.
REACH Annex XVII restrictions on persistent organic pollutants in adhesive formulations are compelling European converters to validate halogen-free chemistries through ECHA-recognized laboratories. The regulation is accelerating substitution of solvent-based acrylics with UV-curable and hot-melt alternatives in medical device labeling. German automotive suppliers are responding fastest, integrating REACH-compliant label specifications into supplier scorecards ahead of 2027 enforcement milestones.
Enterprise pharmaceutical buyers are consolidating label procurement under central technical specifications that privilege DSCSA and FMD compliance over unit cost. This concentration is displacing fragmented purchasing across regional packaging sites, with Merck and Pfizer implementing global master service agreements with engineered-label specialists. The shift is most visible in North American and Western European operations where regulatory liability exposure concentrates decision authority at headquarters level.
Global Thermal Transfer Label Market Segmentation
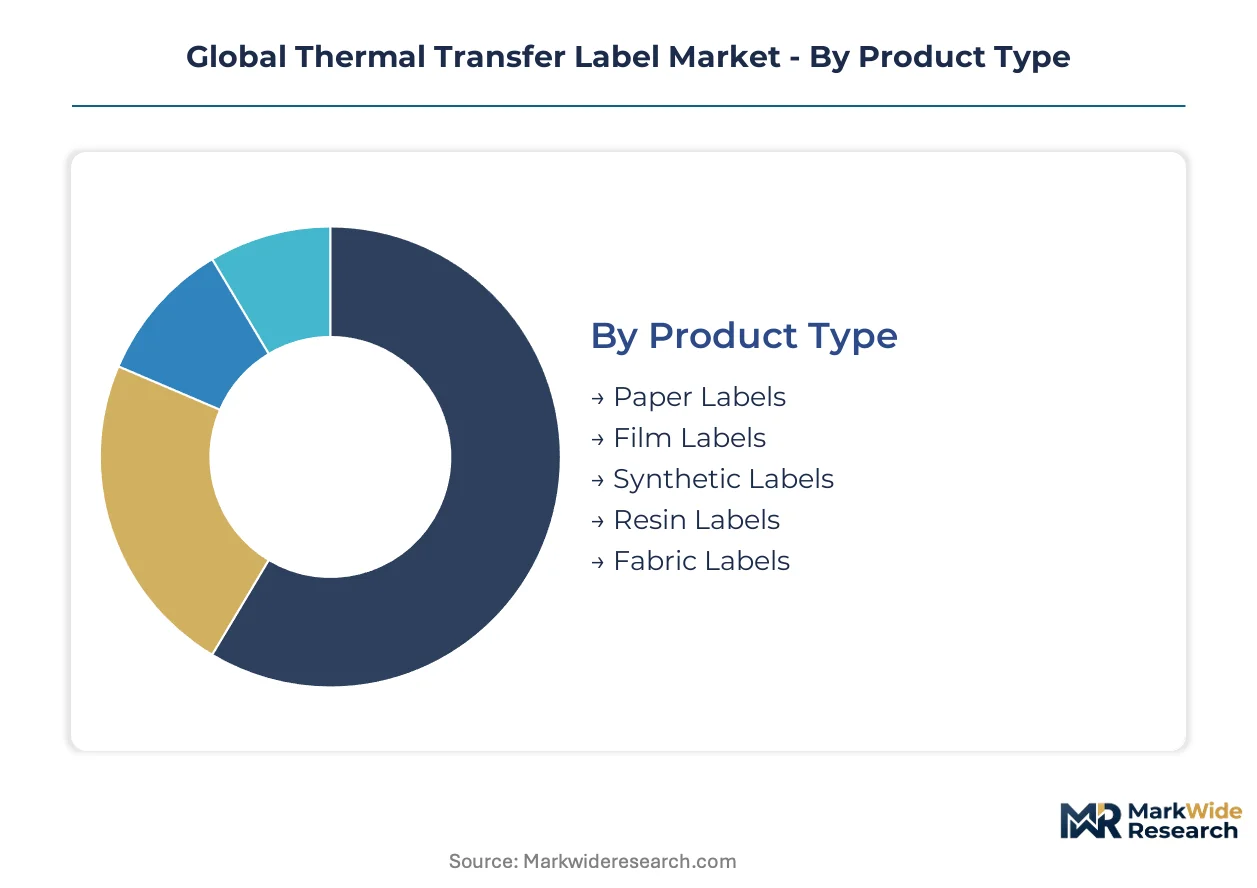
Thermal transfer label procurement patterns fragment sharply across substrate durability requirements and printing technology economics. Converter margins concentrate in specification-driven segments where regulatory compliance mandates override commodity pricing pressures.
Product Type:
Film and synthetic substrates command extended replacement cycles in harsh environments, while paper labels turn over fastest in short-life logistics applications. Resin-coated grades occupy the slowest procurement rhythm due to capital-intensive qualification protocols.
- Film Labels:Polyester and polyimide substrates withstand sub-zero pharmaceutical cold-chain distribution and automotive engine-bay thermal cycling. Bayer packaging operations in Germany specify these grades for DSCSA-compliant unit-level traceability where barcode integrity failures trigger regulatory penalties.
- Paper Labels:Uncoated and top-coated paper stocks dominate high-volume e-commerce parcel tracking where ribbon cost economics favor frequent replenishment over durability. Amazon fulfillment centers in the US and Germany consume these grades at the fastest replacement cadence in the installed base.
- Synthetic Labels:Polypropylene and polyethylene face stocks balance moisture resistance with cost efficiency for chemical drum labeling and outdoor asset tracking.
- Resin Labels:Fully resin-saturated substrates deliver maximum solvent and abrasion resistance for laboratory specimen tracking and industrial process control.
- Fabric Labels:Nylon and polyester textile stocks serve apparel care labeling and soft goods inventory management with sewn or heat-transfer attachment.
Film labels dominate installed base value in pharmaceutical and automotive specifications. Paper labels are where volume expansion concentrates in e-commerce logistics.
Technology:
Direct thermal eliminates ribbon procurement entirely, compressing total cost of ownership in applications under 12-month lifespan. Thermal transfer retains specification authority wherever image longevity exceeds two years.
- Thermal Transfer:Heated printheads melt wax, resin, or hybrid ink ribbons onto substrates, producing archival-grade barcodes resistant to heat, chemicals, and UV degradation. FDA DSCSA mandates in the US and EMA FMD requirements across Europe lock this technology into pharmaceutical serialization infrastructure.
- Direct Thermal:Chemically treated substrates darken under heated printheads without consumable ribbons, slashing operating costs in shipping label applications. DHL and FedEx ground operations in the US and Germany have standardized on this technology for 5-7 day parcel lifecycle tracking.
- Inkjet:Piezoelectric drop-on-demand systems enable full-color variable-data printing for premium product branding and marketing personalization.
- Laser:Toner-based imaging delivers crisp edge definition for small-format electronics component labeling and cleanroom applications.
- Dot Matrix:Impact printing persists in carbon-copy forms and harsh industrial environments where non-contact technologies fail.
Thermal transfer anchors regulatory-compliant pharmaceutical serialization. Direct thermal is gaining share fastest in cost-sensitive logistics.
Application:
Pharmaceutical serialization mandates impose the slowest, most rigid procurement cycles due to validation requirements. Food and beverage labeling turns over fastest as seasonal promotions drive frequent artwork changes.
- Pharmaceuticals:Unit-level traceability mandates under US DSCSA and EU FMD require tamper-evident thermal transfer labels with unique 2D Data Matrix codes. Novartis packaging lines in Switzerland and Pfizer operations in the US specify polyester film grades with 5-year image durability for cold-chain distribution.
- Electronics Manufacturing:High-density PCB assembly operations in Shenzhen and Dongguan, China, demand polyimide labels that survive reflow soldering temperatures exceeding 260°C for component lifetime traceability.
- Food & Beverage:Moisture-resistant synthetic labels withstand refrigeration and condensation in retail supply chains from farm to point-of-sale.
- Automotive Suppliers:Under-hood specifications from Bosch and Continental in Germany mandate thermal cycling resistance across -40°C to 150°C operating ranges.
- Logistics Providers:High-speed sortation systems at DHL hubs in Leipzig and Memphis require labels with reliable barcode readability at conveyor speeds exceeding 3 meters per second.
Pharmaceutical applications dominate specification value and compliance-driven margin. Electronics manufacturing is expanding most quickly as reshoring initiatives diversify supply chains beyond China.
End User:
Warehouse operators cycle through labels fastest due to shipment volume velocity. Chemical processors impose the slowest procurement rhythms as hazardous material certification requirements extend supplier qualification timelines.
- Warehousing Facilities:E-commerce fulfillment centers and third-party logistics providers consume billions of shipping labels annually. Amazon, Shopify, and JD.com distribution networks in the US, Canada, and China specify direct thermal grades for 24-hour turnaround requirements.
- Chemical Processors:Dow and BASF operations in the US and Germany require BS 5609-certified labels that survive 90-day marine immersion for hazardous material drum tracking. GHS pictogram regulations mandate precise color specification that thermal transfer technology delivers consistently.
- Retail Chains:Walmart and Carrefour shelf-edge labeling programs demand thermal transfer for price markdown durability and promotional flexibility.
- Printing Services:Commercial converters supply variable-data labels to brand owners lacking in-house thermal transfer printing capacity.
- Consumer Goods Producers:Unilever and Procter & Gamble specify premium resin ribbons for product authentication and anti-counterfeiting features in luxury personal care lines.
Chemical processors dominate specification complexity and supplier qualification barriers. Warehousing facilities are where unit volume expansion concentrates as e-commerce penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyester substrate manufacturing clusters among Korean and Chinese petrochemical producers, creating geographic concentration that European and North American converters must navigate through diversified sourcing strategies.
United States
FDA DSCSA compliance deadlines mandate unit-level traceability infrastructure across prescription drug packaging. Pharmaceutical serialization investments concentrate in New Jersey and Pennsylvania packaging corridors. Pfizer operations in Kalamazoo and Merck facilities in West Point specify thermal transfer systems for cold-chain distribution.
Germany
EMA serialization rules and REACH Annex XVII chemical restrictions reshape converter specifications simultaneously. Bayer packaging lines in Leverkusen and Novartis operations in Basel-adjacent Baden-Württemberg pilot hybrid thermal transfer-inkjet systems. German automotive suppliers from Bosch and Continental integrate REACH-compliant label specifications into supplier scorecards.
China
Electronics manufacturing in Shenzhen and Dongguan drives premium resin-coated synthetic label consumption for PCB component traceability. NMPA pharmaceutical serialization alignment with international standards accelerates track-and-trace infrastructure investments. E-commerce logistics expansion across Yangtze River Delta fulfillment networks sustains high-volume direct thermal substitution pressures.
India
CDSCO alignment with EU FMD and US DSCSA standards creates export compliance demand among Mumbai and Hyderabad pharmaceutical manufacturers. Domestic electronics assembly growth in Bengaluru and Chennai clusters supports synthetic label specification upgrades. Chemical drum labeling for hazardous material exports requires BS 5609-equivalent certification capabilities.
Japan
PMDA pharmaceutical traceability mandates and METI industrial standardization programs sustain premium resin ribbon specifications. Automotive component labeling from Toyota and Honda supplier networks demands polyimide durability for under-hood traceability. Precision electronics manufacturing in Nagoya and Osaka maintains strict substrate qualification protocols.
Global Thermal Transfer Label Market Competitive Landscape
Backward-integrated substrate specialists and printer-ribbon bundling strategists split the market between specification-driven margin capture and enterprise account lock-in. The competitive structure concentrates among three strategic archetypes: resin-coated film manufacturers controlling upstream chemistry, technology-agnostic converters engineering compliance architectures, and hardware-software bundlers securing warehousing infrastructure. Consolidation pressures intensify as pharmaceutical serialization mandates compress procurement cycles toward engineered-label specialists with integrated software capabilities.
Within the backward-integrated tier, CCL Industries exemplifies resin-coated film manufacturing control, while Avery Dennison anchors technology leadership across pharmaceutical serialization programs. Zebra Technologies occupies the hardware-software bundling position through printer-ribbon-label strategies that secure enterprise warehousing accounts. These three players represent distinct competitive vectors—upstream chemistry control, specification engineering authority, and infrastructure lock-in—rather than direct substitution rivalry.
| Leading Market Players |
|---|
| CCL Industries Inc. |
| Constantia Flexibles Group GmbH |
| Honeywell International Inc. |
| UPM Raflatac Oy |
| LINTEC Corporation |
| 3M Company |
| Zebra Technologies Corporation |
| Brady Corporation |
| Avery Dennison Corporation |
| Others |
Supply & Pricing Matrix
Shenzhen and Dongguan electronics manufacturing clusters anchor global resin-coated synthetic substrate capacity, with their scale dynamics translating directly into pricing leverage over European and North American converters who lack backward integration into film production. Converter margins compress when Korean petrochemical producers tighten polyester supply, forcing specification-driven buyers toward premium resin ribbon formulations that sustain barcode integrity through reflow soldering cycles.
Pricing Analysis
After-sales service contracts and extended technical support agreements drive lifetime value capture among pharmaceutical serialization specialists. Three-tier pricing structure across premium resin, standard wax-resin, and economy wax formulations separates DSCSA-compliant film grades from direct thermal paper substitutes. Cost compression in commodity paper labels intensifies as Amazon and JD.com fulfillment networks standardize on ribbonless direct thermal technology. E-commerce logistics providers exhibit the highest price sensitivity, while pharmaceutical packers prioritize compliance-grade specifications over unit cost.
Supply Chain Analysis
Extended payment terms from Korean and Chinese petrochemical producers to European converters have tightened to 45-60 days as feedstock volatility strains working capital. Polyester substrate manufacturing concentrates in South Korea, China, and Japan, drawing from paraffin and hydrocarbon resin feedstocks anchored in regional refinery complexes. Single-source vulnerability persists for polyimide films used in automotive under-hood applications, where Japanese suppliers dominate qualification protocols. Distribution runs through converter networks that laminate, die-cut, and engineer labels for end-use specifications across pharmaceutical, electronics, and automotive verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery phase as pharmaceutical serialization deadlines compress procurement cycles and force capital deployment into track-and-trace infrastructure.
For Market Incumbents: Pre-empt direct thermal substitution in logistics applications by bundling thermal transfer systems with predictive maintenance software that locks in enterprise warehousing accounts. Acquire resin-coated film manufacturing capabilities to capture margin upstream from commodity converters facing petrochemical input volatility. Defend against emerging Asian competitors by accelerating REACH-compliant adhesive formulations ahead of ECHA enforcement milestones. For New Entrants and Emerging Players: Mid-scale Indian pharmaceutical exporters in Mumbai and Hyderabad represent the most penetrable entry point, as CDSCO alignment with EU FMD and US DSCSA standards forces serialization infrastructure investments without incumbent converter relationships. Target hybrid RFID-thermal label engineering for luxury goods authentication, where dual-mode tracking commands specification premiums over commodity barcode alternatives. Partner with regional distributors who possess existing pharmaceutical packaging line relationships to bypass direct qualification barriers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because pharmaceutical serialization mandates embed thermal transfer technology into irreversible track-and-trace architectures across US and European distribution channels. Acquisition targets should prioritize converters with integrated variable-data printing software and ECHA-recognized laboratory validation capabilities. Watch for FDA DSCSA enforcement acceleration as the inflection signal that compresses procurement cycles toward engineered-label specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin-Coated Film Manufacturing | CCL Industries captures margin upstream from commodity substrate competitors through captive polyester supply. |
| Hybrid Thermal Transfer-Inkjet System Deployment | Bayer and Novartis packaging lines in Germany pilot combined serialization and branding applications. |
| REACH-Compliant Adhesive Reformulation | German automotive suppliers integrate ECHA-validated chemistries into supplier scorecards ahead of enforcement milestones. |
| Printer-Ribbon-Label Bundling Contracts | Zebra Technologies locks enterprise warehousing accounts through consumables-anchored service agreements. |
| RFID-Thermal Convergence Product Development | Hybrid labels enable dual-mode tracking across pharmaceutical cold-chain and luxury goods authentication verticals. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with label converters, pharmaceutical packaging engineers, automotive component traceability managers, and e-commerce logistics procurement directors. Secondary validation drew from FDA DSCSA guidance documents, EMA FMD implementation reports, ECHA REACH Annex XVII restrictions, and customs trade data on polyester substrate flows. Bottom-up segment sizing triangulated against top-down market aggregation across substrate type, printing technology, and end-use application dimensions.
Calibration against historical capacity utilization rates and regulatory deadline impacts anchored the analytical framework across the projection horizon. Segmentation modeling incorporated product type, technology platform, application vertical, end-user category, and regional regulatory cluster dimensions. CAGRs derived from trend extrapolation of pharmaceutical serialization investments, electronics manufacturing reshoring patterns, and cold-chain logistics expansion trajectories. Industry-specific inputs included converter qualification timeline data and REACH compliance cost benchmarks.
Practitioners should monitor FDA enforcement acceleration, ECHA chemical restriction expansions, and petrochemical feedstock volatility for early signals of forecast deviation. Forecasts reflect assumptions about regulatory deadline adherence and substitution elasticity between thermal transfer and direct thermal technologies. Macroeconomic contraction, regulatory delay, or breakthrough direct thermal durability improvements would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Global Laminated Labels Market
Labels
Tags Market
Labels
Europe Shrink and Stretch Sleeve Label Market
Labels
Pre-Gummed Labels Market
Labels
Foil Labels Market
Labels
Freshness Indicator Label Market
Labels
Shipping Label Market
Labels
Polyester Labels Market
Labels
Global Sensormatic Labels Market
Labels
Global Security Labels Market
Labels
HAZMAT Labels Market
Labels
Shrink Sleeve Label Applicator Market
Labels
Wet Glue Labels Market
Labels
Repositionable Labels Market
Labels
Global Label Adhesive Market
Labels
Warning Labels and Stickers Market