
 Global Security Labels Market | 2026-2036
Global Security Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Global Security Labels Market Foresight
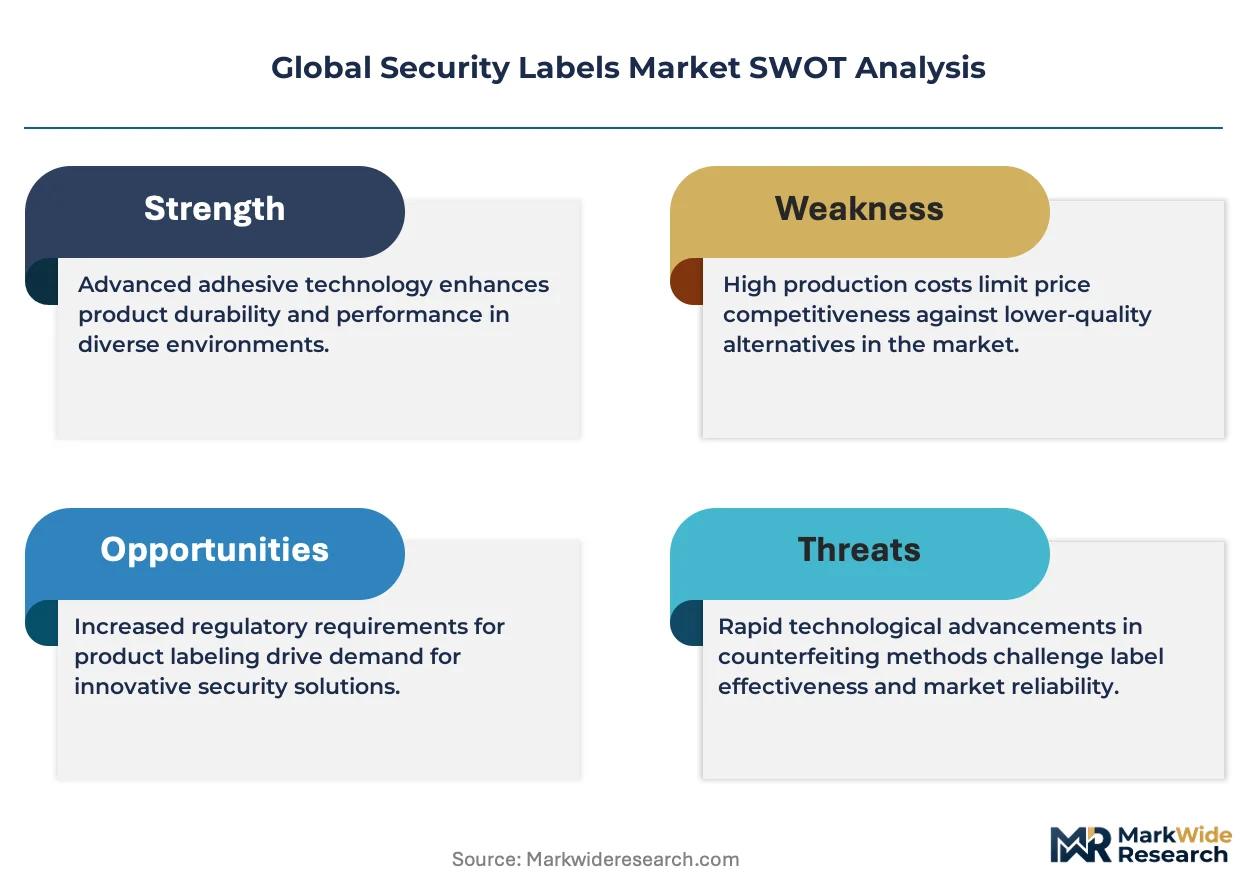
Subscription-based authentication software bundled with RFID label hardware is repositioning vendor-customer relationships toward recurring revenue models. Avery Dennison Corporation leverages its materials science portfolio to dominate high-performance tamper-evident substrates. 3M Company sustains technology leadership in adhesive formulations that withstand extreme environmental conditions. CCL Industries Inc. anchors its position through specialized printing capabilities across pharmaceutical and spirits end markets.
Security labels are multi-layer adhesive constructs incorporating overt, covert, and forensic authentication features, typically manufactured through holographic embossing, micro-optic integration, or RFID inlay lamination processes with read ranges from near-field to ultra-high frequency. These products authenticate product provenance, deter diversion, and enable supply chain visibility across high-value goods. RFID labels capture expanding share in pharmaceutical serialization programs where real-time traceability commands premium positioning. Holographic labels retain entrenched demand in currency and tax stamp applications despite gradual displacement by electronic alternatives. Tamper evident labels occupy stable volume pools in logistics and consumer goods where cost sensitivity limits technology upgrading.
FDA drug supply chain security requirements, EU Falsified Medicines Directive serialization mandates, and China's NMPA traceability regulations collectively compel pharmaceutical manufacturers to upgrade label infrastructure. REACH compliance and RoHS substance restrictions further constrain adhesive and substrate formulations available to European producers. Stakeholders must monitor regulatory divergence between jurisdictions as divergent authentication standards threaten interoperability and complicate multinational deployment strategies.
Market Dynamics
Pharmaceutical serialization mandates are compressing upgrade cycles across label infrastructure as manufacturers race to meet track-and-trace deadlines. The EU Falsified Medicines Directive, FDA Drug Supply Chain Security Act, and China's NMPA traceability regulations have created synchronized compliance pressure that prioritizes authentication spending over cost optimization.
Growth Catalysts
- EU Falsified Medicines Directive:Mandates unit-level serialization for prescription medicines, forcing wholesale replacement of legacy labeling systems across European pharmaceutical supply chains.
- RFID inlay lamination:Near-field and ultra-high frequency tags enable real-time inventory visibility, attracting adoption from logistics providers managing high-value electronics shipments.
- Germany:Concentration of pharmaceutical manufacturing and spirits packaging creates sustained demand for tamper-evident and holographic authentication substrates.
Market Restraints
- Silver price volatility:Conductive inks for RFID antennae expose converters to input cost swings that compress margin predictability on fixed-price contracts.
- Adhesive formulation constraints:REACH and RoHS substance restrictions limit available chemistries for European producers, raising reformulation costs and qualification timelines.
- Blockchain verification:Distributed ledger authentication threatens to displace physical security labels in luxury goods and art provenance tracking.
Strategic Opportunities
- India:CDSCO track-and-trace expansion for domestic pharmaceuticals creates underpenetrated demand for serialization-ready label converters with local production capability.
- Subscription authentication software:Recurring revenue models bundled with RFID hardware reposition vendor relationships beyond transactional substrate supply.
- Micro-optic integration:Convergence of holographic embossing with smartphone-readable micro-optics enables consumer-facing verification without dedicated reading equipment.
Industry Challenges
- Serialization data management:Pharmaceutical manufacturers face integration complexity with legacy ERP systems that lack native support for EPCIS event repositories.
- Forensic feature standardization:Absence of harmonized covert authentication protocols between jurisdictions complicates multinational deployment and law enforcement cooperation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Security Labels Market |
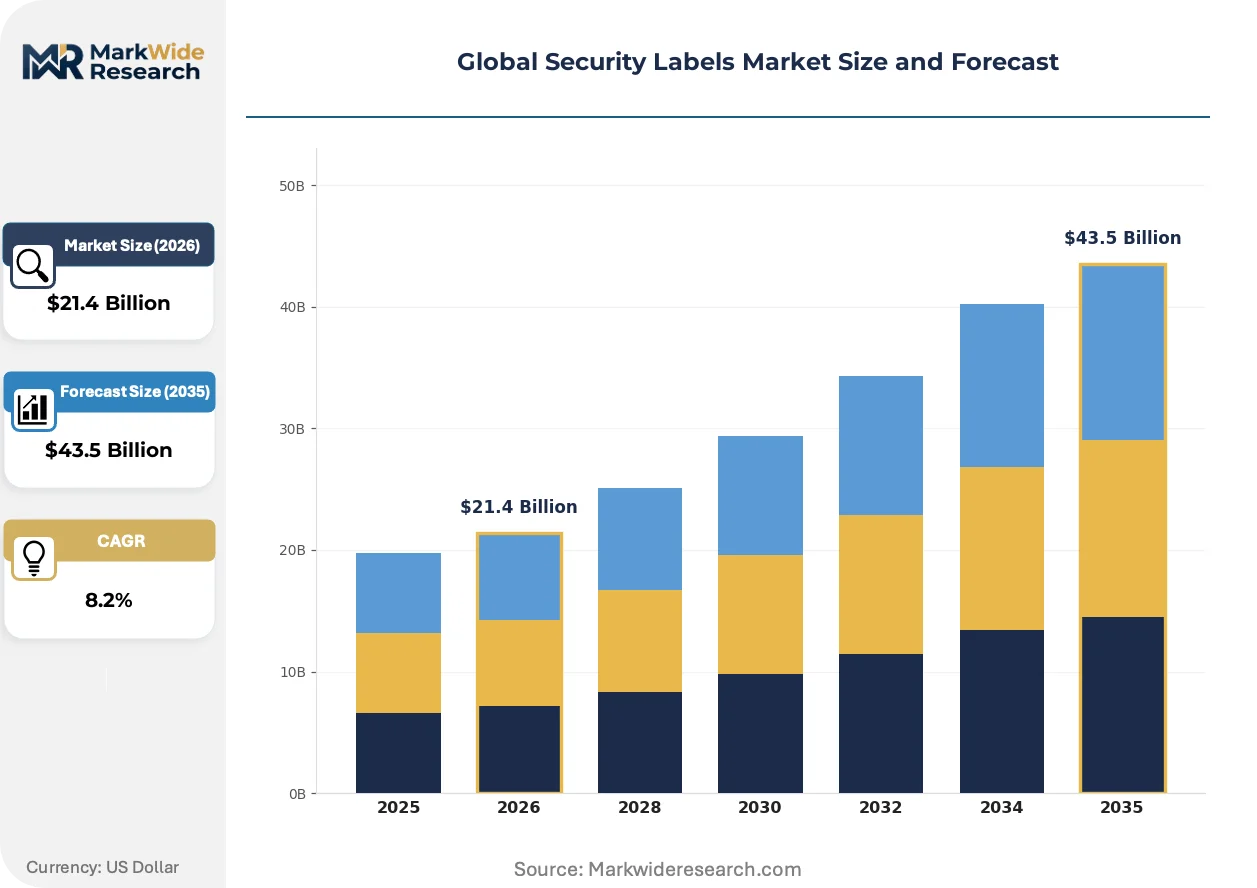
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $43.5 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Void Labels, Tamper Evident Labels, Holographic Labels, RFID Labels, Electronic Security Labels Technology: Inkjet Printing, Laser Marking, Thermal Transfer, Radio Frequency Identification, Digital Watermarking Application: Pharmaceutical Packaging, Luxury Goods Protection, Document Authentication, Electronics Protection, Currency Security End User: Consumer Goods Manufacturers, Government Agencies, Banking Institutions, Pharmaceuticals, Logistics Providers |
| Companies Covered | Avery Dennison Corporation, 3M Company, CCL Industries Inc., UPM, Zebra Technologies, Brady Corporation, Honeywell International Inc., tesa SE, Sato Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Security Labels Market Shifts & Advancements
Authentication technology is fragmenting across multiple verification paradigms as end-users demand flexibility beyond single-point security. Convergence of physical substrates with digital verification layers is redefining how supply chain visibility and consumer trust intersect.
Blockchain-enabled provenance tracking is decentralizing authentication authority away from proprietary vendor databases toward distributed verification networks. Pharmaceutical distributors and luxury goods houses are piloting these systems to enable multi-party audit trails without central data custodians. This architecture is compressing the value capture potential of traditional holographic and RFID providers who previously controlled verification infrastructure.
REACH substance restrictions are forcing adhesive reformulation across European security label production, eliminating legacy solvent-based chemistries. The regulation's industrial consequence is qualification bottlenecks as converters retest bond performance across temperature and humidity extremes. German pharmaceutical packaging specialists are responding fastest, leveraging proximity to materials science clusters to accelerate compliant substrate development.
Brand owners are unbundling authentication hardware from managed verification services, treating physical labels as commodities while paying premiums for cloud-based track-and-trace platforms. This pattern is most visible in United States pharmaceutical distribution, where wholesale buyers now procure RFID inlays through competitive tender while locking into multi-year software subscriptions for serialization data management.
Global Security Labels Market Segmentation
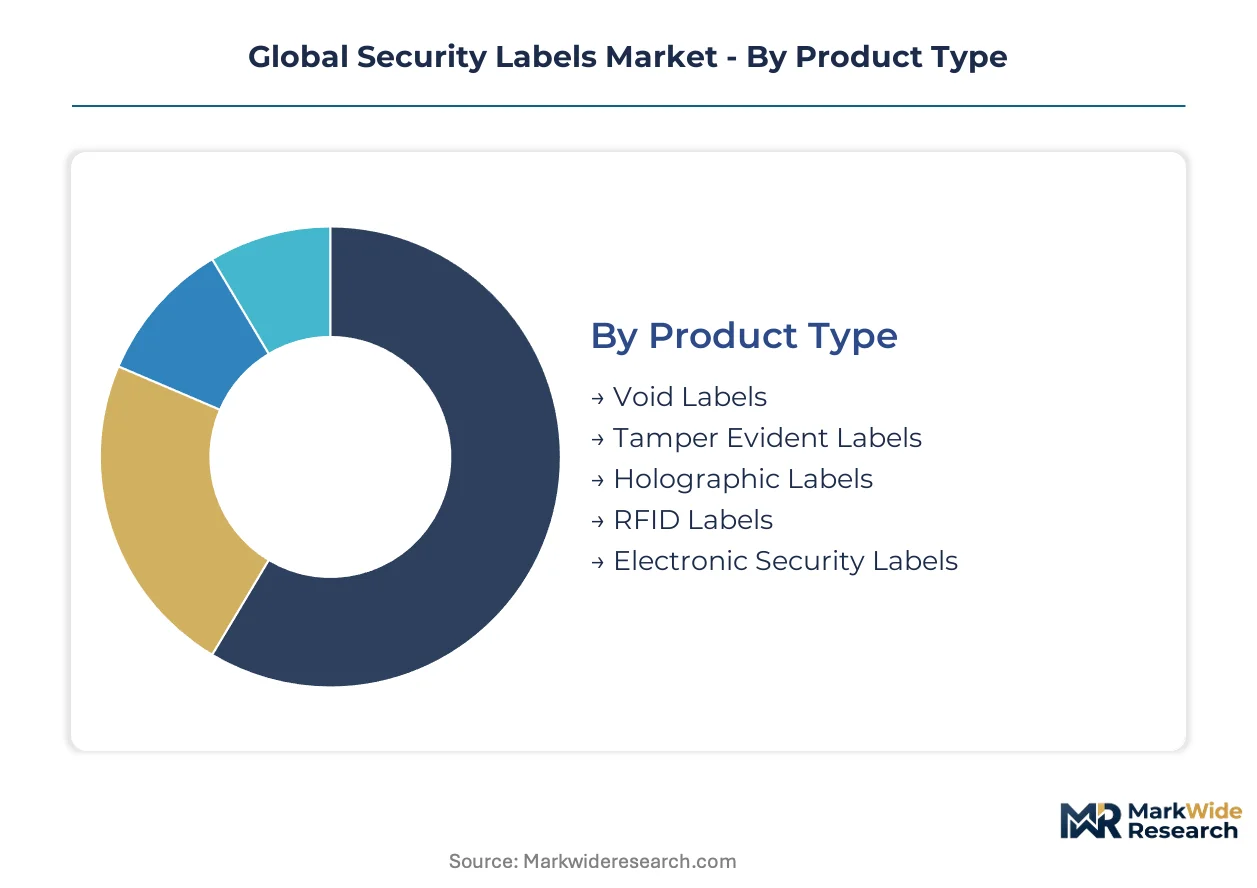
Security label segmentation reflects divergent certification burdens across pharmaceutical serialization, currency authentication, and luxury goods protection. Each category maps distinct technical specifications to compliance mandates that reshape procurement priorities and supplier qualification timelines.
Product Type:
EU Falsified Medicines Directive serialization deadlines and FDA Drug Supply Chain Security Act requirements impose tiered certification burdens: RFID labels demand EPCIS repository integration, while holographic substrates require central bank approval for currency applications.
- RFID Labels:Near-field and ultra-high frequency inlays embed conductive antennae through lamination processes enabling real-time traceability. Pharmaceutical manufacturers in Germany and the United States concentrate procurement here to satisfy unit-level serialization mandates with EPCIS-compliant event repositories.
- Holographic Labels:Micro-optic embossing creates overt authentication features visible without specialized equipment. Demand clusters in currency security and tax stamp applications across India and China where central banks specify proprietary diffraction patterns for banknote integration.
- Void Labels:Adhesive fracture patterns reveal tampering through irreversible substrate damage. Logistics providers deploy these for high-value electronics shipments requiring minimal authentication infrastructure.
- Tamper Evident Labels:Multi-layer constructs separate cleanly to indicate package breach. Consumer goods manufacturers favor these for cost-sensitive applications where overt deterrence suffices.
- Electronic Security Labels:Printed electronics integrate sensors with conductive traces for environmental monitoring. Cold chain pharmaceutical distributors pilot these for temperature excursion detection.
Leading the category by volume: Tamper Evident Labels. Expanding most quickly: RFID Labels.
Technology:
Cost tiering separates capital-intensive laser marking systems from accessible inkjet platforms, with thermal transfer occupying mid-range positioning for variable data serialization.
- Radio Frequency Identification:Inlay lamination combines etched antennae with chip attachment for automated inventory tracking. Logistics providers managing electronics shipments through German distribution hubs drive adoption for real-time visibility without line-of-sight requirements.
- Laser Marking:Ablation and annealing processes create permanent identifiers resistant to environmental degradation. Aerospace and automotive component manufacturers specify these for traceability through extreme thermal cycling.
- Thermal Transfer:Resin ribbon melting produces durable variable data on synthetic substrates. Pharmaceutical converters favor these for serialization compliance at moderate throughput volumes.
- Inkjet Printing:Piezoelectric drop-on-demand enables high-speed customization without plate costs. Spirits packaging specialists deploy these for regional tax stamp variations.
- Digital Watermarking:Imperceptible signal embedding enables smartphone-readable authentication. Luxury goods houses pilot these for consumer-facing provenance verification.
Highest volume deployment: Thermal Transfer. Steepest expansion trajectory: Radio Frequency Identification.
Application:
Customer type differentiation separates regulated pharmaceutical mandates from discretionary luxury goods spending, with document authentication occupying stable government procurement cycles.
- Pharmaceutical Packaging:Unit-level serialization with aggregation requirements demands multi-layer label constructs integrating RFID inlays with human-readable codes. Manufacturers in the United States race to meet FDA Drug Supply Chain Security Act verification system deadlines.
- Currency Security:Central bank specifications mandate proprietary holographic features with forensic authentication layers. India's Reserve Bank and China's central monetary authority drive sustained substrate development through security printing tenders.
- Luxury Goods Protection:Brand authentication combines physical tamper evidence with digital verification layers. European fashion houses deploy micro-optic integration for consumer-facing smartphone validation.
- Electronics Protection:Warranty void labels and component traceability deter gray market diversion. Original equipment manufacturers specify these for high-value semiconductor shipments.
- Document Authentication:Government-issued credentials and academic certificates require substrate-level security features. National identity programs in India and Saudi Arabia generate sustained volume.
Volume leader: Pharmaceutical Packaging. Gaining share fastest: Luxury Goods Protection.
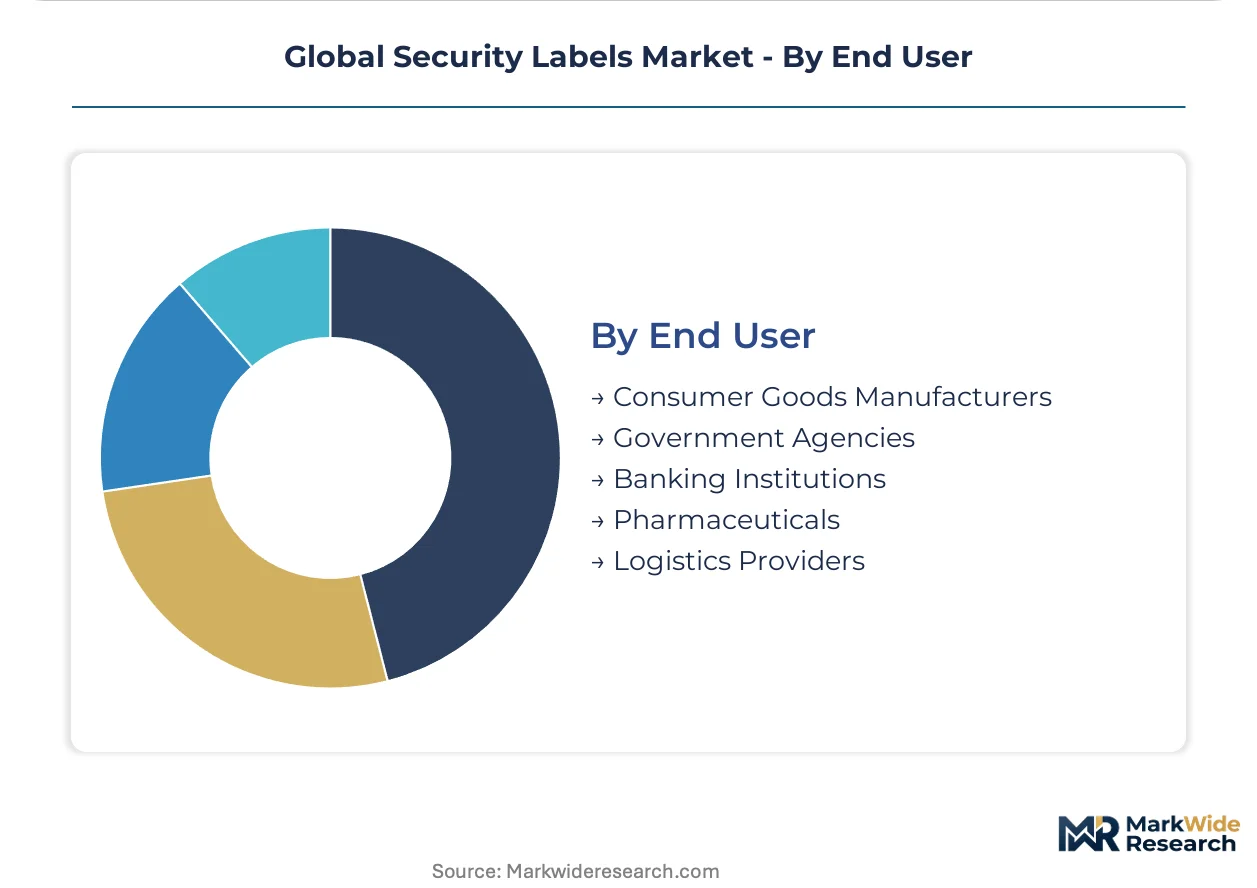
End User:
Geographic concentration patterns show pharmaceutical manufacturers clustering in Germany and the United States, while government agencies anchor demand in India and China through currency and document security programs.
- Pharmaceuticals:Serialization mandates compel wholesale infrastructure replacement across manufacturing and distribution operations. Companies in Germany and the United States prioritize EPCIS-compliant RFID integration for EU and FDA regulatory alignment.
- Government Agencies:Central banks and national security printers specify proprietary authentication substrates for currency and identity documents. India's CDSCO and central monetary authority drive dual demand for pharmaceutical and currency applications.
- Logistics Providers:Third-party fulfillment operations deploy RFID and tamper-evident solutions for high-value cargo visibility. German automotive parts distributors lead adoption for just-in-time supply chain transparency.
- Consumer Goods Manufacturers:Spirits and cosmetics brands balance authentication efficacy against packaging cost constraints. Tax stamp compliance in regulated alcohol markets drives regional specification.
- Banking Institutions:Check fraud prevention and card authentication sustain demand for holographic and electronic security features. Regional banks in the United States prioritize cost-effective thermal transfer serialization.
Dominant procurement volume: Pharmaceuticals. Climbing the fastest: Logistics Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of security labels concentrates in Germany, China, and the United States, while consumption spreads across pharmaceutical hubs in India and Brazil. This production-consumption divide shapes trade flows and localization investments.
Germany
Pharmaceutical packaging and spirits authentication drive label substrate demand across Bavaria and North Rhine-Westphalia. REACH and RoHS substance restrictions force adhesive reformulation among converters near Frankfurt's materials science clusters. The Rhine-Main region hosts specialized holographic embossing operations serving central bank security tenders.
United States
FDA Drug Supply Chain Security Act deadlines compel RFID infrastructure deployment across pharmaceutical distribution networks. Serialization mandates prioritize EPCIS-compliant event repositories for track-and-trace compliance. New Jersey and Pennsylvania manufacturing corridors anchor domestic label converting capacity for regulated drug packaging.
China
NMPA traceability regulations expand pharmaceutical serialization requirements for domestic and export medicine production. The Yangtze River Delta and Pearl River Delta concentrate holographic substrate manufacturing for currency and tax stamp applications. Shanghai-based converters develop micro-optic integration capabilities for consumer-facing authentication.
India
CDSCO track-and-trace expansion for domestic pharmaceuticals creates demand for serialization-ready label infrastructure. Maharashtra and Gujarat pharmaceutical manufacturing clusters drive tamper-evident substrate procurement. Mumbai security printers supply holographic features for central bank currency specifications and government document authentication.
Brazil
ANVISA pharmaceutical serialization mandates accelerate label infrastructure replacement across domestic drug manufacturing. São Paulo state anchors both pharmaceutical production and label converting capacity for regulated packaging. Tax stamp compliance in regulated beverage markets sustains holographic substrate demand from federal revenue programs.
Global Security Labels Market Competitive Landscape
Top-tier vendors anchor premium substrate supply, while mid-scale converters compete on regional qualification speed and customization flexibility. Materials science conglomerates with adhesive and film portfolios dominate high-performance tamper-evident segments. Specialized printing houses capture pharmaceutical and spirits authentication through dedicated embossing capabilities. Competitive moves center on vertical integration into RFID inlay production and subscription-based authentication software bundling.
Within the materials science tier, Avery Dennison Corporation and 3M Company exemplify integrated substrate-to-adhesive positioning. CCL Industries Inc. occupies a specialist role across pharmaceutical and spirits end markets. These three entities represent divergent strategic archetypes: conglomerate-scale materials control, diversified industrial technology, and focused packaging specialization.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| 3M Company |
| CCL Industries Inc. |
| UPM |
| Zebra Technologies |
| Brady Corporation |
| Honeywell International Inc. |
| tesa SE |
| Sato Holdings |
| Others |
Supply & Pricing Matrix
RFID inlay lamination scale-up across German and Chinese production hubs simultaneously compresses unit economics and concentrates supply leverage among converters with captive antenna-etching capacity. This dual effect rewards backward-integrated players while squeezing margin buffers for pure-play substrate suppliers locked into fixed-price pharmaceutical contracts.
Pricing Analysis
Margin tightening in standard-grade tamper-evident substrates reflects silver price volatility and REACH-driven adhesive reformulation costs. Three-tier pricing structure across premium, standard, and economy levels separates EPCIS-compliant RFID bundles from basic void labels, with certification grade and volume scale as primary differentiation drivers. Pharmaceutical manufacturers exhibit lowest price sensitivity due to regulatory compliance deadlines, while logistics providers managing consumer goods shipments resist technology upgrading. Cost compression in mid-tier holographic substrates intensifies as brand owners unbundle hardware from managed verification services.
Supply Chain Analysis
Regional distribution centers in Frankfurt, Shanghai, and New Jersey anchor hub-and-spoke patterns for pharmaceutical and electronics label fulfillment. Manufacturing concentrates in Germany, China, and the United States, with conductive inks, polyester films, and silicon wafers as critical input dependencies. Distribution runs through specialized converters qualified under FDA, EMA, and NMPA serialization protocols. Single-source vulnerability in silver-based antennae supply exposes converters to commodity price swings that disrupt margin predictability on long-term contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive advantage in security labels hinges on controlling upstream RFID inlay production or downstream authentication software platforms, with players racing to capture both layers before standardization commoditizes hardware.
For Market Incumbents: Cement technology leadership by acquiring specialist micro-optic embossing capabilities and locking pharmaceutical customers into multi-year EPCIS repository subscriptions. Blockchain verification threatens to displace physical authentication in luxury goods, making captive software development essential. Backward integration into conductive ink formulation insulates margin exposure to silver volatility. For New Entrants and Emerging Players: Begin with India's CDSCO track-and-trace expansion, where domestic pharmaceutical manufacturing lacks qualified local converters with serialization-ready infrastructure. Target Maharashtra and Gujarat clusters with RFID-tamper evident hybrid offerings bundled with cloud-based aggregation services. Partner with Mumbai security printers for holographic feature co-development to accelerate central bank qualification timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by materials science conglomerates seeking authentication software capabilities, with financial sponsor interest in subscription-revenue models. Mid-scale converters with EPCIS integration expertise and regional pharma relationships represent prime targets. Watch for FDA Drug Supply Chain Security Act verification system deadline acceleration as inflection signal for consolidation urgency.| Strategic Initiative | Industry Significance |
|---|---|
| RFID Inlay Manufacturing Scale-Up | Captive antenna production insulates margin exposure to silver price volatility for German pharmaceutical converters. |
| EPCIS Repository Platform Development | Cloud-based serialization data management locks pharmaceutical manufacturers into recurring revenue relationships beyond substrate supply. |
| Micro-Optic Integration Partnership | Smartphone-readable authentication enables consumer-facing verification without dedicated reading equipment for European luxury brands. |
| REACH-Compliant Adhesive Reformulation | Solvent-free chemistry qualification accelerates European converter approval timelines under ECHA substance restrictions. |
| India Localization Investment | Maharashtra production capability positions converters for CDSCO domestic pharmaceutical track-and-trace mandate expansion. |
Research Methodology
Document review covered FDA Drug Supply Chain Security Act guidance documents, EMA serialization implementation reports, and NMPA traceability regulations, complemented by interviews with pharmaceutical packaging procurement directors, label converter operations managers, RFID hardware engineers, and central bank security printing specialists. Secondary validation drew from customs trade data for holographic substrate flows, SEC filings of listed materials science conglomerates, and pharmaceutical serialization compliance databases. Bottom-up demand modeling across application segments triangulated against top-down market sizing from adhesive and film consumption patterns.
Segmentation outputs reflect disaggregated projections across product type, technology platform, end-use application, and geographic regulatory cluster throughout the forecast period. CAGRs derive from regression analysis of historical pharmaceutical packaging expenditure against serialization mandate implementation timelines, with RFID adoption curves and holographic currency demand as primary industry-specific inputs. Variable data printing throughput assumptions and EPCIS repository deployment rates inform volume-to-value conversion factors.
Underlying measurement precision varies by segment; pharmaceutical packaging and currency security carry tighter precision than emerging electronic sensor labels where pilot deployment data remains sparse. Forecasts reflect documented assumptions regarding regulatory deadline adherence, silver price stability, and blockchain authentication displacement rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Holographic Scratch-Off Labels Market
Labels
Global Metal Detectable Tags and Labels Market
Labels
Waterproof and Weatherproof Label Market
Labels
Holographic Labels Market
Labels
Direct Thermal Labels Market
Labels
Heat Shrink Sleeve Market
Labels
Barcode Label Printer Market
Labels
Global Waterproof Labels Market
Labels
Freezer Label Market
Labels
Primary Packaging Labels Market
Labels
Sustainable Labels Market
Labels
Pin Feed Labels Market
Labels
Shrink Sleeve Labels Market
Labels
Glue Applied Automotive Labels Market
Labels
Time Temperature Indicator Labels Market
Labels
Asia-Pacific Self-Adhesive Labels Market