
 Shrink Sleeve Label Applicator Market | 2026-2036
Shrink Sleeve Label Applicator Market Size, Share, and Industry Trends Forecast 2026-2036
Shrink Sleeve Label Applicator Market Outlook
Buyer concentration in the beverage sector is shifting as mid-sized craft distilleries and functional drink startups fragment demand away from multinational CPG giants. Krones AG leverages its integrated bottling line dominance to bundle applicators with filling and capping systems, locking in brewery and soft drink contracts. Fuji Seal International anchors the Asia-Pacific supply base with film-to-applicator coordination that reduces converter downtime. Accraply competes through narrow-web specialization that serves regional co-packers with shorter run lengths.
A shrink sleeve label applicator is an automated or semi-automated machine that positions a pre-printed polymer sleeve around a container and applies heat—typically via steam tunnel, radiant oven, or hot-air system—to cause controlled contraction and conform the label to the product shape. These systems operate at speeds from 100 to 1,000 containers per minute depending on tunnel configuration and container geometry, serving primary functions of full-body decoration, tamper evidence, and multi-pack collation. Automatic applicators dominate installed base value due to throughput requirements at beverage bottlers, while steam shrink technology leads growth in personal care where gentle heat preserves sensitive formulations. Heat shrink tunnel configurations occupy the mature core of the market with slower upgrade cycles, and manual applicators sustain margin pools in artisanal food segments where capital constraints limit automation.
FDA regulations on food-contact materials and tamper-evident packaging shape applicator specifications for U.S. pharmaceutical and nutritional clients, while REACH compliance in Europe restricts certain adhesive and ink chemistries used in sleeve production. The EU Green Deal and evolving Extended Producer Responsibility frameworks are forcing converters to validate mono-PE and mono-PET sleeve structures that integrate with existing recycling streams. Stakeholders must monitor how rapidly regional recyclability mandates converge on material specifications, as this will determine whether film innovation or machinery retrofitting captures the next wave of replacement demand.
Market Dynamics
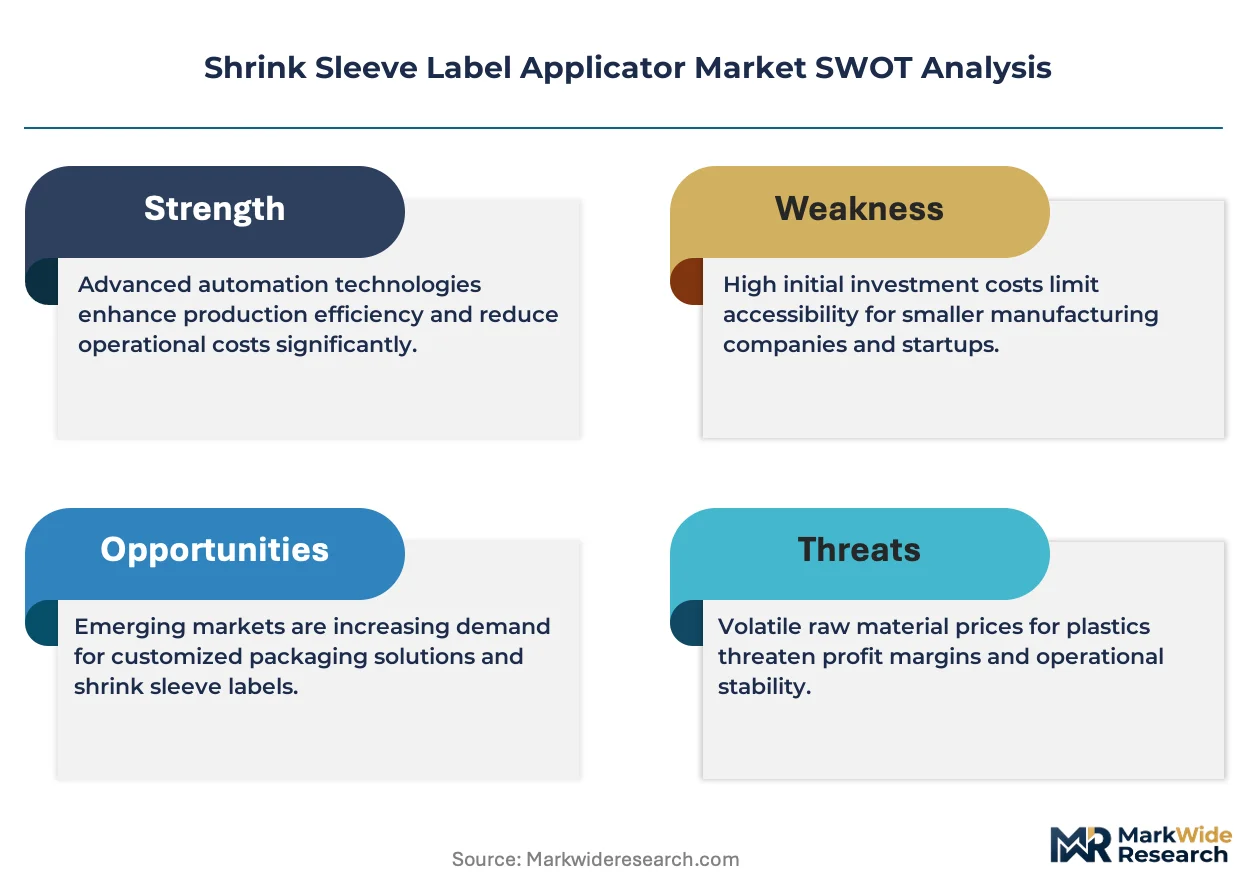
The shrink sleeve label applicator market is restructuring around mono-material film mandates as Extended Producer Responsibility frameworks force converters to redesign sleeve structures for mechanical recycling compatibility.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Tightening recyclability requirements for multi-material labels push converters toward mono-PE and mono-PET sleeve innovations that integrate with existing recycling streams.
- Beverage sector expansion:Craft distilleries and functional drink startups fragment demand away from multinational CPG giants, creating equipment needs for shorter production runs.
- Steam shrink technology:Gentle heat application preserves sensitive personal care formulations, expanding applicator deployment in cosmetic and pharmaceutical bottling.
Market Restraints
- Film supply concentration:Specialty polymer feedstock for high-clarity sleeves concentrates among a limited set of European resin suppliers, exposing converters to input volatility.
- REACH compliance friction:Restricted adhesive and ink chemistries complicate sleeve production for exporters serving European pharmaceutical and food-contact clients.
- Heat tunnel energy intensity:Steam and radiant oven configurations require substantial utility infrastructure, limiting adoption at smaller regional co-packers with constrained capex budgets.
Strategic Opportunities
- India functional beverage growth:FSSAI regulatory alignment with global food-contact standards enables imported applicator deployment as domestic bottling capacity scales.
- Pharmaceutical tamper-evidence mandate:FDA requirements for over-the-counter packaging create dedicated demand for integrated sleeve applicator-tunnel systems in U.S. nutritional supplement manufacturing.
- Digital print convergence:Narrow-web inkjet integration with shrink sleeve converting enables mass customization for regional craft brands without plate changeover downtime.
Industry Challenges
- Retrofit complexity:Legacy heat tunnel infrastructure at established beverage bottlers requires substantial modification to handle thinner mono-material films without distortion.
- Cross-functional technician scarcity:Combined mechanical, thermal, and polymer science expertise needed for applicator optimization outpaces vocational training pipeline output in manufacturing regions.
- Validation timeline compression:Accelerated EU Green Deal compliance deadlines force simultaneous film reformulation and machinery qualification, straining quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shrink Sleeve Label Applicator Market |
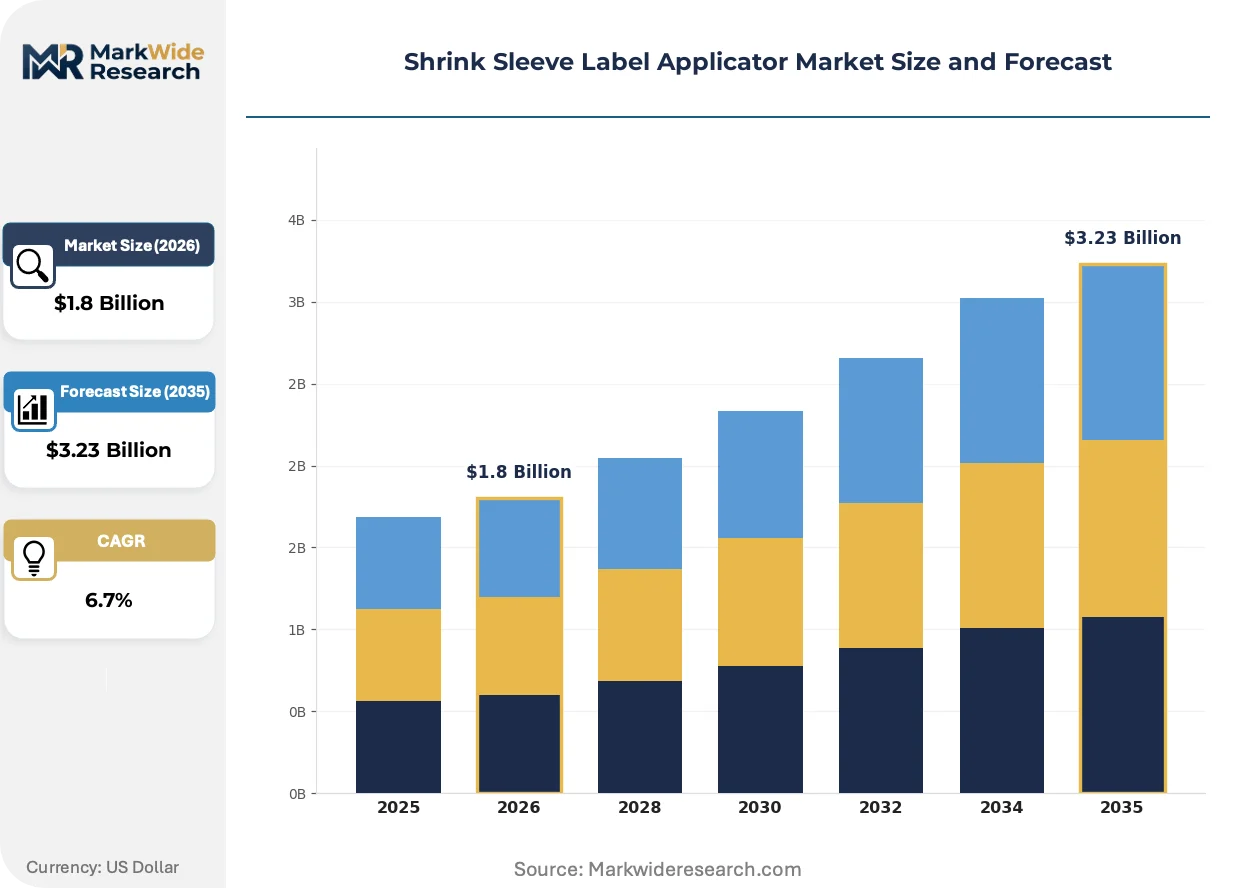
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Applicators, Semi-Automatic Applicators, Manual Applicators, Bottle Applicators End User: Food & Beverage, Pharmaceuticals, Personal Care, Household Products Application: Packaging, Labeling, Branding, Product Protection Technology: Heat Shrink, Steam Shrink, Shrink Tunnel, Labeling Machines |
| Companies Covered | Krones AG, Fuji Seal International, Accraply, PDC International, Axon, Pack Leader Machinery, Sleever International, BW Integrated Systems, Dase-Sing Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shrink Sleeve Label Applicator Market Strategic Shifts
Shrink sleeve applicator technology is converging with downstream sustainability mandates, forcing simultaneous innovation in film chemistry, heat delivery systems, and line integration protocols.
Mono-material sleeve structures are unifying previously separate label and container recycling streams. Beverage bottlers in Germany and the Netherlands adopt these films at accelerating pace to preempt EPR fee penalties. This unification is compressing the addressable market for multi-material adhesive labels while expanding retrofit demand for compatible applicator-tunnel configurations.
REACH restrictions on specific phthalate plasticizers and heavy metal pigments reshape sleeve formulation requirements. Industrial consequence falls heaviest on converters serving European personal care brands, who must validate alternative chemistries without sacrificing shrink curve precision. Pharmaceutical packaging lines in Switzerland and Germany respond by qualifying applicator systems with enhanced process control documentation for regulatory submission.
Regional co-packers now unbundle after-sales service from initial equipment purchase, procuring maintenance and spare parts through independent third-party channels rather than captive OEM networks. This behavior disrupts traditional machinery vendor revenue models concentrated in North American craft beverage clusters. The shift is most visible in U.S. Midwest brewing corridors, where capital-constrained startups prioritize operational flexibility over integrated service contracts.
Shrink Sleeve Label Applicator Market Segmentation
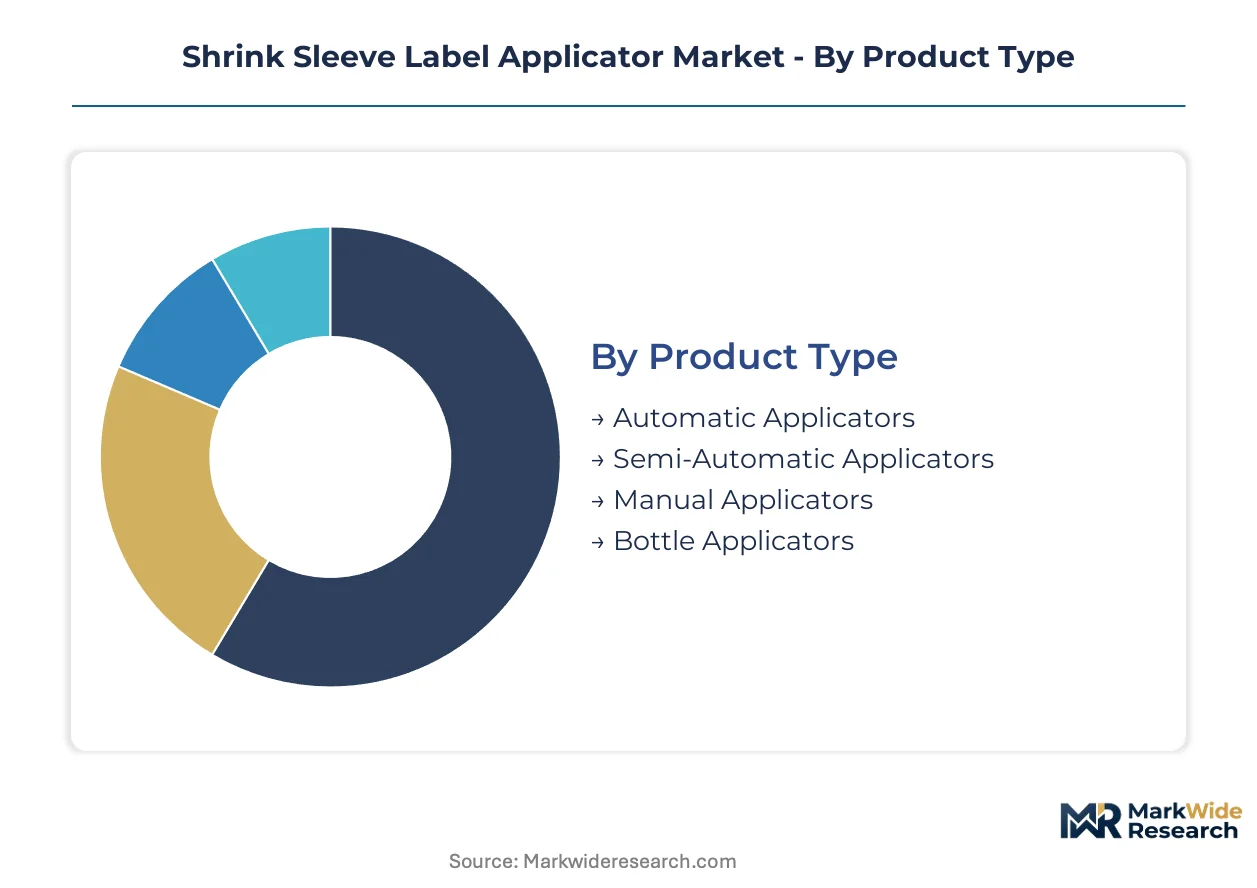
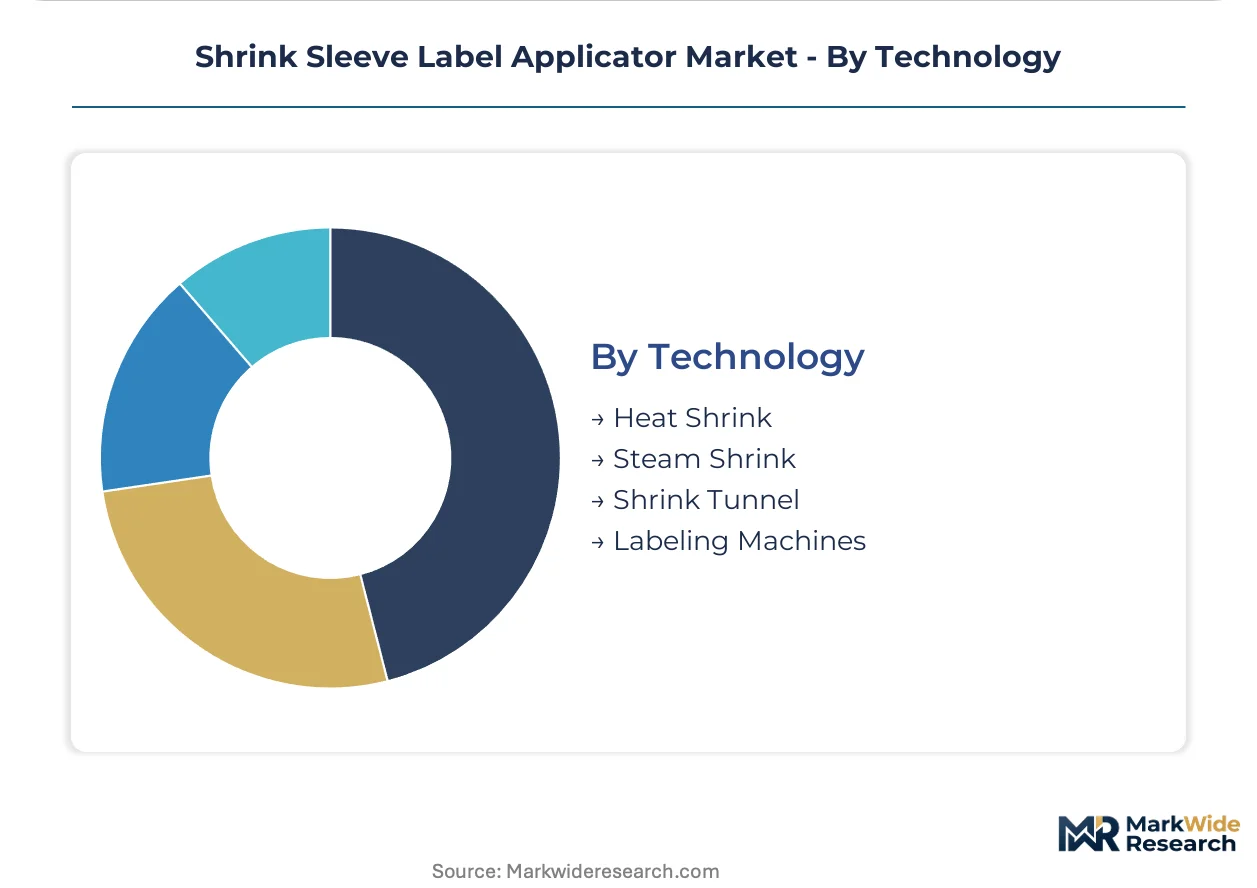
Technology differentiation in shrink sleeve applicators determines capital intensity, throughput ceiling, and retrofit compatibility with emerging mono-material films. Segmentation reveals where equipment vendors concentrate R&D resources versus where aftermarket service margins accumulate.
Product Type:
Automation level dictates line speed, labor dependency, and total cost of ownership across beverage bottling operations.
- Automatic Applicators:These systems integrate with high-speed filling lines at 400-1,000 containers per minute, deploying servo-driven sleeve placement and synchronized heat tunnel control. Demand concentrates at multinational CPG bottlers in Germany and the Netherlands where throughput optimization justifies seven-figure capital outlays. Krones AG bundles these units with complete bottling lines, locking in brewery contracts through integrated line responsibility.
- Semi-Automatic Applicators:Operator-fed machines bridge manual loading with automated heat application, typically achieving 50-200 containers per minute. Regional co-packers in the U.S. Midwest brewing corridor favor this tier for seasonal SKU flexibility without full automation commitment. Capital-constrained craft distilleries prioritize operational flexibility over integrated service contracts when procuring these units.
- Manual Applicators:Hand-loaded systems with standalone heat guns serve artisanal food producers and startup beverage brands.
- Bottle Applicators:Container-specific configurations handle non-cylindrical geometries in premium spirits and cosmetic packaging.
Automatic applicators lead on scale; semi-automatic applicators lead on momentum in fragmented craft beverage clusters.
End User:
Regulatory exposure and packaging sophistication vary sharply across consumer sectors, shaping equipment specification priorities.
- Food & Beverage:This segment generates the largest installed base, spanning carbonated soft drinks, craft beer, functional beverages, and ready-to-drink cocktails. FDA food-contact material regulations and EU Packaging and Packaging Waste Regulation recyclability mandates simultaneously drive equipment replacement cycles. Full-body shrink sleeves deliver 360-degree branding and tamper evidence that adhesive labels cannot replicate.
- Pharmaceuticals:Over-the-counter and nutritional supplement packaging demands validated tamper-evidence systems with process control documentation for FDA submission. Steam shrink technology dominates this segment to preserve heat-sensitive formulations.
- Personal Care:Cosmetic and skincare brands deploy gentle heat application to protect volatile fragrance compounds and active ingredients.
- Household Products:Cleaning chemical and automotive fluid bottlers prioritize chemical resistance and multi-pack collation functionality.
Food and beverage dominates absolute volume; pharmaceuticals is climbing the fastest on regulatory compliance spending.
Application:
Functional purpose determines heat delivery method, sleeve specification, and downstream recycling pathway complexity.
- Packaging:Primary containment protection through full-body sleeve coverage that replaces or supplements rigid secondary packaging. Beverage multi-packs and promotional bundling drive demand in German retail chains facing EPR fee pressure.
- Labeling:Decorative and informational sleeve application competing with pressure-sensitive and in-mold alternatives. Mono-PE and mono-PET innovations are displacing multi-material structures to satisfy EU Green Deal recyclability requirements.
- Branding:Premium shelf differentiation through 360-degree graphic coverage and tactile finishes.
- Product Protection:Tamper-evidence bands and shrink-wrapped seals for pharmaceutical and food safety assurance.
Packaging commands the largest equipment footprint; labeling is gaining share fastest on sustainability-driven material transitions.
Technology:
Heat delivery mechanism constrains film compatibility, energy consumption, and container material tolerance.
- Heat Shrink:Radiant oven and hot-air systems represent the mature installed base, handling standard PET and PVC sleeves at moderate capital cost. Legacy tunnel infrastructure at established bottlers requires substantial modification for thinner mono-material films without distortion.
- Steam Shrink:Gentle heat transfer preserves sensitive personal care formulations and pharmaceutical active ingredients. This configuration expands most quickly in cosmetic bottling where product integrity overrides energy efficiency considerations.
- Shrink Tunnel:Integrated conveyor-tunnel systems dominate high-volume beverage lines with slower upgrade cycles.
- Labeling Machines:Hybrid systems combining sleeve application with pressure-sensitive or roll-fed labeling capability.
Heat shrink retains the widest installed base; steam shrink shows the steepest expansion trajectory on personal care and pharmaceutical demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled automation technicians and polymer engineers concentrate in southern Germany's machinery belt, anchoring the densest cluster of shrink sleeve applicator manufacturing and service expertise worldwide.
Germany
Bavaria and Baden-Württemberg host Krones AG and Sleever International engineering centers serving beverage bottlers across the EU. REACH compliance deadlines from ECHA force simultaneous film reformulation and machinery qualification. The Stuttgart-Munich corridor specializes in mono-material retrofit kits for legacy heat tunnel infrastructure.
United States
Midwest brewing corridors in Michigan and Wisconsin fragment equipment demand toward semi-automatic systems for craft distillery seasonal runs. FDA food-contact material regulations shape tamper-evidence specifications for nutritional supplement packaging. Chicago-area co-packers unbundle after-sales service from OEM contracts to prioritize operational flexibility.
China
Yangtze River Delta packaging machinery clusters scale domestic production for Asia-Pacific beverage bottlers. GB standards for food-contact materials increasingly align with FDA and EFSA specifications to enable export qualification. Shanghai-based converters coordinate film-to-applicator supply chains that reduce converter downtime across regional personal care brands.
India
Maharashtra and Gujarat bottling corridors expand capacity for functional beverage startups requiring imported applicator deployment. FSSAI regulatory alignment with Codex Alimentarius standards enables foreign equipment qualification. Mumbai-Pune industrial zones attract steam shrink technology for cosmetic formulations sensitive to heat degradation.
Switzerland
Swissmedic validation requirements for pharmaceutical packaging drive demand for process control documentation in Basel-Zurich corridor. Precision engineering traditions support applicator-tunnel systems with enhanced thermal regulation. Geneva-area cosmetic brands deploy gentle heat configurations to preserve volatile fragrance compounds in premium skincare packaging.
Shrink Sleeve Label Applicator Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market strata. The installed base concentrates among beverage bottling integrators and narrow-web regional equipment suppliers. Three archetypes dominate: full-line bundlers capturing brewery contracts through integrated responsibility, film-coordinated Asia-Pacific anchors optimizing converter uptime, and specialization-focused narrow-web vendors serving shorter craft production runs. Capacity expansion and strategic partnerships represent the dominant competitive vectors as EPR deadlines compress qualification timelines.
Among German-based full-line integrators, Krones AG and Sleever International occupy positions exemplifying bundled bottling line dominance. Fuji Seal International represents the film-coordinated Asia-Pacific archetype. Accraply sits within the narrow-web specialization tier serving regional co-packers. These three anchors illustrate how geographic concentration and strategic focus differentiate competitive positioning across automation levels and end-use sectors.
| Leading Market Players |
|---|
| Krones AG |
| Fuji Seal International |
| Accraply |
| PDC International |
| Axon |
| Pack Leader Machinery |
| Sleever International |
| BW Integrated Systems |
| Dase-Sing Packaging |
| Others |
Value Chain & Pricing Dynamics
Captive film-to-applicator coordination by Fuji Seal International and Sleever International anchors both supply security and pricing power for converters serving European beverage bottlers. This integration pattern insulates bundled equipment-film packages from spot resin volatility while exposing independent machinery vendors to margin compression on standalone applicator sales.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for mid-range automatic applicators. Pricing stratifies across premium, standard, and economy tiers based on automation level and after-sales bundling. Cost compression in the semi-automatic tier is intensifying because regional co-packers unbundle service contracts to prioritize operational flexibility. Craft distilleries in the U.S. Midwest demonstrate highest price sensitivity; multinational CPG bottlers in Germany show lowest sensitivity due to integrated line responsibility contracts.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme are reshaping sourcing patterns for steam shrink tunnel components. Specialty polymer feedstock concentrates in Germany, Japan, and South Korea. Component fabrication draws from precision engineering clusters in Switzerland and Bavaria. Single-source vulnerability persists for high-clarity mono-PET film substrates qualified under REACH. Distribution runs through OEM captive networks in Europe and independent third-party channels in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory layering, with EU Packaging and Packaging Waste Regulation recyclability deadlines forcing simultaneous film reformulation and machinery replacement cycles.
For Market Incumbents: Deepen backward integration into mono-material film substrate production to capture retrofit demand from legacy heat tunnel infrastructure. Lock in brewery contracts through expanded integrated line responsibility offerings. Counter threat from narrow-web digital print convergence by certifying applicator compatibility with mass customization workflows. For New Entrants and Emerging Players: Enter via India's Maharashtra-Gujarat bottling corridor where FSSAI alignment enables imported equipment qualification against fragmented domestic supply. Target functional beverage startups requiring steam shrink configurations for heat-sensitive formulations. Pursue narrow-web specialization serving regional co-packers with seasonal SKU flexibility. For Investors and Strategic Acquirers: Roll-up economics work for narrow-web specialists serving craft beverage clusters because buyer fragmentation prevents scale advantages for full-line bundlers. Long-term viability rests on EPR mandate convergence determining replacement cycle timing. Watch EU Green Deal compliance deadline acceleration as inflection indicator for qualification bandwidth constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Retrofit Kit Development | Captures EPR-driven replacement demand from German beverage bottlers with legacy tunnel infrastructure. |
| Steam Shrink Technology Licensing | Enables entry into Swiss pharmaceutical packaging lines requiring Swissmedic validation documentation. |
| Digital Print Applicator Integration | Serves U.S. Midwest craft distilleries pursuing mass customization without plate changeover downtime. |
| Regional Service Network Unbundling | Matches Chicago-area co-packer procurement patterns prioritizing operational flexibility over OEM contracts. |
| India PLI-Aligned Local Assembly | Qualifies for domestic-content incentives while serving Maharashtra functional beverage capacity expansion. |
Study Parameters
Direct dialogue with plant engineers at beverage bottlers, aftermarket service heads at machinery distributors, procurement leads at film converters, and regulatory affairs specialists at packaging OEMs grounded qualitative findings. Secondary validation drew from EU ECHA substance restriction databases, FDA food-contact material guidance, SEC filings by listed machinery manufacturers, and trade flow data from European resin suppliers. Bottom-up and top-down triangulation cross-checked equipment shipment tallies against end-use sector capacity expansion announcements.
Bottom-up modeling aggregated applicator unit economics across automation tiers, tunnel configurations, and regional installation cost structures. Segmentation dimensions included product type, end-use sector, heat delivery technology, and geographic regulatory cluster. CAGRs derived from slope analysis of replacement cycle timing against EPR mandate phase-ins. Industry-specific inputs incorporated mono-material film qualification timelines and steam shrink technology adoption curves in pharmaceutical packaging.
Inputs from ECHA regulatory filing databases and FDA guidance documents were available through the study window; gaps in real-time film converter inventory data introduce uncertainty bands around near-term retrofit demand timing. Forecasts reflect assumptions about EU member state transposition speed for Packaging and Packaging Waste Regulation requirements. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Global Security Labels Market
Labels
Integrated Labeling System Market
Labels
Foam Labels Market
Labels
Syringe Labels Market
Labels
Safety Labels Market
Labels
Print Label Market
Labels
Direct Thermal Linerless Labels Market
Labels
Die Cut Labels Market
Labels
Europe Shrink and Stretch Sleeve Label Market
Labels
Global Thermal Transfer Label Market
Labels
BOPP Labels Market
Labels
Indicative Seals Market
Labels
Roll-fed Wraparound Label Substrates Market
Labels
Water Dissolvable Labels Market
Labels
Braille Labels Market
Labels
Holographic Scratch-Off Labels Market