
 Global Label Market | 2026-2036
Global Label Market Size, Share, and Industry Trends Forecast 2026-2036
Global Label Market Outlook
Pharmaceutical and food and beverage buyer demand is bifurcating as traceability requirements diverge from shelf-appeal priorities. Avery Dennison Corporation leverages its materials science portfolio to dominate high-performance adhesive segments. CCL Industries sustains global capacity through specialized pharmaceutical and healthcare label operations. Mondi anchors European demand with integrated paper-based sustainable packaging solutions.
A label is a substrate-backed information carrier, typically constructed from paper, plastic film, or foil with pressure-sensitive adhesive or heat-activated bonding layers, applied to products for identification, tracking, branding, or regulatory compliance. Pressure sensitive labels lead volume due to versatile application across automated and manual packaging lines, while shrink sleeve formats capture premium branding margins in beverages and personal care. Paper materials retain cost-sensitive volume in logistics and retail, though plastic substrates are displacing them in moisture-critical pharmaceutical and food applications where barrier performance determines specification.
The FDA enforces stringent label accuracy and tamper-evidence standards for pharmaceuticals distributed in the United States, while the EU Green Deal and REACH framework in Europe restrict hazardous substances in adhesive formulations and mandate recyclability disclosures. China's SAMR enforces GB standards for pre-packaged food labeling that affect export compliance for multinational suppliers. Stakeholders must monitor evolving extended producer responsibility schemes and material certification requirements that will reshape substrate selection and regional sourcing strategies.
Market Dynamics
Pharmaceutical serialization mandates across multiple jurisdictions are forcing substrate and adhesive suppliers to reconfigure production lines for track-and-trace compatibility, while food exporters in East Asia face divergent multilingual compliance requirements that fragment order specifications and compress batch sizes.
Growth Catalysts
- EU Falsified Medicines Directive:European serialization deadlines compel pharmaceutical contract manufacturers to upgrade label infrastructure, creating sustained specification demand for tamper-evident and aggregation-capable formats.
- Flexible packaging conversion:Beverage and personal care brands are migrating from rigid containers to squeezable pouches, requiring heat-shrink sleeve labels that conform to irregular geometries and withstand pasteurization cycles.
- East Asian export manufacturing:Contract packaging operations in Vietnam and Thailand require multilingual back-panel labels serving EU, US, and Middle Eastern destination markets simultaneously.
Market Restraints
- Petrochemical input volatility:Polypropylene and polyethylene terephthalate film prices fluctuate with naphtha cracking margins, compressing converter gross margins on fixed-price annual contracts.
- Adhesive raw material concentration:Acrylic emulsion supply for pressure-sensitive adhesives concentrates among German and Japanese chemical producers, exposing label converters to freight cost spikes and allocation risk.
- Paper substrate displacement:Moisture-sensitive paper labels face substitution by synthetic films in pharmaceutical cold-chain and refrigerated food applications where barrier performance governs specification.
Strategic Opportunities
- Indian food export compliance:FSSAI-mandated nutritional disclosure expansion creates demand for extended-content booklet labels serving EU and US destination markets from Indian processing facilities.
- China dual carbon policy alignment:SAMR recyclability disclosure requirements and provincial extended producer responsibility schemes favor paper-based and certified-recyclable film substrates in domestic premium packaging.
- Digital printing convergence:Combination of inkjet deposition and inline finishing enables economic production runs below five thousand units, opening pharmaceutical clinical-trial and craft beverage segments.
Industry Challenges
- Serialization integration complexity:Pharmaceutical converters must synchronize variable-data printing with aggregation software and warehouse management systems, requiring cross-functional IT and operations coordination.
- Migration testing timelines:EU REACH and Swissmedic requirements for extractable and leachable analysis extend new adhesive qualification cycles to eighteen months, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Label Market |
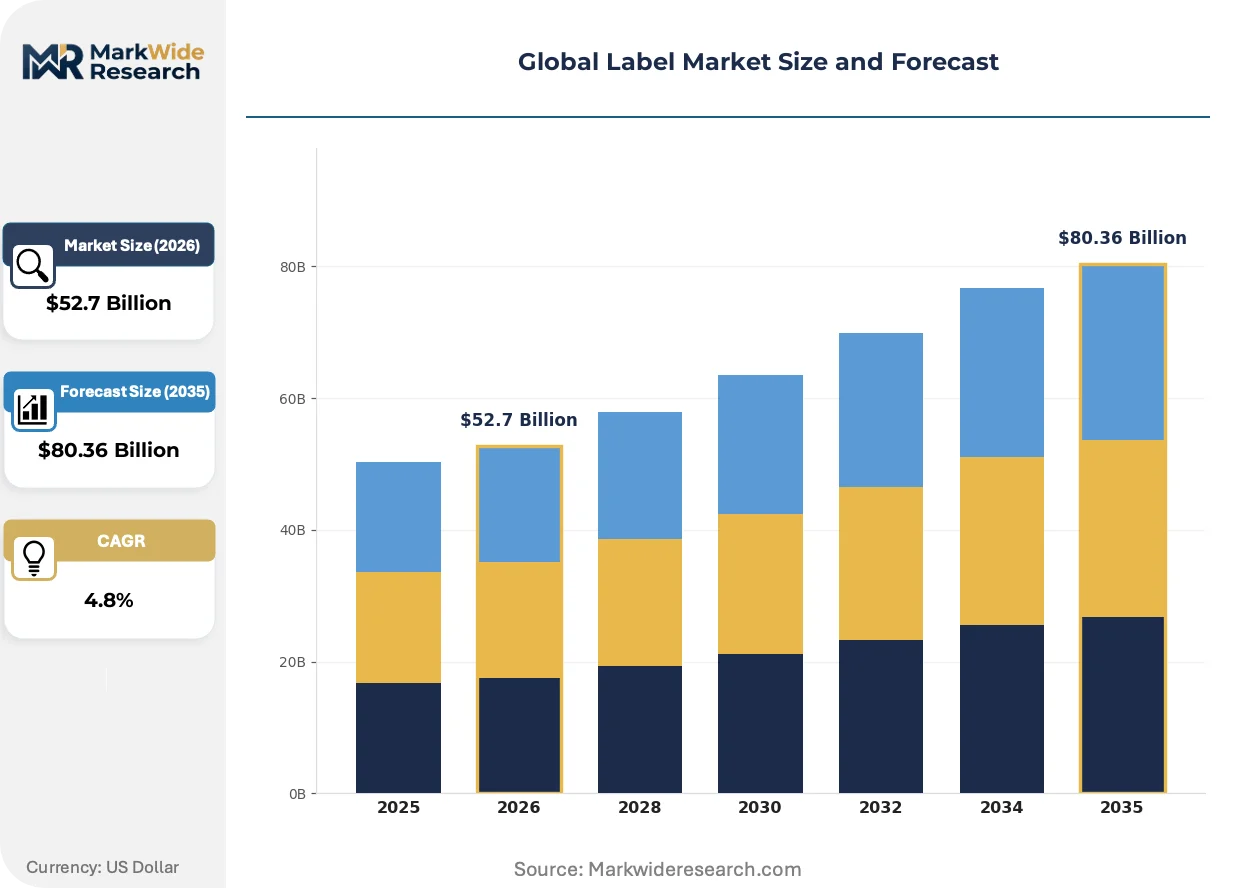
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $80.36 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Sensitive, Shrink Sleeve, In-Mold, Heat Transfer Material: Paper, Plastic, Metal, Fabric End User: Food & Beverage, Pharmaceuticals, Retail, Automotive Application: Branding, Information, Safety, Promotion |
| Companies Covered | Avery Dennison Corporation, CCL Industries, Multi-Color Corporation, Mondi, Huhtamaki Group, Neenah, Inc, Amcor plc, Berry Global, All4Labels, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Label Market Strategic Shifts
Active substrate innovation is compressing traditional material hierarchies as converters and brand owners pursue simultaneous performance, sustainability, and regulatory compliance objectives without accepting cost penalties.
Thin-gauge polyethylene and polypropylene films are displacing conventional paper and standard-thickness plastic labels in moisture-critical pharmaceutical and refrigerated food applications. Major contract packagers serving EU and US distribution channels have accelerated qualification timelines for these substrates over the past eighteen months. The shift is displacing incumbent paper-based specifications in segments where barrier performance and dimensional stability determine supplier selection.
REACH restrictions on hazardous substance content in adhesive formulations and the EU Green Deal's recyclability disclosure mandates are compelling reformulation investments across European converter operations. Substrate suppliers must now provide third-party certification of adhesive layer compatibility with mainstream mechanical recycling streams. Pharmaceutical and personal care brands with pan-European distribution face the most acute compliance pressure, driving preference for suppliers with established ECHA registration dossiers.
Brand owner specification behavior is fragmenting as sustainability commitments diverge from cost-control imperatives across product tiers. Premium-positioned food and beverage lines in Germany and France specify certified-recyclable or fiber-based substrates regardless of unit cost, while value-tier lines in Southern and Eastern Europe prioritize lowest-landed-cost procurement. This bifurcation is forcing converters to maintain parallel substrate inventories and production workflows, complicating capacity planning and margin management across regional facilities.
Global Label Market Segmentation
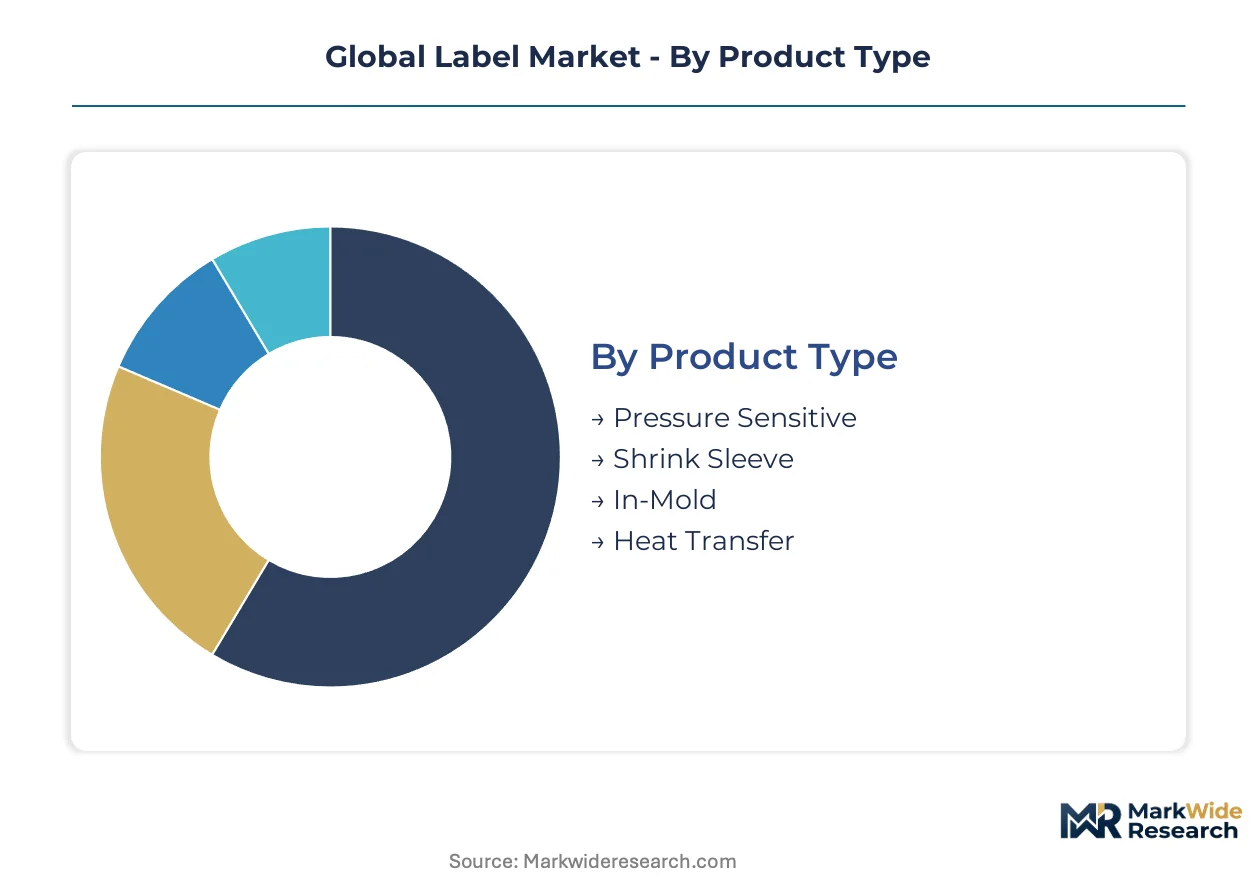
Label converters configure production workflows around four intersecting dimensions that determine substrate selection, printing technology, and margin structure. Product type governs application machinery and line speed. Material chemistry dictates barrier performance and recyclability compliance. End-user verticals impose divergent regulatory and aesthetic specifications. Application purpose separates premium branding budgets from cost-driven information labels.
Product Type:
Plastic substrates and digital printing are eroding traditional format hierarchies, with established segments facing displacement from thin-gauge films and inkjet-compatible structures.
- Pressure Sensitive:Multi-layer construction with face stock, adhesive coating, and release liner enables application across automated packaging lines without heat activation. Demand concentrates in pharmaceutical serialization and retail logistics, where variable-data printing and tamper-evidence requirements from FDA and EU Falsified Medicines Directive specifications drive specification upgrades.
- Shrink Sleeve:Heat-activated polyester or polyolefin films conform to irregular container geometries through steam or radiant tunnel systems. Beverage and personal care brands in Germany and France specify these formats for 360-degree branding coverage, though pasteurization compatibility requirements extend qualification timelines.
- In-Mold:Polypropylene labels fuse with container walls during blow-molding or injection processes, eliminating separate application steps. Automotive and durable goods manufacturers specify these for chemical resistance and permanent bonding.
- Heat Transfer:Wax-resin or resin ribbons transfer ink via thermal printheads onto synthetic face stocks. Industrial asset tracking and cold-chain logistics operations specify these for barcode durability in moisture-exposed environments.
Pressure Sensitive retains volume leadership; Shrink Sleeve holds the steepest expansion curve.
Material:
Cost tiers fragment procurement behavior as premium brands absorb certified-recyclable premiums while value lines minimize landed cost.
- Paper:Cellulose-based substrates with clay coatings or direct thermal sensitivity serve retail price-marking and logistics applications. E-commerce fulfillment centers in India and Vietnam specify these for cost-sensitive shipping labels, though moisture sensitivity limits pharmaceutical cold-chain adoption.
- Plastic:Biaxially oriented polypropylene and polyethylene terephthalate films provide moisture barriers and dimensional stability. Pharmaceutical contract manufacturers in Switzerland and the United States accelerated qualification of thin-gauge specifications to meet EU Green Deal recyclability disclosures while maintaining barrier performance.
- Metal:Aluminum foil laminates deliver absolute moisture and oxygen barriers for aggressive chemical and pharmaceutical applications. Specialty chemical producers specify these for drum labeling in humidity-exposed storage.
- Fabric:Woven or nonwoven synthetic textiles enable removable and repositionable labels for apparel and soft goods. Fast-fashion retailers specify these for care-label applications requiring wash-cycle durability.
Paper retains volume leadership; Plastic holds the steepest expansion curve.
End User:
Customer-type concentration shapes converter capacity allocation, with pharmaceutical and food verticals commanding dedicated production lines.
- Food & Beverage:Multilingual back-panel and front-of-package labels serve export markets from East Asian processing facilities. FSSAI-mandated nutritional disclosure expansion in India drives demand for extended-content booklet formats.
- Pharmaceuticals:Serialization-ready labels with tamper-evidence features and aggregation compatibility serve EU and US distribution channels. Swissmedic and EMA extractable-leachable testing requirements extend adhesive qualification cycles.
- Retail:Price-marking, promotional, and inventory labels serve omnichannel fulfillment operations. Automated warehouse systems in the United States specify direct-thermal paper for scan compliance.
- Automotive:Under-hood and exterior badging labels withstand chemical exposure and thermal cycling. OEM specifications in Germany and Japan demand polyimide or metalized substrates for engine-compartment durability.
Food & Beverage retains volume leadership; Pharmaceuticals holds the steepest expansion curve.
Application:
Margin differentiation separates premium branding budgets from compliance-driven information labels, with safety applications commanding specification premiums.
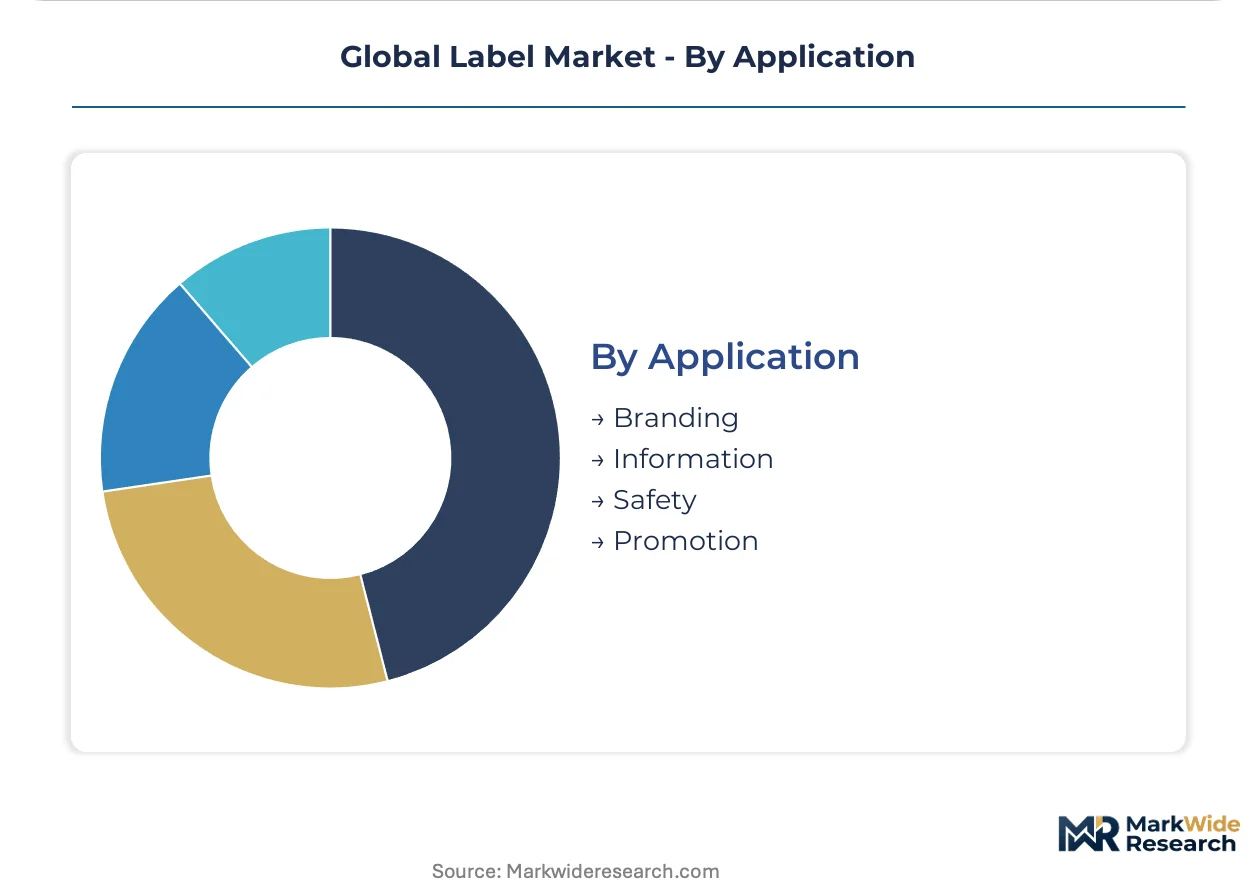
- Branding:High-graphic shrink sleeves and specialty finishes differentiate shelf presence in crowded retail environments. Premium beverage brands in France specify metallic effects and tactile varnishes regardless of unit cost premiums.
- Information:Regulatory-compliant back panels and serialization codes satisfy FDA, SAMR, and EMA disclosure mandates. Pharmaceutical exporters to China must reconcile GB standard pre-packaged food labeling with destination-market requirements.
- Safety:GHS-compliant hazard pictograms and handling instructions serve chemical and industrial applications. OSHA and REACH classification requirements drive substrate durability specifications.
- Promotion:Peel-and-reveal coupons and instant-win game pieces integrate with primary packaging. Seasonal campaigns in the United States specify these for limited-run production with digital printing compatibility.
Information retains volume leadership; Branding holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites European label substrate import flows, while the Yangtze River Delta's manufacturing density generates outbound label demand for export-packaging compliance. These infrastructure assets anchor regional production and distribution patterns across the analysis window.
United States
Pharmaceutical serialization mandates from FDA drive tamper-evident label upgrades across contract packaging operations. The EPA's evolving extended producer responsibility frameworks pressure substrate recyclability certifications. Chicago and Philadelphia metropolitan areas concentrate pharmaceutical label converters serving domestic distribution networks.
Germany
REACH-compliant adhesive reformulation requirements from ECHA accelerate qualification timelines for pharmaceutical applications. The EU Green Deal's recyclability disclosure mandates reshape specification behavior among personal care brands. Bavaria's chemical processing corridor hosts specialized converters serving pan-European pharmaceutical distribution.
China
SAMR's GB standards for pre-packaged food labeling create compliance complexity for export-oriented manufacturers. Provincial extended producer responsibility schemes under dual carbon policy alignment favor certified-recyclable substrates. The Pearl River Delta's contract packaging clusters require multilingual back-panel labels serving simultaneous EU, US, and Middle Eastern destinations.
India
FSSAI-mandated nutritional disclosure expansion generates demand for extended-content booklet labels in food export processing. DGFT export documentation requirements intersect with destination-market compliance standards. Gujarat and Maharashtra processing facilities serve as primary sourcing points for EU and US-bound food shipments.
Switzerland
Swissmedic extractable-leachable testing requirements extend adhesive qualification cycles to eighteen months for pharmaceutical applications. Precision manufacturing standards from ISO frameworks govern substrate dimensional tolerances. The Basel-Zurich corridor concentrates pharmaceutical packaging operations serving global distribution channels.
Global Label Market Competitive Environment
Concentration sits with diversified materials science conglomerates and specialized pharmaceutical converters. The vendor base stratifies across three tiers: integrated substrate-adhesive suppliers with global qualification dossiers, regional converters with vertical specialization in pharmaceutical or food verticals, and digital-native entrants exploiting short-run production economics. M&A activity targets adhesive technology capabilities and regional distribution footprints. Capacity expansion concentrates in East Asian export manufacturing clusters.
Within the integrated materials science tier, Avery Dennison Corporation and CCL Industries occupy anchor positions exemplifying substrate-to-adhesive control. Mondi represents the European paper-based sustainable packaging archetype. These three entities collectively illustrate the competitive divergence between polymer-based performance substrates and fiber-based circular economy positioning.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| CCL Industries |
| Multi-Color Corporation |
| Mondi |
| Huhtamaki Group |
| Neenah, Inc |
| Amcor plc |
| Berry Global |
| All4Labels |
| Others |
Value Chain & Pricing Dynamics
Eighteen-month adhesive qualification cycles now govern converter inventory positioning and contract pricing power in pharmaceutical label procurement. Extended migration testing timelines under EU REACH and Swissmedic requirements compress supplier flexibility, forcing buyers into strategic stockpile commitments that amplify volume-discount leverage for qualified vendors.
Pricing Analysis
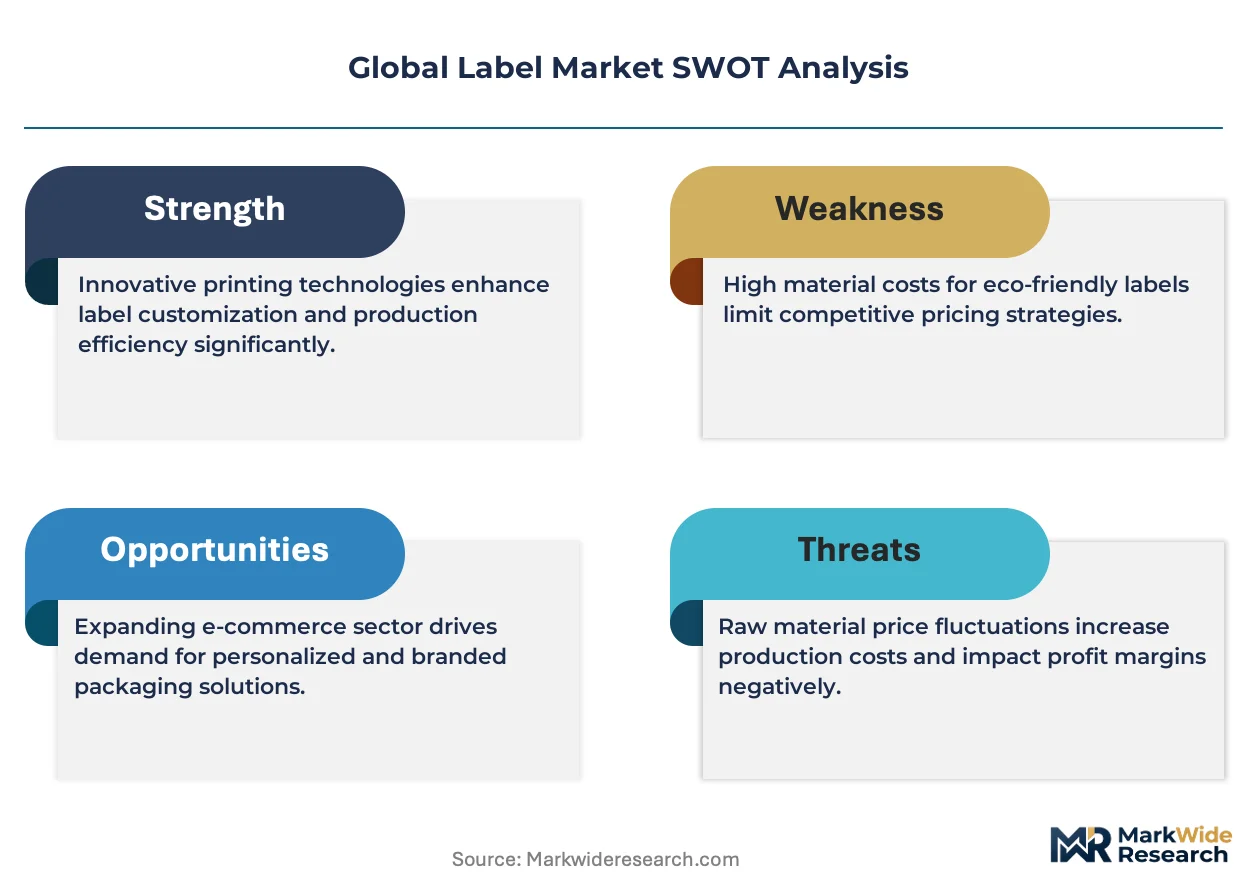
Three-tier pricing structure across premium, standard, and economy levels separates certified-recyclable film substrates from conventional plastic and cost-optimized paper grades. Price differentiation rests on ECHA registration completeness and ISO dimensional tolerance certification, with Swiss and German pharmaceutical buyers absorbing 15-20% premiums for established dossiers. Cost compression in economy-tier paper labels is intensifying because Indian and Vietnamese logistics buyers prioritize landed-cost minimization over barrier performance. Food exporters in East Asia exhibit highest price sensitivity, while EU pharmaceutical contract manufacturers demonstrate lowest sensitivity due to serialization compliance non-negotiability.
Supply Chain Analysis
Just-in-time inventory strategies dominate pharmaceutical label procurement, though acrylic emulsion supply concentration among German and Japanese chemical producers forces strategic safety-stock positioning among tier-one converters. Raw material sourcing draws from Saudi naphtha cracking corridors for polypropylene feedstock, Finnish pulp mills for specialty paper grades, and Chinese biaxial film extrusion facilities for polyester face stocks. Single-source vulnerability concentrates in acrylic adhesive emulsions, where freight cost spikes and allocation risk compound margin pressure. Distribution runs through Rotterdam port consolidation for European pharmaceutical converters and Yangtze River Delta export packaging clusters for East Asian food label demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global label demand is increasingly a service-attach opportunity, with digital printing workflow integration and serialization software companion layers expanding faster than substrate hardware shipments. Recurring revenue from variable-data management and aggregation platform subscriptions now commands valuation multiples above commodity label production.
For Market Incumbents: Fortify adhesive technology portfolios through backward integration into acrylic emulsion production or captive supply agreements with German and Japanese chemical specialists. Digital-native entrants exploiting sub-five-thousand-unit run economics threaten mid-tier pharmaceutical contract manufacturers; defend by embedding inline finishing capabilities that compress turnaround times below challenger thresholds. Prioritize ECHA dossier maintenance as regulatory moat against qualification-timeline compression. For New Entrants and Emerging Players: FDA-registered adhesive fast-tracks offer penetration pathway into US pharmaceutical serialization upgrades, where incumbent qualification backlogs create temporary supply gaps. Target Indian food export processing facilities facing FSSAI-mandated nutritional disclosure expansion, where extended-content booklet label demand outpaces domestic converter capacity. Lead with digital-native production economics enabling economic runs below legacy minimum order quantities. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates seeking to divest non-core label operations amid portfolio rationalization pressures. Five-to-ten-year viability favors converters with established pharmaceutical qualification dossiers and software-integrated serialization platforms over commodity paper label producers. Watch Swissmedic and EMA extractable-leachable testing requirement expansions as inflection indicator for adhesive technology acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Adhesive Technology Acquisition | Secures ECHA-registered formulation portfolios against eighteen-month qualification barriers. |
| Digital Printing Infrastructure Deployment | Enables economic production below five thousand units for clinical-trial and craft beverage segments. |
| East Asian Export Hub Expansion | Captures multilingual compliance label demand from Vietnam and Thailand contract packaging operations. |
| Serialization Software Integration | Links variable-data printing with warehouse management systems for pharmaceutical track-and-trace mandates. |
| Sustainable Substrate Certification | Aligns with EU Green Deal recyclability disclosure requirements for premium brand procurement. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA drug labeling guidance documents, EMA regulatory submission databases, and customs trade flow records for substrate material imports. Interviews with pharmaceutical packaging operations managers, adhesive formulation chemists at German and Japanese suppliers, and procurement directors at East Asian contract manufacturers grounded demand-side validation. Top-down market sizing from global packaging expenditure flows triangulated against bottom-up capacity assessments at major converter facilities.
Segmentation dimensions modeled span product type, material chemistry, end-user vertical, and application purpose across the projection horizon. Product-type splits capture pressure-sensitive, shrink sleeve, in-mold, and heat transfer format economics. Material analysis tracks paper, plastic, metal, and fabric substrate displacement patterns. End-user verticals isolate pharmaceutical serialization upgrade cycles from food export compliance demands. CAGRs derive from volume-outcome modeling calibrated to regulatory deadline phasing and capacity expansion announcements.
Underlying assumptions cover EU Falsified Medicines Directive enforcement continuity, acrylic emulsion supply stability from German and Japanese producers, and East Asian export manufacturing growth persistence, with deviation risk concentrated in REACH adhesive reformulation timeline accelerations or naphtha cracking margin volatility. Revision becomes warranted when pharmaceutical serialization mandate delays or extended producer responsibility scheme implementations cross threshold visibility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Global Label Adhesive Market
Labels
Indicative Seals Market
Labels
Global Automotive Labels Market
Labels
GCC Labels and Release Liners Market
Labels
Printable Tags Market
Labels
Global Print and Apply Labeling and Labeling Equipment Market
Labels
ESD Protective Signage Labels Market
Labels
Laser Markable Labels Market
Labels
Glue-Applied Labels Market
Labels
Barcode Label Printer Market
Labels
Screen Print Label Market
Labels
Industrial Label Printers Market
Labels
Global QR Code Labels Market
Labels
Laser Printable Wristbands Market
Labels
Booklet Labels Market
Labels
Ripeness Indicator Labels Market