
 Tags Market | 2026-2036
Tags Market Size, Share, and Industry Trends Forecast 2026-2036
Tags Market Outlook
Direct-to-manufacturer channel strategy is tilting as Avery Dennison Corporation leverages its materials science portfolio to anchor premium adhesive label supply for apparel brands. Zebra Technologies Corporation dominates enterprise RFID deployments through sustained investment in printer-encoder systems. Brady Corporation specializes in industrial safety tags, occupying niches where chemical resistance specifications exceed commodity offerings.
Tags are identification substrates—paper, plastic, metal, or fabric—bearing printed, encoded, or embedded data for asset tracking, authentication, or consumer communication, typically manufactured through flexographic or digital printing with pressure-sensitive adhesive lamination. Their primary purpose spans inventory visibility, regulatory compliance labeling, and brand-consumer engagement across supply chains. Plastic and smart tags represent the fastest-expanding material and form factor pairing, as RAIN RFID inlays penetrate logistics and retail applications where real-time location data commands premium pricing. Paper hang tags retain volume leadership in fashion retail but face margin compression from sustainability-driven substrate shifts.
The FDA's Drug Supply Chain Security Act and the EU's MDR traceability requirements compel pharmaceutical and medical device manufacturers to adopt serialized, machine-readable tags, reshaping procurement specifications. REACH substance restrictions and California's Proposition 65 labeling mandates further constrain adhesive chemistry and ink formulations, elevating compliance costs for non-specialized converters. Stakeholders must monitor evolving Extended Producer Responsibility frameworks in Germany and France, where packaging tag recyclability will determine market access within the next regulatory cycle.
Market Dynamics
Serialized traceability mandates across pharmaceutical and medical device supply chains are compressing procurement cycles for machine-readable tags while simultaneously elevating technical specifications beyond commodity converter capabilities.
Growth Catalysts
- FDA Drug Supply Chain Security Act:Electronic tracking mandates for prescription drug distribution are accelerating RFID adoption in cold chain logistics networks.
- EU Green Deal packaging directives:Recyclability requirements are pushing European converters toward substrate innovation and adhesive chemistry reformulation.
- E-commerce fulfillment concentration:China's manufacturing belt is driving smart tag contract volumes for real-time inventory visibility systems.
Market Restraints
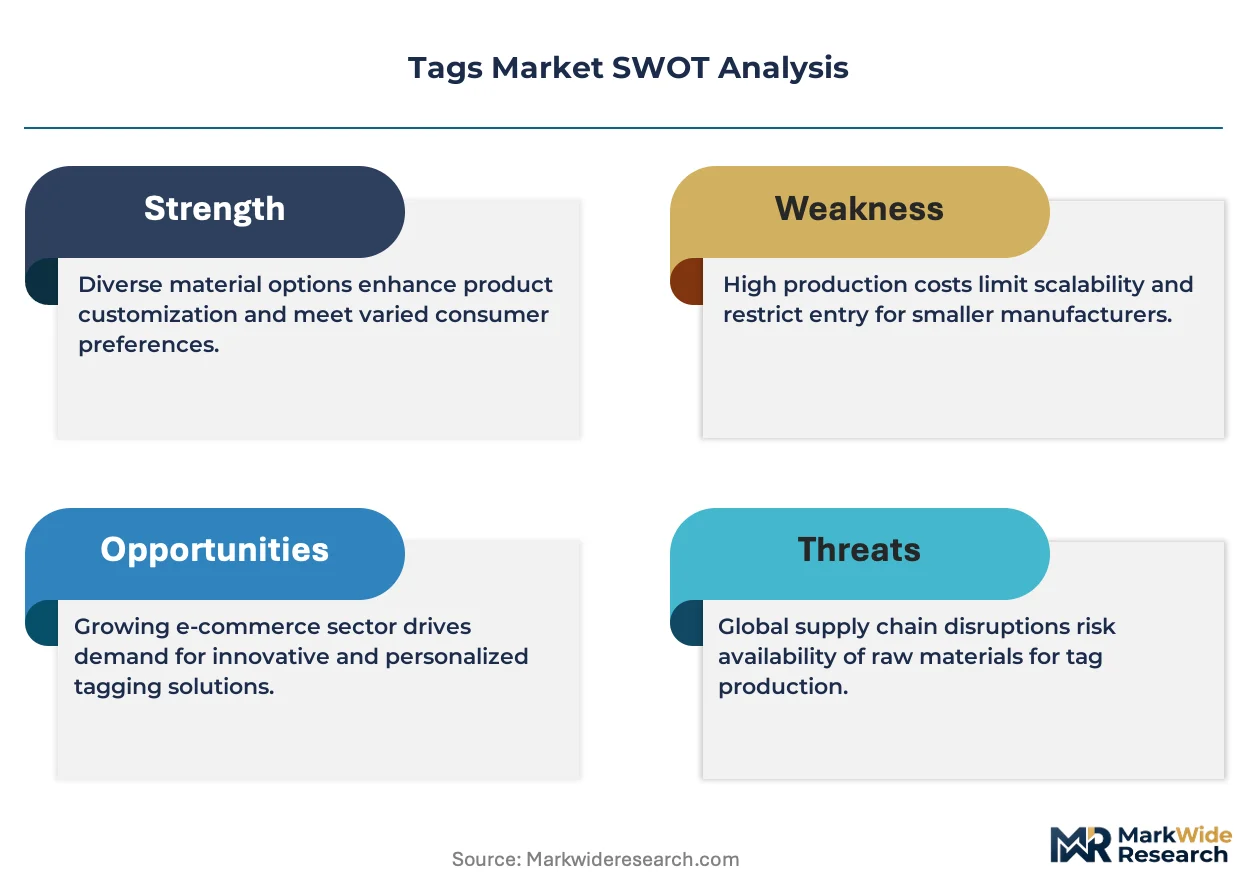
- Silicon wafer supply concentration:RAIN RFID inlay production depends on semiconductor foundry capacity concentrated in East Asia, exposing tag manufacturers to input volatility.
- REACH substance restrictions:European adhesive and ink chemistry constraints are elevating compliance costs for non-specialized converters.
- Digital watermark substitution:Imperceptible codes embedded in packaging graphics threaten to displace physical tags in premium brand authentication applications.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO traceability requirements for export-oriented drug production create untapped demand for serialized labels.
- Battery passport mandates:EU Battery Regulation digital product passports require durable tags for lithium-ion supply chain tracking.
- Near-field communication convergence:NFC-integrated smart packaging enables direct consumer engagement channels for CPG brands.
Industry Challenges
- Antenna design talent scarcity:RF engineering expertise for optimizing inlay performance across metal and liquid environments remains concentrated among specialized firms.
- Legacy warehouse management integration:Enterprise RFID deployments face friction from outdated WMS architectures incapable of processing real-time location data streams.
- California Proposition 65 labeling:Chemical disclosure requirements for adhesive components extend compliance timelines for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tags Market |
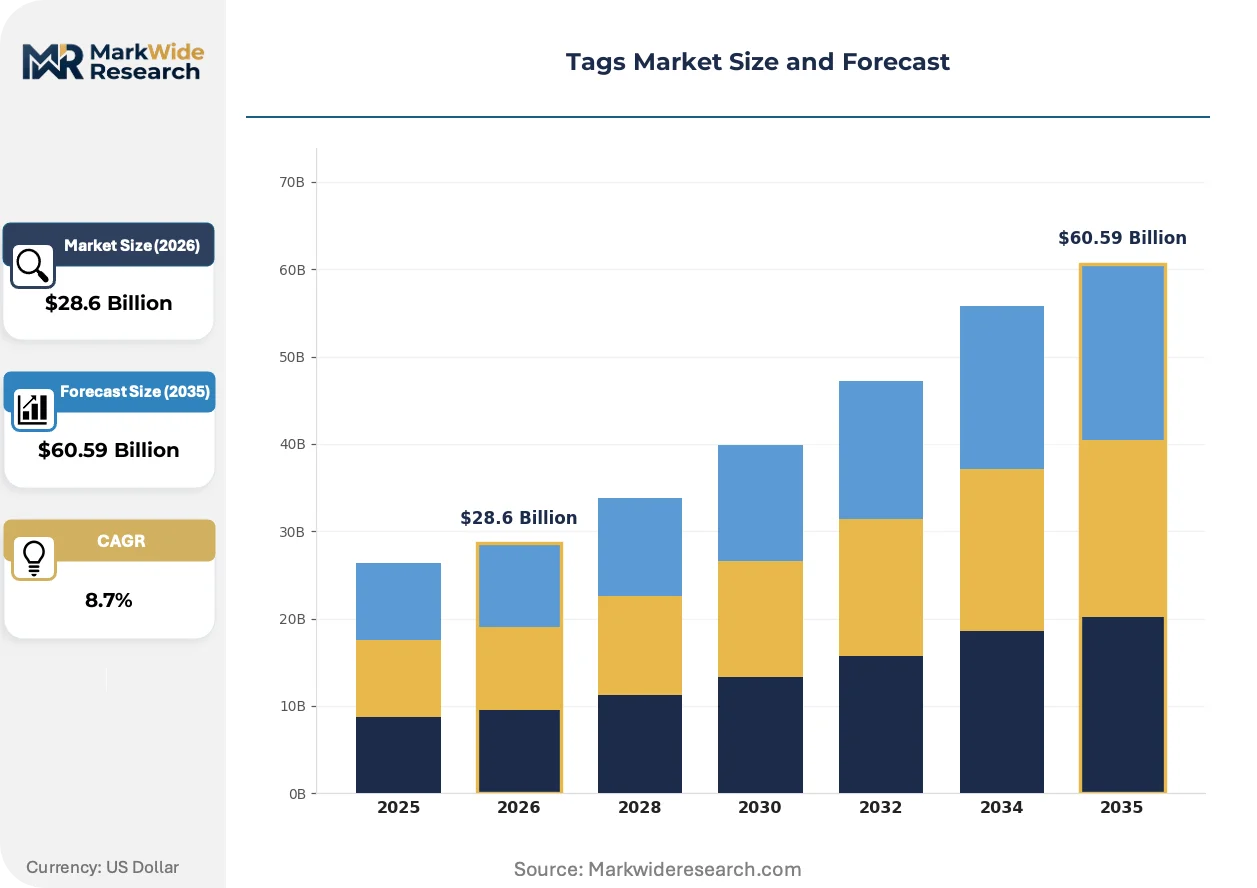
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Paper, Plastic, Metal, Fabric Application: Retail, Logistics, Manufacturing, Events Form Factor: Hang Tags, Adhesive Labels, Barcodes, Smart Tags Distribution Channel: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | Avery Dennison Corporation, Zebra Technologies Corporation, Brady Corporation, 3M, CCL Industries Inc., Honeywell International Inc., SATO Holdings Corporation, Camcode, Identiv, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tags Market Strategic Shifts
Material science breakthroughs and regulatory serialization mandates are converging to transform tag specifications from passive identifiers into active data collection nodes embedded across supply chain infrastructure.
Printed electronics utilizing conductive inks on flexible substrates is rendering obsolete traditional etched-copper RFID inlays in apparel and logistics applications. Retailers operating high-velocity fulfillment centers are adopting these lower-cost alternatives for item-level tracking. The shift compresses inlay manufacturing margins while expanding addressable volume for disposable single-use tags.
REACH substance restrictions on persistent organic pollutants are forcing adhesive reformulations across European converter operations. Manufacturers must qualify alternative chemistries that maintain bond strength across temperature extremes without prohibited phthalates or heavy metal catalysts. Medical device label suppliers face the steepest recertification burdens given biocompatibility requirements.
Direct-to-manufacturer procurement contracts are displacing distributor-mediated purchasing for enterprise RFID deployments. Automotive and aerospace OEMs are consolidating vendor bases to capture volume pricing and technical support integration. Germany's industrial manufacturing clusters exhibit the most advanced procurement centralization, with Tier 1 suppliers mandating unified tag specifications across component supply bases.
Tags Market Segmentation
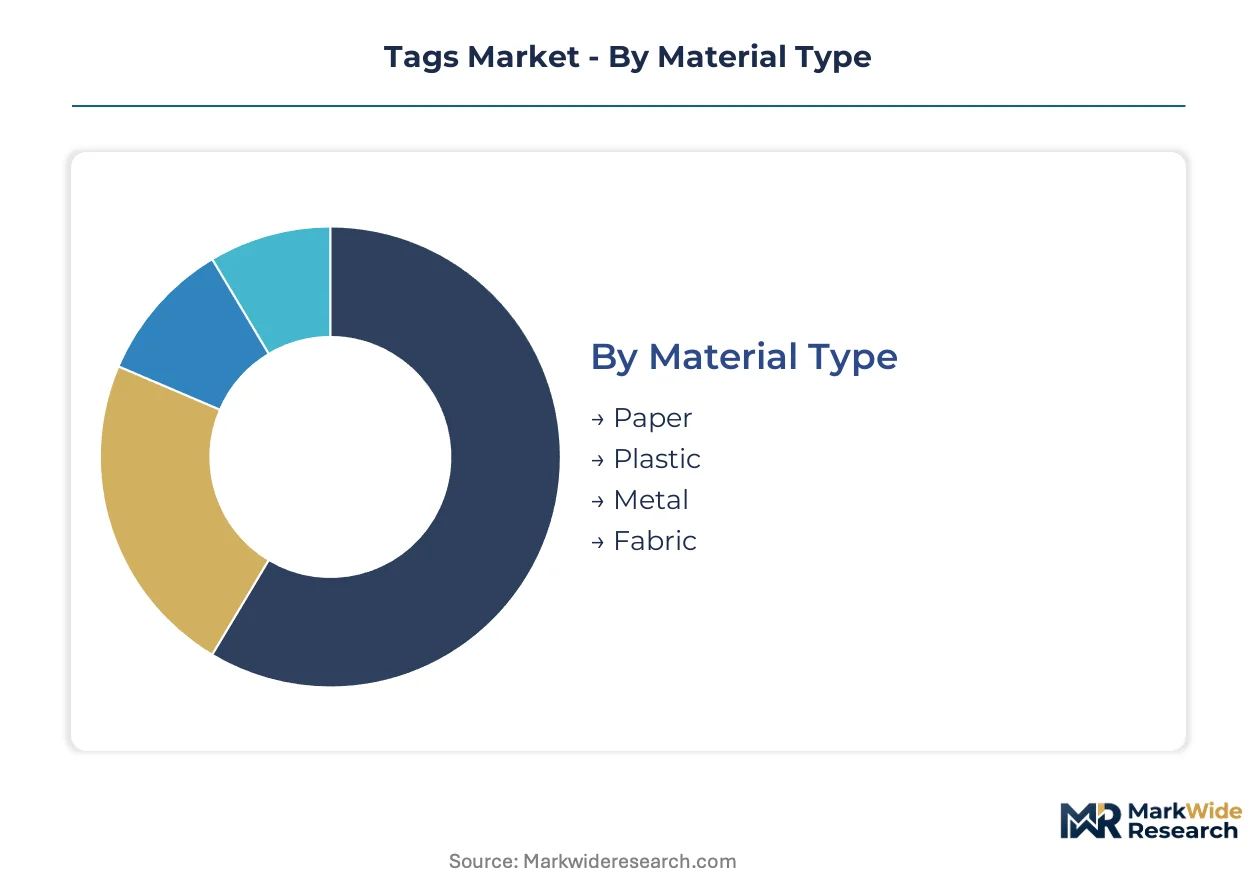
Segmentation in the tags market reveals divergent margin profiles and procurement cycles across substrate types and end-use applications. Understanding these distinctions enables suppliers to align production capacity with segments exhibiting favorable pricing power and technical specification stability.
Material Type:
Cycle times vary dramatically across substrates, with disposable paper tags turning inventory weekly while metal identification plates operate on multi-year replacement schedules.
- Plastic:Polypropylene and polyester substrates dominate logistics applications requiring moisture resistance and mechanical durability. Demand concentrates in e-commerce fulfillment centers across China and Germany where RAIN RFID inlays require flexible, printable bases that withstand automated handling systems.
- Paper:Cellulose-based substrates retain cost leadership for short-lifecycle apparel hang tags and promotional labeling. European fashion retailers are accelerating substrate shifts under EU Green Deal packaging directives, compressing volumes for virgin fiber products while expanding certified recyclable alternatives.
- Metal:Aluminum and stainless steel plates serve industrial asset tracking in aerospace and energy infrastructure where chemical resistance and multi-decade service life justify premium positioning.
- Fabric:Woven and printed textile tags attach to garments and soft goods through sewing or heat-transfer methods, occupying niches where substrate flexibility and wash durability exceed adhesive limitations.
Paper dominates installed base. Plastic is where expansion concentrates.
Application:
Cost tiers separate mission-critical pharmaceutical serialization from commodity retail price marking, with compliance-driven applications commanding three-to-five-fold specification premiums.
- Logistics:Real-time location tracking mandates across pharmaceutical cold chains and high-velocity fulfillment networks are accelerating RAIN RFID adoption. FDA Drug Supply Chain Security Act requirements and EU MDR traceability rules are elevating technical specifications beyond commodity converter capabilities.
- Retail:Item-level tagging for inventory accuracy and loss prevention drives volume in apparel and electronics. China's manufacturing belt exhibits the most concentrated smart tag contract activity as SATO Holdings and Zebra Technologies compete for e-commerce operator deployments.
- Manufacturing:Work-in-process tracking and quality control labeling require substrates resistant to harsh chemicals, temperature extremes, and mechanical abrasion.
- Events:Temporary access control and attendee identification utilize disposable wristbands and badges with minimal durability requirements and compressed procurement cycles.
Retail commands volume leadership. Logistics is climbing the fastest.
Form Factor:
Customer type stratification separates enterprise RFID deployments with integrated technical support from transactional purchases of standardized barcode labels.
- Smart Tags:RAIN RFID and NFC-enabled inlays embed semiconductor chips and printed antennas for wireless data transmission. Battery passport mandates under EU Battery Regulation and pharmaceutical serialization requirements are expanding addressable applications.
- Adhesive Labels:Pressure-sensitive constructions dominate shipping, product identification, and regulatory compliance marking across industrial and consumer goods sectors.
- Hang Tags:Suspended identification substrates remain prevalent in fashion retail for branding and pricing, though sustainability-driven substrate shifts are compressing margins for conventional offerings.
- Barcodes:Linear and two-dimensional optical codes persist in cost-sensitive applications where automated data capture requirements remain limited.
Adhesive labels dominate installed base. Smart tags is where expansion concentrates.
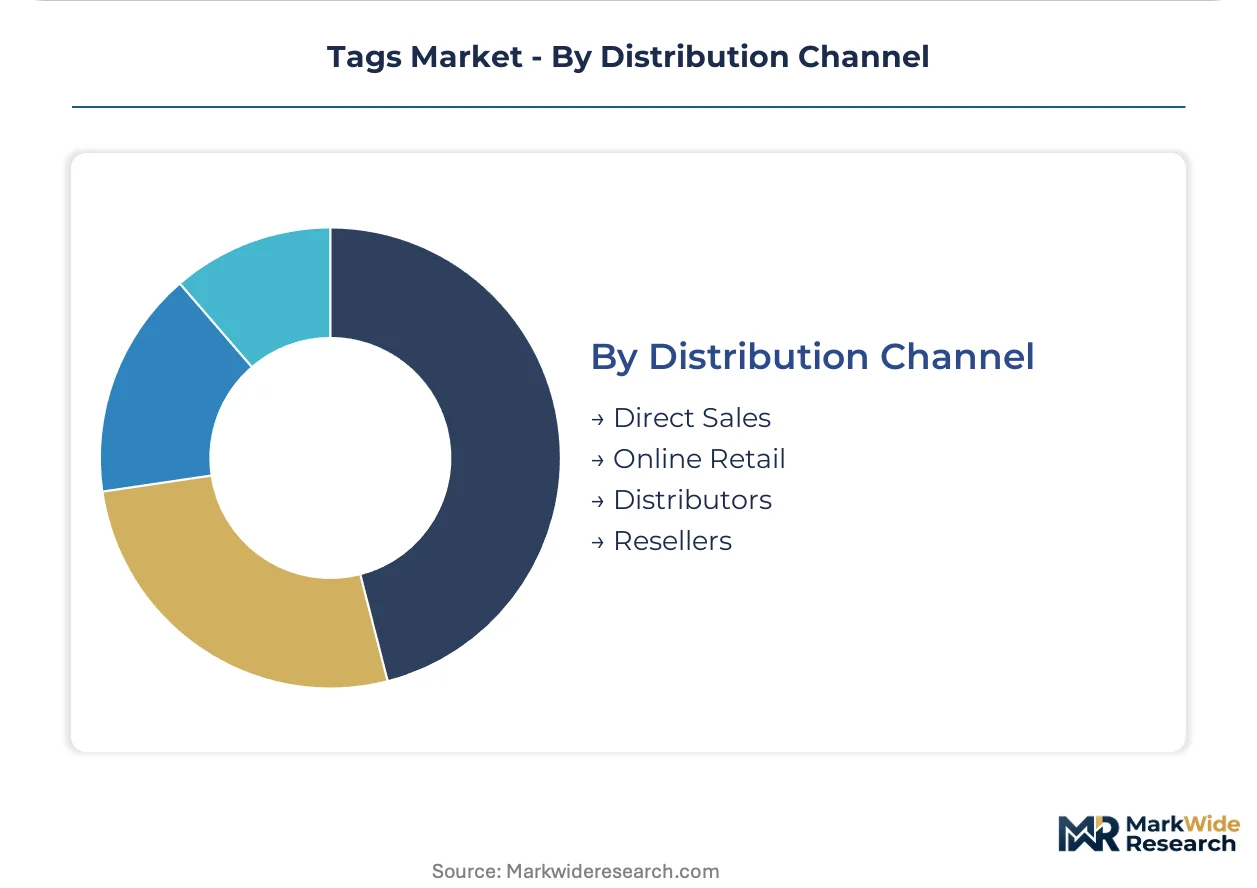
Distribution Channel:
Supply concentration favors direct relationships with large-scale deployers, while fragmented end-user bases sustain distributor and reseller intermediation.
- Direct Sales:Enterprise RFID deployments and pharmaceutical serialization contracts route through manufacturer-direct channels. Automotive and aerospace OEMs in Germany's industrial clusters are consolidating vendor bases to capture volume pricing and unified technical support.
- Distributors:Broad-line industrial supply houses serve mid-market manufacturers with standardized label products and localized inventory availability.
- Online Retail:E-commerce platforms capture transactional purchases of desktop printer supplies and small-format labeling equipment for SMB end users.
- Resellers:Value-added partners integrate tags with software systems and installation services, occupying niches where solution bundling commands premium positioning.
Distributors dominate installed base. Direct sales is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA serialization mandates anchor the United States as the regulatory reference point for pharmaceutical tag specifications. Demand clusters concentrate in three distinct geographies with divergent substrate preferences and compliance frameworks.
United States
Pharmaceutical cold chain logistics drives RAIN RFID adoption as the FDA Drug Supply Chain Security Act mandates electronic tracking for prescription drug distribution. California's Proposition 65 labeling requirements constrain adhesive chemistry formulations for tags entering consumer goods supply chains. The Midwest manufacturing corridor hosts concentrated demand from automotive and aerospace OEMs consolidating vendor bases for unified technical specifications.
Germany
EU Green Deal packaging directives accelerate substrate shifts toward recyclable alternatives across industrial converter operations. REACH substance restrictions on persistent organic pollutants force adhesive reformulations that maintain bond strength across temperature extremes. The Baden-Württemberg industrial cluster exhibits the most advanced procurement centralization, with Tier 1 suppliers mandating standardized tag specifications across component supply bases.
China
E-commerce fulfillment operators in the Yangtze River Delta and Pearl River Delta drive smart tag contract volumes for real-time inventory visibility systems. SAMR standardization initiatives align domestic traceability requirements with export market specifications for pharmaceutical and consumer goods sectors. SATO Holdings and Zebra Technologies compete directly for manufacturing belt contracts where automated handling systems demand flexible, printable substrates.
India
CDSCO traceability requirements for export-oriented pharmaceutical production create untapped demand for serialized labels and machine-readable authentication substrates. The PLI scheme for electronics manufacturing attracts component assembly operations that require work-in-process tracking tags resistant to harsh chemicals. Maharashtra and Gujarat host the densest converter capacity serving both domestic retail and export logistics applications.
Japan
METI industrial digitization programs promote RFID adoption for manufacturing traceability and quality control labeling across automotive and electronics supply chains. JIS standards for data carriers ensure interoperability between domestic and international logistics networks. The Chubu region around Nagoya anchors precision manufacturing demand for substrates resistant to temperature extremes and mechanical abrasion.
Tags Market Competitive Environment
Materials science specialists and enterprise systems integrators split the market between premium adhesive formulations and printer-encoder hardware ecosystems. Consolidation pressure concentrates among mid-scale converters lacking in-house RF engineering capabilities. Three archetypes dominate: diversified materials conglomerates with adhesive chemistry portfolios, industrial identification specialists with vertical application expertise, and semiconductor-enabled smart tag developers with antenna design capabilities. M&A activity targets specialized RFID engineering talent, while capacity expansion focuses on printed electronics lines for lower-cost disposable inlays.
Within the materials science tier, Avery Dennison Corporation anchors premium adhesive label supply through sustained investment in substrate innovation and sustainability certification. Zebra Technologies Corporation exemplifies the enterprise systems integrator archetype, dominating printer-encoder deployments through technical support integration with warehouse management architectures. Brady Corporation occupies the industrial safety specialist position, serving niches where chemical resistance specifications exceed commodity converter capabilities.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| Zebra Technologies Corporation |
| Brady Corporation |
| 3M |
| CCL Industries Inc. |
| Honeywell International Inc. |
| SATO Holdings Corporation |
| Camcode |
| Identiv, Inc. |
| Others |
Value Chain & Pricing Dynamics
Semiconductor foundry capacity concentrated in Taiwan and South Korea feeds directly into margin pools downstream, where RAIN RFID inlay manufacturers with captive antenna design capabilities capture specification premiums unavailable to commodity converters.
Pricing Analysis
Price spreads between European and Asian supply sources widen during periods of wafer shortage, with three-tier pricing structure across premium, standard, and economy levels separating pharmaceutical serialization contracts from logistics commodity volumes. Certification grade under FDA Drug Supply Chain Security Act and EU MDR traceability rules commands three-to-five-fold premiums over standard adhesive labels. Cost compression in paper hang tags intensifies as EU Green Deal recyclability mandates force substrate reformulation. E-commerce fulfillment operators in China exhibit the highest price sensitivity, while pharmaceutical cold chain logistics buyers prioritize technical compliance over unit cost.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk planning for RAIN RFID inlay production, where semiconductor chip sourcing draws from Taiwan, South Korea, and Japan. Conductive ink formulations and flexible substrate films rest on petrochemical feedstocks from Germany and Saudi Arabia. Single-source vulnerability concentrates in antenna etching equipment anchored in Japanese precision manufacturing. Distribution runs through direct manufacturer relationships for enterprise RFID deployments, with distributor intermediation sustaining mid-market label volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tags market represents early-cycle expansion as pharmaceutical serialization mandates and battery passport regulations under EU Battery Regulation create structural demand for machine-readable identification substrates.
For Market Incumbents: Pre-empt margin erosion in paper hang tags by accelerating certified recyclable substrate portfolios ahead of Extended Producer Responsibility enforcement in Germany and France. Backward integration into conductive ink formulation secures supply continuity during REACH substance restriction transitions. Antenna design talent scarcity among mid-scale converters presents acquisition opportunities to consolidate RF engineering capabilities.
For New Entrants and Emerging Players: Establish a beachhead in Indian pharmaceutical serialization, where CDSCO traceability requirements for export-oriented drug production remain underpenetrated by established RFID deployers. Battery passport mandates for lithium-ion supply chain tracking offer a second white-space target with durable tag specifications exceeding commodity converter capabilities. Partner with regional converter networks to bypass direct sales channel investments.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed industrial identification specialists lacking in-house printed electronics capabilities. Long-term viability hinges on exposure to regulatory-mandated serialization rather than discretionary retail branding spend. Watch FDA enforcement timelines for Drug Supply Chain Security Act compliance deadlines as the inflection indicator for pharmaceutical tag demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Printed Electronics Capacity Expansion | Lowers RAIN RFID inlay production costs for apparel and logistics disposable tracking applications. |
| Adhesive Chemistry Reformulation | Qualifies alternative bond formulations eliminating REACH-restricted phthalates for European market access. |
| Direct-to-Manufacturer Channel Development | Captures pharmaceutical serialization contracts with unified technical support integration requirements. |
| Antenna Design Specialist Acquisition | Consolidates scarce RF engineering talent for optimizing inlay performance across metal and liquid environments. |
| Battery Passport Tag Development | Positions for EU Battery Regulation digital product passport mandates in lithium-ion supply chains. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA enforcement documentation, EMA regulatory submissions, SAMR standardization notices, and converter capacity disclosures. Primary interviews engaged RFID engineering directors at inlay manufacturers, procurement leads at pharmaceutical logistics operators, adhesive chemistry specialists at materials suppliers, and technical sales executives at printer-encoder system vendors. Secondary validation drew from customs trade data, SEC 10-K filings of listed identification technology firms, and REACH substance restriction updates. Bottom-up volume modeling triangulated against top-down market sizing across material type, application, and form factor dimensions.
Forecast inputs span RAIN RFID adoption curves in pharmaceutical cold chains, e-commerce fulfillment automation penetration rates, and regulatory compliance deadline schedules. Segmentation modeling incorporates material substrate, end-use application, form factor technology, and distribution channel dynamics. CAGRs derive from volume trajectory analysis across the projection horizon, with specific weighting applied to EU Green Deal implementation pace and FDA serialization enforcement intensity.
Sensitivities concentrate around semiconductor foundry capacity allocation shifts and REACH substance restriction expansion timelines. Forecasts embed assumptions regarding regulatory compliance adoption curves and substrate substitution elasticities. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Indicative Seals Market
Labels
HAZMAT Labels Market
Labels
Global Label Adhesive Market
Labels
Canning Labels Market
Labels
Shrink Sleeve Labels Market
Labels
Laser Printable Wristbands Market
Labels
Pin Feed Labels Market
Labels
Polyester Labels Market
Labels
Global in-Mold Labels Market
Labels
Stand Alone Label Applicator Market
Labels
Thermal Labels Market
Labels
Direct Thermal Labels Market
Labels
Healthcare and Laboratory Labels Market
Labels
Roll-fed Wraparound Label Substrates Market
Labels
Warning Labels and Stickers Market
Labels
Self-Laminating Tags Market