
 Stout Market | 2026-2036
Stout Market Size, Share, and Industry Trends Forecast 2026-2036
Stout Market Intelligence
Advanced nitrogenation for packaged products is narrowing the quality gap between draft and at-home consumption. This technological shift allows major brewers to extend premium experiences far beyond the traditional pub environment. Diageo plc leverages its historical dominance with Guinness to set benchmarks in nitrogenated stout quality. Anheuser-Busch InBev SA/NV competes through its vast portfolio of craft and international brands, while The Boston Beer Co. Inc. specializes in experimental and high-gravity releases.
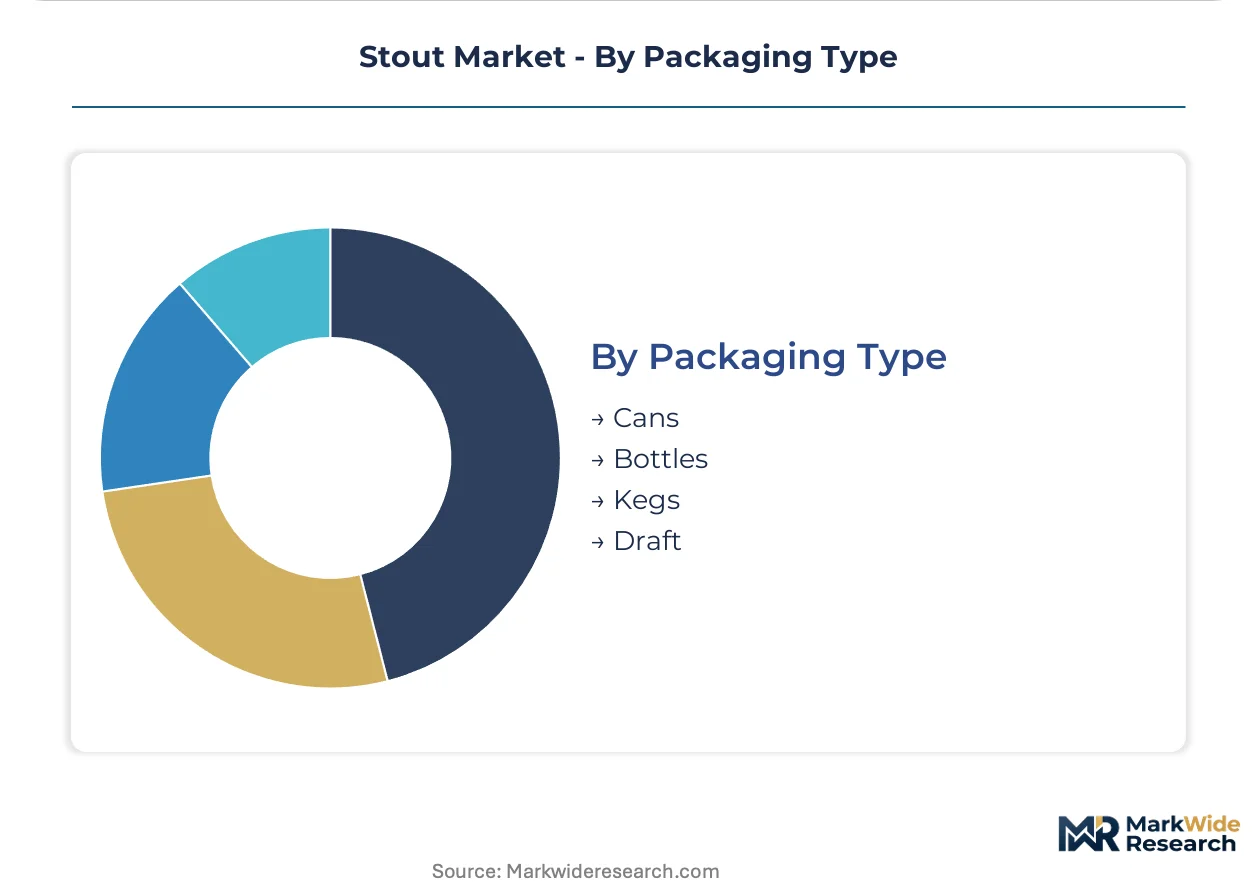
Stout is a top-fermented beer style defined by its dark color and creamy head, derived from the use of roasted malt or barley. It delivers a rich, complex flavor profile, often featuring roasted or coffee notes, for consumers seeking a full-bodied beverage. Within product types, Imperial Stout commands premium pricing due to higher alcohol content and aging potential. The packaging mix shows Cans gaining significant share from Bottles, driven by craft brewer preferences for better flavor preservation and consumer convenience.
Producers must navigate a complex web of national regulations governing alcohol content, labeling, and advertising. Food safety standards enforced by bodies like the US FDA and the European Food Safety Authority (EFSA) dictate production hygiene and ingredient sourcing. Future success depends on a brewer's ability to balance traditional stout profiles with novel flavor innovations to attract new consumer demographics.
Market Dynamics
The central force shaping the stout market is the expansion of brewing technology that enables draft-quality experiences in packaged formats. This innovation is decentralizing premium consumption from the pub to the home, fundamentally altering distribution strategies and consumer expectations.
Growth Catalysts
- Nitrogen-Infusion Technology:The integration of nitrogen widgets into cans allows for the recreation of a creamy draft head at home, expanding the market for premium at-home consumption experiences.
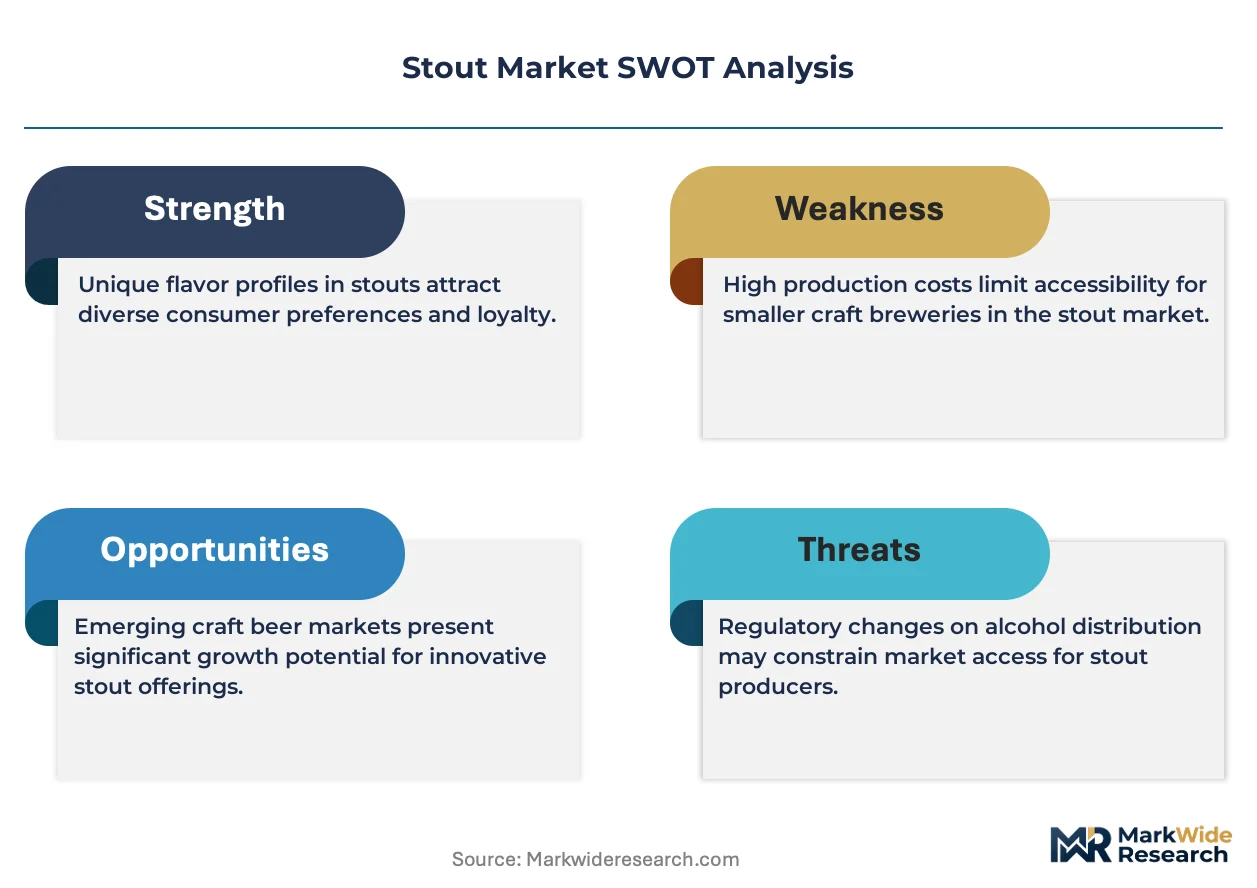
- Craft Beer Culture:The proliferation of craft breweries, particularly in the United States, fosters a culture of experimentation and connoisseurship that introduces new consumers to diverse stout styles.
- On-Premise Specialization:The rise of gastropubs and specialty beer bars creates curated environments where consumers can explore a wide range of premium and niche stouts, driving trial and education.
Market Restraints
- Input Price Volatility:Brewers are exposed to price fluctuations for critical ingredients like specialty roasted malts and specific hop varieties, which can compress margins on premium products.
- Substitution from Other Beverages:Stouts face competition from a growing array of dark, rich beverages, including hard coffee, cold brew concentrates, and dark lagers, which appeal to similar flavor preferences.
- Distribution Complexity:In geographies like the United States, the mandatory three-tier system creates significant hurdles for small brewers, limiting market access and increasing go-to-market costs.
Strategic Opportunities
- Emerging Craft Markets:There is significant white space for stout penetration in developing craft beer scenes, such as in Brazil and Poland, where consumer interest in diverse beer styles is growing.
- Low and Non-Alcoholic Formulations:Developing flavorful low-ABV or alcohol-free stouts can attract health-conscious consumers and open up consumption occasions where full-strength alcohol is not appropriate.
- Barrel-Aging Programs:Utilizing ex-bourbon, rum, or wine barrels for aging stouts allows for the creation of high-value, limited-edition products that command premium prices and attract discerning consumers.
Industry Challenges
- Barrel-Aging Consistency:Managing the inherent variability of wood barrels to produce a consistent, high-quality aged stout requires significant expertise in blending and quality control, posing an operational hurdle.
- Cold Chain Logistics:Maintaining the integrity of flavor-sensitive and nitrogenated stouts requires an unbroken cold chain from the brewery to the consumer, adding significant cost and complexity to logistics.
- International Compliance:Exporting requires brewers to navigate a patchwork of international regulations, including differing food safety standards from the US FDA and the European EFSA, complicating global expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stout Market |
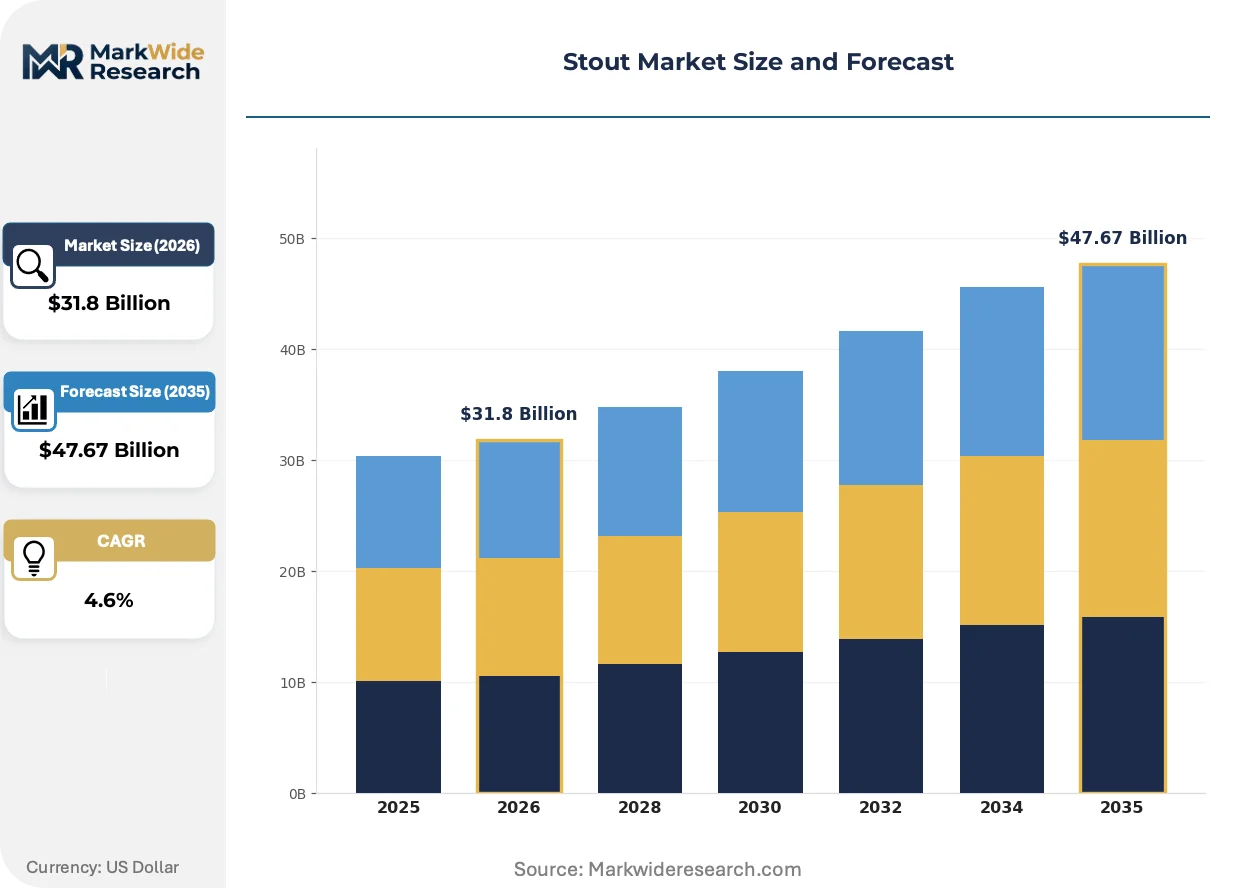
| Market Size in 2026 | $31.8 Billion |
| Market Size in 2035 | $47.67 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imperial Stout, Milk Stout, Oatmeal Stout, Russian Imperial Stout Ingredient: Barley, Hops, Yeast, Water Flavor Profile: Chocolate, Coffee, Caramel, Roasted Packaging Type: Cans, Bottles, Kegs, Draft |
| Companies Covered | Carlsberg Breweries A/S, Asahi Group Holdings Ltd., Diageo plc, The Boston Beer Co. Inc., Kirin Brewery Co. Ltd., Anheuser-Busch InBev SA/NV, Molson Coors Beverage Co., Stone Brewing Co., Heineken N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stout Market Strategic Shifts & Innovations
Technological advancements in brewing and packaging are converging with evolving consumer tastes to redefine the stout category. This is pushing producers to balance deep-rooted traditions with a demand for novelty, creating a more dynamic and segmented market landscape.
Advanced bio-engineered yeast strains and targeted enzymes provide brewers with precise control over flavor and aroma development. Craft and large-scale breweries are adopting these tools to reliably create specific notes like coffee or chocolate without using traditional adjuncts. This precision fermentation capability is rendering obsolete the sole reliance on complex grain bills and less predictable ingredients for achieving desired flavor profiles.
Evolving regulations around nutritional transparency, particularly in the European Union and under consideration by the US TTB, are mandating clearer labeling. This development forces brewers to disclose caloric and ingredient information, impacting consumer choice for traditionally dense styles like Imperial or pastry stouts. Consequently, the high-gravity stout segment is most affected, with some producers exploring reformulation or new marketing approaches to align with health-aware trends.
Consumption patterns are shifting away from conventional retail toward direct-to-consumer (DTC) and taproom-exclusive sales models. This trend allows brewers to bypass traditional distribution tiers, capture higher margins, and cultivate direct relationships with their most dedicated customers. The movement is most visible in the United States craft sector, where limited-edition barrel-aged stouts are frequently sold through online lotteries or at exclusive brewery events.
Stout Market Segmentation
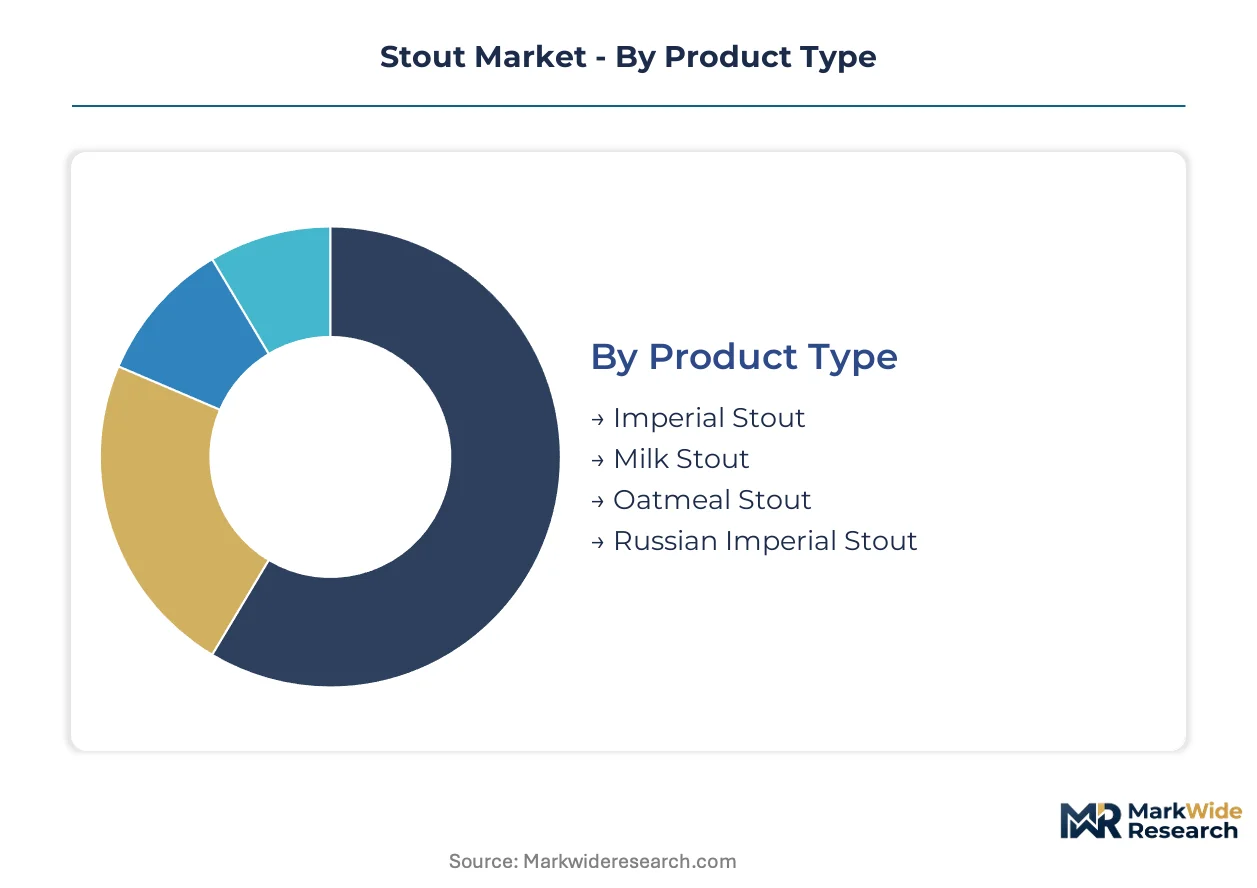
The stout market is characterized by diverse product offerings and consumption patterns, necessitating a detailed segmentation to understand underlying demand drivers. Analyzing these segments helps brewers tailor product development, optimize distribution channels, and refine marketing strategies to reach specific consumer groups effectively.
Product Type:
The diversity of stout product types reflects both historical traditions and modern brewing innovations, catering to a broad spectrum of consumer tastes and occasions.
- Imperial Stout:This high-alcohol stout features a robust, intense flavor profile, often with notes of dark fruit, chocolate, or coffee, and benefits from extended aging. Demand concentrates in the craft segment in the United States, where consumers seek premium, high-gravity expressions.
- Milk Stout:Characterized by the addition of lactose sugar, milk stouts offer a sweeter, creamier mouthfeel and reduced bitterness, appealing to a broader consumer base. This style finds strong demand in traditional markets like the United Kingdom and Ireland, attracting new stout drinkers.
- Oatmeal Stout:Brewed with a proportion of oats, this stout style provides a silky smooth texture and a full body, often with subtle roasted malt characteristics. It maintains a steady presence in established stout-drinking regions.
- Russian Imperial Stout:A historically strong and dark ale, this variant is known for its complex, rich flavors and significant alcohol content, often aged to develop further nuance.
Imperial Stout holds installed capacity. Milk Stout is rotating up the share rankings.
Ingredient:
Supply concentration for key ingredients directly influences the flavor profiles and cost structures of stout production across all market tiers.
- Barley:Roasted barley and malted barley form the backbone of stout's dark color and characteristic roasted, coffee, or chocolate notes, defining its core identity. Demand for specialty roasted malts is high among craft brewers in Europe, who prioritize unique flavor complexity.
- Hops:Hops contribute bitterness to balance the malt sweetness and can introduce aromatic elements, though their role in stouts is typically less prominent than in other beer styles. Craft brewers in the United States increasingly experiment with diverse hop varieties for subtle aromatic contributions.
- Yeast:Specific yeast strains are crucial for fermentation, influencing the final alcohol content, ester profiles, and overall flavor development of the stout. Brewers select strains for desired fermentation characteristics.
- Water:The mineral composition of brewing water significantly impacts the flavor and mouthfeel of stout, with regional water profiles often dictating traditional styles.
The availability of specialty barley drives much of the flavor innovation. Hops are gaining share in experimental stout recipes.
Flavor Profile:
Customer preferences are segmenting the market by flavor profile, with specific taste attributes driving purchasing decisions across different demographics.
- Coffee:Stouts with prominent coffee notes, often achieved through roasted malts or direct coffee additions, appeal to consumers seeking bold, aromatic, and sometimes breakfast-appropriate beverage experiences. This profile sees strong demand in the United States for at-home consumption, aligning with premiumization trends.
- Chocolate:Stouts featuring chocolate flavors, derived from dark malts or cocoa adjuncts, cater to consumers looking for rich, dessert-like, and indulgent beverage options. The chocolate profile is popular in the United Kingdom, where flavor experimentation is common.
- Caramel:Caramel notes in stout typically originate from crystal malts, providing a sweet, toffee-like complexity that balances the roasted characteristics. This profile appeals to consumers preferring a sweeter, smoother stout.
- Roasted:The fundamental roasted flavor profile, stemming from specialty roasted barley, defines traditional stouts and appeals to purists seeking classic, full-bodied expressions.
Coffee-infused stouts are expanding most quickly. Chocolate notes also command significant consumer interest.
Packaging Type:
Volume distribution is increasingly shaped by packaging innovations, which are adapting to evolving consumer lifestyles and consumption environments.
- Cans:Modern canning technologies, including nitrogen widgets, allow stouts to maintain freshness and offer a draft-like experience for at-home consumption, driving significant market share gains. Cans are particularly popular in the United States, favored for convenience and product integrity.
- Bottles:Bottles remain a traditional packaging choice for stouts, especially for premium, high-alcohol, or barrel-aged varieties intended for cellaring and special occasions. Bottles are prevalent in European markets for their perceived quality.
- Kegs:Kegs serve the on-premise market, supplying bars, restaurants, and taprooms with fresh draft stout for immediate consumption. Kegs are essential for gastropubs in the United Kingdom and Ireland.
- Draft:Draft systems provide the traditional pub experience, delivering fresh, perfectly carbonated or nitrogenated stout directly from kegs. This format is crucial for on-premise specialization.
Cans are gaining significant share in retail channels. Draft remains critical for on-premise experiences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The flow of specialty ingredients from Europe to North America underpins much of the global stout market. This trade ensures access to specific malt varieties crucial for traditional and innovative stout profiles. Consumer preferences for diverse stout styles drive demand across several key regions.
United Kingdom
United Kingdom consumers maintain a strong affinity for traditional stouts, particularly milk stouts. The UK government's alcohol duty reforms influence pricing and product accessibility for brewers. London's vibrant pub scene and regional breweries in areas like Manchester concentrate product innovation and consumption.
Ireland
Ireland represents a foundational market for stout consumption, with deeply ingrained cultural ties to the beverage. Irish excise duties and licensing laws significantly shape the market for both local and imported stouts. Dublin remains a central hub for stout production and consumption, influencing global brand standards.
United States
The United States market experiences rapid expansion in craft stout varieties, driven by consumer interest in experimental flavors. Regulations from the US TTB govern alcohol content and labeling, impacting product development. Craft brewing clusters in regions like the Pacific Northwest and New England foster significant innovation.
Germany
German brewers increasingly explore stout styles, moving beyond traditional lagers, with a focus on quality ingredients. Food safety standards enforced by the European EFSA dictate production hygiene for all brewers. Munich and Berlin are emerging centers for craft beer culture, introducing new stout interpretations.
Brazil
Brazil shows significant white space for stout penetration as its craft beer scene matures. National health and safety regulations, enforced by ANVISA, oversee all beverage production. São Paulo and Rio de Janeiro lead in craft brewery development, attracting new consumers to diverse beer styles.
Stout Market Key Industry Players
Channel-controlling players compete with product-specialist players across the global stout market. This market exhibits a tiered structure, with large multinational brewers alongside numerous craft producers. Strategic archetypes include global brand consolidators, regional craft innovators, and niche flavor specialists. Dominant competitive moves involve portfolio diversification and geographic expansion to capture new consumer segments.
Among global brewing giants, Diageo plc and Anheuser-Busch InBev SA/NV represent established players with extensive distribution networks. Diageo plc leverages its historical dominance in traditional stout markets. Anheuser-Busch InBev SA/NV competes through a vast portfolio encompassing both international brands and craft acquisitions. The Boston Beer Co. Inc. exemplifies a specialist in experimental and high-gravity releases within the craft segment.
| Leading Market Players |
|---|
| Carlsberg Breweries A/S |
| Asahi Group Holdings Ltd. |
| Diageo plc |
| The Boston Beer Co. Inc. |
| Kirin Brewery Co. Ltd. |
| Anheuser-Busch InBev SA/NV |
| Molson Coors Beverage Co. |
| Stone Brewing Co. |
| Heineken N.V. |
| Others |
Cost & Logistics Intelligence
Specialty roasted malts, primarily sourced from Europe, concentrate flavor innovation and directly influence the premium pricing potential of craft stouts. This upstream dependency shapes the cost structure for brewers, particularly those targeting high-gravity or experimental styles, where unique ingredient profiles command higher market value.
Pricing Analysis
The advanced nitrogen-infusion technology for packaged stouts creates a significant pricing gap, allowing premium products to command higher prices at retail compared to traditional bottled stouts. Pricing stratifies across premium, standard, and economy tiers, with craft and Imperial Stouts at the higher end due to specialized ingredients and longer aging. Brand premium and the quality grade of ingredients drive price differentiation. Input price volatility, particularly for specialty malts, compresses margins for producers, especially in the standard segment. Consumers in the craft segment exhibit lower price sensitivity for unique or limited-edition stouts, while mainstream buyers prioritize value.
Supply Chain Analysis
The procurement of specialty barley varieties from Europe and experimental hops from the United States forms the upstream core of the stout supply chain. Raw material dependencies include specialty roasted malts, specific hop varieties, and nitrogen widgets for advanced packaging. Input price volatility for these critical ingredients poses a structural risk to brewer profitability. Distribution runs through a complex three-tier system in the United States, adding costs and limiting market access for small brewers. In Europe, direct on-premise supply to gastropubs and specialty taprooms remains a key distribution model.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The stout market presents a fragmentation opportunity, driven by evolving consumer tastes for novel flavor innovations and diverse consumption occasions. Brewers can capitalize on these shifts by targeting specific niches with tailored product offerings.
For Market Incumbents:Insulate core market share by investing in advanced nitrogenation technology for packaged products, ensuring a consistent draft-like experience for at-home consumption. Diversify portfolios with low and non-alcoholic stout formulations to attract health-conscious consumers and expand consumption occasions. This strategy mitigates the threat of substitution from other dark beverages and leverages existing channel control within established markets. Focus on efficiency gains in production to offset input price volatility.
For New Entrants and Emerging Players:Underpenetrated craft beer scenes in Brazil and Poland offer significant entry points for new stout producers. Target consumers seeking novel flavor innovations, particularly in coffee or chocolate profiles, which command significant interest. The most penetrable segment involves developing unique barrel-aged stouts or experimental high-gravity releases. A direct-to-consumer sales model, leveraging online lotteries or exclusive brewery events, provides an effective go-to-market angle, bypassing traditional distribution complexities.
For Investors and Strategic Acquirers:Capital is best deployed toward regional craft innovators with strong direct-to-consumer channels and proven expertise in barrel-aging programs. The long-term viability of the stout market rests on sustained consumer interest in premium, experimental, and flavor-diverse offerings. Target niche flavor specialists or craft breweries with established reputations for quality and innovation. The sustained growth in low and non-alcoholic stout sales represents a key signal to watch as an inflection indicator for future market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Nitrogenation Technology | Enhances at-home consumption experience, narrowing the quality gap between draft and packaged stouts. |
| Develop Low and Non-Alcoholic Stouts | Attracts health-conscious consumers and expands consumption occasions beyond traditional alcoholic settings. |
| Expand Barrel-Aging Programs | Creates high-value, limited-edition products that appeal to discerning consumers and drive premium pricing. |
| Target Emerging Craft Markets | Captures new consumer segments in developing regions with growing interest in diverse beer styles. |
| Strengthen Direct-to-Consumer Channels | Increases margin capture and fosters direct relationships with dedicated customers, bypassing traditional distribution. |
Research Approach
Findings reconcile primary fieldwork against secondary review of industry reports, government publications, and company financial statements. Primary research involved in-depth interviews with master brewers, craft brewery owners, distribution managers, and marketing directors across key regions. This approach ensured a comprehensive understanding of market dynamics, triangulating insights from both top-down market analysis and bottom-up operational perspectives. Data from US FDA filings, EFSA reports, and industry trade association publications provided crucial secondary validation.
Forecast inputs considered include consumer spending patterns, technological advancements in brewing, and evolving regulatory landscapes. The analytical framework integrated quantitative models with qualitative insights and historical market data to project future trends across the analysis window. Segmentation dimensions modeled included product type, ingredient, flavor profile, packaging type, and regional consumption trends. Compound annual growth rates were derived from an assessment of market dynamics, competitive intensity, and consumer demand shifts, incorporating factors like nitrogenation adoption rates and craft beer penetration rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by global brand consolidators or regional craft innovators would shift outcomes. Forecasts reflect assumptions regarding input price stability and the rate of new beverage substitutes entering the market. Cross-checking against national alcohol consumption statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Hookah Charcoal Market
Alcoholic Beverages
South America Fermented Drinks Market
Alcoholic Beverages
Rice Wine Market
Alcoholic Beverages
Premixed Margarita Market
Alcoholic Beverages
Alcohol Enzymes Market
Alcoholic Beverages
Asia-Pacific Alcohol E-Commerce Market
Alcoholic Beverages
Vodka Seltzer Market
Alcoholic Beverages
Wine Filtering Machine Market
Alcoholic Beverages
Mushroom Beer Market
Alcoholic Beverages
Pre-Mixed/RTD Alcoholic Drinks Market
Alcoholic Beverages
Asia-Pacific Wine Market
Alcoholic Beverages
Malaysia Alcohol E-Commerce Market
Alcoholic Beverages
Saffron Beer Market
Alcoholic Beverages
Organic Wine Market
Alcoholic Beverages
Cannabis-Based Alcoholic Beverages Market
Alcoholic Beverages
Distilled Spirits Market