
 Vodka Seltzer Market | 2026-2036
Vodka Seltzer Market Size, Share, and Industry Trends Forecast 2026-2036
Vodka Seltzer Market Analytics
Cane sugar is broadening its role as a premium sweetener base, displacing high-fructose corn syrup across mid-tier and craft-positioned vodka seltzer lines. Diageo leverages its spirits infrastructure to secure consistent ethanol supply for captive seltzer production. Boston Beer Company anchors its position through dedicated hard seltzer brewing capacity and direct-store-distribution muscle. Molson Coors Beverage Company competes via licensed vodka partnerships that bypass capital-heavy distillation investments.
Vodka seltzer denotes a carbonated, ready-to-drink beverage combining distilled vodka with filtered water and natural or artificial flavoring, typically packaged in aluminum cans with alcohol-by-volume ranging from 4.0% to 8.0%. The category serves convenience-oriented consumers seeking lower-calorie alternatives to beer and cocktails without sacrificing portability or sessionability. Flavored variants dominate volume and margin pools, while organic-positioned lines capture premium shelf space despite narrower distribution. Cans sustain the fastest growth trajectory within packaging, driven by single-serve occasion targeting and recycling infrastructure alignment.
The Alcohol and Tobacco Tax and Trade Bureau enforces formula approval and labeling standards that govern interstate commerce, while state-level alcohol beverage control boards impose divergent distribution tiers affecting market access. FDA oversight of ingredient safety and allergen disclosure intersects with TTB authority, creating dual compliance obligations for flavored formulations. Stakeholders must monitor evolving state excise tax proposals and container deposit expansions that threaten margin structures in high-volume markets.
Market Dynamics
Millennial and Gen-Z health-conscious consumption patterns are compressing traditional beer volume while pulling ethanol demand toward lower-calorie, sessionable formats that trade alcohol density for frequency of occasion.
Growth Catalysts
- TTB Formula Modernization:Streamlined approval pathways for flavored malt beverage derivatives reduce time-to-market for new vodka seltzer SKUs entering interstate commerce.
- Cane Sugar Premiumization:Mid-tier producers pivoting away from high-fructose corn syrup capture health-positioned shelf space in conventional grocery.
- California Velocity Concentration:On-premise trial rates in Los Angeles and San Francisco metro areas outpace national benchmarks, validating flavor innovation pipelines.
Market Restraints
- Aluminum Tariff Exposure:Can packaging input costs fluctuate with Section 232 duty adjustments, compressing margin on single-serve price points.
- Three-Tier Distribution Lock:State beverage control boards in Texas and Florida enforce wholesaler exclusivity that limits direct-to-retailer access for craft entrants.
- Wine Spritzer Resurgence:Lower-ABV wine-based alternatives compete for identical convenience-store cooler space without spirits-based excise tax burdens.
Strategic Opportunities
- Organic Certification Gap:USDA Organic-positioned vodka seltzer lines command premium velocity in natural channel doors despite constrained distribution footprint.
- Deposit Return Scheme Expansion:Container deposit legislation advancing in New York and Oregon creates circular packaging infrastructure alignment for aluminum-can formats.
- Cross-Category Licensing:Spirits houses partnering with brewing assets bypass capital-heavy distillation while securing ethanol supply security.
Industry Challenges
- Flavor Stability Expertise:Natural extract formulation requires beverage chemists with carbonated RTD stability experience, a talent pool concentrated at legacy soda and brewing operations.
- Dual Compliance Architecture:FDA allergen disclosure intersecting with TTB label approval creates parallel review timelines that delay seasonal SKU launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vodka Seltzer Market |
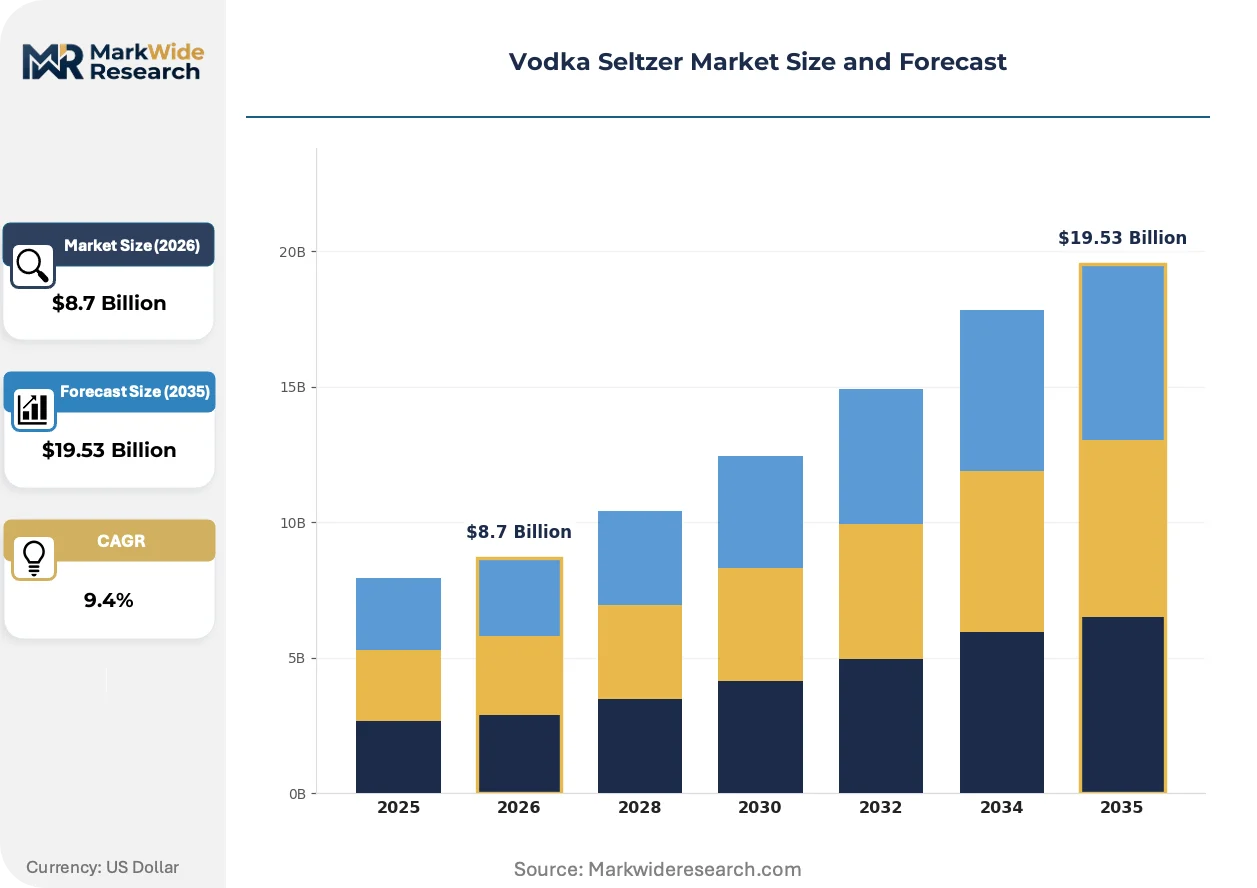
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavored, Unflavored, Organic, Low-Calorie Packaging Type: Cans, Bottles, Tetra Packs, Kegs Distribution Channel: Supermarkets, Liquor Stores, Online Retailers, Bars Consumer Type: Young Adults, Health-Conscious, Party-Goers, Casual Drinkers |
| Companies Covered | Pernod Ricard, Brown-Forman, Diageo, Boston Beer Company, Campari Group, Anheuser-Busch InBev, Molson Coors Beverage Company, Mark Anthony Group, Constellation Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vodka Seltzer Market Evolving Landscape
Reformulation transparency and packaging sustainability are compressing conventional competitive moats while opening white space for challenger positioning.
Natural flavor extraction technology is expanding into vodka seltzer production as producers replace artificial esters with cold-pressed fruit concentrates and botanical distillates. Premium-positioned lines in California and Texas adopt these inputs to justify four-dollar-plus single-serve price points. The shift is expanding into mid-tier private label programs as co-manufacturers scale extraction capacity.
FDA updated labeling requirements for ready-to-drink alcoholic beverages mandate added-sugar disclosure and serving-size standardization across multi-serve packages. The rule compresses formulation flexibility for high-brix flavor systems while advantaging clean-label portfolios with minimal added sweetener. Producers are responding with reformulation sprints ahead of compliance deadlines, particularly in Florida where state-level enforcement capacity exceeds federal baseline.
Single-serve occasion targeting is fragmenting bulk purchase patterns as convenience stores optimize cooler doors for grab-and-go velocity over case-stack efficiency. Younger cohorts in urban Texas markets favor chilled singles over warm-case acquisition, pressuring off-premise retailers to reconfigure cold-chain investment. The pattern is most visible in Miami and Austin, where bodega and convenience formats capture trial-to-purchase conversion ahead of traditional grocery.
Vodka Seltzer Market Segmentation
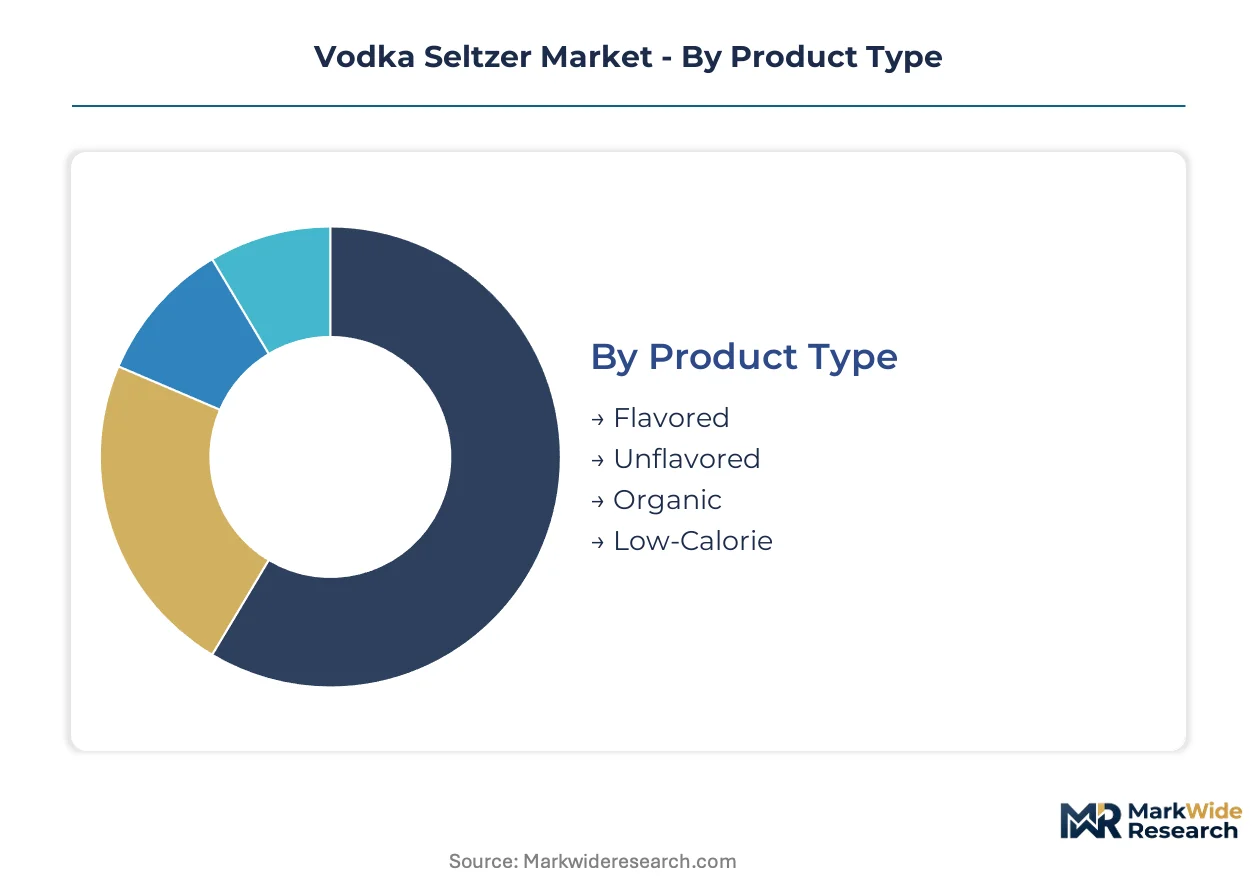
Vodka seltzer producers calibrate portfolio architecture across four distinct segmentation axes. Each dimension governs margin structure, channel access, and formulation investment differently.
Product Type:
Customization intensity spans from commodity unflavored bases to certified organic lines requiring USDA-accredited supply chains.
- Flavored:Carbonated vodka bases carry natural or artificial fruit, botanical, or confectionery flavor systems. California and Texas metro markets concentrate demand for novel flavor rotations, with Los Angeles velocity validating limited-edition pipelines.
- Organic:USDA Organic-certified lines mandate certified organic ethanol sources and flavor inputs, commanding premium shelf space in natural channel doors despite constrained distribution footprint. Supply security depends on accredited organic grain and cane sugar procurement.
- Unflavored:Neutral vodka seltzer serves as a cocktail mixer base and price-entry tier. Volume concentrates in Texas and Florida conventional grocery through private label programs.
- Low-Calorie:Sub-100-calorie formulations target health-positioned segmentation with reduced carbohydrate loads. Formulation requires alternative sweetener stability expertise.
Leading the category by volume: Flavored. Expanding most quickly: Organic.
Packaging Type:
Single-serve portability versus multi-serve efficiency shapes cold-chain investment and retail format targeting.
- Cans:Aluminum formats dominate convenience store cooler doors with recycling infrastructure alignment. Miami and Austin bodega formats favor chilled singles over warm-case acquisition.
- Bottles:Glass packaging retains on-premise presence in California bars where premium perception justifies higher per-serve pricing.
- Tetra Packs:Aseptic cartons target outdoor and festival occasions with lightweight logistics. Limited penetration in core markets.
- Kegs:Draft format serves high-volume on-premise accounts in Texas and Florida with tap system compatibility requirements.
Dominant format by velocity: Cans. Steepest expansion trajectory: Tetra Packs in outdoor occasion targeting.
Distribution Channel:
Channel selection determines margin capture versus volume scale tradeoffs under three-tier constraints.
- Supermarkets:Conventional grocery captures family and routine consumption occasions. State beverage control boards in Texas enforce wholesaler exclusivity that limits direct access.
- Liquor Stores:Specialty retailers concentrate premium and craft-positioned lines with educated staff recommendation. Florida enforcement capacity exceeds federal baseline on labeling compliance.
- Online Retailers:E-commerce channels face state-by-state shipping restrictions with California and Texas showing divergent regulatory interpretation.
- Bars:On-premise drives trial conversion and flavor innovation validation. San Francisco and Los Angeles metro trial rates outpace national benchmarks.
Highest velocity concentration: Supermarkets. Gaining share fastest: Online Retailers where interstate shipping clarifies.
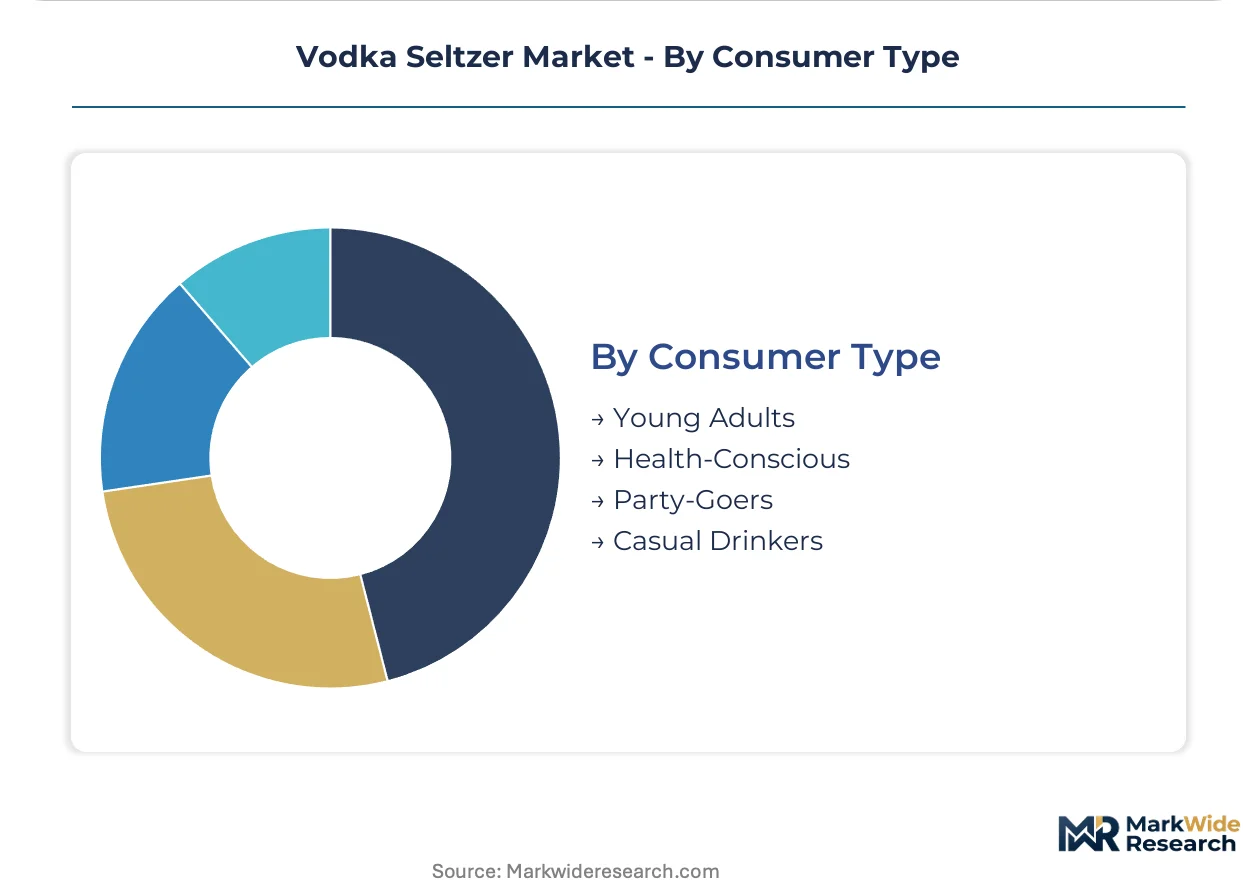
Consumer Type:
Occasion-based targeting fragments mass marketing into cohort-specific messaging and product positioning.
- Young Adults:Millennial and Gen-Z consumers compress traditional beer volume toward sessionable, lower-calorie formats. Urban Texas markets favor chilled single-serve acquisition patterns.
- Health-Conscious:Calorie-aware segmentation demands clean-label portfolios with minimal added sweetener. FDA added-sugar disclosure rules advantage this cohort.
- Party-Goers:Social occasion targeting emphasizes portability and multi-pack formats. Volume concentrates in Florida and California event and entertainment corridors.
- Casual Drinkers:Infrequent consumption occasions favor mainstream flavor profiles with broad retail availability.
Largest addressable base: Young Adults. Climbing the fastest: Health-Conscious with reformulation transparency tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumer demand for vodka seltzer concentrates most intensively in the United States, with California, Texas, and Florida generating disproportionate velocity relative to national population share. Millennial and Gen-Z cohorts in these states compress traditional beer volume toward lower-calorie, sessionable formats. State-level alcohol beverage control boards impose divergent distribution constraints that reshape market access patterns across jurisdictions.
United States
California and Texas metro areas drive national flavor innovation pipelines, with Los Angeles and Austin validating limited-edition rotation strategies. The Alcohol and Tobacco Tax and Trade Bureau enforces formula approval and labeling standards governing interstate commerce. Miami bodega formats capture trial-to-purchase conversion ahead of traditional grocery through chilled single-serve merchandising.
Canada
Health-conscious consumption patterns in Ontario and British Columbia pull ethanol demand toward reduced-calorie alternatives. Provincial liquor control boards maintain distribution monopolies that constrain direct-to-retailer access for craft entrants. Toronto and Vancouver concentrate on-premise trial rates for premium-positioned organic lines.
Mexico
Urban consumers in Mexico City and Monterrey favor convenience-oriented formats with portability for social occasions. The country's federal consumer protection agency mandates nutritional disclosure standards for ready-to-drink alcoholic beverages. Jalisco-based distribution infrastructure supports northern border state penetration targeting cross-border consumption patterns.
United Kingdom
London and Manchester metro areas concentrate demand for clean-label portfolios with minimal added sweetener. The Food Standards Agency intersects with HM Revenue and Customs on alcohol duty and labeling compliance obligations. Southeast England retail chains prioritize canned formats with recycling infrastructure alignment.
Germany
Bavaria and North Rhine-Westphalia generate strong velocity for sessionable, lower-ABV alternatives to traditional beer. The Federal Ministry of Food and Agriculture oversees ingredient safety standards affecting natural flavor extraction formulations. Berlin on-premise accounts drive premium positioning through educated staff recommendation.
Vodka Seltzer Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with spirits houses and brewing operations occupying distinct competitive positions. The vendor base consolidates around entities with captive ethanol supply or licensed partnership structures that bypass capital-heavy distillation investments. Three strategic archetypes dominate: legacy spirits conglomerates with integrated production assets, dedicated hard seltzer brewers with distribution muscle, and licensed vodka partnerships leveraging third-party ethanol sourcing. Competitive moves concentrate on cross-category licensing arrangements and organic certification positioning to capture premium shelf space.
Among spirits-anchored conglomerates, Diageo leverages its production infrastructure to secure consistent ethanol supply for captive seltzer lines. Boston Beer Company anchors the dedicated brewing archetype through specialized hard seltzer fermentation capacity. Molson Coors Beverage Company occupies the licensed partnership position, accessing vodka branding without distillation capital deployment. These three entities exemplify the structural segmentation between integrated production, brewing specialization, and brand licensing strategies that define competitive positioning in the category.
| Leading Market Players |
|---|
| Pernod Ricard |
| Brown-Forman |
| Diageo |
| Boston Beer Company |
| Campari Group |
| Anheuser-Busch InBev |
| Molson Coors Beverage Company |
| Mark Anthony Group |
| Constellation Brands |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between USDA Organic and conventional formulations manifests in both four-dollar-plus single-serve pricing and captive ethanol sourcing requirements that lock premium tiers into accredited supply chains. This bifurcation forces mid-tier producers to arbitrage between cane sugar premiumization and high-fructose corn syrup cost floors while aluminum tariff exposure compresses margin on commodity-positioned lines.
Pricing Analysis
Volume-versus-margin splits concentrate unflavored and private-label SKUs in Texas and Florida conventional grocery at economy price points, while organic-certified and limited-edition flavored lines in California command premium shelf space through natural channel doors. Price differentiation hinges on certification tier and flavor system complexity, with natural extract formulations justifying higher per-serve pricing than artificial ester bases. Cost compression in mid-tier segments is intensifying because aluminum input fluctuations and three-tier distribution markups stack margin pressure. Casual drinkers and price-entry buyers show highest price sensitivity; health-conscious and trial-seeking urban cohorts demonstrate lowest.
Supply Chain Analysis
Freight cost volatility shapes sourcing decisions as ethanol production concentrates in the United States, Canada, and Mexico under divergent regulatory frameworks. Raw material dependencies center on organic grain and cane sugar procurement, aluminum can sheet, and natural flavor extract capacity. Single-source vulnerability looms in certified organic ethanol supply, where accredited distillation infrastructure remains constrained relative to conventional capacity. Distribution runs through state beverage control boards enforcing wholesaler exclusivity that limits direct-to-retailer access for craft entrants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organic ethanol distillation capacity constraints prop pricing power for certified lines, creating supply-constrained conditions that favor incumbents with captive production assets while challengers face procurement bottlenecks.
For Market Incumbents: Hedge against wine spritzer resurgence and three-tier distribution lock by deepening backward integration into organic grain sourcing and securing dedicated co-manufacturing capacity in high-velocity states. Prioritize certification investment to defend margin position as FDA labeling transparency advantages clean-label portfolios. For New Entrants and Emerging Players: The premium-to-economy price-point gap in Texas and Florida conventional grocery offers white-space targeting through private-label unflavored bases and Tetra Pack outdoor occasion formats. Bypass capital-heavy distillation via licensed vodka partnerships with spirits houses holding excess ethanol capacity. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier producers holding USDA Organic certification pipelines given cane sugar premiumization tailwinds and natural channel expansion. Monitor TTB formula modernization implementation velocity as inflection indicator for new SKU time-to-market compression.| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Investment | USDA Organic positioning captures premium velocity in natural channel doors despite constrained distribution footprint. |
| Licensed Vodka Partnership | Spirits house collaborations bypass capital-heavy distillation while securing ethanol supply security for seltzer lines. |
| Natural Flavor Extraction Scale-Up | Cold-pressed fruit concentrate capacity expansion supports four-dollar-plus single-serve pricing in California and Texas. |
| Direct-to-Retail Channel Development | E-commerce interstate shipping clarification in California and Texas opens bypass routes around three-tier wholesaler markups. |
| Aluminum Can Supply Agreement | Long-term can sheet contracts with domestic mills hedge Section 232 tariff exposure on single-serve packaging. |
Research Methodology
Independent corroboration across beverage chemists at legacy soda and brewing operations, procurement leads at aluminum packaging mills, and regulatory affairs specialists at TTB and state beverage control boards underwrites the qualitative findings. Secondary validation draws from FDA labeling guidance documents, TTB formula approval databases, state excise tax legislative records, and Nielsen retail velocity data. Bottom-up SKU-level volume modeling triangulates against top-down category expenditure estimates from consumer panel surveys.
Rate-of-change decomposition separates volume drivers from price-mix effects across the analysis window, with segmentation modeling spanning product type, packaging format, distribution channel, and consumer occasion archetype. CAGRs derive from logistic adoption curves calibrated to millennial and Gen-Z cohort penetration patterns, with inputs including organic ethanol supply capacity expansion timelines and container deposit legislation advancement in New York and Oregon.
Inputs from state regulatory filings and co-manufacturer capacity disclosures were available through the study window; gaps in real-time aluminum tariff adjustment schedules and private-label contract terms introduce uncertainty bands. Forecasts reflect documented assumptions about TTB modernization implementation pace and organic certification audit capacity growth. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Alcohol Gummies Market
Alcoholic Beverages
Europe Craft Spirits Market
Alcoholic Beverages
Premixed Margarita Market
Alcoholic Beverages
Asia-Pacific Kegs Market
Alcoholic Beverages
Wine Aerator Market
Alcoholic Beverages
Mini Brew Fermenter Market
Alcoholic Beverages
Whiskey Market
Alcoholic Beverages
Asia-Pacific Alcoholic Beverage Market
Alcoholic Beverages
Barware Market
Alcoholic Beverages
White Wine Market
Alcoholic Beverages
Gluten Free Alcoholic Drinks Market
Alcoholic Beverages
Portable Keg System Market
Alcoholic Beverages
Rose Wine Market
Alcoholic Beverages
Alcohol Enzymes Market
Alcoholic Beverages
Decanter Market
Alcoholic Beverages
Brazil Alcohol E-Commerce Market