
 Mushroom Beer Market | 2026-2036
Mushroom Beer Market Size, Share, and Industry Trends Forecast 2026-2036
Mushroom Beer Market Foresight
North American craft breweries is repositioning production lines toward functional mushroom-infused formulations. Dogfish Head Brewery leverages its experimental brewing heritage to anchor innovation in adaptogenic beer development. Sierra Nevada Brewing Co. sustains scale advantages through integrated supply chains spanning malt and mycelium sourcing. Four Sigmatic specializes in cross-category functional mushroom expertise that extends into alcoholic applications.
Mushroom beer denotes a fermented malt beverage incorporating adaptogenic or culinary mushroom extracts such as reishi, lion's mane, or chaga, typically processed through secondary infusion or co-fermentation at temperatures below 75 degrees Fahrenheit to preserve bioactive compounds. The category serves consumers seeking functional benefits alongside traditional alcohol consumption. Craft Mushroom Beer dominates current volume as established breweries retrofit existing infrastructure, while Non-Alcoholic Mushroom Beer captures the fastest expansion as wellness-oriented drinkers seek ritual substitutes. Distribution through Specialty Stores commands premium positioning, whereas Online Retail channels erode geographic barriers for niche producers.
The FDA oversees labeling claims for functional ingredients in alcoholic beverages, while TTB governs formula approval and certificate requirements for mushroom-adjunct beers. State-level alcohol control boards impose additional testing protocols that fragment market access across jurisdictions. Stakeholders must monitor evolving mycelium sourcing regulations and adaptogenic claim enforceability to sustain compliant growth trajectories.
Market Dynamics
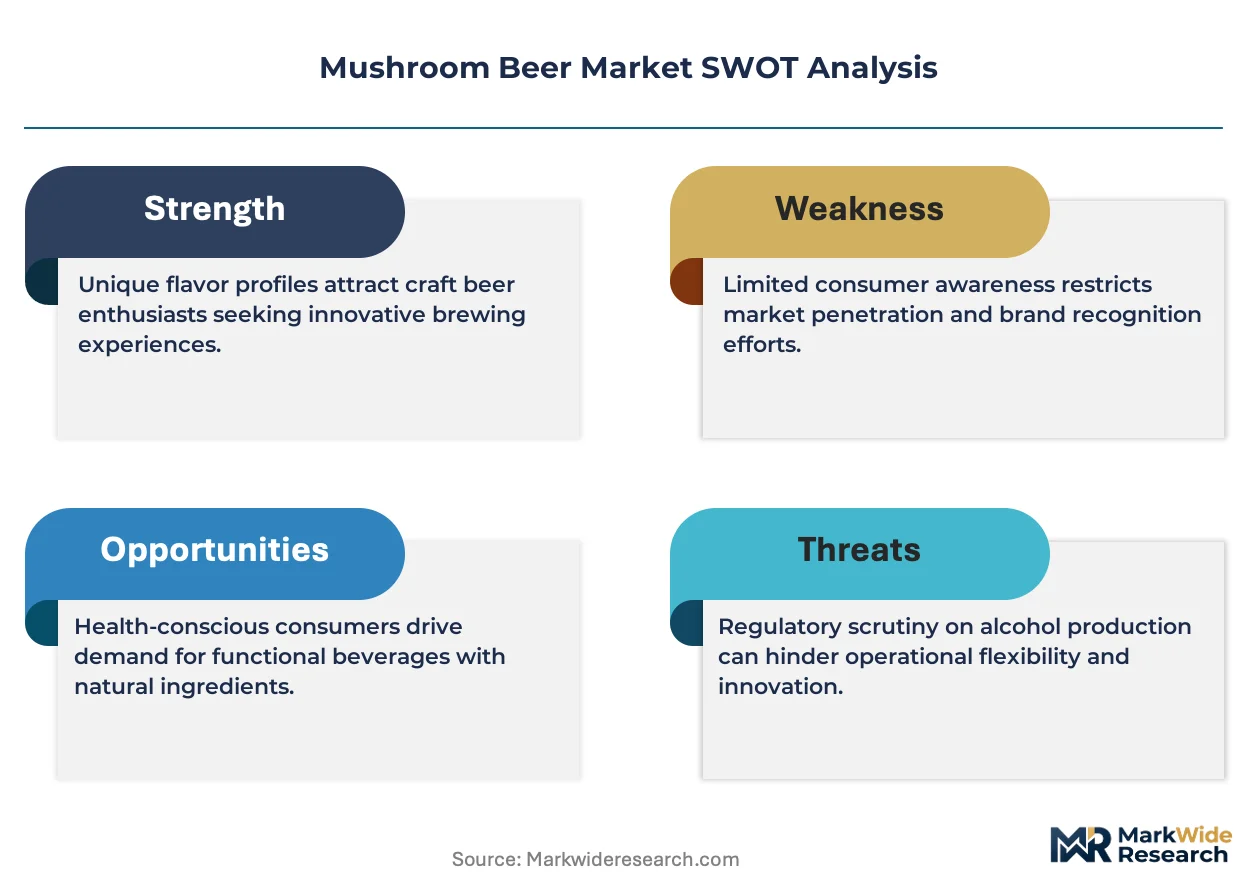
The mushroom beer market pivots on the FDA's evolving functional beverage labeling requirements, which force brewers to reformulate extract concentrations and substantiate adaptogenic claims through clinical validation rather than traditional marketing language.
Growth Catalysts
- TTB Formula Modernization:Streamlined certificate approval processes for mushroom-adjunct beers reduce time-to-market for experimental formulations in Oregon and Colorado craft clusters.
- Wellness Ritual Substitution:Non-alcoholic mushroom beer captures consumers exiting traditional alcohol consumption while preserving social and ceremonial drinking occasions.
- Pacific Northwest Production Density:Concentrated craft brewery infrastructure in Portland, Seattle, and Vancouver enables shared mycelium sourcing cooperatives and cross-brewery knowledge transfer.
Market Restraints
- Chaga Supply Volatility:Wild-harvested chaga faces seasonal availability constraints and climate-driven yield fluctuations across boreal forest regions.
- State-Level Testing Fragmentation:Alcohol control boards in Utah, Pennsylvania, and North Carolina impose divergent mycotoxin screening protocols that multiply compliance costs.
- Functional Kombucha Substitution:Established non-alcoholic adaptogenic beverages with clearer regulatory pathways capture overlapping wellness consumer segments.
Strategic Opportunities
- Canadian Provincial Expansion:British Columbia's regulatory framework for cannabis-infused beverages creates precedent for functional alcohol adjuncts in Vancouver and Victoria markets.
- Direct-to-Consumer Subscription:Brewery-owned subscription channels bypass three-tier distribution constraints and capture full margin on limited-release mushroom beer variants.
- Lion's Mane Nootropic Positioning:Cognitive performance claims align with biohacker and remote worker demographics seeking alcohol alternatives that preserve mental clarity.
Industry Challenges
- Adaptogenic Compound Stability:Maintaining bioactive beta-glucan concentrations through pasteurization and shelf-stable packaging requires specialized cold-chain infrastructure.
- Cross-Trained Fermentation Talent:Brewers with simultaneous expertise in traditional malt processing and mycelium cultivation command premium wages in tight labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mushroom Beer Market |
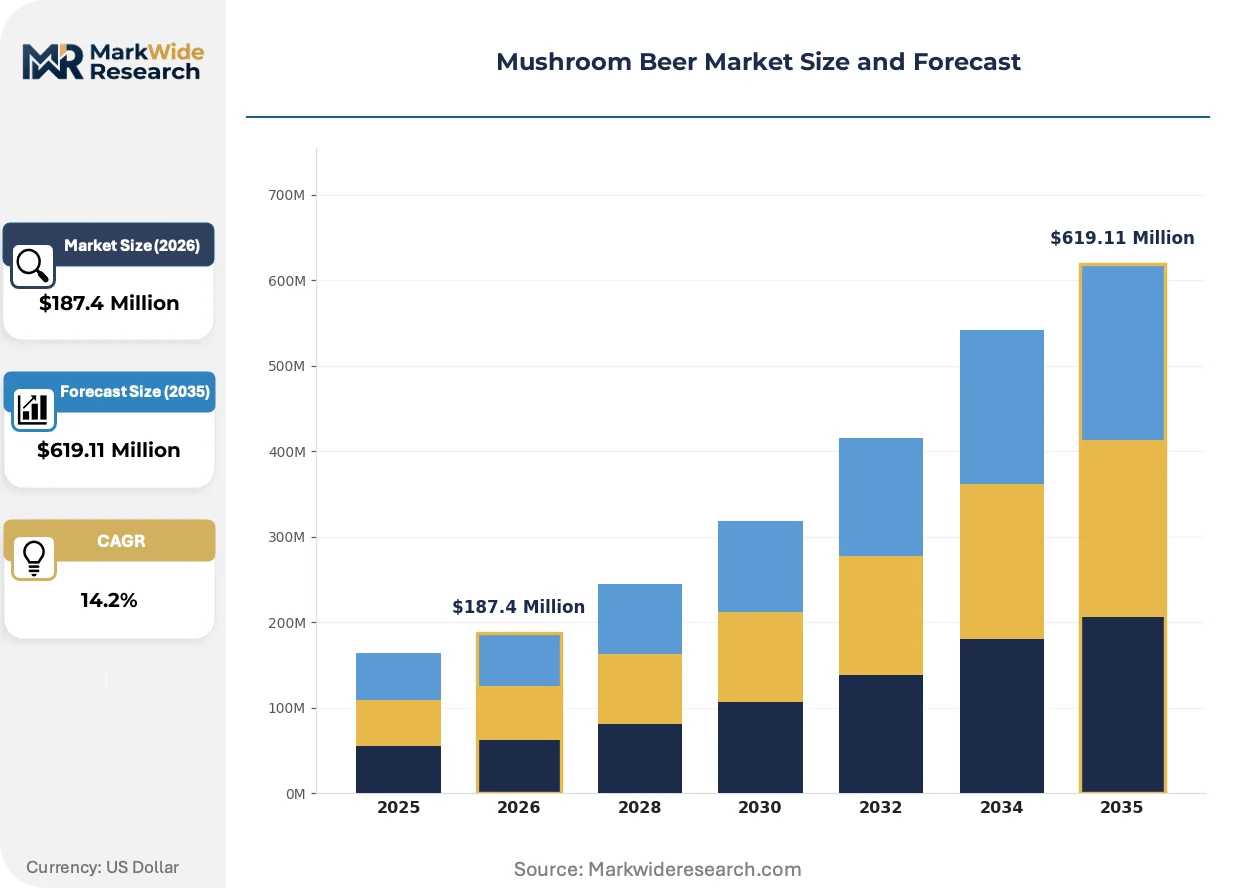
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Craft Mushroom Beer, Organic Mushroom Beer, Low-Alcohol Mushroom Beer, Non-Alcoholic Mushroom Beer Flavor Profile: Earthy, Spicy, Fruity, Herbal Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Restaurants Target Consumer: Health-Conscious Consumers, Millennials, Craft Beer Enthusiasts, Environmental Advocates |
| Companies Covered | Omnipollo, Dogfish Head Brewery, Fungtn, Rogue Ales, Garage Project, Wildcraft Brewery, Four Sigmatic, Sierra Nevada Brewing Co., Brooklyn Brewery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mushroom Beer Market Shifts & Advancements
Functional beverage technology is absorbing brewing science at unprecedented speed, with extract stabilization methods and co-fermentation protocols emerging as decisive competitive differentiators rather than niche experiments.
Cold-water ultrasonic extraction is absorbing the limitations of traditional heat-based methods, preserving heat-sensitive triterpenes in reishi and hericenones in lion's mane. Specialty craft breweries in the Pacific Northwest are retrofitting secondary infusion tanks with ultrasonic equipment at accelerating rates. This technology is absorbing quality variance between batches, compressing the expertise gap between established adaptogenic specialists and traditional beer producers entering the category.
REACH chemical registration requirements in Europe are forcing mycelium suppliers to document full supply chain provenance and extraction solvent residues. The regulation imposes documentation burdens on imported mushroom extracts used in alcoholic beverages. European craft brewers are responding by sourcing from EU-cultivated mycelium operations rather than Asian wild-harvest suppliers.
Wellness-oriented drinkers are segmenting their alcohol occasions by functional intent, selecting mushroom beers for wind-down rituals and traditional lagers for social contexts. Specialty stores and brewery taprooms are displacing conventional bar channels for mushroom beer discovery. This behavioral bifurcation is most pronounced in Portland and Seattle, where consumption data shows distinct day-part patterns for functional versus conventional alcohol purchases.
Mushroom Beer Market Segmentation
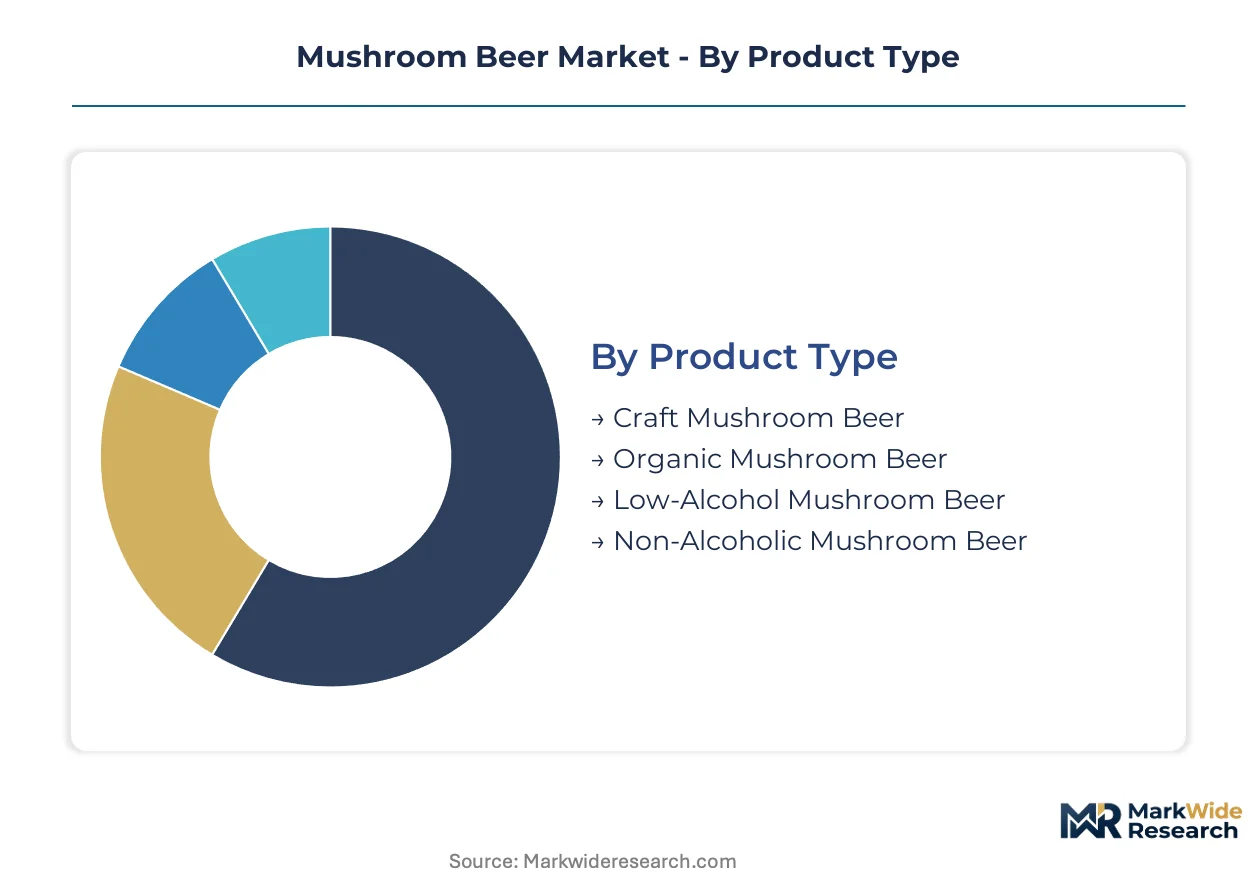
Segmentation in the mushroom beer market reveals how wellness positioning, distribution access, and consumer ritual substitution reshape competitive boundaries. Each dimension exposes distinct margin structures and regulatory exposure profiles that determine sustainable market entry.
Product Type:
Upgrade cycles in mushroom beer track shifting consumer tolerance for alcohol content and willingness to pay for certified functional ingredients.
- Craft Mushroom Beer:Fermented malt beverages produced in small-batch facilities using secondary infusion of reishi, lion's mane, or chaga extracts at sub-75°F temperatures to preserve beta-glucan activity. Demand concentrates in Portland, Seattle, and Vancouver craft brewery clusters where shared mycelium cooperatives reduce input costs.
- Non-Alcoholic Mushroom Beer:Dealcoholized or arrested-fermentation formulations delivering adaptogenic benefits without ethanol content, typically employing reverse osmosis or vacuum distillation. Wellness-oriented millennials in Pacific Northwest urban centers drive volume as ritual substitutes for traditional beer occasions.
- Organic Mushroom Beer:USDA-certified formulations using organically cultivated mycelium and malt inputs.
- Low-Alcohol Mushroom Beer:Session-strength variants below 4% ABV combining functional extracts with reduced ethanol load.
Craft Mushroom Beer sits at the top of the volume ranking, with Non-Alcoholic Mushroom Beer climbing the fastest.
Flavor Profile:
Cost tier differentiation in flavor positioning separates premium extract formulations from commodity adjunct approaches.
- Earthy:Profiles emphasizing chaga and reishi's inherent forest-floor characteristics, requiring precise roast malt balancing to avoid astringency. Portland taprooms report strongest repeat purchase rates for this foundational style.
- Herbal:Botanical-forward formulations incorporating complementary adaptogens like ashwagandha or holy basil. Colorado craft breweries lead experimentation here, leveraging local herbal supply chains.
- Spicy:Pepper and ginger adjuncts masking mushroom bitterness.
- Fruity:Citrus and berry notes from hop selection and fruit puree additions.
Earthy profiles dominate current volume, with Herbal formulations expanding most quickly among biohacker demographics.
Distribution Channel:
Application-based channel selection determines margin capture and regulatory compliance burden for mushroom beer producers.
- Specialty Stores:Curated retail environments commanding premium shelf placement and educated staff recommendations. Vancouver and Seattle natural grocers anchor West Coast penetration for functional beverage positioning.
- Online Retail:Direct-to-consumer and third-party e-commerce bypassing three-tier distribution constraints. Oregon craft breweries leverage subscription models here to capture full margin on limited releases.
- Supermarkets:Mass retail requiring TTB-compliant labeling and scaled production consistency.
- Restaurants:On-premise accounts emphasizing food pairing and experiential consumption.
Specialty Stores currently lead channel volume, with Online Retail gaining share fastest as brewery-owned platforms mature.
Target Consumer:
Customer type segmentation exposes divergent price elasticity and occasion-based purchasing patterns.
- Health-Conscious Consumers:Buyers prioritizing functional ingredient transparency and clinical validation of adaptogenic claims. FDA labeling scrutiny shapes their purchase confidence more than traditional beer marketing.
- Millennials:Demographic cohort driving wellness ritual substitution, seeking alcohol alternatives that preserve social ceremony. Pacific Northwest urban density concentrates this segment's purchasing power.
- Craft Beer Enthusiasts:Traditional beer explorers motivated by novel flavor experiences and brewery provenance.
- Environmental Advocates:Sustainability-motivated buyers prioritizing mycelium cultivation's lower ecological footprint versus conventional agriculture.
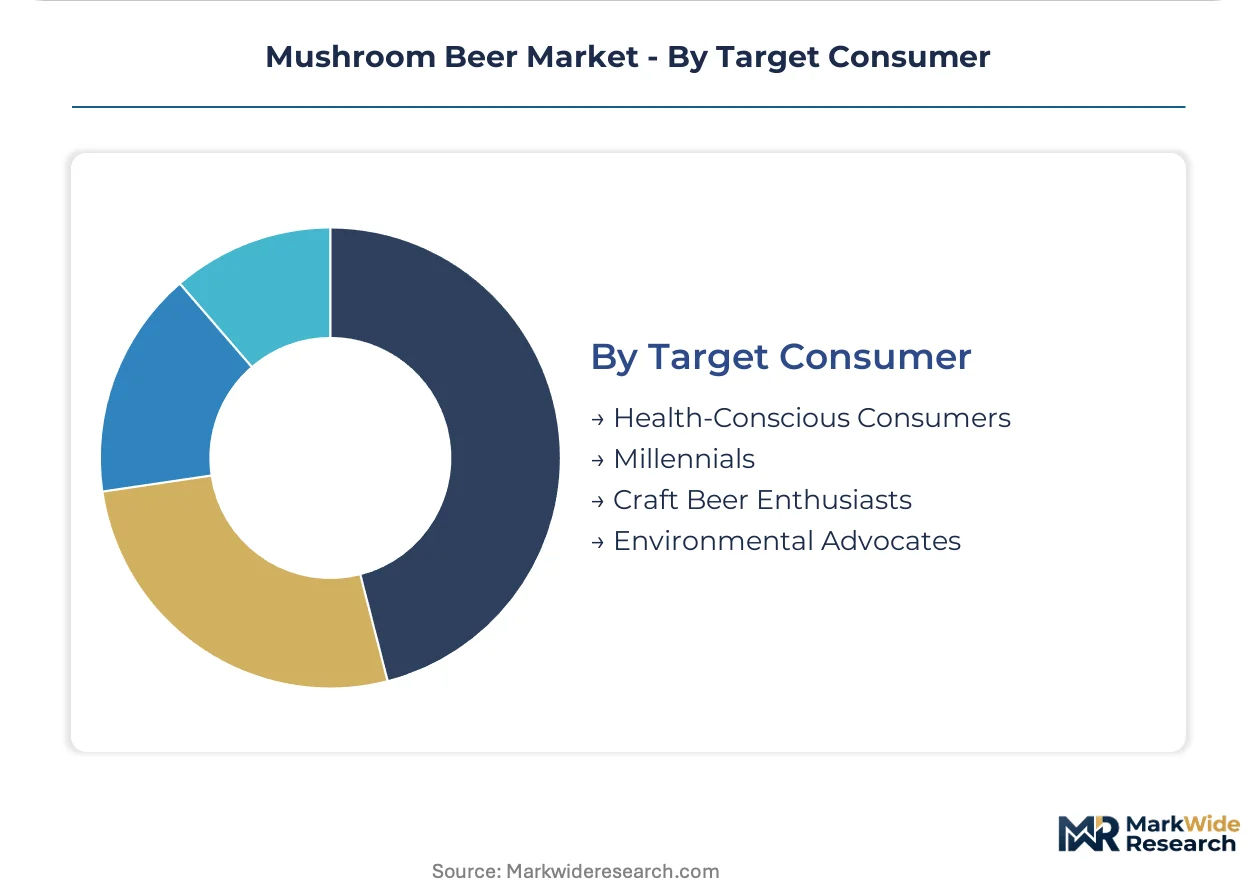
Health-Conscious Consumers represent the largest addressable base, with Millennials showing the steepest expansion trajectory as alcohol moderation trends accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting production toward jurisdictions with streamlined functional-beverage approval pathways, as brewers seek to minimize compliance latency and mycotoxin-testing fragmentation.
United States
The Pacific Northwest craft brewery density in Portland, Seattle, and Vancouver anchors domestic capacity, with wellness-focused millennials driving trial. The FDA's evolving stance on adaptogenic labeling forces reformulation toward clinically substantiated claims rather than traditional marketing language. Oregon and Colorado clusters benefit from TTB formula modernization that accelerates certificate approval for mushroom-adjunct experimental batches.
Canada
British Columbia's regulatory framework for cannabis-infused beverages creates precedent for functional alcohol adjuncts in Vancouver and Victoria markets. Health Canada oversees mycelium import documentation and extraction solvent residue standards that exceed US requirements. The Vancouver-Seattle corridor enables cross-border mycelium sourcing cooperatives and shared cold-chain infrastructure for bioactive compound preservation.
Germany
REACH chemical registration requirements impose documentation burdens on imported Asian wild-harvest extracts used in alcoholic beverages. Bavarian craft brewers are responding by sourcing from EU-cultivated mycelium operations rather than external suppliers. The Munich and Berlin craft clusters are retrofitting secondary infusion tanks with ultrasonic extraction equipment to preserve heat-sensitive triterpenes.
United Kingdom
London's wellness-oriented consumer base segments alcohol occasions by functional intent, selecting mushroom beers for wind-down rituals. The Food Standards Agency coordinates with Trading Standards on adaptogenic claim enforceability in alcoholic products. Manchester and Bristol taprooms are displacing conventional bar channels for mushroom beer discovery through experiential consumption positioning.
Australia
TGA oversight of complementary medicines creates a pathway for functional beverage positioning that alcoholic products cannot access, pushing non-alcoholic variants. Melbourne and Sydney craft breweries are investing in reverse osmosis dealcoholization to capture wellness consumers seeking ritual substitutes. The country's strict mycotoxin screening protocols exceed regional norms, filtering out lower-quality import suppliers.
Mushroom Beer Market Competitive Landscape
Pacific Northwest producers anchor the experimental tier; European specialists hold the regulatory-compliance tier. The vendor base splits between established craft breweries retrofitting existing infrastructure and dedicated functional-beverage entrants building purpose-built mycelium supply chains. Three archetypes dominate: legacy craft brewers leveraging experimental heritage, cross-category functional specialists extending into alcohol, and pure-play mushroom beer startups. Capacity expansion and direct-to-consumer subscription platforms constitute the dominant competitive moves.
Within the legacy craft tier, Dogfish Head Brewery and Sierra Nevada Brewing Co. occupy positions that exemplify divergent scale advantages—experimental heritage versus integrated supply chain control. Four Sigmatic sits within the cross-category functional specialist archetype, representing the extension of mushroom expertise from non-alcoholic applications into alcoholic formulations. Fungtn anchors the pure-play dedicated segment, exemplifying built-from-scratch mycelium sourcing infrastructure without legacy brewing baggage.
| Leading Market Players |
|---|
| Omnipollo |
| Dogfish Head Brewery |
| Fungtn |
| Rogue Ales |
| Garage Project |
| Wildcraft Brewery |
| Four Sigmatic |
| Sierra Nevada Brewing Co. |
| Brooklyn Brewery |
| Others |
Supply & Pricing Matrix
Chaga and lion's mane extract costs cascade through three distinct pricing tiers, with wild-harvested boreal inputs commanding premium positioning against laboratory-cultivated alternatives that serve cost-conscious craft brewers in Oregon and Colorado.
Pricing Analysis
Distributor margin compression in the three-tier alcohol system forces craft breweries toward direct-to-consumer subscription models that capture full markup on limited-release variants. Price differentiation rests on organic certification tier and mycelium sourcing transparency, with FDA-compliant clinical claim substantiation adding formulation overhead that separates premium positioning from commodity adjunct approaches. Pricing pressure stems from functional kombucha substitution in wellness channels, eroding willingness to pay for alcoholic alternatives. Health-conscious consumers in Pacific Northwest urban clusters exhibit lowest price sensitivity, while mass-market craft beer enthusiasts resist functional premiums without clear experiential differentiation.
Supply Chain Analysis
Dual-sourcing requirements for mycelium inputs mandate simultaneous qualification of wild-harvest Canadian suppliers and domestic cultivated operations to hedge against chaga yield volatility. Supply concentration centers on British Columbia, Finland, and China's Yunnan province for raw fungal biomass, with Oregon and Colorado craft clusters drawing from shared regional cooperatives. Cold-chain infrastructure dependency for beta-glucan preservation creates single-point vulnerability during summer transport peaks. Distribution runs through specialty retail and brewery-owned subscription platforms that bypass conventional three-tier markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mushroom beer market functions as a stable compounder, with wellness ritual substitution providing durable demand expansion independent of macroeconomic cyclicality.
For Market Incumbents: Anchor defensive positioning through captive mycelium cultivation investments that insulate against wild-harvest supply shocks, while accelerating TTB formula approval pipelines to outpace emerging non-alcoholic entrants. Cross-train fermentation talent in ultrasonic extraction protocols to preserve bioactive compound stability through shelf-life extension. Regulatory fragmentation across state alcohol control boards represents the primary margin threat requiring proactive compliance infrastructure. For New Entrants and Emerging Players: Enter via direct-to-consumer subscription channels in the Vancouver-Seattle corridor, where wellness-oriented millennials concentrate and three-tier distribution barriers are lowest. Target non-alcoholic formulations for fastest penetration, leveraging reverse osmosis dealcoholization to capture ritual substitution demand. Position around lion's mane nootropic claims with clinical validation partnerships that differentiate from commodity mushroom adjuncts. For Investors and Strategic Acquirers: Consolidation pressure builds where craft breweries lack integrated mycelium supply chains and face margin compression from state-level testing fragmentation. Long-term viability favors vertically integrated operators with proprietary extraction technology and FDA-compliant claim substantiation. Monitor Health Canada and FDA labeling guidance evolution as the decisive inflection signal for functional beverage premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Ultrasonic Extraction Equipment Deployment | Cold-water ultrasonic systems preserve heat-sensitive triterpenes in reishi and hericenones in lion's mane. |
| Direct-to-Consumer Subscription Launch | Brewery-owned channels bypass three-tier constraints and capture full margin on limited releases. |
| Organic Certification Investment | USDA-certified mycelium sourcing commands shelf placement premiums in Vancouver and Seattle natural grocers. |
| Cross-Border Mycelium Cooperative Formation | Vancouver-Seattle corridor shared infrastructure reduces cold-chain costs for Pacific Northwest craft clusters. |
| Non-Alcoholic Product Line Extension | Dealcoholized formulations capture wellness consumers exiting traditional alcohol consumption. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with craft brewery operations directors, mycelium cultivation specialists, TTB regulatory consultants, and specialty store category buyers with secondary validation from FDA guidance documents, TTB formula approval databases, Health Canada mycelium import records, and Oregon and Colorado alcohol control board testing protocols. Bottom-up production volume estimates from Pacific Northwest craft clusters were triangulated against top-down functional beverage market sizing.
Comparable historical reference periods anchored the projection framework across the analysis window, with segmentation modeling across product type, alcohol content tier, distribution channel, and target consumer archetype. CAGRs were derived from trend extrapolation of craft brewery retrofit rates and wellness consumer adoption curves. Forecast inputs incorporated TTB formula modernization timelines, state-level regulatory fragmentation indices, and mycelium cultivation capacity expansion trajectories.
Inputs from regulatory filings and trade association production surveys were available through the study window; gaps in real-time craft brewery capacity utilization data introduce uncertainty bands around near-term volume estimates. Deviation in FDA adaptogenic claim enforceability guidance would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Spain Alcohol E-Commerce Market
Alcoholic Beverages
Beer Brewing Machine Market
Alcoholic Beverages
Home Brew Boiler Market
Alcoholic Beverages
Dark Beer Market
Alcoholic Beverages
Alcopop Market
Alcoholic Beverages
Sake Market
Alcoholic Beverages
Pineapple Beer Market
Alcoholic Beverages
Global Hard Seltzers Market
Alcoholic Beverages
US Frozen Cocktail Popsicles Market
Alcoholic Beverages
Uganda Spirits Market
Alcoholic Beverages
Europe Alcohol E-Commerce Market
Alcoholic Beverages
Premium Wine Cooler Market
Alcoholic Beverages
Hookah Charcoal Market
Alcoholic Beverages
Tea Beer Market
Alcoholic Beverages
CBD Wine Market
Alcoholic Beverages
Premix Bottled Cocktails Market