
 Pre-Mixed/RTD Alcoholic Drinks Market | 2026-2036
Pre-Mixed/RTD Alcoholic Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Pre-Mixed/RTD Alcoholic Drinks Market Outlook
Brewery talent is rotating from traditional beer operations toward RTD formulation and flavor innovation, unlocking new product pipelines for established producers. Diageo leverages its spirits portfolio to anchor premium ready-to-drink offerings across multiple categories. Heineken sustains competitive pressure through global distribution scale and localized brand portfolios. Suntory Holdings Limited differentiates via Japanese whisky-based RTDs and precision flavor engineering for Asian palates.
Pre-mixed or ready-to-drink alcoholic beverages combine distilled spirits, fermented bases, or malt alcohol with flavoring agents, carbonation, and water, then package them at standardized alcohol-by-volume levels for immediate consumption without bartending equipment. The manufacturing process requires precise blending, pasteurization or cold-fill sterilization, and shelf-stable packaging to maintain flavor integrity over months of distribution. Hard seltzers dominate volume in North American markets due to their lower calorie positioning and neutral flavor adaptability, while ready-to-drink spirits capture premium margin pools through higher alcohol content and cocktail authenticity. Cans lead container type demand for their portability, recyclability, and suitability for outdoor consumption occasions.
The FDA governs ingredient safety and nutritional labeling for RTD products sold in the United States, while the Alcohol and Tobacco Tax and Trade Bureau enforces formula approval, tax classification, and advertising restrictions that directly shape product development timelines. The EU Spirits Regulation and country-level excise frameworks across Germany, France, and the United Kingdom create fragmented compliance requirements that favor producers with dedicated regulatory affairs teams. Stakeholders must monitor evolving low-alcohol taxation thresholds and sugar content disclosure mandates that could reclassify products and alter competitive positioning.
Market Dynamics
Urban millennial and Gen Z consumption patterns are compressing product development cycles, forcing manufacturers to accelerate flavor innovation pipelines while maintaining shelf-stable formulation integrity across extended distribution networks.
Growth Catalysts
- Beach culture normalization:Brazil's year-round warm climate sustains outdoor consumption occasions, creating consistent demand velocity that smooths seasonal revenue fluctuations for RTD producers.
- TTB formula approval streamlining:The Alcohol and Tobacco Tax and Trade Bureau's standardized review protocols reduce time-to-market for new product variants, enabling faster portfolio rotation.
- Cold-fill sterilization advancement:Aseptic packaging technology preserves volatile flavor compounds without heat degradation, expanding viable ingredient palettes for premium formulations.
Market Restraints
- Aluminum can supply concentration:North American beverage can manufacturing consolidates among three primary suppliers, creating input bottlenecks during peak summer demand periods.
- EU Spirits Regulation fragmentation:Country-level excise thresholds across Germany, France, and the United Kingdom force redundant compliance investments that erode margin on cross-border shipments.
- Sugar content disclosure mandates:Evolving nutritional labeling requirements in multiple jurisdictions threaten to reclassify products into higher-tax brackets based on formulation chemistry.
Strategic Opportunities
- Japanese whisky-based RTD expansion:Precision flavor engineering for Asian palates remains underexploited in Western markets, offering premium positioning potential.
- DTC subscription channel development:Direct-to-consumer platforms bypass traditional three-tier distribution constraints, capturing margin pools previously allocated to wholesale intermediaries.
- Low-alcohol taxation threshold arbitrage:Reformulated products beneath country-specific ABV cutoffs access reduced excise rates, enabling price-competitive entry against beer and wine.
Industry Challenges
- Brewery talent migration friction:Traditional beer operations face retention pressure as skilled formulators rotate toward RTD innovation teams, creating knowledge gaps in legacy facilities.
- Multi-jurisdiction formula synchronization:FDA ingredient safety standards diverge from TTB classification protocols, forcing parallel approval tracks that extend development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pre-Mixed/RTD Alcoholic Drinks Market |
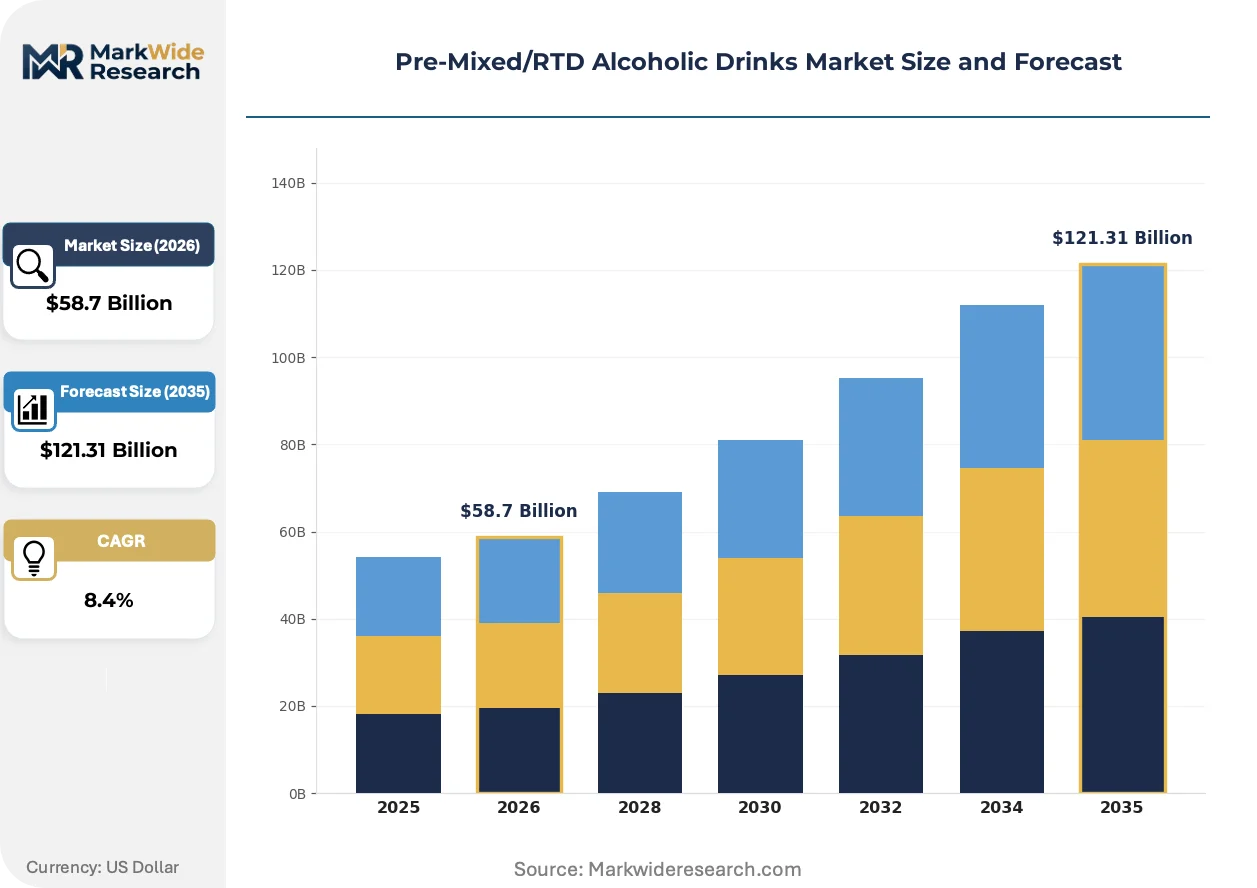
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $121.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cocktails, Hard Seltzers, Ready-to-Drink Spirits, Wine Coolers Container Type: Cans, Bottles, Pouches, Kegs Flavor Profile: Citrus, Berry, Tropical, Spicy Distribution Channel: Retail Stores, Online Platforms, Bars, Restaurants |
| Companies Covered | Bacardi Limited, Heineken, Anheuser-Busch InBev, Pernod Ricard, Carlsberg, Diageo, Suntory Holdings Limited, Molson Coors Beverage Company, Brown-Forman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pre-Mixed/RTD Alcoholic Drinks Market Strategic Shifts
Formulation science and packaging engineering are converging to redefine product stability windows, while regulatory transparency mandates reshape competitive differentiation beyond flavor alone.
Cold-fill aseptic technology is displacing traditional pasteurization in premium RTD manufacturing. Craft distillers and boutique producers adopt these systems to preserve delicate botanical extracts and fresh-pressed juice components. The shift is compressing acceptable shelf-life trade-offs, forcing mass-market brands to reformulate or surrender the authentic-cocktail positioning tier.
EU Spirits Regulation harmonization efforts are encountering national resistance, creating a patchwork compliance environment. Producers must maintain separate formula registrations and labeling schemes for German, French, and British markets. Small-to-mid-sized manufacturers without dedicated regulatory affairs teams face market exclusion as compliance complexity escalates.
Outdoor entertainment consumption patterns are consolidating purchase decisions around portability and occasion-fit. Cans displace glass bottles in beach, festival, and camping contexts due to weight and safety considerations. Brazil's coastal urban centers exemplify this rotation, where RTD volume concentrates in convenience retail formats serving immediate-consumption occasions.
Pre-Mixed/RTD Alcoholic Drinks Market Segmentation
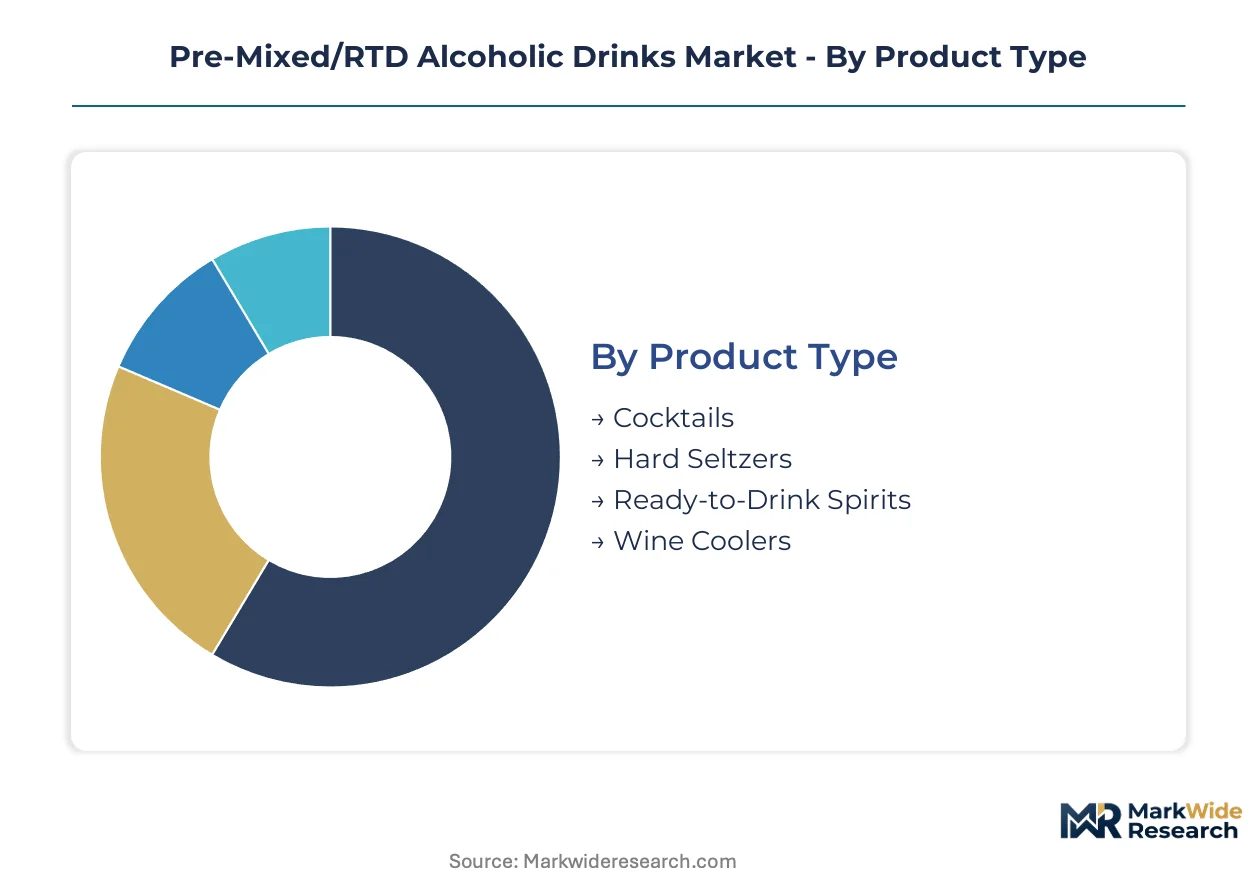
RTD producers calibrate portfolio depth across four distinct segmentation axes. Product type and container format decisions determine margin capture, while flavor innovation cycles and channel access shape competitive durability.
Product Type:
Domestic production concentrates on malt-based and wine-derived formulations, while export-led growth flows through premium spirits-based RTDs targeting developed market cocktail authenticity.
- Cocktails:Blended spirit bases with verified ingredient provenance replicate bar-quality classics at standardized ABV levels. Brazilian beach retail and US festival channels concentrate demand for margarita and mojito variants, driven by TTB formula approval standardization reducing launch timelines.
- Hard Seltzers:Fermented sugar bases with neutral alcohol profiles carry sub-100 calorie positioning. North American volume leadership persists through health-conscious millennial adoption, though aluminum can supply constraints periodically throttle summer peak production.
- Ready-to-Drink Spirits:Distilled spirit bases with higher alcohol content command premium shelf placement.
- Wine Coolers:Wine-derived bases with fruit flavoring occupy mid-tier pricing in established markets.
Hard seltzers command the established base. The steepest expansion runs through ready-to-drink spirits.
Container Type:
Cost tier stratification separates premium glass positioning from economy aluminum scale, with application context driving format selection more than absolute price point.
- Cans:Aluminum single-serve formats dominate outdoor consumption through weight advantages and recyclability infrastructure. Brazilian convenience retail and US festival circuits anchor demand, with three-supplier concentration in North American manufacturing creating periodic input bottlenecks.
- Bottles:Glass formats preserve premium perception for spirits-based RTDs in on-premise accounts. Japanese whisky-based formulations and European cocktail variants concentrate here, driven by occasion-fit requirements in formal dining and home entertaining contexts.
- Pouches:Flexible film formats reduce shipping cube and breakage risk for export markets.
- Kegs:Stainless steel formats serve draft cocktail programs in high-volume bars.
Cans capture volume leadership across price tiers. Pouches are gaining share fastest in export-oriented portfolios.
Flavor Profile:
Customer type differentiation separates experimental younger cohorts seeking novel sensory experiences from established consumers preferring validated taste territories.
- Citrus:Lemon, lime, and grapefruit profiles provide formulation stability and broad palate compatibility. Brazilian year-round consumption and US health-positioned brands anchor demand, driven by cold-fill sterilization technology preserving volatile terpene compounds.
- Berry:Strawberry, raspberry, and blackberry variants target female-skewing demographics in developed markets. Premium positioning in Japanese and South Korean convenience channels concentrates here, with precision flavor engineering requirements elevating technical barriers.
- Tropical:Mango, pineapple, and coconut profiles align with beach and vacation occasion marketing.
- Spicy:Chili, ginger, and pepper infusions attract experimental flavor adopters.
Citrus holds the volume core. Berry formulations are climbing the fastest in premium Asian markets.
Distribution Channel:
Volume concentration favors immediate-consumption formats in warm-climate geographies, while margin capture shifts toward direct and subscription models bypassing wholesale intermediaries.
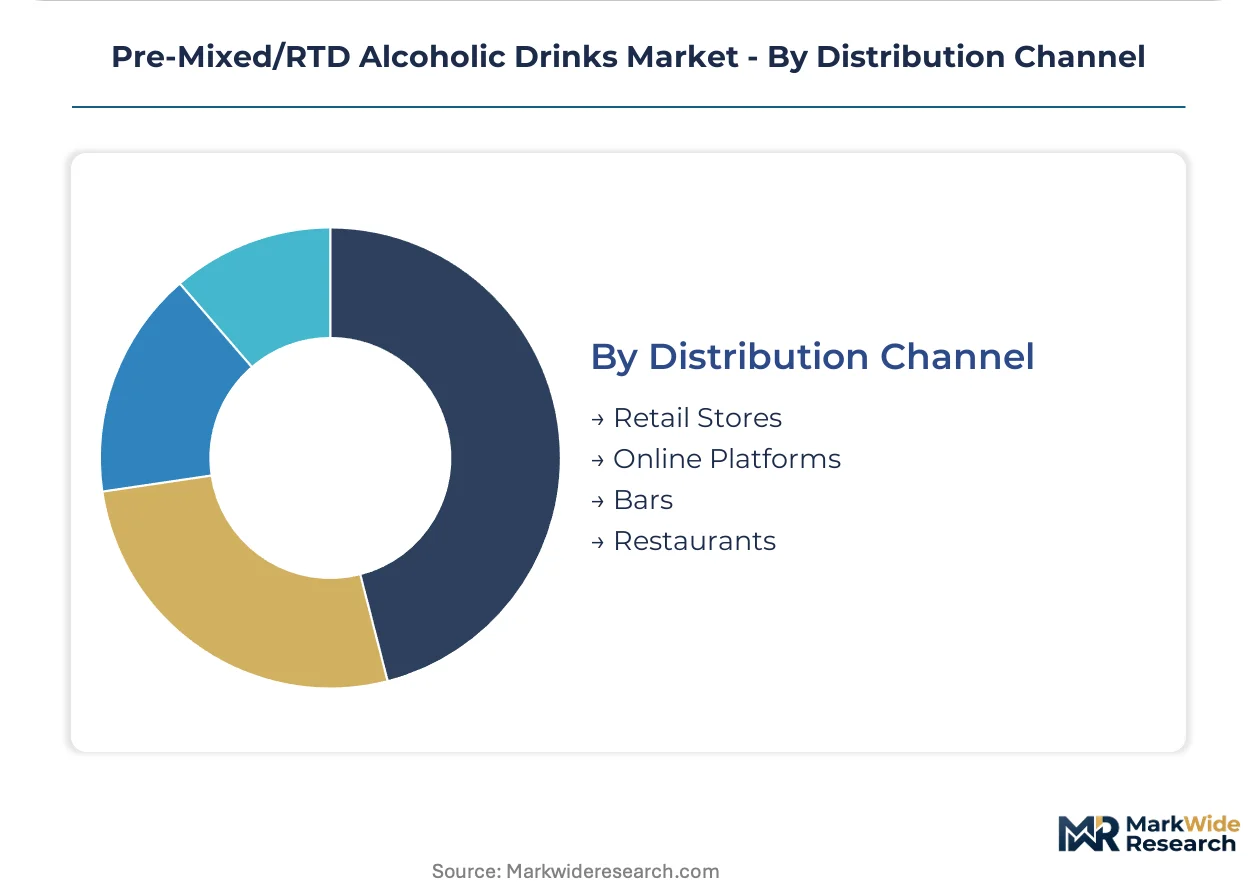
- Retail Stores:Supermarkets, convenience chains, and liquor stores provide mass-market access with refrigerated shelf placement determining velocity. Brazilian coastal urban centers and US suburban big-box formats anchor volume, driven by seasonal promotional cycles and local licensing requirements.
- Online Platforms:E-commerce and DTC subscription services capture margin pools previously allocated to three-tier distribution. EU regulatory fragmentation challenges cross-border fulfillment, though TTB compliance standardization enables smoother US interstate operations.
- Bars:On-premise draft and packaged cocktail programs serve immediate-consumption occasions.
- Restaurants:Licensed food service accounts carry curated RTD selections for table service.
Retail stores maintain volume dominance. Online platforms are expanding most quickly in regulatory-permissive jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's beach-centric consumption model diverges sharply from Japan's precision-engineered cocktail authenticity and Germany's fragmented regulatory compliance environment. These demand-pattern differences reshape how producers configure formulation, packaging, and distribution strategies across markets.
United States
Festival circuits and suburban big-box retail anchor hard seltzer velocity through TTB formula approval standardization. The Alcohol and Tobacco Tax and Trade Bureau's streamlined review protocols compress launch timelines for new variants. California and Texas convenience chains concentrate refrigerated shelf placement investments.
Brazil
Year-round warm climates sustain outdoor consumption occasions that smooth seasonal revenue fluctuations. ANVISA labeling requirements govern alcohol content disclosure and nutritional information standards. São Paulo and Rio de Janeiro coastal urban centers dominate convenience retail formats serving immediate-consumption beach culture.
Japan
Precision flavor engineering for Asian palates drives premium whisky-based RTD positioning in convenience channels. METI standards and national tax agency regulations shape low-alcohol taxation thresholds and product classification. Tokyo and Osaka metropolitan areas concentrate high-margin cocktail-authenticity demand.
Germany
Cross-border shipment complexity from EU Spirits Regulation fragmentation forces redundant compliance investments. Country-level excise thresholds and sugar content disclosure mandates threaten product reclassification. Bavaria and North Rhine-Westphalia industrial clusters house dedicated regulatory affairs teams managing multi-jurisdiction formula synchronization.
United Kingdom
On-premise draft cocktail programs and home entertaining contexts preserve glass-bottle premium positioning. HMRC excise frameworks and evolving low-alcohol taxation thresholds alter competitive positioning against beer and wine. London and Southeast England concentrate curated RTD selections for licensed food service accounts.
Pre-Mixed/RTD Alcoholic Drinks Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with multinational beverage conglomerates leveraging spirits portfolios and global distribution scale against regional formulators focused on flavor innovation. The structure rewards backward integration into can manufacturing and captive supply of malt bases. Three archetypes dominate: spirits-anchored premium players, beer-origin mass-market operators, and precision-flavor Asian specialists. Competitive moves concentrate on portfolio diversification across ABV tiers and strategic partnerships for cold-fill sterilization technology access.
Within the spirits-anchored tier, Diageo and Bacardi Limited represent multinational portfolio leverage, while Suntory Holdings Limited exemplifies precision-engineered regional differentiation. Heineken occupies a position bridging beer-origin scale with RTD adaptation. These three anchors demonstrate how geographic origin and corporate structure shape strategic optionality: London-based Diageo and Bermuda-headquartered Bacardi deploy global distribution networks, while Tokyo-based Suntory concentrates technical formulation capabilities for palate-specific markets.
| Leading Market Players |
|---|
| Bacardi Limited |
| Heineken |
| Anheuser-Busch InBev |
| Pernod Ricard |
| Carlsberg |
| Diageo |
| Suntory Holdings Limited |
| Molson Coors Beverage Company |
| Brown-Forman |
| Others |
Value Chain & Pricing Dynamics
Cold-fill sterilization technology displacing traditional pasteurization simultaneously shifts manufacturing geography toward premium production clusters and compresses margin structures for heat-stable formulations. This substitution dynamic rewards producers with aseptic packaging capabilities while penalizing legacy facilities dependent on thermal processing economics.
Pricing Analysis
Long-term offtake contracts with aluminum suppliers dominate procurement structures, though spot-market purchases spike during summer demand surges. Three-tier pricing structure across premium spirits-based, standard malt-based, and economy wine-derived formulations separates margin capture by alcohol base and flavor complexity. Price differentiation hinges on ABV tier positioning and TTB formula approval status, with certified products commanding shelf-placement premiums. Pricing pressure stems from Brazilian beach-retail price wars and North American hard seltzer commoditization. Convenience retail chains exhibit highest price sensitivity, while DTC subscription buyers prioritize flavor novelty over per-unit cost.
Supply Chain Analysis
Inventory lead times for aluminum cans stretch longest during Q2-Q3 peak periods, forcing producers to pre-position stock before festival season demand. Manufacturing concentrates in the United States, Brazil, and Japan, with each hub serving distinct formulation and packaging requirements. Raw material flows draw from Midwest malt suppliers, Caribbean sugar bases, and Scottish-Japanese whisky stocks. Single-source vulnerability pervades North American can manufacturing, where three suppliers control capacity. Distribution runs through three-tier wholesale networks in the United States, direct retail in Brazil, and convenience-store oligopolies in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around Brazilian convenience chains and North American big-box retailers, compressing supplier margins and demanding promotional support that erodes brand equity investments.
For Market Incumbents: Shield premium positioning through backward integration into cold-fill sterilization technology, denying smaller competitors access to volatile-flavor formulation capabilities. Defend against Japanese whisky-based RTD entrants by accelerating TTB formula approvals for authentic cocktail variants. Prioritize captive aluminum can supply agreements to neutralize summer input bottlenecks. For New Entrants and Emerging Players: Anchor in German regulatory complexity, where EU Spirits Regulation fragmentation excludes resource-constrained competitors. Target precision-flavor engineering for Asian palates as the most penetrable white-space, leveraging METI standards familiarity. Pursue DTC subscription launch to bypass wholesale margin extraction and build direct consumer relationships. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors producers with aseptic packaging capabilities and regulatory affairs scale. Long-term viability rests on formula approval velocity and cold-fill sterilization access rather than brand heritage alone. Monitor TTB review timeline compression as the critical inflection signal for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Fill Sterilization Adoption | Aseptic technology preserves volatile botanicals that heat processing degrades, unlocking premium tier access. |
| TTB Formula Approval Acceleration | Streamlined review protocols compress launch timelines for cocktail-authenticity variants against malt-based competitors. |
| Aluminum Supply Captive Integration | Direct can manufacturing agreements neutralize three-supplier concentration risk during summer demand peaks. |
| DTC Subscription Channel Buildout | Direct platforms bypass three-tier distribution margin extraction and capture consumer preference data. |
| Japanese Whisky-Based RTD Expansion | Precision flavor engineering for Asian palates commands premium positioning in Western convenience channels. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA formula filings, TTB approval databases, ANVISA registration records, and EU Spirits Regulation harmonization documents. Interviews with RTD brand managers, regulatory affairs directors at spirits conglomerates, convenience retail category buyers, and cold-fill equipment suppliers provided ground-truth calibration. Secondary validation drew from customs trade data, aluminum industry capacity reports, and beverage distribution channel audits. Bottom-up volume builds triangulated against top-down market sizing across the analysis window.
Segmentation dimensions modeled include product type, container format, flavor profile, ABV tier, and distribution channel across regional regulatory clusters. CAGRs derive from trend-line extrapolation of historical volume data adjusted for technology adoption curves and regulatory timeline shifts. Forecast inputs incorporate cold-fill sterilization penetration rates and TTB review velocity improvements without assuming harmonization of EU national excise frameworks.
Decision-makers should treat outputs as directional under assumptions of continued aluminum supply concentration and stable TTB approval protocols; material deviation in either would warrant model refresh. Specific risk factors include sugar-content disclosure mandates triggering product reclassification and EU Spirits Regulation fragmentation intensifying compliance costs. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Ready to Drink Cocktails Market
Alcoholic Beverages
Brandy Market
Alcoholic Beverages
North America Tequila Market
Alcoholic Beverages
North America Beer Market
Alcoholic Beverages
Stemware Market
Alcoholic Beverages
US Alcohol E-Commerce Market
Alcoholic Beverages
Fruit Brandy Market
Alcoholic Beverages
Wine Chocolate Market
Alcoholic Beverages
High-End Baijiu Market
Alcoholic Beverages
Craft Wine Market
Alcoholic Beverages
Global Beer Market
Alcoholic Beverages
North America Spirits Market
Alcoholic Beverages
Drinkware, Beverageware, and Barware Market
Alcoholic Beverages
Mini Brew Fermenter Market
Alcoholic Beverages
Gin Market
Alcoholic Beverages
Fermented Beverages Market