
 Saffron Beer Market | 2026-2036
Saffron Beer Market Size, Share, and Industry Trends Forecast 2026-2036
Saffron Beer Market Analytics
Spain is fragmenting as craft brewers in Castilla-La Mancha and Aragon expand saffron infusion capacity alongside traditional wine cooperatives. BrewDog Plc leverages its experimental brewing infrastructure to test limited saffron releases across European markets. Anheuser-Busch InBev anchors mainstream distribution through its specialty import divisions, while Heineken N.V. competes via regional craft portfolio brands that incorporate local spice traditions.
Saffron beer denotes an ale or lager style incorporating Crocus sativus stigmas, typically at dosages of 0.1 to 0.5 grams per liter during secondary fermentation to preserve volatile aromatic compounds. The resulting beverage delivers a distinct golden hue, earthy-honeyed palate, and terpenoid complexity prized in premium positioning. Craft Beer dominates current volume as small-batch producers exploit ingredient storytelling, while Flavored Beer extends fastest as multinational portfolios add saffron to existing fruit-and-spice line extensions. Organic Beer sustains margin concentration where certified saffron sourcing commands price premiums through controlled origin labeling.
EU REACH and F-Gas Regulation frameworks govern solvent residues and refrigerant disclosures in saffron extraction and cold-chain logistics, while the FDA oversees GRAS status for novel saffron infusions entering United States interstate commerce. BIS standards in India affect import certification for Iranian and Kashmiri saffron raw material. Stakeholders must monitor evolving additive disclosure mandates and origin traceability requirements as procurement patterns shift toward verified sustainable sourcing.
Market Dynamics
EU REACH compliance and F-Gas Regulation enforcement are compressing saffron extraction solvent disclosures while tightening cold-chain refrigerant tracking across European brewing operations.
Growth Catalysts
- Castilla-La Mancha cluster expansion:Spanish craft brewers in saffron cultivation zones exploit terroir proximity to reduce raw material transport costs and strengthen origin storytelling for premium positioning.
- REACH additive transparency mandates:European brewers investing in certified solvent-free extraction methods capture shelf space as retailers demand documented residue compliance for saffron-infused portfolios.
- Secondary fermentation dosing protocols:Precision-controlled 0.1-0.5 gram per liter infusion techniques preserve volatile terpenoid compounds that mass-market heat-pasteurization destroys.
Market Restraints
- Iranian saffron supply concentration:Over 85% of global Crocus sativus stigmas originate from Khorasan province, exposing brewers to sanctions volatility and currency fluctuation risks.
- Labor-intensive stigma harvesting:Each flower yields only three stigmas requiring hand-picking at dawn, capping scalable volume expansion regardless of price signals.
- Substitution threat from turmeric and annatto:Cost-conscious flavored beer producers deploy these alternatives for golden coloration without saffron's aromatic complexity or price premium.
Strategic Opportunities
- United States craft brewery underpenetration:American microbreweries outside Colorado and California lack saffron beer portfolios, creating first-mover openings for import partnerships with Spanish producers.
- Organic certification tailwinds:EU organic labeling requirements for processed foods incentivize brewers to source certified saffron from La Mancha Designation of Origin cooperatives.
- Direct-to-consumer subscription channels:Specialty beer clubs bypass traditional three-tier distribution, enabling limited-release saffron SKUs at margin-preserving price points.
Industry Challenges
- Volatile compound stability expertise:Breweries lack in-house analytical chemists capable of monitoring safranal and picrocrocin degradation curves through shelf life.
- Dual certification timeline compression:Simultaneous EU organic and FDA GRAS approval processes extend new product launch windows by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saffron Beer Market |
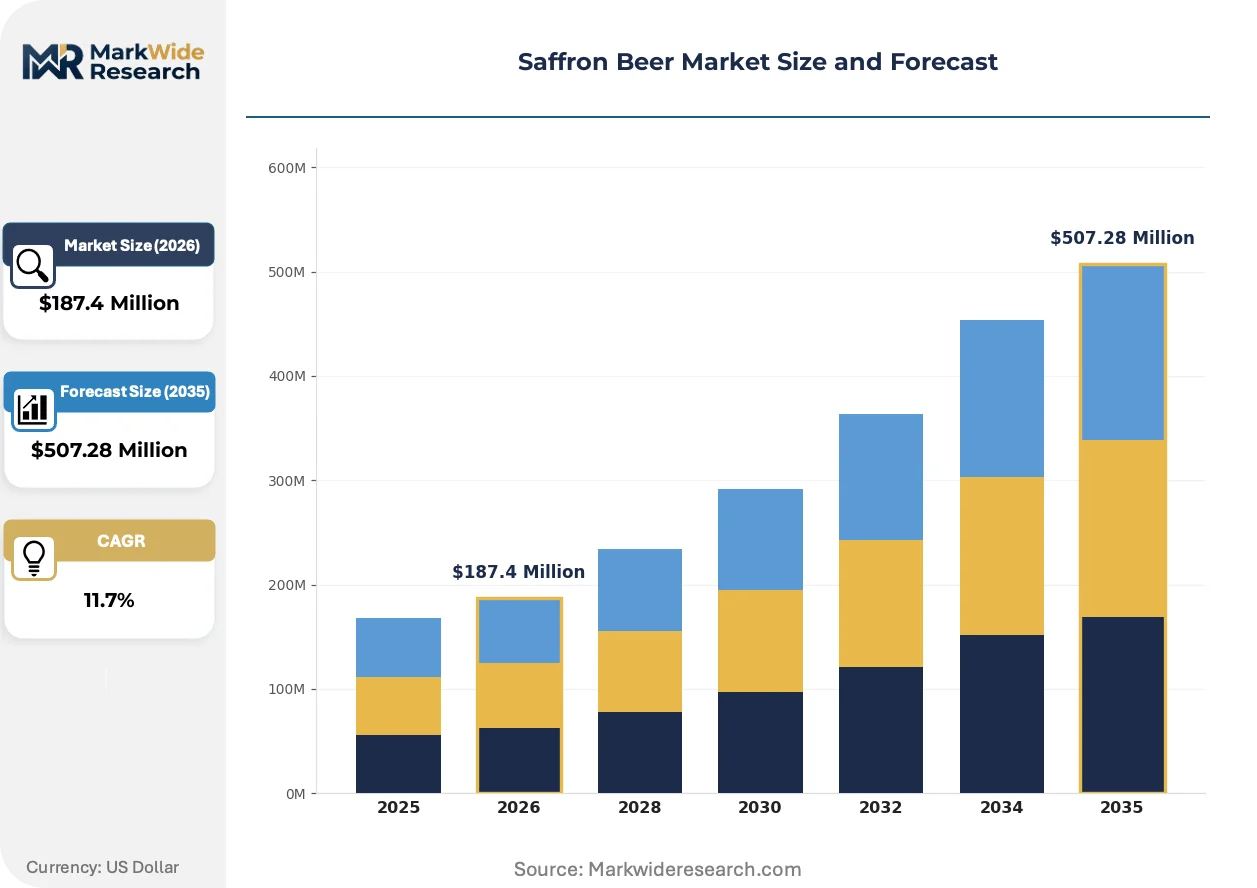
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Craft Beer, Premium Beer, Organic Beer, Flavored Beer Packaging Type: Bottle, Can, Keg, Growler Distribution Channel: Retail Stores, Online Platforms, Breweries, Bars Customer Type: Restaurant Chains, Specialty Stores, Individual Consumers, Event Organizers |
| Companies Covered | BrewDog Plc, Anheuser-Busch InBev, Heineken N.V., Boston Beer Company, Sierra Nevada Brewing Co., New Belgium Brewing, Fifth Ward Brewing Company, Dogfish Head Brewery, Allagash Brewing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saffron Beer Market Evolving Landscape
Cryogenic grinding and nitrogen-flash freezing techniques are preserving saffron aromatic integrity through previously loss-intensive processing stages.
Cryogenic grinding of Crocus sativus stigmas at minus 196 degrees Celsius is rendering obsolete traditional ambient milling that oxidizes volatile terpenoids within hours. Castilla-La Mancha cooperatives and Aragon craft brewers adopted this infrastructure during 2023-2024 equipment upgrade cycles. The technology compresses spoilage windows from days to months, enabling transatlantic raw material shipments without aromatic degradation.
EU F-Gas Regulation phase-down schedules for hydrofluorocarbon refrigerants are forcing cold-chain logistics providers to retrofit extraction and storage facilities with CO2-based systems. Brewers dependent on third-party saffron extraction services face service interruptions as contractors absorb capex burdens. Spanish and Italian producers with captive extraction capacity secure supply continuity while competitors encounter 6-12 month contractor backlogs.
Restaurant chains now specify certified-origin saffron documentation in procurement tenders, displacing commodity spice purchasing from anonymous brokers. Specialty beer buyers at European hospitality groups audit extraction method transparency and stigma traceability to farm level. This specification intensity concentrates in Madrid, Barcelona, and Milan where premium beverage programs compete for culinary tourism traffic.
Saffron Beer Market Segmentation
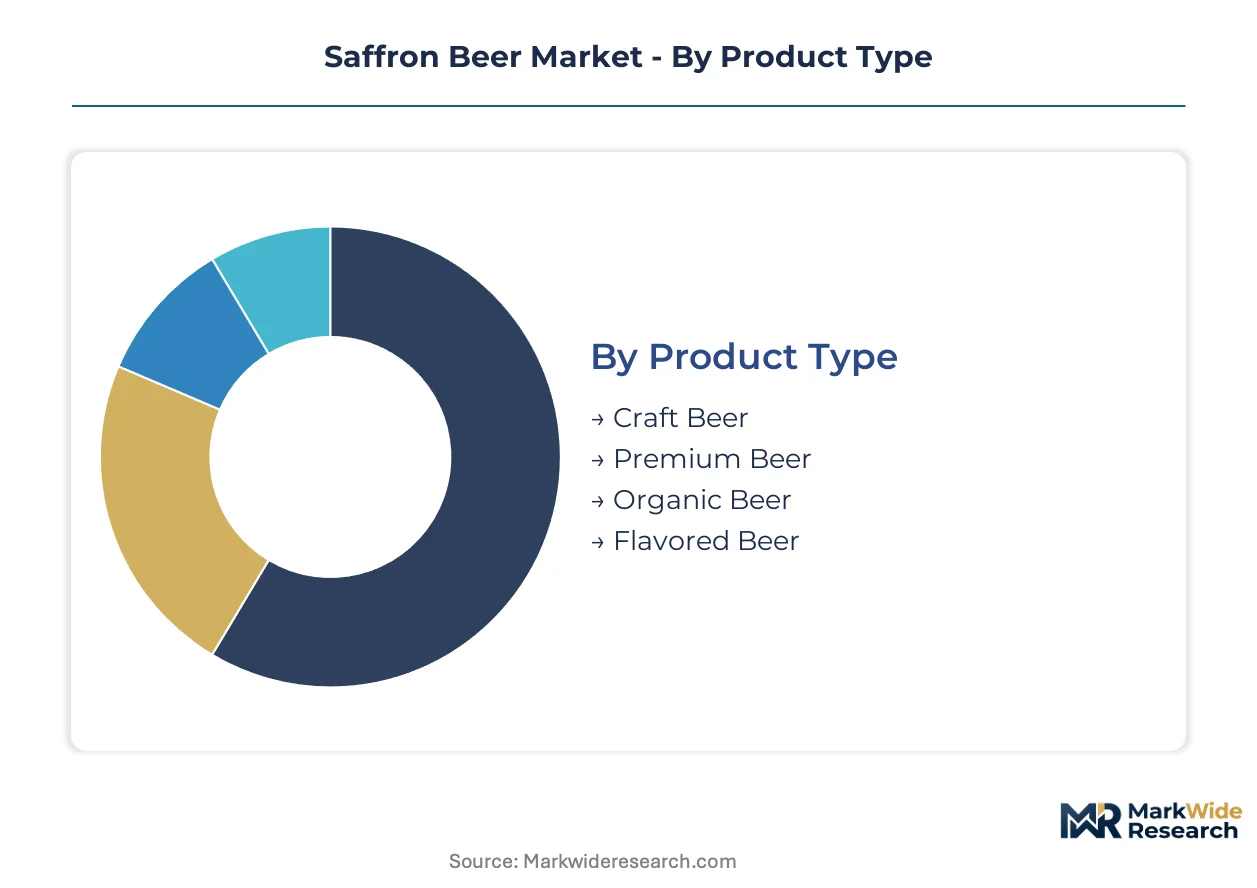
Saffron beer segmentation reflects divergent production scales and consumption contexts. Craft producers exploit ingredient provenance for premium positioning, while multinational portfolios extend saffron into mass-market flavored line extensions. Packaging and channel strategies must preserve volatile aromatic compounds through shelf life.
Product Type:
Spanning from artisanal microbreweries to certified organic supply chains, product architecture determines margin capture and regulatory exposure.
- Craft Beer:Small-batch producers in Castilla-La Mancha and Aragon deploy 0.1-0.5 gram per liter secondary fermentation dosing to preserve safranal and picrocrocin integrity. Specialty stores in Madrid and Barcelona concentrate demand as terroir storytelling commands shelf space premiums.
- Flavored Beer:Multinational portfolios integrate saffron into existing fruit-and-spice extensions, leveraging established distribution infrastructure. United States craft brewery underpenetration outside Colorado and California creates first-mover openings for import partnerships with Spanish producers.
- Premium Beer:Positioning emphasizes controlled origin labeling and extraction method transparency for hospitality procurement tenders.
- Organic Beer:EU organic labeling requirements for processed foods incentivize certified saffron sourcing from La Mancha Designation of Origin cooperatives.
The dominant share belongs to Craft Beer, while Flavored Beer is closing the gap fastest.
Packaging Type:
Material selection directly impacts aromatic stability and cold-chain compliance costs across distribution networks.
- Bottle:Amber glass dominates premium positioning, blocking UV degradation of terpenoid compounds while supporting extended cellar aging programs.
- Can:Aluminum formats with nitrogen-flush sealing preserve volatile integrity through oxygen exclusion, gaining traction in direct-to-consumer subscription channels.
- Keg:Stainless steel keg systems enable draft service in restaurant chains specifying certified-origin saffron documentation.
- Growler:Refillable vessels concentrate in brewery taproom sales, minimizing transport costs for localized Castilla-La Mancha cluster distribution.
Bottle formats retain the largest installed base, though Can packaging is expanding most quickly in e-commerce channels.
Distribution Channel:
Channel architecture determines margin preservation and regulatory disclosure burden for saffron traceability documentation.
- Retail Stores:Specialty beer buyers audit extraction method transparency and stigma traceability to farm level, concentrating specification intensity in Milan and Barcelona.
- Online Platforms:Direct-to-consumer subscription channels bypass traditional three-tier distribution, enabling limited-release SKUs at margin-preserving price points.
- Breweries:Captive taproom sales support growler refill programs and experimental batch releases without interstate commerce FDA GRAS compliance requirements.
- Bars:Premium beverage programs in culinary tourism corridors compete for certified-origin saffron procurement tenders.
Retail Stores command the deepest penetration, yet Online Platforms are gaining share fastest among younger demographics.
Customer Type:
Procurement sophistication varies dramatically across institutional and individual purchaser segments.
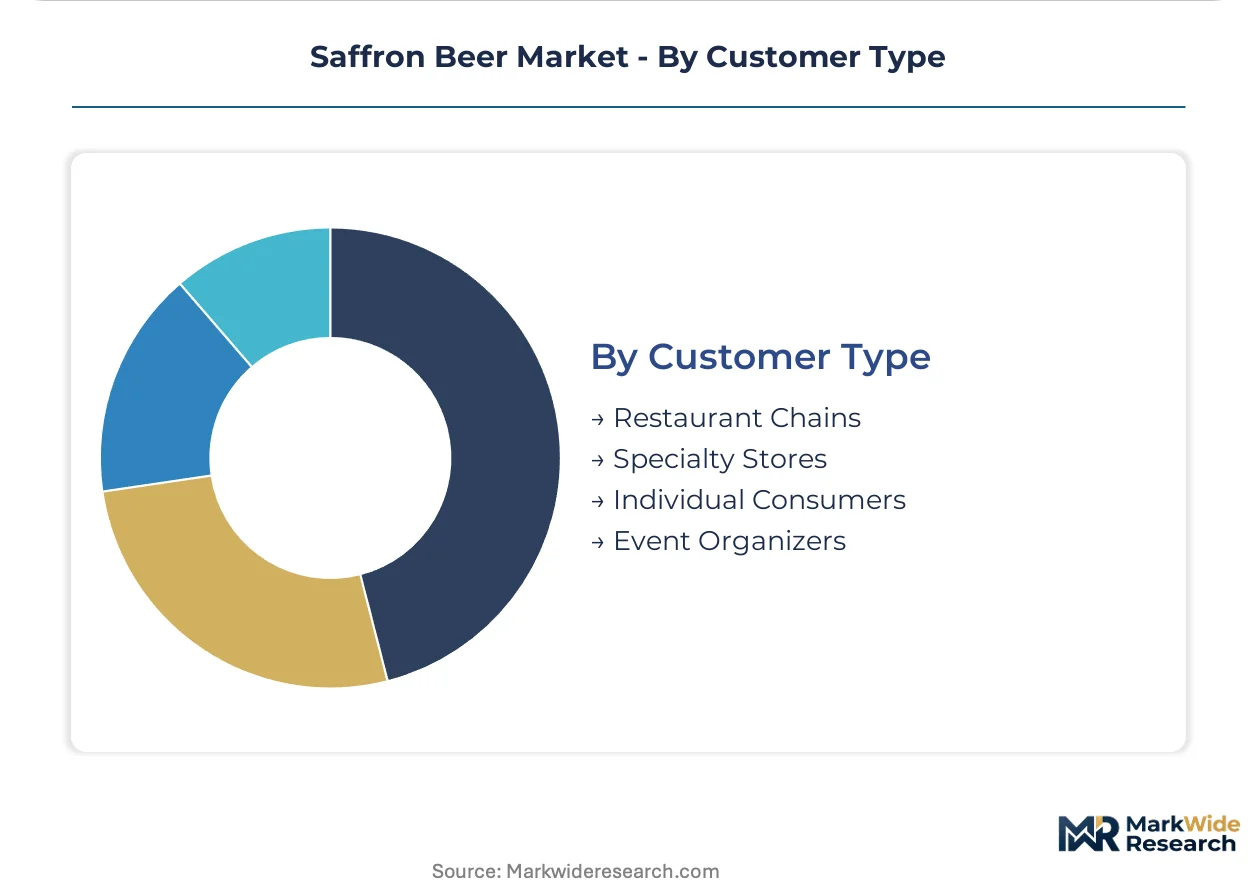
- Restaurant Chains:European hospitality groups now specify certified-origin saffron documentation, displacing commodity spice purchasing from anonymous brokers.
- Specialty Stores:Curated assortments in Madrid, Barcelona, and Milan emphasize controlled origin labeling for culinary tourism traffic.
- Individual Consumers:Subscription club membership concentrates among enthusiasts seeking limited-release experimental batches.
- Event Organizers:Festival and catering procurement favors keg formats with batch-traceable extraction method disclosure.
Restaurant Chains anchor institutional volume, while Individual Consumers are climbing the fastest through subscription channel adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU REACH compliance anchors European brewing operations as the dominant regulatory framework shaping saffron extraction transparency and cold-chain refrigerant tracking across the continent.
Spain
Castilla-La Mancha craft brewers exploit terroir proximity to La Mancha Designation of Origin saffron cooperatives, slashing raw material transport costs. EU F-Gas Regulation phase-down schedules force CO2-based refrigeration retrofits in extraction facilities. Madrid and Barcelona specialty stores concentrate demand as terroir storytelling commands shelf space premiums.
United States
Colorado and California microbreweries anchor current craft production while underpenetrated markets in the Pacific Northwest and Northeast create first-mover openings. FDA GRAS status requirements govern novel saffron infusions entering interstate commerce. Boston Beer Company and Sierra Nevada Brewing Co. exemplify established craft infrastructure positioned for saffron portfolio expansion.
Italy
Milan's premium beverage programs drive certified-origin saffron procurement tenders from European hospitality groups. EFSA oversight aligns with EU organic labeling requirements for processed foods. Piedmont and Lombardy brewing clusters integrate cryogenic grinding infrastructure to preserve volatile terpenoid compounds through extended shelf life.
Germany
Bavarian craft brewers leverage technical brewing expertise to optimize secondary fermentation dosing protocols at 0.1-0.5 grams per liter. German KBA-equivalent state regulators enforce additive disclosure mandates alongside federal REACH implementation. Munich and Berlin specialty retailers audit extraction method transparency to farm-level stigma traceability.
United Kingdom
Experimental brewing infrastructure in Scotland and England supports limited saffron release programs targeting culinary tourism corridors. UK REACH retains EU-aligned solvent residue frameworks post-Brexit. BrewDog Plc anchors British craft innovation capacity with European market testing capabilities for novel infusion techniques.
Saffron Beer Market Competitive Landscape
Capability concentration sits with craft specialists possessing cryogenic processing expertise; scale advantage sits with multinational portfolios leveraging established distribution infrastructure. The market structures around three tiers: terroir-anchored regional brewers, experimental craft platforms, and mass-market flavored beer extensions. Dominant competitive moves include captive extraction capacity investments and direct-to-consumer subscription channel development bypassing traditional three-tier distribution.
Within the experimental craft tier, BrewDog Plc and Dogfish Head Brewery exemplify brewing operations positioned for novel ingredient portfolio expansion. Anheuser-Busch InBev anchors the multinational tier with specialty import division infrastructure capable of mass-market saffron line extension deployment. These three entities represent divergent strategic archetypes: terroir-proximate craft innovation, boundary-pushing experimental brewing, and scale-driven flavored beer commercialization.
| Leading Market Players |
|---|
| BrewDog Plc |
| Anheuser-Busch InBev |
| Heineken N.V. |
| Boston Beer Company |
| Sierra Nevada Brewing Co. |
| New Belgium Brewing |
| Fifth Ward Brewing Company |
| Dogfish Head Brewery |
| Allagash Brewing Company |
| Others |
Value Network & Pricing Analysis
Undercapacity in cryogenic grinding infrastructure across Castilla-La Mancha and Aragon is compressing supplier margins while amplifying pricing power for cooperatives with captive extraction capacity, forcing brewers to accept longer offtake commitments or absorb spot-market volatility in saffron stigma procurement.
Pricing Analysis
Price spreads between certified-origin La Mancha saffron and unverified Iranian material exceed threefold across European specialty retail channels. Three-tier pricing structure across premium, standard, and economy levels segments by organic certification status and extraction method transparency, with EU organic-labeled product commanding shelf space premiums. Pricing pressure stems from turmeric and annatto substitution in mass-market flavored beer tiers, where cost-conscious producers sacrifice aromatic complexity for golden coloration. Restaurant chains exhibit lowest price sensitivity due to procurement tender specifications demanding farm-level traceability documentation, while individual consumers through subscription channels show moderate elasticity.
Supply Chain Analysis
Tariff exposure between Iranian saffron exporters and United States brewers dominates supply chain risk calculus, compounded by sanctions volatility affecting over eighty-five percent of global Crocus sativus stigma origin. Raw material sourcing draws from Khorasan province in Iran, La Mancha Designation of Origin cooperatives in Spain, and emerging cultivation clusters in Kashmir and Afghanistan. Distribution runs through specialty import divisions of multinational brewers for mass-market reach, while direct-to-consumer subscription channels bypass traditional three-tier systems for craft and organic tiers. Single-source vulnerability in Iranian supply concentration forces European brewers toward Spanish and Italian cooperative partnerships with captive cryogenic processing infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saffron beer represents an early-cycle expansion story where United States craft brewery underpenetration outside established Colorado and California clusters offers substantial runway for adoption acceleration through import partnership structures.
For Market Incumbents: Entrench terroir-proximate positioning by acquiring captive cryogenic grinding capacity in Castilla-La Mancha before equipment backlogs extend to twenty-four months, while securing exclusive offtake agreements with La Mancha Designation of Origin cooperatives to preempt competitor access to certified organic supply. Turmeric substitution in mass-market flavored tiers threatens premium positioning; counter by embedding extraction method transparency into procurement tenders for European hospitality groups. For New Entrants and Emerging Players: Pacific Northwest and Northeast United States microbreweries present the most penetrable white-space geography, where absence of saffron portfolios creates first-mover advantage for Spanish import partnerships targeting culinary tourism corridors. Direct-to-consumer subscription channels offer the fastest path to margin-preserving price points without three-tier distribution burden, while experimental batch releases through brewery taprooms circumvent FDA GRAS compliance requirements for interstate commerce. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among craft specialists with cryogenic processing expertise and captive cooperative relationships, positioning these archetypes for sustained cash flow quality across a five-to-ten-year viability window. Acquisition targets should demonstrate EU organic certification infrastructure and established extraction method transparency protocols. The signal to watch is restaurant chain procurement tender specification intensity for certified-origin documentation, which indicates mainstream adoption inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Grinding Capacity Acquisition | Captive infrastructure in Castilla-La Mancha secures aromatic compound preservation through minus 196 degrees Celsius processing. |
| Direct-to-Consumer Subscription Launch | Bypasses three-tier distribution constraints while enabling margin-preserving price points for limited-release SKUs. |
| EU Organic Certification Investment | La Mancha Designation of Origin labeling commands shelf space premiums through controlled origin requirements. |
| Restaurant Chain Procurement Partnership | Madrid and Barcelona hospitality tenders now mandate farm-level saffron traceability documentation. |
| United States Import Distribution Agreement | Colorado and California microbrewery networks anchor craft infrastructure for saffron portfolio expansion. |
Research Methodology
A standing panel of craft brewing operations managers, saffron cooperative extraction specialists, European hospitality procurement directors, and FDA regulatory affairs consultants provided ongoing calibration across primary fieldwork phases. Secondary validation drew from EU REACH compliance filings, EFSA organic processed food labeling databases, Spanish customs export records for La Mancha Designation of Origin products, and United States TTB formulation approvals. Bottom-up volume modeling across product type, packaging format, and distribution channel segments triangulated against top-down macroeconomic demand indicators.
Scenario-bracketing framed analytical outputs across the projection horizon, with segmentation dimensions spanning craft versus flavored versus organic beer categories, bottle versus can versus keg packaging types, and retail versus online versus on-premise channel structures. CAGRs derived from historical volume trajectories adjusted for cryogenic processing adoption curves, EU F-Gas Regulation compliance timelines, and Iranian supply concentration risk factors. Industry-specific inputs included saffron stigma yield coefficients per hectare and secondary fermentation dosing protocol efficiency rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by multinational flavored beer portfolios or unexpected Iranian sanctions relief would shift outcomes materially. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Vodka Seltzer Market
Alcoholic Beverages
Industrial Alcohol Market
Alcoholic Beverages
Pre-Mixed/RTD Alcoholic Drinks Market
Alcoholic Beverages
Digital Shaker Market
Alcoholic Beverages
Pineapple Beer Market
Alcoholic Beverages
Global Craft Vodka Market
Alcoholic Beverages
Asia-Pacific Kegs Market
Alcoholic Beverages
Wine Barrel Market
Alcoholic Beverages
Woozy Bottle Market
Alcoholic Beverages
Organic Alcoholic Beverages Market
Alcoholic Beverages
Wine Production Machinery Market
Alcoholic Beverages
Beer Mug Market
Alcoholic Beverages
Alcoholic Flavors Market
Alcoholic Beverages
Alcopop Market
Alcoholic Beverages
Grain Neutral Spirits Market
Alcoholic Beverages
India Alcohol Market