
 Organic Wine Market | 2026-2036
Organic Wine Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Wine Market Intelligence
The rise of curated mixed-case offerings and direct-to-consumer subscription models is recalibrating buyer choice away from single-bottle purchases. Bonterra Organic Estate leverages its established brand in North America to capture this direct channel. Global giant Treasury Wine Estates competes on its extensive distribution network, placing organic options in major supermarkets. Meanwhile, Concha y Toro sustains its market position through a diverse portfolio spanning multiple price points.
Organic wine is an alcoholic beverage produced from grapes cultivated under certified organic farming practices, which prohibit synthetic pesticides and fertilizers. Its production process, governed by standards like the USDA NOP, also restricts the use of additives, most notably limiting the total sulfite concentration allowed in the final product. Red Wine and White Wine command the largest volume shares, though Rosé Wine shows significant momentum. Sales through Online Retailers are expanding rapidly, challenging the traditional dominance of Supermarkets and Specialty Stores.
Market access and consumer trust are governed by strict certification frameworks, including the USDA National Organic Program in the United States and the EU's "Euro-leaf" logo under Regulation (EU) 2018/848. These regulations define permissible agricultural practices and vinification techniques, creating a high barrier to entry. Producers must now decide whether to pursue mass-market scale or to emphasize terroir and small-batch authenticity to capture premium buyers.
Market Dynamics
The central tension defining the organic wine market is the divergence between producers pursuing mass-market scale through supermarket channels and those emphasizing small-batch authenticity and terroir to capture premium buyers, a split reinforced by increasingly stringent certification frameworks.
Growth Catalysts
- Consumer Trust Frameworks:The EU's "Euro-leaf" logo and similar certifications provide a clear, trusted signal of quality for consumers, encouraging sommeliers in restaurants across Germany and France to feature organic wines more prominently on their lists.
- Health and Wellness Demand:A growing consumer preference for products with fewer synthetic additives drives interest in organic wine, which is subject to strict limits on sulfite concentrations under regulations like the USDA National Organic Program.
- Vinification Advancements:Innovations in natural stabilization and filtration techniques are improving the quality, consistency, and shelf-life of low-sulfite organic wines, making them more commercially viable for producers and appealing to a broader audience.
Market Restraints
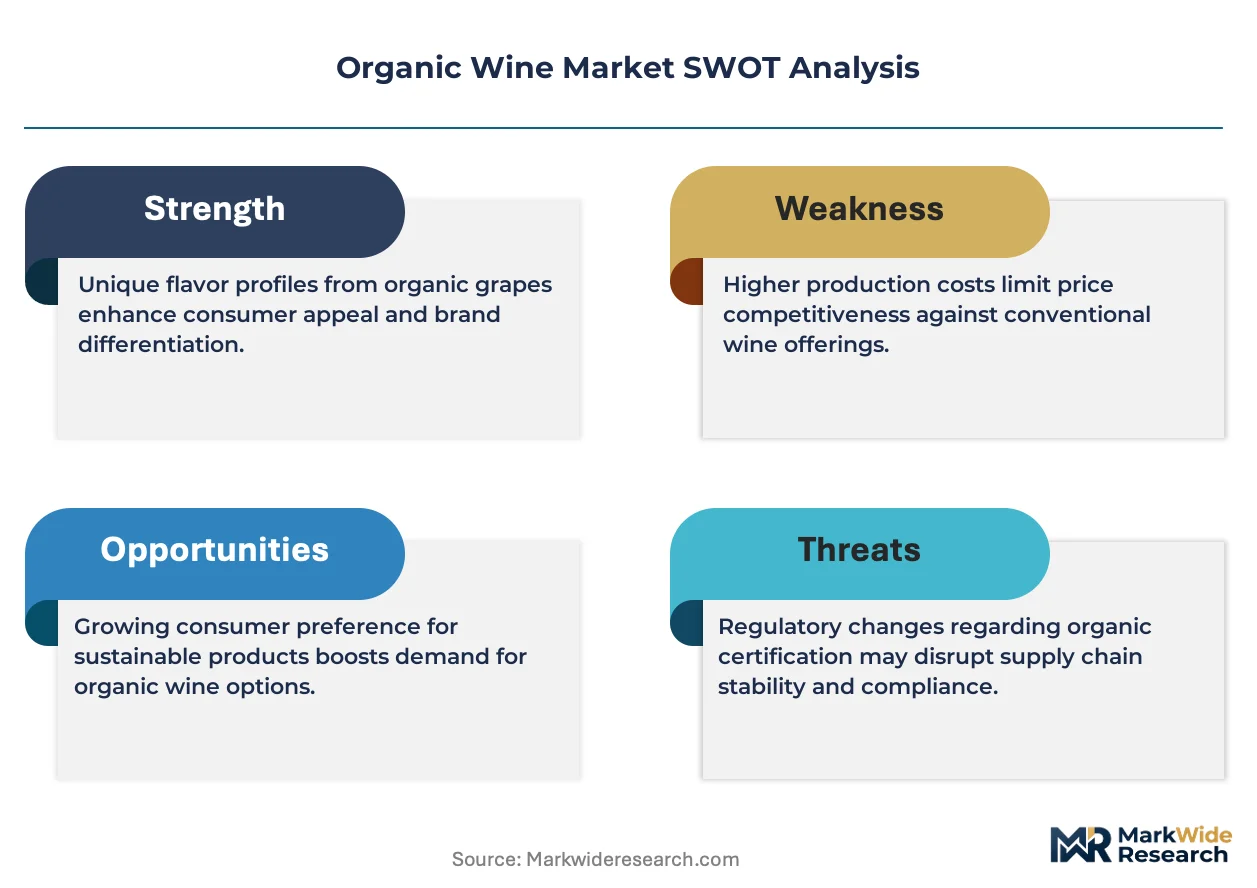
- Elevated Production Costs:Organic viticulture mandates labor-intensive practices such as manual weeding and pest management, leading to higher operational costs that translate into premium pricing, which can deter price-sensitive consumers.
- Climate Vulnerability:Organic vineyards are more susceptible to yield losses from extreme weather events and disease outbreaks, as prohibitions on synthetic fungicides and pesticides limit growers' ability to respond to climate-induced pressures.
- Certification Barriers:The significant time and financial investment required to achieve and maintain organic certification, such as under the USDA NOP, presents a substantial barrier to entry, particularly for small, independent wineries.
Strategic Opportunities
- New Geographic Markets:Significant white-space opportunity exists in affluent Asian markets like Japan and South Korea, where consumer demand for premium, wellness-oriented, and verifiably authentic products is expanding rapidly.
- Channel Innovation:The expansion of direct-to-consumer (DTC) subscription models allows producers to bypass crowded retail shelves, build brand loyalty, and capture higher margins by offering curated mixed-case selections directly to buyers.
- Product Line Extension:Developing certified organic versions of emerging wine categories, including low-alcohol, no-alcohol, and "better-for-you" sparkling wines, can attract new consumer demographics focused on moderation and health.
Industry Challenges
- Supply Chain Integrity:Ensuring temperature-controlled logistics for low-sulfite organic wines during international transit is a critical challenge, as temperature fluctuations can lead to spoilage and compromise product quality before it reaches the consumer.
- Regulatory Fragmentation:Producers face complexity in navigating the differences between major organic certification standards, such as those from the EU and the USDA, which can create friction and add costs to export operations.
- Specialized Skill Scarcity:A shortage of viticulturists and enologists with deep expertise in organic and biodynamic farming and winemaking techniques limits the ability of some wineries to transition or optimize their production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Wine Market |
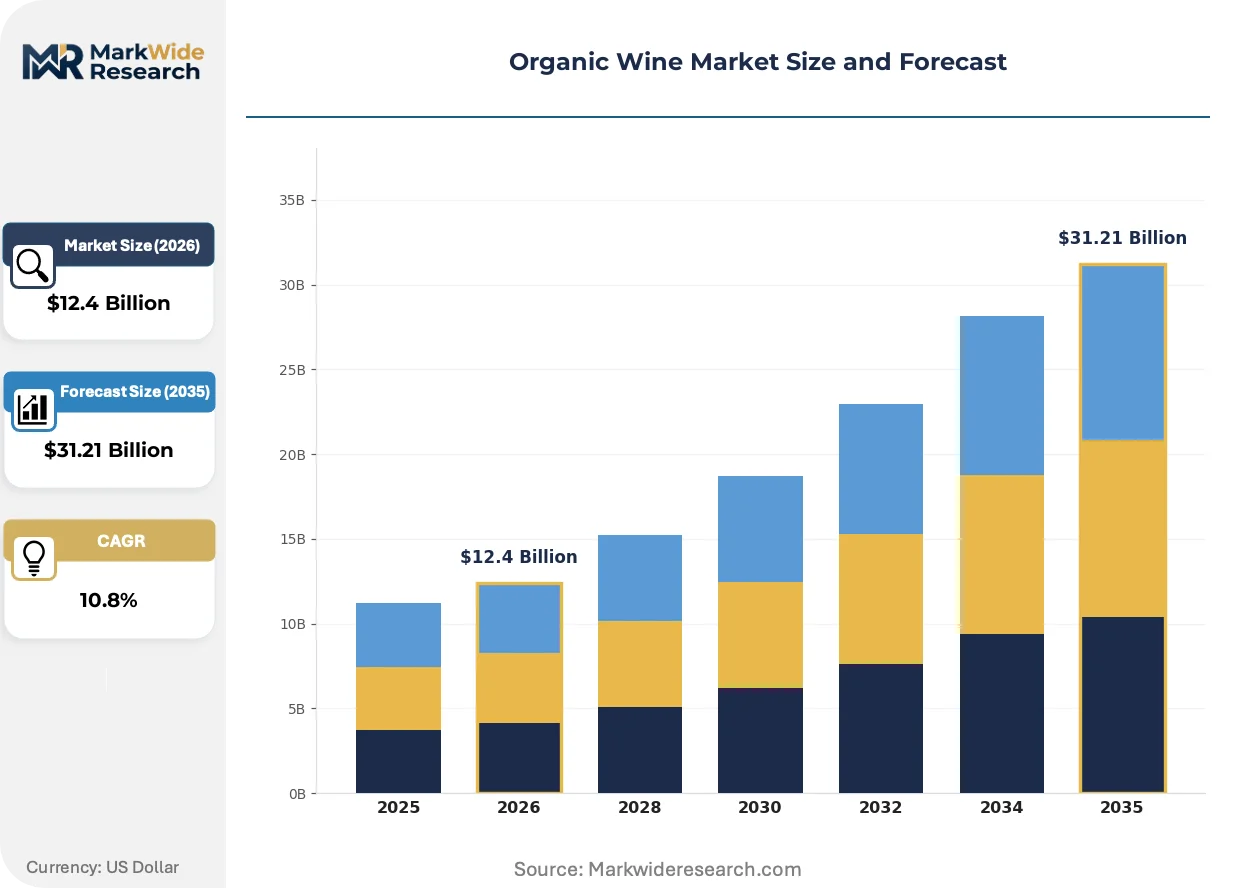
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $31.21 Billion |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Red Wine, White Wine, Rosé Wine, Sparkling Wine, Dessert Wine Grape Variety: Chardonnay, Cabernet Sauvignon, Merlot, Pinot Noir, Sauvignon Blanc Distribution Channel: Supermarkets, Liquor Stores, Online Retailers, Specialty Stores, Restaurants Consumer Demographic: Millennials, Generation X, Baby Boomers, Eco-conscious Consumers, Premium Buyers |
| Companies Covered | Emiliana Organic Vineyards, Concha y Toro, Bronco Wine Company, Bonterra Organic Estate, Frey Vineyards, Kendall-Jackson Winery, Treasury Wine Estates, Societa Agricola Querciabella, King Estate Winery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Wine Market Strategic Shifts & Innovations
The definition of premium organic wine is evolving beyond the mere absence of synthetic inputs. Innovations in viticulture technology and a deeper consumer engagement with production ethics are reshaping quality expectations and competitive positioning across the value chain.
Precision viticulture, utilizing tools like soil sensors and aerial drone imagery, provides granular data on vineyard conditions. Boutique wineries in California and the Bordeaux region of France are adopting these systems to optimize water use and canopy management without synthetic intervention. This data-driven approach is electrifying the relationship between grower and terroir, enabling micro-adjustments that elevate wine quality and consistency.
The European Union's Regulation (EU) 2018/848 enforces stricter rules on organic production and labeling, further limiting permissible vinification aids and processes. This policy compels winemakers to innovate in areas like native yeast cultivation and advanced filtration to ensure product stability and quality. Producers in Italy and Spain are particularly impacted, investing in cellar technology to meet the new standards while preserving their wine's traditional character.
A clear behavioral change is underway as consumers pivot from single-bottle retail buys to curated direct-to-consumer subscription models. This shift disintermediates traditional supermarkets and specialty stores, forging a direct connection and feedback loop between wineries and their customers. The trend is most visible among younger consumer cohorts in the United States and Germany who prioritize discovery, convenience, and producer authenticity.
Organic Wine Market Segmentation
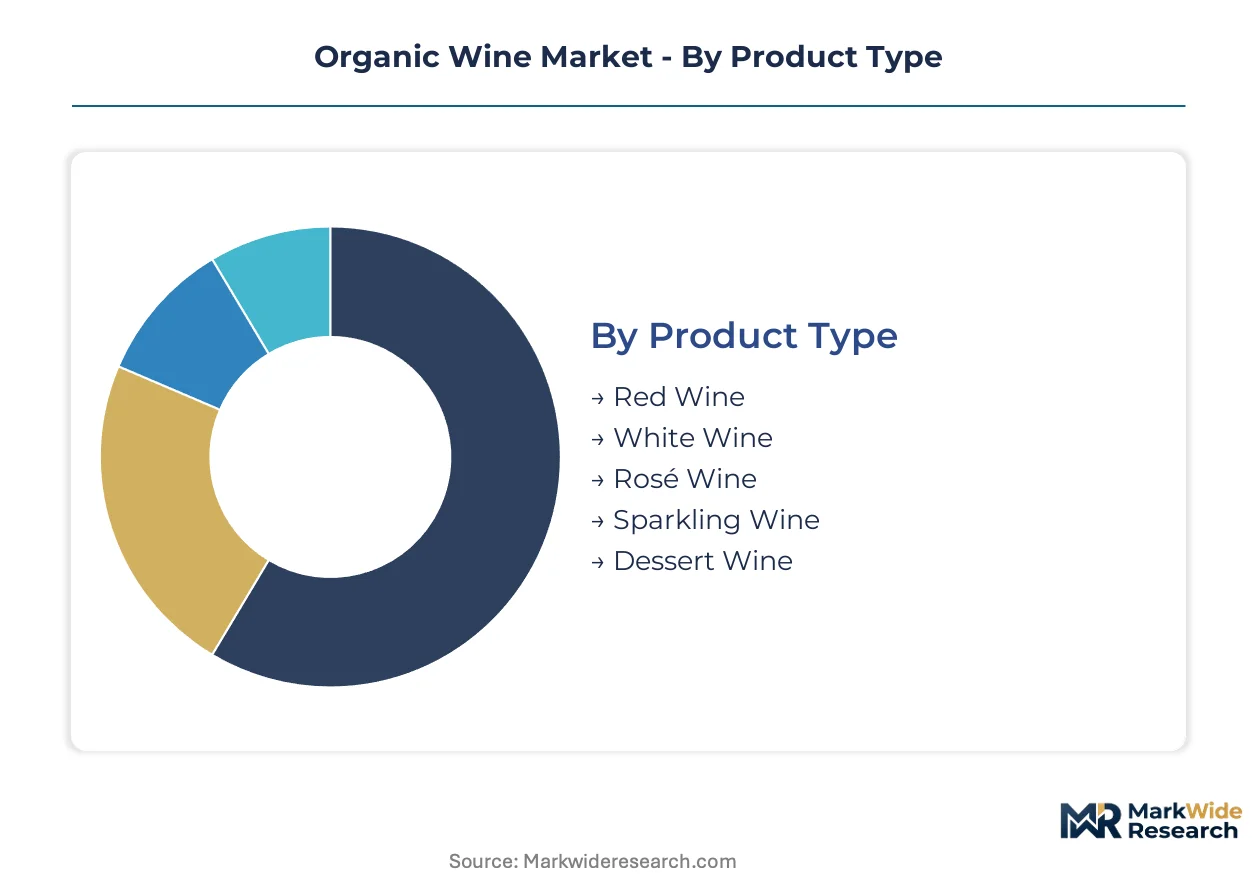
The organic wine market is segmented to analyze diverse product characteristics, varying distribution pathways, and distinct consumer preferences. This granular view reveals how specific product types and grape varieties cater to different buyer demographics, influencing market access and pricing strategies.
Product Type:
The technical specifications of organic wine products define distinct market sub-segments, influencing consumer perception and production techniques.
- Red Wine:Produced through fermentation with grape skins, this category typically features higher tannin levels and a fuller body, appealing to traditional wine drinkers. Demand concentrates heavily within European markets like Germany and France, driven by established culinary traditions.
- White Wine:Fermented without grape skins, white wines generally present a lighter body and crisper acidity, offering versatility for various occasions. The United States and Australia exhibit strong demand for organic white wine options, favored for their refreshing profiles.
- Rosé Wine:Characterized by its pink hue from brief skin contact, rosé wine shows significant momentum among younger consumer cohorts.
- Sparkling Wine:This category includes effervescent wines, often associated with celebratory occasions and increasingly sought after in organic formats for product line extensions.
- Dessert Wine:Sweet wines, often consumed in smaller quantities, cater to a niche market seeking specific culinary pairings and after-dinner experiences.
Mature deployment sits with Red Wine. Newer deployment is concentrated in Rosé Wine.
Grape Variety:
Volume distribution across the organic wine market is heavily influenced by the specific grape varieties cultivated, which dictate regional suitability and consumer familiarity.
- Chardonnay:A highly versatile white grape, Chardonnay adapts well to different winemaking styles, from unoaked and crisp to rich and buttery, often aged in oak barrels. North America, particularly California, drives significant demand for organic Chardonnay due to its broad appeal.
- Cabernet Sauvignon:Known for producing full-bodied red wines with robust tannins and dark fruit flavors, Cabernet Sauvignon is a classic choice for many wine enthusiasts. France and the United States anchor strong demand for organic Cabernet Sauvignon, valued for its aging potential.
- Merlot:This red grape typically yields softer, more approachable wines with smooth textures, often blended or enjoyed as a single varietal.
- Pinot Noir:A delicate red grape, Pinot Noir thrives in cooler climates, producing elegant wines with complex aromatics and lighter body profiles.
- Sauvignon Blanc:Characterized by its crisp acidity and aromatic profile, Sauvignon Blanc offers vibrant citrus and herbal notes, popular in regions like New Zealand and France.
Demand for Cabernet Sauvignon drives significant cultivation efforts, while Pinot Noir is experiencing rapid expansion.
Distribution Channel:
Customer access points for organic wine vary significantly, shaping purchase patterns across different retail and hospitality environments.
- Online Retailers:These platforms leverage direct-to-consumer models and curated mixed-case offerings, providing convenience and discovery for buyers. The United States and Germany show rapid expansion in online organic wine sales, driven by digital-native consumers.
- Supermarkets:Offering broad accessibility and competitive pricing, supermarkets serve as a primary channel for routine grocery shopping and mass-market penetration. Major European markets, including Germany, maintain traditional dominance for organic wine sales through these stores.
- Liquor Stores:These specialized outlets provide a focused selection of alcoholic beverages, often with knowledgeable staff offering expert advice to consumers.
- Specialty Stores:These retailers curate premium ranges and feature niche producers, appealing to buyers seeking unique and high-quality organic wine selections.
- Restaurants:On-premise consumption in restaurants is heavily influenced by sommelier recommendations, which increasingly feature organic wine lists.
The traditional stronghold of Supermarkets faces disruption from the accelerated growth of Online Retailers.
Consumer Demographic:
Margin profiles across the organic wine market are influenced by the purchasing behaviors and willingness-to-pay of distinct consumer demographics.
- Millennials:This digital-native demographic often prioritizes authenticity, sustainability, and transparency in their purchasing decisions, favoring brands with ethical production practices. Consumers in the United States and Germany represent a significant portion of millennial organic wine buyers.
- Premium Buyers:These consumers seek high-quality products, terroir expression, and unique experiences, often willing to pay higher prices for certified organic and small-batch wines. Affluent Asian markets like Japan and South Korea show strong demand from this segment.
- Generation X:This demographic maintains established purchasing habits and demonstrates brand loyalty, often seeking value and consistent quality in their organic wine choices.
- Baby Boomers:With traditional preferences, Baby Boomers consider health implications and established brands when selecting organic wines.
- Eco-conscious Consumers:This group actively seeks products with minimal environmental impact, prioritizing ethical sourcing and sustainable farming practices in their organic wine selections.
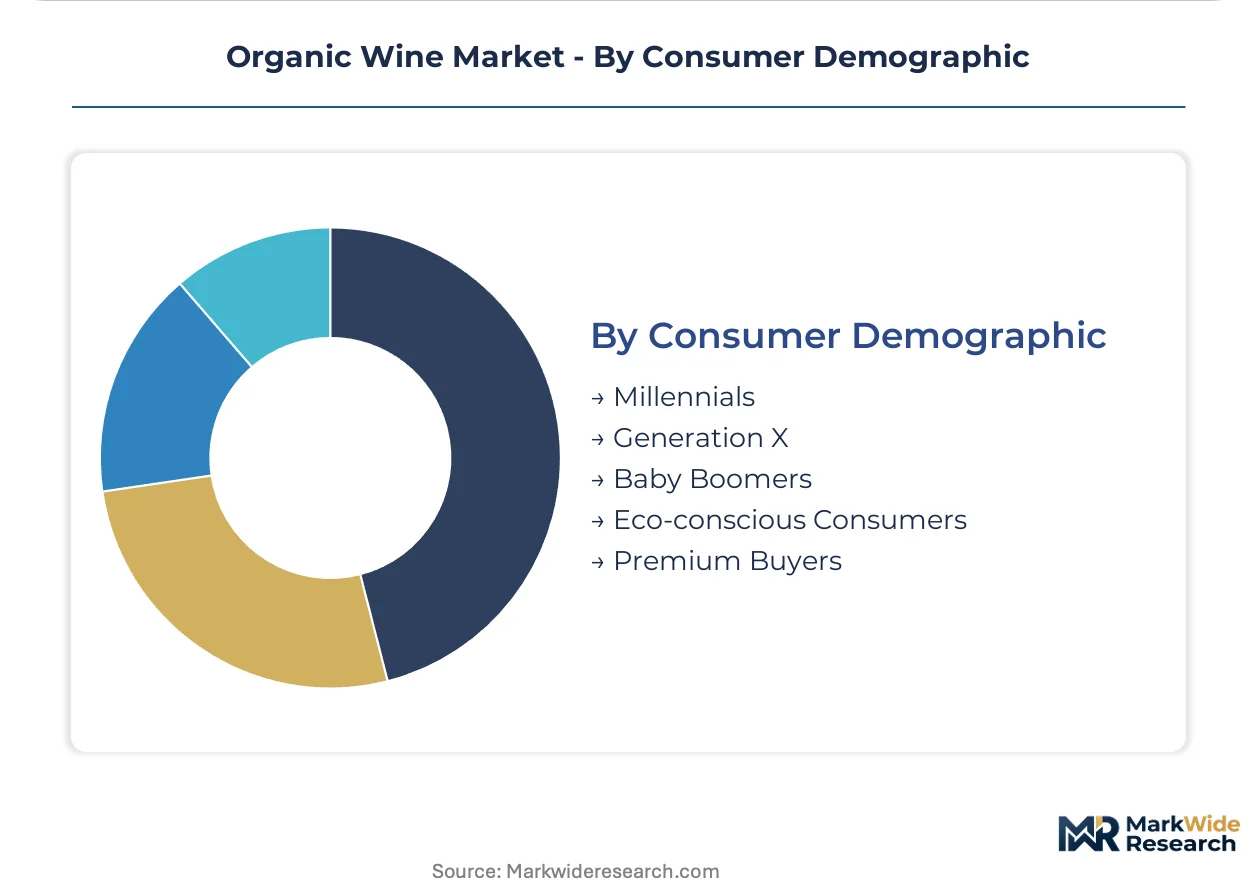
The purchasing power of Generation X continues to anchor market stability, while Millennials represent a critical growth engine.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The organic wine market displays a significant production-versus-consumption divide, with key European nations leading both cultivation and demand. Consumer preferences for health and sustainability are driving expansion across diverse global markets. New certification standards are influencing regional market access and growth trajectories.
Germany
Demand for organic wine in Germany is strong, driven by eco-conscious consumers and prominent restaurant sommeliers. The EU's "Euro-leaf" logo under Regulation (EU) 2018/848 provides critical consumer trust. Munich's specialty stores and Berlin's organic food markets consistently feature a wide array of certified organic wines.
United States
Growing health and wellness trends drive organic white wine demand across the United States. The USDA National Organic Program sets strict standards for organic wine production and labeling. California's Napa Valley and Sonoma regions are investing heavily in organic viticulture and advanced winemaking techniques.
Italy
Italian consumers increasingly seek certified organic wines, valuing both tradition and sustainable practices. Regulation (EU) 2018/848 guides organic farming and vinification processes for producers across the country. Tuscany's boutique wineries and Piedmont's established estates are innovating with native yeast cultivation.
Japan
Affluent consumers in Japan are driving demand for premium, wellness-oriented organic wines. METI promotes sustainable agricultural practices, indirectly supporting organic wine imports. Tokyo's high-end restaurants and department stores are curating exclusive selections of certified organic labels.
France
French culinary traditions increasingly embrace organic wines, particularly in red wine categories. Regulation (EU) 2018/848 dictates stringent organic production rules for French vineyards. Bordeaux and Burgundy producers are adopting precision viticulture to optimize terroir expression without synthetic inputs.
Organic Wine Market Key Industry Players
The competitive structure tilts toward a tiered market, where established global players coexist with specialized organic estates. This market exhibits a blend of consolidation at the top and fragmentation among smaller, authentic producers. Strategic archetypes include large-scale distributors, boutique organic specialists, and diversified wine conglomerates. Key competitive moves involve channel innovation through direct-to-consumer models and product line extensions into emerging categories.
At the scale-driven end, Treasury Wine Estates leverages its extensive distribution network to place organic options in major supermarkets globally, representing a strategy of broad market access. Concha y Toro sustains its market position through a diverse portfolio spanning multiple price points and grape varieties, appealing to a wide consumer base. Bonterra Organic Estate, meanwhile, exemplifies a brand that successfully captures the direct channel through curated mixed-case offerings, building strong brand loyalty among consumers and emphasizing authenticity. These players highlight the dual approach of mass-market penetration and niche premiumization within the organic wine sector.
| Leading Market Players |
|---|
| Emiliana Organic Vineyards |
| Concha y Toro |
| Bronco Wine Company |
| Bonterra Organic Estate |
| Frey Vineyards |
| Kendall-Jackson Winery |
| Treasury Wine Estates |
| Societa Agricola Querciabella |
| King Estate Winery |
Cost & Logistics Intelligence
Labor-intensive viticulture practices for organic grapes translate into higher production costs, directly influencing premium pricing tiers downstream for certified organic wines.
Pricing Analysis
Upward pricing pressure on organic wine stems from elevated cultivation and certification expenses. The market operates with a tiered pricing structure across premium, standard, and economy levels. Price differentiation drivers include stringent certification levels, such as USDA NOP or Euro-leaf, and established brand premium associated with specific terroir. Premium Buyers exhibit the lowest price sensitivity, prioritizing quality and authenticity, while Generation X consumers often seek consistent value.
Supply Chain Analysis
Temperature-controlled logistics for low-sulfite organic wines present a critical cost component in the supply chain, especially during international transit. Geographic supply concentrates in major wine-producing nations like France, Italy, and the United States. The supply chain relies heavily on high-quality organic grape inputs and specialized native yeasts. Climate vulnerability represents a significant structural risk, impacting yield consistency. Distribution runs through a hybrid model, combining mass-market supermarket channels with expanding direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The organic wine market is transitioning as precision viticulture replaces traditional broad-acre farming, fundamentally altering production economics and quality consistency.
For Market Incumbents: Anticipate continued pressure from agile, digitally-native brands leveraging direct-to-consumer models. Incumbents should invest in advanced natural vinification R&D to improve product stability and shelf-life for low-sulfite wines. Expanding distribution networks into affluent Asian markets represents a key defensive move, alongside strategic acquisitions of smaller, authentic organic producers.
For New Entrants and Emerging Players: Regulation (EU) 2018/848 in Europe opens a window for specialized producers focusing on authenticity and sustainability. Target the rapidly expanding low-alcohol and no-alcohol organic wine categories, particularly among younger consumer cohorts in Germany and the United States. A curated mixed-case subscription model offers a compelling go-to-market angle, building direct brand loyalty.
For Investors and Strategic Acquirers: Harmonization of international organic certification standards is the leading indicator that signals market maturation and reduced regulatory friction. The long-term viability of the organic wine sector appears strong over the next five to ten years, driven by sustained consumer health and wellness trends. Acquisition targets should include tech-enabled direct-to-consumer platforms and boutique organic specialists with strong brand equity in niche segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Precision Viticulture | Optimizes water usage and canopy management, enhancing grape quality and yield consistency. |
| Expand Direct-to-Consumer Channels | Builds brand loyalty and captures higher margins by bypassing traditional retail intermediaries. |
| Develop Low-Alcohol Organic Wines | Attracts new consumer demographics focused on moderation and health, expanding product relevance. |
| Secure Organic Certification (Global) | Ensures market access and consumer trust across diverse international regulatory landscapes. |
| Implement Temperature-Controlled Logistics | Maintains product integrity for sensitive low-sulfite organic wines during international shipping. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, which were then validated through primary interviews. This approach combined insights from organic vineyard managers, winery owners, certification auditors, and sommeliers. Bottom-up and top-down triangulation ensured data accuracy and comprehensive market coverage across various segments.
Volume and value outputs were modeled at a granular level across product type, grape variety, distribution channel, consumer demographic, and regional regulatory frameworks. The analytical framework projected market dynamics across the analysis window, deriving compound annual growth rates from historical trends and future projections of key market drivers. Industry-specific forecast inputs included organic land conversion rates and consumer health and sustainability perception indices.
The model assumes a particular technology adoption path; alternative pathways for precision viticulture would alter the outlook. Forecasts reflect assumptions regarding climate stability and regulatory evolution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Craft Beer Market
Alcoholic Beverages
Cooking Wine Market
Alcoholic Beverages
Craft Rum Market
Alcoholic Beverages
South America Fermented Drinks Market
Alcoholic Beverages
Beer Adjuncts Market
Alcoholic Beverages
Asia-Pacific Craft Beer Market
Alcoholic Beverages
Non-Fuel Grade Alcohol Market
Alcoholic Beverages
Beer Dispenser Market
Alcoholic Beverages
Liqueurs Market
Alcoholic Beverages
Premixed Margarita Market
Alcoholic Beverages
Ethyl Alcohol (Ethanol) Market
Alcoholic Beverages
Canada Alcohol E-Commerce Market
Alcoholic Beverages
Spirit-Based RTD Mixes Market
Alcoholic Beverages
High-End Chinese Spirits Market
Alcoholic Beverages
India Alcohol Market
Alcoholic Beverages
Guerbet Alcohols Market