
 Beer Adjuncts Market | 2026-2036
Beer Adjuncts Market Size, Share, and Industry Trends Forecast 2026-2036
Beer Adjuncts Market Analytics
North American corn processors is decoupling from traditional malt supply chains as brewers seek price-stable alternatives to barley. Cargill leverages its grain origination network to secure consistent corn adjunct volumes for large-scale brewers. Briess Malt & Ingredients Co. specializes in custom malted adjunct blends that address craft brewers' flavor specifications. Archer Daniels Midland Company dominates bulk corn grits distribution through integrated elevator-to-brewery logistics.
Beer adjuncts are non-malt carbohydrate sources—typically corn, rice, maltodextrin, or sugar—added to the mash to dilute protein content, lighten body, and reduce raw material costs while maintaining fermentable sugar yields; standard corn grits specifications require 85-90% starch content with protein below 8% to prevent haze formation in finished beer. Powder and granule forms lead volume due to extended shelf stability and predictable dissolution rates in mashing, though liquid extracts are gaining traction among mid-size breweries seeking batch consistency. The brewing application segment anchors value generation, while flavoring applications represent a faster-growing niche as experimental brewers deploy maltodextrin for mouthfeel modulation without residual sweetness.
The FDA governs adjunct labeling and food-grade certification for US-sourced corn and rice products, while the EU Green Deal carbon accounting requirements are pressuring malt houses to document supply chain emissions for adjunct imports. BIS standards in India and GB standards in China impose separate purity thresholds on imported brewing ingredients, fragmenting compliance obligations for multinational suppliers. Stakeholders must monitor how tightening scope-three emissions disclosure rules reshape procurement preferences across integrated brewers and independent craft operators.
Market Dynamics
The EU F-Gas Regulation and tightening scope-three emissions disclosure rules are forcing malt houses to reconfigure sourcing networks and document carbon footprints across adjunct supply chains.
Growth Catalysts
- Carbon accounting mandates:The EU Green Deal requires documented supply chain emissions for imported brewing ingredients, creating competitive advantage for low-carbon corn and rice processors.
- Craft experimentation:Independent brewers in Germany and the United States deploy maltodextrin for mouthfeel modulation without residual sweetness, expanding flavoring applications beyond traditional brewing.
- Price stability mechanisms:Large-scale brewers lock multi-year corn grits contracts through integrated elevator networks, insulating production costs from barley volatility.
Market Restraints
- Input cost volatility:Weather-driven corn and rice price swings compress margin predictability for adjunct-dependent breweries lacking long-term origination contracts.
- Supply concentration risk:Bulk corn grits distribution concentrates among North American grain processors with captive elevator infrastructure, limiting second-source options for European brewers.
- Technical limitation:Standard corn grits specifications requiring 85-90% starch content with protein below 8% restrict acceptable supplier pools and extend qualification timelines.
Strategic Opportunities
- Underpenetrated geography:India's BIS standards for imported brewing ingredients create compliance barriers that first-mover suppliers can convert into market share through certified local partnerships.
- Regulatory tailwind:China's dual carbon goals and GB standards incentivize domestic maltodextrin production with verified low-emission profiles for export-oriented breweries.
- Channel innovation:Direct-to-brewery liquid extract distribution bypasses traditional distributor markups, capturing mid-size operators seeking batch consistency without powder handling infrastructure.
Industry Challenges
- Certification timeline compression:FDA food-grade certification for US-sourced corn products and parallel EU EFSA evaluations extend product launch cycles by 12-18 months for new entrants.
- Integration complexity:Legacy mashing systems designed for traditional malt ratios require recalibration to accommodate higher adjunct loads without enzyme supplementation failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beer Adjuncts Market |
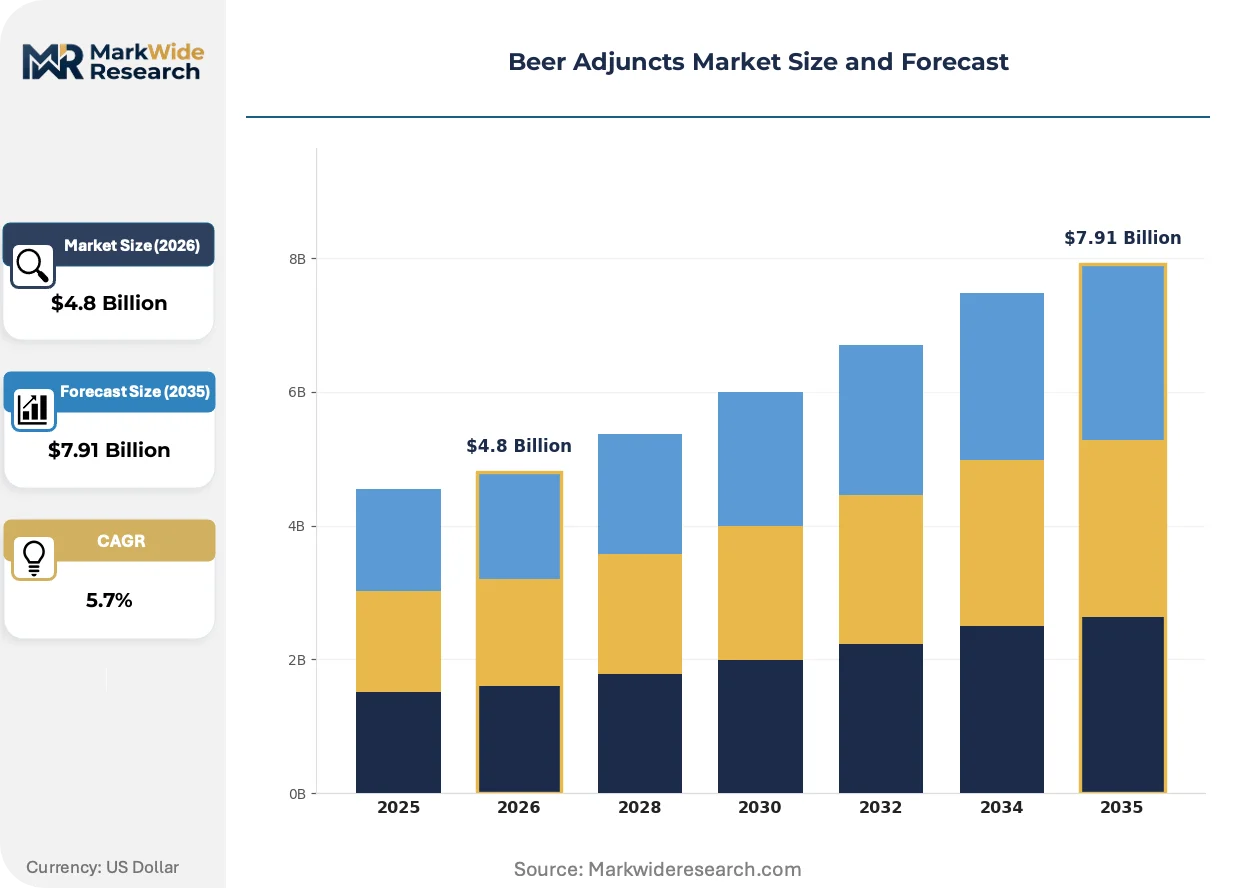
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Corn, Rice, Maltodextrin, Sugar Application: Brewing, Fermentation, Flavoring, Carbonation Form: Powder, Granule, Liquid, Extract Market Channel: Offline, Online, Wholesale, Retail |
| Companies Covered | Cargill, Briess Malt & Ingredients Co., Kerry Group plc, Muntons plc, Brewers Supply Group Inc, Archer Daniels Midland Company, Ingredion, Malteurop, Soufflet Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beer Adjuncts Market Evolving Landscape
Adjunct processing technologies and procurement models are converging to reshape how brewers source, specify, and deploy non-malt carbohydrates across production scales.
Enzymatic adjunct liquefaction systems are rewriting brewhouse efficiency benchmarks by enabling higher gravity worts with reduced energy input. Mid-size craft operators in Belgium and the Czech Republic adopt these systems fastest, drawn by shortened mash cycles and lower steam requirements. The technology is compressing capital recovery timelines for breweries retrofitting legacy infusion mash tuns.
The EU F-Gas Regulation phases down hydrofluorocarbon use in malting and adjunct drying operations, forcing thermal process redesign across supplier facilities. Malt houses in Bavaria and Bohemia retrofit kilns with heat recovery systems to maintain export eligibility under tightening carbon intensity thresholds. Powder and granule adjunct categories face disproportionate compliance costs versus liquid extracts with lower processing energy footprints.
Brewery technical buyers now specify adjunct lots by carbon intensity certificates rather than price-per-pound alone, rotating procurement toward suppliers with documented scope-three disclosures. This specification shift disrupts traditional spot-market purchasing through grain cooperatives, favoring vertically integrated origination networks with audit-ready emissions data. The pattern concentrates in Germany and the Netherlands, where integrated brewers face binding supply chain disclosure requirements under CSRD implementation timelines.
Beer Adjuncts Market Segmentation
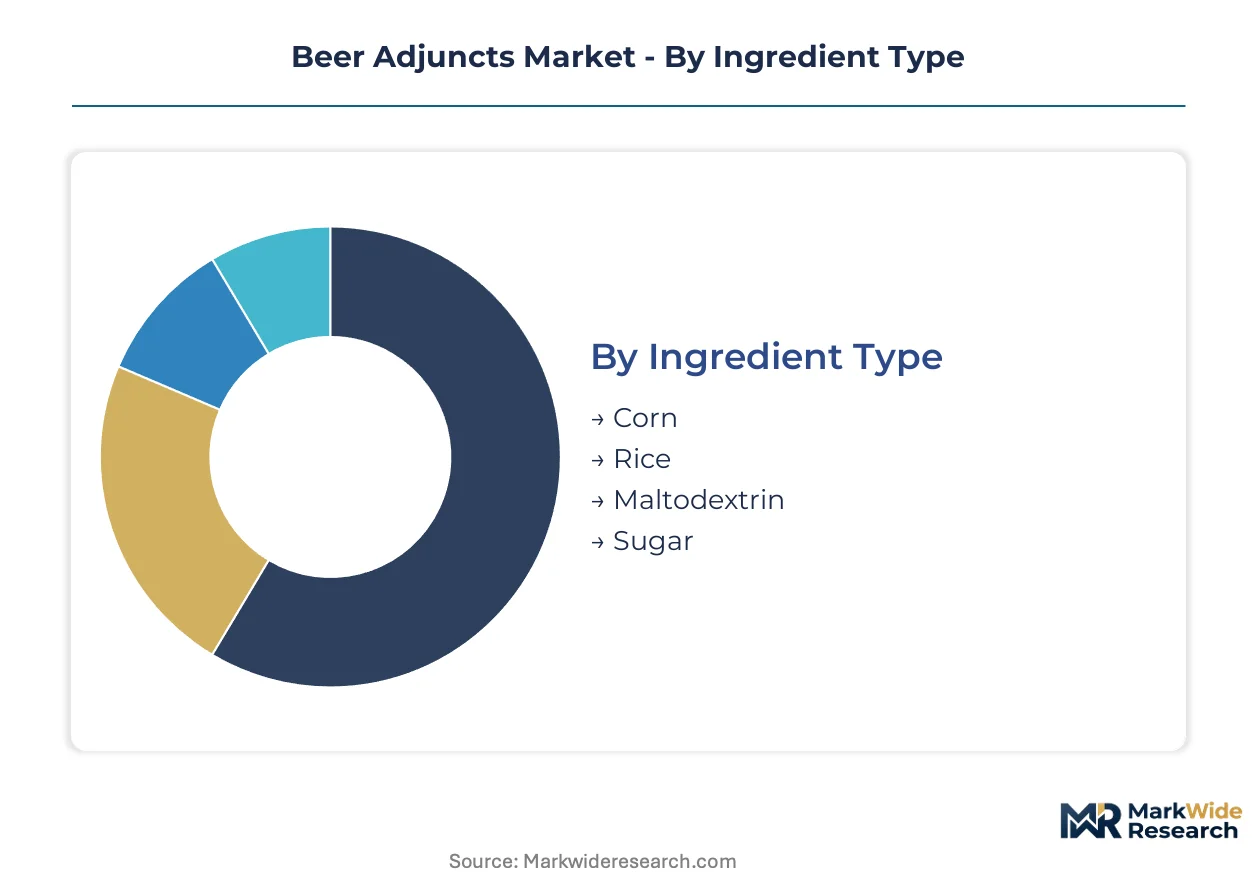
Segmentation in beer adjuncts determines capital allocation across processing infrastructure, procurement contracts, and regulatory compliance pathways. Breweries configure their mash systems and supplier relationships around specific ingredient types and physical forms, creating divergent margin structures and qualification timelines.
Ingredient Type:
Capital intensity varies sharply across ingredient categories, with corn grits processing requiring the heaviest elevator and milling infrastructure while maltodextrin demands specialized enzymatic conversion equipment.
- Corn:Standard specifications mandate 85-90% starch content with protein below 8% to prevent haze formation in finished lagers. Demand concentrates in the United States, where integrated grain processors lock multi-year supply contracts with large-scale brewers seeking insulation from barley price volatility.
- Rice:Adjunct rice delivers the lightest body profiles and lowest protein contribution among major cereals, making it essential for American-style lagers and export formulations targeting Asian markets. German brewers are expanding rice ratios in export-focused production to meet cost targets without sacrificing clarity.
- Maltodextrin:Enzymatically derived from corn or tapioca starch, this soluble carbohydrate enables mouthfeel modulation without residual sweetness. Craft experimentation in Belgium and the United States is displacing traditional sugar additions in experimental recipes.
- Sugar:Sucrose and dextrose sources provide rapid fermentability for high-gravity brewing and alcohol extension, though purity thresholds under FDA and EFSA guidelines extend supplier qualification timelines.
Corn absorbs the bulk of installed capacity across North American and European brewing; maltodextrin is expanding most quickly as flavoring applications multiply.
Application:
End-use configuration determines enzyme supplementation requirements, brewhouse cycle times, and the regulatory scrutiny applied to finished product labeling.
- Brewing:Primary mash adjunct deployment for gravity adjustment and body lightening consumes the largest volume share, with standard load rates of 20-40% adjunct in American lager formulations. Integrated brewers in Germany and the Netherlands now specify carbon intensity certificates alongside traditional quality metrics.
- Fermentation:Adjunct sugars introduced during fermentation extend alcohol content without diluting flavor, a technique concentrated in high-gravity brewing operations. The approach demands precise nitrogen supplementation to prevent stalled fermentations.
- Flavoring:Maltodextrin and specialty syrups modulate mouthfeel and perceived sweetness without fermentable residue, a niche climbing fastest among craft operators seeking differentiation. Belgian mid-size breweries adopt these techniques fastest.
- Carbonation:Priming sugars for bottle conditioning represent a minor volume segment with specialized purity requirements under BIS and GB standards for export markets.
Brewing commands the dominant share of adjunct volume; flavoring is climbing the fastest as experimental brewers diversify beyond traditional style guidelines.
Form:
Physical state selection drives handling infrastructure requirements, shelf stability profiles, and energy inputs across supplier processing facilities.
- Powder:Spray-dried adjuncts offer extended shelf stability and predictable dissolution rates, though pneumatic handling systems require capital investment. EU F-Gas Regulation compliance costs for thermal drying disproportionately burden this category.
- Granule:Agglomerated particles reduce dust generation and improve flow characteristics for automated dosing systems. Large-scale American brewers favor granule corn grits for elevator-to-brewery logistics integration.
- Liquid:Syrup concentrates eliminate powder handling infrastructure and enable precise volumetric dosing, appealing to mid-size operators without pneumatic systems. Energy footprints run lower than dried alternatives.
- Extract:Highly concentrated carbohydrate solutions target craft breweries seeking batch consistency without mashing raw grains, a channel expanding through direct-to-brewery distribution models.
Powder and granule forms dominate volume through legacy infrastructure; liquid extracts are gaining share fastest among operators retrofitting brewhouses for efficiency.
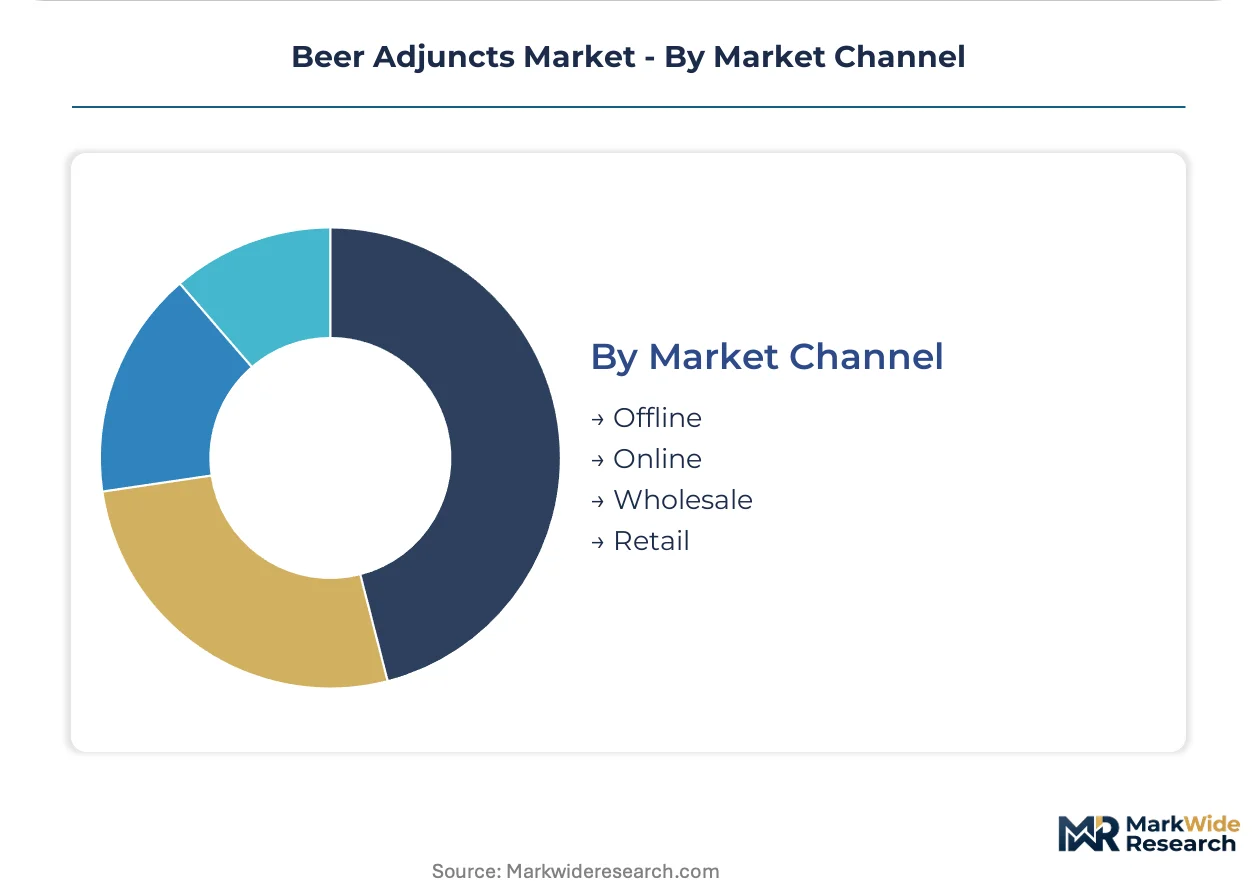
Market Channel:
Channel structure determines price realization, technical support intensity, and the documentation burden for regulatory compliance across jurisdictions.
- Offline:Direct sales through grain cooperatives and ingredient distributors remain the default for large breweries with established supplier relationships and qualified quality assurance protocols.
- Online:E-procurement platforms are displacing traditional phone-and-fax ordering for smaller craft operators, though food-grade certification documentation requirements complicate pure digital transactions.
- Wholesale:Bulk purchasing through integrated grain elevators captures cost advantages for high-volume brewers with storage capacity and multi-year contract appetite.
- Retail:Small-package adjunct sales to homebrewers and nano-breweries represent minimal volume but highest per-unit margins, concentrated in specialty ingredient shops and direct-to-consumer platforms.
Wholesale channels capture the majority of volume throughput; online procurement is expanding most quickly as mid-size breweries digitize supplier management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Barley fields in North Dakota and Minnesota anchor the upstream supply base for corn grits processing, while Bavarian malt houses drive downstream formulation standards for export lagers.
United States
Large-scale brewers in the Midwest lock multi-year corn grits contracts through integrated elevator networks. The FDA governs adjunct labeling and food-grade certification for domestic corn products. Processing clusters concentrate in Iowa and Illinois, where Cargill and Archer Daniels Midland Company operate captive origination infrastructure.
Germany
Traditional brewing standards intersect with experimentation in adjunct ratios for export lagers. The EU F-Gas Regulation and EU Green Deal carbon accounting requirements pressure malt houses to document supply chain emissions. Bavarian kilns in Munich and Bamberg retrofit with heat recovery systems to maintain export eligibility under tightening carbon intensity thresholds.
China
Domestic maltodextrin production scales to serve export-oriented breweries across Asia-Pacific. GB standards impose purity thresholds on imported brewing ingredients, fragmenting compliance obligations for multinational suppliers. Shandong Province hosts concentrated enzymatic conversion facilities serving both brewing and flavoring applications.
India
BIS standards for imported brewing ingredients create compliance barriers that first-mover suppliers convert into market share through certified local partnerships. The FSSAI regulates food-grade adjunct imports alongside BIS technical specifications. Maharashtra and Karnataka emerge as brewing hubs where craft operators experiment with rice adjunct ratios for lighter body profiles.
Belgium
Mid-size craft breweries adopt maltodextrin for mouthfeel modulation without residual sweetness faster than neighboring markets. EFSA evaluations run parallel to national purity requirements under EU harmonized standards. Flemish brewing clusters around Leuven and Ghent deploy enzymatic adjunct liquefaction systems to shorten mash cycles and lower steam requirements.
Beer Adjuncts Market Competitive Landscape
Global majors compete with regional champions across origination networks and carbon disclosure capabilities. The vendor base splits between integrated grain processors with captive elevator infrastructure and specialized malt houses with custom blending expertise. Three archetypes dominate: North American bulk commodity handlers, European malt specialists, and Asian enzymatic conversion operators. Capacity expansion and backward integration into origination networks constitute the dominant competitive moves as brewers prioritize supply security over spot-market flexibility.
Among North American integrated processors, Cargill and Archer Daniels Midland Company exemplify the scale-driven archetype with elevator-to-brewery logistics networks. Briess Malt & Ingredients Co. occupies a position within the specialty tier, representing custom formulation capabilities that address craft brewers' flavor specifications. These three anchors illustrate how competitive positioning diverges between commodity volume handlers and specification-driven blenders.
| Leading Market Players |
|---|
| Cargill |
| Briess Malt & Ingredients Co. |
| Kerry Group plc |
| Muntons plc |
| Brewers Supply Group Inc |
| Archer Daniels Midland Company |
| Ingredion |
| Malteurop |
| Soufflet Group |
| Others |
Value Network & Pricing Analysis
Chicago Board of Trade corn futures volatility cascades through beer adjunct supply chains into three distinct pricing tiers: premium certified-organic lots with full carbon disclosure, standard food-grade grits with basic FDA documentation, and economy-grade options for cost-sensitive high-volume brewers.
Pricing Analysis
Technical service bundling separates premium-tier suppliers from commodity handlers, with carbon-certificate verification and on-site brewhouse calibration included in contracted rates while spot-market transactions leave enzyme optimization and quality troubleshooting unbundled. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with EU Green Deal compliance documentation commanding substantial premiums over basic FDA food-grade certification. Cost compression in the economy tier is intensifying as barley price volatility drives more brewers toward corn grits, squeezing handlers without captive origination infrastructure. Large-scale integrated brewers with multi-year contracts show the least price sensitivity, while independent craft operators without elevator access face the highest procurement cost volatility.
Supply Chain Analysis
Regional distribution centers in Iowa, Illinois, and Nebraska anchor North American corn grits logistics, with hub-and-spoke patterns radiating from processing clusters to brewery destinations across the Midwest and export ports. Geographic supply concentration centers on the United States, Germany, and China, with enzymatic conversion capacity scaling fastest in Shandong Province. Raw material flows draw from North Dakota and Minnesota barley-corn rotation fields, Thai fragrant rice varieties, and Brazilian tapioca starch for maltodextrin production. Single-source vulnerability runs through Cargill and Archer Daniels Midland Company elevator networks, which control bulk origination infrastructure. Distribution runs through integrated grain cooperatives for large brewers and specialty ingredient distributors for craft operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The beer adjuncts market functions as a cost-of-compliance story where EU F-Gas Regulation carbon intensity thresholds and CSRD scope-three disclosure requirements erect substantial barrier-to-entry moats favoring suppliers with audit-ready emissions documentation and certified processing infrastructure.
For Market Incumbents: Cement market position by retrofitting kilns with heat recovery systems to maintain export eligibility under tightening EU carbon intensity thresholds, while extending backward integration into origination networks to lock multi-year supply contracts that insulate against barley price volatility. The threat of enzymatic liquefaction system displacement by craft operators demands technical service bundling that locks in switching costs through on-site brewhouse calibration support. For New Entrants and Emerging Players: Launch via direct-to-brewery liquid extract distribution to bypass entrenched grain cooperative channels, targeting mid-size Belgian and Czech craft operators seeking batch consistency without powder handling capital investment. India's BIS certification barriers represent the most penetrable white-space geography, where certified local partnerships convert compliance obligations into defensible market share. Flavoring applications for maltodextrin mouthfeel modulation offer the fastest-expanding application niche with lowest incumbent saturation. For Investors and Strategic Acquirers: Distressed-cycle entries favor enzymatic conversion specialists with verified low-emission profiles in Shandong Province and Bavaria, where regulatory tailwinds from China's dual carbon goals and EU Green Deal implementation create acquisition optionality. Long-term viability over the next decade hinges on scope-three disclosure capabilities becoming table stakes for integrated brewer procurement. The signal to watch is CSRD enforcement timelines accelerating specification shifts toward carbon-intensity certificates as primary buying criteria.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Recovery Kiln Retrofit | Bavarian malt houses maintain EU F-Gas Regulation export eligibility through thermal process redesign. |
| Backward Integration into Origination | Integrated elevator networks secure multi-year corn grits contracts against barley price volatility. |
| Enzymatic Liquefaction System Deployment | Belgian craft operators shorten mash cycles and reduce steam requirements through technology adoption. |
| Direct-to-Brewery Liquid Extract Channel | Mid-size operators bypass distributor markups while achieving batch consistency without pneumatic infrastructure. |
| Carbon Intensity Certification Investment | German integrated brewers meet CSRD supply chain disclosure requirements through documented scope-three data. |
Research Methodology
Multi-period observation of corn futures volatility, EU carbon intensity threshold implementations, and craft brewery capacity expansions anchored the trend analysis, supplemented by interviews with plant managers at North American grain processors, procurement leads at integrated brewers, technical R&D directors at malt houses, and distribution channel partners across European markets. Secondary validation drew from FDA food-grade certification databases, EFSA evaluation registries, BIS technical specifications, customs and trade data for corn and rice flows, and SEC filings from major grain processors. Bottom-up volume modeling across ingredient types, applications, and forms triangulated against top-down market sizing from production capacity assessments.
Segment-weighting approaches distributed value across corn, rice, maltodextrin, and sugar categories with further disaggregation by powder, granule, liquid, and extract forms, while application splits between brewing, fermentation, flavoring, and carbonation shaped volume trajectories. CAGRs were derived from elasticity-adjusted demand projections incorporating brewer capacity expansion plans and regulatory compliance cost passthrough assumptions. Industry-specific forecast inputs included EU F-Gas Regulation phase-down schedules and CSRD implementation timelines for supply chain disclosure requirements.
Weather-driven commodity price swings, regulatory enforcement delays, and craft brewery closure rates are the dominant revision risks that could compress or extend projected expansion trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
North America Soju Market
Alcoholic Beverages
South America Fermented Drinks Market
Alcoholic Beverages
Dark Beer Market
Alcoholic Beverages
Cooking Wine Market
Alcoholic Beverages
Canada Alcohol E-Commerce Market
Alcoholic Beverages
Absinthe Market
Alcoholic Beverages
Bioalcohols Market
Alcoholic Beverages
Asia-Pacific Tequila Market
Alcoholic Beverages
Coconut Alcohol Market
Alcoholic Beverages
Europe Wine Market
Alcoholic Beverages
Hard Kombucha Market
Alcoholic Beverages
High-End Baijiu Market
Alcoholic Beverages
Mezcal Market
Alcoholic Beverages
Middle East and Africa Fermented Drinks Market
Alcoholic Beverages
Vodka Seltzer Market
Alcoholic Beverages
North America Alcoholic Beverages Market