
 Asia-Pacific Wine Market | 2026-2036
Asia-Pacific Wine Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Wine Market Outlook
The capital-intensity divergence between boutique estate producers and mass-market bottlers is collapsing as climate adaptation costs equalize vineyard investment thresholds. Yantai Changyu Pioneer Wine Co Ltd leverages its Shandong terroir control to dominate domestic red-wine distribution. Treasury Wine Estates sustains premium positioning through Penfolds brand equity and direct-to-retail channel strength in Greater China.
Asia-Pacific wine encompasses fermented grape beverages with alcohol content typically ranging from 11.5% to 15% ABV, produced through controlled yeast conversion of sugars followed by aging in stainless steel or oak vessels. Red wine commands the largest volume share across the region, though sparkling wine generates disproportionate margin concentration in celebratory and gift segments. Bottles remain the dominant packaging format for premium and super-premium tiers, while tetra packs occupy the economy segment where price-sensitive urban consumers in India and Southeast Asia drive repeat purchase frequency.
Australia's Food Standards Code, China's SAMR labeling directives, and India's FSSAI import certification requirements collectively shape product formulation, packaging disclosure, and cross-border market access protocols. Compliance costs favor larger producers with dedicated regulatory affairs capacity, squeezing mid-tier importers. Stakeholders must monitor evolving excise structures and e-commerce alcohol licensing frameworks as digital channels capture share from traditional retail and on-premise routes.
Market Dynamics
Climate adaptation costs are compressing the capital gap between boutique Barossa Valley estates and mass-market Australian bottlers, forcing vineyard consolidation across the Asia-Pacific region.
Growth Catalysts
- China's SAMR labeling directives:Mandatory disclosure reforms are accelerating premium product differentiation as producers compete on transparency credentials.
- Sparkling wine gift segments:Celebratory consumption patterns in urban Southeast Asia are expanding margin-rich gifting channels for premium producers.
- Shandong terroir control:Domestic Chinese producers leveraging regional grape supply dominance are capturing distribution scale previously held by import-dependent competitors.
Market Restraints
- Climate input volatility:Water scarcity and heat stress in Australia's Margaret River cluster are destabilizing cool-climate varietal yields and vintage consistency.
- Import certification friction:India's FSSAI requirements create multi-month clearance delays that freeze working capital for mid-tier distributors.
- Substitution by ready-to-drink spirits:Younger consumers in Southeast Asian metropolitan markets are pivoting toward convenience-oriented alcoholic alternatives.
Strategic Opportunities
- Vietnam's underpenetrated Ho Chi Minh City corridor:Premium dining expansion in this emerging market offers first-mover positioning before competitor saturation.
- E-commerce alcohol licensing liberalization:Digital channel regulatory easing in select Asia-Pacific jurisdictions enables direct-to-consumer bypass of traditional retail gatekeepers.
- AI-driven precision viticulture:Convergence of satellite imagery and soil sensor networks is enabling yield optimization for estates managing climate-stressed terroirs.
Industry Challenges
- Certification timeline compression:Australia's Food Standards Code updates are forcing reformulation cycles that outpace smaller producers' technical staffing capacity.
- Legacy distributor integration:Direct-to-retail channel buildouts by major brands are stranding traditional import partnerships and creating contract renegotiation conflicts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Wine Market |
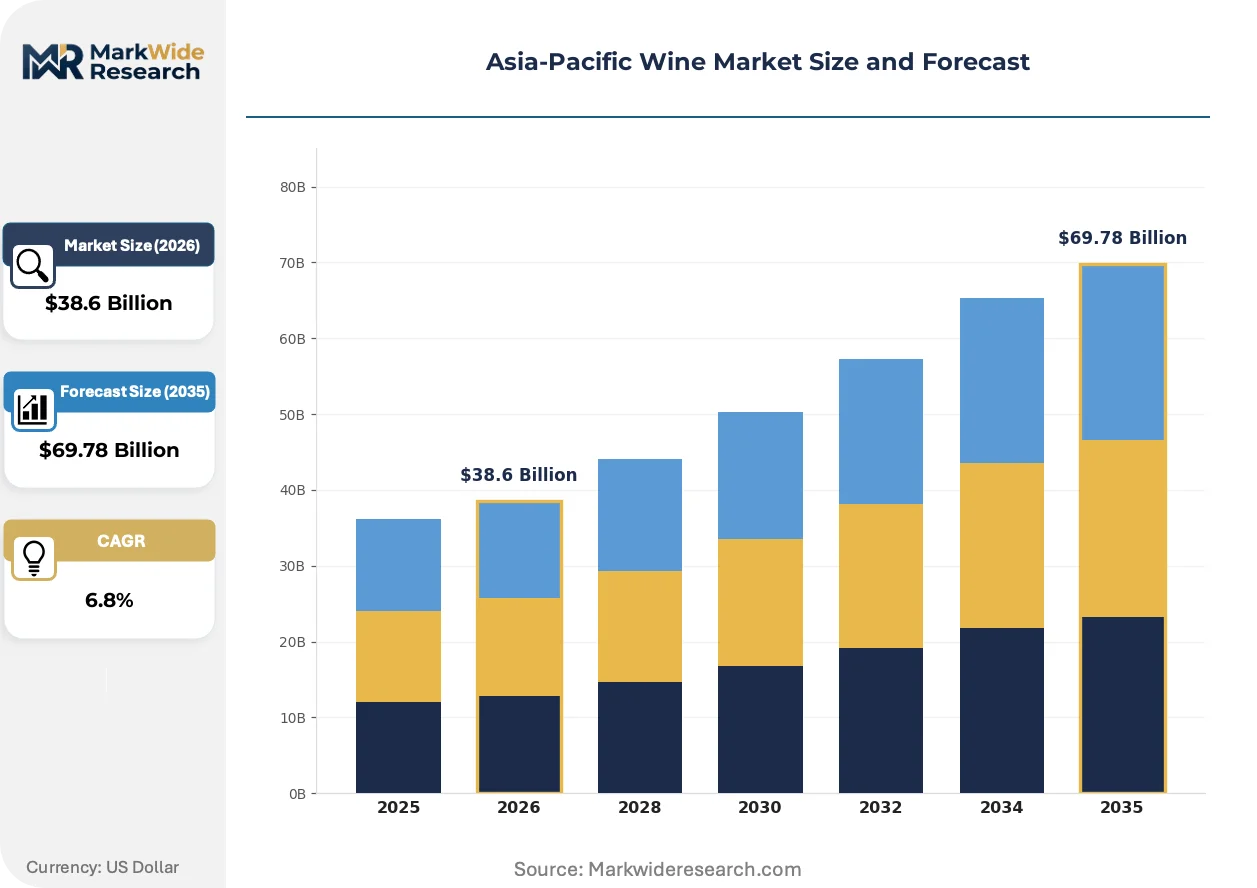
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Red Wine, White Wine, Sparkling Wine, Rosé Wine Packaging Type: Bottles, Casks, Tetra Packs, Kegs Sales Channel: Retail Stores, Online Sales, Distributors, Restaurants Price Tier: Premium, Economy, Super Premium, Mass |
| Companies Covered | Accolade Wines, Dynasty Fine Wines Group, Yantai Changyu Pioneer Wine Co Ltd, Sula Vineyards, Tonghua Grape Wine Co Ltd, Constellation Brands, Wei Long Grape Wine Co Ltd, Grover Vineyards, Treasury Wine Estates, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Wine Market Strategic Shifts
Digital channel capture from traditional retail routes is forcing simultaneous investment in compliance infrastructure and last-mile logistics across Asia-Pacific wine markets.
Precision fermentation monitoring systems using real-time sugar and pH analytics are bifurcating quality control standards between technology-adopting estates and conventional producers. Premium Australian vineyards in the Barossa Valley are deploying these sensors at accelerated rates. This technology compression is enabling vintage consistency that commands price premiums while marginalizing non-adopting competitors.
China's National Health Commission tightened labeling requirements for alcoholic beverages in recent regulatory cycles, compelling producers to reformulate disclosure practices across ingredient sourcing and additive transparency. Industrial consequence includes accelerated SKU consolidation as smaller import portfolios fail compliance cost thresholds. Premium and super-premium tiers are responding fastest, using enhanced transparency as competitive differentiation against economy-segment competitors.
Buyer concentration among Southeast Asian premium dining establishments is rotating procurement authority toward sommelier-driven list curation rather than distributor push models. Traditional import agents are losing volume to direct-retail relationships as restaurant groups consolidate purchasing across regional chains. This shift is most visible in Singapore and Bangkok, where hospitality group scale enables supplier bypass and customized private-label development.
Asia-Pacific Wine Market Segmentation
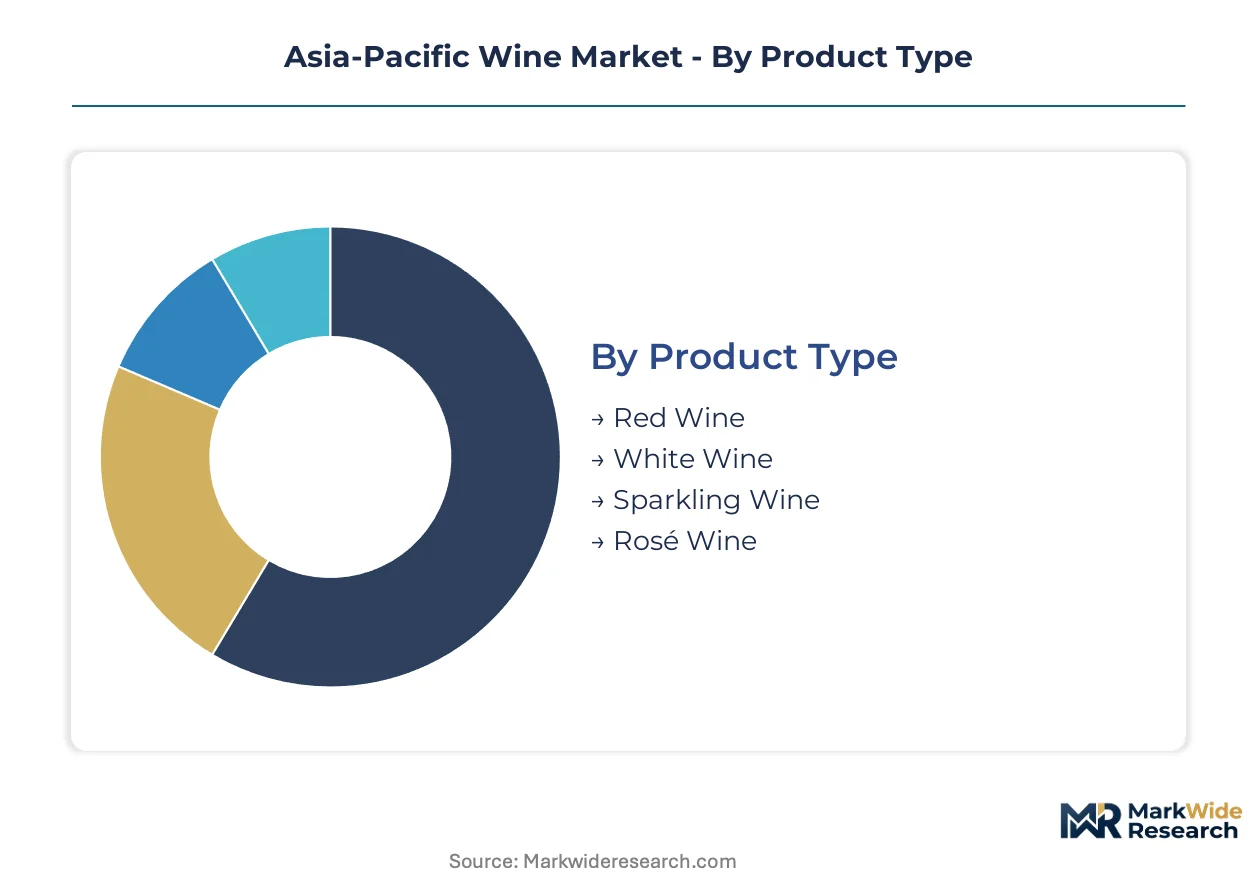
Wine segmentation across Asia-Pacific reflects divergent margin architectures between gift-driven premium tiers and volume-heavy economy channels. Producer investment prioritizes segments where regulatory compliance costs create defensive moats against import competition.
Product Type:
Margin pools concentrate in varietals where terroir scarcity supports sustained price premiums against commodity substitutes.
- Red Wine:Fermented with grape skins intact, delivering tannin structure and age-worthiness. Demand concentrates in China's Shandong corridor, where domestic producers exploit regional supply control to displace import-dependent competitors facing labeling compliance burdens.
- Sparkling Wine:Secondary fermentation creates persistent carbonation, traditionally via méthode champenoise or tank processes. Southeast Asian metropolitan gift segments in Singapore and Bangkok rotate procurement authority toward sommelier-driven curation, expanding margin-rich celebratory channels.
- White Wine:Skin-contact exclusion produces lighter body and higher acidity profiles suited to regional cuisine pairing.
- Rosé Wine:Limited skin contact yields intermediate color and tannin extraction, gaining trial among younger urban consumers.
Red wine holds installed capacity. Sparkling wine is rotating up the share rankings.
Packaging Type:
Packaging economics bifurcate between premium bottle aesthetics and economy-format logistics efficiency.
- Bottles:Glass containers with cork or screwcap closure dominate super-premium and premium tiers. Australia's Barossa Valley estates deploy precision fermentation monitoring to justify bottle-format price premiums through vintage consistency credentials.
- Tetra Packs:Aseptic cartons with laminated barrier layers occupy economy segments where price-sensitive urban consumers in India and Vietnam drive repeat purchase frequency through modern trade penetration.
- Casks:Bag-in-box formats with tap dispensing reduce per-liter packaging cost for informal consumption occasions.
- Kegs:Stainless steel returnable vessels serve on-premise volume accounts with throughput economics.
Bottles command the value pool. Tetra packs are climbing the fastest on volume metrics.
Sales Channel:
Channel restructuring accelerates as regulatory easing permits digital alcohol licensing in select jurisdictions.
- Restaurants:On-premise consumption with sommelier-mediated selection. Premium dining expansion across Ho Chi Minh City's underpenetrated corridor offers first-mover positioning before competitor saturation.
- Online Sales:Direct-to-consumer platforms bypassing traditional retail gatekeepers. China's SAMR labeling directives favor producers with dedicated regulatory affairs capacity, squeezing mid-tier importers from digital channel participation.
- Retail Stores:Licensed physical outlets with inventory depth and staff-assisted selection.
- Distributors:Traditional import agents facing volume erosion as major brands build direct-to-retail relationships.
Restaurants anchor premium throughput. Online sales are expanding most quickly on regulatory tailwinds.
Price Tier:
Three-tier pricing stratification separates gift-grade positioning from daily consumption economics.
- Premium:Positioned above economy through terroir designation or brand heritage. Australia's Margaret River cluster sustains buyer interest for cool-climate varietals despite water scarcity and heat stress destabilizing yields.
- Super Premium:Ultra-premium positioning with limited production runs and provenance documentation. Treasury Wine Estates leverages Penfolds brand equity to sustain this tier through direct-to-retail channel strength in Greater China.
- Economy:Volume-focused pricing with standardized blends and minimal aging.
- Mass:Entry-tier positioning for price-sensitive trial and informal occasions.
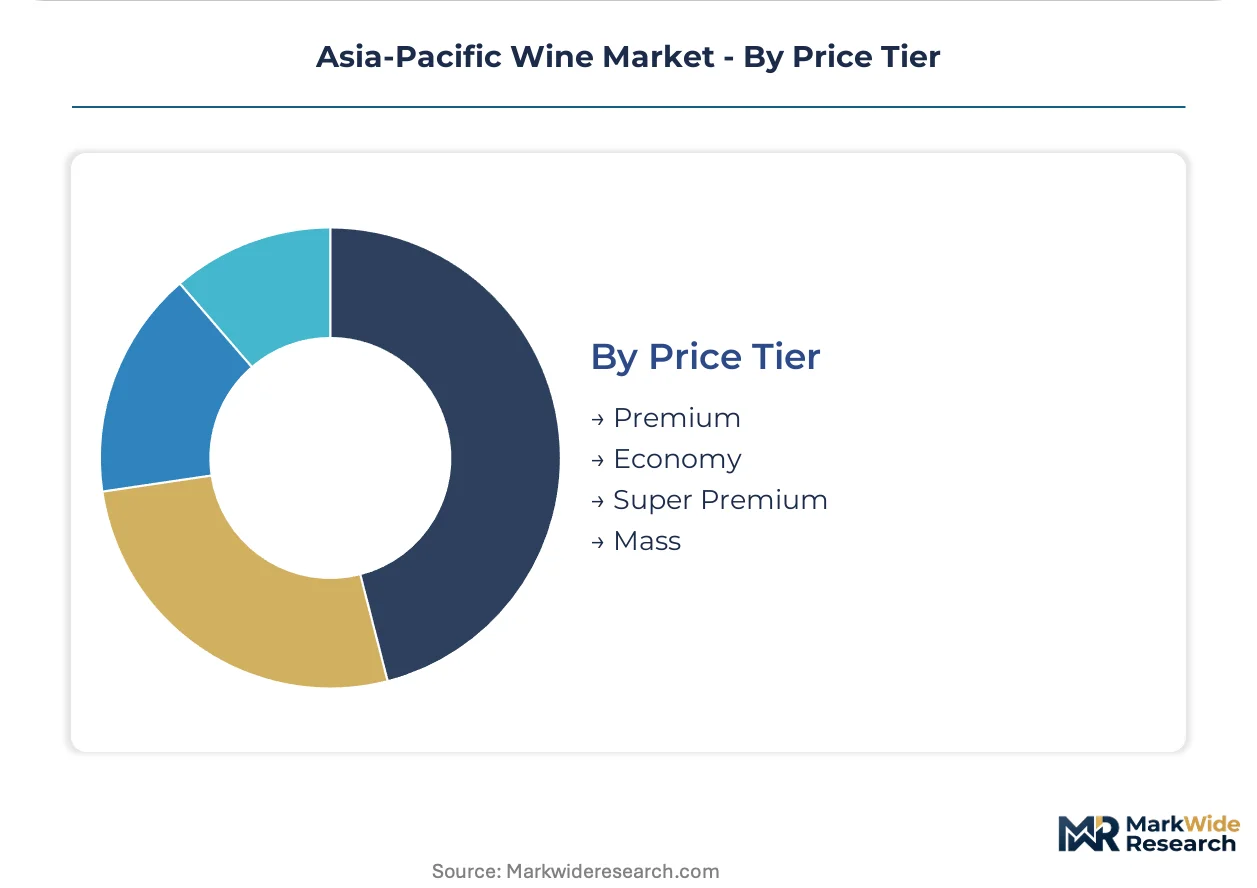
Super premium captures margin concentration. Premium is gaining share fastest on middle-class expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in China's Shandong corridor outstrips Australia's Margaret River cluster by a widening margin as domestic supply control displaces import-dependent competitors. Domestic producers leverage terroir dominance to capture distribution scale previously held by foreign labels facing compliance burdens.
China
Shandong province anchors domestic red-wine capacity through Yantai Changyu Pioneer's regional grape supply control. SAMR labeling directives compel reformulation cycles that favor dedicated regulatory affairs capacity. The Yangtze River Delta concentrates premium dining procurement authority toward sommelier-driven curation.
Australia
Barossa Valley estates deploy precision fermentation monitoring to justify bottle-format premiums through vintage consistency. The Food Standards Code updates force technical staffing investments that compress smaller producers' margins. Margaret River clusters sustain cool-climate varietal buyer interest despite water scarcity destabilizing yields.
India
Maharashtra's Nashik district hosts Sula Vineyards' installed capacity serving price-sensitive urban consumers through modern trade penetration. FSSAI import certification requirements create multi-month clearance delays freezing working capital for mid-tier distributors. Tetra pack formats dominate repeat purchase frequency in Mumbai and Delhi metropolitan corridors.
Vietnam
Ho Chi Minh City's underpenetrated premium dining corridor offers first-mover positioning before competitor saturation. E-commerce alcohol licensing liberalization enables direct-to-consumer bypass of traditional retail gatekeepers. Tetra pack economy segments capture price-sensitive trial among younger urban consumers.
Singapore
Hospitality group procurement consolidation rotates authority toward direct-retail relationships and customized private-label development. Sparkling wine gift segments expand margin-rich celebratory channels through sommelier-mediated selection. Restaurant chain scale enables supplier bypass stranding traditional import agents.
Asia-Pacific Wine Market Competitive Environment
Concentration sits with terroir-controlled domestic producers and brand-equity multinational portfolios. The vendor base spans three tiers: Shandong-based supply dominators, Australian premium estates with direct-to-retail channel strength, and Indian modern-trade specialists. Competitive moves center on regulatory compliance infrastructure buildout and hospitality procurement consolidation bypassing legacy distributors.
Among China-based supply controllers, Yantai Changyu Pioneer Wine Co Ltd and Tonghua Grape Wine Co Ltd exemplify terroir-anchored domestic producers leveraging regional grape dominance. Treasury Wine Estates occupies a position representing Australian premium portfolio strength through Penfolds brand equity and Greater China channel depth. Sula Vineyards anchors Indian modern-trade penetration serving price-sensitive urban consumers through format-optimized packaging.
| Leading Market Players |
|---|
| Accolade Wines |
| Dynasty Fine Wines Group |
| Yantai Changyu Pioneer Wine Co Ltd |
| Sula Vineyards |
| Tonghua Grape Wine Co Ltd |
| Constellation Brands |
| Wei Long Grape Wine Co Ltd |
| Grover Vineyards |
| Treasury Wine Estates |
| Others |
Value Chain & Pricing Dynamics
Ninety-day inventory cycles in Australia's Margaret River cluster compress working capital efficiency and amplify vintage-to-vintage price volatility for cool-climate varietals. This lead-time exposure concentrates pricing power with Shandong-based producers who command domestic grape supply continuity.
Pricing Analysis
The customization-premium spread between sommelier-curated restaurant lists and standard retail formats exceeds three-to-one in Southeast Asian metropolitan markets. Three-tier pricing structure across premium, standard, and economy levels dominates, with terroir designation and SAMR compliance certification as primary differentiation drivers. Pricing pressure stems from climate input volatility in Australian growing regions, eroding margin buffers for import-dependent distributors. Economy-tier tetra pack segments exhibit highest price sensitivity among urban Indian and Vietnamese consumers, while super-premium bottle formats sustain inelastic demand in Singapore and Bangkok gift channels.
Supply Chain Analysis
China and Australia anchor Asia-Pacific wine production, with Shandong province and Barossa Valley estates commanding distinct terroir advantages. Raw material dependencies center on Shandong grape supply, Australian oak barrel cooperage, and imported yeast strains for controlled fermentation. Single-source vulnerability concentrates in Shandong's regional grape dominance, exposing competitors to supply disruption from domestic policy shifts. Distribution runs through direct-to-retail channel buildouts by Treasury Wine Estates and Yantai Changyu Pioneer, bypassing legacy import agents in Greater China and Southeast Asian hospitality corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of dedicated regulatory affairs capacity separates viable competitors from compliance-squeezed mid-tier operators across Asia-Pacific wine markets. This capability gap intensifies as SAMR, FSSAI, and Food Standards Code updates accelerate reformulation cycles.
For Market Incumbents: Consolidate vineyard holdings in climate-stressed Margaret River and Barossa Valley clusters to secure cool-climate varietal supply continuity against heat stress and water scarcity. Deepen backward integration into Shandong grape supply networks to defend distribution scale against domestic Chinese producers. Prioritize direct-to-retail channel control in Ho Chi Minh City and Singapore hospitality corridors before competitor saturation erodes first-mover positioning. For New Entrants and Emerging Players: Differentiate on AI-driven precision viticulture credentials to command vintage consistency premiums in premium and super-premium tiers. Target Vietnam's underpenetrated e-commerce alcohol channel as regulatory liberalization enables direct-to-consumer bypass of stranded import agents. Pursue private-label partnerships with consolidating Southeast Asian restaurant groups seeking customized list development outside traditional distributor relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational beverage portfolios seeking to divest non-core wine assets amid category margin compression. Long-term viability hinges on terroir-controlled supply positions and regulatory compliance infrastructure rather than brand equity alone. Monitor FSSAI certification timeline compression in India and SAMR disclosure enforcement in China as inflection indicators for working capital stress among mid-tier import-dependent competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Viticulture Technology Deployment | Barossa Valley estates leverage sensor networks to justify bottle-format premiums through vintage consistency credentials. |
| Direct-to-Retail Channel Expansion | Penfolds brand equity sustains super-premium positioning through bypass of traditional import agents in Greater China. |
| Regulatory Affairs Capacity Buildout | Dedicated compliance teams capture SAMR labeling directive advantages over mid-tier competitors facing SKU consolidation. |
| Terroir-Controlled Vineyard Consolidation | Shandong grape supply dominance enables Yantai Changyu Pioneer to displace import-dependent competitors in domestic red-wine distribution. |
| E-Commerce Alcohol Licensing Positioning | Digital channel regulatory easing in Vietnam enables direct-to-consumer bypass of traditional retail gatekeepers. |
Study Parameters
A standing panel of vineyard operations directors, regulatory affairs managers at import houses, sommelier procurement leads for Southeast Asian hospitality groups, and modern trade category buyers provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with these stakeholders and secondary validation against customs import records, FSSAI certification databases, SAMR disclosure filings, and Food Standards Code update registers. Bottom-up volume triangulation from provincial production statistics and top-down value estimation from retail audit data converged on segment-level outputs.
Consistency checks against external benchmarks validated analytical framework outputs across the projection horizon. Segmentation dimensions modeled include product type, packaging format, sales channel, and price tier, with additional granularity on regulatory compliance burden by jurisdiction. CAGRs derived from vintage-adjusted production trends and channel shift elasticity parameters, incorporating climate stress indices for Australian growing regions and e-commerce penetration curves for Southeast Asian markets.
Material uncertainties — excise structure revisions, e-commerce alcohol licensing reversals, and climate-induced vintage failures — sit outside the modeled envelope. Forecasts reflect assumptions on regulatory enforcement continuity and consumer preference stability that material shifts in named drivers could invalidate. Recalibration cycles align with material shifts in SAMR directive implementation, FSSAI clearance timelines, and precision viticulture adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Hogshead Barrel Market
Alcoholic Beverages
RTD Bottled Cocktails Market
Alcoholic Beverages
Fruit Brandy Market
Alcoholic Beverages
Grain Alcohol Market
Alcoholic Beverages
Honey Wine Market
Alcoholic Beverages
Middle East and Africa Wine Market
Alcoholic Beverages
Cigar and Cigarillos Market
Alcoholic Beverages
Beer Adjuncts Market
Alcoholic Beverages
Stout Market
Alcoholic Beverages
Cider and Perry Market
Alcoholic Beverages
Global Malted Barley Market
Alcoholic Beverages
Puncheon Barrel Market
Alcoholic Beverages
Tea Beer Market
Alcoholic Beverages
Vodka Seltzer Market
Alcoholic Beverages
Europe Wine Market
Alcoholic Beverages
N-Hexyl Alcohol Market