
 Fish-Free Omega-3 Ingredients Market | 2026-2036
Fish-Free Omega-3 Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Fish-Free Omega-3 Ingredients Market Foresight
Premium algal oil with verified EPA/DHA potency is repositioning away from commodity flaxseed and chia alternatives on price and clinical substantiation. Koninklijke DSM N.V. leverages its life sciences division to sustain high-purity fermentation-derived omega-3 output for infant formula clients. BASF SE anchors European supply through microbial oil platforms that compete on batch consistency and contaminant-free profiles. Croda International Plc differentiates via lipid chemistry expertise that controls encapsulation stability for pharmaceutical applications.
Fish-free omega-3 ingredients comprise EPA, DHA, and ALA fatty acids extracted from non-marine biomass through fermentation, cold-pressing, or solvent-free supercritical CO2 methods, typically standardized to 15-40% omega-3 concentration for nutraceutical and food fortification use. Algae oil dominates source type segmentation due to direct DHA biosynthesis without trophic conversion losses, while microbial oil captures fastest growth from precision-fermentation yield improvements. Powder and capsule forms lead product form segmentation by shelf-life stability and dosing precision, though emulsion formats are gaining share in functional beverages where oil dispersion challenges persist.
FDA GRAS notifications and EFSA Novel Food opinions shape market access timelines for new microbial and algal strains, with REACH compliance adding purity documentation burdens for European cosmetic applications. EPA and OSHA guidelines govern solvent residues and worker exposure limits in extraction facilities, particularly for hexane-alternative processes. Stakeholders must monitor evolving pharmacopeial monographs for algal DHA as pharmaceutical companies evaluate fish-free alternatives for prescription omega-3 therapies.
Market Dynamics
Precision fermentation yield improvements are compressing production costs for microbial-derived EPA and DHA, forcing algal oil suppliers to defend margin positions through pharmaceutical-grade certification and infant formula contract exclusivity.
Growth Catalysts
- FDA GRAS pathway streamlining:The FDA's GRAS notification process for microbial oils accelerates novel strain commercialization, reducing time-to-market for fermentation-derived omega-3 suppliers targeting US nutraceutical brands.
- Vegan capsule demand from supplement manufacturers:German pharmaceutical-grade procurement contracts demonstrate how algal oil EPA/DHA potency verification commands premium positioning over flaxseed alternatives in ethical-label segments.
- EFSA Novel Food opinions:European regulatory clarity on algal strain safety creates predictable approval timelines, enabling capital deployment into EU-located extraction facilities.
Market Restraints
- Hexane-alternative extraction capex:Supercritical CO2 and solvent-free cold-pressing equipment requires substantial capital outlay, concentrating processing capacity among well-capitalized fermentation platform operators.
- REACH compliance documentation:European cosmetic applications face purity verification burdens that extend commercialization timelines and inflate regulatory affairs staffing costs.
- Flaxseed and chia price competition:Plant-based ALA sources maintain cost advantages in economy-tier fortification, limiting algal oil penetration in price-sensitive food applications.
Strategic Opportunities
- Prescription omega-3 therapy substitution:Pharmaceutical companies evaluating fish-free DHA alternatives for prescription cardiovascular applications present high-margin offtake potential pending pharmacopeial monograph adoption.
- Functional beverage emulsion formats:Oil dispersion technology advances enable algae-derived omega-3 integration into ready-to-drink products, bypassing capsule form limitations.
- OSHA-guided extraction automation:Worker exposure limit compliance for hexane-alternative processes incentivizes capital investment in closed-system fermentation and automated downstream processing.
Industry Challenges
- Pharmacopeial monograph delays:Absence of finalized algal DHA standards in major pharmacopeias stalls pharmaceutical company formulation decisions and contract negotiations.
- Fermentation specialist talent scarcity:Microbial strain optimization and lipid chemistry expertise concentrates among limited personnel pools, inflating compensation and retention costs.
- Batch-to-batch potency verification:EPA/DHA concentration standardization demands sophisticated analytical chemistry capabilities that smaller suppliers struggle to maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fish-Free Omega-3 Ingredients Market |
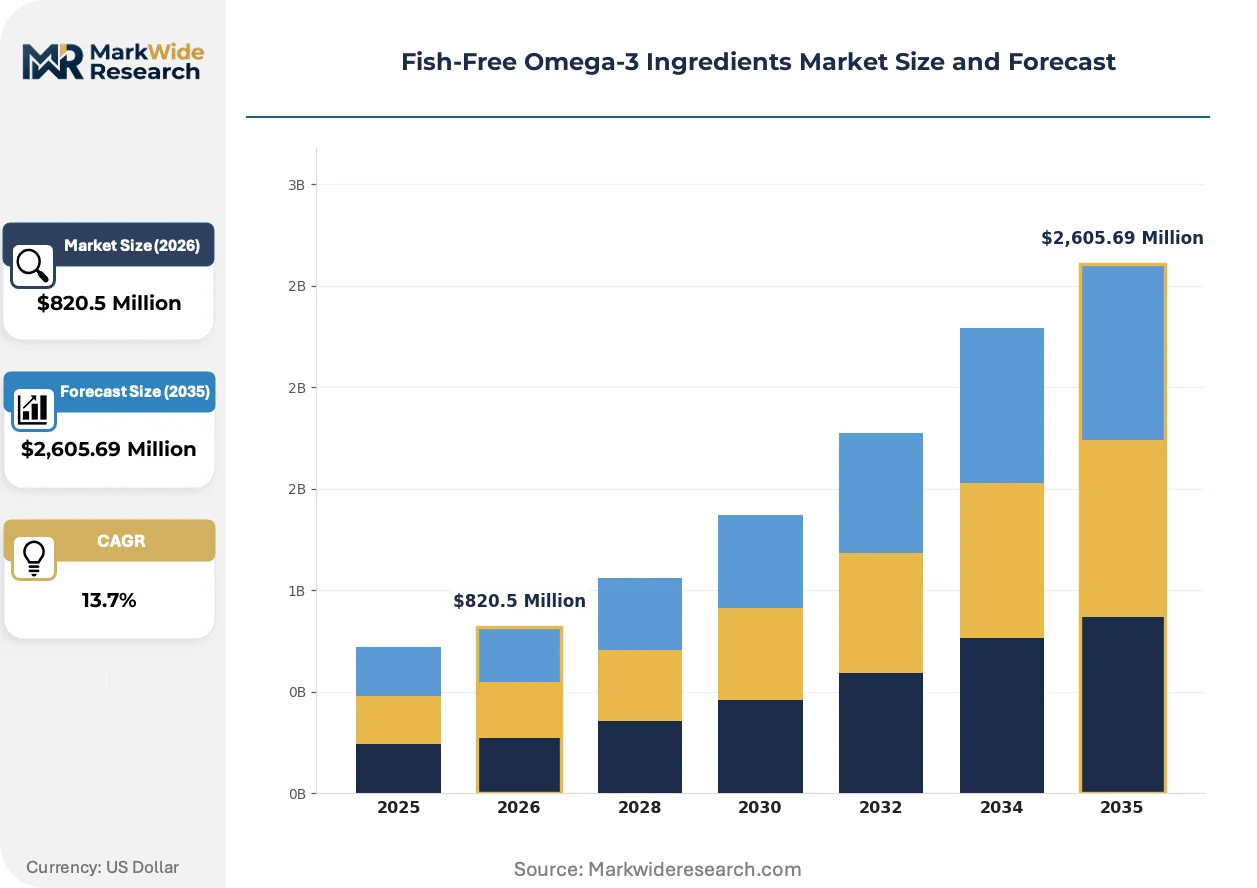
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $2,605.69 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Source Type: Algae Oil, Microbial Oil, Plant-Based, Fungal Oil, Egg Oil, Others Product Form: Oil, Powder, Capsule, Emulsion, Gel, Crystal Application: Dietary Supplements, Infant Nutrition, Functional Foods, Animal Feed, Pharmaceuticals, Cosmetics End User: Supplement Manufacturers, Pet Food Producers, Pharmaceutical Companies, Cosmetic Brands, Nutraceutical Firms, Food Processors |
| Companies Covered | Croda International Plc, Archer Daniels Midland Company, Koninklijke DSM N.V., Neptune Wellness Solutions Inc., Epax Norway AS, BASF SE, Corbion, Cellana Inc., Cargill Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fish-Free Omega-3 Ingredients Market Shifts & Advancements
Bioprocess engineering advances and regulatory clarity are converging to reposition fish-free omega-3 from niche vegan alternatives toward mainstream pharmaceutical and clinical nutrition applications.
Precision fermentation platforms producing microbial oils with tunable fatty acid profiles are overtaking traditional algal cultivation methods in capital efficiency. Infant formula manufacturers in North America and Europe are accelerating qualification programs for fermentation-derived DHA. This technology compression is enabling suppliers to offer contaminant-free profiles at scale previously unattainable through photobioreactor cultivation.
REACH documentation requirements for European cosmetic applications are tightening purity thresholds for lipid ingredients. ECHA compliance burdens now demand comprehensive residual solvent and heavy metal testing that smaller extraction facilities cannot support. German and Swiss cosmetic formulators are consolidating supplier bases toward integrated fermentation-to-lipid-chemistry operations with in-house analytical capabilities.
Direct-to-practitioner distribution is gaining traction among clinical nutrition specialists seeking verified-potency algal oil for patient protocols. Traditional supplement retail channels face disintermediation as functional medicine practitioners in the United States and Australia establish preferred supplier relationships with batch-tested fermentation operators. This channel shift rewards transparency investments and punishes commodity-positioned flaxseed competitors lacking clinical substantiation packages.
Fish-Free Omega-3 Ingredients Market Segmentation
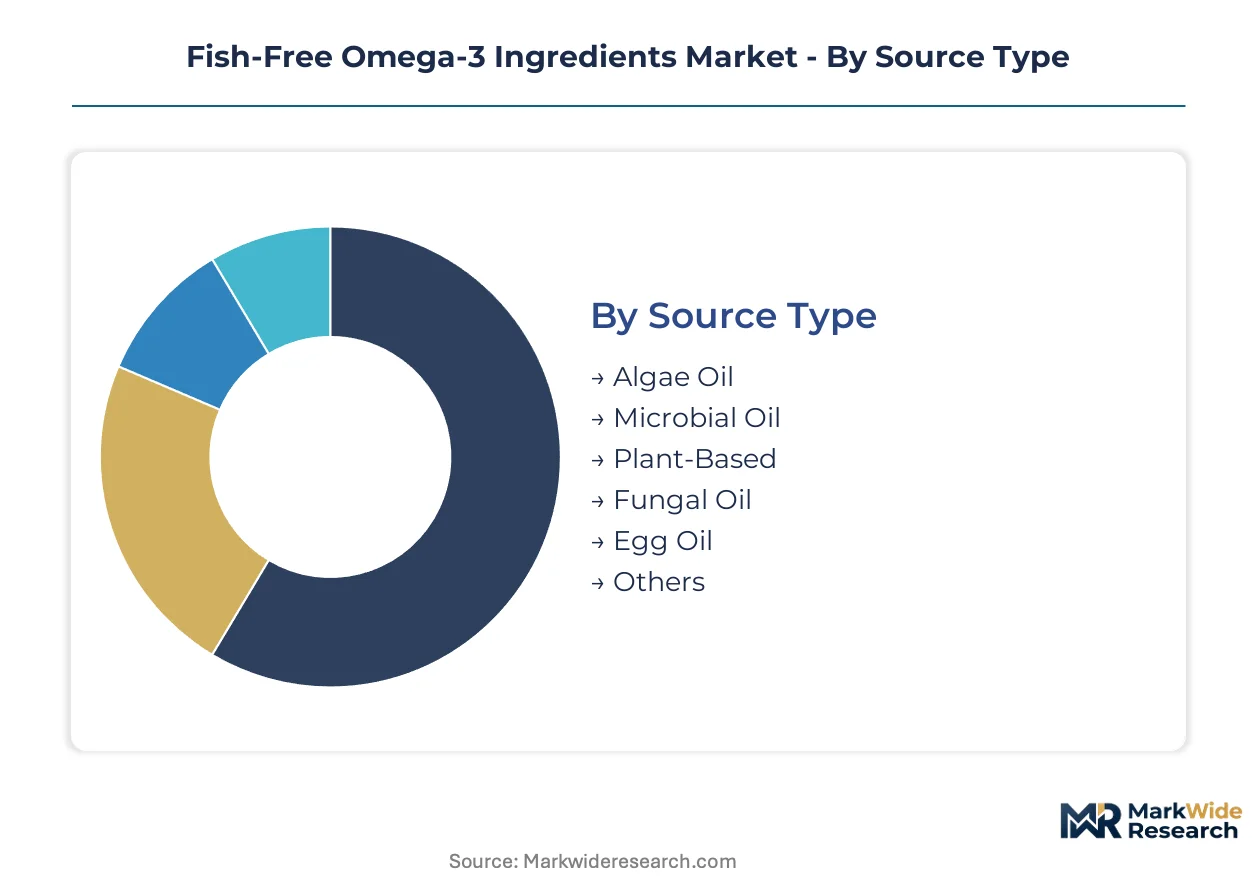
Segmentation in fish-free omega-3 ingredients reveals how technical specifications, regulatory pathways, and end-use requirements fragment sourcing strategies across supplier tiers. Manufacturers must align fermentation scale, extraction methods, and certification grades with distinct customer procurement criteria.
Source Type:
Standardization levels vary sharply across biomass platforms, from photobioreactor-cultivated algae to precision-fermented microbial strains.
- Algae Oil:Direct DHA biosynthesis through photobioreactor cultivation delivers 15-40% omega-3 concentration without trophic conversion losses. German pharmaceutical-grade procurement contracts concentrate demand for potency-verified EPA/DHA specifications in infant formula applications.
- Microbial Oil:Precision fermentation platforms achieve tunable fatty acid profiles with batch-to-batch consistency. US FDA GRAS notifications accelerate strain commercialization for nutraceutical brands seeking contaminant-free alternatives to marine sources.
- Plant-Based:Flaxseed and chia-derived ALA maintains cost positioning in economy-tier food fortification where EPA/DHA bioequivalence is not required.
- Fungal Oil:Mortierella alpina fermentation yields ARA-rich lipids for infant nutrition formulations requiring specific fatty acid ratios.
- Egg Oil:Specialized phospholipid profiles serve niche cosmetic and pharmaceutical encapsulation applications.
- Others:Emerging biomass sources including genetically modified yeasts and heterotrophic microalgae under early-stage regulatory evaluation.
Leading the category by volume: Algae Oil. Growing fastest: Microbial Oil.
Product Form:
Processing intensity and stability requirements create distinct margin tiers across delivery formats.
- Oil:Bulk crude and refined oils dominate ingredient supply to food processors and softgel manufacturers. REACH documentation burdens for European cosmetic applications concentrate demand toward integrated fermentation-to-lipid operations with in-house analytical capabilities.
- Capsule:Hard and soft gelatin capsules command premium positioning through dosing precision and shelf-life stability. Direct-to-practitioner distribution channels in the United States and Australia favor batch-tested capsule suppliers with clinical substantiation packages.
- Powder:Microencapsulated formats enable dry blending into functional foods and infant formula powders.
- Emulsion:Oil dispersion technology advances support ready-to-drink functional beverage integration where solubility challenges persist.
- Gel:Semi-solid matrices target topical cosmetic applications requiring specific rheological properties.
- Crystal:Highly purified free fatty acid crystals serve pharmaceutical synthesis and specialized research applications.
Highest volume concentration: Oil. Steepest expansion trajectory: Emulsion.
Application:
Regulatory complexity and clinical substantiation demands stratify end-use markets by entry barrier height.
- Dietary Supplements:Vegan-labeled capsules and softgels represent the primary revenue channel for algal and microbial EPA/DHA. EFSA Novel Food opinions create predictable approval timelines enabling EU-located extraction facility investment.
- Infant Nutrition:Fermentation-derived DHA qualification programs accelerate across North American and European formula manufacturers. Pharmacopeial monograph adoption stalls pending finalized algal DHA standards for prescription-grade positioning.
- Functional Foods:Microencapsulated powders and emulsions enable fortification of beverages, dairy alternatives, and bakery products.
- Animal Feed:Pet food producers seek sustainable omega-3 sources for premium companion animal nutrition positioning.
- Pharmaceuticals:Prescription cardiovascular therapy substitution presents high-margin offtake potential contingent on contaminant-free profile verification.
- Cosmetics:ECHA compliance demands comprehensive residual solvent and heavy metal testing that smaller extraction facilities cannot support.
Dominant revenue share: Dietary Supplements. Climbing the fastest: Infant Nutrition.
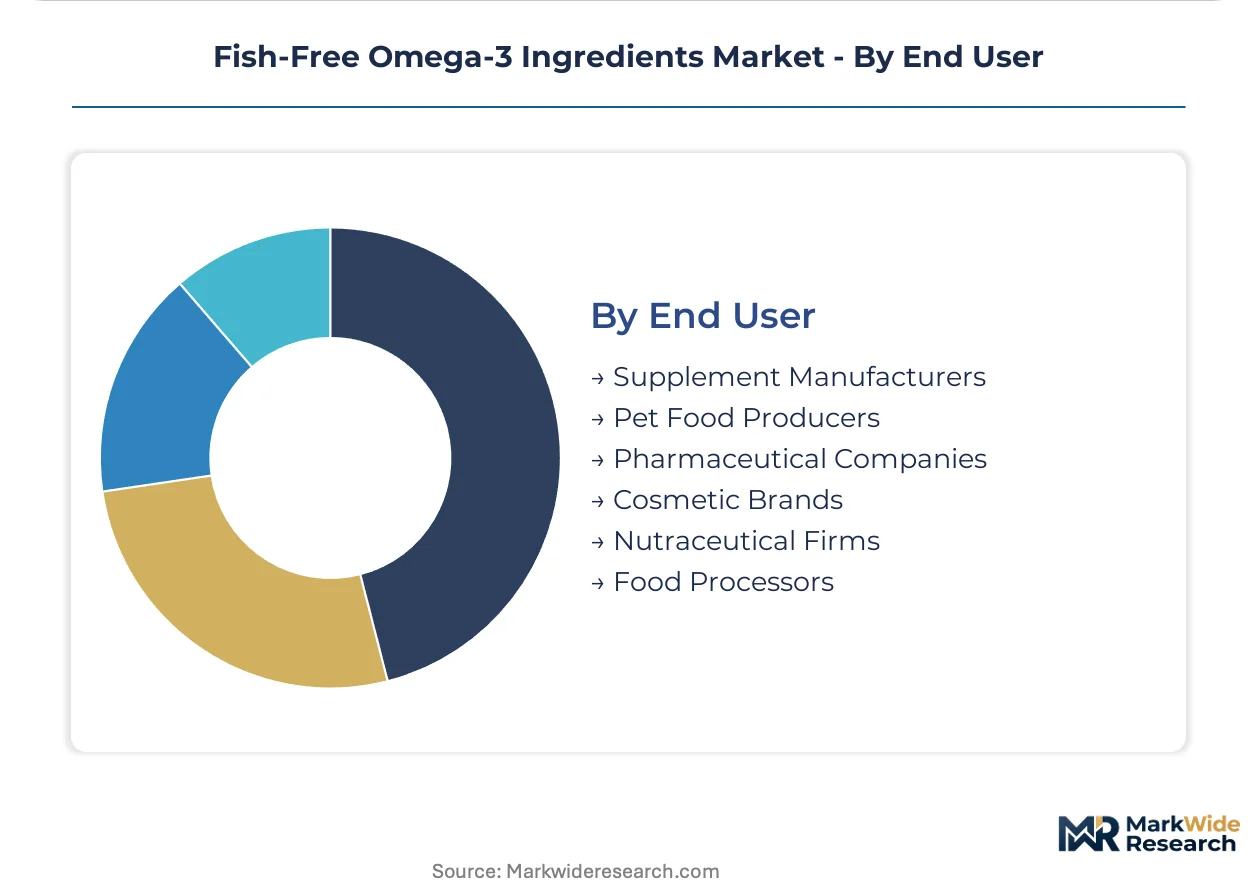
End User:
Procurement sophistication and volume scale separate enterprise-grade buyers from specialty niche purchasers.
- Supplement Manufacturers:Large-scale contract manufacturers drive standardization requirements for vegan certification and potency verification. OSHA-guided extraction automation incentives concentrate supplier selection toward closed-system fermentation operators.
- Pharmaceutical Companies:Prescription omega-3 therapy developers demand pharmacopeial-grade documentation and batch release testing. Talent scarcity in microbial strain optimization inflates supplier qualification timelines and contract negotiation complexity.
- Nutraceutical Firms:Mid-tier brands balance clinical substantiation investments with price competitiveness against flaxseed alternatives.
- Food Processors:Volume buyers prioritize cost stability and supply security for fortification applications.
- Pet Food Producers:Premium companion animal brands source algae-derived DHA for sustainability messaging differentiation.
- Cosmetic Brands:Swiss and German formulators consolidate supplier bases toward integrated operations with REACH-compliant documentation.
Largest procurement volume: Supplement Manufacturers. Gaining share fastest: Pharmaceutical Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kaiserlautern's precision fermentation corridor anchors European microbial oil production, while DSM's Dutch facilities and Corbion's Spanish operations concentrate supply chain control in the Rhine-Ruhr and Barcelona-Catalonia clusters.
Germany
Pharmaceutical-grade algal oil procurement contracts from Frankfurt and Munich nutraceutical formulators drive demand concentration. EFSA Novel Food opinions under EU Regulation 2015/2283 streamline strain approval timelines for fermentation operators. The Lower Saxony extraction corridor near Hamburg hosts BASF's microbial oil platforms serving infant formula manufacturers.
United States
FDA GRAS notifications for microbial-derived EPA and DHA accelerate strain commercialization for supplement brands in California and New Jersey. OSHA guidelines on solvent residues shape extraction facility automation investments in the Great Lakes region. Boston's biotech corridor hosts direct-to-practitioner distribution networks for clinical nutrition specialists.
Netherlands
DSM's life sciences division sustains high-purity fermentation output from Delft and Heerlen facilities for global infant formula clients. REACH compliance documentation demands concentrate supplier selection toward integrated operations with in-house analytical chemistry. The Rotterdam-Antwerp port cluster handles bulk algal oil imports for European cosmetic applications.
China
SAMR's national food safety standards for algal oil DHA specifications enable domestic infant formula fortification growth. NMPA regulatory pathways for novel microbial strains remain under development, slowing pharmaceutical-grade positioning. The Yangtze River Delta fermentation corridor near Shanghai concentrates heterotrophic microalgae cultivation capacity.
Australia
TGA's complementary medicine regulations govern algal oil capsule potency verification requirements for practitioner-distributed brands. Direct-to-practitioner channels in Sydney and Melbourne favor batch-tested fermentation operators with clinical substantiation packages. The Queensland marine biotechnology cluster evaluates tropical microalgae strains for DHA yield optimization.
Fish-Free Omega-3 Ingredients Market Competitive Landscape
Capital-heavy fermentation platform operators compete with asset-light lipid chemistry specialists for margin capture across extraction and formulation tiers. The vendor base stratifies between integrated life sciences conglomerates with captive strain libraries and independent algal cultivation facilities dependent on photobioreactor yield consistency. Three archetypes dominate: pharmaceutical-grade certification holders, infant formula contract exclusivity players, and commodity-positioned plant-based ALA suppliers. Consolidation pressure intensifies through M&A targeting analytical chemistry capabilities and strategic partnerships bridging fermentation scale with encapsulation expertise.
Among Dutch and German integrated operators, Koninklijke DSM N.V. and BASF SE exemplify the fermentation-to-lipid-chemistry archetype with captive supply chains, while Croda International Plc represents specialty lipid chemistry positioning for pharmaceutical encapsulation stability. These three anchors demonstrate how European regulatory compliance investments create defensive moats against precision fermentation cost compression from emerging microbial oil platforms.
| Leading Market Players |
|---|
| Croda International Plc |
| Archer Daniels Midland Company |
| Koninklijke DSM N.V. |
| Neptune Wellness Solutions Inc. |
| Epax Norway AS |
| BASF SE |
| Corbion |
| Cellana Inc. |
| Cargill Incorporated |
| Others |
Supply & Pricing Matrix
Precision fermentation yield improvements compress production costs for microbial-derived EPA and DHA while simultaneously concentrating supply capacity among capital-intensive platform operators in Germany, the Netherlands, and the United States. This technological transition rewards integrated fermentation-to-lipid-chemistry operations with pricing power over smaller photobioreactor-dependent suppliers.
Pricing Analysis
Pharmaceutical-grade certification anchors value-based pricing for infant formula and prescription therapy applications, separating premium microbial oil from commodity plant-based ALA alternatives. Price differentiation hinges on EPA/DHA potency verification and REACH-compliant documentation for European cosmetic buyers. Pricing pressure intensifies in economy-tier dietary supplements as flaxseed and chia sources undercut algal oil on cost. Large-scale supplement manufacturers exhibit highest price sensitivity, while pharmaceutical companies prioritize batch consistency over unit economics.
Supply Chain Analysis
Direct-to-manufacturer channels handle pharmaceutical and infant formula procurement, with distributor intermediaries serving mid-tier nutraceutical brands. Supply concentrates in Germany, the Netherlands, and Spain, where integrated fermentation platforms control strain libraries and extraction capacity. Raw material dependencies include glucose feedstocks, nitrogen sources, and specialized lipid chemistry reagents. Single-source vulnerability persists for high-purity analytical standards and pharmacopeial reference materials. Distribution runs through Rotterdam-Antwerp port logistics for bulk oil movements and regional cold-chain networks for finished capsules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation specialist talent scarcity constrains capacity expansion across microbial oil platforms, propping pricing for qualified suppliers. This bottleneck sustains margin capture for incumbents with captive strain optimization capabilities.
For Market Incumbents: Deepen backward integration into glucose feedstock supply and closed-system extraction automation to defend against precision fermentation cost compression from emerging microbial platforms. Prioritize pharmacopeial-grade certification investments to lock in infant formula contract exclusivity before algal DHA monograph finalization accelerates pharmaceutical substitution demand. For New Entrants and Emerging Players: FDA GRAS pathway streamlining in the United States opens a window for fermentation-derived EPA/DHA qualification with supplement brands seeking contaminant-free alternatives. Target functional beverage emulsion formats where oil dispersion technology gaps limit incumbent penetration. Pursue direct-to-practitioner distribution partnerships with clinical nutrition specialists in Australia and the United States to bypass saturated retail channels. For Investors and Strategic Acquirers: Re-rating potential sits with integrated fermentation-to-lipid-chemistry operators given EFSA Novel Food opinion predictability enabling EU facility investment. Long-term viability favors platforms with in-house analytical capabilities and REACH-compliant documentation infrastructure. Monitor pharmacopeial monograph adoption for algal DHA as the inflection signal for pharmaceutical-grade contract acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | DSM and BASF capacity additions in Delft and Lower Saxony tighten supply control over infant formula clients. |
| Pharmacopeial Certification Investment | Algal DHA monograph alignment unlocks prescription cardiovascular therapy substitution opportunities for compliant suppliers. |
| Direct-to-Practitioner Channel Buildout | Boston and Sydney clinical nutrition networks disintermediate traditional supplement retail for batch-tested fermentation operators. |
| REACH Compliance Integration | German and Swiss cosmetic formulators consolidate supplier bases toward in-house analytical chemistry capabilities. |
| Emulsion Technology Partnership | Functional beverage ready-to-drink formats bypass capsule limitations through advanced oil dispersion systems. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with fermentation platform executives, lipid chemistry specialists, infant formula procurement managers, and regulatory affairs directors at nutraceutical firms combined with FDA GRAS notifications, EFSA Novel Food opinions, and REACH registration databases. Bottom-up strain capacity modeling and top-down end-use demand triangulation validated market sizing.
Data-stream reconciliation across production volume disclosures, import-export flows, and end-use consumption patterns informed the analytical framework. Segmentation modeling incorporated source type, product form, application, and end user dimensions across the projection horizon. CAGRs derived from capacity expansion timelines, regulatory approval velocities, and substitution elasticity assumptions for pharmaceutical-grade positioning.
The model assumes a particular technology adoption path; alternative pathways for heterotrophic microalgae cultivation would alter the outlook. Forecasts reflect assumptions about EFSA Novel Food opinion timelines and pharmacopeial monograph progression that regulatory delays could revise. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Argentina Food Preservatives Market
Food Additives and Ingredients
Antimicrobial Packaging Ingredients for Food Packaging Market
Food Additives and Ingredients
Argentina Sodium Reduction Ingredient Market
Food Additives and Ingredients
Natural Food Preservatives Market
Food Additives and Ingredients
Argentina Food Acidulants Market
Food Additives and Ingredients
Food Grade Calcium Hydroxide Market
Food Additives and Ingredients
Oxidized Starch Market
Food Additives and Ingredients
Food and Beverage Sterilizing Agent Market
Food Additives and Ingredients
Food Bleaching Agents Market
Food Additives and Ingredients
Food Grade Sodium Selenite Market
Food Additives and Ingredients
Curcumin Food Color Market
Food Additives and Ingredients
Natural Ferulic Acid Market
Food Additives and Ingredients
Food Encapsulation Market
Food Additives and Ingredients
North America Food Starch Market
Food Additives and Ingredients
Oxygen Absorbers Market
Food Additives and Ingredients
Amaranth (E123) Market