
 Gluten Free Beverages Market | 2026-2036
Gluten Free Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Gluten Free Beverages Market Outlook
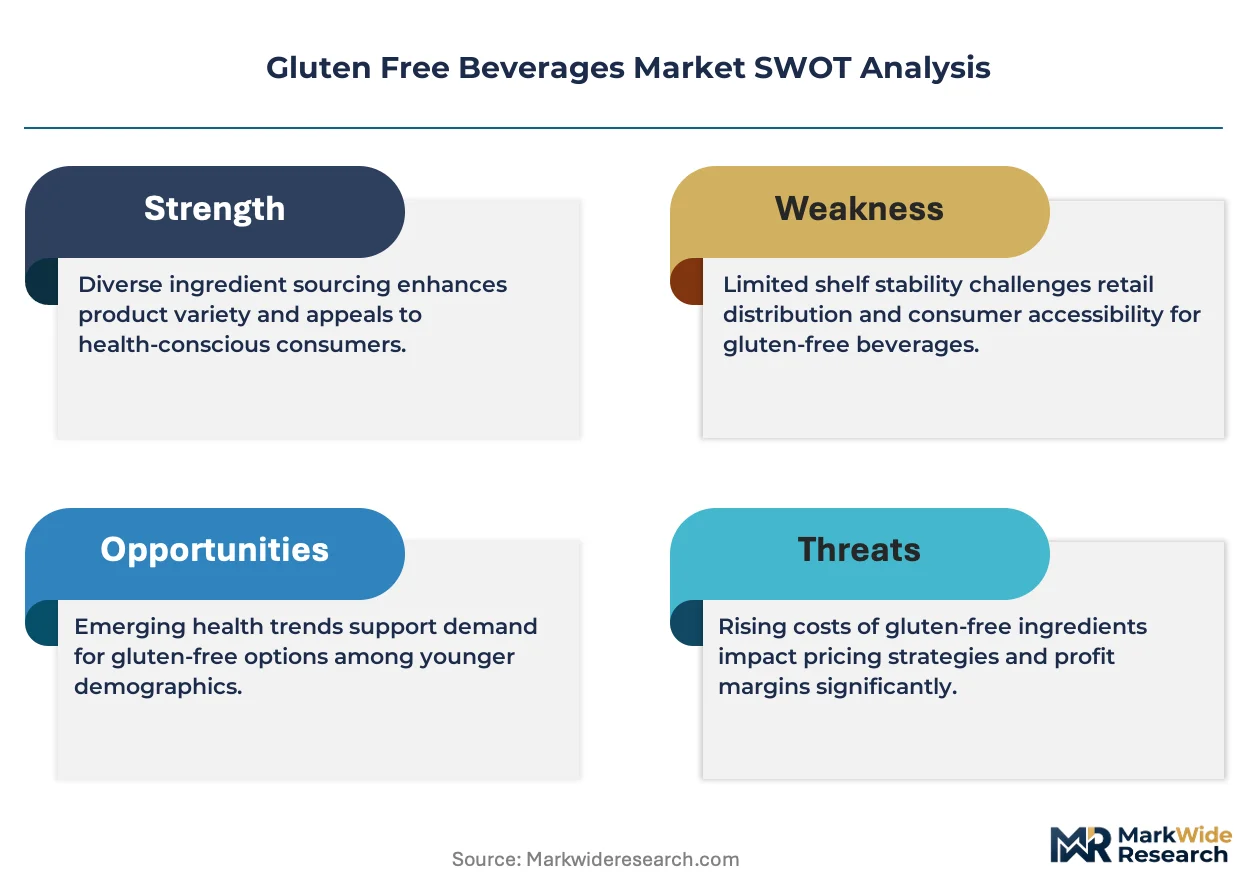
The Gluten-Free Certification Organization (GFCO) standard is unwinding market access for uncertified producers, forcing reformulation investments across the supply chain. PepsiCo leverages its global bottling infrastructure to secure shelf space in premium health channels. The Hain Celestial Group specializes in organic-certified gluten-free portfolios that anchor its position in natural retail. Anheuser-Busch InBev competes through dedicated brewing protocols that eliminate cross-contamination in malt-adjacent production.
Gluten free beverages exclude wheat, barley, rye, and their crossbred derivatives below 20 parts per million gluten content, verified through enzyme-linked immunosorbent assay (ELISA) testing protocols. These products serve celiac patients, gluten-sensitive consumers, and proactive health seekers who require documented ingredient traceability from raw material to finished liquid. Soft drinks and juices currently dominate volume, though tea segments are capturing margin pools through functional positioning around digestive wellness. The online distribution channel is expanding fastest as direct-to-consumer subscription models bypass traditional retail slotting constraints.
The FDA enforces gluten-free labeling under the Food Allergen Labeling and Consumer Protection Act, while the EU applies Commission Regulation (EC) No 41/2009 for products marketed across member states. The USDA Organic seal frequently co-appears with gluten-free claims, creating dual-compliance costs that smaller bottlers struggle to absorb. Stakeholders must monitor evolving threshold definitions as analytical methods improve and consumer litigation around trace contamination escalates.
Market Dynamics
The Gluten Free Beverages Market is undergoing structural compression as certification requirements harden into market-access gates, forcing capital reallocation toward compliance infrastructure and testing protocols.
Growth Catalysts
- Millennial wellness cohorts:Health-conscious consumers in the United States are demanding certified gluten-free soft drinks with documented ingredient traceability, creating pull-through for premium-positioned products.
- FDA labeling enforcement:The Food Allergen Labeling and Consumer Protection Act mandates strict gluten thresholds, legitimizing products that meet verification standards and marginalizing uncertified competitors.
- ELISA testing maturation:Enzyme-linked immunosorbent assay protocols now detect gluten at 20 parts per million, enabling quality guarantees that reduce consumer litigation risk for compliant producers.
Market Restraints
- Dual-certification cost burden:The USDA Organic seal frequently co-appears with gluten-free claims, forcing smaller bottlers to absorb overlapping compliance expenditures that strain working capital.
- Raw material traceability complexity:Wheat, barley, and rye derivatives appear in flavorings and processing aids, requiring farm-to-bottle documentation systems that inflate procurement overhead.
- Cross-contamination infrastructure:Dedicated brewing and bottling lines for malt-adjacent production demand capital outlays that exclude contract manufacturers without segregated facilities.
Strategic Opportunities
- Direct-to-consumer subscription channels:Online distribution models bypass traditional retail slotting constraints, capturing margin pools that brick-and-shelf arrangements erode.
- Functional tea positioning:Digestive wellness claims in tea segments command price premiums over commodity soft drinks, attracting health seekers beyond celiac-diagnosed populations.
- EU regulatory alignment:Commission Regulation (EC) No 41/2009 creates harmonized standards across member states, reducing fragmentation costs for exporters targeting European wellness channels.
Industry Challenges
- Certification timeline compression:The Gluten-Free Certification Organization standard accelerates audit cycles, demanding continuous documentation systems that strain quality-assurance staffing.
- Analytical method obsolescence risk:Improving detection thresholds threaten to invalidate existing 20 ppm certifications, requiring proactive reinvestment in testing technology before regulatory mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gluten Free Beverages Market |
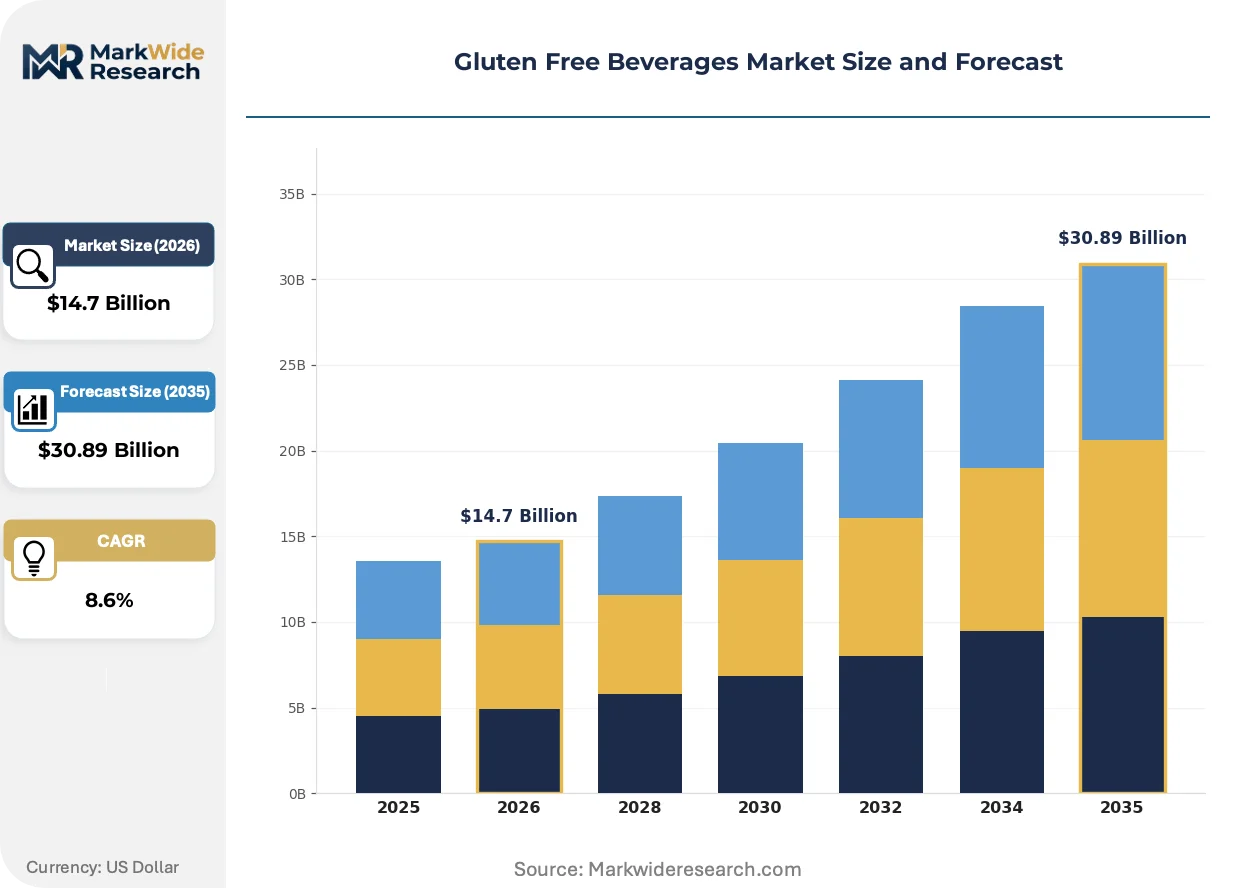
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Juices, Soft Drinks, Tea, Coffee Distribution Channel: Online, Supermarkets, Health Stores, Restaurants Consumer Type: Health Conscious, Celiac Patients, Dietary Restriction, Fitness Enthusiasts Flavor Profile: Citrus, Berry, Herbal, Exotic |
| Companies Covered | PepsiCo, The Coca-Cola Company, General Mills, The Kraft Heinz Company, Conagra Brands, Nestle, The Hain Celestial Group, Dr. Schär, Anheuser-Busch InBev, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gluten Free Beverages Market Strategic Shifts
Certification technology and channel architecture are actively restructuring competitive advantage in gluten-free beverages, with verification systems and distribution models displacing traditional brand equity as primary value determinants.
Blockchain-enabled ingredient traceability is decomposing opacity in supply chain documentation. Premium health channels in the United States are adopting distributed-ledger verification for raw material provenance. This transparency infrastructure is compressing information asymmetry between producers and celiac patient advocacy networks.
REACH chemical safety protocols in Europe are tightening scrutiny of processing aids and flavor carriers with gluten contamination potential. Industrial consequence includes mandatory supplier disclosure requirements for malt-derived ingredients. Beverage exporters to EU member states are responding by segregating production lines and establishing dedicated European contract manufacturing relationships.
Subscription-based replenishment models are displacing intermittent retail purchase patterns among diagnosed celiac consumers. Natural retail channels are integrating auto-ship functionality that locks in recurring revenue and reduces price sensitivity. This behavioral shift is most visible in urban United States markets where direct-to-consumer platforms capture pantry-stocking occasions previously held by conventional grocery.
Gluten Free Beverages Market Segmentation
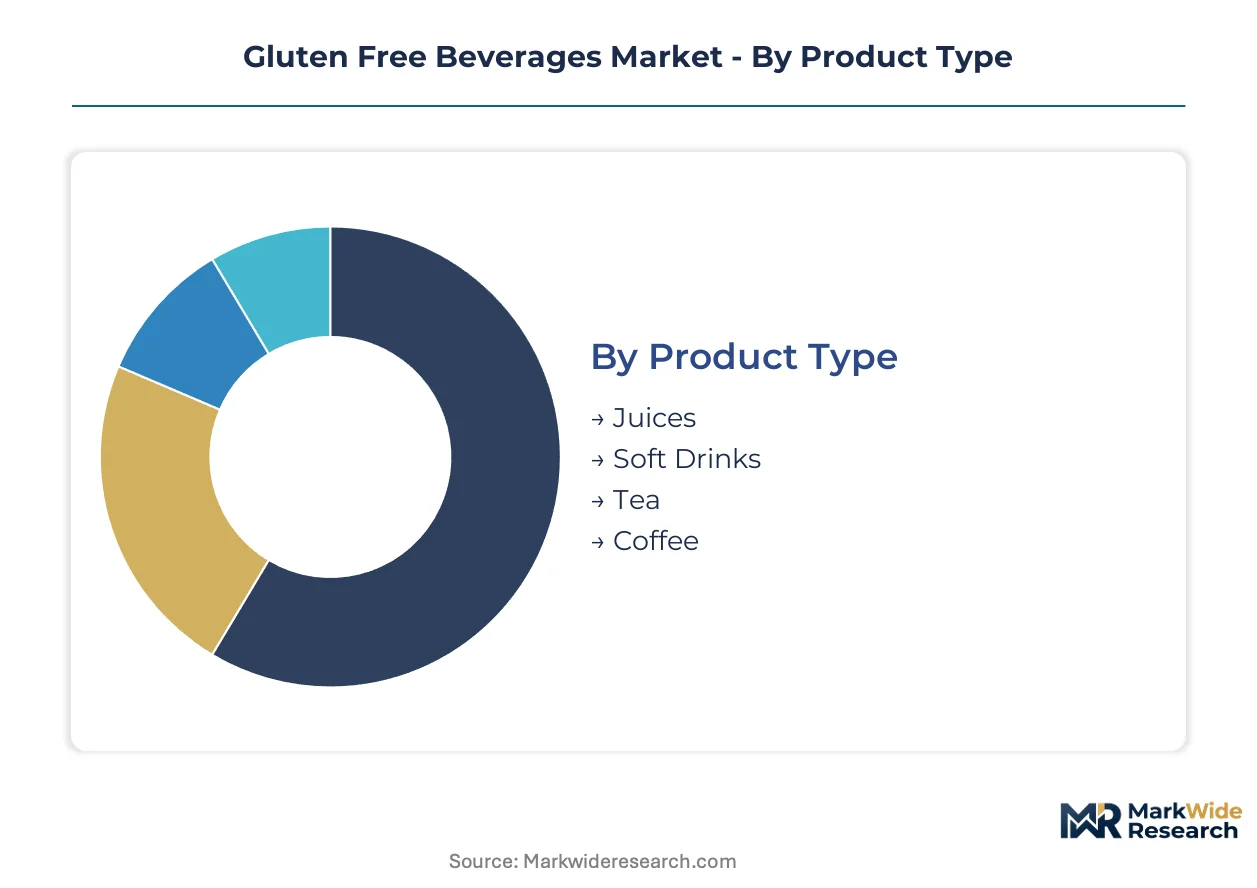
Gluten-free beverage segmentation reveals divergent channel economics and compliance burdens across product formats. Certification requirements and traceability infrastructure create tiered market access that favors capitalized players in premium channels.
Product Type:
Channel-mix dynamics concentrate certified juices and soft drinks in mass retail, while tea and coffee command premium placement in health-focused outlets.
- Juices:Cold-pressed and NFC formulations require ELISA-verified fruit sourcing to eliminate cross-contamination from barley-based clarifying agents. Demand clusters in United States urban wellness corridors where millennial consumers prioritize documented ingredient provenance.
- Soft Drinks:Carbonated formulations exclude malt-derived flavorings and rely on corn or cane sugar bases with third-party gluten-free certification. Volume concentrates in conventional supermarket channels where FDA labeling compliance serves as a shelf-stocking prerequisite.
- Tea:Functional positioning around digestive wellness supports price premiums in natural retail and direct-to-consumer subscription models.
- Coffee:Single-origin and specialty roasters emphasize supply chain transparency to capture celiac-conscious consumers in premium café and online channels.
Soft drinks dominate installed base. Tea is where expansion concentrates.
Distribution Channel:
Cost tier stratification separates high-compliance online and health store channels from volume-driven supermarket and foodservice routes.
- Online:Direct-to-consumer platforms bypass slotting fees and capture recurring revenue through subscription replenishment models. United States urban markets show strongest adoption where pantry-stocking convenience outweighs shipping premiums.
- Supermarkets:Mass retail placement demands GFCO certification and dedicated supply chain segregation that excludes smaller contract bottlers. Shelf space allocation favors PepsiCo and Hain Celestial with established gluten-free portfolios.
- Health Stores:Natural retail channels prioritize dual-certified organic-gluten-free products with blockchain-enabled traceability documentation.
- Restaurants:Foodservice distribution requires batch-level testing protocols and staff training on cross-contamination prevention.
Supermarkets anchor volume throughput. Online channels are climbing the fastest.
Consumer Type:
Application-driven segmentation separates medical necessity from discretionary wellness purchasing with divergent price elasticity profiles.
- Health Conscious:Proactive wellness seekers without diagnosed conditions drive premium positioning and functional ingredient innovation in tea and juice categories.
- Celiac Patients:Medically diagnosed consumers demand documented 20 ppm compliance and supply chain transparency, concentrating in subscription and health store channels with lowest contamination risk tolerance.
- Dietary Restriction:Consumers managing multiple eliminations (gluten-free plus dairy-free or low-FODMAP) prioritize clean-label simplicity over functional claims.
- Fitness Enthusiasts:Athletic consumers seeking post-workout recovery beverages favor protein-fortified gluten-free formulations in gym-adjacent retail and online channels.
Celiac patients anchor certification standards. Health conscious consumers are gaining share fastest.
Flavor Profile:
Maturity gradients separate established citrus and berry formulations from emerging herbal and exotic variants with higher innovation risk.
- Citrus:Lemon, lime, and orange profiles dominate commodity soft drinks and juices with established supply chains and lowest raw material traceability complexity.
- Berry:Strawberry, blueberry, and raspberry formulations capture premium positioning in natural retail with organic co-certification driving margin expansion.
- Herbal:Chamomile, ginger, and peppermint infusions align with digestive wellness positioning in functional tea segments.
- Exotic:Dragon fruit, yuzu, and acerola variants attract adventurous wellness consumers in direct-to-consumer channels with limited retail distribution.
Citrus dominates installed base. Exotic profiles are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles anchors trans-Pacific ingredient flows for certified gluten-free beverage supply chains, while Rotterdam's container terminals distribute ELISA-verified raw materials across European manufacturing networks.
United States
Millennial wellness cohorts in New York and Los Angeles drive demand for GFCO-certified soft drinks with blockchain traceability. FDA enforcement under the Food Allergen Labeling and Consumer Protection Act tightens 20 ppm compliance verification. Chicago's beverage manufacturing corridor hosts dedicated gluten-free bottling lines serving health store distribution.
Germany
REACH chemical safety protocols scrutinize malt-derived processing aids in flavor formulations. Commission Regulation (EC) No 41/2009 harmonizes gluten-free standards across EU member states. Bavaria's brewing heritage clusters now segregate production protocols for certified gluten-free malt alternatives.
United Kingdom
London's premium café channels demand single-origin coffee with documented supply chain transparency. The Food Standards Agency enforces labeling alignment with EU-derived gluten thresholds post-Brexit. Manchester's contract manufacturing hub invests in dedicated bottling infrastructure for celiac-safe beverage production.
Canada
Health Canada and PMRA regulate gluten-free claims alongside organic certification requirements. Toronto's urban wellness corridors concentrate demand for functional tea positioning around digestive health. Vancouver's natural retail channels integrate subscription replenishment models for diagnosed celiac consumers.
Australia
TGA oversight of gluten-free labeling intersects with stringent food allergen management protocols. Sydney's health-conscious demographics drive premium positioning for cold-pressed juices with ELISA-verified fruit sourcing. Melbourne's specialty coffee roasters emphasize farm-to-bottle traceability documentation.
Gluten Free Beverages Market Competitive Environment
Listed leaders compete with private specialists across certification infrastructure and channel access, producing a tiered structure where scale advantages in testing protocols separate capitalized players from contract-dependent entrants. Strategic archetypes include multinational beverage conglomerates with global bottling networks, organic-certified specialty portfolios anchored in natural retail, and dedicated gluten-free specialists with segregated production assets. Dominant competitive moves center on M&A absorption of certified brands and vertical control over ELISA testing capacity.
Within the multinational tier, PepsiCo and The Coca-Cola Company occupy positions defined by mass retail shelf access and slotting fee leverage. The Hain Celestial Group exemplifies the organic-gluten-free dual-certification specialist archetype. Anheuser-Busch InBev represents brewing-sector adaptation through dedicated protocol segregation.
| Leading Market Players |
|---|
| PepsiCo |
| The Coca-Cola Company |
| General Mills |
| The Kraft Heinz Company |
| Conagra Brands |
| Nestle |
| The Hain Celestial Group |
| Dr. Schär |
| Anheuser-Busch InBev |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts for ELISA-verified raw materials lock in both supply access and price visibility for certified gluten-free beverage producers, insulating compliant manufacturers from spot-market volatility in barley-adjacent ingredient markets. These contractual structures concentrate procurement power among capitalized players with dedicated testing infrastructure, while smaller bottlers absorb margin compression from fragmented spot purchasing.
Pricing Analysis
Volume-discount tiering structures stratify across certification grade, with GFCO-certified organic portfolios commanding 40-60% premiums over uncertified commodity alternatives. Price differentiation hinges on dual-certification status and blockchain-enabled traceability documentation, with health-conscious millennials in United States urban corridors showing lowest price sensitivity. Cost compression in standard-tier carbonated soft drinks is intensifying as supermarket slotting fees escalate and corn-sugar input costs fluctuate.
Supply Chain Analysis
Strategic stockpile preferences dominate raw material procurement, with certified gluten-free grain alternatives and ELISA-verified fruit concentrates held in buffer inventory against contamination risk. Supply concentrates in United States corn-belt processing facilities, Canadian organic grain networks, and European malt-alternative brewing hubs. Single-source vulnerability in specialized testing reagents and dedicated bottling line infrastructure creates chokepoint exposure. Distribution runs through refrigerated logistics networks serving mass retail and direct-to-consumer subscription fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates durable competitive advantage. Certification requirements under FDA and GFCO protocols erect structural barriers that marginalize uncertified competitors and protect incumbent returns.
For Market Incumbents: Consolidate testing infrastructure through captive ELISA laboratory acquisition or exclusive third-party partnerships, eliminating queue-time vulnerability for audit cycles. Deepen backward integration into certified organic grain supply through long-term offtake with United States and Canadian producers, securing raw material access against emerging specialist entrants. For New Entrants and Emerging Players: Lead with functional tea positioning in direct-to-consumer subscription channels, where digestive wellness claims capture margin pools beyond celiac-diagnosed populations with minimal slotting-fee burden. Target health-conscious millennials in secondary United States urban markets where incumbent shelf-space concentration remains incomplete. For Investors and Strategic Acquirers: Capital is best deployed toward dual-certified organic-gluten-free specialists with established GFCO audit relationships and segregated production assets, as these capabilities compound over extended holding periods. Monitor FDA threshold-definition proceedings as the inflection indicator that would trigger reinvestment in next-generation testing technology.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Infrastructure Investment | GFCO audit capacity expansion secures market access against tightening compliance timelines. |
| Direct-to-Consumer Channel Launch | Subscription models bypass supermarket slotting fees and capture recurring revenue from celiac patients. |
| Blockchain Traceability Integration | Distributed-ledger verification compresses information asymmetry with health-conscious millennial buyers. |
| Dual-Certification Portfolio Expansion | USDA Organic co-certification commands price premiums in natural retail channels. |
| Segregated Production Line Buildout | Dedicated gluten-free bottling infrastructure eliminates cross-contamination liability for malt-adjacent categories. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with beverage brand managers, category buyers at natural retail chains, ELISA testing laboratory directors, and certified organic grain procurement specialists. Secondary validation drew from FDA gluten-free labeling guidance documents, GFCO certification audit protocols, USDA organic trade data, and Nielsen retail audit filings. Bottom-up volume modeling triangulated against top-down market sizing from trade association disclosures.
Across the analysis window, projections incorporated product-type segmentation by certification tier, distribution-channel cost structures, and consumer-type price elasticity profiles. CAGRs were derived from regression analysis of historical adoption curves among diagnosed celiac populations and health-conscious wellness seekers. Forecast inputs included ELISA testing capacity expansion rates, supermarket slotting-fee trajectories, and subscription-channel penetration assumptions.
The analysis sits within stated boundaries; outcomes outside sustained FDA enforcement intensity or GFCO audit standard stability would require recalibration. Forecasts reflect assumptions around certification threshold permanence and raw material traceability technology cost curves. Revision becomes warranted when detection method obsolescence risk crosses regulatory mandate thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
South America Dairy Based Beverages Market
Beverages
Sparkling Soda Market
Beverages
Vegetable Juice Market
Beverages
Saudi Arabia Retail Bubble Tea Kits Market
Beverages
Apple Cider Vinegar Market
Beverages
Citrus Water Market
Beverages
Chocolate Malt Drink Market
Beverages
Spring Water Market
Beverages
India Bottled Water Market
Beverages
Europe Yerba Mate Market
Beverages
Collagen-Infused Water Market
Beverages
Japan Energy Drink Market
Beverages
Packaged Milkshake Market
Beverages
Freezer & Beverage and Wine Cooler Market
Beverages
Oat Based Beverages Market
Beverages
Hot Cocoa Mix Market