
 Stevia Market | 2026-2036
Stevia Market Size, Share, and Industry Trends Forecast 2026-2036
Stevia Market Intelligence
The EU Green Deal's farm-to-fork sustainability targets is rebalancing sweetener procurement across European food and beverage supply chains. Ingredion Incorporated leverages its global ingredient distribution network to secure downstream placement in reformulated product lines. PureCircle sustains proprietary leaf varieties and extraction patents that anchor its position in high-purity rebaudioside supply. Cargill competes through integrated agricultural partnerships that control stevia leaf sourcing from cultivation through refining.
Stevia comprises steviol glycosides extracted from Stevia rebaudiana Bertoni leaves, with rebaudioside A and stevioside as the principal sweetening compounds measured by purity grades ranging from 80% to 99%. These glycosides deliver zero-calorie sweetness at 200–350 times the intensity of sucrose, serving industrial formulators seeking sugar reduction without artificial additive labels. Rebaudioside A commands premium positioning in beverage applications where clean taste profiles justify higher ingredient costs, while stevia extract powder occupies volume-driven positions in bakery and confectionery manufacturing. Liquid stevia formats are gaining traction in pharmaceutical and personal care formulations where precise dosing and solubility prove critical.
FDA GRAS notifications, EFSA novel food opinions, and China's GB standards for food additives collectively govern steviol glycoside purity thresholds, labeling requirements, and maximum usage levels across major producing and consuming jurisdictions. Regulatory divergence in approved glycoside variants and daily intake limits forces manufacturers to maintain region-specific formulation portfolios. Stakeholders must monitor evolving maximum residue limits for processing aids and emerging requirements for stevia supply chain sustainability certifications.
Market Dynamics
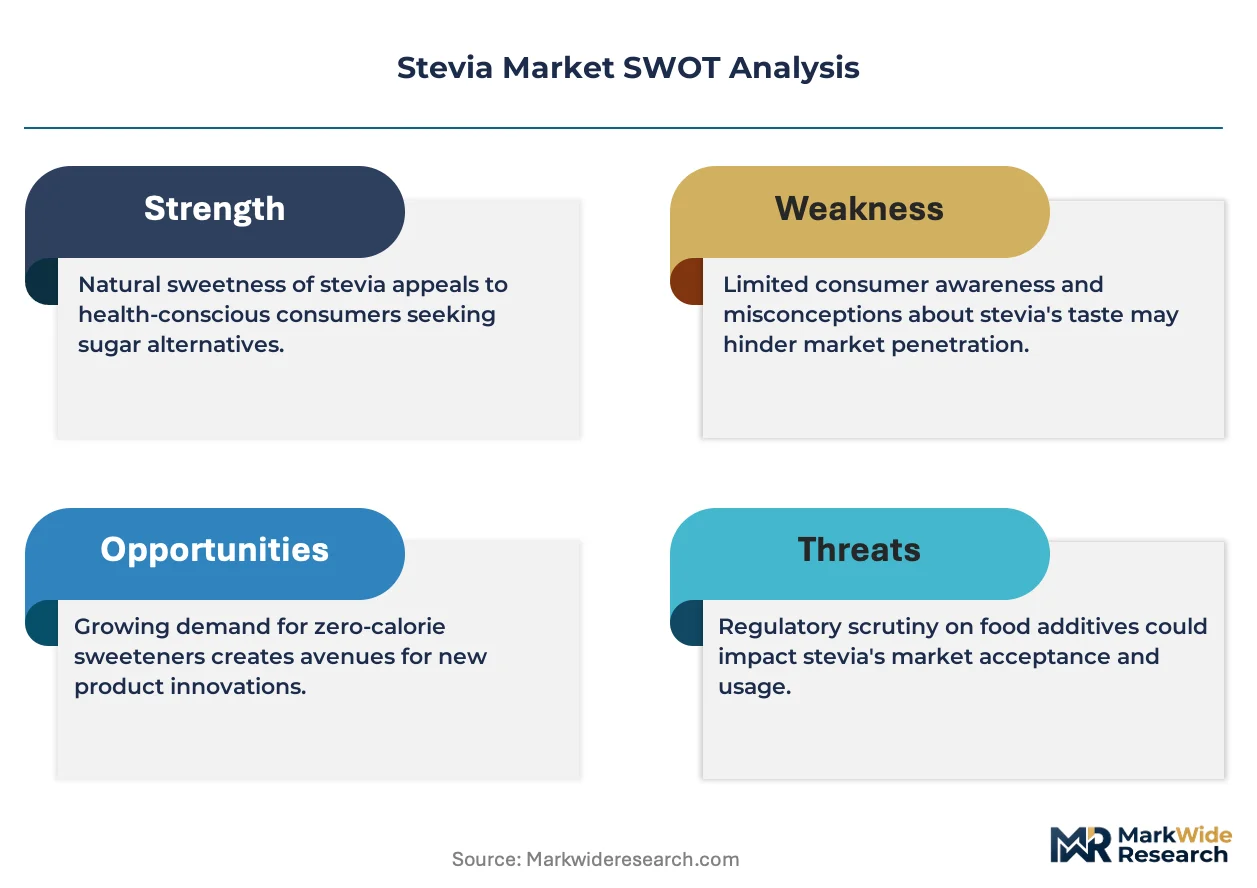
Clean-label sugar reduction mandates from major beverage and food manufacturers are compressing formulation cycles and forcing sweetener suppliers to prove taste parity at lower cost-in-use thresholds.
Growth Catalysts
- FDA GRAS pathway expansion:Streamlined notifications for novel steviol glycosides accelerate ingredient approvals and reduce time-to-market for reformulated products.
- Beverage industry sugar reduction targets:Carbonated drink and flavored water manufacturers anchor procurement volumes for high-purity rebaudioside variants.
- EU Green Deal farm-to-fork targets:Sustainability-linked procurement criteria reallocate sweetener sourcing toward certified supply chains with verified carbon footprints.
Market Restraints
- Leaf supply concentration:Cultivation clusters in Paraguay and China create geographic risk exposure for processors dependent on specific harvest conditions.
- Rebaudioside M production cost:Limited natural abundance and complex bioconversion economics constrain volume scalability versus rebaudioside A.
- Regulatory fragmentation:Divergent EFSA and FDA approved glycoside lists force manufacturers to maintain parallel formulation inventories.
Strategic Opportunities
- Pharmaceutical excipient applications:Liquid stevia formats penetrate tablet coatings and pediatric formulations where precise dosing outweighs cost premiums.
- India FSSAI clean-label adoption:Emerging middle-class demand for natural sweeteners in packaged foods outpaces domestic supply infrastructure.
- Enzymatic glycoside conversion:Biocatalytic processing converges with precision fermentation to unlock rare steviol glycosides at commercial scale.
Industry Challenges
- Extraction technology talent scarcity:Specialized biochemists with steviol glycoside purification expertise command premium compensation and limited mobility.
- Organic certification timelines:Multi-year field conversion periods delay premium positioning for growers transitioning from conventional cultivation.
- Flavor masking integration:Bitter aftertaste suppression requires complex co-formulation with taste modulators, extending R&D cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stevia Market |
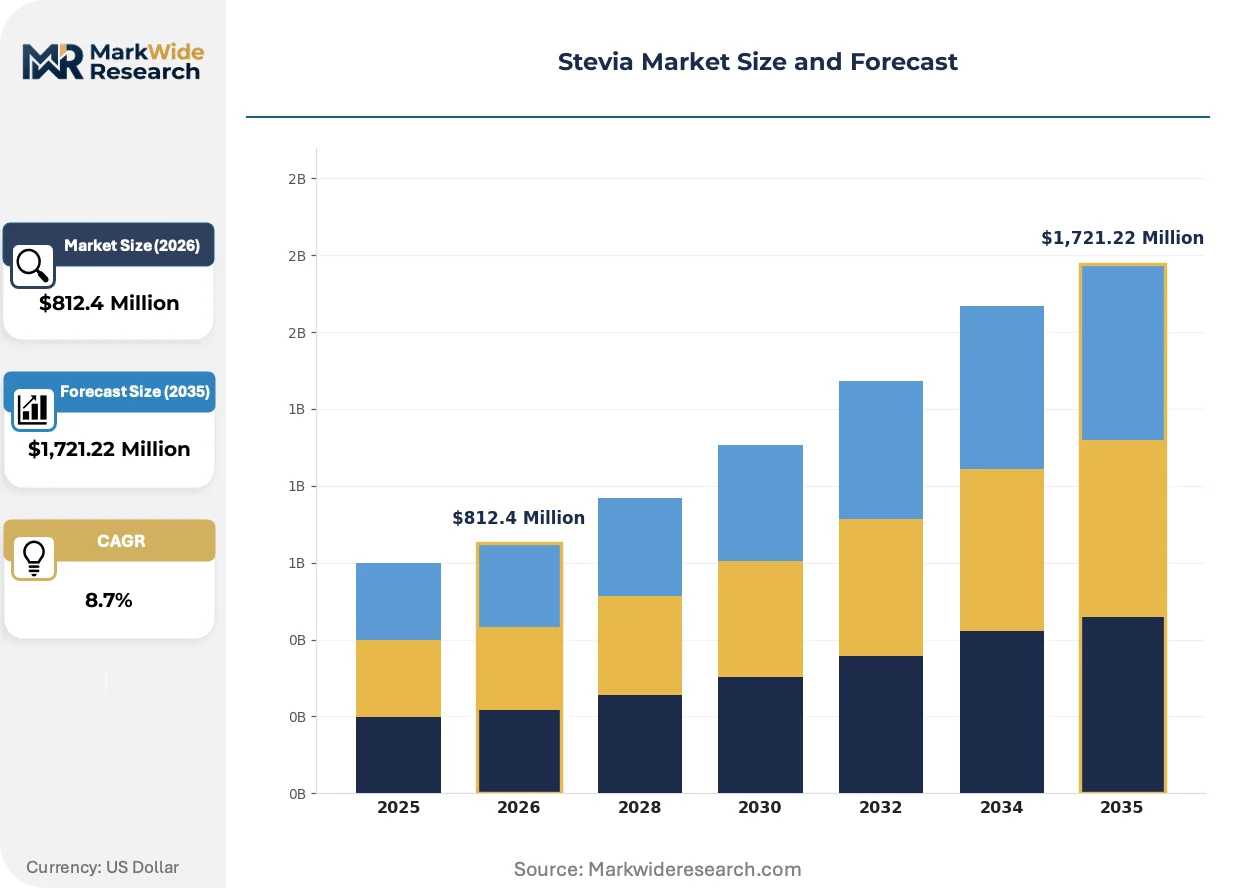
| Market Size in 2026 | $812.4 Million |
| Market Size in 2035 | $1,721.22 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stevioside, Rebaudioside A, Stevia Extract Powder, Liquid Stevia, Purified Stevia Application: Beverages, Confectionery, Dairy Products, Pharmaceuticals, Personal Care End User: Food & Beverage Manufacturers, Nutraceutical Companies, Cosmetic Producers, Pharmaceutical Firms, Dietary Supplement Makers Packaging Type: Bulk Packaging, Sachets, Bottles, Pouches, Jars |
| Companies Covered | Ingredion Incorporated, Archer Daniels Midland Company, PureCircle, Sweet Green Fields, Sunwin Stevia International, Cargill, GLG Life Tech Corporation, Foodchem International Corporation, Tate & Lyle PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stevia Market Strategic Shifts & Innovations
Biotechnological production methods and enzymatic refinement are displacing conventional leaf extraction as the dominant supply modality, while regulatory harmonization efforts and shifting procurement criteria reshape competitive positioning.
Enzymatically produced steviol glycosides is overtaking leaf-extracted equivalents in purity-grade supply, with beverage formulators adopting the biocatalytic route for rebaudioside M and D variants. The technology enables taste-profile precision that natural extraction cannot achieve at equivalent cost structures. This shift compresses margins for conventional agronomic processors while rewarding biotech-integrated suppliers with premium placement.
EFSA novel food opinion harmonization is narrowing the gap between EU and US approved glycoside lists, reducing formulation complexity for multinational manufacturers. The convergence eliminates redundant SKU maintenance and simplifies supply chain rationalization. Beverage applications in Germany and France show earliest alignment benefits as reformulation cycles accelerate.
Direct sourcing contracts between end-users and cultivation cooperatives are fragmenting traditional distributor intermediation in high-volume procurement. Manufacturers in the United States now negotiate leaf supply agreements with Paraguayan grower associations, bypassing layered trading structures. This disintermediation concentrates price risk with buyers while securing traceability credentials demanded by retail chains.
Stevia Market Segmentation
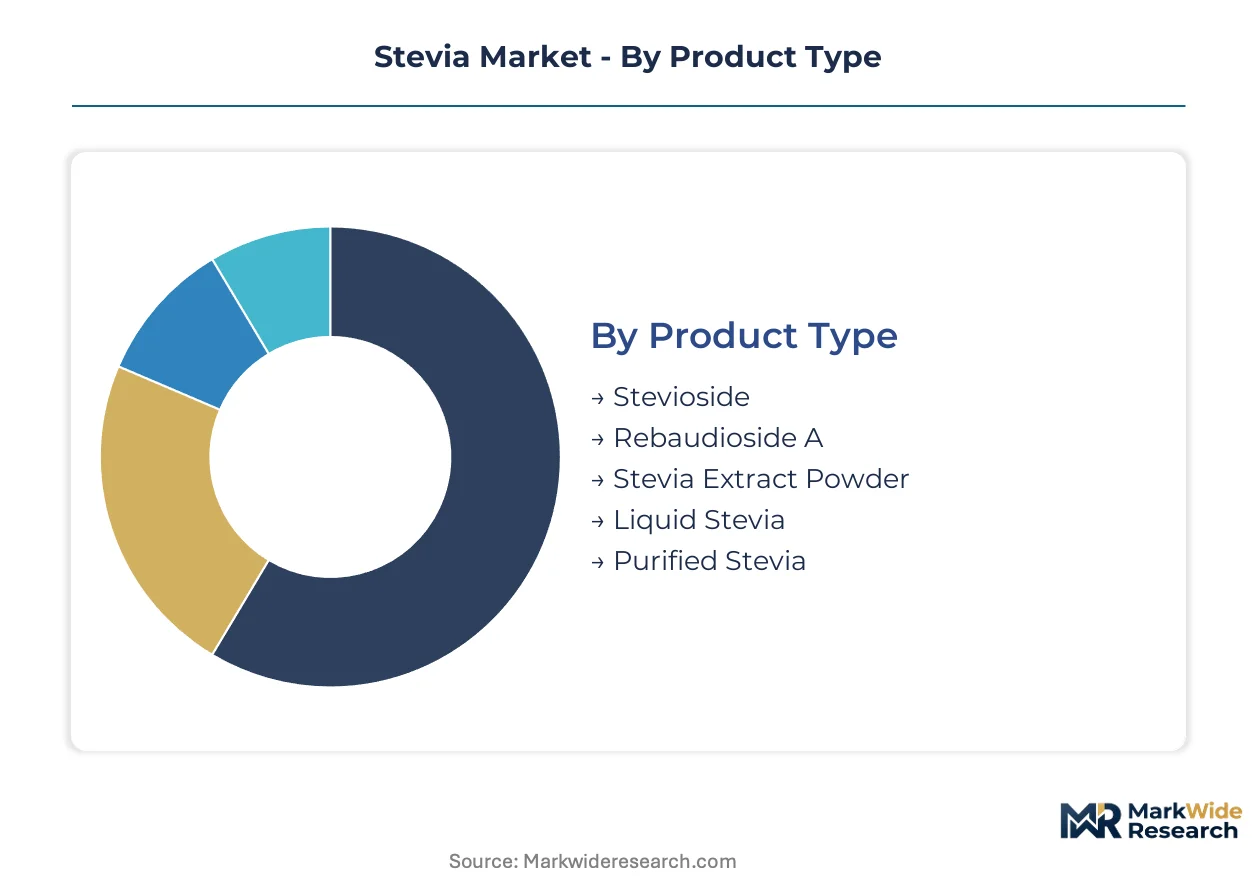
Stevia's functional diversity across sweetness intensity, solubility, and formulation compatibility creates distinct procurement patterns by product chemistry and end-use requirements. Manufacturers segment procurement portfolios across glycoside purity grades and physical formats to match specific application constraints.
Product Type:
Volume applications favor commodity glycoside grades, while premium beverage formulations command higher-purity rebaudioside variants with superior taste profiles.
- Rebaudioside A:This high-purity glycoside delivers clean sweetness with minimal bitter aftertaste at 250–350 times sucrose intensity. Carbonated drink manufacturers in the United States specify Reb-A for zero-calorie reformulations where taste parity with sugar justifies ingredient premiums.
- Stevioside:The most abundant natural glycoside extracted from Stevia rebaudiana leaves, stevioside offers cost-efficient sweetness at 200–300 times sucrose intensity. Bakery and confectionery manufacturers in China leverage stevioside for bulk sugar replacement in volume-driven applications where slight bitterness is masked by other flavors.
- Stevia Extract Powder:Standardized blends of multiple glycosides provide intermediate purity for general food manufacturing.
- Liquid Stevia:Pre-dissolved formats enable precise dosing in pharmaceutical and personal care formulations requiring solubility control.
- Purified Stevia:Ultra-high purity grades serve specialized nutraceutical applications with stringent residual solvent limits.
Mature deployment sits with Stevioside. Newer deployment is concentrated in Rebaudioside A.
Application:
Beverage sector procurement volumes dwarf other segments, while pharmaceutical and personal care applications generate premium pricing through specialized formulation requirements.
- Beverages:Carbonated drinks, flavored waters, and ready-to-drink teas constitute the dominant demand channel for high-purity rebaudioside variants. Major beverage manufacturers in the United States have established sugar reduction targets that lock in multi-year stevia procurement contracts.
- Pharmaceuticals:Tablet coatings, syrups, and pediatric formulations utilize liquid stevia for precise dosing and patient compliance advantages. The FDA's GRAS notification pathway enables rapid ingredient qualification for drug excipient applications.
- Confectionery:Hard candies and chewing gums employ stevia for sustained sweetness release without caloric load.
- Dairy Products:Yogurts and flavored milk applications require glycoside stability across pasteurization temperatures.
- Personal Care:Toothpastes and mouthwashes incorporate stevia for sweetness without cariogenic risk.
Established integration dominates Beverages. Steepest expansion trajectory appears in Pharmaceuticals.
End User:
Food and beverage manufacturers drive procurement scale, while pharmaceutical and nutraceutical buyers prioritize certification documentation and supply traceability.
- Food & Beverage Manufacturers:Multinational CPG companies anchor stevia demand through clean-label reformulation mandates. These buyers negotiate direct sourcing agreements with Paraguayan cultivation cooperatives to secure volume commitments and sustainability credentials.
- Nutraceutical Companies:Dietary supplement and functional food producers specify organic-certified stevia for premium positioning. The EU Green Deal's farm-to-fork targets influence procurement criteria for European nutraceutical buyers.
- Pharmaceutical Firms:Drug manufacturers require excipient-grade stevia with documented purity and stability data.
- Cosmetic Producers:Personal care formulators seek stevia for natural positioning in oral care products.
- Dietary Supplement Makers:Capsule and powder supplement manufacturers utilize stevia for palatability enhancement.
Volume concentration rests with Food & Beverage Manufacturers. Emerging demand clusters with Nutraceutical Companies.
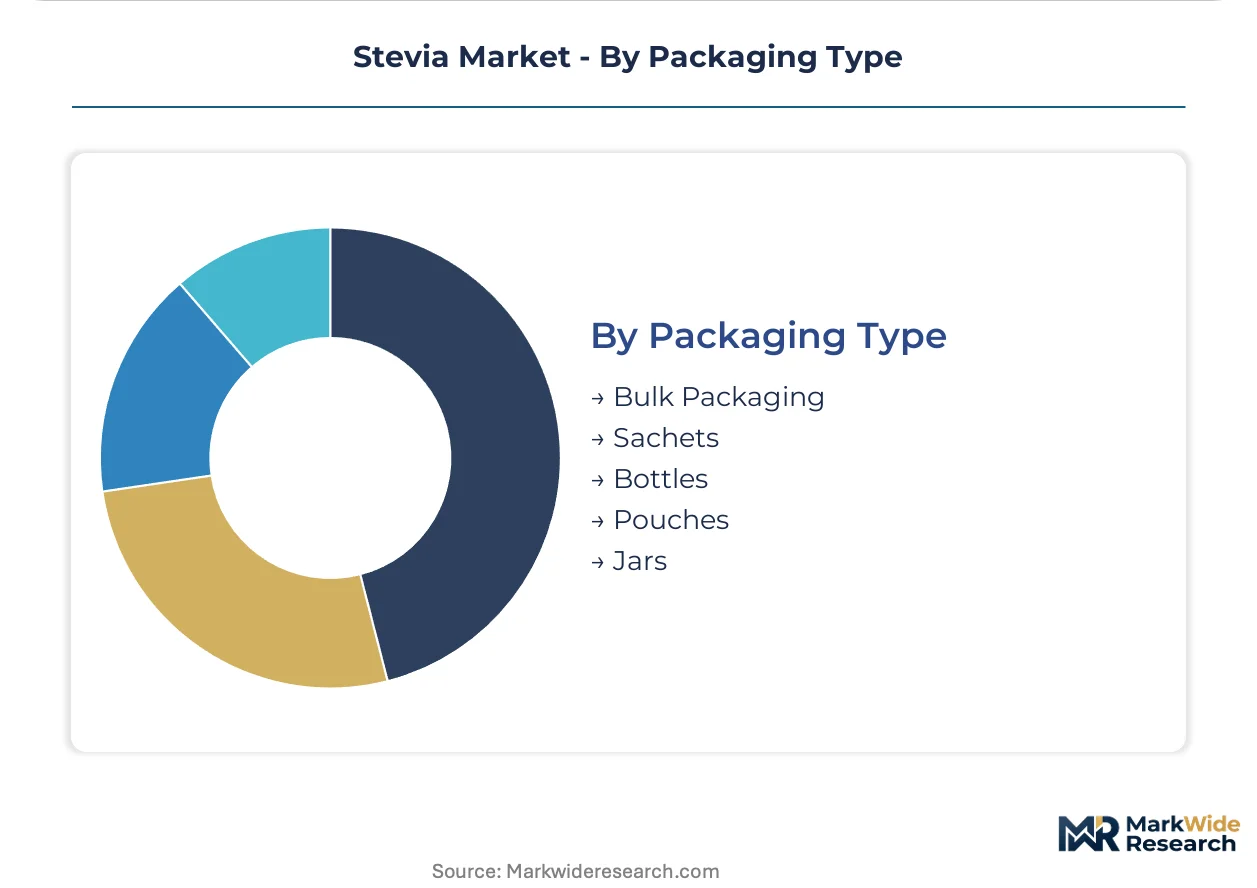
Packaging Type:
Industrial procurement favors bulk formats for cost efficiency, while retail and foodservice channels drive single-serve and consumer-oriented packaging.
- Bulk Packaging:25-kilogram drums and supersacks serve high-volume food manufacturers with dedicated formulation facilities. These formats minimize per-unit packaging costs and support just-in-time production scheduling.
- Sachets:Single-serve packets target foodservice and hospitality channels where portion control and convenience drive specification. Coffee shop chains and airline catering operations represent concentrated demand for sachet formats.
- Bottles:Liquid stevia in dropper bottles serves home bakers and small-scale food producers.
- Pouches:Flexible packaging accommodates powder stevia for retail grocery distribution.
- Jars:Wide-mouth containers facilitate scoop access for commercial kitchen environments.
Procurement scale favors Bulk Packaging. Format innovation concentrates in Sachets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paraguay's Itapúa Department anchors global stevia leaf cultivation, with the Guairá and Caazapá corridors supplying raw material to extraction facilities across three continents. Procurement patterns reflect regulatory divergence and sustainability certification requirements that reshape sourcing decisions.
United States
Carbonated beverage manufacturers in Atlanta and Chicago metropolitan areas drive procurement volumes for high-purity rebaudioside variants. The FDA's GRAS notification pathway accelerates ingredient qualification timelines for reformulated product lines. California-based clean-label food startups negotiate direct sourcing agreements with South American grower cooperatives, bypassing traditional distributor channels.
China
Shandong Province extraction facilities process stevia leaf from domestic cultivation clusters in Fujian and Guangxi provinces. GB standards for food additives govern glycoside purity thresholds and maximum usage levels across manufacturing applications. Qingdao port infrastructure supports bulk export shipments to European and North American formulators seeking cost-efficient stevioside grades.
Germany
Beverage formulators in Bavaria and North Rhine-Westphalia leverage EFSA novel food opinions to align product portfolios with harmonizing EU-US glycoside approval lists. The EU Green Deal's farm-to-fork sustainability targets influence procurement criteria toward certified supply chains with verified carbon footprints. Frankfurt-based ingredient distributors manage regional logistics for multinational CPG manufacturers.
India
Maharashtra and Karnataka food processors adopt stevia for clean-label packaged foods targeting emerging middle-class consumers in Mumbai and Bangalore metropolitan areas. FSSAI regulations on natural sweeteners create compliance frameworks for domestic manufacturers and importers. Domestic supply infrastructure lags demand growth, creating import dependency for high-purity glycoside grades.
Brazil
São Paulo state confectionery manufacturers integrate stevia for sugar-reduced candy and chewing gum formulations serving health-conscious urban consumers. ANVISA food additive regulations govern glycoside usage levels and labeling requirements across packaged food categories. Local cultivation trials in Minas Gerais seek to reduce import dependency on Paraguayan leaf supply.
Stevia Market Key Industry Players
The competitive structure tilts toward integrated agricultural processors with captive leaf supply and biotech-integrated specialists commanding premium placement. Market concentration reflects consolidation among extraction technology holders and downstream formulation partners. Three archetypes dominate: vertically integrated agricultural processors controlling cultivation-through-refining value chains, biotech-integrated suppliers leveraging enzymatic conversion for rare glycosides, and commodity traders managing spot market leaf procurement. Capacity expansion and direct sourcing contract negotiation constitute the dominant competitive moves.
Among North American ingredient conglomerates, Ingredion Incorporated and Cargill exemplify the vertically integrated archetype through agricultural partnerships spanning multiple continents. PureCircle occupies a position within the biotech-integrated tier, anchored by proprietary leaf varieties and extraction patents. Archer Daniels Midland Company represents the diversified agricultural processor model with global distribution infrastructure. These three anchors illustrate how competitive positioning stratifies across supply chain control, technological differentiation, and geographic reach.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| Archer Daniels Midland Company |
| PureCircle |
| Sweet Green Fields |
| Sunwin Stevia International |
| Cargill |
| GLG Life Tech Corporation |
| Foodchem International Corporation |
| Tate & Lyle PLC |
| Others |
Cost & Logistics Intelligence
The EU Green Deal's farm-to-fork sustainability targets govern both qualified supply access and premium-tier pricing eligibility, as certification requirements filter out uncertified growers while rewarding verified carbon-footprint suppliers with preferential contract terms. Buyers lacking sustainability credentials face exclusion from European procurement channels, compressing their effective supply base and amplifying price premiums for compliant material.
Pricing Analysis
Taste-parity outcomes anchor value-based pricing, with beverage formulators paying premiums for rebaudioside A grades that achieve sugar-equivalent sweetness profiles without bitter aftertaste. Three-tier pricing structure across premium, standard, and economy levels separates high-purity rebaudioside M from commodity stevioside and unrefined leaf extracts. Cost compression in standard grades is intensifying because enzymatic bioconversion methods displace conventional extraction, eroding margins for agronomic processors. Food and beverage manufacturers show highest price sensitivity, while pharmaceutical buyers accept cost premiums for excipient-grade documentation.
Supply Chain Analysis
Domestic-content mandates in India's FSSAI framework and China's GB standards are reshaping sourcing patterns, pushing multinational formulators to establish local extraction partnerships rather than rely on imported refined glycosides. Leaf supply concentrates in Paraguay, China, and Brazil, with Itapúa Department cultivation anchoring global raw material flows. Processing draws from stevia leaf biomass, enzymatic conversion catalysts, and pharmaceutical-grade filtration membranes. Single-source vulnerability runs through Paraguayan harvest concentration, where climate variability threatens annual leaf availability. Distribution runs through regional ingredient distributors and direct procurement contracts with cultivation cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over enzymatic conversion technology and captive leaf supply determines margin capture. Players are pursuing backward integration into rare glycoside bioproduction to escape commodity pricing traps.
For Market Incumbents: To counter enzymatic bioconversion specialists eroding traditional extraction margins, secure proprietary leaf varieties through breeding partnerships and expand in-house bioprocessing capacity. Lock in multi-year direct sourcing agreements with Paraguayan grower cooperatives to preempt competitor access to certified sustainable supply.
For New Entrants and Emerging Players: Pharmaceutical excipient buyers remain underserved by incumbent suppliers focused on beverage volume contracts. Penetrate this segment through FDA GRAS notification support services and excipient-grade documentation capabilities. Build initial beachheads through liquid stevia formulations for pediatric and geriatric drug applications where precise dosing commands price insensitivity.
For Investors and Strategic Acquirers: EFSA-FDA glycoside approval list convergence is the leading indicator that formulation complexity costs are about to collapse, rewarding suppliers with harmonized global product portfolios. Target biotech-integrated specialists with enzymatic rebaudioside M and D production capabilities. Watch for direct sourcing contract announcements between major beverage manufacturers and South American cultivation cooperatives as signals of distributor disintermediation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Conversion Scale-Up | Biocatalytic processing unlocks rare glycosides at commercial purity thresholds, displacing leaf extraction. |
| Direct Sourcing Partnership | Bypassing distributor layers concentrates price risk with buyers while securing farm-to-fork traceability credentials. |
| Regulatory Harmonization Investment | Aligning formulation portfolios with converging EFSA-FDA approval lists eliminates redundant SKU maintenance costs. |
| Sustainability Certification Program | EU Green Deal compliance gates European procurement access and commands premium positioning in clean-label channels. |
| Pharmaceutical Excipient Qualification | FDA GRAS pathway penetration opens tablet coating and pediatric formulation markets with specialized margin structures. |
Research Approach
Document review covered FDA GRAS notifications, EFSA novel food opinions, FSSAI regulations, and GB standards for food additives, complemented by interviews with extraction technology directors, beverage formulation scientists, pharmaceutical excipient procurement managers, and Paraguayan cultivation cooperative representatives. Secondary sources included customs and trade data on stevia leaf and refined glycoside shipments, SEC filings from publicly traded ingredient companies, and sustainability certification databases. Bottom-up volume estimates from end-use application modeling were triangulated against top-down supply-side capacity assessments.
Market size and growth projections were generated across the analysis window through segmented demand modeling by glycoside purity grade, physical format, application sector, and geographic regulatory cluster. The analytical framework incorporated beverage industry sugar reduction target announcements, pharmaceutical excipient qualification timelines, and enzymatic conversion technology adoption curves as industry-specific forecast inputs. CAGRs were derived from regression analysis of historical procurement volume trends and projected reformulation cycle accelerations.
Revisions become necessary when regulatory divergence re-emerges between major jurisdictions, enzymatic production economics shift dramatically, or climate events disrupt Paraguayan leaf harvests. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Compressible Sugar Market
Sweeteners
D Psicose Market
Sweeteners
Oligofructose Market
Sweeteners
Specialty Sweeteners Market
Sweeteners
Invert Sugar Market
Sweeteners
South Africa Food Sweetener Market
Sweeteners
Non Sugar Sweeteners Market
Sweeteners
Saccharin Market
Sweeteners
Erythritol Market
Sweeteners
Plant-Derived Sweetener Market
Sweeteners
Global Brown Sugar Market
Sweeteners
Gluten-Free Sugar Syrup Market
Sweeteners
South America Sugar Substitutes Market
Sweeteners
Natural Stevia Market
Sweeteners
North America Sugar Substitutes Market
Sweeteners
Natural Sweeteners Market