
 Compressible Sugar Market | 2026-2036
Compressible Sugar Market Size, Share, and Industry Trends Forecast 2026-2036
Compressible Sugar Market Outlook
Multi-source procurement is decoupling from traditional single-source dependencies across compressible sugar supply chains. Cargill leverages its integrated agricultural sourcing to secure consistent raw material flows. Südzucker anchors European production capacity with specialized refining infrastructure for pharmaceutical-grade output. DFE Pharma differentiates through dedicated excipient certification programs that serve contract manufacturing organizations.
Compressible sugar denotes a refined sucrose or sugar-based material processed to achieve specific particle size distribution, hardness, and flow properties enabling direct compression into tablets without granulation. The material typically contains 95-99% sucrose with added binders such as maltodextrin or invert sugar to enhance compaction behavior, serving primarily as a filler-binder in pharmaceutical oral dosage forms and as a functional ingredient in confectionery tableting. Powdered sugar variants command premium positioning due to their superior dissolution profiles in quick-melt applications, while granulated formats sustain volume leadership across conventional bakery and beverage manufacturing where flowability requirements are less stringent. Confectionery applications are gaining structural importance as clean-label tableted candies replace traditional boiled-sugar processes.
The FDA enforces ICH Q3D elemental impurity limits that elevate purity requirements for pharmaceutical-grade compressible sugar, while the EPA regulates wastewater discharge from sucrose refining operations that constrains capacity expansion at older facilities. The European Medicines Agency applies EudraLex Volume 4 GMP annexes to excipient manufacturing, creating compliance barriers for food-grade suppliers attempting upstream migration into pharmaceutical channels. Stakeholders must monitor evolving pharmacopeial harmonization between USP-NF and EP monographs for sugar-based excipients, as divergence in testing protocols directly shapes qualification costs and market access timelines.
Market Dynamics
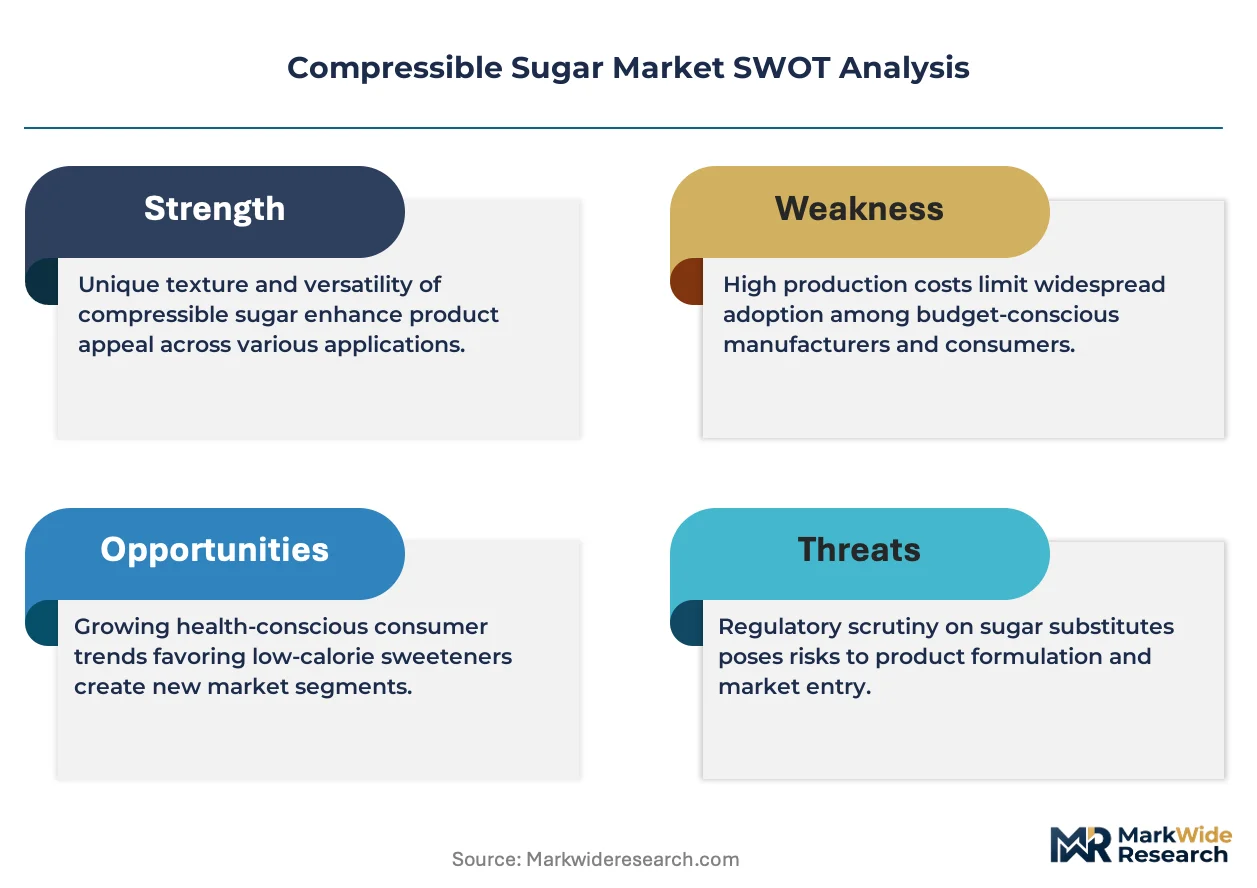
Pharmaceutical-grade purity mandates from the FDA's ICH Q3D guidelines are compressing supply bases while pulling food-grade processors toward dedicated excipient infrastructure. This regulatory gravity is restructuring competitive positions across raw material sourcing and refining investments.
Growth Catalysts
- Direct-compression tablet demand:Oral solid dosage manufacturers are bypassing wet granulation steps, pulling specialized compressible sugar grades into high-volume production lines.
- ICH Q3D elemental limits:The FDA's impurity thresholds are disqualifying conventional sucrose refiners and concentrating qualified supply among pharmaceutical-certified processors.
- Clean-label confectionery pivot:Boiled-sugar candy makers are migrating to tableting processes that require compressible sugar's flow and compaction properties.
Market Restraints
- Beet and cane price volatility:Agricultural commodity swings compress margin structures for processors lacking long-term grower contracts.
- Rhineland-Palatinate supply concentration:Südzucker's specialized facilities create single-point vulnerability for European pharmaceutical-grade supply security.
- Granulation substitution:Roller-compacted lactose and microcrystalline cellulose are capturing share in moisture-sensitive formulations.
Strategic Opportunities
- Indian contract manufacturing penetration:CDMOs in Hyderabad and Ahmedabad are expanding excipient qualification programs for export markets.
- Quick-dissolve candy applications:Sublingual and orally disintegrating formats are opening premium positioning for ultra-fine powdered sugar variants.
- EMA EudraLex Annex compliance:Food-grade suppliers achieving GMP certification are accessing pharmaceutical channels with 40-60% price premiums.
Industry Challenges
- Excipient qualification timelines:USP-NF and EP monograph divergence is extending customer approval cycles for new supplier onboarding.
- Legacy wastewater infrastructure:EPA discharge permits at older refineries constrain capacity expansion without multi-million dollar treatment upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compressible Sugar Market |
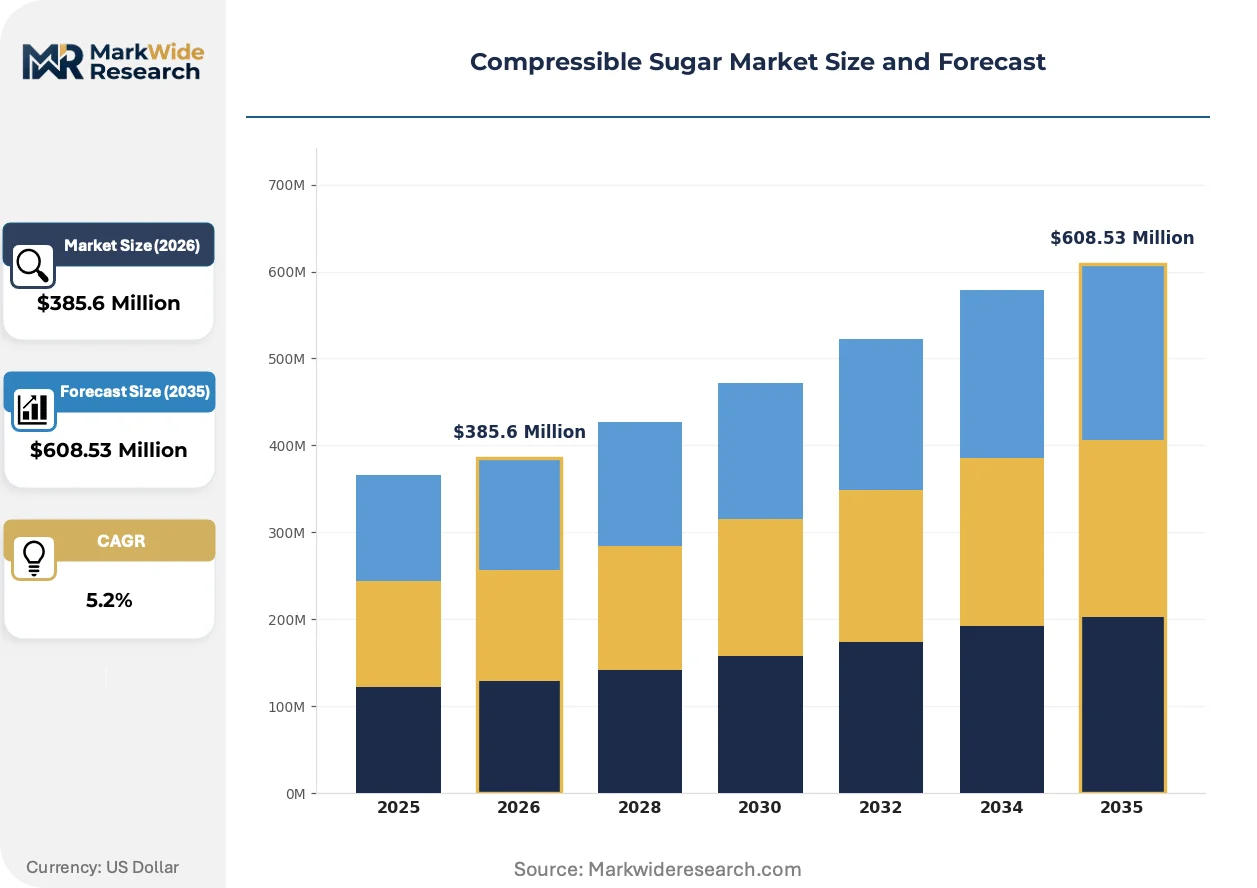
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $608.53 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cubed Sugar, Granulated Sugar, Powdered Sugar, Brown Sugar Application: Bakery Products, Beverages, Confectionery, Dairy Products End User: Food Manufacturers, Retail Chains, Restaurants, Catering Services Packaging Type: Bags, Jars, Bulk Containers, Sachets |
| Companies Covered | Cargill, Ingredion Incorporated, Südzucker, Roquette Frères, Nordzucker, Indiana Sugars, Colorcon, Tate & Lyle, DFE Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compressible Sugar Market Strategic Shifts
Continuous processing technologies are displacing batch refining across sucrose purification, compressing cycle times and enabling real-time release testing. These shifts are redrawing capital deployment patterns and quality assurance architectures.
Continuous manufacturing platforms are decentralizing quality control from centralized labs to production-line sensors. Pharmaceutical tablet makers in Germany and Switzerland are adopting these systems for direct-compression workflows, collapsing batch release timelines from weeks to hours. This compression is decentralizing supplier qualification burdens toward real-time data sharing rather than retrospective documentation.
REACH registration requirements for sugar derivatives are tightening substance identity specifications across EU member states. Refiners must now document full supply chain provenance from agricultural source to final particle engineering, elevating compliance costs for multi-origin processors. Pharmaceutical-grade suppliers with integrated beet sourcing are capturing preferential positioning against traders blending multiple origins.
Buyer consolidation among top-ten generic pharmaceutical manufacturers is compressing supplier rosters and extending contract durations. These procurement patterns are displacing spot-market relationships with multi-year volume commitments tied to audit rights and dedicated capacity provisions. The shift is most visible in North American and Western European markets where three buyers now account for majority excipient procurement volumes.
Compressible Sugar Market Segmentation
Compressible sugar procurement decisions pivot on functional specifications that vary sharply across tablet hardness requirements, dissolution profiles, and regulatory compliance tiers. Manufacturers segment their portfolios to align particle engineering with end-use constraints, from pharmaceutical direct-compression to confectionery tableting workflows.
Product Type:
Buyers select particle morphology based on compaction behavior and dissolution speed requirements, with pharmaceutical applications demanding tighter specification bands than food-grade uses.
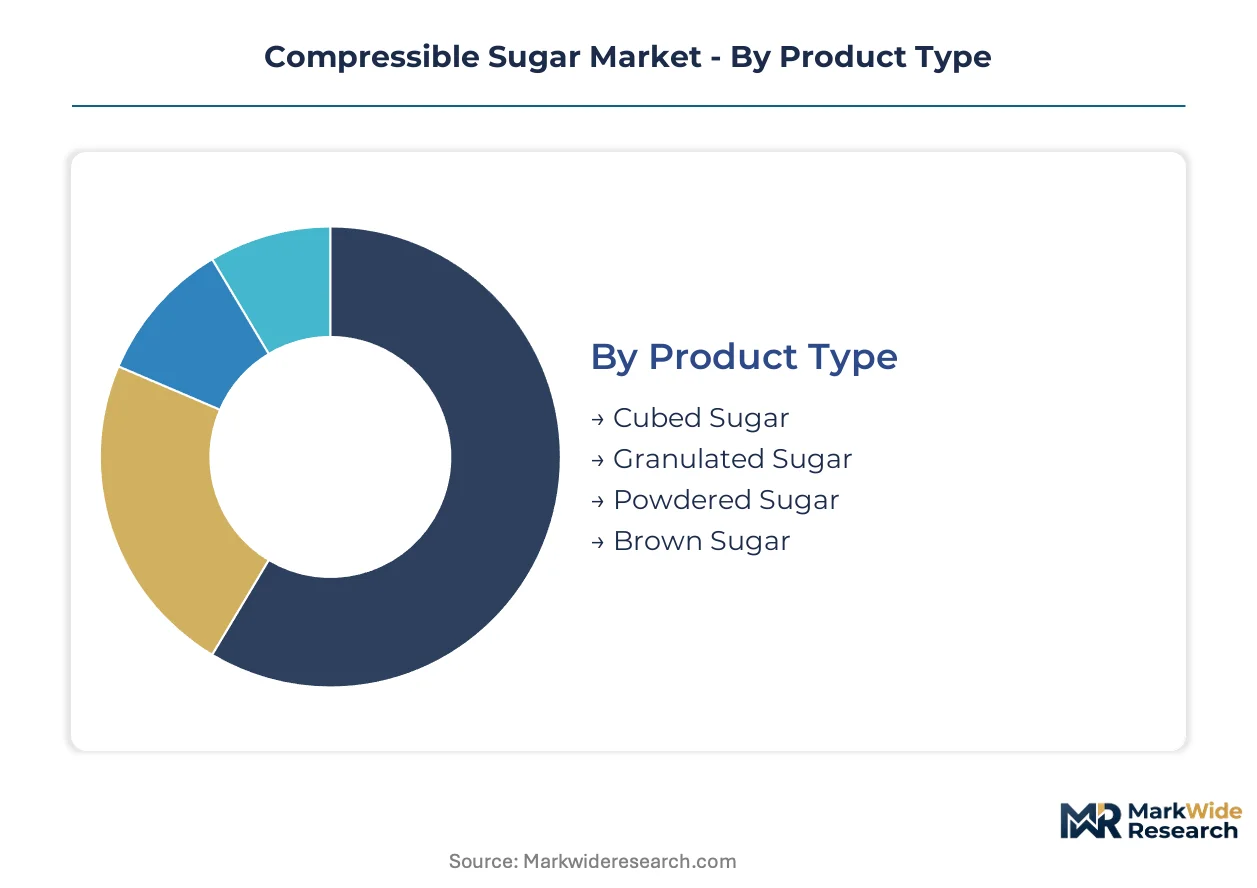
- Powdered Sugar:Ultra-fine sucrose particles (typically below 100 microns) with added maltodextrin binders deliver superior dissolution kinetics for quick-melt tablets and sublingual formats. Demand concentrates in Swiss and German pharmaceutical manufacturing clusters where FDA ICH Q3D compliance commands 40-60% price premiums over standard grades.
- Granulated Sugar:Crystalline sucrose with controlled particle size distribution (200-500 microns) provides flowability for high-speed rotary tablet presses without pre-granulation steps. Volume leadership holds across conventional bakery and beverage applications in the United States where flowability requirements are less stringent and cost sensitivity runs higher.
- Cubed Sugar:Agglomerated crystals bonded with invert sugar syrup for controlled hardness and fracture patterns in specialty confectionery tableting.
- Brown Sugar:Molasses-retained variants with elevated moisture content and distinct flavor profiles serving niche confectionery and artisanal bakery segments.
Volume sits with Granulated Sugar; growth tilts toward Powdered Sugar.
Application:
End-use specifications diverge across moisture sensitivity, tablet hardness tolerances, and clean-label positioning that reshape formulation choices.
- Confectionery:Clean-label tableted candies are displacing traditional boiled-sugar processes, pulling compressible sugar with specific flow and compaction properties into high-volume production lines. European manufacturers in Belgium and the Netherlands lead this pivot as REACH documentation requirements favor single-origin beet supply chains.
- Bakery Products:Compressible sugar functions as a functional filler in pressed cookie and biscuit formats where particle size controls spread behavior and surface finish. North American contract bakeries drive procurement volumes for standardized granulated grades with less stringent purity thresholds than pharmaceutical channels.
- Beverages:Instant drink mixes and effervescent tablets employ compressible sugar as a carrier and sweetener in single-serve formats.
- Dairy Products:Tableted milk powders and probiotic delivery systems use compressible sugar for moisture protection and flow enhancement.
Confectionery captures the steepest expansion trajectory; Bakery Products anchor current volume.
End User:
Procurement scale and qualification intensity separate large-scale manufacturing from fragmented foodservice channels.
- Food Manufacturers:Integrated production facilities with dedicated excipient qualification teams and multi-year supply agreements. These buyers concentrate in Germany, Switzerland, and the United States where FDA and EMA compliance architectures are embedded.
- Retail Chains:Private-label tableted confectionery and bakery products drive demand for mid-tier grades with basic food-safety certification.
- Restaurants:Limited compressible sugar use confined to specialty dessert preparations and beverage garnishes.
- Catering Services:Minimal penetration due to batch-scale cooking methods that bypass tableting processes entirely.
Food Manufacturers dominate procurement volumes; Retail Chains are expanding most quickly.
Packaging Type:
Logistics economics and contamination risk shape format selection across pharmaceutical and food-grade supply chains.
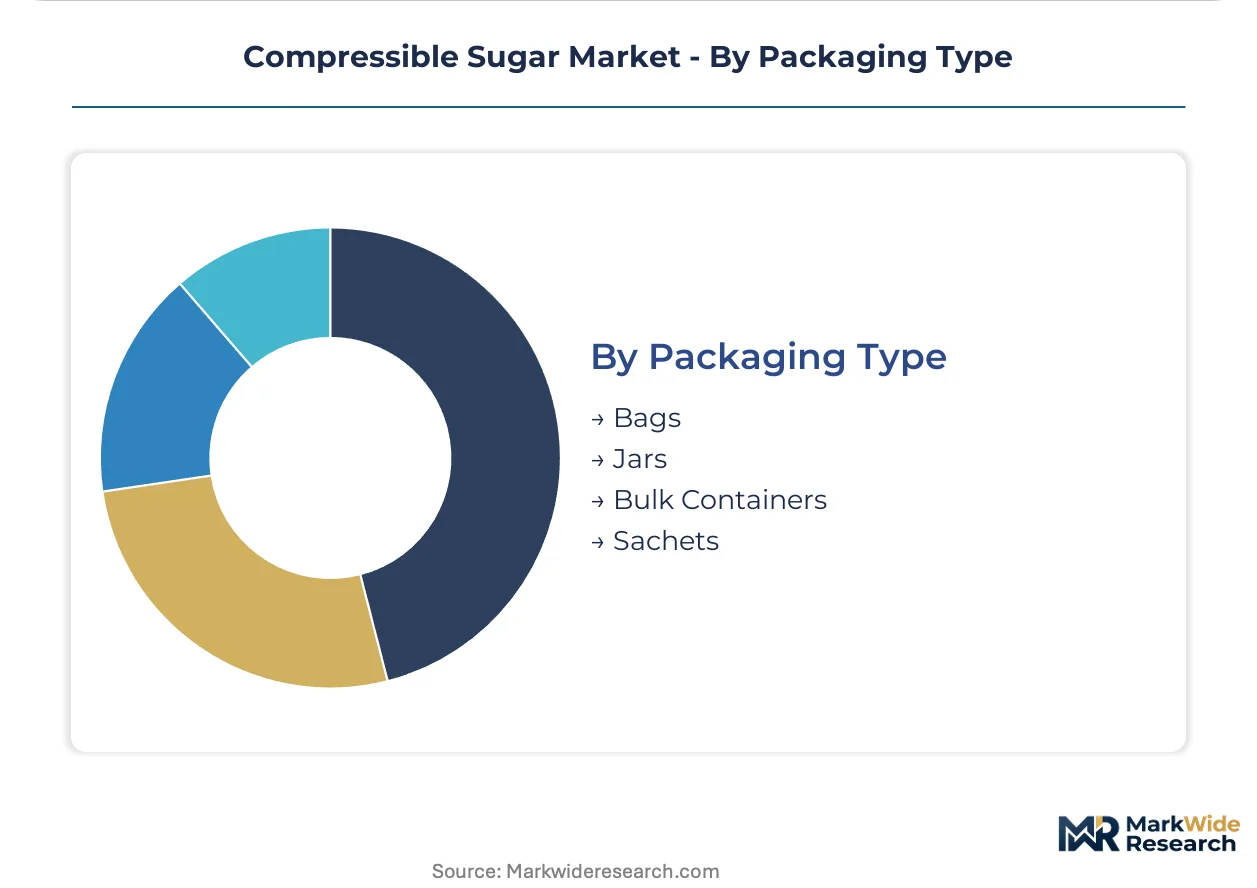
- Bulk Containers:Intermediate bulk containers and lined totes serve pharmaceutical manufacturers with dedicated production lines and validated cleaning protocols. These formats minimize per-kilogram packaging costs for high-volume tablet operations in Germany and the United States.
- Sachets:Single-serve moisture-barrier packets protect hygroscopic powdered sugar grades for quick-dissolve applications and field-use pharmaceuticals.
- Bags:Multi-layer paper and polymer bags balance cost and protection for standard food-grade granulated sugar.
- Jars:Rigid containers serve retail and foodservice channels requiring repeated access and visual product presentation.
Bulk Containers carry the volume base; Sachets gain share fastest in pharmaceutical logistics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical-grade demand concentrates in Germany due to Südzucker's specialized production infrastructure and strong regional distribution networks. Food-grade procurement anchors volume in the United States, while confectionery tableting growth accelerates in Belgium and the Netherlands.
Germany
Direct-compression tablet manufacturers in Rhineland-Palatinate drive pharmaceutical-grade demand for ICH Q3D-compliant compressible sugar. EMA EudraLex Volume 4 GMP annexes create compliance barriers for food-grade suppliers attempting upstream migration. Mannheim-based refining clusters specialize in ultra-fine powdered sugar variants for quick-melt applications.
United States
Contract bakeries and beverage manufacturers sustain volume leadership for standard granulated grades with less stringent purity thresholds. FDA ICH Q3D elemental impurity limits elevate qualification costs for pharmaceutical channels. Chicago and Minneapolis metropolitan areas concentrate food-grade procurement for pressed cookie and instant drink mix production.
Belgium
Clean-label tableted candy manufacturers displace traditional boiled-sugar processes, pulling specialized compressible sugar grades into high-volume confectionery lines. REACH registration requirements favor single-origin beet supply chains with full provenance documentation. Antwerp industrial zones anchor European confectionery tableting capacity expansion.
India
Contract manufacturing organizations in Hyderabad and Ahmedabad expand excipient qualification programs for export markets. CDSCO pharmaceutical regulations align with USP-NF monographs to accelerate customer approval cycles. Gujarat's specialized refining infrastructure supports backward integration into pharmaceutical-grade sucrose purification.
Switzerland
Swissmedic oversight drives premium positioning for ultra-fine powdered sugar in sublingual and orally disintegrating tablet formats. Continuous manufacturing platforms collapse batch release timelines from weeks to hours. Basel and Zurich pharmaceutical clusters adopt real-time release testing for direct-compression workflows.
Compressible Sugar Market Competitive Environment
Capacity expansion dominates the current landscape as food-grade processors build dedicated excipient infrastructure to capture pharmaceutical price premiums. The vendor base stratifies across integrated agricultural conglomerates, specialized European refiners, and pharmaceutical-focused excipient houses. Three archetypes define competitive positioning: beet-centric integrated processors with captive sourcing, multi-origin traders blending agricultural inputs, and certification-heavy specialists serving contract manufacturing organizations. M&A activity concentrates among mid-tier refiners seeking GMP compliance capabilities, while strategic partnerships link raw material security to long-term pharmaceutical supply agreements.
Among integrated agricultural processors, Cargill leverages its North American sourcing networks to secure consistent raw material flows for food-grade and pharmaceutical channels alike. Südzucker anchors European production capacity with specialized refining infrastructure located in Germany's Rhineland-Palatinate region. DFE Pharma occupies a position within the pharmaceutical-certified specialist tier, differentiating through dedicated excipient certification programs that serve contract manufacturing organizations in regulated markets.
| Leading Market Players |
|---|
| Cargill |
| Ingredion Incorporated |
| Südzucker |
| Roquette Frères |
| Nordzucker |
| Indiana Sugars |
| Colorcon |
| Tate & Lyle |
| DFE Pharma |
| Others |
Value Chain & Pricing Dynamics
Captive beet sourcing from Rhineland-Palatinate agricultural networks anchors both Südzucker's supply security and its pricing power over pharmaceutical-grade compressible sugar. This backward integration insulates the producer from commodity spot volatility while enabling 40-60% price premiums for ICH Q3D-compliant grades.
Pricing Analysis
Warranty-like certification bundling separates pharmaceutical-grade contracts from unbundled food-grade spot purchases. Three-tier pricing structure across premium, standard, and economy levels tracks certification intensity, with FDA ICH Q3D compliance and EMA EudraLex Annex adherence commanding the top tier. Cost compression in standard granulated grades is intensifying because Cargill's integrated North American sourcing floods bakery and beverage channels. Food manufacturers with multi-year contracts show the least price sensitivity; spot-market confectionery buyers exhibit the most.
Supply Chain Analysis
Ocean freight and Rhine barge economics concentrate pharmaceutical-grade flows through Antwerp and Rotterdam ports toward German tablet manufacturers. Germany, Belgium, and the United States anchor supply, with India emerging through Gujarat's specialized refining infrastructure. Production draws from beet sugar in Europe and cane sugar in North America, with maltodextrin binders sourced from corn processing clusters. Single-source vulnerability around Südzucker's Rhineland-Palatinate facilities threatens European pharmaceutical-grade security. Distribution runs through validated bulk container networks for pharmaceutical channels and multi-layer bag formats for food-grade procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The compressible sugar market is a vertical-integration race, with players pursuing captive agricultural sourcing to lock in raw material security and capture pharmaceutical price premiums.
For Market Incumbents: Acquire specialized GMP-certified refining assets in pharmaceutical-dense geographies to consolidate excipient qualification capabilities. Expand backward integration into beet supply contracts in Germany's Rhineland-Palatinate region. Roller-compacted lactose substitutes threaten share in moisture-sensitive formulations; defensive patent positioning around particle engineering processes preserves differentiation. For New Entrants and Emerging Players: Mid-tier contract manufacturing organizations in India represent the most penetrable buyer archetype, as CDSCO-aligned qualification programs accelerate customer approval cycles. Target quick-dissolve candy applications where ultra-fine powdered sugar variants command premium positioning and regulatory barriers remain lower than pharmaceutical channels. Lead with dedicated excipient certification programs that mirror DFE Pharma's contract manufacturing organization service model. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated agricultural conglomerates seeking pharmaceutical-grade capabilities. Five-to-ten-year viability hinges on EMA EudraLex Annex compliance infrastructure that food-grade processors cannot replicate without multi-million dollar investments. Watch for FDA-USP-NF and EP monograph harmonization progress as the inflection signal—convergence collapses qualification timelines and unlocks margin expansion for certified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Beet Sourcing | Cargill and Südzucker secure Rhineland-Palatinate agricultural networks against commodity volatility. |
| GMP Certification Investment | Food-grade suppliers access pharmaceutical channels with 40-60% price premiums through EMA EudraLex Annex compliance. |
| Continuous Manufacturing Platform Adoption | German and Swiss tablet makers collapse batch release timelines from weeks to hours with real-time release testing. |
| Indian CDMO Partnership Expansion | Hyderabad and Ahmedabad contract manufacturers accelerate excipient qualification for export markets. |
| REACH Registration Completion | European confectionery tableting secures single-origin beet supply chains with full provenance documentation. |
Study Parameters
Independent corroboration across excipient procurement managers at contract manufacturing organizations, regulatory affairs leads at pharmaceutical tablet manufacturers, and technical directors at sugar refiners underwrites the qualitative findings. Secondary validation drew from FDA ICH Q3D guidance documents, EMA EudraLex Volume 4 GMP annexes, USP-NF and EP monograph drafts, and customs trade data for sucrose derivative flows. Bottom-up segmentation modeling triangulated against top-down market sizing from agricultural processing capacity disclosures.
Rate-of-change decomposition across product type, application, end user, and packaging format dimensions structured the analytical framework. CAGRs derived from volume-to-value conversion using segment-specific price points for pharmaceutical-grade versus food-grade tiers. Modeled inputs included ICH Q3D compliance adoption curves, clean-label confectionery tableting penetration rates, and continuous manufacturing platform deployment timelines across German and Swiss pharmaceutical clusters.
Revisions become necessary when FDA-USP-NF and EP monograph divergence accelerates, REACH registration requirements tighten substance identity specifications, or beet and cane commodity volatility exceeds historical bands. Forecasts reflect documented assumptions about regulatory harmonization progress and agricultural supply contract structures. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
South America Stevia Market
Sweeteners
Natural Sweetener Blends Market
Sweeteners
Allulose Market
Sweeteners
Japan Food Sweetener Market
Sweeteners
Sweet Modulator Market
Sweeteners
Natural Caloric Sweeteners Market
Sweeteners
Africa Stevia Market
Sweeteners
Galactose Market
Sweeteners
Sugar Substitutes Market
Sweeteners
North America Food Sweetener Market
Sweeteners
Clarified Rice Syrup Market
Sweeteners
Allulose Powder Market
Sweeteners
Middle East and Africa Low Calorie Sweeteners Market
Sweeteners
Tagatose Market
Sweeteners
Tapioca Maltodextrin Market
Sweeteners
China Allulose Market