
 Natural Sweeteners Market | 2026-2036
Natural Sweeteners Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Sweeteners Market Analysis
The EU Green Deal's farm-to-fork strategy is consolidating procurement standards for plant-derived ingredients across European food manufacturers. Cargill leverages its South American stevia supply chain to secure raw material continuity for European processors. Tate & Lyle PLC anchors its position through specialty sweetener formulations targeting reduced-sugar dairy applications. Ingredion Incorporated competes on enzymatic conversion technologies that enhance Reb M yields from stevia leaf.
Natural sweeteners comprise non-caloric or low-caloric carbohydrate substitutes extracted from botanical sources such as Stevia rebaudiana, Agave tequilana, and Cocos nucifera sap, typically standardized to specific glycoside concentrations or degrees Brix for industrial consistency. Their primary commercial purpose centers on replicating sucrose's sensory profile while enabling compliance with sugar reduction mandates from public health authorities. Stevia extracts dominate volume flows due to established GRAS status and scalable leaf processing infrastructure, whereas agave nectar commands premium positioning in organic-certified beverage lines. The bakery application segment presents formulation complexity around Maillard reaction preservation, creating specialized demand for heat-stable Reb D variants.
The FDA's added sugars declaration requirement and EFSA's ongoing evaluations of novel sweetener safety profiles shape product development timelines and market access conditions for new entrants. BIS certification requirements in India and China's NMPA food additive standards further fragment approval pathways for steviol glycoside variants. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and prioritize approval investments.
Market Dynamics
The FDA's added sugars labeling mandate compresses reformulation timelines for beverage manufacturers, forcing accelerated stevia and monk fruit adoption while Brazil's stevia cultivation clusters tighten raw material access for processors.
Growth Catalysts
- EU Green Deal farm-to-fork strategy:Consolidated procurement standards across European food manufacturers expand certified plant-derived ingredient volumes.
- Enzymatic conversion technologies:Enhanced Reb M yields from stevia leaf reduce production costs for high-purity glycoside extracts.
- Reduced-sugar dairy applications:Specialty sweetener formulations penetrate yogurt and flavored milk segments with heat-stable variants.
Market Restraints
- Stevia leaf supply concentration:Brazil's cultivation clusters create geographic vulnerability for global extractors dependent on South American raw material flows.
- Regulatory fragmentation:Divergent BIS certification requirements in India and NMPA food additive standards in China multiply approval costs for steviol glycoside variants.
- Maillard reaction limitations:Bakery applications face formulation barriers as conventional stevia extracts degrade under thermal processing conditions.
Strategic Opportunities
- Organic-certified beverage lines:Agave nectar commands premium positioning in health-focused consumer segments with supply chain traceability requirements.
- Heat-stable Reb D variants:Specialized glycoside development unlocks high-temperature bakery and confectionery applications previously closed to natural sweeteners.
- EFSA novel sweetener evaluations:Ongoing safety assessments create pathways for expanded glycoside approvals across European processed food categories.
Industry Challenges
- Multi-jurisdiction compliance timelines:Stakeholders must sequence approval investments across FDA, EFSA, BIS, and NMPA frameworks with non-overlapping evaluation periods.
- Legacy sucrose formulation expertise:Food technologists require retraining in glycoside blending ratios and bulking agent compensation for functional parity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Sweeteners Market |
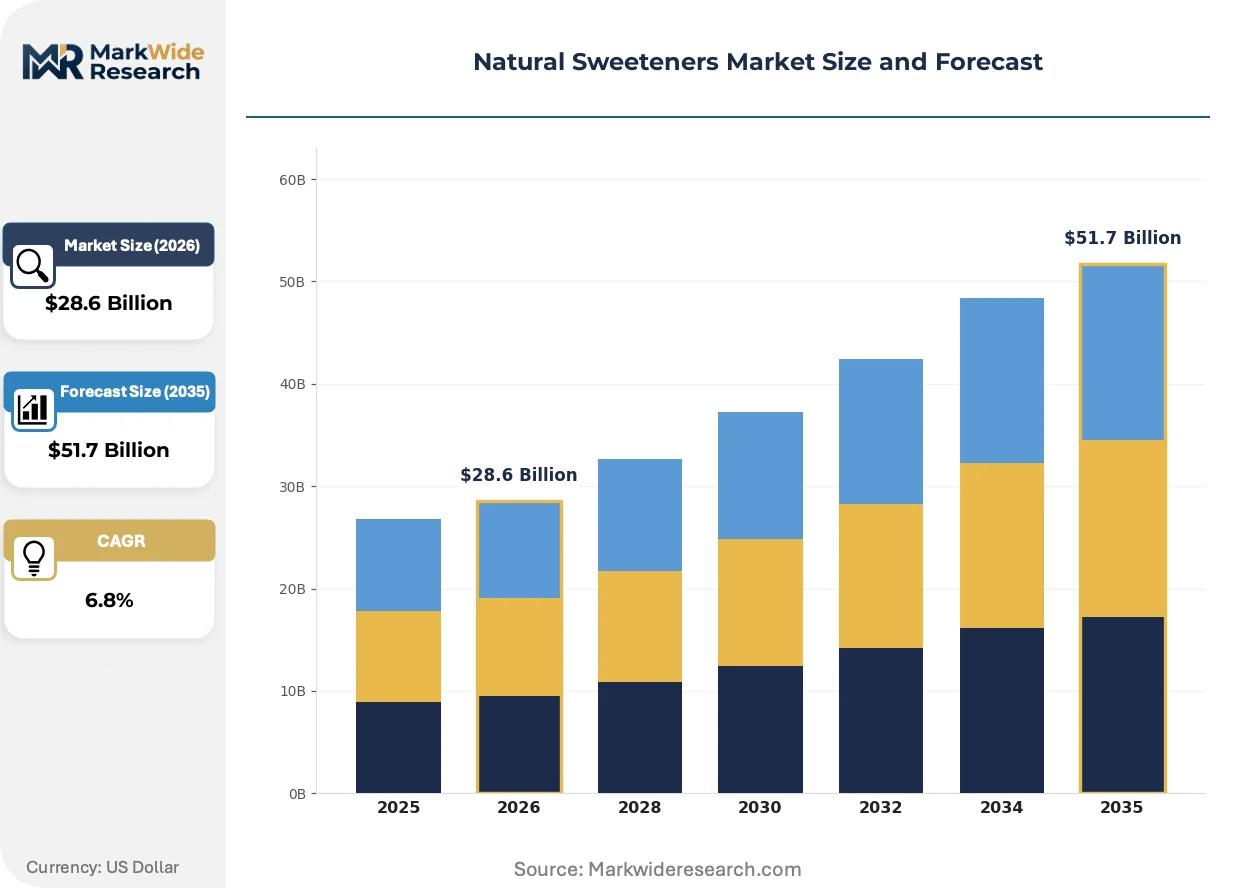
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stevia, Agave Nectar, Honey, Coconut Sugar Application: Beverages, Bakery, Confectionery, Dairy End User: Retail Consumers, Food Manufacturers, Restaurants, Health-focused Brands Form: Liquid, Powder, Granulated, Syrup |
| Companies Covered | Tate & Lyle PLC, PureCircle, Cargill, International Flavors & Fragrances Inc., GLG Life Tech Corp, Archer Daniels Midland Company, Roquette Frères, DSM-Firmenich AG, Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Sweeteners Market Emerging Trajectories
Bioprocessing advances and regulatory disclosure requirements are restructuring how sweetener developers engineer glycoside purity and position extracts across temperature-sensitive applications.
Precision fermentation for steviol glycoside production is converging with traditional leaf extraction methods, allowing ingredient suppliers to bypass agricultural yield constraints. Biotech-enabled manufacturers now supply beverage formulators with consistent Reb M concentrations independent of harvest cycles. This convergence is compressing cost differentials between synthetic biology and botanical extraction routes.
EFSA's ongoing evaluations of novel sweetener safety profiles are extending product development timelines for entrants seeking European market access. The industrial consequence is delayed revenue recognition and redirected R&D budgets toward jurisdictions with established GRAS-equivalent pathways. Reduced-sugar dairy applications face the tightest certification bottlenecks as EFSA demands expanded toxicological datasets for heat-processed glycoside formulations.
Direct procurement contracts between beverage manufacturers and stevia cultivation cooperatives are displacing traditional multi-tier sourcing structures. Large-scale formulators in North America and Western Europe now negotiate exclusive leaf supply agreements with Brazilian producer associations. This pattern is most visible in carbonated soft drink segments where volume commitments justify captive agricultural investment.
Natural Sweeteners Market Segmentation
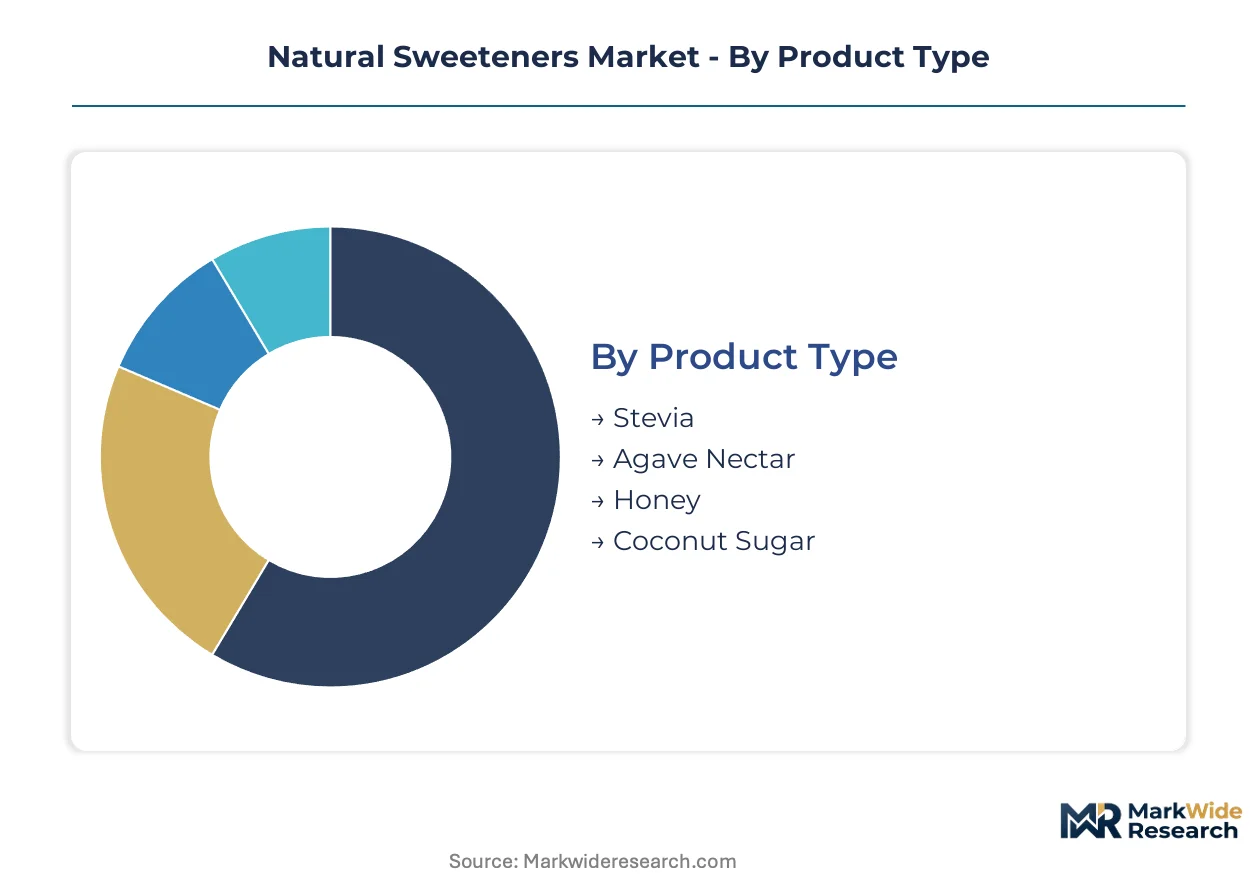
Natural sweetener procurement decisions pivot on glycoside concentration standards, thermal stability requirements, and clean-label certification tiers. Manufacturers sequence ingredient adoption across product lines based on reformulation complexity and regulatory approval status in target markets.
Product Type:
Upgrade cycles in beverage reformulation are accelerating displacement of conventional sucrose across multiple glycoside classes, with heat-stable variants commanding premium positioning in processed food applications.
- Stevia:Purified steviol glycosides standardized to Reb A, Reb M, or Reb D concentrations deliver non-caloric sweetness with GRAS-equivalent regulatory pathways in major jurisdictions. Beverage manufacturers in the United States and Brazil concentrate procurement on high-purity Reb M extracts for carbonated soft drink lines, driven by FDA added sugars labeling mandates.
- Agave Nectar:Fructose-dominant syrup extracted from Agave tequilana cores carries organic certification premiums and lower glycemic index positioning. Health-focused brands in Mexico and California leverage supply chain traceability for premium beverage positioning, constrained by seasonal harvest variability and water-intensive cultivation.
- Honey:Floral-source varietals with standardized pollen content and enzymatic activity markers serve regional bakery and confectionery formulators seeking non-GMO positioning.
- Coconut Sugar:Sap-derived granules with retained mineral content occupy niche organic retail segments, limited by Southeast Asian supply concentration and moisture sensitivity in industrial processing.
Stevia sits at the top of the volume ranking, with agave nectar climbing the fastest among premium-positioned alternatives.
Application:
Cost-tier differentiation separates commodity beverage sweetening from specialized bakery formulations requiring Maillard reaction preservation and thermal stability engineering.
- Beverages:Carbonated soft drinks, flavored waters, and ready-to-drink teas drive bulk glycoside consumption with formulation emphasis on cold-dissolution rates and clean aftertaste profiles.
- Bakery:Heat-stable Reb D variants unlock bread and pastry applications where conventional stevia degrades under oven temperatures, with European manufacturers leading adoption.
- Confectionery:Hard candies and chewing gums demand precise crystallization control and bulking agent compensation for texture parity with sucrose-based benchmarks.
- Dairy:Yogurt and flavored milk segments require acid-stable glycoside formulations that maintain sweetness intensity through fermentation and pasteurization cycles.
Beverages capture the largest volume share, while dairy applications are gaining share fastest through reduced-sugar product line expansions.
End User:
Customer-type stratification reflects divergent procurement scales, with food manufacturers negotiating direct agricultural contracts while retail channels prioritize SKU breadth and certification labeling.
- Retail Consumers:Supermarket and e-commerce channels emphasize organic certification, non-GMO verification, and single-ingredient positioning for home baking and beverage preparation.
- Food Manufacturers:Industrial buyers secure volume commitments through exclusive supply agreements with Brazilian stevia cooperatives, bypassing traditional multi-tier sourcing structures.
- Restaurants:Foodservice operators prioritize cost-stable liquid formats for fountain beverage systems and recipe consistency across franchise locations.
- Health-focused Brands:Functional food and supplement companies specify glycoside purity thresholds and third-party testing protocols for keto-aligned and diabetic-friendly product lines.
Food manufacturers dominate procurement volume, with health-focused brands expanding most quickly through direct-to-consumer channels.
Form:
Supply concentration in liquid extraction infrastructure versus powder processing capacity shapes regional availability and freight economics for international shipments.
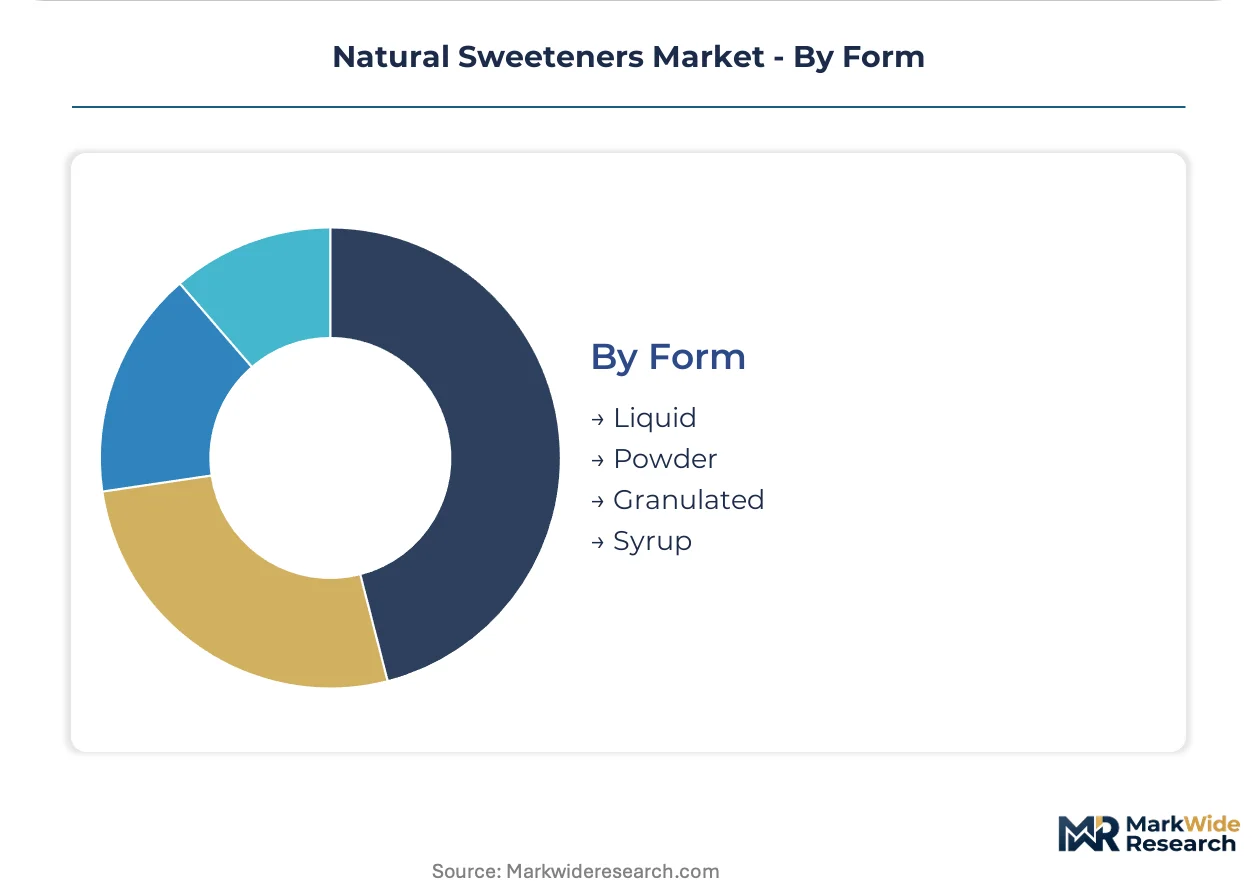
- Liquid:Concentrated extracts with defined degrees Brix enable precise dosing in beverage manufacturing and foodservice fountain systems, with Brazilian processing clusters supplying North American formulators.
- Powder:Spray-dried glycosides with standardized particle size distribution facilitate dry blending in bakery premixes and tabletop sweetener packaging.
- Granulated:Agglomerated formats with bulking agent incorporation mimic sucrose handling properties for consumer baking substitution.
- Syrup:Viscous agave and coconut sap derivatives serve organic-certified beverage lines and artisanal confectionery with minimal processing claims.
Liquid extracts lead industrial procurement volumes, with powder formats expanding most quickly through retail channel distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stevia cultivation originated in Paraguay's Guaraní communities before commercial scaling shifted to Brazilian agro-industrial zones. The market's geographic footprint now spans five demand centers with divergent regulatory frameworks and processing capabilities.
Brazil
Beverage manufacturers in São Paulo and Minas Gerais drive procurement volumes for high-purity Reb M extracts. ANVISA's streamlined food additive approvals accelerate glycoside variant commercialization versus neighboring jurisdictions. Maringá-based processing clusters supply North American formulators through exclusive supply agreements with cultivation cooperatives.
United States
FDA's added sugars labeling mandate compresses reformulation timelines for carbonated soft drink producers. The agency's GRAS notification pathway enables faster steviol glycoside approvals than EFSA's novel food evaluations. California's beverage innovation hubs in Los Angeles and San Francisco pilot monk fruit and stevia blends for clean-label positioning.
Germany
EFSA's ongoing safety assessments for heat-processed glycoside formulations delay dairy application launches. The EU Green Deal's farm-to-fork strategy consolidates procurement standards for plant-derived ingredients across food manufacturers. Cologne and Hamburg anchor European distribution networks for South American stevia extracts.
China
NMPA food additive standards fragment approval pathways for steviol glycoside variants not covered by GB national standards. Domestic enzymatic conversion technology developers in Jiangsu and Zhejiang provinces compete on Reb M yield enhancement. Qingdao and Shanghai processing facilities supply regional beverage manufacturers with liquid extract formats.
India
BIS certification requirements for imported stevia extracts multiply compliance costs for global suppliers targeting food manufacturers. FSSAI's evolving standards for natural sweeteners in traditional dairy products create formulation uncertainty. Gujarat and Maharashtra host emerging extraction facilities serving domestic yogurt and flavored milk producers.
Natural Sweeteners Market Vendor Landscape
Premium-margin players sit above commodity-margin players across glycoside purity tiers and thermal stability specifications. The vendor base clusters around three strategic archetypes: South American agricultural integrators controlling raw material flows, European specialty ingredient formulators targeting dairy applications, and North American biotechnology developers advancing enzymatic conversion platforms. Dominant competitive moves include direct procurement contracts with Brazilian cultivation cooperatives and patent licensing for heat-stable Reb D variants.
Within the agricultural integration tier, Cargill and Tate & Lyle PLC exemplify upstream control strategies through South American supply chain investments. Among biotechnology-enabled specialists, Ingredion Incorporated occupies a position representing enzymatic yield enhancement capabilities. These three anchors illustrate divergent pathways to margin capture: captive raw material security versus conversion technology differentiation versus formulation expertise in temperature-sensitive applications.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| PureCircle |
| Cargill |
| International Flavors & Fragrances Inc. |
| GLG Life Tech Corp |
| Archer Daniels Midland Company |
| Roquette Frères |
| DSM-Firmenich AG |
| Ingredion Incorporated |
| Others |
Supply Flow & Price Mechanics
Beverage manufacturers negotiating exclusive supply agreements with Brazilian cultivation cooperatives anchor pricing power in long-term contract structures rather than spot market dynamics. This procurement concentration compresses margin flexibility for processors dependent on South American leaf flows while locking in volume commitments that insulate buyers from harvest volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates heat-stable Reb D extracts from conventional Reb A grades and bulk agave nectar. Price differentiation rests on glycoside purity thresholds and organic certification status, with FDA-mandated reformulation timelines intensifying cost compression in standard-tier stevia extracts. Food manufacturers demonstrate lowest price sensitivity due to captive supply agreements, while retail channels exhibit highest sensitivity to per-unit sweetener costs.
Supply Chain Analysis
Freight economics from Brazilian processing clusters to North American formulators constitute 12-18% of landed glycoside costs, with container availability fluctuations amplifying working capital requirements. Raw material flows draw from Paraguayan heritage cultivars, Brazilian agro-industrial zones, and emerging Indian extraction facilities. Single-source vulnerability concentrates in Maringá-based processing infrastructure. Distribution runs through direct procurement contracts displacing traditional multi-tier sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Natural Sweeteners Market functions as a stable compounder, with regulatory disclosure mandates across FDA, EFSA, and NMPA jurisdictions generating predictable reformulation demand from processed food manufacturers.
For Market Incumbents: To counter enzymatic conversion technology disruption from biotechnology-enabled competitors, Cargill and Tate & Lyle PLC should deepen backward integration into Brazilian cultivation cooperatives while patent-protecting heat-stable Reb D variant formulations. Certification investment in EU Green Deal farm-to-fork compliance creates switching costs for European dairy processors.
For New Entrants and Emerging Players: Capture white-space opportunity in acid-stable glycoside formulations for Indian yogurt and flavored milk segments where FSSAI standards remain unsettled. Direct-to-health-brand channels offer fastest penetration with third-party testing protocols and keto-aligned positioning bypassing incumbent food manufacturer procurement lock-ins.
For Investors and Strategic Acquirers: Beverage conglomerates with carbonated soft drink portfolios are the most active acquirer in this space, seeking captive stevia supply security. Targets with enzymatic yield enhancement capabilities or exclusive Brazilian cooperative contracts offer 5-10 year structural advantage. Monitor EFSA novel sweetener evaluation timelines as inflection signal for European dairy application revenue recognition.
| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Supply Agreement with Brazilian Cooperatives | Cargill's Maringá cluster investments secure raw material continuity for North American beverage reformulation. |
| Patent Licensing for Heat-Stable Reb D Variants | Tate & Lyle PLC unlocks high-temperature bakery applications previously closed to natural sweeteners. |
| Enzymatic Conversion Technology Scale-Up | Ingredion Incorporated's yield enhancement reduces production costs for high-purity Reb M extracts. |
| EU Green Deal Farm-to-Fork Certification Program | European manufacturers consolidate procurement standards for plant-derived ingredients across member states. |
| Direct Procurement Contract Displacement | Large-scale formulators bypass traditional multi-tier sourcing with Brazilian producer association negotiations. |
Methodological Framework
Multiple input streams — executive interviews with stevia extraction facility managers, procurement leads at North American beverage manufacturers, regulatory affairs specialists at FDA and ANVISA, and distribution channel partners — were reconciled against customs records, SEC 10-K filings from listed ingredient suppliers, and food additive approval databases. Bottom-up volume estimates from application-level consumption data and top-down market sizing from trade flow analysis were triangulated to constrain forecast variance.
Data-stream reconciliation across product type, application, end user, and form dimensions modeled consumption patterns over the projection horizon. CAGRs were derived from segment-level growth rate synthesis with input from enzymatic conversion technology adoption curves and regulatory approval timeline assumptions for EFSA novel sweetener evaluations.
Regulatory evaluation delays, harvest yield volatility in Brazilian cultivation zones, and biotechnology-enabled production cost compression are the dominant revision risks to modeled outputs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
North America Low-Calorie Sweeteners Market
Sweeteners
Sucralose Market
Sweeteners
Africa Stevia Market
Sweeteners
Plant-Derived Sweetener Market
Sweeteners
Asia-Pacific Low-Calorie Sweeteners Market
Sweeteners
Trehalose Market
Sweeteners
North America Starch Sweetener Market
Sweeteners
Europe B2B Brown Sugar Market
Sweeteners
Maltitol Market
Sweeteners
Middle East and Africa Plant-Derived and Synthetic Sugar Market
Sweeteners
Xylitol Market
Sweeteners
Digestion Resistant Maltodextrin Market
Sweeteners
Isomaltooligosaccharide Market
Sweeteners
Short-Chain Fructooligosaccharides (Scfos) Market
Sweeteners
Europe Natural Sweetener Market
Sweeteners
Russia Food Sweetener Market