
 Specialty Sweeteners Market | 2026-2036
Specialty Sweeteners Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Sweeteners Market Analysis
Food formulation chemistry expertise is collapsing across the specialty sweeteners supply chain, forcing manufacturers to compete for scarce talent capable of balancing taste profiles with clean-label requirements. Cargill Incorporated leverages its integrated stevia supply from leaf to extract to sustain cost advantages in high-purity Reb M production. Tate & Lyle PLC anchors European demand through its allulose and fiber-based sweetener platforms, while Ajinomoto Co., Inc. dominates amino-acid-derived sweetener segments with aspartame and advantame specialization.
Specialty sweeteners encompass high-intensity and bulk alternatives to sucrose that deliver sweetness at significantly lower caloric loads or glycemic impact, typically manufactured through extraction, fermentation, or enzymatic conversion processes achieving purity thresholds above 95 percent. Their primary commercial purpose centers on enabling food and beverage producers to meet reformulation targets without sacrificing sensory performance. Stevia-derived products lead volume adoption among natural-positioned offerings, while allulose and monk fruit extracts represent the fastest-expanding margin pools as brands pursue differentiated clean-label positioning. Erythritol occupies a mature cost-competitive niche in bulk applications, particularly within confectionery and bakery end uses where crystallization behavior mimics sucrose.
FDA enforcement of added-sugar disclosure on Nutrition Facts panels directly steers beverage manufacturer procurement toward high-potency alternatives that minimize carbohydrate declarations. EFSA novel food authorizations and WHO sugar reduction guidelines collectively constrain conventional sweetener use across formulated food categories. Stakeholders must monitor evolving GRAS self-affirmation pathways and pending FDA guidance on allulose caloric labeling to anticipate reformulation timelines and ingredient qualification requirements.
Market Dynamics
Formulation chemistry expertise scarcity is compressing product development timelines across the specialty sweeteners supply chain, forcing manufacturers to consolidate R&D partnerships or acquire captive formulation capabilities to maintain reformulation service levels for beverage and confectionery clients.
Growth Catalysts
- FDA Added Sugar Disclosure Mandates:Nutrition Facts panel enforcement compels beverage manufacturers to procure high-potency alternatives that minimize carbohydrate declarations on retail packaging.
- Fermentation-Derived Reb M Production:Bioconversion platforms reduce stevia leaf dependency and stabilize supply chains for natural-positioned high-intensity sweeteners.
- Diabetes Prevalence Patterns:Glycemic management demand from North American and Asia-Pacific consumer bases accelerates adoption of non-nutritive alternatives in functional food formulations.
Market Restraints
- Stevia Leaf Supply Concentration:Cultivation clusters in China and Paraguay expose processors to climate volatility and geopolitical friction in raw material procurement.
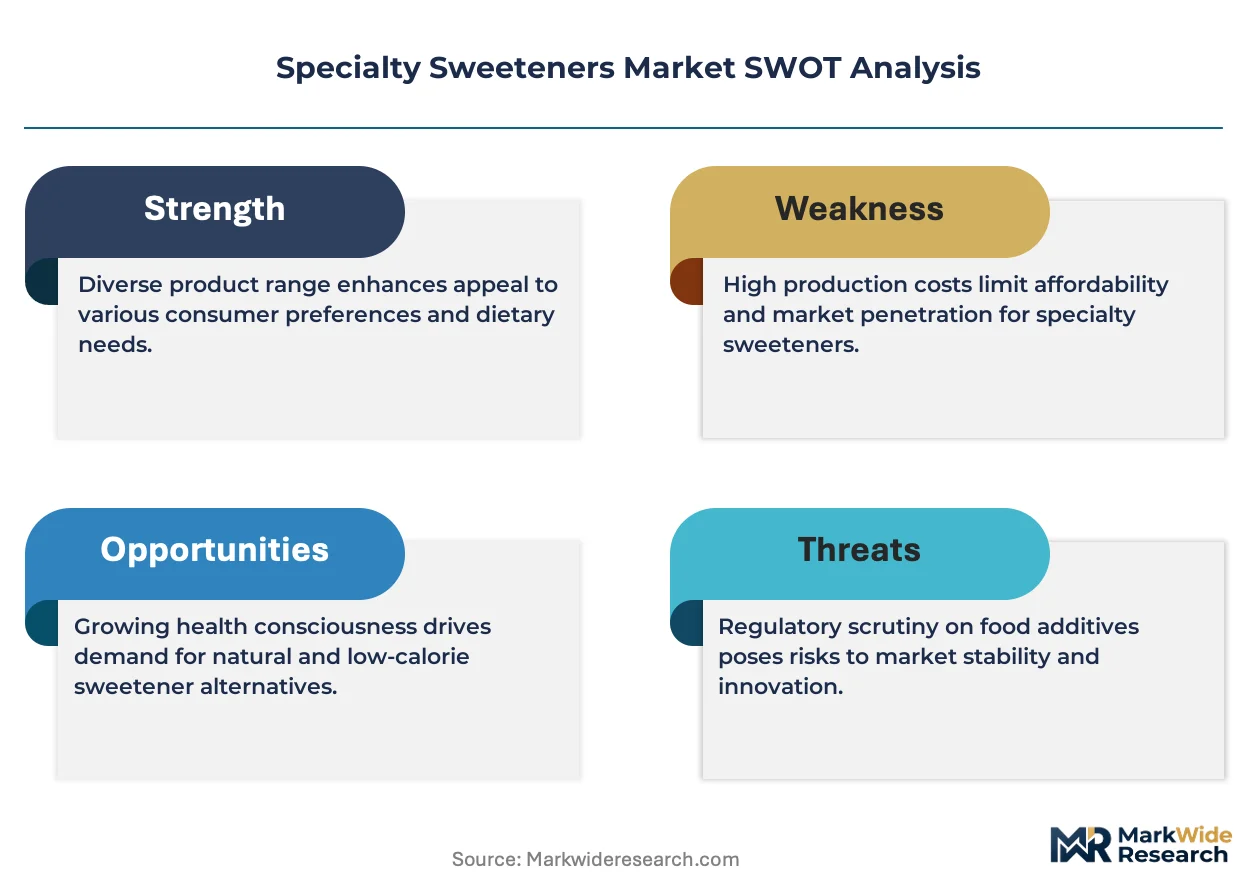
- Allulose GRAS Uncertainty:Pending FDA guidance on caloric labeling creates qualification delays for manufacturers awaiting clarity on carbohydrate declaration requirements.
- Aftertaste Engineering Limitations:Lingering bitterness and cooling effects in high-purity steviol glycosides constrain applications in premium chocolate and dairy categories.
Strategic Opportunities
- Latin American Formulation Services:Underdeveloped regional expertise in clean-label reformulation creates whitespace for technical service providers targeting Mexican and Brazilian beverage manufacturers.
- EFSA Novel Food Pathway Acceleration:Streamlined authorization timelines for fermentation-derived sweeteners enable faster European market entry relative to extraction-based alternatives.
- Direct-to-Consumer Ingredient Channels:E-commerce platforms for home baking and keto-diet segments bypass traditional foodservice distribution markups for bulk erythritol and monk fruit blends.
Industry Challenges
- Flavor Chemist Talent Scarcity:Retirements and academic program contractions shrink the pool of specialists capable of masking off-notes in high-intensity formulations.
- Multi-Jurisdiction Certification Complexity:Divergent GRAS self-affirmation protocols between FDA, EFSA, and Health Canada extend product qualification timelines and legal review costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Sweeteners Market |
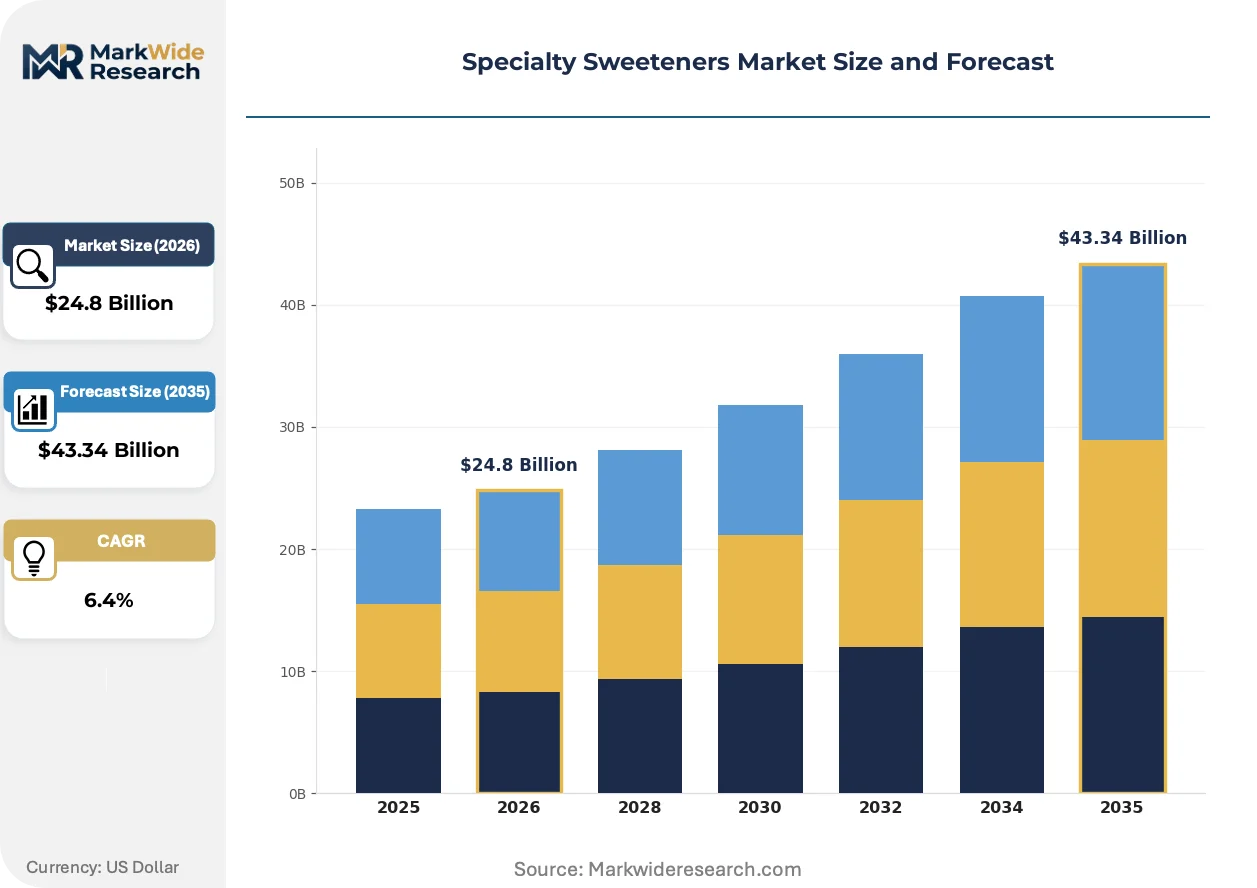
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stevia, Erythritol, Monk Fruit, Acesulfame K End User: Beverage Manufacturers, Bakery Products, Dairy Products, Confectionery Form: Liquid, Granular, Powder, Crystal Application: Food Products, Nutritional Supplements, Pharmaceuticals, Cosmetics |
| Companies Covered | Cargill Incorporated, Tate & Lyle PLC, Archer Daniels Midland Company, Ingredion Incorporated, DuPont, PureCircle Limited, Roquette Frères, Monk Fruit Corp., Ajinomoto Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Sweeteners Market Emerging Trajectories
Biomanufacturing platforms and regulatory labeling evolution are actively restructuring how sweetness is produced, qualified, and positioned in packaged goods. These shifts compress legacy extraction economics while opening novel application categories.
Precision fermentation for steviol glycoside production is fragmenting the traditional agricultural supply chain. Biotech-enabled manufacturers now synthesize Reb M and Reb D without leaf cultivation, reducing land-use dependencies and harvest volatility. Beverage giants in North America and Western Europe are qualifying these bioidentical molecules at accelerated pace, eroding cost premiums previously commanded by vertically integrated agricultural processors.
EFSA's evolving novel food frameworks and WHO sugar reduction guidelines are tightening permissible health claims around sweetness. European manufacturers face compressed formulation windows as EFSA evaluates cumulative exposure data for high-intensity alternatives. Confectionery and dairy sectors in Germany and France are pre-emptively reformulating to avoid retrospective labeling adjustments.
Clean-label procurement patterns now prioritize supply chain transparency over single-attribute performance. Retail buyers in the United States and United Kingdom are auditing sweetener provenance through blockchain-enabled traceability platforms. This behavioral shift disadvantages opaque Asian leaf traders while rewarding vertically integrated producers with certified sustainable cultivation programs.
Specialty Sweeteners Market Segmentation
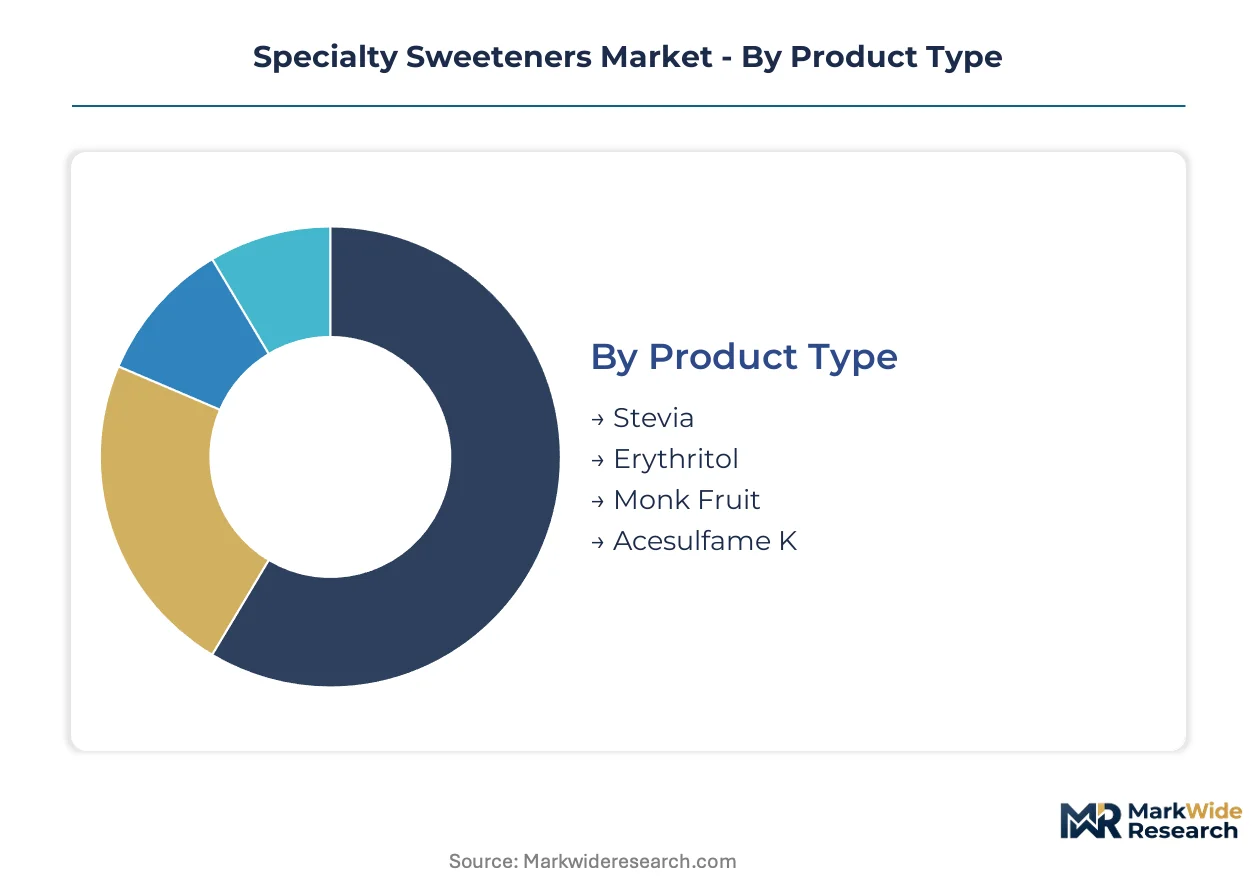
Specialty sweeteners fragment across four intersecting dimensions that determine procurement economics and formulation service requirements. Product chemistry dictates stability profiles and regulatory pathways, while end-use concentration shapes volume contracting patterns and technical support intensity.
Product Type:
Channel mix varies sharply by molecular source—stevia and monk fruit dominate natural-positioned retail SKUs, while acesulfame K concentrates in fountain beverage and foodservice bulk channels where cost minimization overrides clean-label positioning.
- Stevia:High-purity steviol glycosides, particularly Reb M and Reb D, deliver sweetness intensity 200-350x sucrose with zero glycemic impact. Beverage manufacturers in the United States have secured broad retail acceptance for stevia-sweetened carbonated and still drinks, though lingering bitterness constrains premium chocolate applications.
- Erythritol:A four-carbon sugar alcohol manufactured through corn-derived glucose fermentation, erythritol provides bulk sweetness at 0.2 kcal/g with crystallization behavior mimicking sucrose. Bakery and confectionery end uses in North America absorb the majority of volume given its thermal stability and cooling effect in hard candies.
- Monk Fruit:Mogroside V extracts from Siraitia grosvenorii fruit deliver high-intensity sweetness with clean taste profiles. Keto-diet and clean-label segments in direct-to-consumer channels are expanding most quickly as brands pursue differentiated positioning beyond stevia.
- Acesulfame K:A synthetic high-intensity sweetener stable across pH and temperature ranges. Blended applications with aspartame or sucralose dominate mass-market beverage and tabletop sweetener formulations where cost thresholds override natural positioning.
By volume, erythritol leads given its bulk applications across bakery and confectionery. By growth pace, monk fruit extracts are climbing the fastest as brands diversify beyond stevia-saturated positioning.
End User:
Cost tier stratification separates premium formulation services for beverage multinationals from commodity supply relationships serving regional bakery and confectionery processors.
- Beverage Manufacturers:Carbonated, still, and functional drink producers command the largest procurement volumes and most intensive technical collaboration. FDA added-sugar disclosure mandates are compressing reformulation timelines for legacy portfolios.
- Bakery Products:Bread, cake, and pastry applications require bulk sweeteners with Maillard-reactive properties and moisture retention. Erythritol and allulose blends are gaining formulation share as sugar reduction targets tighten.
- Dairy Products:Yogurt, ice cream, and flavored milk applications prioritize clean taste and freeze-thaw stability. Aftertaste engineering limitations in high-purity stevia constrain penetration in premium chocolate dairy desserts.
- Confectionery:Hard candy, chewing gum, and chocolate segments demand precise crystallization control and thermal stability. Sugar alcohols dominate functional sugar-free positioning while high-intensity alternatives enable extreme calorie reduction.
By revenue concentration, beverage manufacturers anchor procurement volumes. By margin expansion, dairy applications show steepest trajectory as clean-label premiumization accelerates.
Form:
Application requirements and handling economics determine format selection—liquid concentrates minimize weighing error in automated beverage lines, while granular and crystalline forms serve tabletop and small-batch foodservice needs.
- Liquid:Concentrated aqueous solutions enable precise dosing in high-speed beverage manufacturing. Fountain and foodservice channels favor liquid formats for dispensing consistency and reduced dust exposure.
- Granular:Free-flowing particles approximate sucrose handling characteristics for direct substitution in bakery and home baking applications. Flowability additives determine performance in humid climates.
- Powder:Fine particle sizes accelerate dissolution in instant beverage and nutritional supplement applications. Agglomeration technologies address caking challenges in high-purity stevia and monk fruit extracts.
- Crystal:Large, uniform crystals serve visual and textural roles in premium confectionery and tabletop sweetener positioning. Erythritol crystallization processes are optimized for clarity and hardness matching sucrose.
By manufacturing throughput, liquid concentrates dominate commercial-scale procurement. By channel expansion, powder formats are expanding most quickly through e-commerce direct-to-consumer routes.
Application:
Regulatory qualification burden and performance specifications create four distinct demand clusters with divergent margin structures and technical service intensity.
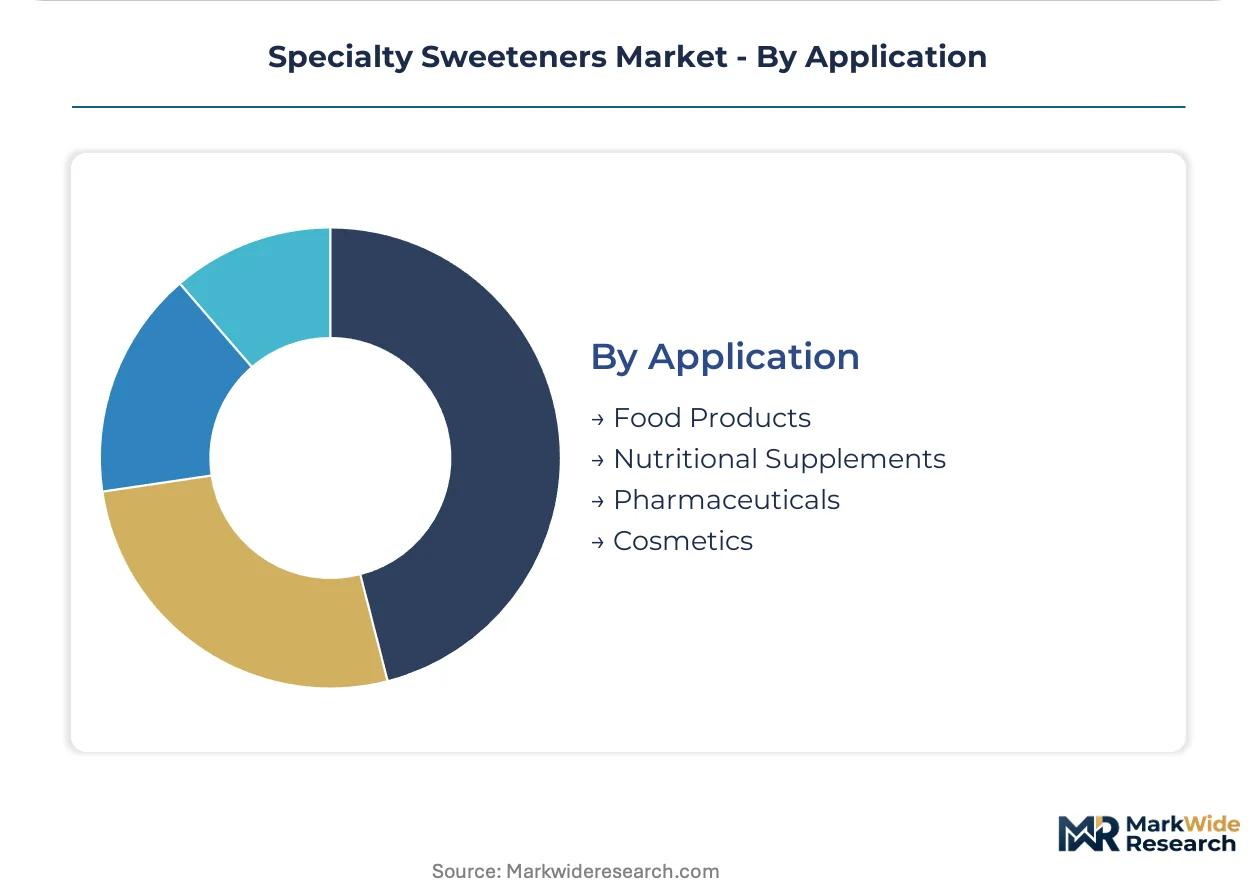
- Food Products:Processed foods, beverages, and prepared meals constitute the core volume base. GRAS self-affirmation pathways and EFSA novel food authorizations govern ingredient qualification timelines.
- Nutritional Supplements:Protein powders, meal replacements, and sports nutrition products prioritize low-glycemic impact and clean-label positioning. Keto and diabetic consumer segments drive premium pricing for monk fruit and allulose.
- Pharmaceuticals:Excipient applications in chewable tablets, syrups, and pediatric formulations require pharmacopeial compliance and documented purity thresholds. USP and EP certification adds qualification cost and timeline.
- Cosmetics:Oral care and personal care applications leverage sweetness for taste masking and sensory enhancement. Regulatory burden remains lighter than ingestible categories, though clean-label positioning is migrating from food into beauty.
By absolute volume, food products anchor demand. By margin expansion, nutritional supplements are gaining share fastest as functional positioning commands price premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns for specialty sweeteners diverge sharply across geographies. The United States favors high-potency natural extracts for beverage reformulation, while European buyers prioritize fermentation-derived molecules under stricter novel food frameworks. Asian markets blend traditional botanical knowledge with industrial-scale biomanufacturing.
United States
Beverage manufacturers in Atlanta and Chicago drive procurement volumes for stevia-derived Reb M and allulose blends. FDA enforcement of added-sugar disclosure on Nutrition Facts panels compels rapid portfolio reformulation. California-based clean-label brands are pioneering monk fruit adoption in direct-to-consumer nutritional supplements.
Germany
Confectionery producers in Cologne and Munich anchor European demand for erythritol and isomalt in sugar-free chocolate applications. EFSA novel food authorizations govern qualification timelines for fermentation-derived sweeteners. Bavarian biotech clusters are scaling precision fermentation capacity for steviol glycoside production.
China
Stevia leaf cultivation concentrates in Guangxi and Sichuan provinces, supplying global extract processors. SAMR oversight of food additive standards shapes domestic formulation practices. Yangtze River Delta manufacturers are integrating downstream into high-purity Reb M purification for export markets.
Brazil
São Paulo-based beverage bottlers represent Latin America's largest addressable demand pool for high-intensity sweeteners. ANVISA regulatory pathways for novel food ingredients create qualification bottlenecks versus GRAS-equivalent timelines. Regional formulators in Minas Gerais are developing localized stevia varieties adapted to domestic cultivation.
Japan
Tokyo and Osaka food conglomerates maintain sophisticated formulation capabilities for amino-acid-derived sweeteners. PMDA and METI coordination on food additive standards preserves strict purity thresholds. Ajinomoto's Chubu-region production complex anchors regional supply for aspartame and advantame segments.
Specialty Sweeteners Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in specialty sweeteners supply. Agricultural processors with captive cultivation and extraction assets compete against biotech-enabled manufacturers leveraging fermentation platforms. Strategic archetypes include vertically integrated agricultural processors, precision fermentation specialists, and regional formulation service providers. Capacity expansion in biomanufacturing and backward integration into stevia leaf cultivation represent the dominant competitive moves reshaping supply economics.
Within the integrated agricultural processor tier, Cargill Incorporated and Tate & Lyle PLC exemplify scale-driven positioning through upstream control over raw material supply chains. Ajinomoto Co., Inc. occupies a distinct position as a fermentation and amino-acid chemistry specialist with deep expertise in synthetic high-intensity molecules. These three anchors span the primary competitive vectors—natural-extraction scale, regional regulatory navigation, and biotechnology-enabled production—defining how formulation chemistry capabilities are distributed across the supplier base.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Tate & Lyle PLC |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| DuPont |
| PureCircle Limited |
| Roquette Frères |
| Monk Fruit Corp. |
| Ajinomoto Co., Inc. |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day leaf-to-extract lead times for steviol glycosides concentrate procurement power among vertically integrated agricultural processors in China and Paraguay, compressing margins for formulation-dependent buyers while elevating price premiums for biomanufactured Reb M alternatives. This temporal structure forces beverage manufacturers to choose between volatile spot markets for botanical extracts and contracted offtake from fermentation platforms with longer qualification cycles but greater cost predictability.
Pricing Analysis
Long-term offtake agreements dominate procurement relationships between multinational beverage manufacturers and stevia extract suppliers, insulating buyers from spot volatility in Chinese leaf markets while locking in volume commitments that disadvantage smaller confectionery processors forced into premium spot pricing. Price differentiation separates fermentation-derived high-purity Reb M from conventional leaf-extracted steviol glycosides, with the former commanding 15-25 percent premiums justified by supply stability and clean-label positioning. Pricing pressure intensifies in bulk erythritol segments as Chinese fermentation capacity expansion outpaces North American and European demand growth. Beverage multinationals exhibit lowest price sensitivity given reformulation timelines mandated by FDA disclosure rules, while regional bakery processors face acute margin compression from input cost volatility.
Supply Chain Analysis
Strategic stockpiling of stevia leaf inventories characterizes processor behavior in Guangxi and Sichuan provinces, where harvest timing and climate variability necessitate 4-6 month coverage buffers that tie up working capital and amplify price swings during poor growing seasons. Raw material supply draws from concentrated cultivation zones in China and Paraguay for stevia, corn-derived glucose fermentation feedstocks in the United States and Brazil, and Siraitia grosvenorii orchards in Guangxi for monk fruit. Single-source vulnerability concentrates in Chinese leaf processing infrastructure, where 70 percent of global steviol glycoside extraction capacity resides. Distribution runs through three-tier structures: bulk ingredient traders supply regional formulators, direct contracts link integrated processors to multinational beverage manufacturers, and e-commerce platforms serve direct-to-consumer nutritional supplement brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation for steviol glycoside production represents a high-growth disruption reshaping competitive economics, with FDA guidance on allulose caloric labeling poised to trigger accelerated portfolio reformulation across beverage and dairy categories.
For Market Incumbents: Fortify upstream control over biomanufacturing capacity through captive fermentation facility investments or exclusive tolling arrangements with precision fermentation specialists, while accelerating EFSA novel food dossier submissions to preempt European market entry barriers. The threat of biotech-enabled Reb M cost parity eroding agricultural extraction premiums demands immediate backward integration into fermentation platforms or strategic abandonment of commodity leaf-extraction tiers. For New Entrants and Emerging Players: Technical service gaps in Latin American clean-label reformulation create immediate whitespace for specialized formulation laboratories targeting Mexican and Brazilian beverage manufacturers underserved by incumbent technical support networks. Direct-to-consumer monk fruit and allulose blends through e-commerce channels offer the most penetrable entry vector, bypassing entrenched foodservice distribution relationships and capturing premium pricing from keto-diet and diabetic consumer segments. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food ingredient conglomerates with underperforming or non-core sweetener divisions lacking fermentation capabilities or regional formulation service networks. Long-term viability across the projection horizon favors precision fermentation specialists with validated bioidentical molecule production and established GRAS self-affirmation pathways. Watch FDA allulose caloric guidance publication as the critical inflection signal triggering accelerated M&A activity in biomanufacturing assets.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Biomanufactured Reb M production reduces land-use dependencies and harvest volatility for beverage clients. |
| EFSA Novel Food Dossier Investment | Streamlined European authorization timelines accelerate market entry versus extraction-based alternatives. |
| Backward Integration into Leaf Cultivation | Captive stevia supply from Guangxi and Paraguay secures cost advantages in high-purity extraction. |
| Technical Service Partnership | Localized formulation expertise in São Paulo and Mexico City addresses Latin American whitespace demand. |
| Blockchain Traceability Implementation | Retail buyers in the United States and United Kingdom audit provenance through transparent supply chain platforms. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with beverage formulation chemists, stevia leaf procurement managers, fermentation platform engineers, and regulatory affairs specialists at FDA and EFSA, cross-validated against secondary sources including customs trade databases, SEC 10-K filings of publicly traded ingredient suppliers, SAMR food additive standard notifications, and ANVISA novel food regulatory pathways. Bottom-up volume modeling triangulated against top-down market sizing from industry association reports produced triangulated demand estimates.
Across the analysis window, the forecasting framework modeled volume and value trajectories through segmented projections across product chemistry types, end-use applications, geographic consumption clusters, and regulatory qualification pathways. CAGRs derived from historical volume elasticities against sugar reduction policy intensity and diabetes prevalence patterns, with fermentation capacity expansion curves and EFSA authorization timelines as industry-specific demand shapers.
Forecasts assume regulatory continuity in FDA GRAS self-affirmation protocols and EFSA novel food frameworks; material policy shifts would require re-modeling of reformulation timelines and ingredient qualification costs. Revision becomes warranted when FDA allulose caloric guidance or WHO sugar reduction threshold recommendations cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Global Artificial Sweeteners Market
Sweeteners
Compressible Sugar Market
Sweeteners
Fermented Sweeteners Market
Sweeteners
Mannitol Market
Sweeteners
Resistant Maltodextrin Market
Sweeteners
Europe Natural Sweetener Market
Sweeteners
North America Plant-Derived and Synthetic Sugar Market
Sweeteners
Europe Plant-Derived and Synthetic Sugar Market
Sweeteners
Floral Nectar Market
Sweeteners
Europe Stevia Market
Sweeteners
Canada Food Sweetener Market
Sweeteners
Turbinado Sugar Market
Sweeteners
Vietnam Food Sweetener Market
Sweeteners
Stevia Market
Sweeteners
Low-Calorie Sweetener Market
Sweeteners
China Saccharin Market