
 Invert Sugar Market | 2026-2036
Invert Sugar Market Size, Share, and Industry Trends Forecast 2026-2036
Invert Sugar Market Outlook
EU F-Gas Regulation is realigning capital requirements for European sucrose hydrolysis operations by mandating lower-global-warming-potential refrigerants in vacuum evaporation stages. Südzucker AG anchors its position through captive beet sugar supply chains that feed directly into invert syrup production at German facilities. Cargill, Incorporated leverages ocean freight networks to move liquid invert sugar from Brazilian mills into North American beverage plants. Nordzucker AG competes on crystalline sucrose purity grades that determine final invert sugar color specifications for confectionery buyers.
Invert sugar consists of equimolar mixtures of glucose and fructose produced through acid or enzymatic hydrolysis of sucrose, typically yielding a reducing sugar content exceeding 95 percent on a dry basis and moisture levels between 25 and 30 percent for liquid grades. The hydrolyzed disaccharide functions primarily as a humectant and browning accelerator in baked goods, with its hygroscopic properties extending shelf life in soft cookies and fondant applications. Liquid invert sugar dominates volume flows into beverage industry tanker deliveries, while dry invert sugar commands premium positioning in artisan confectionery segments where powder handling and extended ambient stability matter. High fructose syrup variants are displacing standard invert grades in some dairy applications where enhanced sweetness intensity reduces formulation costs.
FDA food additive regulations under 21 CFR 184.1854 govern invert sugar safety for direct human consumption in the United States, while EFSA evaluates novel enzymatic hydrolysis processes under updated food enzyme guidance. BIS certification requirements in India mandate labeling accuracy for reducing sugar claims on commercial invert syrup shipments. Stakeholders must monitor evolving carbon accounting rules for beet-versus-cane sucrose feedstocks, as scope-three emissions disclosures reshape supplier qualification criteria across European and North American procurement desks.
Market Dynamics
The EU F-Gas Regulation is compressing capital cycles for European sucrose hydrolysis facilities by mandating lower-global-warming-potential refrigerants in vacuum evaporation stages, while Brazilian ethanol-to-sugar flex mills redirect sucrose streams toward specialty sweetener production.
Growth Catalysts
- EU F-Gas Regulation:Mandates for lower-global-warming-potential refrigerants in vacuum evaporation stages are accelerating facility retrofits and creating demand for process engineering services across German and French processing corridors.
- Beverage formulation demand:Latin American soft drink manufacturers are expanding tanker procurement of liquid invert sugar for carbonated and still beverage lines, concentrating volume flows through São Paulo state production clusters.
- Enzymatic hydrolysis:Novel enzyme processes evaluated under EFSA food enzyme guidance are reducing acid-catalyzed conversion times and improving color specifications for confectionery-grade output.
Market Restraints
- Beet sugar input volatility:European beet harvest fluctuations and energy-intensive processing costs constrain margin stability for German and Polish hydrolysis operations.
- High fructose syrup substitution:Enhanced sweetness intensity variants are displacing standard invert grades in dairy applications, compressing addressable volume in yogurt and ice cream segments.
- REACH compliance burden:Chemical safety documentation requirements for acid catalysts used in hydrolysis create regulatory friction for smaller European processors.
Strategic Opportunities
- Indian BIS certification gap:Domestic labeling accuracy mandates for reducing sugar claims create first-mover positioning for exporters establishing certified syrup supply chains to Mumbai and Delhi food manufacturers.
- Carbon accounting differentiation:Scope-three emissions disclosures for beet-versus-cane sucrose feedstocks enable supplier qualification advantages for Brazilian cane-based producers serving European procurement desks.
- Artisan confectionery dry grades:Powder handling and extended ambient stability requirements in premium chocolate and fondant segments support premium positioning for crystalline invert sugar variants.
Industry Challenges
- Process cooling retrofit timelines:EU F-Gas Regulation compliance deadlines compress engineering schedules for vacuum evaporation stage upgrades at legacy beet sugar facilities.
- Enzyme supply security:Novel food enzyme approval pathways under EFSA guidance create uncertainty for processors transitioning from acid-catalyzed to biocatalytic hydrolysis systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Invert Sugar Market |
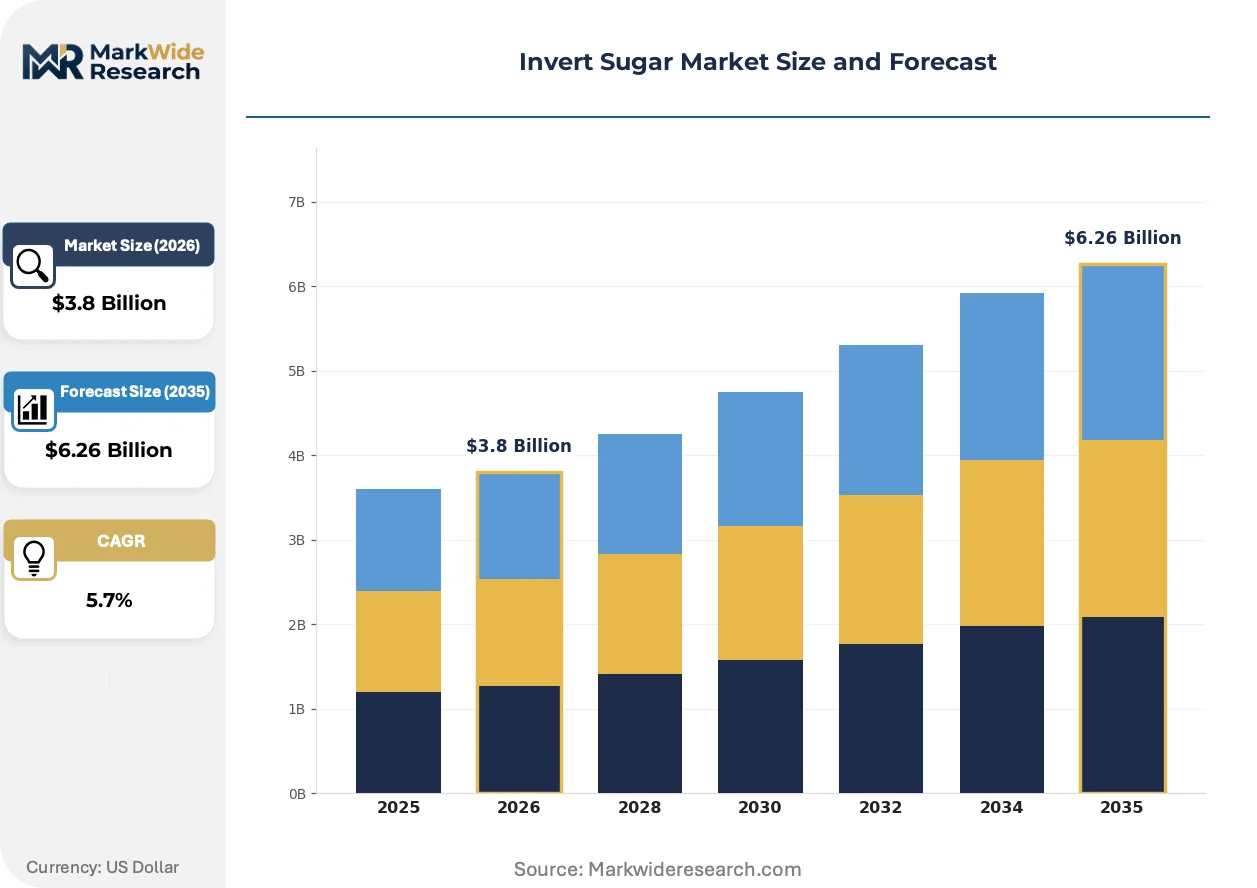
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Invert Sugar, Dry Invert Sugar, High Fructose Syrup, Others End User: Beverage Industry, Bakery Products, Confectionery, Dairy Packaging Type: Bottles, Bags, Drums, Tankers Purpose: Sweetening Agent, Humectant, Flavoring, Preservative |
| Companies Covered | Archer Daniels Midland Company, Cargill, Incorporated, Nordzucker AG, Südzucker AG, Tereos, Ragus Sugars Manufacturing Limited, International Molasses Corporation, AP Multi Products Pvt. Ltd, Galam, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Invert Sugar Market Strategic Shifts
Process intensification and regulatory carbon accounting are reshaping competitive positioning across sucrose hydrolysis operations, with technology adoption pacing diverging between enzymatic conversion advocates and legacy acid-catalyzed systems.
Continuous enzymatic hydrolysis systems are integrating immobilized enzyme reactor designs that reduce conversion residence times from hours to minutes. North American beverage concentrate manufacturers are piloting these systems at mid-scale facilities. This integration is compressing batch cycle economics and enabling smaller-footprint production layouts near urban distribution hubs.
REACH authorization requirements for sulfuric acid catalysts are forcing acid-catalyzed processors toward enzyme substitution or closed-loop acid recovery investments. German beet sugar hydrolysis facilities face the steepest compliance timelines. Confectionery-grade producers with stringent color specifications are responding by qualifying enzyme-derived syrup streams for premium fondant applications.
Bulk tanker procurement contracts are consolidating beverage industry demand around multi-year supply agreements with fixed-index pricing. Soft drink bottlers in São Paulo state are displacing spot market purchases with direct mill relationships. This pattern is most visible in Brazil's flex mill corridor, where ethanol-to-sugar arbitrage decisions now incorporate long-term invert sugar contract premiums.
Invert Sugar Market Segmentation
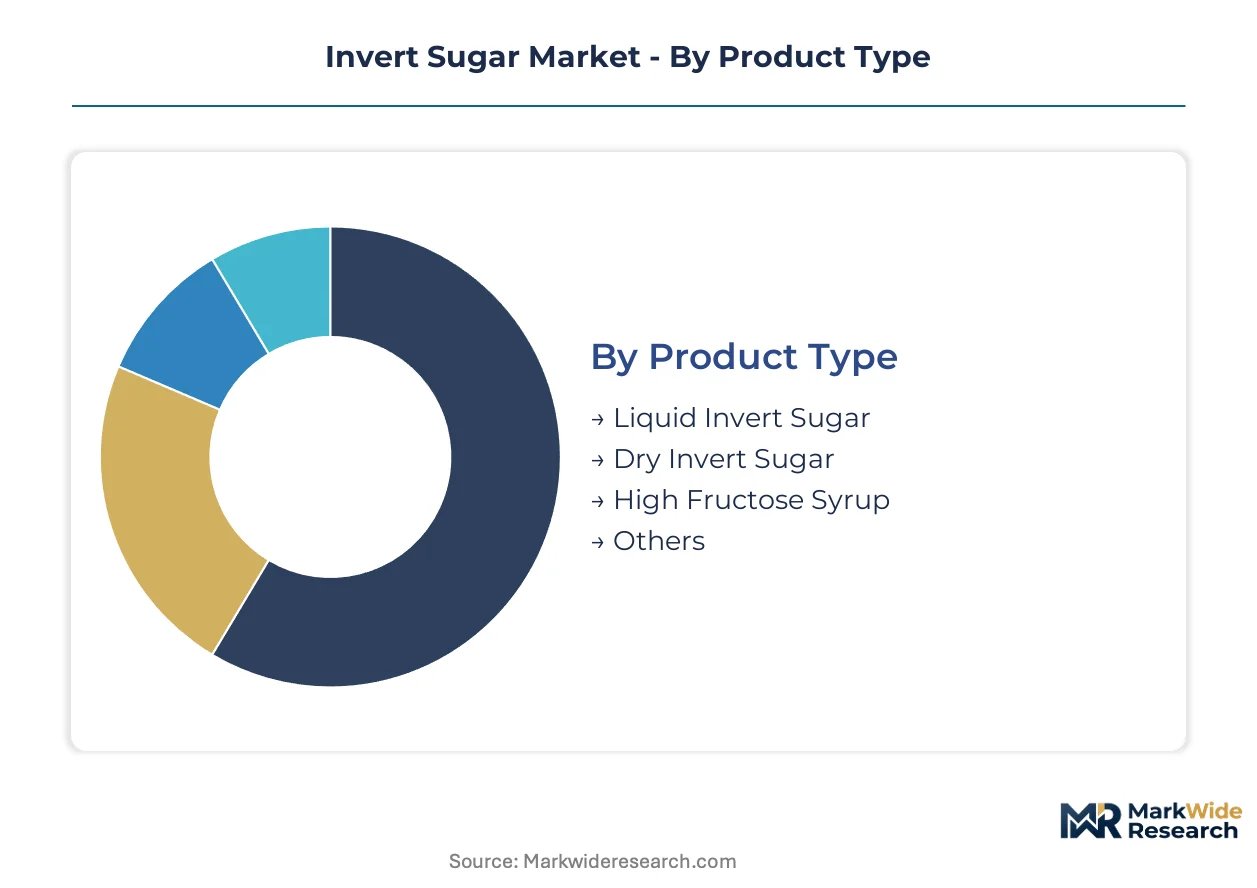
Invert sugar specifications diverge sharply across applications, with moisture content, reducing sugar purity, and packaging format determining procurement patterns. Manufacturers configure production lines around these segment boundaries, as beverage tanker deliveries bear little resemblance to artisan confectionery powder handling.
Product Type:
Supply concentration in Brazilian flex mills favors liquid grades, while European beet processors dominate crystalline and dry variants.
- Liquid Invert Sugar:Contains 25-30 percent moisture with reducing sugar content exceeding 95 percent on a dry basis. São Paulo state flex mills redirect sucrose streams toward liquid grades for Latin American beverage tanker procurement, capitalizing on ethanol-to-sugar arbitrage flexibility.
- Dry Invert Sugar:Spray-dried or crystallized variants with extended ambient stability and powder handling characteristics. German and Polish beet sugar facilities supply confectionery manufacturers requiring precise color specifications for fondant and premium chocolate applications.
- High Fructose Syrup:Enhanced fructose ratio variants displacing standard invert grades in dairy yogurt and ice cream formulations where sweetness intensity reduces formulation costs.
- Others:Specialty hydrolyzed syrups for pharmaceutical and industrial fermentation applications with custom dextrose equivalent specifications.
Today's leader: Liquid Invert Sugar. Tomorrow's challenger: High Fructose Syrup.
End User:
Cost tier differentiation separates commodity beverage procurement from premium confectionery specifications.
- Beverage Industry:Carbonated and still soft drink manufacturers in Brazil and Mexico drive tanker-scale procurement. Multi-year supply agreements with fixed-index pricing displace spot market purchases across São Paulo production clusters.
- Bakery Products:Humectant functionality extends shelf life in soft cookies and accelerates Maillard browning. Industrial bakeries favor liquid grades for automated dosing systems.
- Confectionery:Artisan chocolate and fondant producers demand crystalline invert sugar with stringent color grades. Powder handling requirements support premium positioning against liquid alternatives.
- Dairy:Yogurt and ice cream formulators increasingly specify high fructose syrup variants for sweetness intensity, compressing standard invert sugar volume in this segment.
Volume concentrates in Beverage Industry. Margin concentrates in Confectionery.
Packaging Type:
Customer type and logistics infrastructure dictate format selection across procurement tiers.
- Tankers:Bulk liquid delivery for beverage industry manufacturing plants with dedicated unloading infrastructure. São Paulo flex mills anchor supply for Latin American bottling operations.
- Drums:Intermediate volume for mid-scale bakeries and confectionery manufacturers without tanker receiving capability. German hydrolysis facilities export drum quantities across European Union corridors.
- Bottles:Retail and foodservice channels for small-batch artisan producers. Limited volume but premium pricing.
- Bags:Dry invert sugar packaging for powder-handling confectionery operations and industrial bakeries with pneumatic conveying systems.
Tankers capture procurement volume. Drums capture procurement flexibility.
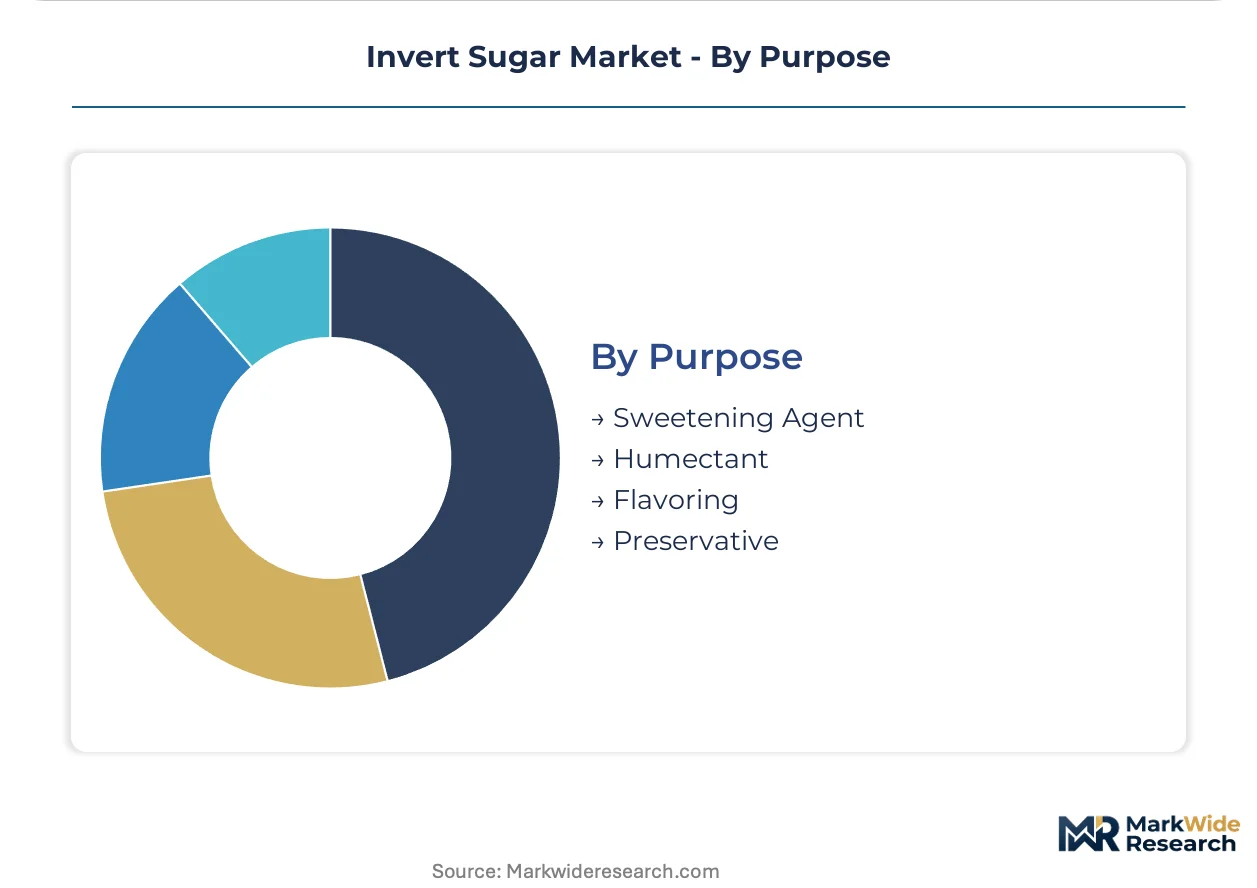
Purpose:
Application maturity separates established humectant functionality from emerging preservative claims.
- Humectant:Hygroscopic properties retain moisture in baked goods and extend shelf life. This functional driver dominates bakery segment procurement specifications.
- Sweetening Agent:Primary caloric contribution across beverages, dairy, and confectionery. Standard invert sugar and high fructose variants compete on sweetness intensity per formulation cost.
- Flavoring:Caramelization and Maillard reaction enhancement in baked goods and confectionery. Color development specifications vary by end-use.
- Preservative:Water activity reduction through hygroscopic binding. Emerging functional claim requiring BIS certification accuracy in Indian commercial shipments.
Humectant functionality anchors current demand. Preservative positioning offers expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The invert sugar industry traces its commercial origins to nineteenth-century European beet sugar refineries, where acid hydrolysis first transformed sucrose into glucose-fructose mixtures for confectionery applications. German chemical engineers standardized vacuum evaporation techniques that spread across continental processing corridors. Contemporary production geography reflects this lineage while incorporating Brazilian cane-based flex mill innovations.
Germany
Beet sugar processors dominate European invert syrup output through integrated hydrolysis operations. The EU F-Gas Regulation mandates refrigerant retrofits in Lower Saxony vacuum evaporation facilities by 2027. Captive beet supply chains in the Magdeburg-Anhalt corridor feed directly into liquid and crystalline grade production.
Brazil
São Paulo state flex mills redirect sucrose streams toward specialty sweetener production when ethanol margins soften. ANVISA food additive standards govern liquid invert sugar purity claims for domestic beverage manufacturers. Santos port infrastructure anchors tanker-scale exports to North American bottling plants.
United States
FDA regulations under 21 CFR 184.1854 establish safety parameters for invert sugar in direct human consumption. Beverage concentrate manufacturers in the Midwest pilot continuous enzymatic hydrolysis systems. Chicago-area distribution hubs receive bulk liquid shipments via rail from coastal import terminals.
India
BIS certification requirements mandate labeling accuracy for reducing sugar claims on commercial syrup shipments. Maharashtra and Uttar Pradesh cane processors expand enzymatic conversion capacity for domestic bakery and confectionery demand. Mumbai food manufacturers qualify certified suppliers for fondant and chocolate applications.
France
EFSA food enzyme guidance shapes approval pathways for novel biocatalytic hydrolysis investments. Tereos operates integrated beet-to-syrup processing in the Picardy region. Normandy coastal refineries export drum quantities across European Union corridors under REACH compliance frameworks.
Invert Sugar Market Competitive Environment
The competitive structure tilts toward integrated agribusiness conglomerates with captive sucrose feedstock access. Processing specialists and regional syrup blenders occupy mid-tier positions between beet sugar refiners and beverage procurement desks. Three archetypes dominate: integrated sugar-to-syrup operators, independent hydrolysis processors, and import-dependent distribution specialists. Capacity expansion and strategic partnerships represent the dominant competitive moves, with flex mill operators leveraging ethanol-to-sugar arbitrage to secure long-term beverage contracts.
Within the integrated agribusiness tier, Cargill, Incorporated and Archer Daniels Midland Company exemplify global supply chain orchestration, leveraging ocean freight networks and inland distribution infrastructure to serve multinational beverage formulations. Südzucker AG anchors European production through captive beet sugar supply chains feeding German hydrolysis facilities. These three entities represent distinct geographic and feedstock specializations—North American grain and oilseed processing heritage, Brazilian cane-based flex milling, and continental European beet sugar integration—without direct product overlap in procurement specifications.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| Nordzucker AG |
| Südzucker AG |
| Tereos |
| Ragus Sugars Manufacturing Limited |
| International Molasses Corporation |
| AP Multi Products Pvt. Ltd |
| Galam |
| Others |
Value Chain & Pricing Dynamics
ICE sugar futures contract movements cascade through Brazilian flex mill procurement decisions into three-tier pricing structures across premium confectionery crystalline grades, standard liquid tanker deliveries, and economy bulk drum formats for mid-scale bakery operations.
Pricing Analysis
Contract-based long-term offtake dominates beverage industry procurement, with multi-year agreements locking fixed-index pricing against raw sugar benchmarks. Price differentiation separates certified organic grades commanding certification premiums from conventional liquid tanker volumes and unbranded drum quantities for smaller bakeries. Cost compression in standard liquid grades intensifies as high fructose syrup substitution accelerates in dairy applications. Beverage bottlers exhibit lowest price sensitivity due to formulation lock-in, while artisan confectionery buyers absorb premium crystalline pricing for color specification guarantees.
Supply Chain Analysis
Single-source vulnerability sits with São Paulo state flex mills supplying Latin American beverage tanker volumes. Raw material flows draw from Brazilian cane crush, German beet harvests, and Indian Uttar Pradesh cane belts. Sucrose feedstock dependency, immobilized enzyme supply, and ocean freight container availability constitute critical input chains. Tariff exposure threatens Brazilian export competitiveness into North American ports. Distribution runs through Santos port infrastructure for transoceanic liquid bulk shipments and Magdeburg-Anhalt rail corridors for European drum distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The invert sugar market reads as a late-cycle quality story as artisan confectionery demand shifts toward certified low-color crystalline grades with extended ambient stability specifications.
For Market Incumbents: Deploy captive beet supply chain control to lock sucrose feedstock costs against Brazilian cane price volatility. Expand enzymatic hydrolysis capacity at Lower Saxony facilities ahead of EU F-Gas Regulation retrofit deadlines. Acid-catalyzed legacy infrastructure faces stranded asset risk from REACH authorization timelines for sulfuric acid catalysts.
For New Entrants and Emerging Players: Begin with BIS certification positioning for Indian domestic syrup supply chains, where labeling accuracy mandates create qualification barriers for unverified imports. Maharashtra cane processors offer penetrable white-space for enzymatic conversion capacity serving Mumbai fondant manufacturers. Qualify enzyme-derived streams for premium chocolate applications as acid-catalyzed color specifications tighten.
For Investors and Strategic Acquirers: Asymmetric upside sits with integrated flex mill operators commanding ethanol-to-sugar arbitrage flexibility and long-term beverage contract anchoring. Five-to-ten year viability favors Brazilian cane-based producers with scope-three emissions advantages for European procurement qualification. Monitor EFSA novel food enzyme approval velocity as inflection signal for enzymatic hydrolysis capital deployment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Hydrolysis Capacity Expansion | Reduces conversion residence times from hours to minutes at North American pilot facilities. |
| EU F-Gas Refrigerant Retrofit | Accelerates facility engineering schedules for Lower Saxony vacuum evaporation stages. |
| Long-term Tanker Supply Agreement | Displaces São Paulo spot market purchases with direct flex mill relationships. |
| BIS Certification Investment | Creates first-mover positioning for Mumbai and Delhi food manufacturer supply chains. |
| Carbon Accounting Differentiation | Enables Brazilian cane-based supplier qualification advantages across European procurement desks. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement covered beverage formulation chemists at Latin American bottling operations, beet sugar procurement leads at German processing facilities, confectionery quality directors at artisan chocolate manufacturers, and flex mill operations managers in São Paulo state. Secondary validation drew from ANVISA food additive filings, EU F-Gas Regulation implementation schedules, BIS certification databases, and customs trade records for liquid bulk syrup movements. Bottom-up volume modeling triangulated against top-down sucrose hydrolysis capacity assessments.
Segment-weighting approaches distributed value and volume across product type tiers, end-use application clusters, and geographic production corridors. The analytical framework modeled liquid invert sugar, dry crystalline grades, and high fructose syrup variants against beverage, bakery, confectionery, and dairy demand segments. CAGRs derived from time-series regression of sucrose feedstock cost trajectories, enzymatic conversion adoption curves, and regulatory compliance investment cycles. Forecast inputs incorporated ethanol-to-sugar arbitrage decision thresholds and EFSA food enzyme approval pathway timelines.
Caveats apply where EU F-Gas retrofit deadline extensions, EFSA enzyme authorization delays, or Brazilian ethanol margin spikes could materially shift the outlook. Forecasts reflect assumptions about sucrose hydrolysis technology transition pacing and carbon accounting rule finalization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Icing Sugar Market
Sweeteners
United States Food Sweetener Market
Sweeteners
Africa Stevia Market
Sweeteners
Resistant Maltodextrin Market
Sweeteners
Middle East and Africa Food Sweetener Market
Sweeteners
Asia-Pacific Stevia Market
Sweeteners
Rare Sugar Market
Sweeteners
North America Low-Calorie Sweeteners Market
Sweeteners
Galactose Market
Sweeteners
Raw Beetroot Sugar Market
Sweeteners
Clarified Rice Syrup Market
Sweeteners
France Food Sweetener Market
Sweeteners
Global Stevia Sugar Blends Market
Sweeteners
Intensive Sweeteners Market
Sweeteners
Sugar-Free Syrups Market
Sweeteners
Oligofructose Market